
 Infant Food Compliance Ready Fertility Input Market | 2026-2036
Infant Food Compliance Ready Fertility Input Market Size, Share, and Industry Trends Forecast 2026-2036
Infant Food Compliance Ready Fertility Input Market Insights
Specialty infant formula manufacturing is pivoting toward vertically controlled agricultural supply chains. Nestlé leverages backward integration into dairy farming cooperatives to secure contaminant-free milk protein inputs. Danone anchors its European sourcing network through long-term contracts with biodynamic farms certified under EU organic standards. Abbott Laboratories differentiates via in-house laboratory screening of all agricultural raw materials for pesticide residues and heavy metals.
Infant Food Compliance Ready Fertility Input denotes agricultural fertility products engineered to produce raw materials meeting infant food safety thresholds for contaminants, pathogens, and chemical residues, typically requiring nitrogen-phosphorus-potrogen formulations below detectable heavy metal limits and manufactured through controlled fermentation or thermal processing. These inputs serve the primary commercial purpose of enabling dairy, grain, and vegetable suppliers to achieve lot-level certification for infant nutrition procurement. Biofertilizers now occupy the fastest-expanding product category as manufacturers seek microbial alternatives that eliminate synthetic chemical carryover risks. Agricultural Cooperatives represent the most concentrated end-user channel, aggregating demand and enforcing unified compliance standards across member farms. Direct Sales channels dominate margin pools by eliminating intermediary markups on certified-input transactions between fertility producers and large infant food processors.
The EU EFSA and REACH frameworks mandate maximum residue limits for agricultural inputs entering infant food supply chains, compelling fertility manufacturers to reformulate products and document full substance inventories. The US FDA enforces Infant Formula Quality Control Program standards that cascade backward to raw agricultural suppliers through purchaser audits. China's SAMR implements GB standards for infant formula raw materials that restrict fertilizer-derived contaminants in domestic dairy production. Stakeholders must monitor evolving contaminant detection thresholds and pre-qualify alternative suppliers before regulatory deadlines tighten.
Market Dynamics
REACH compliance deadlines and EU F-Gas phase-down mandates are forcing fertility input manufacturers to eliminate synthetic chemical precursors from production lines, compressing reformulation timelines to eighteen-month windows.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon propellants in fertilizer manufacturing equipment accelerates investment in closed-loop fermentation systems for biofertilizer production.
- Biodynamic farming cooperatives:German dairy collectives are aggregating demand for certified inputs, creating volume commitments that justify dedicated production lines at specialty fertility manufacturers.
- Microbial inoculant technology:Nitrogen-fixing bacterial formulations eliminate synthetic nitrogen carryover risks, enabling lot-level certification for infant formula raw material procurement.
Market Restraints
- Phosphate rock price volatility:Moroccan and Chinese export quotas on high-purity phosphate ore create input cost instability for low-heavy-metal fertilizer formulations.
- Specialty laboratory capacity:Third-party testing facilities certified for EU EFSA contaminant protocols face twelve-month backlogs, delaying supplier qualification timelines.
- Organic substrate scarcity:Composted agricultural waste meeting infant-grade pathogen standards concentrates in Dutch and Danish processing hubs, creating geographic supply risk.
Strategic Opportunities
- China GB standard alignment:Domestic infant formula manufacturers seeking import substitution create demand for SAMR-certified fertility inputs produced through joint ventures with European technology licensors.
- Direct-to-processor channels:Large infant nutrition manufacturers are bypassing agricultural cooperatives to negotiate volume contracts directly with certified biofertilizer producers.
- Carbon credit stacking:Biofertilizer fermentation systems qualifying under EU Green Deal carbon farming incentives generate secondary revenue streams from emissions reduction certificates.
Industry Challenges
- Microbiome standardization:Batch-to-batch variability in commercial microbial consortia complicates regulatory dossier preparation for novel biofertilizer registrations.
- Legacy equipment retrofit costs:Thermal processing lines originally designed for synthetic chemical fertilizers require capital-intensive modifications to handle temperature-sensitive organic substrates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infant Food Compliance Ready Fertility Input Market |
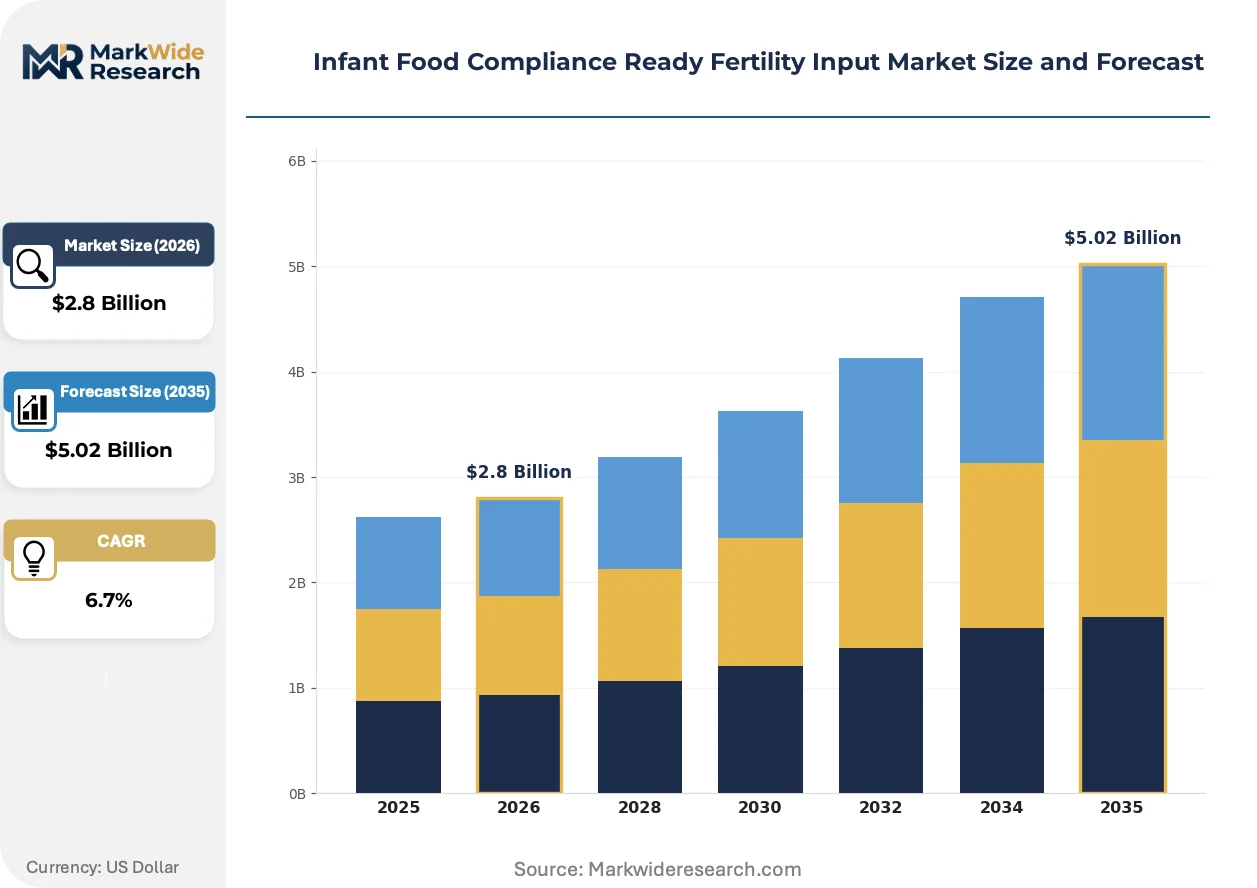
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Fertilizers, Biofertilizers, Mineral Fertilizers, Compost, Liquid Fertilizers Application: Soil Conditioning, Crop Nutrition, Seed Treatment, Foliar Feeding, Root Zone Enhancement End User: Smallholder Farmers, Agricultural Cooperatives, Horticulture Specialists, Agribusiness Firms, Greenhouse Operators Distribution Channel: Direct Sales, Agricultural Retailers, Online Marketplaces, Supply Cooperatives, Wholesale Distributors |
| Companies Covered | Nestlé, Danone, Abbott Laboratories, Reckitt, China Feihe, Yili Group, FrieslandCampina, Arla Foods Ingredients, HiPP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infant Food Compliance Ready Fertility Input Market Trends and Innovations
Precision fermentation platforms and enzymatic processing methods are displacing conventional thermal treatment in fertility input manufacturing, enabling tighter control over heavy metal and pathogen thresholds demanded by infant food safety protocols.
Cell-free enzymatic bioprocessing is rewriting contaminant removal economics in organic fertilizer production. Specialty manufacturers deploying immobilized enzyme reactors achieve ninety-nine percent pesticide residue degradation at ambient temperatures. Infant formula processors in the Netherlands and Denmark are prioritizing enzymatically treated inputs in procurement specifications. The technology is compressing capital requirements for new market entrants previously blocked by thermal processing infrastructure costs.
REACH substance inventory mandates now require full disclosure of fertilizer additive compositions down to 0.1 percent concentration thresholds. ECHA enforcement actions against non-compliant suppliers have triggered contract cancellations across German and French agricultural cooperatives. Biofertilizer manufacturers with pre-submitted dossiers are capturing shelf space previously held by synthetic incumbents facing reformulation deadlines.
Certificate-of-analysis requirements are migrating upstream from infant formula packagers to agricultural input purchasers. Dairy cooperatives in Bavaria and Normandy now require lot-specific contaminant documentation before accepting fertilizer deliveries. This documentation burden favors integrated manufacturers with in-house laboratory networks over trading companies reliant on third-party verification. The shift is visible most acutely in contract structures linking input pricing to real-time laboratory test results rather than fixed specifications.
Infant Food Compliance Ready Fertility Input Market Segmentation
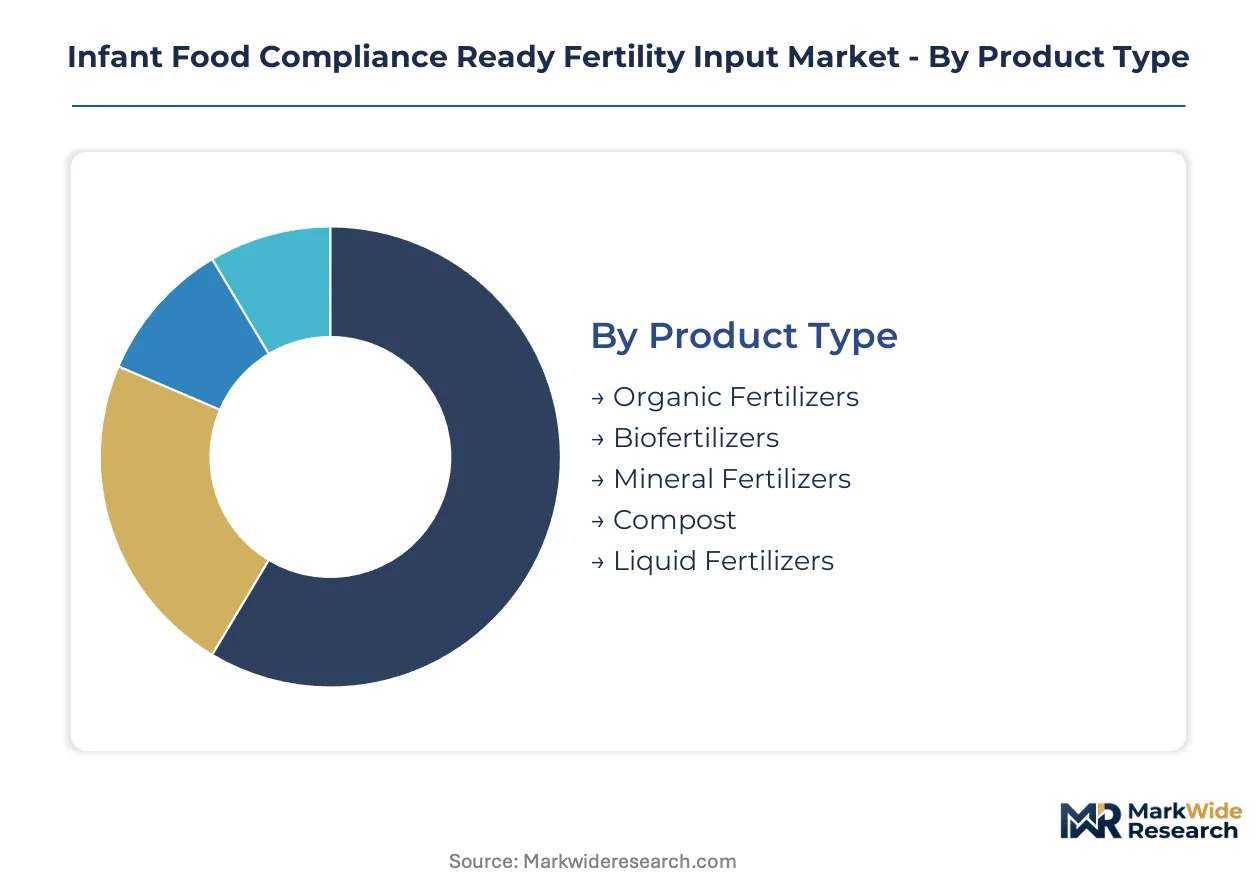
Segmentation in this market tracks how compliance requirements cascade through distinct input categories and user channels. Procurement patterns diverge sharply between infant-grade certified products and conventional agricultural fertility inputs.
Product Type:
Supply concentration in infant-grade raw materials favors manufacturers with dedicated production lines and in-house laboratory networks.
- Biofertilizers:Microbial formulations including nitrogen-fixing bacteria and phosphate-solubilizing consortia eliminate synthetic chemical carryover risks. German dairy cooperatives in Bavaria and Lower Saxony are aggregating volume commitments for certified biofertilizer supply, driven by EFSA contaminant threshold enforcement. Biofertilizers absorb the bulk of installed capacity; Mineral Fertilizers are expanding most quickly.
- Mineral Fertilizers:Low-heavy-metal formulations derived from purified phosphate rock and potassium salts meet REACH substance inventory mandates. Moroccan export quotas on high-purity phosphate ore create input cost instability for European manufacturers.
- Organic Fertilizers:Composted plant and animal residues processed to infant-grade pathogen standards, with Dutch and Danish hubs dominating substrate supply.
- Compost:Thermally processed organic matter meeting EU EFSA microbial thresholds, concentrated in specialized regional processing facilities.
- Liquid Fertilizers:Soluble nutrient solutions enabling precision application and reduced contamination risk in greenhouse vegetable production for infant food supply chains.
Cost tier differentiation separates premium certified inputs from commodity-grade alternatives across all product categories.
Application:
Application methods correlate directly with crop type and contamination risk profiles in infant food raw material production.
- Soil Conditioning:Long-term pH and organic matter adjustment for dairy pasture lands supplying infant formula processors. Danish biodynamic farms prioritize soil conditioning applications to maintain EFSA-compliant milk protein outputs.
- Crop Nutrition:Scheduled nutrient delivery aligned with plant growth stages in grain and vegetable production for infant food ingredients. French agricultural cooperatives in Normandy enforce unified crop nutrition protocols across member farms.
- Seed Treatment:Microbial inoculation at planting to establish beneficial rhizosphere communities and suppress pathogen loads.
- Foliar Feeding:Direct leaf surface nutrient application reducing soil-borne contaminant uptake in sensitive vegetable crops.
- Root Zone Enhancement:Targeted fertility placement optimizing nutrient uptake efficiency in controlled-environment horticulture.
Soil Conditioning commands the longest contract durations; Seed Treatment is climbing the fastest as microbial technology advances.
End User:
Customer type determines procurement scale, certification requirements, and supplier relationship structures.
- Agricultural Cooperatives:Member-owned aggregators enforcing unified compliance standards and volume commitments across dairy and arable farming operations. German cooperatives in Schleswig-Holstein and Baden-Württemberg negotiate direct supply contracts with certified biofertilizer manufacturers.
- Agribusiness Firms:Large-scale integrated producers with captive laboratory networks for lot-level contaminant screening and documentation.
- Smallholder Farmers:Individual producers accessing certified inputs through cooperative membership or supply cooperative intermediation.
- Horticulture Specialists:Intensive vegetable and fruit producers serving infant food ingredient processors with specialized substrate requirements.
- Greenhouse Operators:Controlled-environment producers requiring pathogen-free liquid and substrate inputs for year-round supply security.
Agricultural Cooperatives aggregate the largest procurement volumes; Greenhouse Operators are gaining share fastest through year-round demand stability.
Distribution Channel:
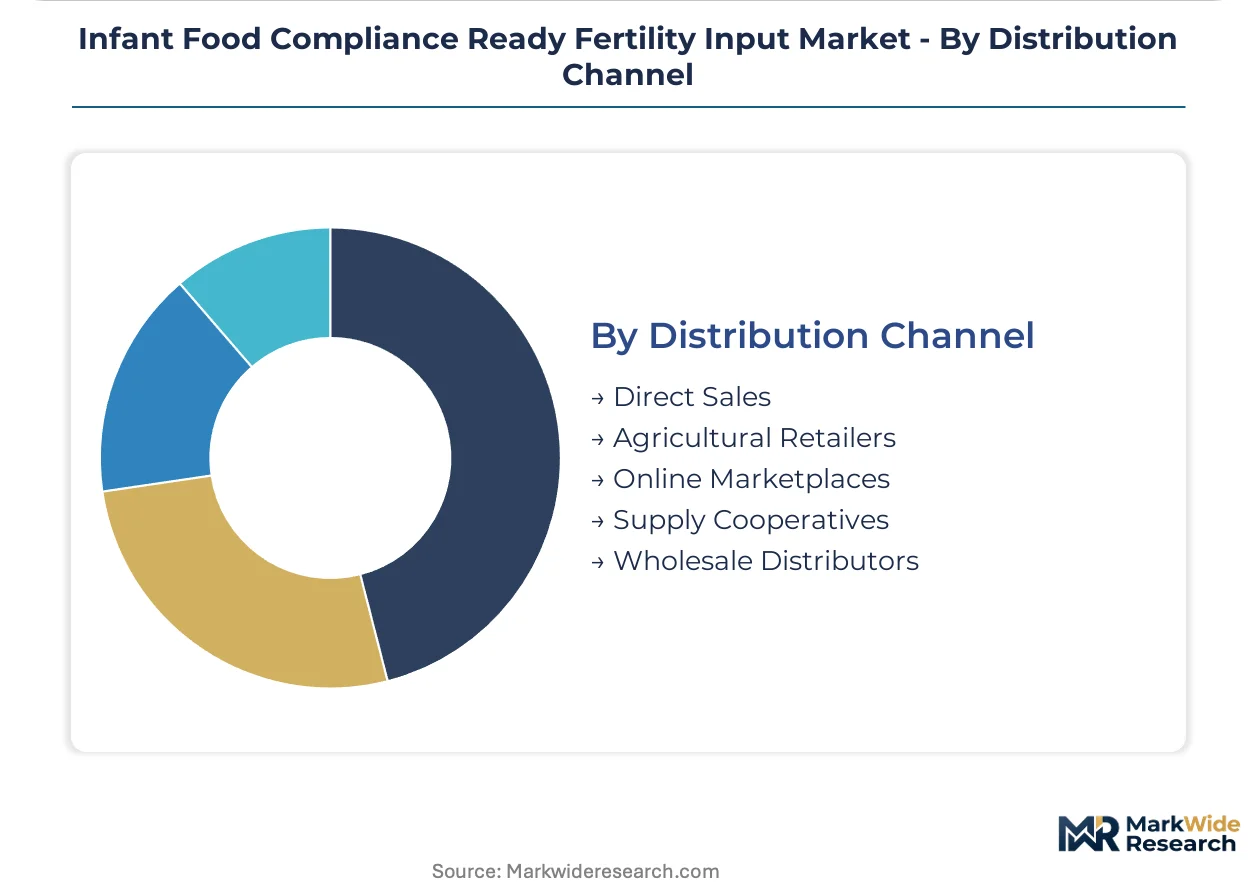
Channel selection determines margin capture, documentation integrity, and speed of supplier qualification.
- Direct Sales:Manufacturer-to-processor contracts eliminating intermediary markups and enabling real-time laboratory result linkage to pricing terms. Nestlé and Danone negotiate direct biofertilier supply agreements with European specialty manufacturers.
- Supply Cooperatives:Member-owned purchasing organizations consolidating demand and enforcing input compliance standards across affiliated farms.
- Agricultural Retailers:Regional distributors with certified product portfolios and third-party documentation capabilities.
- Wholesale Distributors:Volume-focused intermediaries handling commodity-grade and certified-input product lines.
- Online Marketplaces:Digital procurement platforms emerging for standardized certified products with pre-submitted regulatory dossiers.
Direct Sales captures the highest margin pools; Online Marketplaces are expanding most quickly through documentation transparency advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in China's Hainan Free Trade Port and India's Pharmaceutical Parks concentrate infant-grade agricultural input processing through tax incentives and streamlined customs clearance for imported fermentation equipment.
Germany
Biodynamic farming cooperatives in Bavaria and Lower Saxony aggregate certified biofertilizer demand through unified procurement contracts. The EU F-Gas Regulation and REACH substance inventory mandates compress supplier qualification timelines to eighteen months. Stuttgart-based specialty manufacturers operate dedicated production lines for contaminant-free nitrogen-fixing bacterial formulations.
China
Domestic infant formula manufacturers seeking import substitution under SAMR GB standards drive demand for certified fertility inputs. The Hainan Free Trade Port offers zero-tariff treatment for European fermentation technology imports. Yangtze River Delta dairy processors negotiate direct supply contracts with biofertilizer producers bypassing agricultural cooperatives.
United States
FDA Infant Formula Quality Control Program standards cascade backward to raw agricultural suppliers through purchaser audit protocols. Midwest dairy cooperatives in Wisconsin and Minnesota enforce lot-level contaminant documentation requirements. California's Central Valley vegetable producers serving infant food processors prioritize pathogen-free liquid fertilizer applications.
Netherlands
Dutch composting hubs dominate organic substrate supply meeting infant-grade pathogen standards under EFSA enforcement. The country's greenhouse operators generate year-round demand for certified liquid fertility inputs. Wageningen University research clusters accelerate precision fermentation platform adoption among regional manufacturers.
Denmark
Arla Foods Ingredients anchors demand for EFSA-compliant milk protein inputs through long-term contracts with biodynamic farms. Danish agricultural cooperatives pioneered certificate-of-analysis requirements migrating upstream to fertilizer suppliers. Copenhagen-region laboratory networks reduce third-party testing backlogs for supplier qualification.
Infant Food Compliance Ready Fertility Input Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated nutrition corporations capturing premium-tier volume through backward integration into agricultural supply chains while independent biofertilizer producers serve cooperative aggregators. The vendor base concentrates around three strategic archetypes: dairy-processor-affiliated input suppliers, independent microbial technology specialists, and mineral fertilizer purifiers with heavy-metal removal capabilities. Dominant competitive moves include direct-to-processor channel expansion and carbon credit stacking under EU Green Deal frameworks.
Among integrated nutrition corporations, Nestlé, Danone, and Abbott Laboratories exemplify the backward-integration archetype through captive supply relationships with certified agricultural cooperatives. These Switzerland-based and France-based entities occupy positions where laboratory screening capabilities and long-term volume commitments create defensive moats against independent specialty manufacturers. Each represents a distinct geographic anchor point for procurement network formation across European and North American dairy basins.
| Leading Market Players |
|---|
| Nestlé |
| Danone |
| Abbott Laboratories |
| Reckitt |
| China Feihe |
| Yili Group |
| FrieslandCampina |
| Arla Foods Ingredients |
| HiPP |
| Others |
Pricing and Supply Chain Analysis
Backward integration into dairy farming cooperatives anchors supply positions while compressing procurement costs for infant-grade certified inputs. Nestlé and Danone leverage captive supply relationships to bypass intermediary markups and enforce lot-level contaminant documentation directly.
Pricing Analysis
Short lead-time premiums dominate contract structures as EFSA-mandated testing backlogs stretch supplier qualification windows. Three-tier pricing structure across infant-grade certified, organic-compliant, and conventional agricultural inputs reflects certification investment differentials. Cost compression in mineral fertilizer formulations intensifies as Moroccan phosphate export quotas constrain high-purity ore availability. Agricultural cooperatives exhibit highest price sensitivity due to volume aggregation mandates, while direct-to-processor channels absorb premiums for real-time laboratory linkage.
Supply Chain Analysis
Regional distribution centers in the Netherlands and Denmark concentrate organic substrate processing under EFSA pathogen protocols. The supply chain draws from German biodynamic farming cooperatives, Moroccan phosphate mining operations, and Chinese fermentation equipment manufacturers. Single-source vulnerability concentrates in Dutch composting hubs handling infant-grade waste processing. Distribution runs through agricultural cooperative aggregators in Bavaria and direct manufacturer-to-processor contracts with Nestlé and Danone.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty laboratory capacity constraints prop pricing power for certified input manufacturers with in-house testing networks. EFSA enforcement timelines compress supplier qualification windows, creating defensive moats for pre-certified producers.
For Market Incumbents: Extend in-house laboratory screening capabilities to eliminate third-party testing dependencies and accelerate lot-level certification turnaround. Consolidate direct supply relationships with Yangtze River Delta dairy processors before SAMR GB standard alignment deadlines tighten. Capacity addition in Stuttgart-region fermentation facilities defends against microbial inoculant technology substitutes.
For New Entrants and Emerging Players: Online procurement platforms offer the lowest barrier route for standardized certified products with pre-submitted REACH dossiers. White-space concentrates in Chinese domestic infant formula supply chains seeking European technology licensors for joint venture production. Carbon credit stacking under EU Green Deal frameworks provides differentiated go-to-market positioning against synthetic incumbents.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated nutrition corporations pursuing backward integration into agricultural supply chains. Long-term viability hinges on regulatory dossier pre-submission status and captive laboratory network scale. Watch for EFSA contaminant threshold tightening as inflection indicator for biofertilizer demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dairy Cooperatives | Nestlé and Danone secure contaminant-free milk protein through Bavaria biodynamic farm contracts. |
| Precision Fermentation Platform Adoption | Wageningen University clusters accelerate enzymatic bioprocessing for pesticide residue degradation. |
| Direct-to-Processor Channel Expansion | Large infant nutrition manufacturers bypass cooperatives to negotiate volume contracts with biofertilizer producers. |
| Carbon Credit Stacking Certification | EU Green Deal carbon farming incentives generate secondary revenue from emissions reduction certificates. |
| SAMR GB Standard Joint Ventures | European technology licensors partner with Chinese domestic infant formula manufacturers for import substitution. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with infant formula procurement directors, agricultural cooperative managers, biofertilizer R&D leads, and EFSA regulatory consultants combined with secondary validation from REACH substance inventory databases and EU F-Gas Regulation implementation reports. Bottom-up volume modeling across product type, application method, end user category, and distribution channel triangulated against top-down market sizing from agricultural input trade flows.
Data-stream reconciliation across shipment records, production capacity announcements, and certification database entries informed the analytical framework. Segmentation dimensions modeled include product formulation technology, compliance certification tier, crop application method, customer scale archetype, and regional regulatory cluster. CAGRs derived from weighted average growth assumptions across input cost trajectories, enforcement timeline impacts, and technology substitution elasticities. Infant-grade pathogen standard adoption curves and phosphate ore export quota volatility served as industry-specific forecast inputs across the projection horizon.
Inputs from ECHA enforcement action records and German cooperative procurement disclosures were available through the study window; gaps in real-time laboratory capacity utilization data introduce uncertainty bands around supplier qualification timeline assumptions. Forecasts reflect documented assumptions regarding regulatory deadline adherence and technology cost curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Infant Formula Milk Powder with A2 Beta-Casein Market
Baby Food and Infant Formula
Middle East and Africa Organic Baby Food Market
Baby Food and Infant Formula
United States Baby Food and Infant Formula Market
Baby Food and Infant Formula
BRIC Organic Baby Food Market
Baby Food and Infant Formula
Baby Food and Infant Formula Market
Baby Food and Infant Formula
Organic Follow Up Formula Market
Baby Food and Infant Formula
North America Baby Food Market
Baby Food and Infant Formula
Baby Food Products Market
Baby Food and Infant Formula
India Baby Food Market
Baby Food and Infant Formula
Ready to Use Supplementary Food Market
Baby Food and Infant Formula
Standard Milk Formula Market
Baby Food and Infant Formula
Middle-Aged and Elderly Milk Powder Market
Baby Food and Infant Formula
Europe Baby Food Market
Baby Food and Infant Formula
Wet Cat Food Market
Baby Food and Infant Formula
Goat Milk Formula Market
Baby Food and Infant Formula
Vietnam Pet Food Market