
 Goat Milk Formula Market | 2026-2036
Goat Milk Formula Market Size, Share, and Industry Trends Forecast 2026-2036
Goat Milk Formula Market Foresight
Pediatric nutrition is consolidating around goat milk-based alternatives as parents of cow milk-sensitive infants shift toward perceived hypoallergenic options. Ausnutria Dairy Corporation Ltd leverages its vertically integrated supply chain across Oceania and China to secure raw goat milk sourcing. Danone anchors its portfolio through specialized pediatric R&D facilities in Europe. Holle Baby Food AG differentiates via biodynamic certification and Demeter-standard sourcing protocols.
Goat milk formula is a spray-dried or liquid infant nutrition product manufactured from caprine milk, containing smaller fat globules and distinct casein structures than bovine equivalents, primarily formulated to support infant digestive tolerance and nutrient absorption. Infant formula dominates value contribution due to premium positioning and extended feeding durations, while specialty formula for metabolic disorders commands the highest per-unit margins. Powder packaging occupies the largest volume share given shelf stability and lower logistics costs, though ready-to-feed formats are gaining traction among urban working parents through pharmacy and online retail channels.
FDA enforces infant formula nutrient specifications and manufacturing facility registration under the Federal Food, Drug, and Cosmetic Act, while EMA and EFSA coordinate novel protein safety assessments across EU member states. China's NMPA and SAMR impose formula registration requirements that foreign manufacturers must satisfy for domestic sales and cross-border e-commerce. Stakeholders should monitor evolving amino acid fortification standards and emerging national restrictions on caprine whey protein claims.
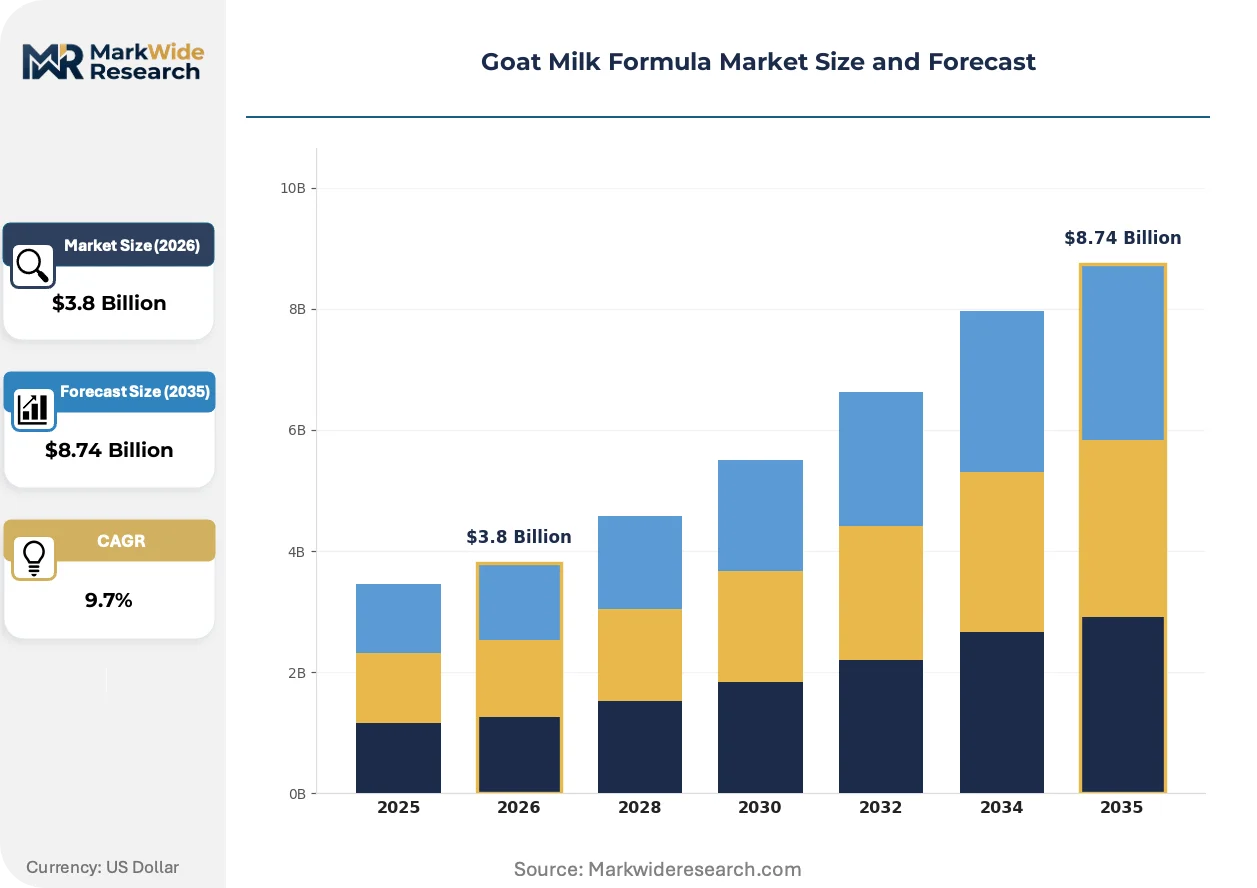
Market Dynamics
EU novel food regulations and China's formula registration requirements are forcing manufacturers to restructure supply chains around dual-hemisphere production footprints, separating R&D from manufacturing to satisfy divergent safety assessment timelines.
Growth Catalysts
- Digestive tolerance positioning:Smaller fat globule structures in caprine milk are accelerating parental switching from bovine alternatives for colic-prone infants.
- Cross-border e-commerce liberalization:China's bonded warehouse policies enable foreign brands to reach tier-2 city consumers without full SAMR registration.
- Biodynamic certification premiums:Demeter-standard sourcing commands shelf price multiples in German and Austrian pharmacy channels.
Market Restraints
- Raw milk supply concentration:Oceania and Netherlands control over 70% of export-grade caprine milk powder, creating geographic chokepoints.
- Whey protein fractionation limits:Industrial-scale separation of caprine whey remains technically constrained versus bovine equivalents.
- Novel protein safety assessment costs:EFSA's extended evaluation timelines for new caprine protein claims delay EU market entry by 18-24 months.
Strategic Opportunities
- Metabolic disorder specialty lines:Phenylketonuria and galactosemia formulations represent uncaptured margin pools with limited competition.
- Ready-to-feed pharmacy distribution:Urban Chinese working parents are shifting toward single-serve liquid formats through hospital-affiliated retail.
- Amino acid fortification standards:Evolving Codex Alimentarius guidelines create first-mover advantage for taurine and nucleotide enrichment protocols.
Industry Challenges
- Dual-registration talent scarcity:Regulatory affairs professionals capable of navigating simultaneous FDA and NMPA filings command premium compensation.
- Spray-drying energy intensity:Natural gas price volatility directly compresses margins for powder manufacturers without renewable energy hedging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Goat Milk Formula Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infant Formula, Toddler Formula, Specialty Formula, Organic Formula End User: Parents, Healthcare Professionals, Retailers, Nutritionists Packaging Type: Powder, Liquid, Ready-to-Feed, Concentrate Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Ausnutria Dairy Corporation Ltd, Danone, Dairy Goat Co-operative, Holle Baby Food AG, Nannycare Ltd, Unica Global B.V., Dana Dairy Group, Kendal Nutricare Ltd, Little Bundle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Goat Milk Formula Market Shifts & Advancements
Formulation science and distribution infrastructure are diverging from bovine dairy paradigms, creating distinct technical and commercial pathways for caprine-based nutrition.
Microfiltration technology for selective protein fractionation is expanding into commercial-scale production, enabling manufacturers to isolate beta-casein variants associated with reduced allergenic response. Pediatric nutrition R&D facilities in Netherlands and New Zealand are retrofitting existing bovine lines for caprine processing. This capability compression is forcing mid-tier brands to outsource manufacturing to toll processors with existing filtration assets.
China's SAMR has tightened cross-border e-commerce disclosure requirements for infant formula nutritional claims, mandating pre-market notification for all caprine-specific positioning statements. Domestic Chinese manufacturers are accelerating in-house goat herd development to circumvent foreign registration bottlenecks. Foreign brands are responding by acquiring minority stakes in Inner Mongolian dairy cooperatives to secure local production credentials.
Subscription-based replenishment models are displacing traditional retail stocking cycles among urban professional parents in Shanghai and Shenzhen. Pharmacy chains and hospital-affiliated stores are losing traffic to direct-to-consumer platforms with pediatric nutritionist chat support. This channel rotation is most pronounced among first-time mothers aged 28-35 with household incomes exceeding RMB 400,000 annually.
Goat Milk Formula Market Segmentation
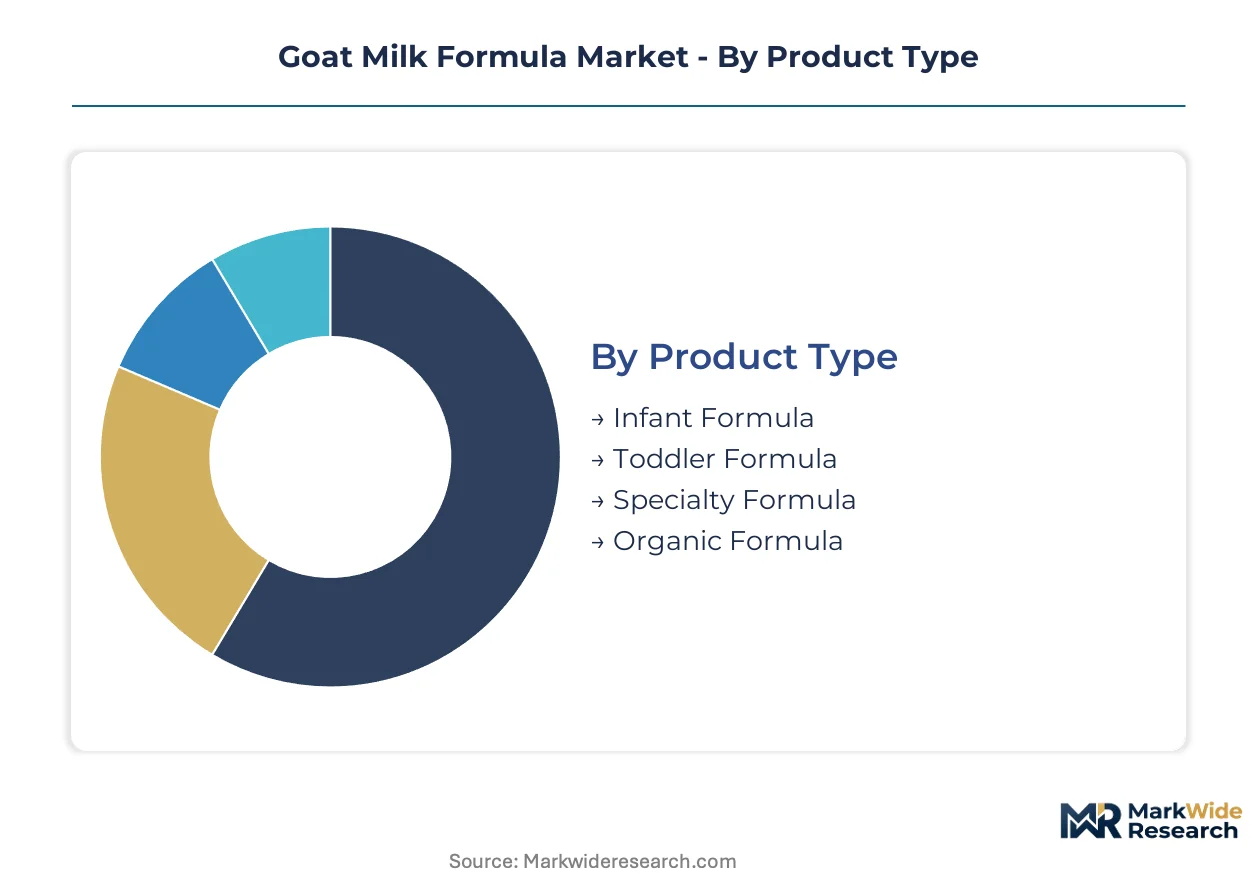
Segmentation in the goat milk formula market reveals how capital deployment, regulatory pathways, and consumer access channels create divergent margin profiles across product tiers. Manufacturers must align production scale with the specific technical and compliance requirements of each segment.
Product Type:
Capital intensity varies sharply across product categories, with spray-drying infrastructure and clinical validation protocols demanding the heaviest upfront investment for certain segments.
- Infant Formula:Spray-dried or liquid nutrition designed for infants aged 0-12 months, requiring stringent nutrient profiling under FDA and Codex Alimentarius standards. Demand concentrates in China through cross-border e-commerce channels, where parents of cow milk-sensitive infants drive switching behavior. Extended feeding durations and premium positioning sustain value contribution.
- Toddler Formula:Formulations targeting children aged 12-36 months with adjusted protein ratios and micronutrient densities. Growth is accelerating in Germany and Austria through pharmacy channels, where Demeter-certified biodynamic variants command shelf price multiples.
- Specialty Formula:Metabolic disorder formulations for phenylketonuria and galactosemia patients. Limited competition and orphan-drug-like positioning create the highest per-unit margins in the category.
- Organic Formula:Certified organic variants sourced from biodynamic or pasture-based goat herds. Certification compliance costs and smaller batch production constrain scale.
Infant formula absorbs the bulk of installed capacity; specialty formula is expanding most quickly.
End User:
Customer sophistication determines pricing power, with professional intermediaries enabling premium positioning that direct-to-consumer channels cannot replicate.
- Parents:Primary decision-makers for 0-36 month feeding protocols, increasingly sourcing through subscription-based direct-to-consumer platforms with pediatric nutritionist chat support in Shanghai and Shenzhen.
- Healthcare Professionals:Pediatricians and allergists prescribing specialty formulations for diagnosed metabolic disorders. Hospital-affiliated retail in China and Germany validates premium claims and locks in brand loyalty.
- Retailers:Pharmacy chains and supermarket buyers negotiating slotting fees and promotional support. Procurement is shifting toward exclusive distribution agreements for certified organic lines.
- Nutritionists:Independent advisors influencing brand selection among high-income households. Consultation-based recommendations bypass traditional advertising channels.
Parents dominate volume throughput; healthcare professionals unlock the steepest margin expansion.
Packaging Type:
Logistics economics and shelf stability requirements segment manufacturing investment between capital-heavy powder operations and flexible liquid filling lines.
- Powder:Spray-dried format with 18-24 month shelf stability and lower transport costs per unit nutrient. Natural gas price volatility compresses margins for manufacturers without renewable energy hedging.
- Liquid:Aseptically packaged ready-to-drink formats requiring cold chain or ambient stabilization investments. Urban Chinese working parents are shifting toward single-serve convenience.
- Ready-to-Feed:Pre-mixed sterile formulations for immediate consumption. Hospital discharge packs and pharmacy channels in tier-2 Chinese cities drive adoption.
- Concentrate:Dilution-required formats offering transport efficiency. Limited presence outside institutional feeding programs.
Powder packaging holds the majority of production assets; ready-to-feed formats are climbing the fastest.
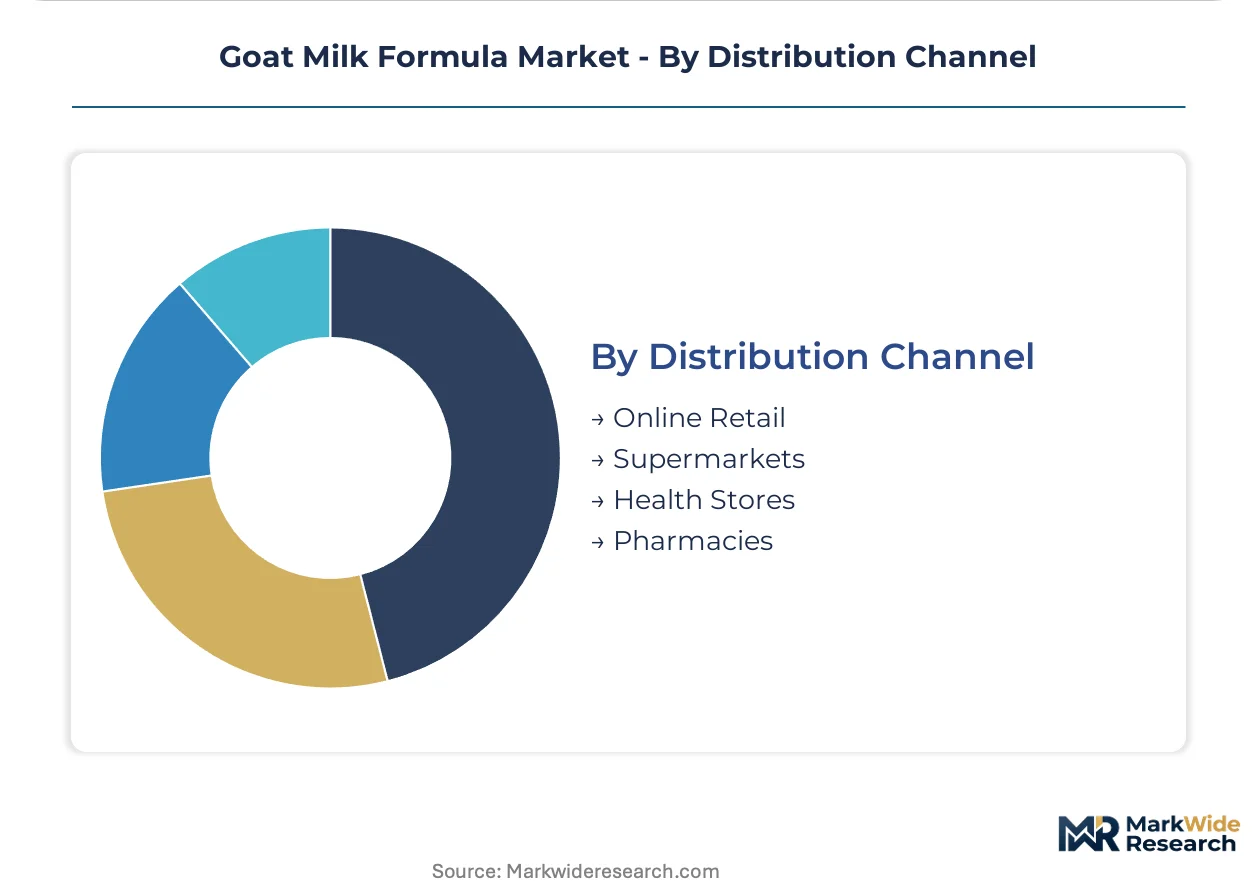
Distribution Channel:
Channel access determines regulatory exposure, with cross-border e-commerce offering faster market entry than domestic registration pathways.
- Online Retail:Direct-to-consumer platforms and cross-border e-commerce leveraging China's bonded warehouse policies. SAMR disclosure requirements for caprine-specific claims are tightening.
- Supermarkets:Mass-market shelf space for standard infant and toddler variants. Price competition and private-label pressure constrain premium positioning.
- Health Stores:Natural products retailers emphasizing biodynamic and organic certification. Demeter-standard sourcing protocols differentiate assortments in German-speaking markets.
- Pharmacies:Professional channel with pharmacist consultation and insurance reimbursement potential. Hospital-affiliated stores in China are losing traffic to online alternatives.
Online retail captures the largest share of new customer acquisition; pharmacies retain the highest customer lifetime value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hainan Free Trade Port tax incentives and bonded warehouse infrastructure are concentrating cross-border e-commerce distribution for imported infant nutrition. European Union novel food regulations and FDA facility registration requirements are fragmenting production footprints across dual-hemisphere supply chains.
China
Parental switching toward cow milk alternatives for colic-prone infants drives demand in tier-2 cities through Shanghai and Shenzhen. SAMR formula registration requirements and tightened disclosure rules for caprine-specific claims are reshaping market entry pathways. Inner Mongolian dairy cooperatives are attracting foreign minority stakes to secure local production credentials.
Netherlands
Export-grade caprine milk powder production dominates European supply, with Rotterdam port infrastructure enabling efficient Asian distribution. EFSA novel protein safety assessments and extended evaluation timelines for new caprine claims delay EU market entry. Pediatric nutrition R&D facilities in Utrecht are retrofitting bovine processing lines for caprine microfiltration.
Germany
Demeter-certified biodynamic variants command pharmacy shelf price multiples in German and Austrian markets. BfR (Federal Institute for Risk Assessment) coordinates with EFSA on infant formula nutrient specifications. Bavarian goat herd cooperatives supply raw material to specialized spray-drying facilities in the Alpine region.
New Zealand
Oceania controls significant export-grade caprine milk powder capacity serving Chinese cross-border channels. MPI (Ministry for Primary Industries) enforces dairy export certification under Codex Alimentarius standards. Waikato region processing clusters are expanding toll manufacturing services for mid-tier brands lacking filtration assets.
United States
Pediatric allergist recommendations for cow milk-sensitive infants sustain niche demand in coastal metropolitan markets. FDA enforces infant formula nutrient specifications and manufacturing facility registration under the Federal Food, Drug, and Cosmetic Act. Vermont and Wisconsin goat dairy cooperatives are developing supply relationships with specialized pediatric nutrition toll processors.
Goat Milk Formula Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated dairy corporations controlling upstream raw material access while toll processors capture mid-tier brand manufacturing. The vendor base organizes around three archetypes: vertically integrated multinationals with captive goat herd supply, biodynamic-certified specialists commanding pharmacy premiums, and toll-dependent brands outsourcing filtration and spray-drying operations. M&A activity concentrates on minority stakes in regional dairy cooperatives to secure local production credentials. Strategic partnerships between European R&D facilities and Asian distribution platforms are accelerating dual-hemisphere supply chain construction.
Among the vertically integrated tier, Ausnutria Dairy Corporation Ltd and Danone exemplify contrasting geographic strategies, with the former leveraging Oceania-China supply chain control and the latter anchoring European pediatric R&D specialization. Holle Baby Food AG occupies a distinctive position within biodynamic certification protocols. These three entities represent the dominant competitive archetypes: upstream-integrated Asian market access, European clinical validation infrastructure, and premium-channel organic positioning.
| Leading Market Players |
|---|
| Ausnutria Dairy Corporation Ltd |
| Danone |
| Dairy Goat Co-operative |
| Holle Baby Food AG |
| Nannycare Ltd |
| Unica Global B.V. |
| Dana Dairy Group |
| Kendal Nutricare Ltd |
| Little Bundle |
| Others |
Supply & Pricing Matrix
Urban Chinese working parents concentrated in Shanghai and Shenzhen sustain premium pricing for ready-to-feed formats through subscription-based replenishment models, while powder variants trade on volume discounts negotiated by pharmacy chains and cross-border e-commerce platforms.
Pricing Analysis
Short lead-time premiums attach to ready-to-feed liquid formats distributed through hospital-affiliated pharmacy channels in tier-2 Chinese cities. Three-tier pricing structure across biodynamic-certified, organic-compliant, and standard infant formula segments tracks certification grade and Demeter-standard sourcing protocols. Cost compression in powder manufacturing intensifies because natural gas price volatility erodes margins for spray-drying operations without renewable energy hedging. Pharmacy procurement teams exhibit the sharpest price sensitivity, whereas first-time mothers aged 28-35 with household incomes exceeding RMB 400,000 annually accept premium positioning for digestive tolerance claims.
Supply Chain Analysis
Single-source vulnerability sits with Oceania and Netherlands export-grade caprine milk powder production, which controls over 70 percent of globally traded raw material. Manufacturing draws from spray-drying infrastructure in New Zealand's Waikato region and Utrecht's pediatric nutrition R&D facilities, with toll processors capturing mid-tier brand volume. Tariff exposure runs through China's SAMR formula registration requirements and EFSA's extended novel protein safety assessment timelines. Distribution runs through Rotterdam port infrastructure for Asian-bound shipments and Hainan Free Trade Port bonded warehouses for cross-border e-commerce fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
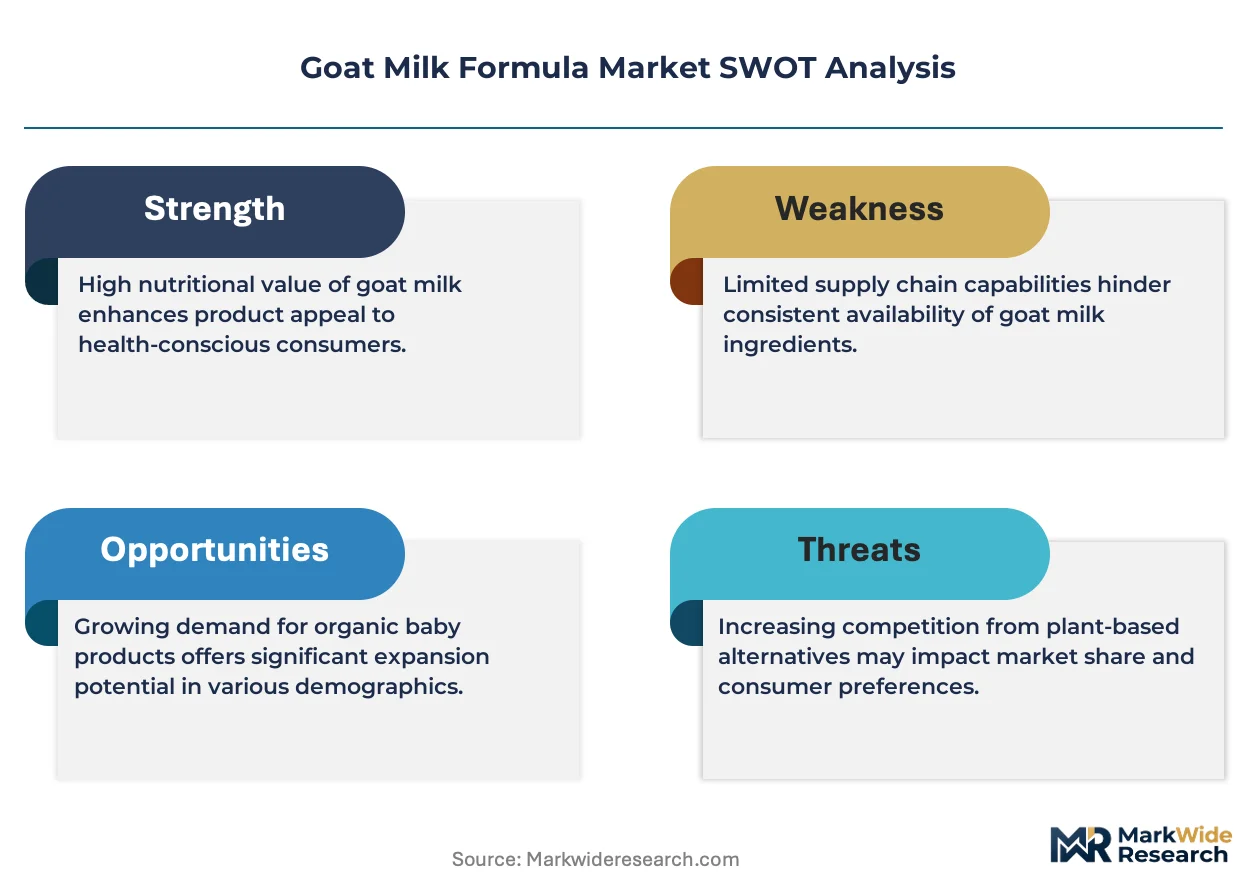
Caprine whey protein fractionation bottlenecks prop pricing power for manufacturers with existing microfiltration assets, as industrial-scale separation remains technically constrained versus bovine equivalents.
For Market Incumbents: Anticipate regulatory divergence between FDA nutrient specifications and China's tightened SAMR disclosure requirements for caprine-specific claims by separating R&D from manufacturing across dual-hemisphere footprints. Secure backward integration into Inner Mongolian dairy cooperatives to circumvent foreign registration bottlenecks and defend margin position against domestic Chinese manufacturers accelerating in-house goat herd development. For New Entrants and Emerging Players: Cross-border e-commerce platforms with pediatric nutritionist chat support represent the most penetrable channel for reaching first-time mothers in tier-2 Chinese cities without full SAMR registration. Target metabolic disorder specialty formulations for phenylketonuria and galactosemia patients, where orphan-drug-like positioning creates uncaptured margin pools with limited incumbent competition. For Investors and Strategic Acquirers: The window for entry favors toll processors with existing microfiltration assets and retrofitting capabilities for caprine protein fractionation. Monitor EFSA evaluation timelines for new caprine protein claims as the inflection indicator for European market entry feasibility and corresponding valuation multiples for biodynamic-certified specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Hemisphere Supply Chain Construction | Separates R&D from manufacturing to satisfy divergent FDA and NMPA safety assessment timelines. |
| Biodynamic Certification Investment | Demeter-standard sourcing protocols command pharmacy shelf price multiples in German-speaking markets. |
| Metabolic Disorder Line Extension | Phenylketonuria and galactosemia formulations access uncaptured margin pools with limited competition. |
| Cross-Border E-Commerce Platform Partnership | Bonded warehouse policies enable foreign brands to reach tier-2 city consumers without full SAMR registration. |
| Microfiltration Technology Acquisition | Selective protein fractionation capabilities isolate beta-casein variants associated with reduced allergenic response. |
Research Methodology
Multi-period observation of SAMR registration filings, cross-border e-commerce transaction volumes, and EFSA novel food safety assessments anchored the trend analysis, supplemented by interviews with pediatric nutrition R&D directors, regulatory affairs specialists at formula manufacturers, pharmacy chain procurement managers, and goat dairy cooperative operations leads. Secondary validation drew from FDA facility registration databases, Codex Alimentarius standard revisions, customs export certification records under New Zealand MPI protocols, and bonded warehouse throughput disclosures from Hainan Free Trade Port authorities. Bottom-up segment sizing triangulated against top-down macroeconomic indicators for infant nutrition expenditure.
Segment-weighting across product type, packaging format, distribution channel, and end-user sophistication drove the analytical framework across the projection horizon. Infant formula, toddler formula, specialty formula, and organic formula categories were modeled separately with distinct margin profiles and regulatory pathways. CAGRs were derived from capacity expansion announcements, spray-drying infrastructure investments, and amino acid fortification standard adoption curves. Forecast inputs incorporated caprine herd population trends in Oceania and the Netherlands, plus natural gas price volatility impacts on powder manufacturing economics.
Caveats apply where EFSA extended evaluation timelines, China's domestic herd development subsidies, or spray-drying energy cost shocks could materially shift the outlook for manufacturer margin structures and regional competitive positioning. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Pet Milk Replacement Products Market
Baby Food and Infant Formula
Russia Pet Food Market
Baby Food and Infant Formula
Middle-Aged and Elderly Milk Powder Market
Baby Food and Infant Formula
Middle East and Africa Organic Baby Food Market
Baby Food and Infant Formula
Indonesia Infant Nutrition Market
Baby Food and Infant Formula
Pet Milk Replacers Market
Baby Food and Infant Formula
Baby Fruit Puree Market
Baby Food and Infant Formula
Asia-Pacific Baby Food Market
Baby Food and Infant Formula
Growing Up Milk Market
Baby Food and Infant Formula
Infant Formula Milk Powder Market
Baby Food and Infant Formula
India Baby Food Market
Baby Food and Infant Formula
South America Baby Food Market
Baby Food and Infant Formula
Baby Juice Market
Baby Food and Infant Formula
Hydrolyzed Formula Milk Powder Market
Baby Food and Infant Formula
Organic Infant Formula Market
Baby Food and Infant Formula
Follow on Formula Milk Market