
 Global Oligosaccharides in Infant Nutrition Market | 2026-2036
Global Oligosaccharides in Infant Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oligosaccharides in Infant Nutrition Market Foresight
The EU Green Deal is recalibrating ingredient sourcing standards across European infant nutrition supply chains. DSM-Firmenich leverages its biotechnology platforms to produce fermentation-based human milk oligosaccharides at scale. Glycom A/S anchors its position through dedicated HMO manufacturing facilities and pharmaceutical-grade certifications. Jennewein Biotechnologie GmbH specializes in rare oligosaccharide structures for clinical nutrition applications.
Oligosaccharides in infant nutrition comprise short-chain carbohydrate polymers, typically two to ten monosaccharide units, that resist upper-gastrointestinal digestion and selectively nourish beneficial gut microbiota. Manufacturers synthesize these compounds through enzymatic conversion of lactose or microbial fermentation, achieving purity thresholds exceeding ninety-five percent for pharmaceutical-grade applications. Galactooligosaccharides dominate volume consumption due to mature production economics and broad regulatory acceptance across major jurisdictions. Infant formula applications capture the largest value pool, while probiotic supplements represent the fastest-expanding channel as direct-to-consumer wellness brands enter pediatric positioning.
FDA, EFSA, and China's SAMR each maintain distinct approval pathways for novel oligosaccharide ingredients in infant formula, creating fragmented market access conditions. EFSA's novel food assessments and China's GB standards for formula composition impose the most stringent preclinical and clinical evidence requirements. Stakeholders must monitor evolving regulatory convergence between WHO Codex guidelines and national infant food standards to anticipate reformulation obligations and timing of market entry windows.
Market Dynamics
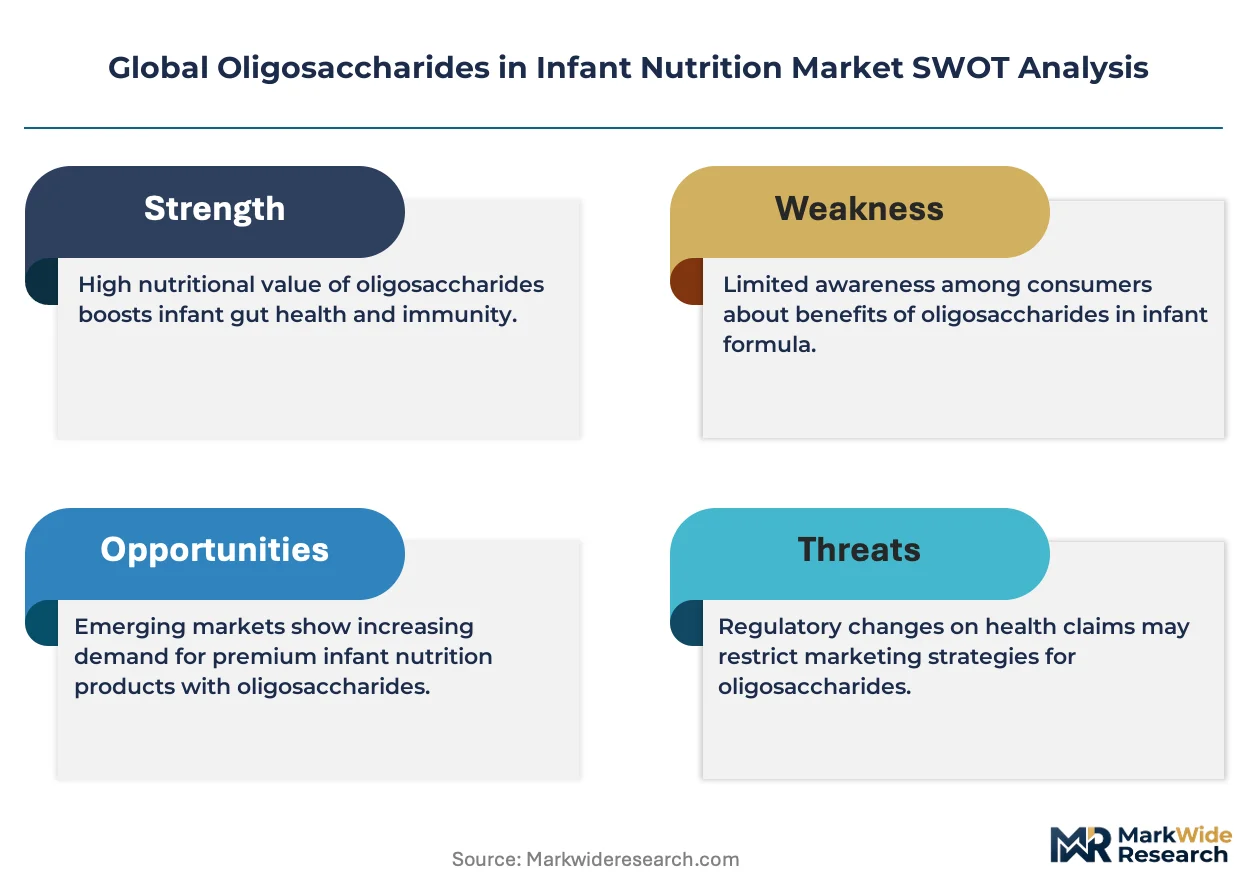
Biotechnology platforms are absorbing capital and talent from traditional dairy extraction methods, compressing production economics for fermentation-derived human milk oligosaccharides while EFSA and China's SAMR tighten evidence requirements for novel ingredient approvals.
Growth Catalysts
- EFSA Novel Food Pathways:Streamlined safety assessments for microbial fermentation oligosaccharides accelerate European market entry timelines for biotech-derived ingredients.
- China's GB Standards Reform:Updated infant formula composition rules mandate prebiotic inclusion thresholds, forcing domestic manufacturers to secure oligosaccharide supply contracts.
- Precision Fermentation Scale-Up:Single-use bioreactor advances cut capital intensity for pharmaceutical-grade HMO production, enabling mid-volume manufacturers to achieve cost parity with galactooligosaccharide suppliers.
Market Restraints
- Lactose Feedstock Volatility:Dairy commodity price swings transmit directly to enzymatic conversion economics, squeezing margin stability for European and North American producers.
- Clinical Evidence Burden:SAMR's GB standards demand multi-center infant trials for novel oligosaccharide structures, extending approval timelines to 4-7 years for entrants lacking existing pediatric nutrition portfolios.
- Galactooligosaccharide Substitution:Mature GOS supply chains and established gut-health positioning limit pricing power for differentiated HMO structures in cost-sensitive formula segments.
Strategic Opportunities
- India's FSSAI Window:Emerging regulatory clarity on prebiotic infant food claims creates first-mover positioning for fermentation-based oligosaccharide suppliers before domestic manufacturing scales.
- Follow-On Formula Extension:Oligosaccharide fortification beyond 12-month products remains underdeveloped, offering volume expansion as pediatric probiotic positioning migrates to toddler nutrition.
- EU Green Deal Sourcing Mandates:Renewable energy requirements for dairy processing create competitive openings for cell-culture oligosaccharides with verifiable carbon footprints.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Microbial strain optimization and downstream purification expertise concentrates among a handful of academic and industrial centers, inflating compensation for scale-up specialists.
- Pharmaceutical-Grade Certification Timelines:ISO 22000 and FSSC 22000 audits for infant-grade facilities extend 18-24 months, delaying revenue recognition for greenfield manufacturing investments.
- Cross-Jurisdictional IP Complexity:Overlapping patent estates covering HMO biosynthesis pathways force licensing negotiations across multiple technology holders for comprehensive product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oligosaccharides in Infant Nutrition Market |
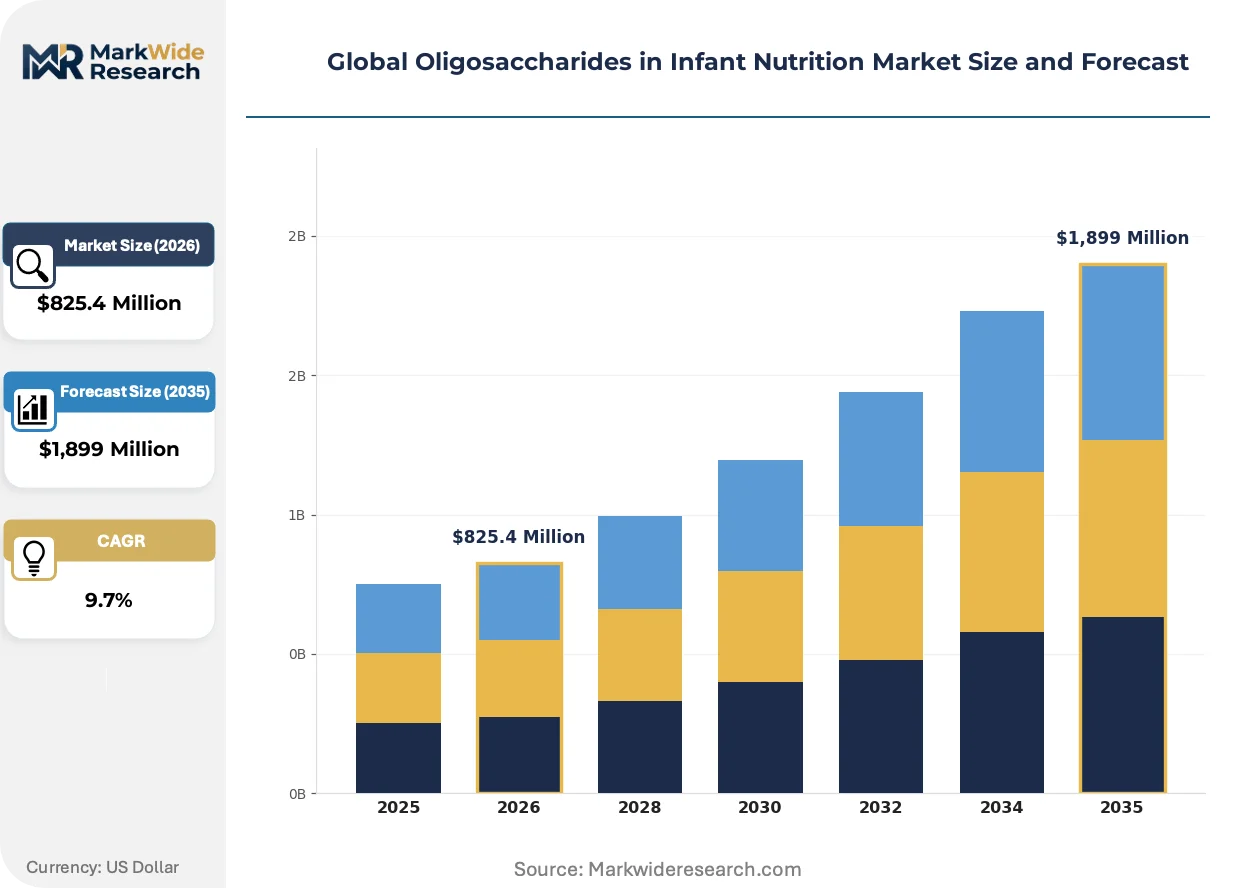
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,899 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
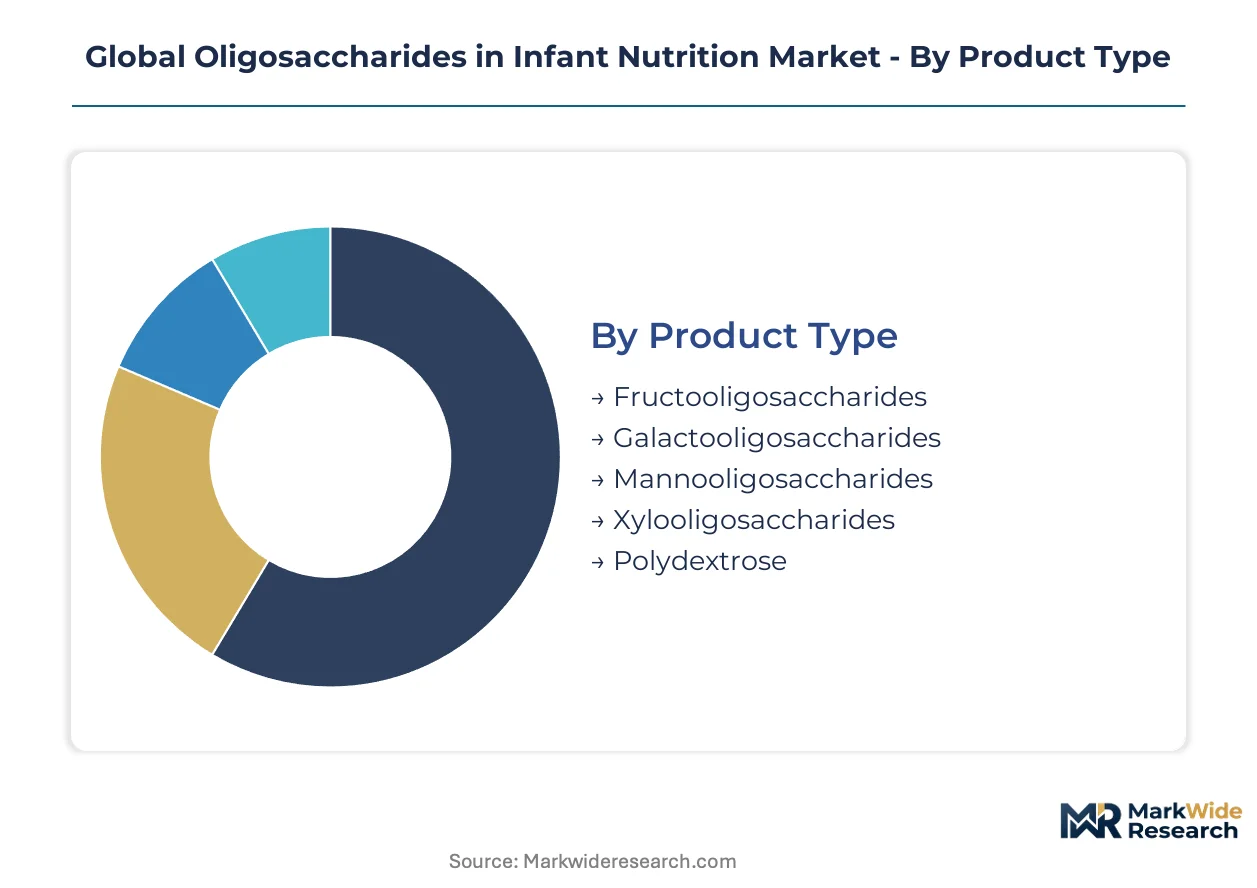
| Segmentation | Product Type: Fructooligosaccharides, Galactooligosaccharides, Mannooligosaccharides, Xylooligosaccharides, Polydextrose Application: Infant Formula, Baby Food, Nutritional Supplements, Probiotic Supplements, Clinical Nutrition Form: Powder, Liquid, Granules, Syrup, Capsules End User: Hospitals, Pediatric Clinics, Nutritionists, Retail Pharmacies, Baby Care Centers |
| Companies Covered | Nestlé SA, Abbott Laboratories, DSM-Firmenich, Royal FrieslandCampina N.V., BASF SE, BENEO, Glycom A/S, DuPont Nutrition & Biosciences, Jennewein Biotechnologie GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oligosaccharides in Infant Nutrition Market Shifts & Advancements
Fermentation-based production architectures are displacing enzymatic conversion dominance, while regulatory convergence pressures and direct-to-consumer channel experimentation reshape competitive boundaries across infant nutrition supply chains.
Cell-culture human milk oligosaccharide production is absorbing investment previously allocated to lactose-derived galactooligosaccharide expansion. DSM-Firmenich and dedicated biotech specialists deploy CRISPR-optimized microbial chassis to achieve 10-gram-per-liter titers for 2'-fucosyllactose and lacto-N-neotetraose structures. Pharmaceutical-grade purity specifications are compressing the supplier base to fermentation specialists with captive purification capabilities.
China's SAMR implementation of GB 10765-2021 infant formula standards imposes compositional ceilings and mandatory labeling for oligosaccharide content. Domestic brands reformulate to meet dual-carbon sourcing preferences while multinationals navigate extended clinical trial requirements for novel HMO structures. The regulation fragments competitive positioning between established GOS suppliers and fermentation entrants awaiting full approval portfolios.
Pediatric probiotic supplement brands are disintermediating traditional pharmacy and grocery channels through subscription direct-to-consumer models. Parents in urban China and metropolitan US markets receive monthly oligosaccharide-probiotic bundles with personalized microbiome testing add-ons. This channel compression threatens infant formula manufacturers' historical control over early-life gut-health positioning.
Global Oligosaccharides in Infant Nutrition Market Segmentation
Oligosaccharide suppliers configure product portfolios around distinct upgrade cycles—formula manufacturers refresh ingredient specifications every 3-5 years while clinical nutrition contracts lock in multi-year supply agreements. Segmentation clarity exposes where pricing power concentrates and which application channels absorb novel fermentation-derived structures fastest.
Product Type:
Reformulation cycles in infant nutrition accelerate as manufacturers replace first-generation prebiotics with precision-fermented alternatives that command premium positioning.
- Galactooligosaccharides:Enzymatic conversion of lactose yields beta-linked galactose oligomers with degree of polymerization 2-8. European and North American formula manufacturers anchor procurement contracts here, though margin compression from dairy commodity volatility constrains pricing flexibility.
- Fructooligosaccharides:Short-chain fructose polymers derived from sucrose or inulin hydrolysis resist salivary digestion and selectively stimulate bifidobacterial colonization. Chinese domestic brands source heavily from Thai and Indonesian feedstock suppliers to meet GB standard prebiotic thresholds.
- Mannooligosaccharides:Yeast cell wall extracts with established immunomodulatory properties in livestock applications seek pediatric regulatory clearance.
- Xylooligosaccharides:Xylan-derived oligomers from agricultural residues attract sustainability-positioned brands seeking EU Green Deal compliance pathways.
- Polydextrose:Synthetic glucose polymers function as low-calorie bulking agents with partial prebiotic activity in follow-on formula applications.
Volume placements concentrate in Galactooligosaccharides; the faster expansion belongs to fermentation-derived alternatives climbing the fastest as EFSA novel food approvals accumulate.
Application:
Channel-specific regulatory burdens fragment commercial timelines—infant formula demands multi-year clinical evidence while probiotic supplements navigate lighter substantiation requirements.
- Infant Formula:First and follow-on formula compositions face mandatory prebiotic inclusion floors under China's GB 10765-2021 standards. SAMR's clinical trial mandates extend approval timelines to 4-7 years for novel HMO structures, entrenching incumbent galactooligosaccharide suppliers.
- Probiotic Supplements:Direct-to-consumer subscription models in urban China and metropolitan US markets bundle oligosaccharides with microbiome testing services. Pediatric positioning here escapes infant formula's regulatory density, allowing faster ingredient iteration.
- Baby Food:Cereal and pureed fruit applications incorporate prebiotic fibers for digestive health claims targeting 6-12 month consumption windows.
- Nutritional Supplements:Specialized pediatric formulations for premature infants or allergy management command pharmaceutical-grade purity premiums.
- Clinical Nutrition:Hospital and long-term care settings prescribe oligosaccharide-fortified enteral feeds for gut microbiome restoration in compromised pediatric patients.
Revenue concentration sits with Infant Formula; steepest expansion trajectory belongs to Probiotic Supplements as channel disintermediation accelerates.
Form:
Processing compatibility and shelf stability requirements drive form selection—spray-dried powders dominate high-volume manufacturing while liquid concentrates serve specialized clinical applications.
- Powder:Spray-dried and agglomerated formats integrate into dry-blend infant formula manufacturing with moisture specifications below 5%. Bulk handling infrastructure at DSM-Firmenich and Glycom facilities optimizes for this form factor.
- Liquid:Aqueous concentrates with preserved bioactivity target ready-to-feed formula systems and clinical nutrition compounding pharmacies.
- Granules:Free-flowing agglomerates improve dispersibility in instantized beverage applications.
- Syrup:High-solids solutions serve confectionery and flavored supplement delivery systems.
- Capsules:Unit-dose formats appear in pediatric probiotic supplements with age-appropriate dosing flexibility.
Procurement scale favors Powder; the emerging volume shift moves toward Liquid as ready-to-feed formula segments gain share.
End User:
Purchasing authority fragmentation shapes go-to-market architecture—hospital formulary committees control clinical nutrition budgets while parents drive retail pharmacy and direct-to-consumer decisions.
- Retail Pharmacies:Pharmacist-recommended probiotic supplements and specialized formula products capture parent trust in Germany, France, and Japan. OTC positioning here bypasses prescription regulatory burdens while maintaining clinical credibility signals.
- Hospitals:Neonatal intensive care units and pediatric wards specify oligosaccharide-fortified enteral nutrition for premature infant gut colonization support. Group purchasing organizations consolidate procurement across hospital networks, concentrating volume with approved supplier lists.
- Pediatric Clinics:Outpatient settings prescribe therapeutic nutrition for allergy management and failure-to-thrive interventions.
- Nutritionists:Independent practitioners recommend targeted prebiotic interventions for digestive complaints and immune support.
- Baby Care Centers:Institutional early childhood facilities incorporate prebiotic-fortified foods into group feeding programs.
Account concentration pools in Retail Pharmacies; the customer acquisition momentum shifts toward Hospitals as clinical evidence requirements tighten elsewhere.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of fermentation-derived human milk oligosaccharides concentrates in European biotechnology clusters, while consumption gravitates toward China's infant formula market and North American direct-to-consumer channels.
China
Domestic brands compete with multinationals for premium formula market share, driving oligosaccharide fortification as a differentiation vector. SAMR's GB 10765-2021 standards mandate prebiotic inclusion thresholds and multi-center infant trials for novel structures. Yangtze River Delta manufacturers secure supply contracts to meet dual-carbon sourcing preferences.
United States
Direct-to-consumer subscription models bundle oligosaccharides with microbiome testing in metropolitan markets. FDA maintains distinct approval pathways for novel ingredients in infant formula, creating fragmented access conditions. Greater Boston biotechnology clusters advance precision fermentation scale-up for pharmaceutical-grade production.
Germany
Retail pharmacies capture parent trust through pharmacist-recommended probiotic supplements and specialized formula products. EU Green Deal sourcing mandates accelerate sustainable requirements for dairy-derived prebiotic ingredients. Bavarian industrial centers host pharmaceutical-grade certification facilities serving European supply chains.
Netherlands
Dairy commodity processing infrastructure supports enzymatic conversion economics for galactooligosaccharide production. EFSA novel food assessments impose stringent preclinical and clinical evidence requirements for biotech-derived ingredients. Randstad logistics hubs coordinate bulk handling of spray-dried powder formats.
India
Emerging regulatory clarity from FSSAI on prebiotic infant food claims creates first-mover positioning opportunities. Domestic manufacturing scales lag fermentation-based supply, opening windows for import-dependent formulation. Maharashtra pharmaceutical corridors develop pediatric nutrition portfolios targeting middle-class demand expansion.
Global Oligosaccharides in Infant Nutrition Market Competitive Landscape
The competitive structure tilts toward biotechnology specialists with captive fermentation capabilities and established dairy processors with enzymatic conversion infrastructure. Two archetypes dominate: precision fermentation platforms achieving pharmaceutical-grade purity thresholds, and integrated nutrition conglomerates controlling formula manufacturing and distribution. Consolidation pressures intensify as EFSA and SAMR evidence requirements favor capital-intensive clinical trial portfolios. Capacity expansion and strategic technology licensing represent the primary competitive moves.
Within the biotechnology specialist tier, DSM-Firmenich and Glycom A/S exemplify fermentation-based production architectures. Jennewein Biotechnologie GmbH occupies a position among rare oligosaccharide structure specialists. These entities represent the shift from traditional dairy extraction toward microbial chassis optimization for human milk oligosaccharide manufacturing.
| Leading Market Players |
|---|
| Nestlé SA |
| Abbott Laboratories |
| DSM-Firmenich |
| Royal FrieslandCampina N.V. |
| BASF SE |
| BENEO |
| Glycom A/S |
| DuPont Nutrition & Biosciences |
| Jennewein Biotechnologie GmbH |
| Others |
Supply & Pricing Matrix
Lactose feedstock costs transmit directly through enzymatic conversion economics to galactooligosaccharide price tiers, while fermentation-derived human milk oligosaccharides anchor premium positioning to pharmaceutical-grade purity thresholds. Buyers in China's infant formula sector face divergent procurement economics as SAMR's GB standards force domestic brands toward certified supply contracts.
Pricing Analysis
Value-based pricing tied to clinical outcome substantiation anchors the market's premium tier, with fermentation-derived HMO structures commanding substantial markups over commodity galactooligosaccharides. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—ISO 22000 and pharmaceutical-grade tiers separate from food-grade specifications. Cost compression in standard-grade GOS intensifies because dairy commodity volatility squeezes margin stability for European enzymatic converters. Price-sensitive domestic Chinese manufacturers absorb economy-tier supply, while multinational formula brands in Germany and the Netherlands absorb premium-tier premiums for novel HMO structures.
Supply Chain Analysis
Reverse-logistics flows for expired or recalled infant formula products remain underdeveloped, creating disposal cost burdens that concentrate with manufacturers rather than distributed recovery networks. Supply concentrates in the Netherlands, Germany, and Denmark for fermentation-based HMO production, while Thailand and Indonesia anchor fructooligosaccharide feedstock processing for Chinese buyers. Raw material dependencies center on lactose whey streams, sucrose/inulin hydrolysis feedstocks, and CRISPR-optimized microbial chassis strains. Single-source vulnerability runs through precision fermentation capacity held by biotechnology specialists with captive purification capabilities. Distribution runs through bulk handling infrastructure at Randstad logistics hubs and direct-to-consumer subscription platforms in metropolitan US and Chinese markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation-based production architectures are displacing enzymatic conversion dominance across infant nutrition supply chains, with precision-fermented human milk oligosaccharides replacing legacy galactooligosaccharide fortification in premium formula positioning.
For Market Incumbents: Anchor defensive positioning through backward integration into microbial strain optimization capabilities and captive pharmaceutical-grade certification facilities. DSM-Firmenich and Glycom demonstrate how fermentation scale-up investments entrench supply relationships with multinational formula manufacturers facing SAMR's extended clinical trial timelines. Capacity addition in Bavarian industrial centers and Randstadt logistics corridors reinforces European supply security against dairy commodity volatility. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable channel for pediatric probiotic positioning outside infant formula's regulatory density. India's FSSAI regulatory clarity window creates geographic white-space before domestic manufacturing scales. Toddler nutrition extensions beyond 12-month products represent application white-space with lighter substantiation burdens. A go-to-market angle bundling oligosaccharides with microbiome testing services captures parent trust in metropolitan Chinese and US markets. For Investors and Strategic Acquirers: EFSA novel food approval accumulation for 2'-fucosyllactose and lacto-N-neotetraose structures is the leading indicator that fermentation-derived HMO economics are achieving cost parity with established GOS supply chains. The acquisition target archetype centers on biotechnology specialists with CRISPR-optimized microbial chassis and captive downstream purification capabilities, positioned for 5-10 year supply contract horizons as regulatory convergence pressures consolidate the supplier base. Practitioners should monitor SAMR's GB standards implementation pace and EFSA approval timelines for early signals of competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Single-use bioreactor advances enable DSM-Firmenich and Glycom to achieve pharmaceutical-grade HMO titers at mid-volume cost parity. |
| EFSA Novel Food Approval Pathway | Streamlined safety assessments for microbial fermentation oligosaccharides accelerate European market entry timelines for biotechnology entrants. |
| Backward Integration into Strain Development | Captive CRISPR-optimized microbial chassis capabilities reduce licensing dependency across overlapping HMO biosynthesis patent estates. |
| Direct-to-Consumer Channel Launch | Subscription models disintermediate traditional pharmacy and grocery channels for pediatric probiotic positioning in urban China and metropolitan US markets. |
| Pharmaceutical-Grade Certification Investment | ISO 22000 and FSSC 22000 audits for infant-grade facilities lock in supplier status with multinational formula manufacturers facing SAMR's stringent evidence requirements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with infant formula procurement directors, biotechnology scale-up specialists, regulatory affairs leads at fermentation suppliers, and pediatric nutrition brand managers with secondary validation. EFSA novel food assessment databases, SAMR GB standards documentation, FDA GRAS filings, and WHO Codex guideline revisions provided regulatory trajectory inputs. Bottom-up volume modeling across product type, application, and form segments triangulated against top-down market sizing from customs trade flows and industry association disclosures.
Data-stream reconciliation across supply-side capacity announcements, demand-side procurement contract disclosures, and price point observations from retail pharmacy and direct-to-consumer channels informed the analytical framework. Segmentation dimensions modeled include oligosaccharide structure type, infant formula versus probiotic supplement application, powder versus liquid form factor, and geographic regulatory cluster. CAGRs were derived from trend extrapolation of fermentation capacity buildout timelines and substitution elasticity estimates for HMO structures displacing GOS fortification. Infant trial completion rates for novel oligosaccharide structures and EFSA approval queue progression served as industry-specific forecast inputs.
Caveats apply where SAMR clinical trial timeline extensions, EFSA novel food assessment delays, or lactose commodity price shocks could materially shift the outlook. Forecasts reflect assumptions regarding regulatory convergence between WHO Codex guidelines and national infant food standards, fermentation scale-up cost reduction trajectories, and parent willingness-to-pay for gut-health positioning. Practitioners should monitor EFSA approval accumulation rates, SAMR GB standards enforcement intensity, and precision fermentation titer improvements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Canada Baby Food Market
Baby Food and Infant Formula
Second Stage Organic Infant Formula Market
Baby Food and Infant Formula
Europe Baby Food and Infant Formula Market
Baby Food and Infant Formula
Middle East and Africa Organic Baby Food Market
Baby Food and Infant Formula
North America Baby Food and Infant Formula Market
Baby Food and Infant Formula
Growing Up Milk Market
Baby Food and Infant Formula
Ready to Use Supplementary Food Market
Baby Food and Infant Formula
Baby Fruit Puree Market
Baby Food and Infant Formula
Baby Formula Market
Baby Food and Infant Formula
India Baby Food Market
Baby Food and Infant Formula
Canned Pet Food Market
Baby Food and Infant Formula
Functional Milk Replacers Market
Baby Food and Infant Formula
Infant Food Compliance Ready Fertility Input Market
Baby Food and Infant Formula
West Africa Baby Food Market
Baby Food and Infant Formula
Baby Cereal-Based Complementary Food Market
Baby Food and Infant Formula
A2 Infant Formula Market