
 Personalized Nutrition Market | 2026-2036
Personalized Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Personalized Nutrition Market Intelligence
Modular subscription bundling is pivoting how consumers assemble personalized nutrition programs. Nestlé Health Science leverages its pharmaceutical heritage to anchor clinical credibility in condition-specific formulations. ZOE differentiates through microbiome-testing integration that ties blood glucose response to meal timing recommendations. Viome Life Sciences competes on RNA sequencing depth, sustaining a technology moat in microbial transcriptomics.
Personalized nutrition denotes the formulation and delivery of dietary interventions tailored to an individual's genetic profile, microbiome composition, metabolic biomarkers, and lifestyle inputs, typically manufactured through small-batch compounding or algorithm-driven recipe generation with nutrient density specifications within five percent of target values. Its primary commercial purpose is to improve health outcomes beyond generic supplementation by matching nutrient interventions to verified biological need states. Powders and capsules dominate current form-factor revenue as they accommodate variable dosing protocols and flavor masking for functional ingredients. Online services and apps represent the fastest-expanding delivery mode, capturing margin pools through recurring data subscriptions that lock in consumer engagement beyond initial kit purchases.
The FDA oversees supplement labeling and health claim substantiation in the United States, while the EMA and national bodies such as BfArM govern novel food classifications across Europe, collectively raising compliance costs for cross-border microbiome product launches. ISO standards for genetic testing quality management further constrain market access for laboratories lacking accredited collection and analysis protocols. Stakeholders must monitor regulatory divergence between jurisdictions on whether microbiome diagnostics constitute medical devices or wellness products, as this classification determines reimbursement eligibility and channel strategy.
Market Dynamics
Wearable device proliferation is compressing feedback loops between biological data capture and dietary intervention timing, forcing nutrition platforms to rebuild their recommendation engines around real-time glucose and activity streams rather than static genetic profiles.
Growth Catalysts
- Continuous Glucose Monitor Integration:Dexcom and Abbott FreeStyle Libre data feeds enable meal-timing algorithms that adjust recommendations within hours rather than weeks. Fitness applications now ingest CGM streams as primary inputs.
- FDA Enforcement Discretion Letters:The agency's 2022 guidance on direct-to-consumer genetic health claims clarified permissible language for polygenic risk scores, reducing legal review costs for microbiome testing kits.
- Employer Wellness Subsidies:Self-insured corporations in the United States now reimburse biometric screening and personalized nutrition programs as preventive care under IRS Section 213(d) definitions.
Market Restraints
- Omega-3 and Prebiotic Input Volatility:Algal DHA and inulin prices fluctuate with marine harvest cycles and chicory root yields, compressing gross margins on condition-specific formulations.
- Laboratory Accreditation Concentration:ISO 15189-certified clinical laboratories capable of RNA sequencing concentrate in Massachusetts, California, and Switzerland, creating geographic bottlenecks for sample processing.
- Medical Device Classification Uncertainty:The FDA's pending determination on whether microbiome diagnostics qualify as Class II devices would trigger 510(k) requirements that most wellness startups cannot fund.
Strategic Opportunities
- Germany's DiGA Fast-Track Pathway:The BfArM digital health application approval process offers reimbursement codes for prescription nutrition apps, opening insured patient populations to subscription models.
- Menopause-Specific Formulation White Space:Phytoestrogen and calcium-microbiome interaction protocols remain underdeveloped relative to diabetes and fitness verticals, despite high willingness-to-pay among women aged 45-60.
- RNA Sequencing and Metabolomics Convergence:Platforms combining Viome's transcriptomic depth with mass spectrometry metabolite panels can deliver multi-omic recommendations that single-modality competitors cannot replicate.
Industry Challenges
- Bioinformatics Talent Scarcity:Computational biologists capable of integrating multi-omic datasets command salaries exceeding $180,000 in Boston and San Francisco, draining R&D budgets at mid-stage firms.
- CLIA Certification Timelines:Laboratory licensing for interstate sample processing requires 14-18 month approval cycles in New York and California, delaying product launches in high-density markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personalized Nutrition Market |
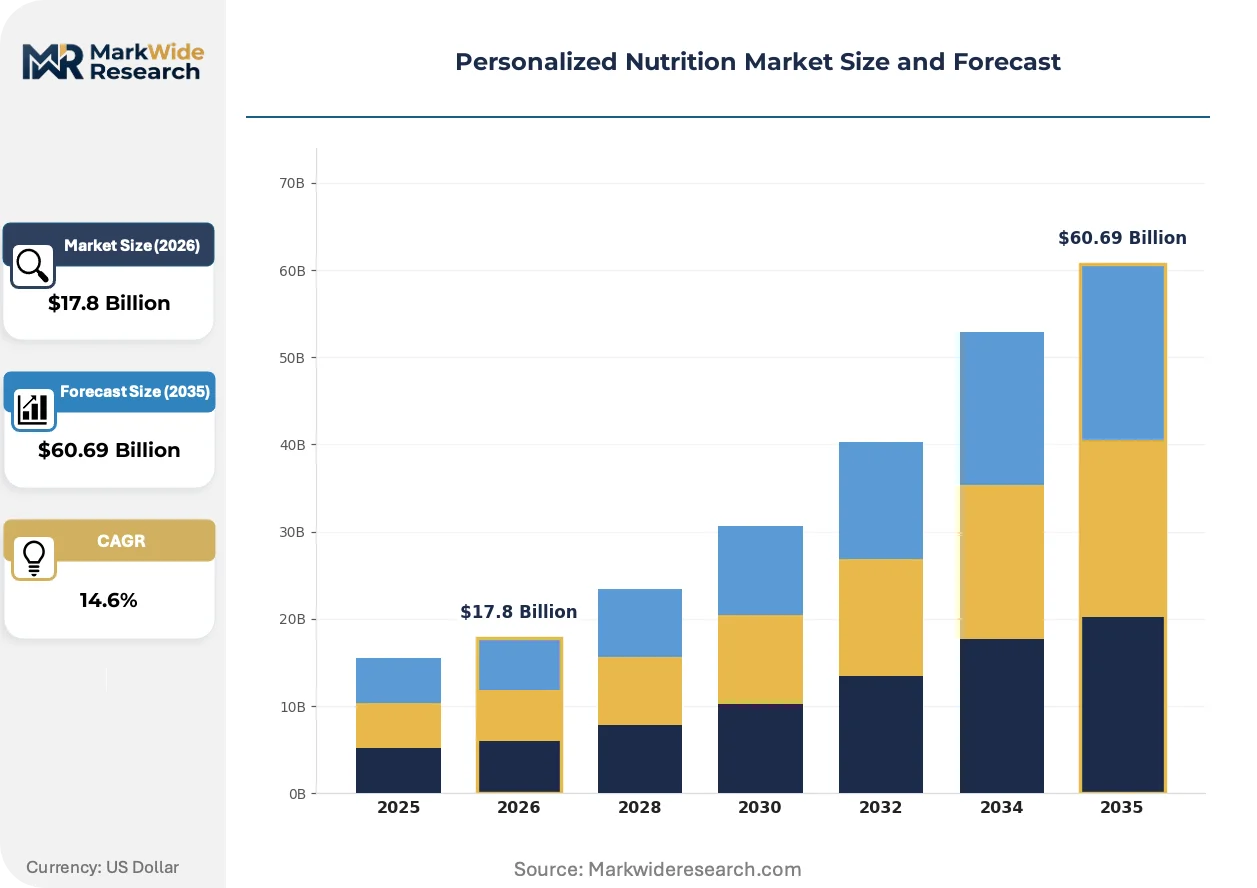
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $60.69 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Supplements, Functional Foods, Beverages End User: Individuals, Dietitians, Fitness Enthusiasts, Healthcare Providers Delivery Mode: Online Services, Apps, Retail, Personalized Plans Form: Powders, Capsules, Liquids, Bars |
| Companies Covered | Nestlé Health Science, Abbott, Viome Life Sciences, DSM, Herbalife Nutrition, ZOE, InsideTracker, 23andMe, DNAfit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personalized Nutrition Market Strategic Shifts & Innovations
Algorithmic recommendation engines are displacing static meal plans as the core product deliverable, with nutrition platforms investing in reinforcement learning architectures that improve prediction accuracy through continuous user feedback loops.
Multi-omic data fusion is unifying previously siloed genetic, microbiome, and metabolomic inputs into single inference models. Precision nutrition startups in California and Massachusetts deploy these unified pipelines to generate meal recommendations that account for glycemic response variation within individuals. The technology is compressing competitive differentiation around data integration depth rather than any single biomarker modality.
The FDA's evolving framework for dietary supplement health claims is forcing reformulation of product positioning language. Manufacturers now avoid structure-function claims that imply disease treatment, instead emphasizing "wellness support" categories that require less substantiation. Direct-to-consumer testing kits face the highest compliance burden, with several firms withdrawing polygenic obesity risk reports pending additional clinical validation.
Subscription bundling is displacing one-time test kit purchases as the dominant commercial model. Consumers in the United States and United Kingdom now expect ongoing algorithm updates and seasonal menu rotations rather than static PDF reports. This shift concentrates lifetime value in platforms capable of sustaining engagement through app-based coaching interfaces rather than initial hardware sales.
Personalized Nutrition Market Segmentation
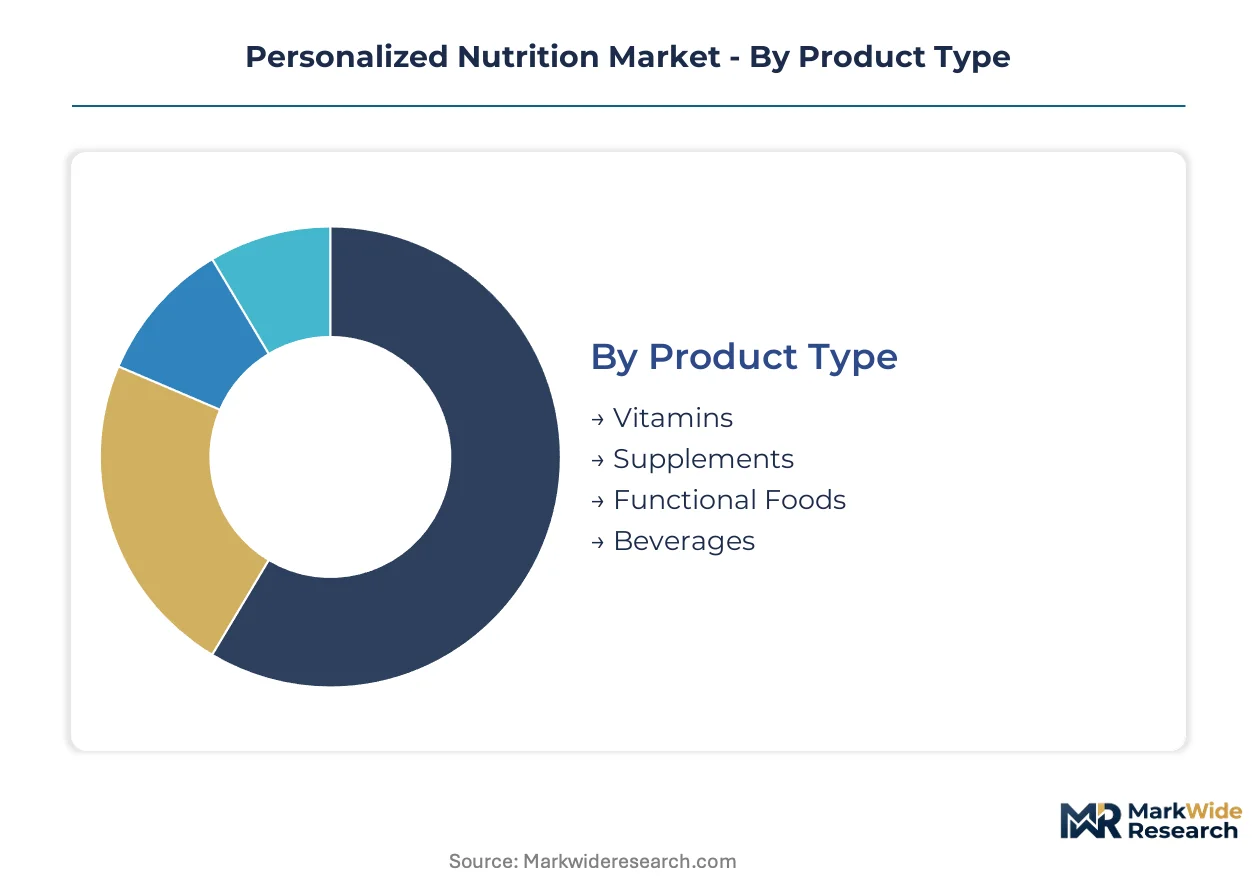
Personalized nutrition segmentation reflects divergent consumer sophistication levels and data integration capabilities. Product form and delivery channel choices determine margin structures and customer lifetime value capture. Understanding these splits enables targeted resource allocation across development, marketing, and distribution functions.
Product Type:
Vitamins command volume leadership through subscription replenishment models, while functional foods capture premium positioning through meal-replacement claims.
- Vitamins:Single-nutrient and complex formulations tailored to genetic polymorphisms in vitamin D and B12 metabolism. Demand clusters among employer wellness programs in the United States seeking measurable biomarker improvements for insurance premium reductions.
- Supplements:Condition-specific stacks combining adaptogens, nootropics, and targeted minerals. Sports nutrition verticals in California and Massachusetts drive formulation innovation through athlete biometric partnerships.
- Functional Foods:Probiotic-enriched and microbiome-modulating meal components. European markets under EFSA novel food regulations constrain speed-to-market for fermented product lines.
- Beverages:Ready-to-drink shakes with personalized macronutrient ratios. Direct-to-consumer cold-chain logistics limit geographic reach to urban corridors with same-day delivery infrastructure.
Today's leader: Vitamins. Tomorrow's challenger: Functional Foods.
End User:
Individual consumers dominate transaction volume, though healthcare provider channels unlock reimbursement pathways and clinical validation credibility.
- Individuals:Direct purchasers responding to algorithm-generated recommendations from microbiome testing platforms. CGM data integration is shifting purchase triggers from monthly schedules to real-time glucose threshold alerts.
- Dietitians:Licensed practitioners prescribing condition-specific protocols as adjuncts to medical nutrition therapy. CLIA-certified laboratory partnerships determine platform selection criteria.
- Fitness Enthusiasts:Wearable-native users demanding peri-workout timing optimization. Dexcom and Abbott data feeds enable pre- and post-exercise nutrient timing algorithms that static testing cannot match.
- Healthcare Providers:Physicians and nurse practitioners integrating nutrition into chronic disease management. FDA enforcement discretion on genetic health claims clarified permissible clinical dialogue frameworks.
Individual self-service currently captures the highest transaction frequency. Healthcare provider integration offers the steepest expansion trajectory for prescription-adjacent revenue models.
Delivery Mode:
Digital channels concentrate margin capture, while retail maintains relevance for impulse replenishment and older demographic access.
- Online Services:Subscription platforms with recurring algorithm updates and seasonal menu rotations. ZOE and Viome compete on data integration depth rather than initial kit pricing.
- Apps:Mobile-first coaching interfaces sustaining engagement through push-notification meal timing. Germany's BfArM DiGA fast-track pathway offers reimbursement codes for prescription nutrition applications.
- Retail:Pharmacy and specialty store distribution for grab-and-go replenishment. Shelf-space economics favor established CPG brands with slotting fee capacity.
- Personalized Plans:Hybrid human-coach and algorithm-delivered protocols. High-touch models command annual contract values exceeding pure digital subscriptions.
Online services anchor current revenue concentration. App-based delivery is gaining share fastest through employer wellness subsidy expansion.
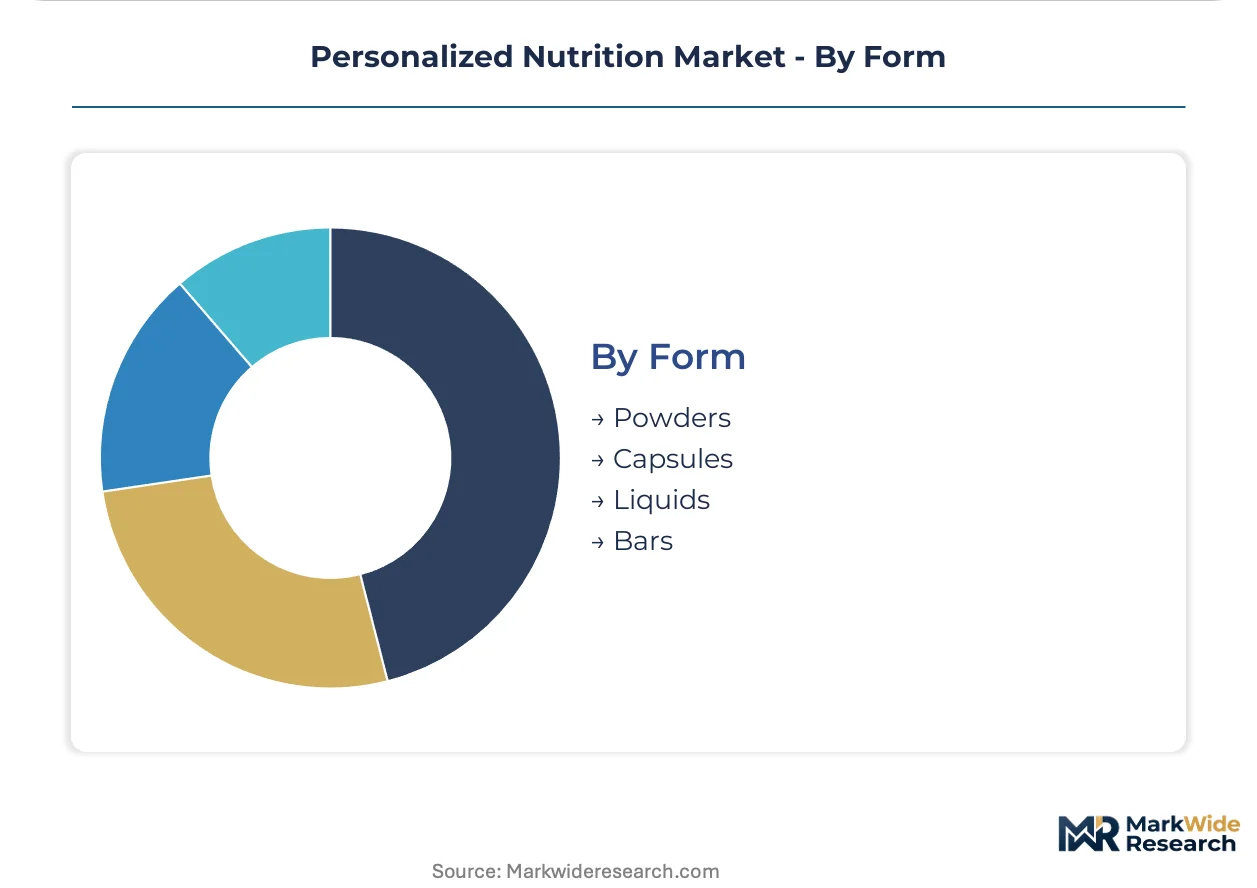
Form:
Powders and capsules accommodate variable dosing precision, while liquids and bars serve convenience-oriented consumption occasions.
- Powders:Bulk formulations enabling gram-level macronutrient customization. Flavor masking requirements drive formulation complexity for functional ingredients with bitter profiles.
- Capsules:Encapsulated single-nutrient and multi-ingredient stacks. Precise dosing protocols for genetic variants in MTHFR and APOE metabolism favor this format.
- Liquids:Liposomal and emulsified delivery systems for bioavailability enhancement. Cold-chain requirements constrain distribution to controlled logistics networks.
- Bars:Shelf-stable meal replacements with personalized protein-carbohydrate ratios. Texture and stability challenges limit micronutrient density compared to powder alternatives.
Powders dominate compounding flexibility. Capsules are climbing the fastest through travel convenience and precise dosing compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The personalized nutrition industry traces its commercial origins to the direct-to-consumer genetic testing wave that scaled through California and Massachusetts laboratories during the early 2010s. Silicon Valley venture capital funded the algorithmic infrastructure that translated biomarker data into dietary protocols. European regulators subsequently adapted pharmaceutical frameworks to accommodate microbiome diagnostics, while Asian markets imported subscription models through mobile-first platforms.
United States
Employer wellness subsidies and high consumer willingness-to-pay for DNA-based programs drive transaction density. The FDA's 2022 enforcement discretion on genetic health claims clarified permissible language for polygenic risk scores. Boston and San Francisco host ISO 15189-certified laboratories specializing in RNA sequencing for microbiome analysis.
Germany
Insured patient populations access prescription nutrition apps through reimbursement pathways. The BfArM DiGA fast-track approval process offers specific codes for digital health applications with nutritional components. Munich and Berlin clusters concentrate bioinformatics talent for multi-omic data integration platforms.
United Kingdom
Subscription bundling expectations among consumers sustain recurring revenue models for algorithm-driven meal planning. The Medicines and Healthcare products Regulatory Agency monitors borderline claims between wellness and medical device classifications. London's venture ecosystem funds microbiome-testing startups targeting glycemic response optimization.
Switzerland
Precision fermentation capabilities and pharmaceutical heritage attract condition-specific formulation investments. Swissmedic oversees novel food classifications affecting probiotic-enriched product launches. Basel and Zurich house laboratories capable of metabolomics panels for multi-omic recommendation engines.
China
Mobile health application penetration creates distribution channels for algorithmic nutrition coaching at scale. The National Medical Products Administration evaluates functional food claims under evolving supplement frameworks. Shanghai and Shenzhen clusters develop wearable data integration for real-time dietary intervention timing.
Personalized Nutrition Market Key Industry Players
Premium-margin players sit above commodity-margin players across data integration depth and clinical validation intensity. The market exhibits tiered concentration where pharmaceutical heritage anchors credibility in condition-specific formulations while technology-native startups compete on algorithmic personalization speed. Three archetypes dominate: legacy nutrition conglomerates with diagnostic partnerships, RNA-sequencing specialists with microbiome moats, and CGM-integrated platforms with real-time feedback loops. Dominant competitive moves include laboratory accreditation acquisitions and employer wellness channel partnerships.
Within the pharmaceutical heritage tier, Nestlé Health Science and Abbott exemplify incumbents leveraging clinical credibility for condition-specific protocols. ZOE occupies a position among microbiome-native platforms that tie blood glucose response to meal timing recommendations. Viome Life Sciences sits within the RNA-sequencing specialist archetype, sustaining technology differentiation through transcriptomic depth that single-modality competitors cannot replicate.
| Leading Market Players |
|---|
| Nestlé Health Science |
| Abbott |
| Viome Life Sciences |
| DSM |
| Herbalife Nutrition |
| ZOE |
| InsideTracker |
| 23andMe |
| DNAfit |
| Others |
Cost & Logistics Intelligence
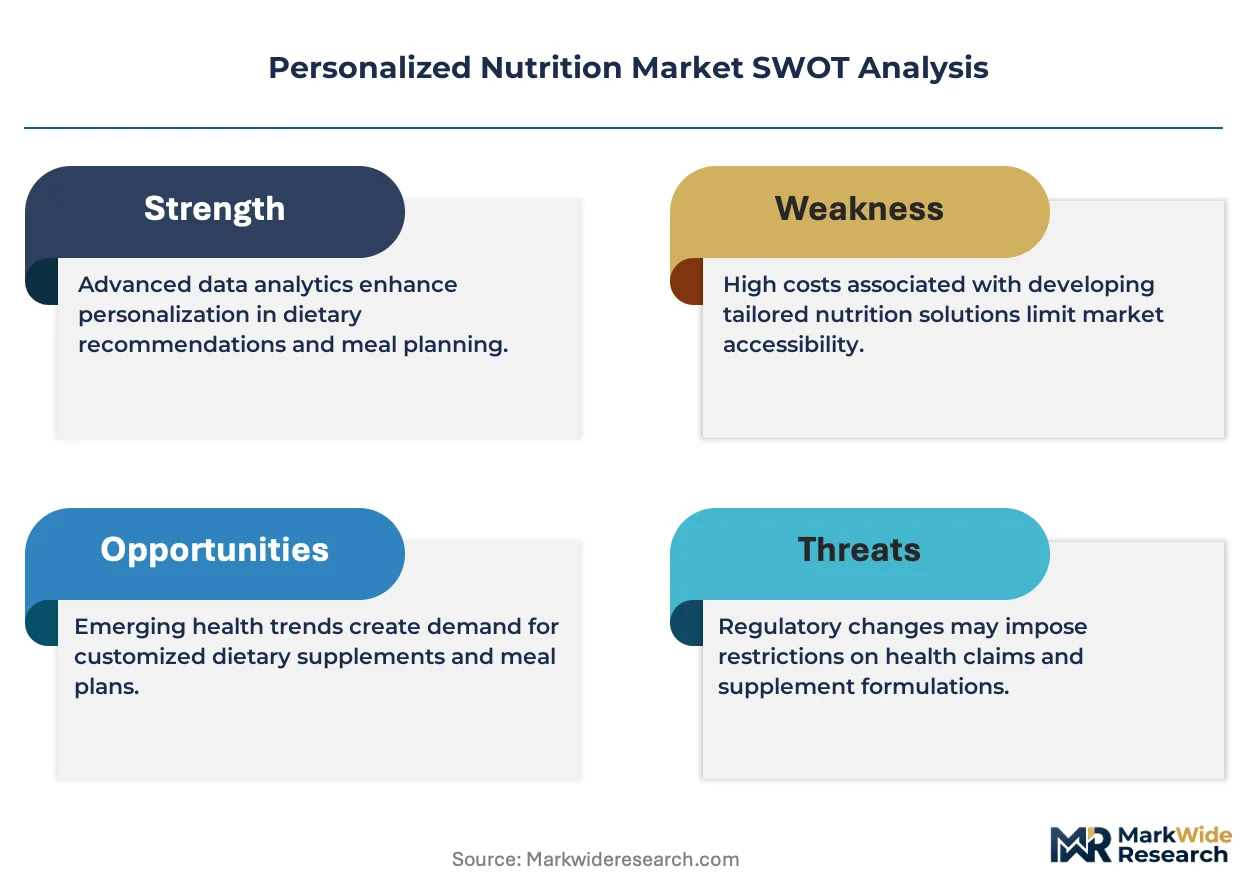
Algal DHA and inulin spot indices cascade through personalized nutrition supply chains, compressing margins on condition-specific formulations while concentrating pricing power among vertically integrated compounders with captive omega-3 fermentation capacity. Price stratification across premium, standard, and economy tiers reflects laboratory accreditation intensity and multi-omic data integration depth rather than ingredient cost alone.
Pricing Analysis
Subscription-based recurring revenue models dominate commercial architecture, with algorithm update frequency and coaching interface depth separating premium tiers from baseline offerings. Price differentiation hinges on ISO 15189 certification status and RNA sequencing depth, with employer wellness channels showing lowest price sensitivity and direct-to-consumer fitness segments experiencing acute cost compression. Pricing pressure stems from algal DHA harvest volatility and prebiotic input scarcity, forcing mid-tier platforms toward white-label manufacturing partnerships.
Supply Chain Analysis
Sample return logistics and cold-chain refurbishment flows for microbiome testing kits concentrate operational complexity in Massachusetts, California, and Switzerland, where ISO-certified laboratories cluster. Raw material dependencies span algal omega-3s, chicory-derived inulin, and synthetic vitamin precursors sourced from fermentation facilities in China and India. Single-source vulnerability in RNA sequencing reagents creates supply risk, while distribution runs through direct-to-consumer cold-chain networks and employer wellness procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's DiGA reimbursement pathway offers cost-advantaged market entry compared to FDA 510(k) device classification uncertainty in the United States, creating geographic-arbitrage value for platforms with clinical validation capacity.
For Market Incumbents: To counter CGM-integrated platform disruption, Nestlé Health Science and Abbott should deepen clinical trial infrastructure for condition-specific protocols while acquiring ISO 15189-certified laboratories in Zurich and Boston to secure sample processing capacity. Laboratory accreditation concentration represents the primary defensive moat against algorithm-native entrants. For New Entrants and Emerging Players: Menopausal women aged 45-60 represent an underserved buyer archetype with high willingness-to-pay and minimal competitive saturation relative to diabetes and fitness verticals. Phytoestrogen-microbiome interaction protocols offer white-space entry, with BfArM DiGA fast-track reimbursement enabling insured patient channel access unavailable to direct-to-consumer competitors. For Investors and Strategic Acquirers: Asymmetric upside sits with RNA-sequencing specialists possessing multi-omic data fusion pipelines, as transcriptomic depth creates irreplicable technology moats against single-modality competitors. Long-term viability over the analysis window favors platforms combining Viome-level sequencing with metabolomics partnerships; practitioners should monitor FDA Class II device determinations and employer wellness subsidy expansion as inflection triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Omic Platform Integration | Viome's RNA sequencing depth combined with mass spectrometry metabolite panels creates recommendation engines competitors cannot replicate. |
| DiGA Fast-Track Pathway Entry | BfArM reimbursement codes unlock insured German patient populations to subscription nutrition models previously limited to direct-to-consumer channels. |
| CGM Data Feed Partnerships | Dexcom and Abbott FreeStyle Libre integration enables real-time meal timing algorithms that displace static genetic profile recommendations. |
| Laboratory Accreditation Acquisition | ISO 15189-certified facilities in Massachusetts and California resolve geographic bottlenecks constraining sample processing scalability. |
| Menopause-Specific Formulation Development | Phytoestrogen and calcium-microbiome protocols address high-willingness-to-pay demographic with underdeveloped competitive presence. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with precision nutrition platform executives, CLIA laboratory directors, employer wellness benefits managers, and FDA regulatory affairs specialists with secondary validation against FDA enforcement discretion letters, BfArM DiGA approval databases, ISO 15189 accreditation registries, and EFSA novel food classification rulings. Bottom-up subscription revenue modeling and top-down addressable market sizing were triangulated against wearable device shipment data and direct-to-consumer testing kit volume estimates.
Segment-weighting approaches modeled product type splits across vitamins, supplements, functional foods, and beverages alongside end-user differentiation between individual consumers, dietitians, fitness enthusiasts, and healthcare providers. Delivery mode segmentation incorporated online services, apps, retail, and personalized hybrid coaching protocols. CAGRs were derived from algorithmic engagement retention curves and employer wellness subsidy expansion trajectories, with RNA sequencing cost decline curves and CGM penetration rates serving as technology adoption inputs across the projection horizon.
Inputs from FDA guidance documents and BfArM reimbursement code releases were available through the study window; gaps in real-time CGM data licensing terms and pending Class II device classification determinations introduce uncertainty bands around platform revenue forecasts. Practitioners should monitor employer wellness program expansion, algal DHA harvest yields, and microbiome diagnostic regulatory rulings for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Food Grade Beta-Alanine Market
Nutritional Supplements
Nutraceutical Oral Thin Films Market
Nutritional Supplements
Choline Market
Nutritional Supplements
Middle East and Africa Feed Antioxidants Market
Nutritional Supplements
Argentina Nutraceuticals Market
Nutritional Supplements
Calcium Malate Market
Nutritional Supplements
Nutrient Dense Food Products Market
Nutritional Supplements
Folate Market
Nutritional Supplements
Germany Whey Protein Market
Nutritional Supplements
Carnitine Supplements Market
Nutritional Supplements
Botanical Supplements Market
Nutritional Supplements
Throat Lozenges Market
Nutritional Supplements
North America Protein Market
Nutritional Supplements
Calcium Market
Nutritional Supplements
Diet Pills Market
Nutritional Supplements
Liquid Dietary Supplements Market