
 Infant Formula Market | 2026-2036
Infant Formula Market Size, Share, and Industry Trends Forecast 2026-2036
Infant Formula Market Intelligence
The gap between premium and commodity infant formula is broadening as ingredient sourcing, clinical validation, and packaging sophistication split the market into distinct value tiers. Nestlé leverages its global dairy supply network to sustain premium positioning across multiple continents. Danone anchors its competitive stance through specialized nutrition science and region-specific formulation expertise.
Infant formula constitutes a nutritionally engineered breast milk substitute, typically comprising demineralized whey, vegetable oils, lactose, and micronutrient fortification including iron, DHA, and ARA, manufactured through spray-drying or wet-mixing processes to achieve precise osmolality and protein ratios for neonatal digestion. Powdered formula occupies the largest volume share due to cost efficiency and extended shelf stability, while organic formula captures the fastest value growth as parental willingness to pay for certified clean-label products intensifies. DHA-enriched variants concentrate margin pools where clinical substantiation commands pricing power.
FDA in the United States enforces stringent nutrient mandates and facility registration requirements that shape product development timelines and market entry barriers. EFSA and China's SAMR impose parallel compositional standards and import certification protocols that manufacturers must navigate simultaneously. Stakeholders must monitor evolving regulatory divergence between major jurisdictions to determine where reformulation investments yield the greatest market access returns.
Market Dynamics
China's GB 10765-2021 standard revision has intensified compositional scrutiny, forcing manufacturers to reformulate protein ratios and micronutrient matrices while extending product registration timelines by 12-18 months.
Growth Catalysts
- Urbanization density:Megacities in China and India concentrate birth cohorts above replacement rates, creating localized demand surges that favor shelf-stable powdered formats.
- DHA fortification mandates:EFSA's updated guidance on long-chain polyunsaturated fatty acid claims has validated premium pricing for clinically substantiated neurodevelopment positioning.
- Spray-drying efficiency gains:Continuous processing technology reduces thermal degradation of whey proteins, improving batch consistency and lowering rejection rates at import inspection.
Market Restraints
- Dairy commodity volatility:New Zealand and EU milk powder auctions transmit price shocks directly to formula input costs, compressing margin buffers for mid-tier brands.
- Registration backlog:China's SAMR product formula registration queue creates 18-24 month entry delays for new market entrants regardless of manufacturing quality.
- Breastfeeding promotion:WHO Code implementation in 35 countries restricts marketing channels and point-of-sale placement, limiting customer acquisition tactics.
Strategic Opportunities
- Southeast Asia penetration:Vietnam and Indonesia exhibit formula consumption per capita at 40% of China's level, presenting volume expansion potential for compliant exporters.
- Organic certification pipelines:EU organic logo and USDA organic seals command 35-50% price premiums where parental clean-label sensitivity intersects with disposable income growth.
- Subscription direct-to-consumer:E-commerce platforms bypass traditional pharmacy and grocery gatekeepers, capturing recurring revenue with lower customer acquisition costs.
Industry Challenges
- Specialized regulatory affairs talent:Simultaneous compliance with FDA infant formula monographs, EU delegated acts, and GB standards requires rare cross-jurisdictional expertise that commands compensation premiums.
- Legacy ERP integration:Track-and-trace serialization mandates in China and EU conflict with decades-old manufacturing execution systems, forcing costly middleware deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infant Formula Market |
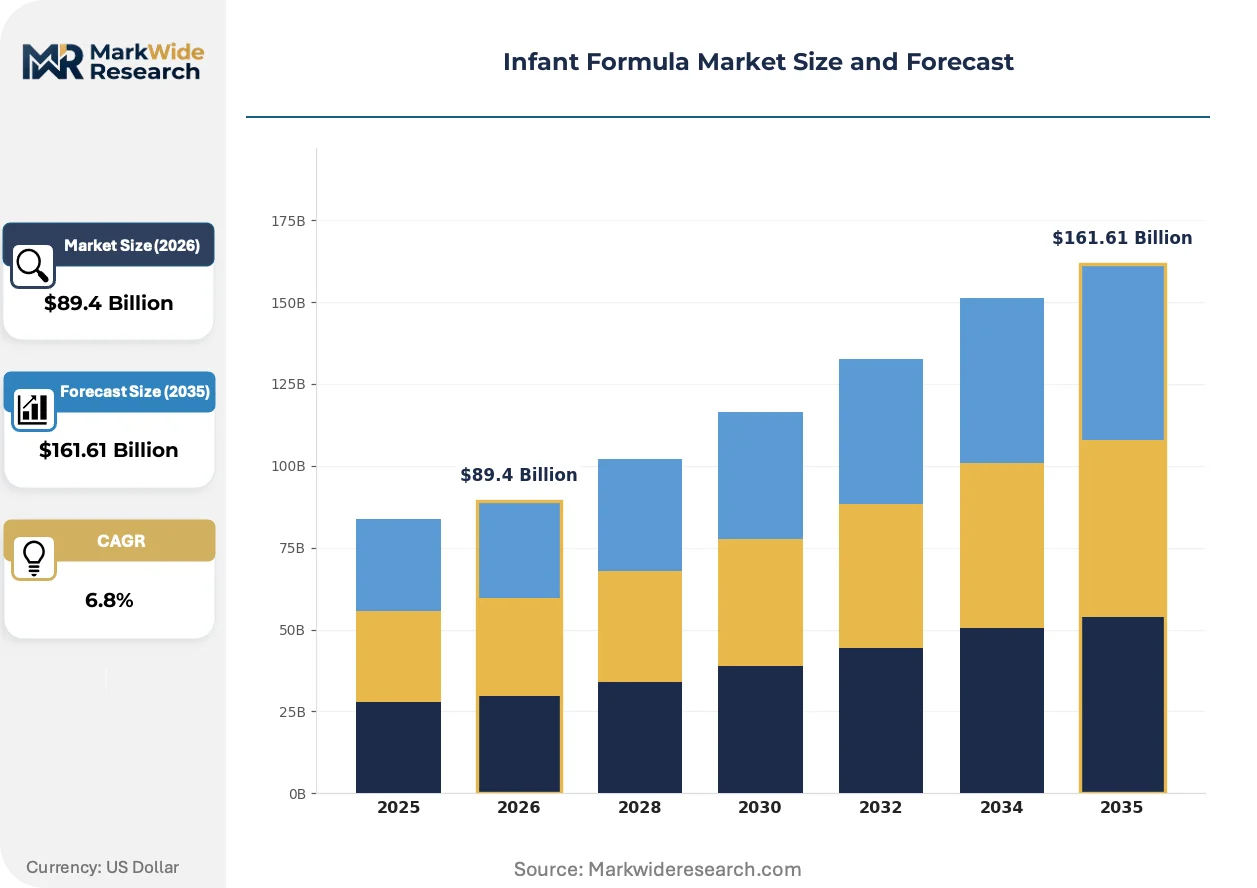
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $161.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Formula, Liquid Formula, Ready-to-Feed, Organic Formula Age Group: 0-6 Months, 6-12 Months, 12-24 Months, Special Needs Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores Nutritional Value: High-Protein, Iron-Fortified, DHA-Enriched, Probiotics |
| Companies Covered | Nestlé, Danone, Abbott Laboratories, Reckitt, Perrigo Company, FrieslandCampina, Arla Foods, Yili Group, China Feihe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infant Formula Market Strategic Shifts & Innovations
Biotechnology and precision fermentation are restructuring protein sourcing economics while regulatory divergence between major jurisdictions is fragmenting product portfolios into geography-specific SKUs.
Precision fermentation-derived lactoferrin and human milk oligosaccharides are converging with traditional dairy supply chains, enabling biosynthetic ingredients that bypass agricultural commodity cycles. Premium brands in Germany and Netherlands are piloting these inputs for hypoallergenic positioning. This convergence is compressing the cost gap between biotechnology-sourced and extracted bioactives, threatening incumbent ingredient supplier margins.
China's SAMR has implemented real-time production monitoring requirements through its infant formula traceability platform, mandating lot-level data transmission from powder blending through distribution. Manufacturers must retrofit legacy SCADA systems or face registration suspension. European exporters with centralized European manufacturing are most affected, accelerating localized production investments.
Hospital discharge sample programs are losing share to pediatrician-endorsed digital subscription trials, particularly in US urban markets where millennial parents research ingredients via mobile before first purchase. Telehealth platforms now host formula recommendation algorithms that bypass traditional retail discovery. This channel rotation is most visible in coastal US states and Australian capital cities where digital health adoption precedes national averages.
Infant Formula Market Segmentation
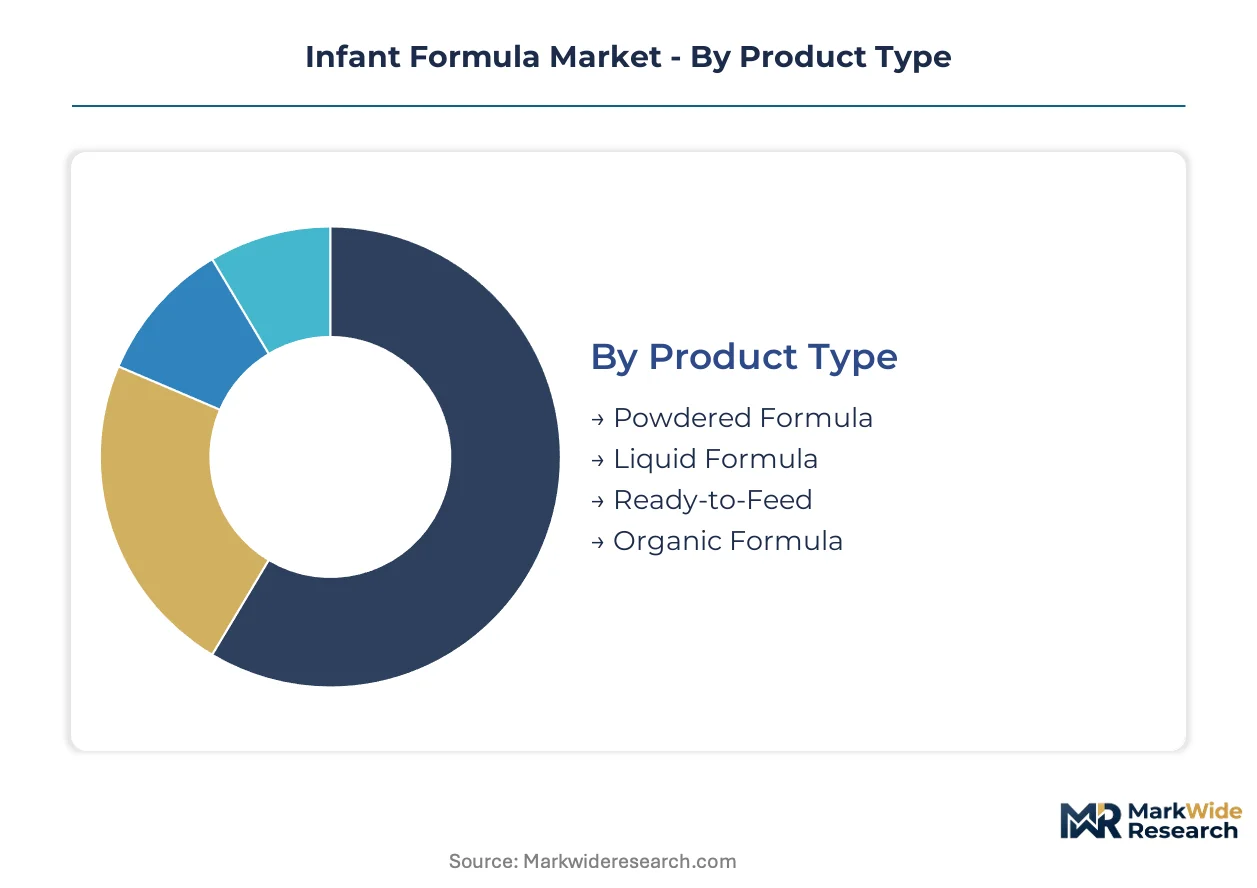
Infant formula manufacturers must navigate divergent cost structures and parental willingness-to-pay across formats and fortification levels. Segmentation reveals where margin pools concentrate versus where volume scale accumulates.
Product Type:
Powdered formats dominate total volume shipped while liquid and ready-to-feed variants capture disproportionate value per liter.
- Powdered Formula:Spray-dried or wet-mixed concentrate requiring reconstitution with water. Shelf stability and lower per-feeding cost concentrate demand in China's tier-2 cities and India's urban periphery where price sensitivity intersects with birth rate density.
- Liquid Formula:Concentrated or ready-to-dilute format in aseptic packaging. Convenience positioning commands premium pricing in US coastal metros and German urban centers where dual-income households prioritize preparation speed.
- Ready-to-Feed:Sterile single-serve bottles requiring no preparation. Travel and nighttime feeding occasions concentrate demand among high-income professionals in Singapore and Sydney.
- Organic Formula:Certified ingredient sourcing excluding synthetic pesticides and GMOs. USDA and EU organic logos validate 35-50% price premiums where parental clean-label sensitivity meets disposable income growth.
Today's leader: Powdered Formula. Tomorrow's challenger: Organic Formula.
Age Group:
Regulatory frameworks and nutritional specifications tighten progressively for younger cohorts, concentrating R&D investment and registration complexity.
- 0-6 Months:Stage 1 formulation with protein ratios mimicking colostrum and mature breast milk. SAMR's GB 10765-2021 standard mandates precise osmolality limits that extend registration timelines for entrants targeting China's first-time parents.
- 6-12 Months:Stage 2 with elevated iron and complementary feeding transition support. Volume expansion potential concentrates in Indonesia and Vietnam where per-capita consumption remains below Chinese benchmarks.
- 12-24 Months:Stage 3 and growing-up milk with reduced fat and adapted micronutrient profiles. Lower regulatory barriers attract private-label entrants in European markets.
- Special Needs:Hypoallergenic, lactose-free, and metabolic disorder-specific formulations. Prescription and pediatrician endorsement requirements limit channel access to pharmacies and hospital discharge programs.
Stage 1 registrations absorb the most regulatory capital. Stage 2 offers the steepest expansion trajectory in emerging Asian markets.
Distribution Channel:
Channel mix is fragmenting as e-commerce platforms disintermediate traditional pharmacy and grocery gatekeepers.
- Online Retail:Direct-to-consumer subscriptions and marketplace platforms. Recurring revenue models and lower customer acquisition costs concentrate investment in US and Australian markets where millennial parents research ingredients via mobile before first purchase.
- Supermarkets:Mass-market shelf placement with promotional pricing. Volume concentration persists in European markets where retail concentration favors negotiating leverage.
- Pharmacies:Professional endorsement and specialized nutritional counseling. Regulatory preference for infant formula placement concentrates channel share in Germany and France.
- Specialty Stores:Premium positioning with organic and imported assortment. China's cross-border e-commerce pilot zones and domestic premium chains attract affluent urban parents.
Pharmacies retain trust advantage for first-time purchases. Online Retail is gaining share fastest in subscription recapture.
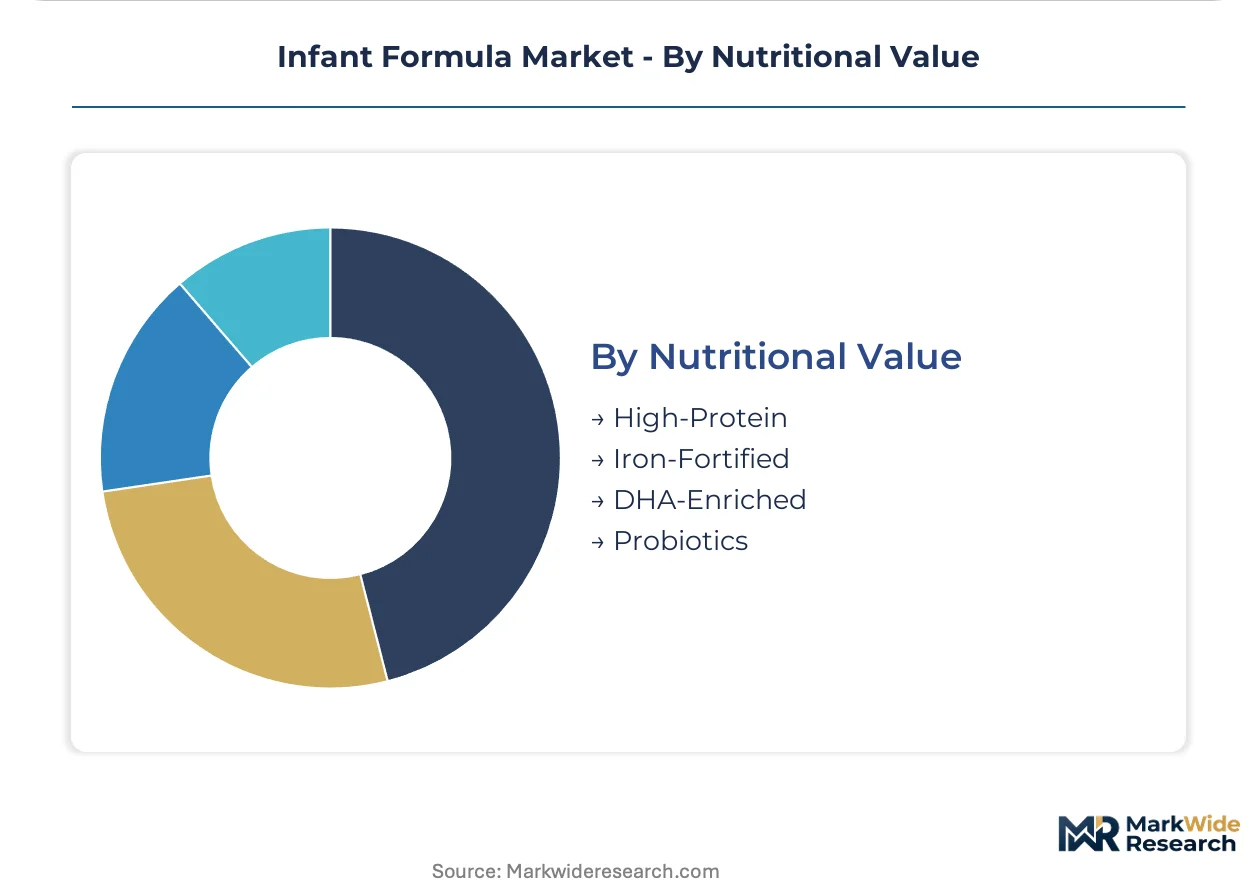
Nutritional Value:
Fortification intensity determines pricing tier and clinical substantiation requirements.
- High-Protein:Elevated whey-to-casein ratios for rapid neonatal growth phases. Formulation adjustments to meet China's revised GB protein caps have forced reformulation across multinational portfolios.
- Iron-Fortified:Critical for anemia prevention in exclusively formula-fed infants. Baseline requirement in FDA and EFSA standards limits differentiation potential.
- DHA-Enriched:Docosahexaenoic acid for neurodevelopment claims. EFSA's updated LC-PUFA guidance validated premium pricing where clinical substantiation commands margin expansion.
- Probiotics:Bifidobacterium and Lactobacillus strains for gut microbiome support. Strain-specific clinical trials required for claim permissibility in major jurisdictions.
DHA-Enriched commands the strongest pricing power. Probiotics face the steepest evidentiary burden for regulatory clearance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's formula consumption per capita towers over Southeast Asian benchmarks, while India's birth cohort density concentrates demand in entirely different consumption patterns. Regulatory divergence between these markets forces manufacturers to maintain parallel formulation portfolios.
China
SAMR's GB 10765-2021 standard revision has compressed protein ratios and mandated real-time traceability data transmission from powder blending through distribution. Tier-1 cities including Shanghai and Beijing concentrate premium and organic variant demand where parental clean-label sensitivity intersects with disposable income growth.
United States
FDA nutrient mandates and facility registration requirements shape product development timelines with stringent iron and DHA fortification baselines. Coastal metros from Boston to San Francisco favor liquid and ready-to-feed formats where dual-income households prioritize preparation speed over per-feeding cost.
Germany
EFSA compositional standards and delegated acts on long-chain polyunsaturated fatty acid claims validate premium pricing for clinically substantiated neurodevelopment positioning. The North Rhine-Westphalia industrial corridor hosts spray-drying facilities serving both domestic pharmacy channels and export markets.
Vietnam
Per-capita formula consumption sits at 40% of Chinese levels, presenting volume expansion potential for compliant exporters from EU and Oceania. Ho Chi Minh City and Hanoi concentrate urban birth cohorts above replacement rates, creating localized demand surges that favor shelf-stable powdered formats.
Australia
TGA import certification protocols and parallel China SAMR registration requirements create dual-compliance burdens for domestic manufacturers. Sydney and Melbourne millennial parents research ingredients via mobile before first purchase, accelerating digital subscription trial adoption over hospital discharge sample programs.
Infant Formula Market Key Industry Players
Top-tier vendors anchor premium positioning through clinical validation and global dairy supply networks, while mid-tier players compete on reformulation speed and regional registration expertise. The vendor base stratifies across multinational nutrition conglomerates, specialized dairy cooperatives, and emerging Asian challengers with domestic distribution depth. Three archetypes dominate: science-led specialists with pediatric research pipelines, scale-driven dairy processors with backward integration into milk powder auctions, and digital-native entrants leveraging e-commerce platform algorithms. Competitive moves concentrate on M&A for regional registration portfolios and localized production investments to bypass import inspection bottlenecks.
Within the multinational tier, Nestlé and Danone exemplify divergent strategic anchors—one leveraging global supply chain scale, the other anchoring through specialized nutrition science and region-specific formulation expertise. Among Asia-Pacific challengers, Yili Group and China Feihe occupy positions shaped by domestic GB standard compliance and tiered-city distribution penetration rather than export orientation.
| Leading Market Players |
|---|
| Nestlé |
| Danone |
| Abbott Laboratories |
| Reckitt |
| Perrigo Company |
| FrieslandCampina |
| Arla Foods |
| Yili Group |
| China Feihe |
| Others |
Cost & Logistics Intelligence
Premium-commodity bifurcation in infant formula concentrates pricing power with clinical validation holders while compressing mid-tier margins through dairy input cost volatility. This divergence manifests in supply chain configurations where biotechnology-sourced bioactives bypass agricultural commodity cycles, and real-time traceability mandates force legacy system retrofits that stratify compliance costs across manufacturer tiers.
Pricing Analysis
Capacity additions in precision fermentation facilities are reshaping price floors for DHA-enriched and hypoallergenic variants as biosynthetic lactoferrin converges with traditional dairy supply chains. Three-tier pricing structure across premium, standard, and economy levels anchors on certification grade and clinical substantiation depth, with USDA and EU organic logos validating substantial premiums. Pricing pressure stems from New Zealand and EU milk powder auction volatility transmitting directly to input costs. First-time parents in China's tier-1 cities exhibit lowest price sensitivity, while India's urban periphery concentrates volume-seeking buyers.
Supply Chain Analysis
Direct-to-pharmacy channels handle first-purchase trust requirements, while direct-to-consumer subscriptions capture recurring revenue with lower acquisition costs. Geographic supply concentration centers on New Zealand, the Netherlands, and Ireland for spray-dried whey and lactose derivatives. Raw material dependencies rest on demineralized whey powder, vegetable oil blends, and human milk oligosaccharide precursors. Single-source vulnerability in biotechnology-derived bioactives threatens margin stability as precision fermentation scales. Distribution runs through e-commerce platforms, pharmacy networks, and cross-border pilot zones with divergent serialization requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Infant formula manufacturing functions as a geographic-arbitrage play where regulatory compliance costs in China exceed Southeast Asian benchmarks by multiples, creating localized production incentives that reshape competitive entry economics.
For Market Incumbents: Deepen backward integration into precision fermentation capacity to secure biotechnology-sourced ingredient supply against agricultural commodity volatility. Fortify registration portfolios through accelerated GB 10765-2021 compliance investments before SAMR extends timelines further. Digital-native entrants leveraging subscription algorithms threaten pharmacy channel dominance; defend through pediatrician endorsement networks and hospital discharge program retention.
For New Entrants and Emerging Players: Launch via cross-border e-commerce platforms into Vietnam and Indonesia where per-capita consumption sits below Chinese benchmarks and local production compliance burdens remain lighter. Target Stage 2 formulation registrations in Ho Chi Minh City and Hanoi corridors where birth cohort density concentrates demand growth. Position through organic certification pipelines capturing parental clean-label willingness-to-pay before incumbent portfolio rotation completes.
For Investors and Strategic Acquirers: Consolidation pressure builds where SAMR registration backlogs strand capital for 18-24 months regardless of manufacturing quality, favoring acquisition of existing registration portfolios over de novo entry. Long-term viability hinges on biotechnology ingredient integration and localized production footprints bypassing import inspection bottlenecks. Target acquisition archetype: regional specialists with compliant GB registration assets and tiered-city distribution depth. Watch precision fermentation cost curves as inflection signal for bioactive ingredient economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Biosynthetic lactoferrin bypasses New Zealand dairy auction volatility for margin stability. |
| GB 10765-2021 Compliance Investment | SAMR registration acceleration prevents 12-18 month timeline extensions from reformulation mandates. |
| Direct-to-Consumer Subscription Launch | E-commerce platforms disintermediate pharmacy gatekeepers in US coastal metros and Australian capitals. |
| Southeast Asia Manufacturing Footprint | Localized production bypasses China's real-time traceability retrofit costs for Vietnam and Indonesia demand. |
| Organic Certification Pipeline Buildout | USDA and EU organic logos validate substantial price premiums where clean-label sensitivity meets income growth. |
Research Approach
Bottom-up infant consumption modeling reconciled against top-down dairy supply chain tracking forms the analytical core of this study. Primary interviews with regulatory affairs specialists, SAMR registration consultants, pediatric nutrition scientists, and e-commerce platform category managers combined with secondary validation from FDA infant formula monographs, EFSA delegated acts, SAMR registration databases, and New Zealand milk powder auction records. Triangulation between stakeholder-reported formulation timelines and customs-tracked import volumes ensures cross-verified demand estimates.
Input-output matrices segment volume and value projections across product format, age-stage formulation, distribution channel, and fortification intensity throughout the forecast period. CAGRs derive from regression analysis against birth cohort trajectories, urbanization density indices, and disposable income elasticities specific to parental purchase behavior. Industry-specific forecast inputs include SAMR registration queue dynamics and precision fermentation capacity expansion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence acceleration or biotechnology cost curve disruption. Projections reflect assumptions around breastfeeding promotion policy stability and dairy commodity auction volatility persistence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Canned Pet Food Market
Baby Food and Infant Formula
Global DHA Algae Oil for Infant Formula Market
Baby Food and Infant Formula
Infant Formula Milk Powder with A2 Beta-Casein Market
Baby Food and Infant Formula
Cow Milk Infant Formula Market
Baby Food and Infant Formula
Infant Formula Ingredients Market
Baby Food and Infant Formula
Asia-Pacific Prebiotics for Infant Formula Market
Baby Food and Infant Formula
Asia-Pacific Baby Food Market
Baby Food and Infant Formula
Baby Cereal-Based Complementary Food Market
Baby Food and Infant Formula
Baby Infant Formula Market
Baby Food and Infant Formula
Europe Baby Food Market
Baby Food and Infant Formula
Infant Nutrition Market
Baby Food and Infant Formula
A2 Infant Formula Market
Baby Food and Infant Formula
Global Oligosaccharides in Infant Nutrition Market
Baby Food and Infant Formula
Functional Milk Replacers Market
Baby Food and Infant Formula
Asia Pacific Organic Baby Food Market
Baby Food and Infant Formula
BRIC Organic Baby Food Market