
 Baby Fruit Puree Market | 2026-2036
Baby Fruit Puree Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Fruit Puree Market Analytics
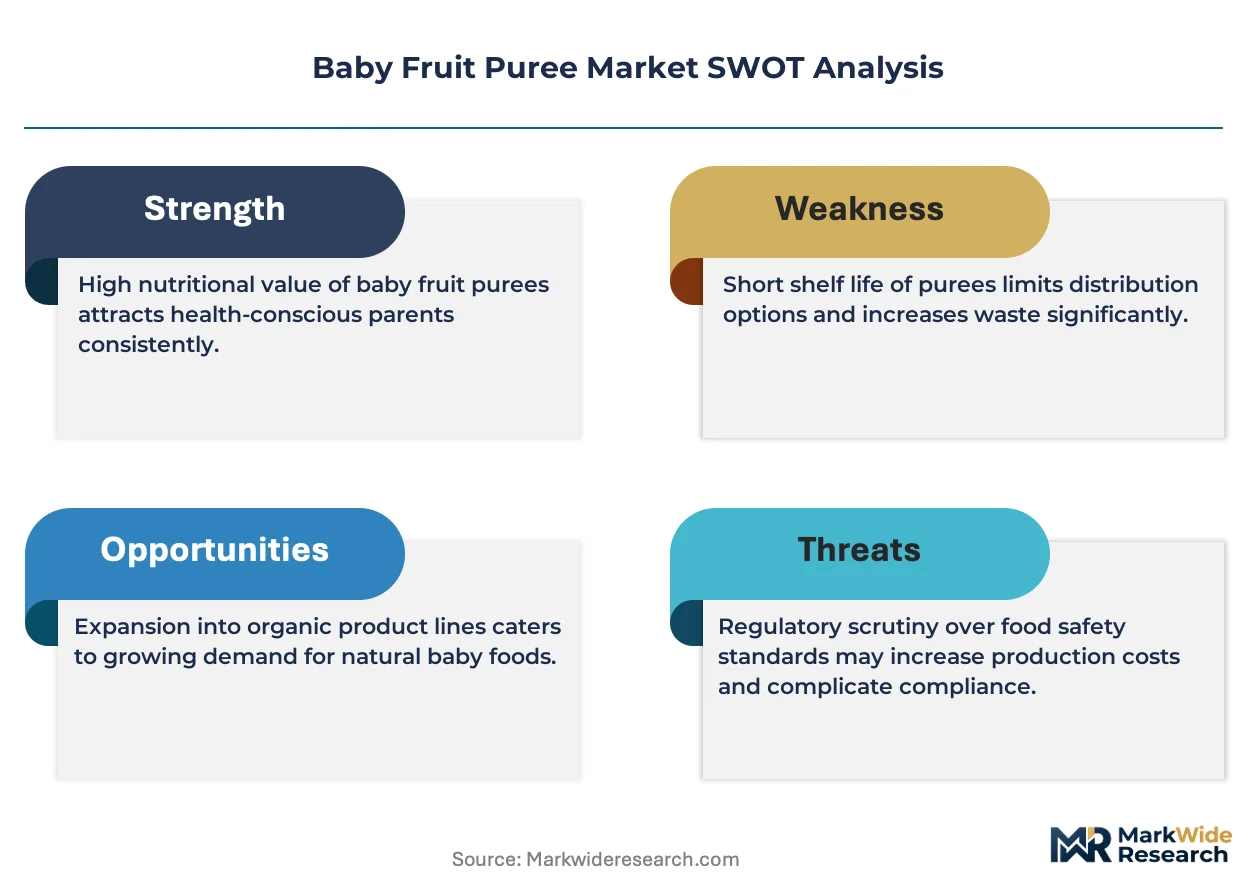
Pediatric nutrition expertise is redrawing competitive boundaries as manufacturers race to staff food scientists and infant dietitians. Gerber leverages its in-house agricultural sourcing network to secure consistent fruit supply across growing seasons. Plum Organics differentiates through flavor innovation in mixed berry and mango blends that command shelf space in premium retail channels.
Baby fruit puree consists of mechanically processed, pasteurized fruit pulp formulated for infants aged four to twelve months, typically achieving a smooth texture below three millimeters particle size and a water activity below 0.85 for shelf stability. The product serves as a transitional food delivering micronutrients during weaning while accommodating parental convenience demands. Organic formulations now lead value generation as consumers pay premiums for residue-free sourcing, while pouches displace jars as the dominant packaging format due to portability and reduced spoilage. Online retail channels capture the fastest volume growth as subscription models lock in recurring purchases from time-constrained households.
FDA oversight of heavy metal limits in infant foods, alongside USDA organic certification requirements and state-level California Proposition 65 enforcement, compels processors to invest in upstream soil testing and dual-source supply arrangements. The EU's contamination standards, referenced by exporters targeting European parents through cross-border e-commerce, add parallel compliance layers. Stakeholders must weigh organic certification costs against private-label pricing pressure while monitoring evolving heavy metal thresholds that could disqualify legacy suppliers.
Market Dynamics
Dual-income household time constraints are compressing purchase cycles toward single-serve pouch formats and subscription replenishment models that eliminate stockout risk during weekday routines.
Growth Catalysts
- USDA Organic Certification:Premium pricing tolerance for residue-free sourcing creates margin expansion for processors meeting certification thresholds. Parents in metropolitan clusters pay sustained premiums for verified supply chains.
- Pouch Packaging Technology:Retort pouch sterilization enables ambient shelf stability without refrigeration, unlocking convenience-store distribution and travel-pack occasions previously inaccessible to jarred formats.
- China:Cross-border e-commerce platforms expose middle-class parents to imported formulations, driving demand for EU-compliant heavy metal standards as a quality signal.
Market Restraints
- Apple Concentrate Volatility:Fruit input costs fluctuate with climate-driven harvest variability in Washington State and Chinese growing regions, compressing processor margins during poor yield seasons.
- FDA Heavy Metal Action Levels:Proposed arsenic and lead thresholds in rice-based and root vegetable formulations force reformulation costs and supply base changes that strain smaller processors.
- Glass Jar Substitution:Environmental preference among some parent segments retains demand for recyclable packaging, limiting complete pouch conversion and complicating line economics.
Strategic Opportunities
- India:Urban nuclear family formation and rising female workforce participation create latent demand for convenience weaning solutions in tier-1 cities where traditional home-prepared foods dominate.
- Direct-to-Consumer Subscription:Recurring revenue models with pediatric nutritionist curation lock in household lifetime value while bypassing retail slotting fee structures.
- High-Pressure Processing:Cold pasteurization technology convergence with organic sourcing preserves nutrient profiles and enables clean-label positioning without thermal degradation.
Industry Challenges
- Pediatric Dietitian Talent Scarcity:Formulation teams require specialized infant nutrition expertise that competes with clinical and pharmaceutical sectors for limited credentialed professionals.
- Dual-Source Certification Timelines:Organic and heavy metal compliance testing across multiple supplier geographies extends new product development cycles and delays seasonal flavor launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Fruit Puree Market |
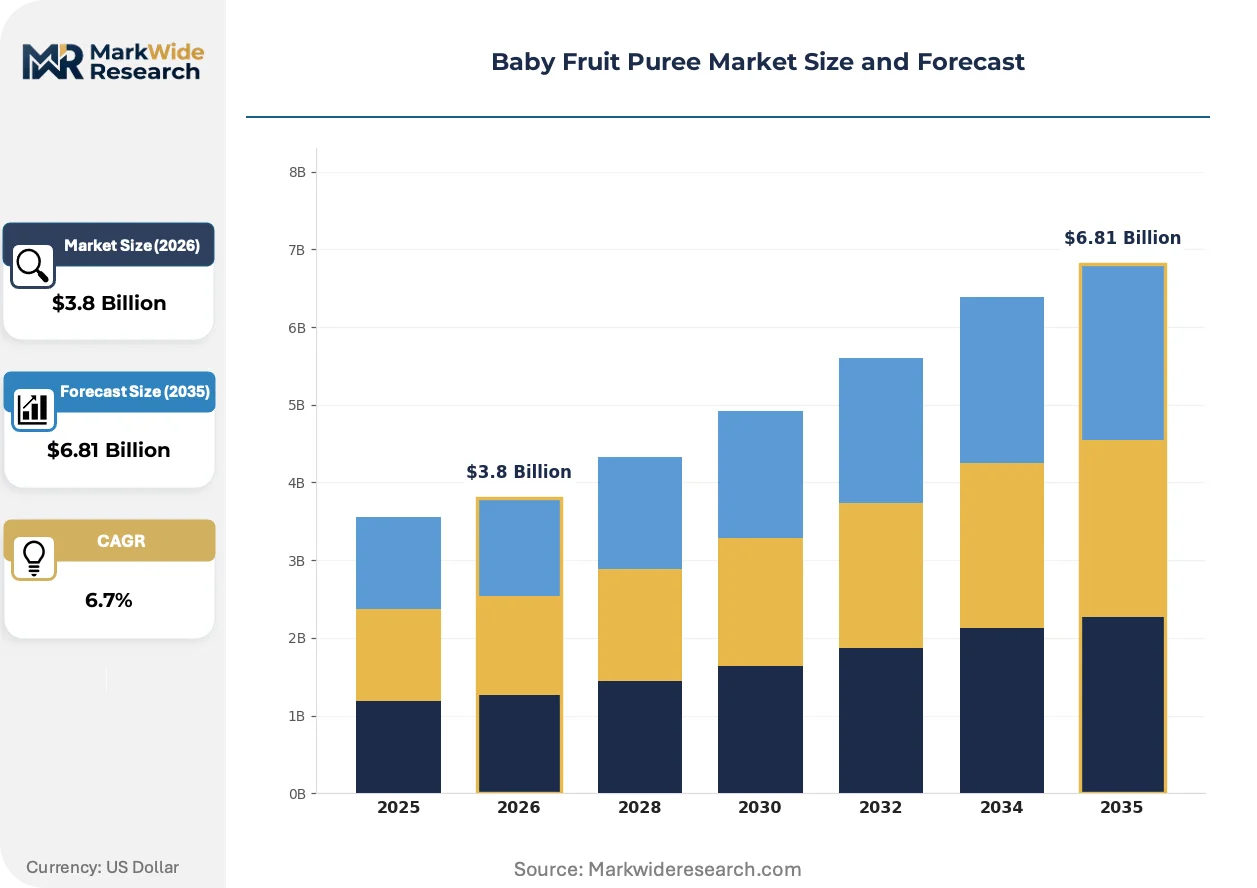
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Instant, Freeze-Dried Packaging Type: Pouches, Jars, Tubs, Tetra Packs Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores Flavor Profile: Apple, Banana, Mango, Mixed Berry |
| Companies Covered | Gerber, Beech-Nut, Plum Organics, Earth's Best, Happy Family, Döhler Group, AGRANA Beteiligungs-AG, Ingredion Incorporated, SVZ International B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Fruit Puree Market Evolving Landscape
Reformulation pressures and packaging material science are converging to reshape product architecture, with cold-chain alternatives and clean-label preservation methods gaining technical validation.
High-pressure processing is fragmenting thermal pasteurization's historical dominance in premium organic segments. Parents in coastal metropolitan markets are adopting HPP-treated fruit and vegetable blends at accelerating rates. Cold pasteurization is fragmenting the conventional shelf-stable category into ambient and refrigerated sub-segments with divergent margin structures.
REACH chemical safety standards in the European Union are tightening migration limits for packaging adhesives and printing inks. Industrial consequence includes accelerated migration testing protocols and supplier qualification costs for exporters. Pouch-format processors targeting EU parents through cross-border channels are reformulating barrier layers to meet evolving substance restrictions.
Subscription-based replenishment is compressing traditional grocery purchase cycles for time-constrained households. Direct-to-consumer platforms with AI-driven consumption prediction are displacing periodic retail stock-up trips. This behavioral shift concentrates in United States dual-income suburbs where delivery reliability outweighs price comparison.
Baby Fruit Puree Market Segmentation
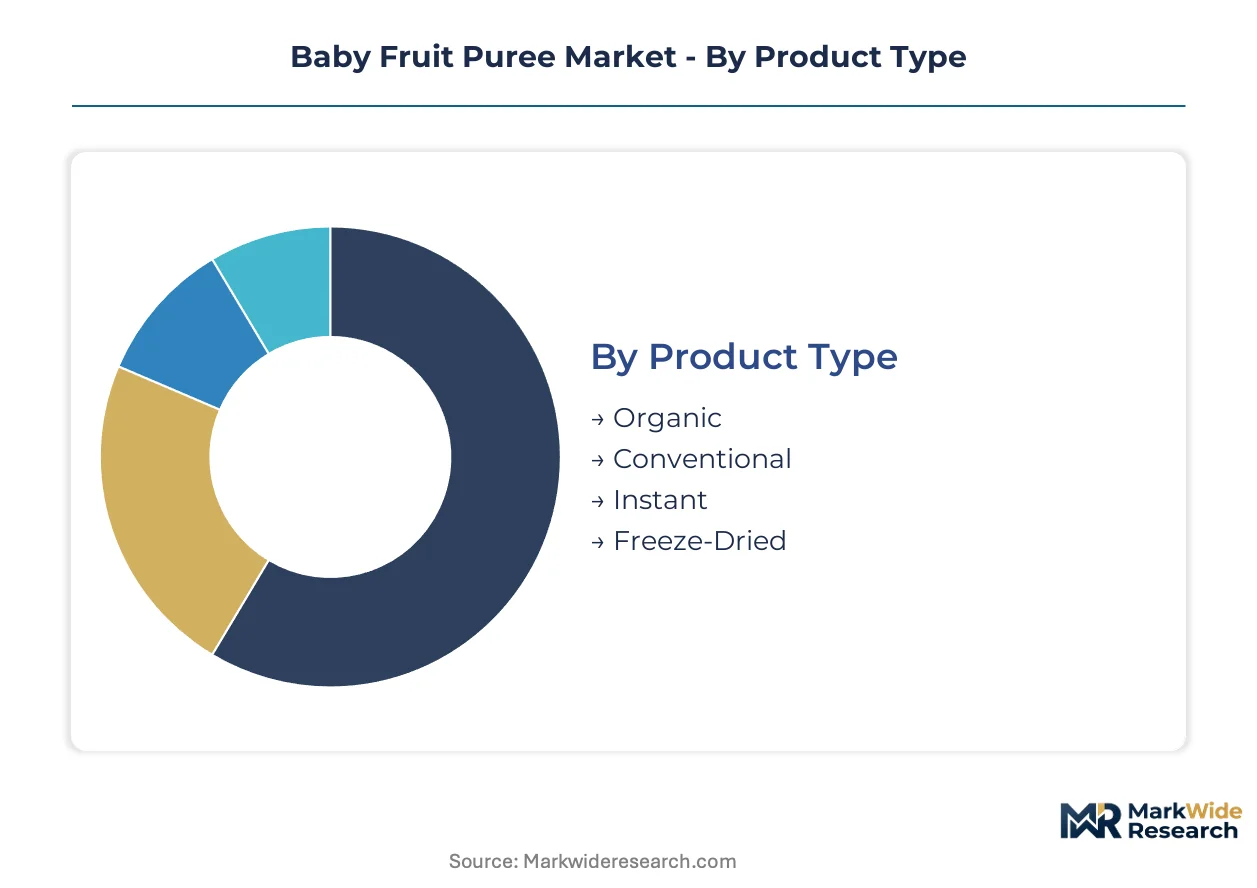
Baby fruit puree segmentation reveals how certification tiers, convenience formats, and channel preferences fragment purchasing behavior across parent demographics. Regulatory pressure on heavy metal testing and organic verification creates divergent cost structures that stratify the competitive landscape.
Product Type:
USDA organic certification and FDA heavy metal action levels create tiered compliance costs that separate residue-free formulations from conventional alternatives.
- Organic:Formulations meeting USDA NOP standards for synthetic pesticide exclusion command shelf price premiums in metropolitan retail clusters. Parents in dual-income households pay sustained markups for verified supply chains with documented soil testing and dual-source fruit procurement.
- Conventional:Standard fruit purees without organic certification rely on cost-optimized sourcing from Washington State apple growers and Chinese concentrate suppliers. Price-sensitive households in suburban markets concentrate demand here during inflationary periods.
- Instant:Powdered formulations requiring water reconstitution target travel and emergency stockpile occasions with extended ambient stability.
- Freeze-Dried:Lyophilized fruit pieces preserving enzyme activity appeal to clean-label adherents seeking minimal processing.
Conventional handles the majority of throughput; organic is climbing the fastest on share.
Packaging Type:
Retort sterilization technology and material science advances have reconfigured portability against environmental compliance trade-offs.
- Pouches:Multilayer laminated films with spout fitments enable single-hand feeding and reduced spoilage through partial consumption. Urban parents in transit-dependent cities concentrate purchases here for stroller and car seat compatibility.
- Jars:Glass containers retain preference among environmentally motivated segments seeking curbside recyclable options. European cross-border e-commerce channels sustain jar demand where REACH packaging standards restrict certain adhesive chemistries.
- Tubs:Polypropylene containers with resealable lids serve multi-serve occasions in daycare and institutional settings.
- Tetra Packs:Aseptic carton formats with straw attachments target older infant self-feeding development stages.
Pouches dominate volume movement; Tetra Packs are gaining share fastest in Asian export markets.
Distribution Channel:
Subscription logistics and last-mile delivery reliability are compressing traditional grocery purchase cycles toward digital replenishment.
- Supermarkets:Brick-and-mortar shelf space remains critical for impulse trial and coupon-driven stock-up behavior. Mass retailers in United States exurbs allocate end-cap positioning to private-label entrants.
- Online Retail:Direct-to-consumer platforms with AI-driven consumption prediction lock in recurring revenue from time-constrained households. Auto-replenishment algorithms reduce stockout risk during weekday routines.
- Specialty Stores:Boutique baby retailers curate premium organic assortments with pediatric nutritionist staffing.
- Convenience Stores:Ambient-stable pouches unlock travel-pack and emergency purchase occasions previously inaccessible to refrigerated formats.
Supermarkets maintain the largest transaction base; online retail shows the steepest expansion trajectory.
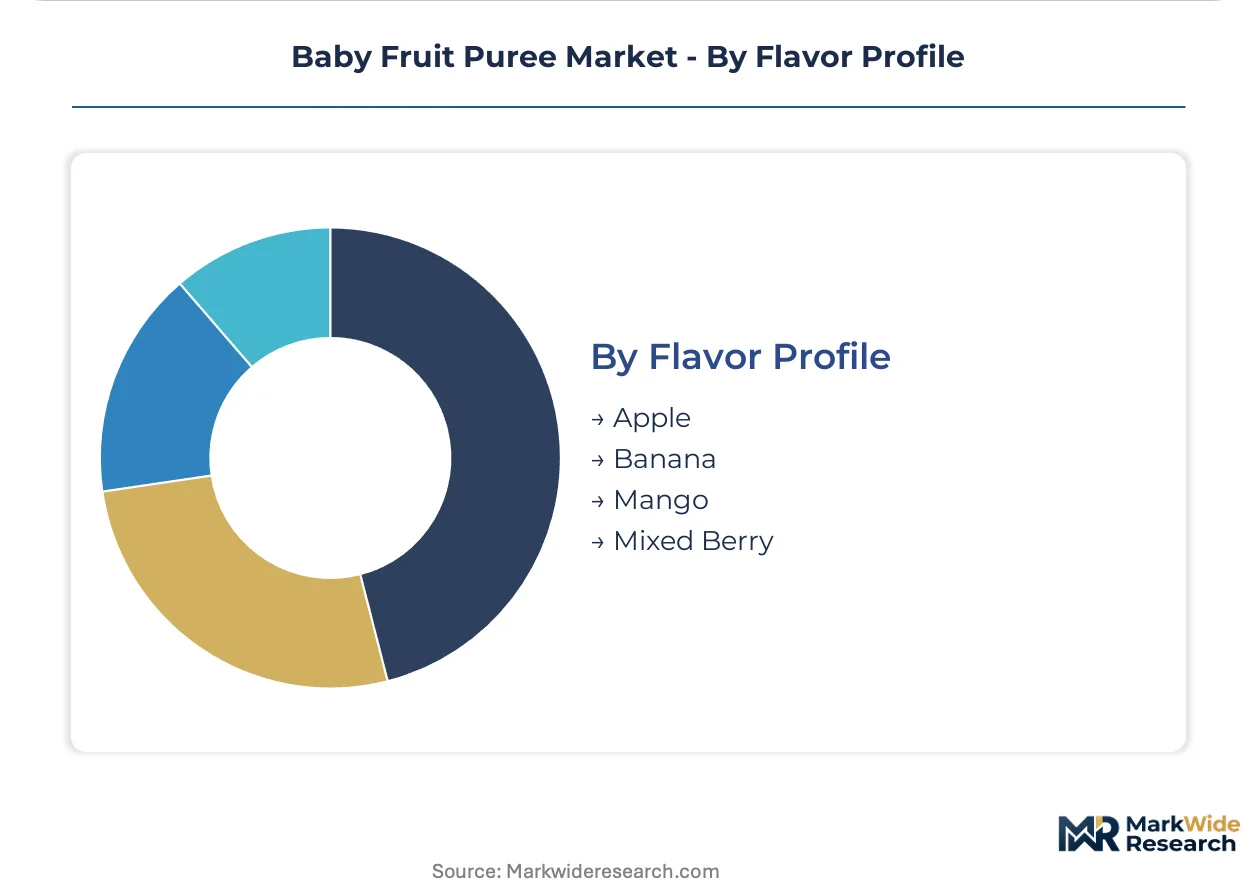
Flavor Profile:
Botanical sourcing geography and seasonal harvest windows determine supply security and formulation flexibility across fruit varieties.
- Apple:Washington State and Chinese concentrate supply chains provide year-round availability with established pasteurization protocols. Climate-driven harvest volatility in Pacific Northwest growing regions creates periodic margin compression.
- Banana:Central American and Ecuadorian sourcing networks deliver consistent brix levels for texture standardization. Cavendish crop disease pressure in Latin American plantations threatens long-term supply security.
- Mango:Indian and Mexican varietal sourcing enables seasonal rotation for flavor complexity in premium blends.
- Mixed Berry:Blueberry, raspberry, and strawberry combinations command shelf space in premium retail channels through antioxidant positioning.
Apple handles the majority of formulation volume; mixed berry is expanding most quickly on premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States metropolitan clusters where dual-income households absorb organic premiums, while Chinese cross-border channels compete on heavy metal compliance credentials rather than margin expansion.
United States
Private-label expansion at mass retailers and subscription delivery penetration in suburban markets drive volume concentration. FDA heavy metal action levels for infant foods compel processors to reformulate sourcing protocols and invest in upstream soil testing. California's Proposition 65 enforcement creates additional compliance layers for suppliers targeting coastal metropolitan clusters.
Germany
Parental preference for glass jar formats and REACH-compliant packaging sustains demand for environmentally certified supply chains. EFSA contamination standards and EU organic regulations shape formulation requirements for exporters serving German households. Bavarian retail clusters anchor organic assortment curation with pediatric nutritionist staffing in specialty channels.
China
Cross-border e-commerce platforms expose middle-class parents to imported formulations with EU-compliant heavy metal standards as quality signals. SAMR food safety supervision and GB standards for infant foods create parallel compliance frameworks for domestic and imported products. Shanghai and Beijing metropolitan areas concentrate demand for premium pouch formats through digital replenishment models.
India
Urban nuclear family formation and rising female workforce participation in tier-1 cities create latent demand for convenience weaning solutions. FSSAI food safety standards and BIS certification requirements govern domestic manufacturing and import channels. Maharashtra and Karnataka industrial corridors host emerging processing capacity targeting metropolitan parent segments.
United Kingdom
Subscription delivery models and online retail penetration reshape purchase cycles for time-constrained households in Greater London and Southeast corridors. UK Food Standards Agency oversight of infant food contaminants aligns with EU reference standards post-transition. Midlands manufacturing clusters supply private-label entrants competing with established branded portfolios.
Baby Fruit Puree Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with organic certification and cold pasteurization capabilities separating premium-positioned specialists from scale-driven commodity processors. The vendor base stratifies across three tiers: multinational infant nutrition platforms with in-house agricultural networks, regional co-manufacturers serving private-label programs, and ingredient suppliers providing fruit concentrates and purees to branded formulators. Dominant competitive moves include backward integration into controlled agricultural sourcing and direct-to-consumer subscription platform development.
Among multinational infant nutrition platforms, Gerber and Plum Organics exemplify divergent strategic archetypes within the premium tier, while Döhler Group occupies a position as a specialized ingredient and co-manufacturing partner serving multiple branded portfolios.
| Leading Market Players |
|---|
| Gerber |
| Beech-Nut |
| Plum Organics |
| Earth's Best |
| Happy Family |
| Döhler Group |
| AGRANA Beteiligungs-AG |
| Ingredion Incorporated |
| SVZ International B.V. |
| Others |
Value Network & Pricing Analysis
Scale economies in retort pouch sterilization equipment anchor supply concentration among processors running multi-line facilities, compressing unit economics for smaller competitors while establishing price floors that reflect capital recovery schedules across high-volume runs.
Pricing Analysis
The customization-premium spread separates USDA organic certified formulations from conventional alternatives, with residue-free sourcing and dual-source fruit procurement commanding sustained markups in metropolitan retail clusters. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and packaging format, with pouch convenience extracting additional premiums over glass jar equivalents. Pricing pressure stems from private-label expansion at mass retailers, eroding branded shelf space and forcing promotional intensity. Price-sensitive households in suburban exurbs concentrate demand in conventional segments during inflationary periods, while dual-income parents in urban cores absorb organic premiums with limited elasticity.
Supply Chain Analysis
Inventory lead times for organic fruit concentrates extend seasonal procurement windows, compelling processors to secure forward contracts before Washington State and Chinese harvest cycles. Geographic supply concentration centers on Washington State apple growers, Chinese concentrate suppliers, and Central American banana plantations for base formulations. Raw material dependencies include apple concentrate, banana puree, and mango pulp from Indian and Mexican varietal rotations. Single-source vulnerability in Cavendish banana networks threatens long-term supply security as crop disease pressure intensifies across Latin American plantations. Distribution runs through mass retail shelf-space allocation, direct-to-consumer subscription platforms, and cross-border e-commerce channels serving Chinese middle-class parents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against home-prepared weaning foods and fresh fruit blending appliances that threaten processed puree relevance among time-abundant households.
For Market Incumbents: Shield market position by deepening backward integration into controlled agricultural sourcing networks that secure consistent fruit supply across growing seasons and buffer climate-driven harvest volatility. Prioritize pediatric dietitian staffing investments that differentiate formulation expertise from commodity processors, as specialized infant nutrition talent scarcity constrains competitor replication. Defend against private-label encroachment by locking subscription replenishment relationships with AI-driven consumption prediction that reduces household stockout risk. For New Entrants and Emerging Players: Differentiate on cold pasteurization technology convergence with organic sourcing, capturing clean-label adherents in coastal metropolitan markets where minimal processing commands shelf space premiums. Target tier-1 Indian cities where urban nuclear family formation and rising female workforce participation create latent demand for convenience weaning solutions against traditional home-prepared food dominance. Pursue direct-to-consumer launch with pediatric nutritionist curation that bypasses retail slotting fee structures and locks recurring revenue. For Investors and Strategic Acquirers: Co-manufacturing specialists with dual-source organic certification capabilities and established FDA compliance protocols represent priority acquisition targets, as regulatory testing timelines extend new product development cycles and strain smaller processors. Long-term viability hinges on subscription platform infrastructure and cold-chain logistics networks that capture behavioral shift toward digital replenishment. Watch FDA heavy metal action level enforcement as the inflection indicator that disqualifies legacy suppliers and concentrates share among compliance-invested processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled Agricultural Sourcing | Secures consistent fruit supply across Washington State and Chinese growing seasons while buffering climate-driven harvest volatility. |
| Direct-to-Consumer Subscription Platform Launch | Locks recurring revenue from time-constrained dual-income households with AI-driven consumption prediction algorithms. |
| High-Pressure Processing Technology Adoption | Captures premium organic segments with clean-label positioning through cold pasteurization that preserves nutrient profiles. |
| Pediatric Dietitian Team Expansion | Differentiates formulation expertise from commodity processors as specialized infant nutrition talent scarcity intensifies. |
| Dual-Source Organic Certification Investment | Buffers against FDA heavy metal action level enforcement that threatens to disqualify single-source legacy suppliers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA enforcement actions, USDA organic certification databases, and Nielsen retail audit data, combining structured interviews with infant food brand managers, category buyers at mass retailers, pediatric nutritionists, and co-manufacturing procurement leads with bottom-up and top-down triangulation across trade flow records and customs declarations.
Segmentation dimensions modeled span product type certification tier, packaging format technology, distribution channel structure, and flavor profile sourcing geography across the analysis window. CAGRs derive from regression analysis against demographic drivers including dual-income household formation rates and female workforce participation patterns, with forecast inputs incorporating FDA heavy metal threshold evolution and REACH packaging standard migration limits.
Material uncertainties — regulatory threshold revisions, climate-driven harvest volatility, and cross-border e-commerce policy shifts — sit outside the modeled envelope, with outputs reflecting documented assumptions rather than deterministic predictions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Infant Formula Milk Powder with A2 Beta-Casein Market
Baby Food and Infant Formula
Europe Baby Food Market
Baby Food and Infant Formula
Organic Infant Formula Market
Baby Food and Infant Formula
Asia-Pacific Baby Food Market
Baby Food and Infant Formula
Hypo Anti Allergic Baby Food Market
Baby Food and Infant Formula
Infant Nutrition Market
Baby Food and Infant Formula
BRIC Organic Baby Food Market
Baby Food and Infant Formula
Middle East and Africa Organic Baby Food Market
Baby Food and Infant Formula
Fortified Pet Food Market
Baby Food and Infant Formula
Japan Baby Food and Infant Formula Market
Baby Food and Infant Formula
Parenteral Formula Market
Baby Food and Infant Formula
Infant Formula Ingredients Market
Baby Food and Infant Formula
A2 Infant Formula Market
Baby Food and Infant Formula
Ready to Use Supplementary Food Market
Baby Food and Infant Formula
Global DHA Algae Oil for Infant Formula Market
Baby Food and Infant Formula
Baby Cereal-Based Complementary Food Market