
 Baby Formula Market | 2026-2036
Baby Formula Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Formula Market Insights
The baby formula sector is consolidating around a sharp divergence between premium hypoallergenic and organic offerings and commodity standard formulations. Nestle S.A. leverages its global dairy supply chain to sustain cost advantages across mass-market powdered segments. Danone S.A. specializes in medical nutrition and hypoallergenic products, competing on clinical credibility rather than price. Abbott Laboratories anchors its position through hospital channel relationships and metabolic disorder formulations.
Baby formula denotes a manufactured breast milk substitute formulated from modified cow's milk or plant proteins, fortified with lipids, carbohydrates, vitamins, and minerals to meet infant nutritional requirements, typically processed through spray-drying or liquid sterilization to achieve microbiological safety. Its primary commercial purpose is to provide complete nutrition for infants from birth through twelve months when breastfeeding is unavailable or insufficient. Powdered formula occupies the largest volume share due to shelf stability and lower logistics costs, while ready-to-feed liquid commands premium pricing in convenience-oriented channels. Organic and hypoallergenic ingredient types capture expanding margin pools as parental willingness to pay for certified formulations rises.
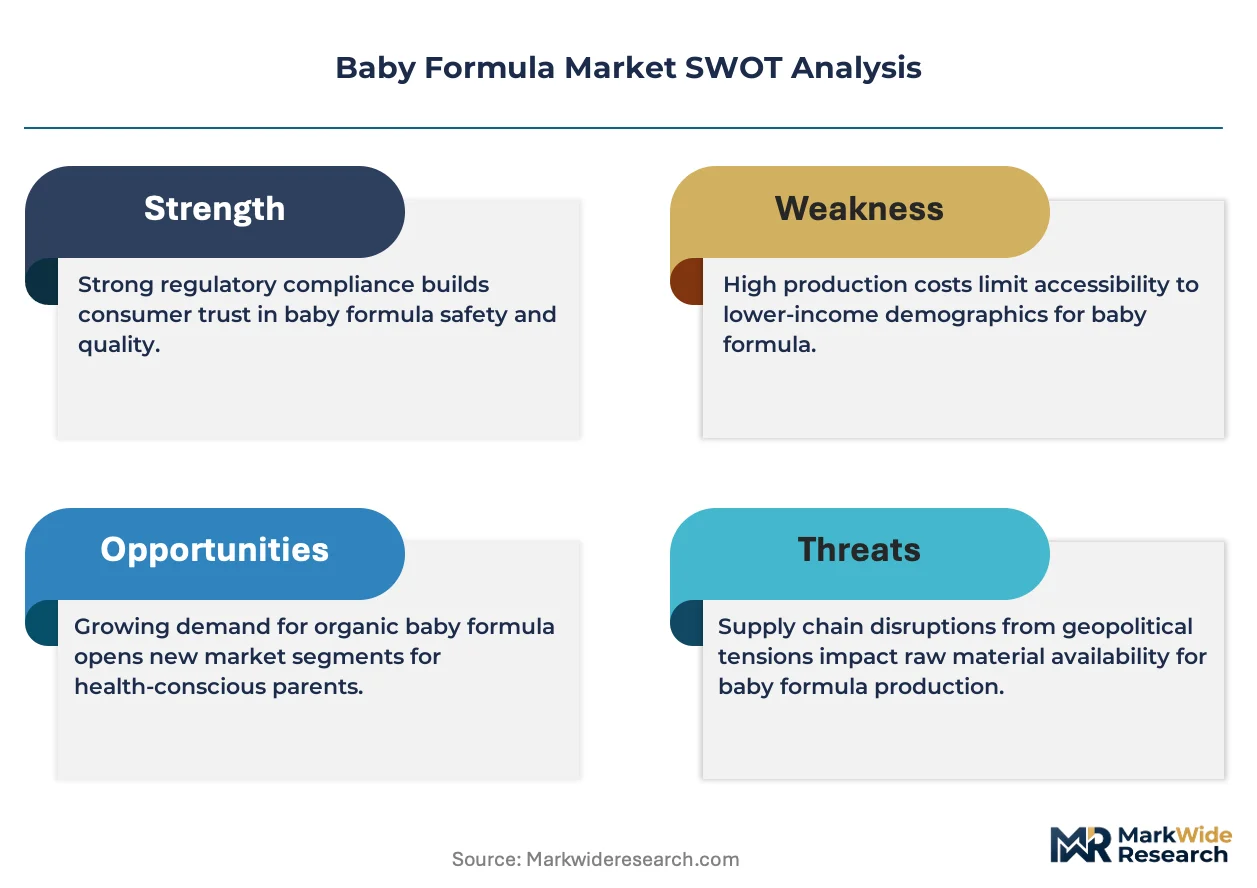
FDA enforces infant formula quality and nutrient specifications under the Federal Food, Drug, and Cosmetic Act, requiring pre-market notification and adherence to Good Manufacturing Practices. EFSA and China's SAMR impose parallel compositional standards, creating a fragmented compliance landscape for multinational manufacturers. WHO's International Code of Marketing of Breast-milk Substitutes restricts promotional claims, constraining brand communication strategies in emerging markets. Stakeholders must monitor evolving national food safety standards and channel-specific labeling requirements to maintain market access across jurisdictions.
Market Dynamics
China's updated national food safety standards for infant formula are forcing reformulation investments across multinational portfolios while dual-income households accelerate format migration toward ready-to-feed convenience.
Growth Catalysts
- Dual-income household penetration:Working parents in China and India prioritize time-saving liquid formats over powdered alternatives. Urban density and retail pharmacy expansion support this channel shift.
- GB 10765-2021 standards:China's revised infant formula regulations mandate stricter protein and carbohydrate specifications. Manufacturers must reformulate to maintain SAMR registration and shelf access.
- Clinical nutrition protocols:Hospital discharge programs for premature infants standardize specialized metabolic formulations. Medical channel endorsement drives parental trust and repeat purchase.
Market Restraints
- Dairy commodity volatility:Whey protein concentrate and lactose prices fluctuate with New Zealand and EU milk powder auctions. Input cost instability compresses margin on standard formulations.
- Single-source ingredient dependence:DHA and ARA fatty acids concentrate among three global suppliers. Geopolitical friction or contamination events threaten formulation continuity.
- GB standards compliance lag:Foreign manufacturers face 12-18 month registration timelines with SAMR. Extended approval windows delay product launches versus domestic competitors.
Strategic Opportunities
- India's organized retail gap:Modern trade and e-commerce penetration in tier-2 cities remains below 35%. First-mover brands can establish direct-to-parent subscription models before infrastructure matures.
- A2 protein certification:Consumer willingness to pay premiums for verified beta-casein sourcing creates margin expansion. Genetic testing of dairy herds enables supply-side differentiation.
- Pharmacy channel integration:Cross-merchandising with pediatric probiotics and vitamin D builds basket economics. Retail pharmacy chains seek exclusive formulation partnerships.
Industry Challenges
- Formulation scientist scarcity:Expertise in lipid microencapsulation and protein hydrolysis concentrates among aging cohorts. Universities lack specialized infant nutrition curricula.
- Clean-label certification timelines:USDA Organic and EU Organic conversions require 36-month pasture transitions for dairy suppliers. Certification lag constrains portfolio pivots.
- Legacy ERP integration:Batch record systems from acquired regional brands resist harmonization with centralized quality management platforms. Data fragmentation complicates recall protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Formula Market |
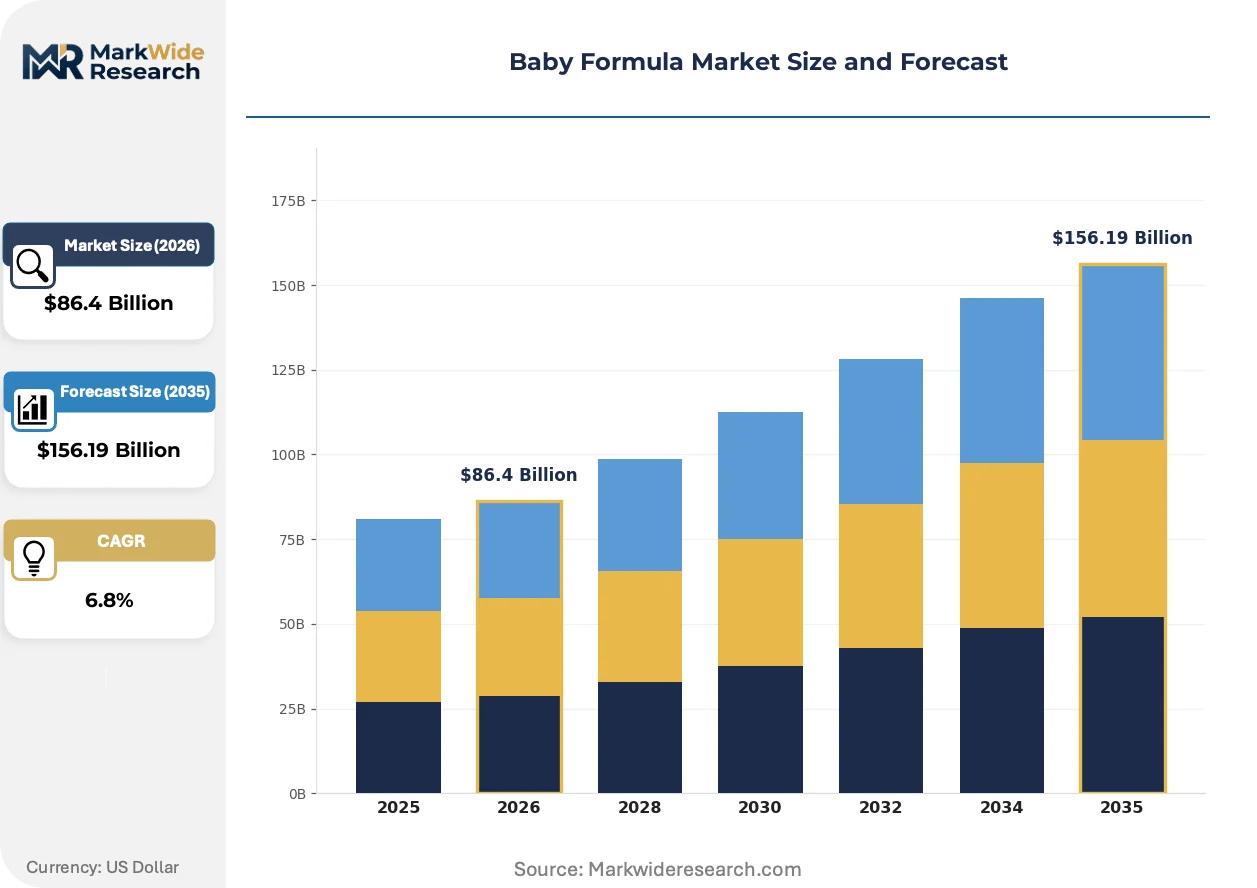
| Market Size in 2026 | $86.4 Billion |
| Market Size in 2035 | $156.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered, Liquid, Concentrate, Ready-to-Feed Ingredient Type: Organic, Non-GMO, Standard, Hypoallergenic Packaging Type: Tin Can, Pouch, Bottle, Carton Distribution Channel: Supermarkets, Online Retail, Pharmacies, Convenience Stores |
| Companies Covered | Nestle S.A., Danone S.A., Abbott Laboratories, Reckitt Benckiser Group PLC, Perrigo Company plc, FrieslandCampina, Arla Foods, Yili Group, Mead Johnson Nutrition Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Formula Market Trends and Innovations
Precision fermentation and cell-cultured dairy proteins are rewriting ingredient sourcing economics while regulatory scrutiny intensifies on marketing claims and environmental disclosures.
Precision fermentation platforms from Perfect Day and Remilk are rewriting whey and casein production economics by decoupling protein supply from herd agriculture. Specialty ingredient divisions at Nestle and Danone are evaluating these inputs for hypoallergenic lines where conventional dairy allergen control proves costly. The technology is rewriting cost structures for manufacturers facing pastureland constraints and methane emission accounting.
EFSA's updated guidance on health claims for infant formula restricts references to immune support and cognitive development without clinical trial dossiers. Manufacturers must retire legacy packaging language or invest in pediatric intervention studies. The regulation most affects European premium brands that built positioning on developmental benefit assertions.
Subscription-based replenishment models through pediatrician-endorsed apps are displacing supermarket impulse purchases among first-time parents. These platforms capture feeding pattern data to predict consumption and automate delivery. The shift concentrates in South Korea and urban China where smartphone penetration and logistics density support just-in-time fulfillment.
Baby Formula Market Segmentation
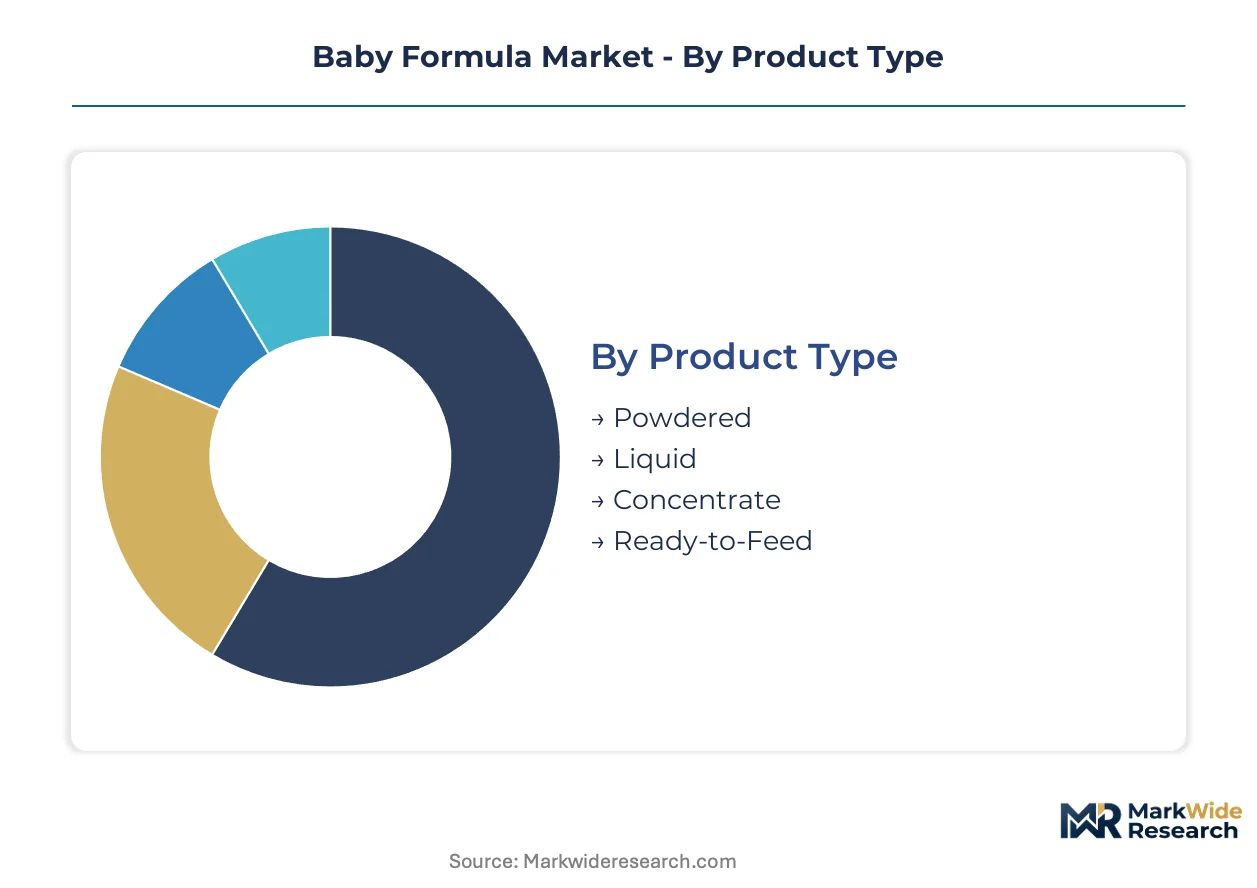
Segmentation in baby formula reveals how capital allocation, regulatory compliance, and channel economics fragment the addressable market. Manufacturers must prioritize segments where formulation complexity and distribution infrastructure create sustainable competitive moats.
Product Type:
Capital intensity varies sharply across production formats, with liquid sterilization requiring aseptic filling lines that powdered processing avoids entirely.
- Powdered:Spray-dried formulations achieve microbiological safety through heat treatment rather than terminal sterilization. Demand concentrates in rural India and tier-3 Chinese cities where cold chain infrastructure remains underdeveloped and price sensitivity dominates purchase decisions.
- Ready-to-Feed:Aseptic liquid packaging demands retort or UHT systems with validation protocols exceeding powdered lines by 40-60% in capital expenditure. Urban dual-income households in Shanghai and Seoul drive adoption where convenience premiums offset per-ounce cost multiples.
- Liquid:Concentrated liquid formats require refrigerated distribution and shorter shelf lives, limiting geographic reach to mature cold chain corridors.
- Concentrate:Dilution-required formats occupy a narrowing niche between powdered economy and ready-to-feed convenience, with demand tethered to cost-conscious parents in transitional economies.
Most installed capacity flows through Powdered. Expansion is steepest in Ready-to-Feed.
Ingredient Type:
Margin structures diverge based on certification burden and raw material traceability requirements, with organic and hypoallergenic commanding 2-4x ingredient costs versus standard formulations.
- Standard:Modified cow's milk bases with commodity whey and lactose sourcing dominate volume production. Cost volatility at New Zealand GlobalDairyTrade auctions directly compresses margin on these formulations.
- Hypoallergenic:Extensively hydrolyzed proteins and amino acid-based formulations require dedicated production lines with allergen cleaning protocols. Clinical channel endorsement through hospital discharge programs in Germany and Japan sustains premium pricing despite manufacturing complexity.
- Organic:USDA and EU Organic certification demands 36-month pasture conversion for dairy suppliers, constraining supply elasticity and locking in premium positioning.
- Non-GMO:Identity-preserved supply chains for soy and corn-derived carbohydrates add traceability costs without the full certification burden of organic standards.
Volume leadership sits with Standard. Value expansion concentrates in Hypoallergenic.
Packaging Type:
Packaging format selection determines shelf life, logistics density, and retail channel access, with metal and flexible formats requiring distinct supplier ecosystems.
- Tin Can:Three-piece welded cans with nitrogen flushing provide 24-month shelf stability for powdered formats. Asian retail infrastructure retains heavy reliance on this format for humidity protection in tropical climates.
- Pouch:Flexible retort pouches reduce shipping cube by 60% versus rigid alternatives but require specialized filling equipment. South Korean and Chinese e-commerce channels favor this format for subscription replenishment models.
- Bottle:PET and HDPE bottles dominate ready-to-feed liquid presentation, with aseptic blow-fill-seal lines representing concentrated capital deployment.
- Carton:Gable-top and brick cartons for liquid concentrates align with dairy industry packaging conventions but struggle to differentiate on premium shelves.
Tin Can retains the largest installed base. Pouch is climbing the fastest in new capacity additions.
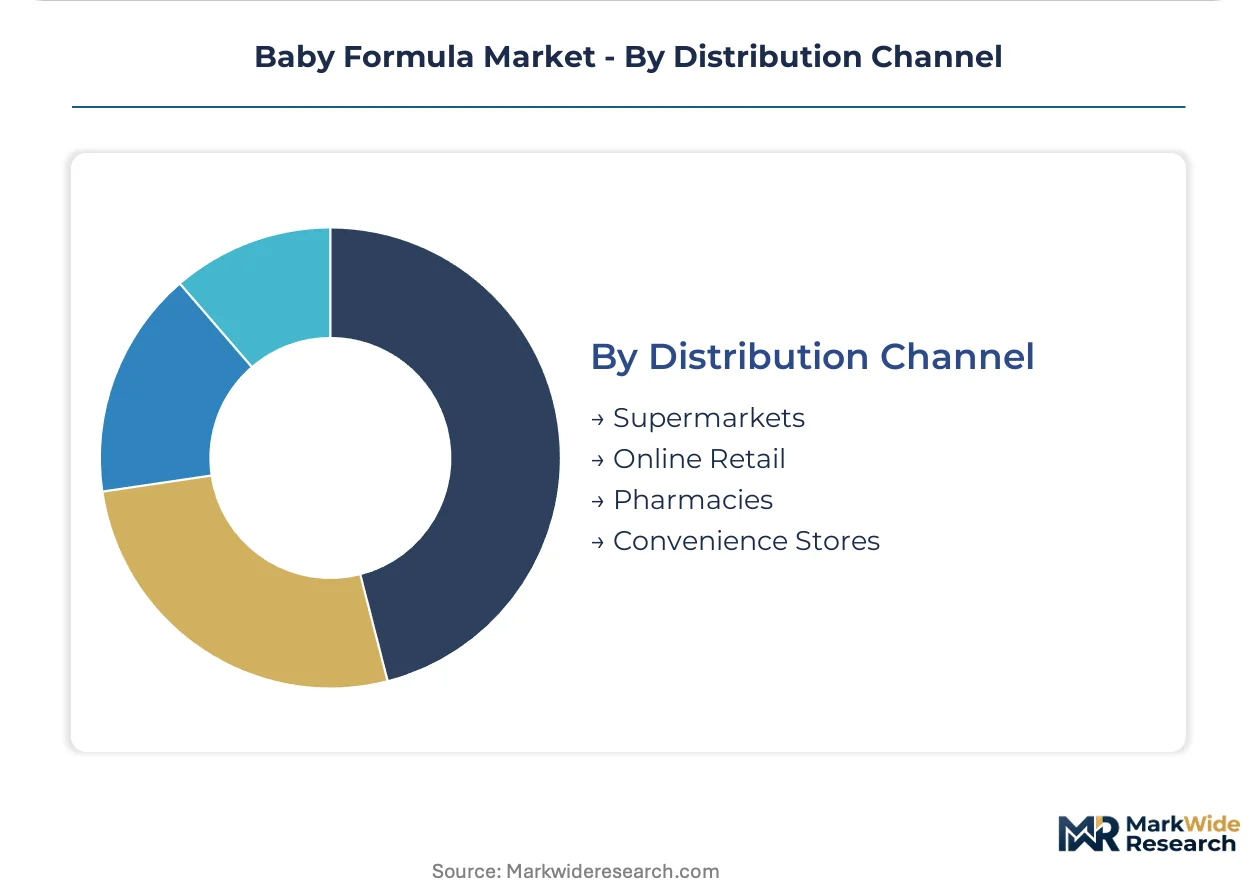
Distribution Channel:
Channel economics dictate working capital intensity, with pharmacy and online models requiring divergent inventory and fulfillment architectures.
- Supermarkets:Mass merchandisers in Brazil and Mexico capture impulse purchases through end-cap placement and promotional bundling. Slotting fees and trade spend compress net margin despite high throughput.
- Pharmacies:Retail pharmacy chains in France and Italy cross-merchandise formula with pediatric probiotics and vitamin D, building basket economics through professional endorsement. Inventory carrying costs exceed supermarket models due to SKU fragmentation.
- Online Retail:Direct-to-parent subscription platforms in urban China and South Korea capture feeding pattern data to automate replenishment. Last-mile cold chain requirements for liquid formats elevate logistics complexity.
- Convenience Stores:Emergency purchase occasions in Japan and Taiwan sustain limited SKU presence despite premium pricing, with format constraints favoring small-format powdered sachets.
Supermarkets still process the highest transaction volume. Online Retail is gaining share fastest in first-time parent cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation scientists and dairy protein specialists cluster in Switzerland, the Netherlands, and New Zealand, anchoring the industry's technical talent base. These concentrations shape where multinational manufacturers locate R&D centers and pilot facilities.
China
Urban dual-income households in Shanghai and Beijing drive ready-to-feed liquid adoption through pharmacy and e-commerce channels. SAMR's GB 10765-2021 standards mandate protein and carbohydrate reformulation, forcing 12-18 month registration timelines for foreign manufacturers. The Yangtze River Delta hosts the densest concentration of domestic formulation facilities serving tier-1 city demand.
United States
Hospital discharge programs for premature infants standardize specialized metabolic formulations, locking in medical channel loyalty. FDA enforces pre-market notification under the Federal Food, Drug, and Cosmetic Act with strict Good Manufacturing Practice adherence. Greater Boston and Research Triangle Park anchor clinical nutrition R&D clusters where metabolic disorder expertise concentrates.
Germany
EFSA's tightened health claims guidance restricts immune support and cognitive development packaging language without clinical trial dossiers. Extensively hydrolyzed protein specialists serve the pediatric allergy segment through pharmacy-centric distribution. Bavaria's dairy processing corridor supplies organic-certified whey protein for premium export formulations.
India
Tier-2 city organized retail penetration below 35% creates first-mover opportunities for direct-to-parent subscription models. FSSAI compositional standards for infant milk foods govern local manufacturing and import registration. Maharashtra and Gujarat host the largest spray-drying capacity clusters serving domestic powdered formula demand.
Netherlands
FrieslandCampina's cooperative structure and Arla Foods' northern European supply networks concentrate whey protein and lactose sourcing expertise. EU Organic certification requirements enforce 36-month pasture conversion timelines for dairy suppliers. The Randstad region functions as the primary logistics hub for Middle East and African export markets.
Baby Formula Market Competitive Landscape
Top-tier vendors anchor mass-market powdered segments through global dairy supply chain control, while mid-tier specialists compete on hypoallergenic certification and clinical channel relationships. The market exhibits tiered consolidation with three to four multinational groups commanding volume leadership and regional cooperatives defending niche organic positioning. Strategic archetypes include dairy-integrated multinationals leveraging backward integration into whey processing, medical nutrition specialists building hospital endorsement protocols, and emerging market challengers exploiting regulatory lag for domestic share gains. Dominant competitive moves center on precision fermentation technology licensing for cell-cultured protein sourcing and exclusive pharmacy chain partnerships for cross-merchandising with pediatric supplements.
Within the dairy-integrated multinational tier, Nestle S.A. and Danone S.A. exemplify divergent specialization strategies—one optimizing commodity scale economics, the other anchoring hypoallergenic clinical credibility. Abbott Laboratories occupies a distinct position bridging medical nutrition protocols with metabolic disorder formulation expertise. These three S.A.- and Laboratories-suffixed entities represent how geographic origin and corporate structure signal competitive archetype to channel partners and procurement officers.
| Leading Market Players |
|---|
| Nestle S.A. |
| Danone S.A. |
| Abbott Laboratories |
| Reckitt Benckiser Group PLC |
| Perrigo Company plc |
| FrieslandCampina |
| Arla Foods |
| Yili Group |
| Mead Johnson Nutrition Company |
| Others |
Pricing and Supply Chain Analysis
Dairy-integrated multinationals with captive whey processing assets command upstream pricing discipline that commodity-dependent competitors cannot replicate. This ownership pattern concentrates margin capture among Swiss and Dutch cooperatives while forcing price-based competition on standard formulation tiers.
Pricing Analysis
Bundled clinical channel services versus unbundled retail shelf presence defines the pricing architecture. Three-tier pricing structure across premium hypoallergenic, standard modified cow's milk, and economy powdered tiers separates formulations by certification burden and protein hydrolysis complexity. Price differentiation rests on organic pasture conversion timelines and SAMR registration status. Cost compression in standard powdered segments is intensifying because New Zealand GlobalDairyTrade auction volatility transmits directly to commodity whey and lactose inputs. Rural Indian parents in tier-3 cities exhibit highest price sensitivity; hospital discharge programs for premature infants show least sensitivity due to metabolic protocol standardization.
Supply Chain Analysis
Regional distribution centers in the Randstad region and Bavarian dairy corridor anchor hub-and-spoke patterns serving Middle East and African export markets. Manufacturing concentrates in the Netherlands, New Zealand, and China's Yangtze River Delta. Raw material sourcing draws from Irish and Danish whey protein concentrate, New Zealand whole milk powder, and Malaysian palm oil derivatives for lipid fractions. Single-source vulnerability concentrates in DHA and ARA fatty acid supply among three global fermentation specialists. Distribution runs through pharmacy-centric models in Europe and direct-to-parent subscription platforms in urban China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's 12-18 month FSSAI registration timelines lag China's SAMR protocols, creating first-mover windows for domestic challengers before multinational compliance investments mature.
For Market Incumbents: Anchor hospital channel relationships through metabolic disorder formulation exclusivity to defend against precision fermentation entrants. Deepen backward integration into A2 protein dairy herds to capture genetic certification premiums. Prioritize ERP harmonization across acquired regional brands to unify batch record systems before recall protocol failures compound liability exposure.
For New Entrants and Emerging Players: Working parents in India's tier-2 cities represent the most penetrable buyer archetype given organized retail penetration below 35%. Establish direct-to-parent subscription models before cold chain infrastructure matures. Target pharmacy cross-merchandising partnerships with pediatric probiotics to build basket economics against supermarket slotting fee barriers.
For Investors and Strategic Acquirers: Dairy-integrated multinationals seeking hypoallergenic capability are the most active acquirer in this space, driving valuation premiums for extensively hydrolyzed protein specialists. Long-term viability centers on clinical nutrition credibility rather than commodity scale. Target acquisition archetypes include regional organic-certified cooperatives with EU pasture conversion completion and hospital discharge program relationships. Watch precision fermentation cost parity with conventional dairy protein as the inflection signal for ingredient sourcing economics disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Licensing | Perfect Day and Remilk partnerships decouple whey supply from pastureland constraints and methane accounting. |
| Exclusive Pharmacy Partnerships | Cross-merchandising with pediatric vitamin D builds basket economics in France and Italy. |
| A2 Protein Herd Certification | Genetic testing of dairy suppliers enables verified beta-casein sourcing premiums in China. |
| Subscription Platform Integration | Pediatrician-endorsed apps in Seoul and Shanghai automate replenishment through feeding pattern data. |
| SAMR Registration Acceleration | Domestic Chinese facilities bypass 12-18 month foreign manufacturer approval windows. |
Research Methodology
Coverage spans Asia-Pacific, Europe, and North America, with primary inputs from each region combining formulation scientist interviews, retail pharmacy procurement managers, and pediatric nutrition specialists with secondary validation. Regulatory filings from FDA, EFSA, and SAMR anchor compliance landscape mapping. Trade data from New Zealand GlobalDairyTrade and EU dairy auction platforms inform input cost modeling. Nielsen retail audit data and hospital procurement databases provide channel volume triangulation. Bottom-up capacity assessments and top-down expenditure analysis converge on segment-level outputs.
Granularity-level modeling operates at product format, ingredient certification tier, and distribution channel resolution across the analysis window. Segmentation dimensions include production format, protein source modification level, organic certification status, and regional regulatory cluster. CAGRs derive from expenditure elasticity models calibrated to dual-income household penetration rates and birth cohort trajectories. Precision fermentation cost curves and GB standards compliance timelines serve as industry-specific forecast inputs.
Underlying measurement precision varies by segment; ready-to-feed liquid and hypoallergenic formulations carry tighter precision than commodity powdered tiers due to concentrated manufacturer disclosure. Forecasts reflect assumptions about SAMR registration timeline stability and dairy commodity auction volatility. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Middle-Aged and Elderly Milk Powder Market
Baby Food and Infant Formula
Parenteral Formula Market
Baby Food and Infant Formula
Indonesia Infant Nutrition Market
Baby Food and Infant Formula
Russia Pet Food Market
Baby Food and Infant Formula
Infant Nutritional Premix Market
Baby Food and Infant Formula
Pureed Food Market
Baby Food and Infant Formula
Hydrolyzed Formula Milk Powder Market
Baby Food and Infant Formula
Ready to Use Supplementary Food Market
Baby Food and Infant Formula
Standard Milk Formula Market
Baby Food and Infant Formula
Pet Milk Replacement Products Market
Baby Food and Infant Formula
North America Baby Food Market
Baby Food and Infant Formula
Asia-Pacific Baby Food Market
Baby Food and Infant Formula
Baby Cereal-Based Complementary Food Market
Baby Food and Infant Formula
Europe Organic Baby Food Market
Baby Food and Infant Formula
West Africa Baby Food Market
Baby Food and Infant Formula
Baby Food Products Market