
 GCC Baby Food and Infant Formula Market | 2026-2036
GCC Baby Food and Infant Formula Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Baby Food and Infant Formula Market Intelligence
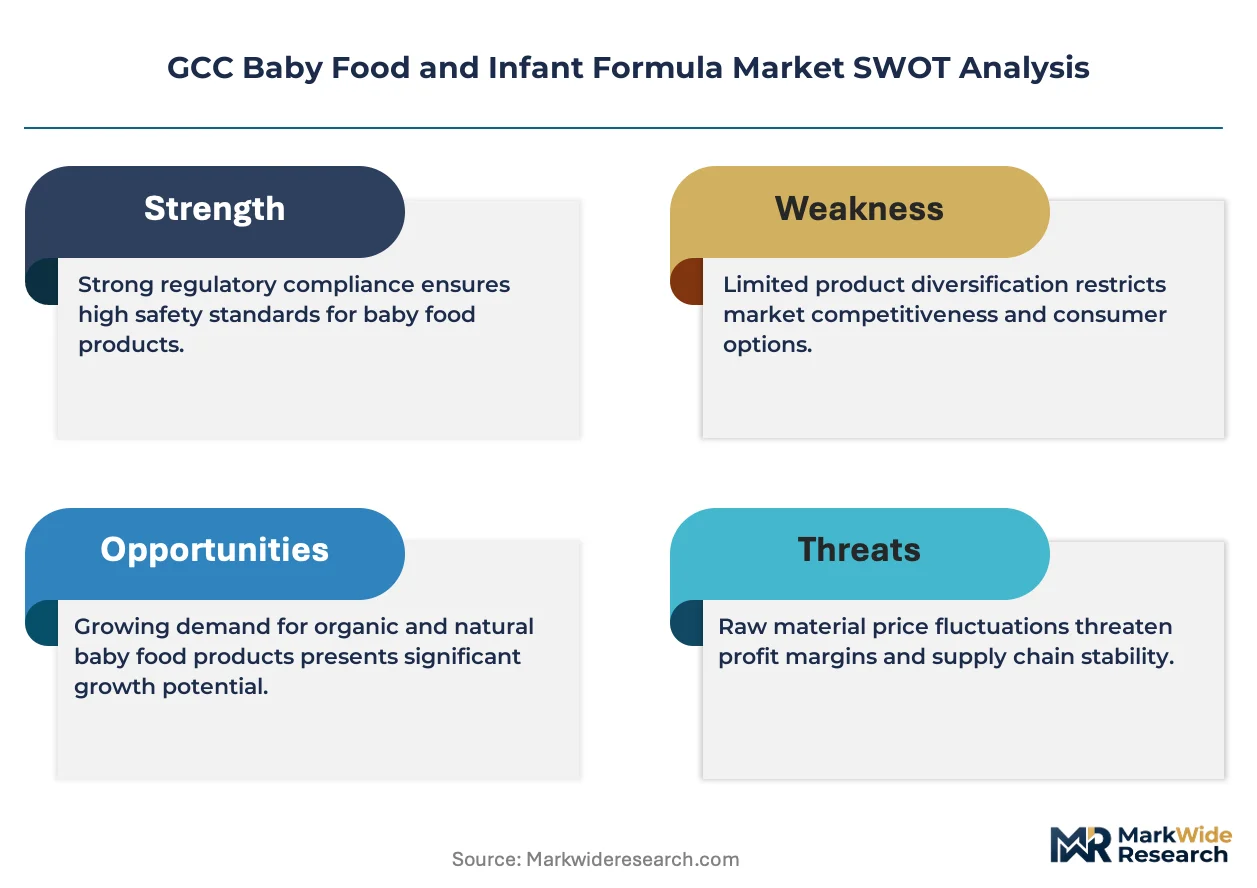
Subscription-based replenishment services and digital pediatric nutrition advisory bundles are recalibrating what parents purchase beyond the physical product. Nestle leverages its extensive Gulf distribution infrastructure to sustain shelf dominance across hypermarket chains. Mead Johnson anchors its position through specialized newborn metabolic formulas that target hospital discharge protocols. Danone competes via premium organic lines that command attention among health-conscious expatriate communities.
GCC baby food and infant formula encompasses processed nutritional products formulated for children from birth through 36 months, typically manufactured through spray-drying, wet-mixing, and aseptic liquid filling processes to achieve microbiological safety and nutrient stability. These products serve as breast-milk substitutes or complementary feeding solutions in contexts where maternal employment patterns, medical necessity, or cultural preference limit exclusive breastfeeding duration. Organic and premium brand segments attract disproportionate margin pools as Gulf consumers associate European certification marks with safety assurance. Powdered formulations occupy the volume core due to lower per-unit cost and extended ambient shelf stability, while ready-to-feed liquids capture pharmacy and hospital channels where convenience and sterility outweigh price sensitivity.
SFDA in Saudi Arabia and MOHAP in the UAE enforce compositional standards for infant formula that exceed baseline Codex Alimentarius thresholds on protein ratios and micronutrient floors, compelling reformulation investments from all market entrants. BIS-equivalent conformity assessments in Kuwait and Qatar add further certification layers that filter out smaller regional traders. Stakeholders must monitor evolving Gulf Cooperation Council harmonization talks on unified nutrition labeling, as any pan-GCC standard would reshape competitive access across the six-member bloc.
Market Dynamics
SFDA and MOHAP tightening of nutritional composition standards is forcing manufacturers to accelerate reformulation cycles and absorb certification costs that smaller traders cannot shoulder. This regulatory compression is restructuring competitive access across Saudi Arabia, the UAE, and Qatar.
Growth Catalysts
- Dual-income household expansion:Metropolitan Saudi Arabia and the UAE report rising female labor participation that compresses breastfeeding duration and elevates demand for convenient infant nutrition substitutes.
- SFDA compositional mandates:Stricter protein ratio and micronutrient floor requirements exceed Codex Alimentarius baselines, creating barrier-to-entry protection for compliant manufacturers with established Gulf distribution.
- Spray-drying technology advancement:Improved nutrient retention during thermal processing enables cleaner-label positioning that commands shelf space in premium hypermarket channels.
Market Restraints
- Whey protein concentrate import dependency:GCC domestic dairy processing capacity remains insufficient, exposing margins to New Zealand and European commodity price volatility.
- BIS-equivalent conformity assessment layering:Kuwait and Qatar maintain certification requirements distinct from Saudi-UAE harmonization talks, fragmenting compliance investment across the six-member bloc.
- Extended breastfeeding promotion campaigns:MOHAP and Saudi Ministry of Health public health messaging creates cultural stigma around formula feeding that constrains category normalization.
Strategic Opportunities
- Oman and Bahrain underpenetration:Modern retail infrastructure in secondary GCC markets remains less saturated, offering first-mover positioning ahead of hypermarket chain expansion.
- Digital pediatric nutrition advisory bundles:Subscription services that integrate telehealth consultations with automated replenishment are capturing recurring revenue streams beyond physical product margins.
- Pan-GCC labeling harmonization:Active Cooperation Council standardization discussions could collapse six separate compliance regimes into unified market access protocols.
Industry Challenges
- Specialized pediatric nutritionist talent scarcity:Gulf universities produce insufficient formulation scientists familiar with both Islamic dietary law and SFDA technical requirements.
- Aseptic liquid filling capex intensity:Ready-to-feed segment expansion demands sterile manufacturing infrastructure that exceeds regional contract manufacturer capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Baby Food and Infant Formula Market |
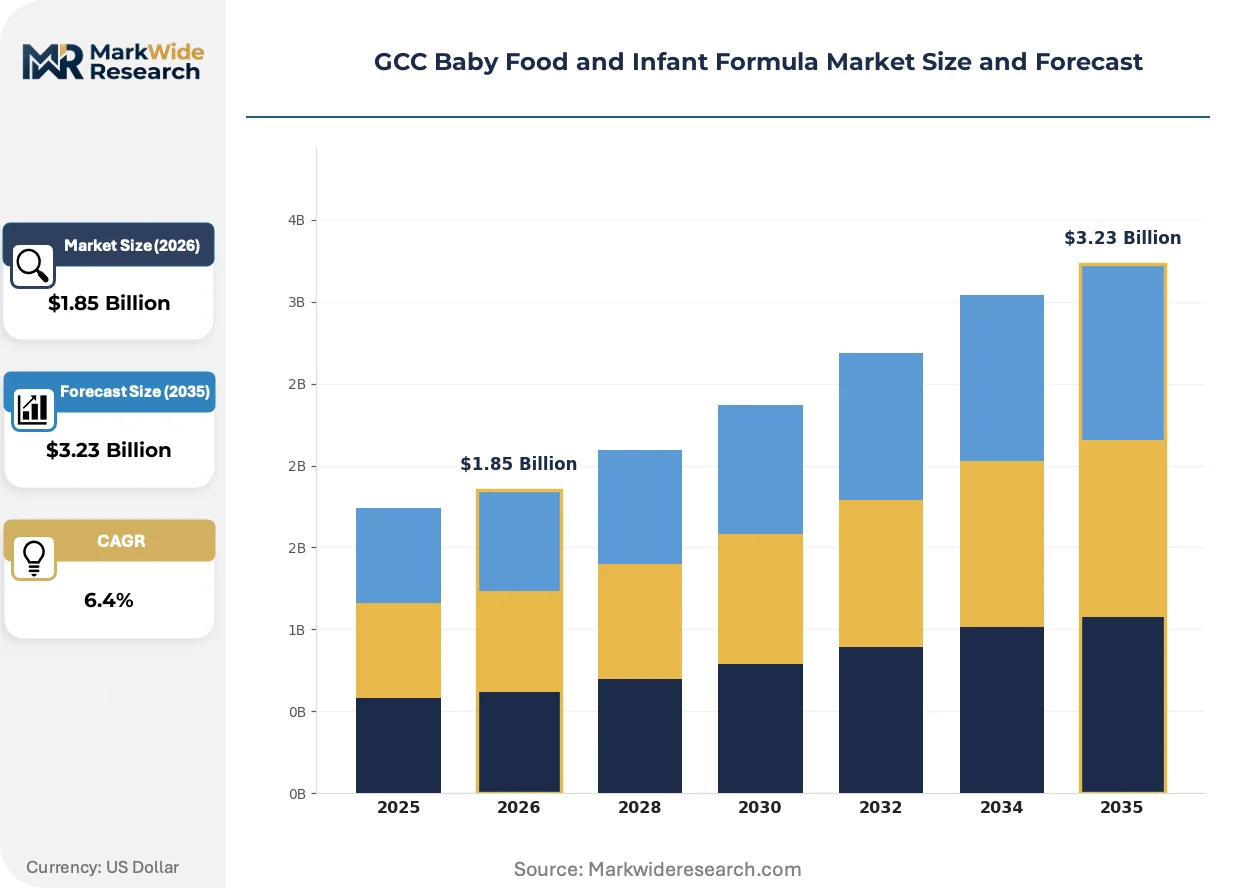
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Powdered, Ready-to-Feed Age Group: Infants, Toddlers, Newborns, 6-12 Months Distribution Channel: Supermarkets, Online Retail, Pharmacies, Convenience Stores Brand Type: Private Label, National Brands, Premium Brands, Value Brands |
| Companies Covered | Reckitt Benckiser Group, Mead Johnson, Nestle, HiPP, FrieslandCampina, Danone, Perrigo Company, Arla Foods, Abbott Nutrition, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Baby Food and Infant Formula Market Strategic Shifts & Innovations
Clean-label spray-drying protocols and digital replenishment platforms are compressing traditional purchase cycles while elevating safety-assurance signaling through European organic certification marks.
Cold-chain aseptic processing is unifying microbiological safety with extended ambient stability in liquid formulations. Pharmacy and hospital procurement teams across Doha and Abu Dhabi are adopting these formats for discharge protocols. The technology is unifying convenience positioning with sterility guarantees that powdered alternatives cannot replicate.
SFDA's 2024 draft guidelines on glycemic index disclosure for complementary foods are compelling carbohydrate source reformulation. Manufacturers must re-engineer cereal-based purees to meet pending thresholds. Stage-two and stage-three baby food segments in Riyadh and Jeddah are responding with lentil and quinoa base substitutions ahead of enforcement.
Direct-to-parent subscription models are displacing hypermarket bulk purchasing among affluent expatriate households in Dubai and Doha. Automated replenishment algorithms calibrated to pediatric growth curves are capturing loyalty through convenience lock-in. This behavioral pivot concentrates margin retention with brands that own customer data infrastructure rather than retail shelf payments.
GCC Baby Food and Infant Formula Market Segmentation
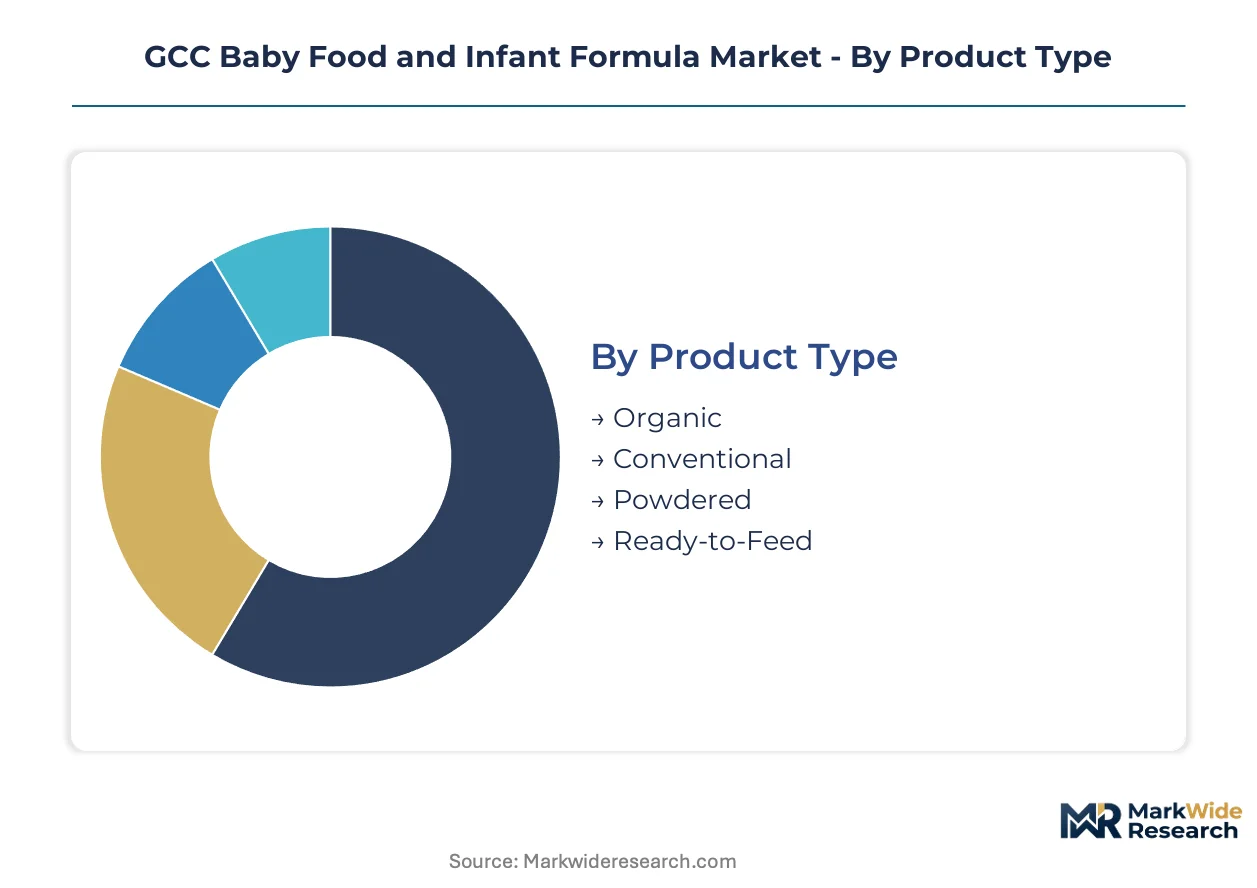
GCC infant nutrition purchasing fragments across formulation preferences, household income tiers, and channel loyalty patterns. Manufacturers must calibrate portfolio depth against regulatory compliance costs that vary sharply by product category.
Product Type:
Standardization dominates at the volume core while customization commands margin pools through certification premiums and convenience positioning.
- Powdered:Spray-dried formulations achieve extended ambient shelf stability through low moisture content and nitrogen-flushed packaging. Demand concentrates in Saudi hypermarket chains serving Riyadh and Jeddah households where unit economics favor bulk purchasing and home preparation.
- Organic:European certification marks signal safety assurance to Gulf parents associating EU organic standards with superior quality control. Expatriate communities in Dubai and Doha drive disproportionate volume for these SKUs despite 40-60% price premiums over conventional alternatives.
- Ready-to-Feed:Aseptic liquid filling delivers sterility guarantees for hospital discharge protocols and pharmacy channels.
- Conventional:Baseline formulations without organic certification occupy economy-tier positioning in value-oriented retail.
Leading the category by volume: Powdered. Growing fastest: Organic.
Age Group:
Developmental milestones dictate nutritional specifications and regulatory scrutiny intensity across feeding stages.
- Infants:Birth-to-twelve-month formulations face strictest SFDA compositional mandates on protein ratios and micronutrient floors. Hospital procurement teams in Abu Dhabi and Doha specify these products for neonatal discharge bundles.
- Newborns:Specialized metabolic formulas address premature birth complications and inherited enzyme deficiencies. Mead Johnson anchors hospital formulary positioning through targeted newborn nutrition protocols.
- 6-12 Months:Complementary feeding transition drives cereal and puree introduction alongside continued formula consumption.
- Toddlers:Twelve-to-thirty-six-month nutritional products bridge toward family food consumption patterns.
Volume leadership: Infants. Steepest expansion trajectory: Newborns.
Distribution Channel:
Channel selection determines margin retention, customer data ownership, and regulatory exposure for infant nutrition brands.
- Supermarkets:Hypermarket chains across Saudi Arabia and the UAE consolidate shelf space negotiations with multinational suppliers. Carrefour and Lulu dominate baby food aisle placement through centralized category management.
- Pharmacies:Hospital-adjacent retail and clinic-based dispensing channels capture prescription-adjacent formula sales with higher trust transfer.
- Online Retail:Subscription algorithms calibrated to pediatric growth curves are displacing bulk purchasing among affluent Dubai households.
- Convenience Stores:Emergency replenishment and travel-size formats address immediate-need scenarios with limited SKU depth.
Volume concentration: Supermarkets. Channel gaining share fastest: Online Retail.
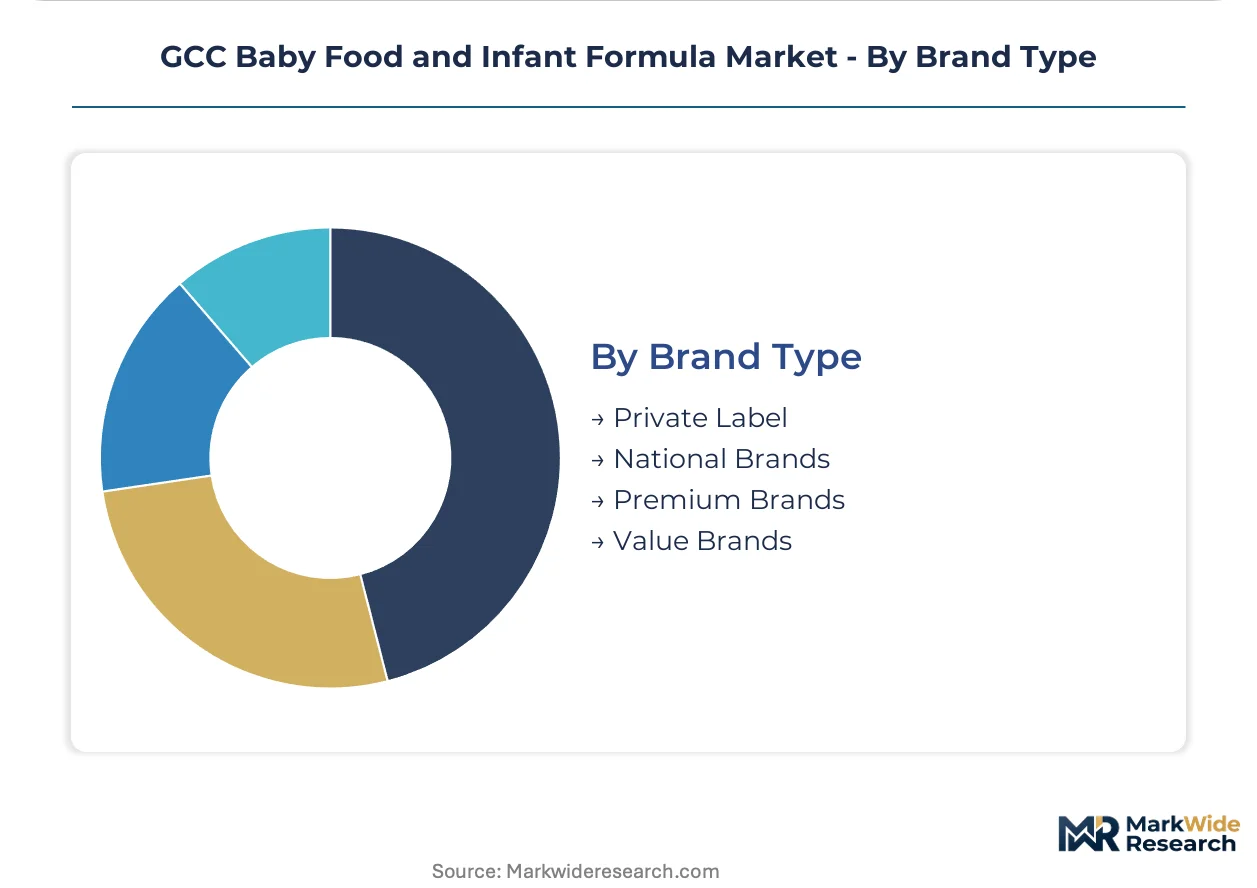
Brand Type:
Brand architecture stratifies across certification investment capacity and distribution infrastructure ownership.
- Premium Brands:Danone and Nestle deploy European manufacturing credentials and Gulf-wide cold chain infrastructure to sustain price positioning. Health-conscious expatriate communities in Qatar and the UAE demonstrate lowest price elasticity for these SKUs.
- National Brands:Regional manufacturers leverage local production assets and shorter supply chains to compete on freshness signaling.
- Private Label:Retailer-owned formulations capture value-tier volume through hypermarket chain exclusivity.
- Value Brands:Economy positioning targets price-sensitive households with reduced certification layering.
Revenue concentration: Premium Brands. Segment expanding most quickly: Private Label.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh and Jeddah anchor GCC infant nutrition demand through dense modern retail corridors and dual-income household concentration. Metropolitan purchasing power across these Saudi hubs exceeds secondary Gulf markets by significant margins. National regulatory frameworks diverge sharply, fragmenting compliance investment across the six-member bloc.
Saudi Arabia
Riyadh's hypermarket chains and Jeddah's pharmacy corridors drive volume concentration for powdered formulations. SFDA compositional mandates on protein ratios and micronutrient floors exceed Codex Alimentarius baselines, filtering out smaller traders. Eastern Province industrial zones host spray-drying facilities serving domestic label requirements.
United Arab Emirates
Dubai's expatriate corridors and Abu Dhabi's hospital procurement networks elevate premium organic positioning. MOHAP labeling standards reshape product development cycles for complementary foods. Northern Emirates retail infrastructure remains underpenetrated relative to Dubai-Abu Dhabi concentration.
Qatar
Doha's pharmacy channels and hospital discharge protocols capture ready-to-feed liquid demand. BIS-equivalent conformity assessments add certification layering distinct from Saudi-UAE harmonization talks. Lusail development corridors attract modern retail expansion ahead of population density maturation.
Kuwait
Kuwait City metropolitan retail consolidates shelf negotiations with multinational suppliers. National standards authority requirements maintain distinct technical specifications from neighboring regulators. Hawalli and Salmiya districts concentrate affluent household purchasing for premium-tier SKUs.
Oman
Muscat's modern retail penetration lags Saudi and UAE benchmarks, offering first-mover positioning ahead of hypermarket chain expansion. Ministry of Health breastfeeding promotion campaigns constrain category normalization relative to neighboring markets. Sohar industrial zones develop dairy processing capacity to reduce import dependency.
GCC Baby Food and Infant Formula Market Key Industry Players
Capital-heavy producers compete with asset-light brand licensors across divergent margin structures. Spray-drying facility ownership and cold-chain infrastructure separate integrated multinationals from regional distributors. Three archetypes dominate: European-certified organic specialists, hospital-formulary anchor brands, and private-label contract manufacturers. Consolidation pressure intensifies through distribution infrastructure acquisition and pan-GCC labeling harmonization positioning.
Among Swiss-anchored nutrition conglomerates, Nestle occupies a position exemplifying Gulf-wide distribution scale. Mead Johnson represents the hospital-formulary archetype through specialized newborn metabolic protocols. Danone sits within the European-certified premium tier targeting health-conscious expatriate communities. These three anchors illustrate how regulatory compliance capacity and cold-chain infrastructure ownership stratify competitive access across Saudi, UAE, and Qatar corridors.
| Leading Market Players |
|---|
| Reckitt Benckiser Group |
| Mead Johnson |
| Nestle |
| HiPP |
| FrieslandCampina |
| Danone |
| Perrigo Company |
| Arla Foods |
| Abbott Nutrition |
| Others |
Cost & Logistics Intelligence
SFDA compositional mandates on protein ratios and micronutrient floors gate qualified supply access while anchoring premium-tier pricing power for compliant manufacturers serving Saudi Arabia and the UAE. European certification marks for organic lines command shelf space through safety-assurance signaling that justifies 40-60% price premiums over conventional alternatives in Gulf hypermarkets.
Pricing Analysis
Value-based pricing anchored to pediatric health outcomes and metabolic efficacy separates hospital-formulary positioning from retail commodity tiers. Three-tier pricing structure across premium organic, standard compliant, and economy private-label levels stratifies margin retention by certification investment depth. Price differentiation hinges on European organic accreditation and SFDA registration status, with cost compression in the economy tier intensifying due to raw material import volatility. Expatriate households in Dubai and Doha demonstrate lowest price sensitivity, while value-conscious Saudi families in secondary cities drive volume through private-label substitution.
Supply Chain Analysis
Whey protein concentrate supply rests on New Zealand and European dairy processors, with GCC domestic spray-drying capacity insufficient for regional demand coverage. Lactose, vegetable oils, and specialized micronutrient premixes constitute critical input dependencies alongside protein sources. Single-source vulnerability in whey imports exposes margin structures to Oceania commodity price swings and currency fluctuation. Distribution runs through hypermarket chain centralized procurement in Riyadh and Jeddah, with pharmacy and hospital channels capturing premium liquid formulations through direct formulary negotiation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA protein ratio and micronutrient mandates erect a cost-of-compliance barrier that filters out smaller traders and consolidates pricing power among established Gulf distributors with reformulation infrastructure.
For Market Incumbents: Deploy cold-chain infrastructure expansion to capture ready-to-feed liquid growth in hospital discharge protocols. Nestle and Danone should anchor backward integration into aseptic filling capacity to defend margin position against emerging contract manufacturers. Mead Johnson's hospital-formulary anchoring through metabolic specialization offers a template for defensive positioning against private-label encroachment in the newborn segment. For New Entrants and Emerging Players: MOHAP labeling standardization talks in the UAE open a window for first-mover positioning in underpenetrated Northern Emirates retail corridors. Target Oman and Bahrain ahead of hypermarket chain expansion, leveraging shorter regulatory approval cycles relative to Saudi SFDA pathways. A direct-to-parent subscription model with telehealth bundling captures customer data ownership that retail shelf payments cannot replicate. For Investors and Strategic Acquirers: Pan-GCC labeling harmonization announcement is the leading indicator that compliance cost structures will collapse six separate regimes into unified market access. Acquisition focus should center on regional contract manufacturers with existing SFDA registration and spray-drying facility ownership. Watch for spray-drying facility acquisition activity by multinational nutrition conglomerates as the signal that consolidation pressure is accelerating.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aseptic Filling | Captures ready-to-feed margin pools in Abu Dhabi and Doha hospital procurement networks. |
| European Organic Certification Investment | Unlocks 40-60% price premiums through EU safety signaling in Dubai expatriate corridors. |
| Direct-to-Consumer Subscription Launch | Displaces hypermarket bulk purchasing through automated replenishment calibrated to pediatric growth curves. |
| Pan-GCC Regulatory Harmonization Positioning | Pre-empts unified compliance standards through early engagement with Cooperation Council technical committees. |
| Specialized Newborn Metabolic Formulation R&D | Secures hospital formulary anchoring against discharge protocol standardization in Qatar and Saudi Arabia. |
Research Approach
Multi-period observation of SFDA registration timelines, MOHAP labeling enforcement patterns, and hypermarket SKU velocity anchored the trend analysis, supplemented by interviews with pediatric nutrition formulation scientists, Gulf hypermarket category managers, hospital procurement directors, and regulatory affairs specialists at multinational suppliers. Secondary validation drew from SFDA public registration databases, MOHAP technical guideline releases, customs import records for whey protein concentrates, and Nielsen retail audit data for Saudi Arabia and the UAE. Bottom-up volume modeling triangulated against top-down macroeconomic consumption projections.
Input-output matrices mapped spray-drying capacity utilization, aseptic liquid filling infrastructure deployment, and certification cost burdens across product type and age group segments throughout the forecast period. CAGRs were derived from regression analysis against female labor force participation rates, modern retail penetration indices, and regulatory compliance cost trajectories. Modeled dimensions included formulation type, developmental feeding stage, distribution channel, and brand tier positioning.
The model assumes a particular technology adoption path for cold-chain aseptic processing; alternative pathways for sterile liquid filling automation would alter the outlook for ready-to-feed segment economics. Forecasts reflect assumptions on breastfeeding promotion campaign intensity, GCC customs union harmonization progress, and New Zealand dairy commodity price stability. A small set of triggers—pan-GCC labeling standardization implementation, major whey supplier consolidation, and hospital formulary generic substitution mandates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Hydrolyzed Formula Milk Powder Market
Baby Food and Infant Formula
West Africa Baby Food Market
Baby Food and Infant Formula
Global Lactose-Free Infant Formula Market
Baby Food and Infant Formula
Middle-Aged and Elderly Milk Powder Market
Baby Food and Infant Formula
Asia-Pacific Baby Food Market
Baby Food and Infant Formula
Europe Organic Baby Food Market
Baby Food and Infant Formula
South America Baby Food Market
Baby Food and Infant Formula
Infant Formula Ingredients Market
Baby Food and Infant Formula
Canned Pet Food Market
Baby Food and Infant Formula
Baby Formula Ingredients Market
Baby Food and Infant Formula
Second Stage Organic Infant Formula Market
Baby Food and Infant Formula
Infant Nutritional Premix Market
Baby Food and Infant Formula
Europe Baby Food Market
Baby Food and Infant Formula
Infant Formula Milk Powder Market
Baby Food and Infant Formula
Baby Food Products Market
Baby Food and Infant Formula
Growing Up Formula Market