
 Growing Up Milk Market | 2026-2036
Growing Up Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Growing Up Milk Market Outlook
Pediatric nutritionist shortages across emerging markets is bifurcating competitive outcomes, with well-staffed multinationals pulling ahead of local challengers. Nestlé leverages its dedicated early-life nutrition science workforce to sustain clinical credibility in physician channels. Danone anchors its competitive position through specialized training programs for pharmacy staff across Latin American and African markets. Mead Johnson Nutrition competes by embedding registered dietitians directly into its mother-and-baby center partnerships.
Growing up milk denotes fortified dairy or dairy-alternative beverages formulated for children aged one to twelve years, typically containing added iron, DHA, prebiotics, and vitamins A through D at levels exceeding standard milk composition. Manufacturers employ spray-drying or UHT processing to preserve micronutrient stability through shelf life, with powder formats dominating in price-sensitive regions and liquid ready-to-drink variants gaining traction where refrigeration infrastructure improves. Powdered formulations occupy the largest volume share due to lower logistics costs and longer shelf stability, while ready-to-drink segments generate disproportionate margin pools in premium urban channels. The one-to-three-years age bracket leads absolute consumption, though seven-to-twelve-years fortified formulations represent the fastest-growing segment as school-nutrition programs expand.
China's SAMR enforces GB 10767 standards for older-infant and follow-up formula, directly constraining permissible additive portfolios and labeling claims. The FDA oversees growing up milk sold in the United States under food rather than infant formula regulations, creating a less stringent but still closely monitored compliance environment. EFSA scientific opinions on DHA and iron bioavailability shape reformulation priorities for European manufacturers seeking health claim authorizations. Stakeholders must monitor divergent regulatory classification between food and formula regimes, as reclassification risks in major economies would force immediate portfolio restructuring and channel requalification.
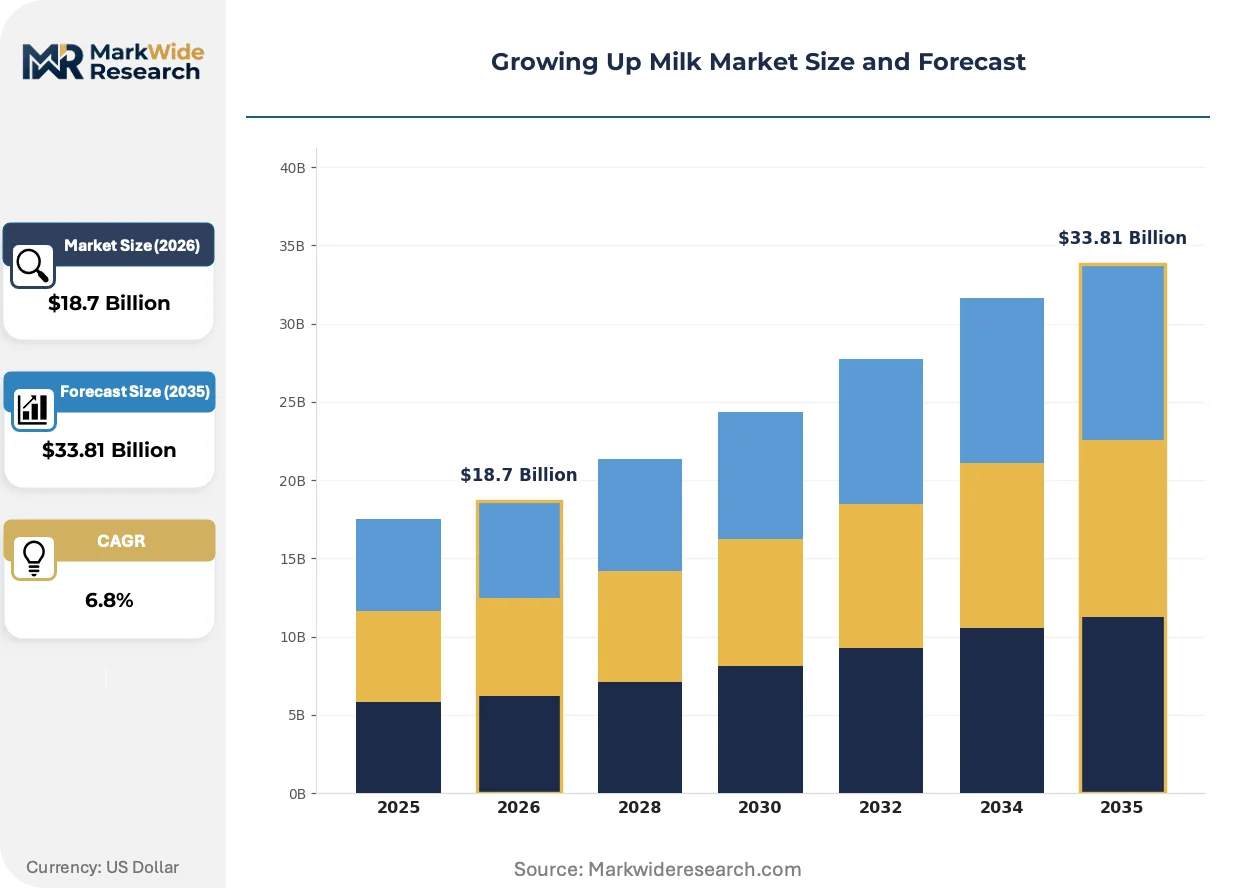
Market Dynamics
Pediatric nutrition specialists in urban China and Southeast Asia are reshaping formulation standards, while the EU's updated Food for Specific Groups regulation tightens compositional requirements that manufacturers must navigate across divergent national classification regimes.
Growth Catalysts
- GB 10767 Standards:China's SAMR enforcement of older-infant formula specifications creates clear compliance pathways for fortified additive portfolios, accelerating premium product development in tier-one cities.
- School-Nutrition Programs:Government-backed feeding initiatives across Southeast Asia expand addressable demand for seven-to-twelve-years fortified formulations in institutional channels.
- WHO Codex Guidelines:International adoption of harmonized micronutrient benchmarks reduces reformulation costs for manufacturers operating across multiple jurisdictions.
Market Restraints
- Dairy Input Volatility:Powdered formulation dominance in price-sensitive regions exposes margins to global skim milk powder auction fluctuations at Fonterra's GDT platform.
- Refrigeration Infrastructure Gaps:Ready-to-drink liquid variants face last-mile cold chain deficiencies across African and South Asian distribution networks.
- Regulatory Classification Divergence:The FDA's food-category treatment versus SAMR's formula-category treatment forces parallel compliance architectures for identical formulations.
Strategic Opportunities
- Pharmacy Channel Expansion:Specialized training programs for pharmacy staff across Latin American markets unlock professional recommendation networks previously captured by infant formula incumbents.
- Organic Certification Tailwinds:EU Green Deal agricultural transition incentives reduce organic dairy input costs for European manufacturers seeking health claim authorizations through EFSA.
- Mother-and-Baby Center Integration:Embedded dietitian partnerships in China's urban childcare facilities create captive sampling environments for trial-to-purchase conversion.
Industry Challenges
- Registered Dietitian Scarcity:Emerging markets face acute shortages of pediatric nutrition specialists capable of sustaining clinical credibility in physician channels.
- Micronutrient Stability Validation:Spray-drying and UHT processing require extended shelf-life certification timelines that compress product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Growing Up Milk Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered, Liquid, Ready-to-Drink, Nutritional Formulation: Whole Milk, Skim Milk, Fortified, Organic Distribution Channel: Supermarkets, Online Retail, Pharmacies, Convenience Stores Age Group: 1-3 Years, 4-6 Years, 7-12 Years, 12+ Years |
| Companies Covered | Mead Johnson Nutrition, Arla Foods, Nestlé, Mengniu Dairy, Yili Group, Danone, FrieslandCampina, Fonterra, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Growing Up Milk Market Strategic Shifts
Formulation science and channel architecture are undergoing parallel transformation as micronutrient delivery systems advance and professional recommendation networks displace traditional retail discovery pathways.
Microencapsulation technology for DHA and iron bioavailability preservation is displacing conventional spray-drying methods in premium formulation development. Pediatric nutrition specialists in Shanghai and Beijing are specifying these stabilized variants for children with documented absorption concerns. The structural consequence is compressing R&D cycles for manufacturers seeking EFSA health claim authorizations.
EFSA scientific opinions on DHA bioavailability are reshaping European reformulation priorities ahead of formal health claim authorization pathways. Manufacturers seeking premium positioning must now generate clinical evidence packages that exceed baseline compositional compliance. The seven-to-twelve-years segment faces the steepest evidentiary requirements given its faster growth trajectory relative to established one-to-three-years formulations.
Parental discovery patterns are fragmenting across professional and digital channels. Pharmacy staff recommendations in São Paulo and Mexico City are displacing supermarket aisle browsing as the primary trial mechanism for first-time purchasers. This behavioral shift concentrates influence with trained intermediaries rather than mass-market packaging and shelf placement investments.
Growing Up Milk Market Segmentation
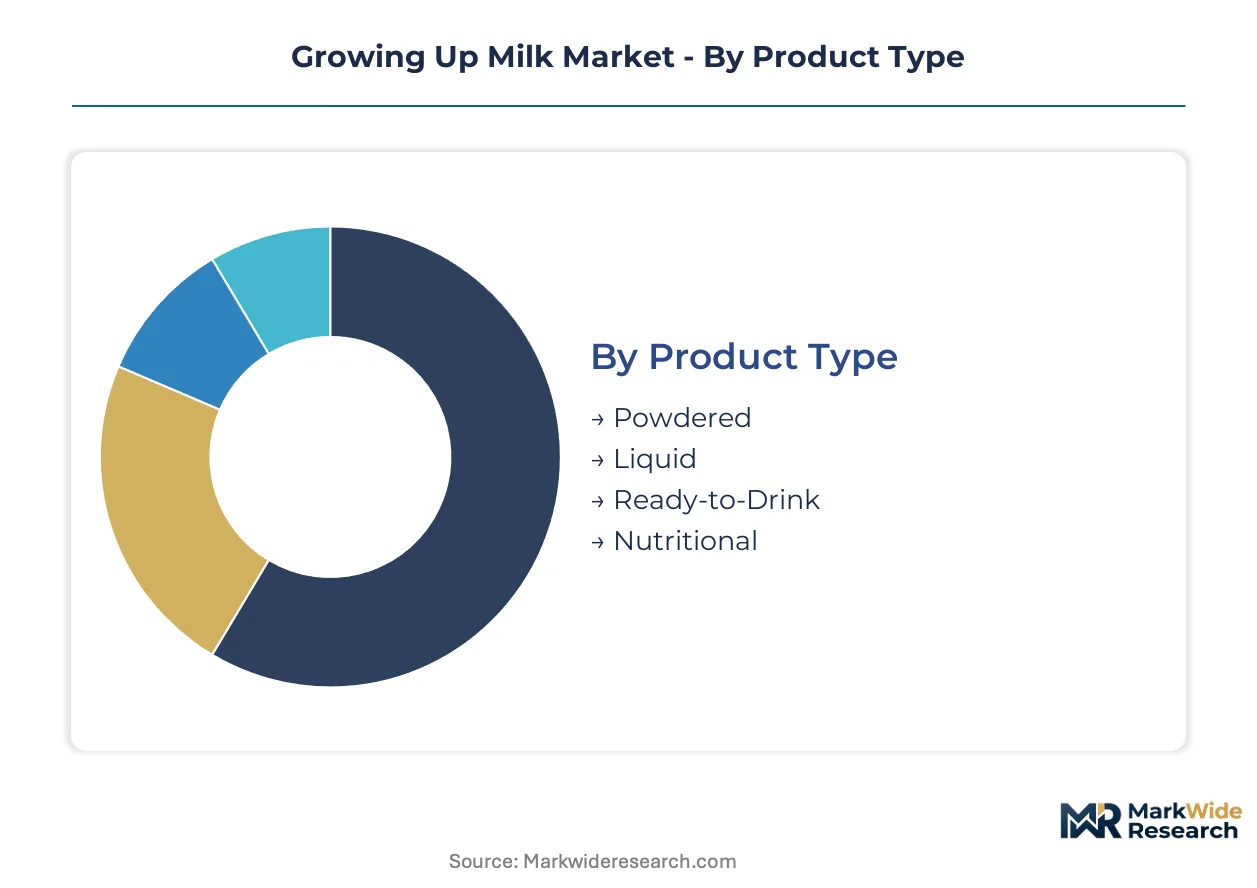
Growing up milk segmentation reveals divergent margin architectures across physical formats, nutritional positioning, channel access, and developmental targeting. Manufacturers optimize portfolio mix against refrigeration infrastructure, professional recommendation networks, and age-specific micronutrient requirements.
Product Type:
Premium margin pools concentrate in liquid ready-to-drink variants where cold chain reliability permits, while powder formats dominate absolute volume through lower logistics burden and extended shelf stability.
- Powdered:Spray-dried formulations with 18-24 month shelf stability anchor volume share in price-sensitive African and South Asian markets. SAMR's GB 10767 compositional standards constrain additive portfolios for manufacturers exporting to China's tier-one cities.
- Liquid:UHT-processed variants requiring refrigeration infrastructure generate disproportionate margins in premium urban channels across São Paulo and Mexico City. Cold chain gaps in last-mile distribution constrain penetration beyond metropolitan cores.
- Ready-to-Drink:Single-serve formats with stabilized DHA microencapsulation command pharmacy channel placement in Latin American markets where trained staff drive trial conversion.
- Nutritional:Clinically positioned formulations for documented absorption concerns specify iron and vitamin D levels exceeding standard fortification, targeting pediatric nutrition specialist recommendations in Shanghai and Beijing.
The dominant share belongs to Powdered, while Ready-to-Drink is closing the gap fastest.
Formulation:
Cost tier stratification separates commodity whole milk from premium organic positioning, with fortified variants capturing institutional demand through school-nutrition programs.
- Whole Milk:Full-fat base formulations retain native dairy lipid profiles for energy-dense pediatric requirements. Demand concentrates in traditional retail channels across Southeast Asian markets where parental preference favors familiar nutritional profiles.
- Skim Milk:Reduced-fat variants with reintroduced essential fatty acids address pediatric obesity concerns in urban Chinese households. EFSA bioavailability opinions shape reformulation priorities for European health claim authorization seekers.
- Fortified:Iron, DHA, and prebiotic additives at levels exceeding standard milk composition target the seven-to-twelve-years segment through government-backed feeding initiatives. Spray-drying and UHT processing require extended shelf-life certification timelines.
- Organic:EU Green Deal agricultural transition incentives reduce organic dairy input costs for manufacturers seeking EFSA health claim authorizations. Premium shelf positioning in China's tier-one cities commands disproportionate parental preference.
Fortified formulations hold the largest volume position, with Organic climbing the fastest on certification tailwinds.
Distribution Channel:
Channel architecture determines customer acquisition economics, with professional recommendation networks displacing traditional retail discovery pathways in high-margin urban markets.
- Supermarkets:Mass-market shelf placement and packaging-driven trial dominate first-time purchaser behavior in price-sensitive regions. Aisle browsing yields to trained intermediary influence where pharmacy infrastructure penetrates.
- Online Retail:Subscription models and direct-to-parent sampling reduce customer acquisition costs for powdered formats with lower logistics burden. Digital discovery fragments alongside professional channel influence in tier-one Chinese cities.
- Pharmacies:Specialized staff training programs unlock professional recommendation networks previously captured by infant formula incumbents across Latin American markets. Danone anchors competitive position through dedicated pharmacy workforce development.
- Convenience Stores:Impulse-ready single-serve liquid placement targets urban commuter parents with limited refrigeration access. Cold chain deficiencies constrain ready-to-drink penetration in African distribution networks.
Supermarkets retain the dominant channel share, though Pharmacies are gaining share fastest on professional recommendation concentration.
Age Group:
Application-driven segmentation aligns micronutrient specifications with developmental windows, from foundational absorption concerns through school-performance positioning.
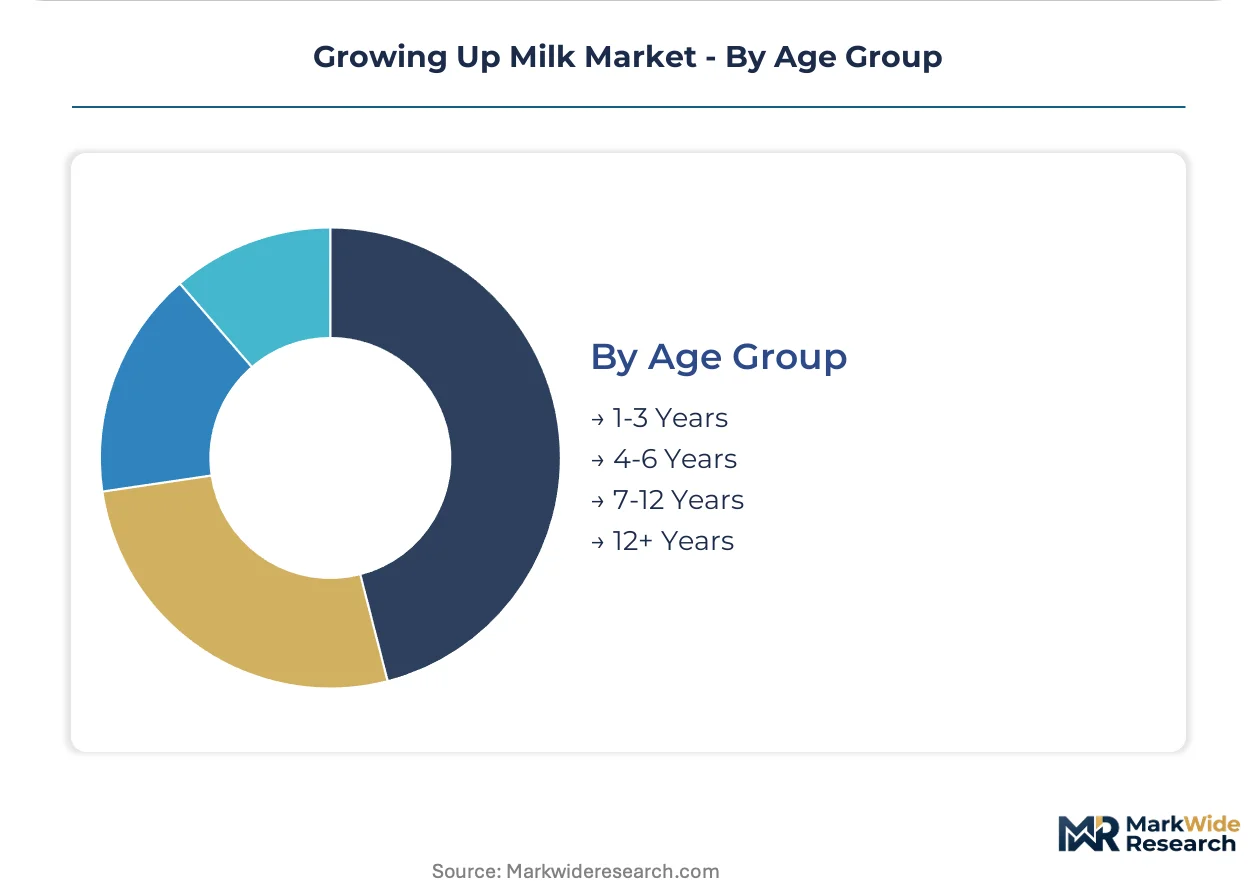
- 1-3 Years:Follow-up formula specifications under GB 10767 govern compositional requirements for this foundational bracket. Absolute consumption leadership reflects parental transition from infant formula continuity.
- 4-6 Years:Pre-school formulations bridge nutritional gaps as dietary diversification accelerates. Institutional channel development lags behind older cohort targeting.
- 7-12 Years:School-nutrition program specifications drive fortified formulation demand with the steepest expansion trajectory. Government-backed feeding initiatives across Southeast Asia expand addressable institutional demand.
- 12+ Years:Adolescent nutritional positioning with sports-performance and cognitive-function claims targets parental concern extension. EFSA evidentiary requirements for health claims compress product launch windows.
The 1-3 Years bracket commands dominant consumption volume, while 7-12 Years shows the steepest expansion trajectory on school-nutrition program adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns bifurcate sharply between East Asian pharmacy-driven professional recommendation systems and Latin American supermarket-dominated mass-market discovery, with European organic certification creating a third distinct demand architecture.
China
Pediatric nutrition specialists in Shanghai and Beijing specify microencapsulated DHA formulations for children with documented absorption concerns. SAMR enforces GB 10767 standards that constrain permissible additive portfolios and accelerate premium product development in tier-one cities. Yangtze River Delta manufacturing clusters concentrate spray-drying capacity for export-ready powdered formulations.
United States
Pharmacy channel expansion unlocks professional recommendation networks previously captured by infant formula incumbents across metropolitan markets. FDA oversight under food rather than infant formula regulations creates a less stringent but closely monitored compliance environment. Greater Boston and Pacific Northwest urban clusters drive ready-to-drink variant adoption where refrigeration infrastructure permits.
Brazil
School-nutrition program specifications expand addressable institutional demand for seven-to-twelve-years fortified formulations. ANVISA registration requirements shape reformulation priorities for manufacturers seeking health claim authorizations. São Paulo metropolitan distribution networks concentrate trained pharmacy staff capable of driving trial conversion.
Germany
EU Green Deal agricultural transition incentives reduce organic dairy input costs for manufacturers seeking EFSA health claim authorizations. EFSA scientific opinions on DHA and iron bioavailability reshape European reformulation priorities ahead of formal authorization pathways. Bavaria and North Rhine-Westphalia anchor organic dairy sourcing clusters for premium formulation supply.
Indonesia
Government-backed feeding initiatives across Southeast Asia expand addressable demand for seven-to-twelve-years fortified formulations in institutional channels. Cold chain deficiencies in last-mile distribution constrain ready-to-drink penetration beyond Jakarta and Surabaya metropolitan cores. Java-based manufacturing facilities dominate spray-dried powder production for domestic and regional export markets.
Growing Up Milk Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with multinational nutrition conglomerates commanding physician-channel credibility through dedicated early-life nutrition workforces while regional dairy processors compete on organic certification and local sourcing proximity. The market structure rewards clinical evidence generation capabilities alongside cold chain logistics scale. Three archetypes dominate: science-led multinationals with embedded dietitian networks, dairy-origin cooperatives leveraging farm-to-formulation traceability, and emerging-market challengers optimizing for GB 10767 compliance speed. Competitive intensity concentrates on pharmacy staff training investments and mother-and-baby center partnership density.
Within the science-led multinational tier, Nestlé and Danone occupy positions defined by clinical workforce scale and geographic training program reach. Mead Johnson Nutrition exemplifies the embedded specialist model through registered dietitian integration into childcare facility partnerships. Among dairy-origin cooperatives, Arla Foods and FrieslandCampina represent farm-to-formulation traceability positioning, with Fonterra anchoring southern hemisphere milk powder supply security. Mengniu Dairy and Yili Group exemplify emerging-market challengers optimizing compliance velocity under SAMR jurisdiction.
| Leading Market Players |
|---|
| Mead Johnson Nutrition |
| Arla Foods |
| Nestlé |
| Mengniu Dairy |
| Yili Group |
| Danone |
| FrieslandCampina |
| Fonterra |
| Abbott Laboratories |
| Others |
Value Chain & Pricing Dynamics
Organic dairy input substitution for conventional skim milk powder is redrawing procurement geography and compressing margin structures for European manufacturers seeking EFSA health claim authorizations. This input shift simultaneously elevates sourcing proximity requirements around Bavarian and North Rhine-Westphalian clusters while pricing stratifies across premium, standard, and economy tiers based on certification grade and cold chain reliability.
Pricing Analysis
Long-term offtake contracts with Fonterra's GDT platform anchor pricing for powdered formulations in price-sensitive African and South Asian markets, while spot-market volatility in organic dairy inputs drives premium tier expansion. Price differentiation rests on certification level and geographic delivery cost, with refrigeration infrastructure gaps in last-mile distribution intensifying cost compression for ready-to-drink variants. Supermarket channel buyers in Southeast Asia exhibit highest price sensitivity, whereas pharmacy-channel purchasers in São Paulo demonstrate lowest sensitivity due to professional recommendation influence.
Supply Chain Analysis
China and New Zealand anchor global spray-drying capacity for powdered formulations, with Germany and Denmark concentrating organic dairy sourcing for premium health claim seekers. Raw material dependencies center on skim milk powder, microencapsulated DHA, and prebiotic fibers sourced from specialized fermentation facilities. Single-source vulnerability around Fonterra's auction platform exposes margin compression risk during commodity price spikes. Distribution runs through mother-and-baby center partnerships in tier-one Chinese cities and pharmacy networks across Latin American metropolitan cores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The growing up milk market is recovering from input cost cyclicality as organic dairy supply expansion and school-nutrition program institutional demand create synchronized uplift.
For Market Incumbents: Shield formulation portfolios from SAMR reclassification risk by accelerating GB 10767 compliance certification across all SKUs before regulatory tightening spreads to ASEAN markets. Deepen backward integration into Yangtze River Delta spray-drying capacity to capture cost advantages as powder formats retain volume dominance. Prioritize embedded dietitian workforce scale as the defensive moat against emerging-market challengers optimizing for compliance velocity.
For New Entrants and Emerging Players: Lead with microencapsulation technology partnerships targeting the seven-to-twelve-years segment where EFSA evidentiary requirements have compressed incumbent R&D cycles and created white-space for clinically positioned challengers. Penetrate Indonesia's institutional feeding initiatives through government contract bidding rather than retail channel buildout. Anchor go-to-market strategy around pediatric nutrition specialist certification programs that bypass supermarket shelf placement investments.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional dairy processors holding organic certification but lacking clinical evidence generation capabilities. Five-to-ten year viability hinges on portfolio migration from commodity whole milk positioning toward fortified and organic health claim portfolios. Watch for SAMR enforcement intensity in tier-two Chinese cities as the inflection signal for regulatory reclassification risk spreading beyond current tier-one concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacy Channel Training Program | Danone's Latin American workforce development unlocks professional recommendation networks previously captured by infant formula incumbents. |
| Microencapsulation R&D Partnership | Shanghai-based pediatric nutrition specialists specify stabilized DHA variants for children with documented absorption concerns. |
| Organic Certification Acceleration | EU Green Deal agricultural transition incentives reduce input costs for manufacturers seeking EFSA health claim authorizations. |
| Mother-and-Baby Center Integration | Mead Johnson's embedded dietitian partnerships create captive sampling environments for trial-to-purchase conversion in Beijing. |
| School-Nutrition Program Contracting | Government-backed feeding initiatives across Southeast Asia expand addressable institutional demand for seven-to-twelve-years formulations. |
Study Parameters
Operator-level perspectives from pediatric nutrition specialists, pharmacy category managers, dairy procurement directors, and SAMR regulatory consultants anchored the qualitative base for this analysis. Primary interview insights combined with secondary validation from EFSA scientific opinion databases, GB standards filing records, Fonterra GDT auction data, and ASEAN school-nutrition program procurement disclosures. Bottom-up volume modeling across powder, liquid, and ready-to-drink formats triangulated against top-down value estimates from customs trade flows and retail audit data.
Sensitivity analysis tested forecast robustness across regulatory reclassification scenarios, organic input cost volatility bands, and cold chain infrastructure penetration rates. Segmentation dimensions modeled include product format, formulation type, distribution channel, and age-specific developmental targeting alongside regional regulatory cluster differentiation. CAGRs were derived from trend extrapolation of historical volume shifts and elasticity-adjusted price evolution. Key forecast inputs incorporated pediatric nutritionist workforce growth projections and school-nutrition program budget allocation trajectories.
The analysis sits within stated boundaries; outcomes outside sustained SAMR enforcement intensity, continued EU Green Deal subsidy flows, or stable Fonterra auction liquidity would require recalibration. Forecasts reflect documented assumptions regarding micronutrient stability validation timelines and pharmacy channel professionalization rates. Recalibration cycles align with material shifts in regulatory classification regimes, organic dairy supply expansion, and institutional feeding program adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Europe Baby Food and Infant Formula Market
Baby Food and Infant Formula
Cow Milk Infant Formula Market
Baby Food and Infant Formula
Canada Baby Food Market
Baby Food and Infant Formula
Baby Formula Ingredients Market
Baby Food and Infant Formula
Infant Nutrition Market
Baby Food and Infant Formula
Asia-Pacific Baby Food Market
Baby Food and Infant Formula
Global Oligosaccharides in Infant Nutrition Market
Baby Food and Infant Formula
South America Organic Baby Food Market
Baby Food and Infant Formula
GCC Baby Food and Infant Formula Market
Baby Food and Infant Formula
Second Stage Organic Infant Formula Market
Baby Food and Infant Formula
Functional Milk Replacers Market
Baby Food and Infant Formula
Wet Cat Food Market
Baby Food and Infant Formula
Pet Milk Replacement Products Market
Baby Food and Infant Formula
Growing Up Formula Market
Baby Food and Infant Formula
Organic Infant Formula Market
Baby Food and Infant Formula
West Africa Baby Food Market