
 Ready to Use Supplementary Food Market | 2026-2036
Ready to Use Supplementary Food Market Size, Share, and Industry Trends Forecast 2026-2036
Ready to Use Supplementary Food Market Analytics
WHO guidelines on community-based management of acute malnutrition is shifting procurement criteria toward lipid-based nutrient supplements with stricter micronutrient profiles. Nutriset leverages its French manufacturing base and patent portfolio to sustain dominant supply relationships with UNICEF and Médecins Sans Frontières. GC Rieber Compact anchors Nordic production capacity for compressed food bars and nutrient-dense pastes. Edesia Nutrition competes through U.S.-based production dedicated to Plumpy'Nut and similar peanut-based formulations.
Ready to use supplementary food denotes pre-formulated, shelf-stable nutrient-dense products designed for direct consumption without cooking, water, or refrigeration, typically containing 500 kcal per 100g with protein at 10-12% of total energy and lipid content exceeding 50%. These products address acute malnutrition, micronutrient deficiencies, and emergency food security gaps in humanitarian, clinical, and preventive care contexts. Powder supplements occupy the largest volume share due to lower logistics costs and longer stability windows in tropical climates. Bar supplements represent the fastest-expanding category among military and outdoor recreation buyers seeking portability. Liquid supplements concentrate margin pools in pediatric and geriatric clinical settings where swallowing difficulties drive premium positioning.
FDA regulations govern U.S. manufacturing standards for nutritional content and allergen labeling, while EFSA and the EU Green Deal framework shape European sourcing requirements and sustainability disclosures for imported ingredients. WHO and UNICEF procurement specifications function as de facto global standards, determining which formulations qualify for institutional purchasing and humanitarian funding streams. Stakeholders must monitor evolving Codex Alimentarius guidelines on micronutrient fortification levels and emerging national procurement localization mandates that could redirect supply flows toward regional manufacturing hubs.
Market Dynamics
WHO procurement specifications are compressing formulation diversity into a narrow band of lipid-based nutrient supplements, forcing manufacturers to retool production lines around standardized micronutrient profiles rather than proprietary recipes.
Growth Catalysts
- Community-based management of acute malnutrition protocols:WHO guidelines now endorse outpatient treatment models that require shelf-stable, ready-to-distribute formulations. This protocol shift expands addressable patient populations beyond clinic walls.
- Sub-Saharan Africa procurement localization mandates:Government nutrition programs in Ethiopia, Kenya, and Nigeria are requiring domestic production quotas for therapeutic food purchases. Local manufacturing investments are accelerating to meet these requirements.
- Peanut-based paste formulations:Lipid-dense, protein-rich recipes achieve superior weight-gain outcomes in severe acute malnutrition cases. UNICEF procurement volumes for these formulations are rising steadily.
Market Restraints
- Peanut commodity price volatility:Peanut butter constitutes 25-30% of raw material costs for Plumpy'Nut-type formulations. West African drought cycles create input cost instability that manufacturers cannot fully hedge.
- French manufacturing concentration:Nutriset's patent-controlled production in Normandy supplies over 50% of global RUTF volumes. Single-source dependency creates supply security vulnerabilities for humanitarian agencies.
- EFSA novel food authorization timelines:New ingredient approvals for alternative protein sources or lipid carriers face 18-24 month regulatory review periods. Innovation pipelines stall awaiting market access clearance.
Strategic Opportunities
- India domestic production scale-up:FSSAI regulatory harmonization with Codex Alimentarius standards positions Indian manufacturers for WHO prequalification. Gujarat and Maharashtra industrial corridors offer cost-competitive manufacturing infrastructure.
- Military and outdoor recreation channels:Compressed nutrient bars with 5-year stability windows are displacing traditional field rations. Defense procurement offices in the US, UK, and Australia are piloting RUSF-derived emergency food systems.
- EU Green Deal sustainable sourcing incentives:CSRD-aligned sustainability disclosures create procurement preference for deforestation-free palm oil alternatives. Shea butter and sunflower oil supply chains from West Africa qualify for green procurement scoring.
Industry Challenges
- Food technologist specialization gaps:Formulation expertise combining lipid stability science, micronutrient bioavailability, and tropical shelf-life engineering remains scarce. Universities in producing regions lack dedicated RUTF training programs.
- WHO prequalification timeline compression:Manufacturing facility audits and product registration reviews now average 14-18 months. New market entrants face working capital strain during qualification delays.
- Legacy ERP integration with UN procurement portals:Humanitarian agency ordering systems require EDI compliance and real-time inventory visibility. Mid-size manufacturers struggle with IT infrastructure upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready to Use Supplementary Food Market |
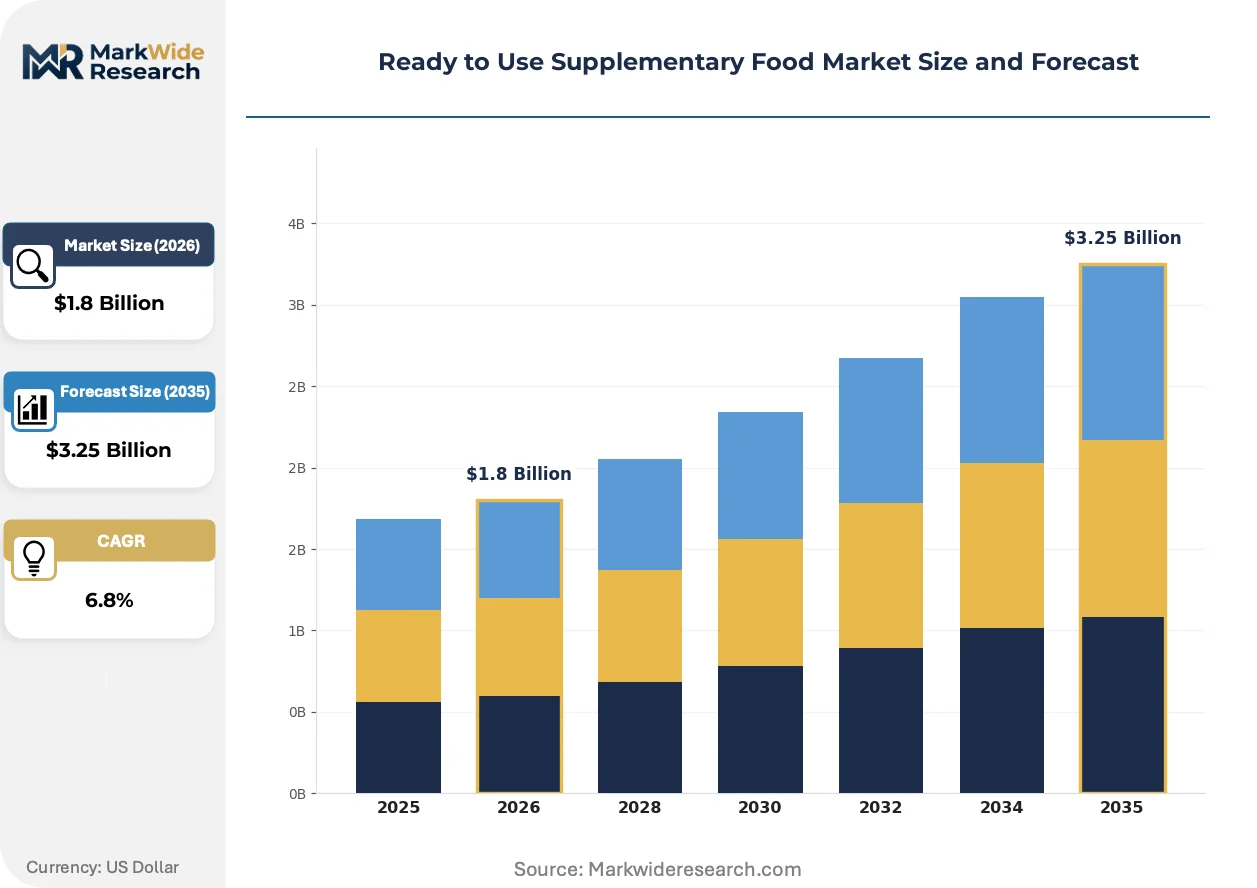
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Supplements, Powder Supplements, Bar Supplements, Ready-to-Drink End User: Children, Elderly, Athletes, Pregnant Women Formulation: Protein-Fortified, Vitamin-Enriched, Mineral-Supplemented, Herbal Extract Distribution Channel: Supermarkets, Online Retailers, Health Stores, Pharmacies |
| Companies Covered | Nutriset, Mani, Edesia Nutrition, Valid Nutrition, GC Rieber Compact, Hilina Enriched Foods, Candyland, Compact India, Diva Nutritional Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready to Use Supplementary Food Market Evolving Landscape
Reformulation science and procurement digitization are converging to reshape how nutrient-dense foods are designed, manufactured, and distributed to crisis-affected populations.
Oleogel-based lipid matrices are expanding into ready-to-use therapeutic food production as alternatives to traditional peanut-paste carriers. These structured oil systems maintain caloric density while reducing allergen exposure and enabling local oil sourcing from sunflower or sesame. UNICEF procurement teams in East Africa are piloting oleogel formulations from Ethiopian manufacturers, compressing the traditional supply chain from French import dependency to regional production.
REACH registration requirements for imported lipid ingredients are tightening documentation burdens on European manufacturers sourcing from West African cooperatives. ECHA substance volume tracking now extends to shea butter and palm oil derivatives used in nutrient supplements. German and Dutch formulators are responding by investing in blockchain-verified supply chain traceability systems that satisfy both REACH compliance and EU Green Deal deforestation-free mandates.
Humanitarian buyers are consolidating procurement through centralized UN Global Marketplace platforms that disintermediate traditional distributor networks. Médecins Sans Frontières and Save the Children are shifting from bilateral supplier contracts to pooled purchasing mechanisms managed by UNICEF Supply Division. This channel migration concentrates volume with prequalified manufacturers and marginalizes smaller regional producers lacking platform integration capabilities, with the shift most visible in Kenya and Bangladesh procurement flows.
Ready to Use Supplementary Food Market Segmentation
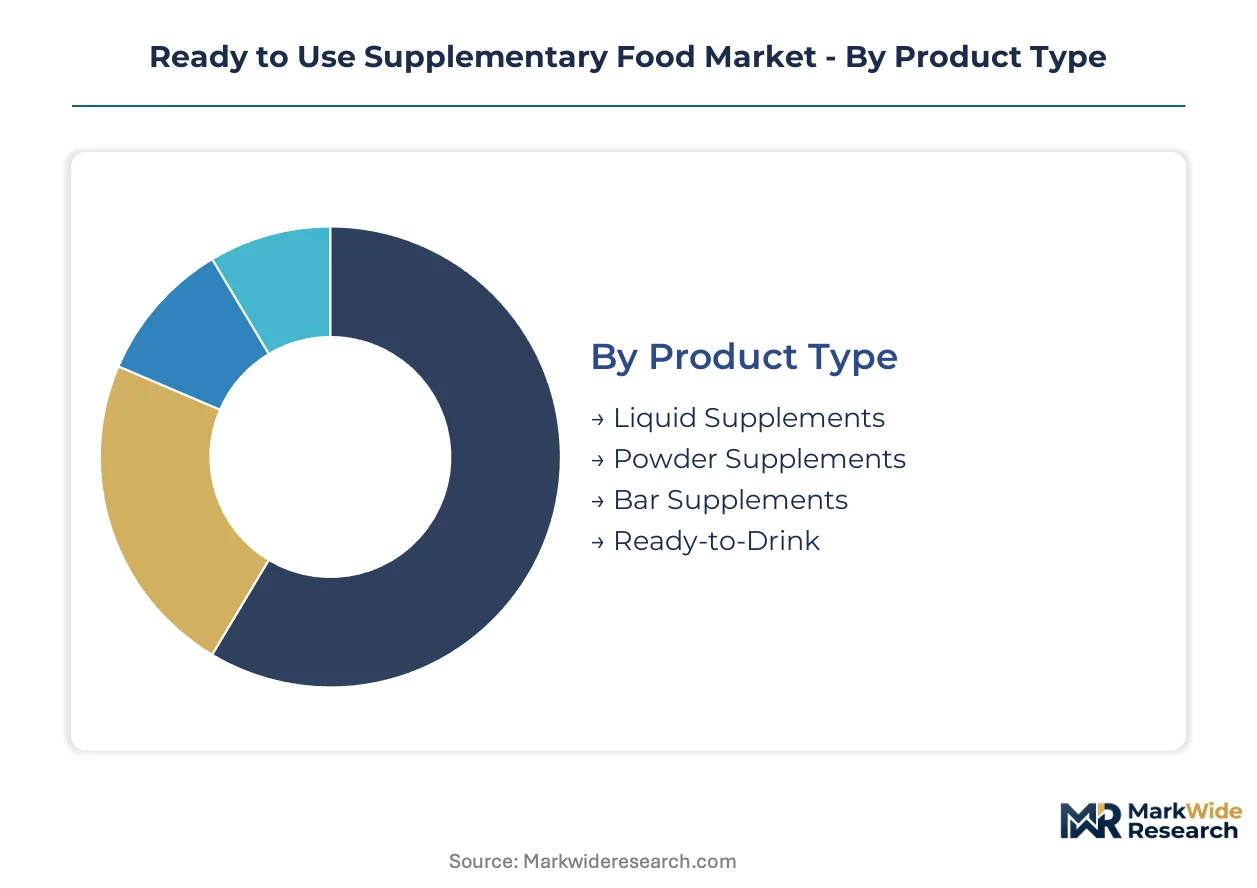
Product differentiation in ready-to-use supplementary food hinges on stability engineering, caloric density, and distribution logistics. Manufacturers configure production lines around specific formulation architectures that determine shelf life, transport costs, and end-user compliance rates.
Product Type:
Supply concentration for lipid-based pastes in Normandy and peanut-processing clusters in West Africa shapes global availability of therapeutic formulations.
- Powder Supplements:Dried blends containing micronutrients and protein isolates achieve 24-36 month stability in tropical climates with minimal packaging. UNICEF procurement in Kenya and Bangladesh favors sachet formats for last-mile distribution to community health workers. Lower logistics costs per calorie sustain dominance in humanitarian channels.
- Bar Supplements:Compressed nutrient-dense formulations deliver 500+ kcal in shelf-stable formats with 5-year stability windows. Military procurement offices in Australia and the UK are piloting these for field ration displacement. Portability drives premium positioning in outdoor recreation segments.
- Liquid Supplements:Ready-to-drink formulations address pediatric and geriatric swallowing difficulties in clinical settings. Higher water activity limits tropical shelf life to 12-18 months.
- Ready-to-Drink:Pre-mixed beverages target convenience-oriented consumers in urban pharmacies and health stores. Cold chain requirements constrain distribution reach.
Today's leader: Powder Supplements. Tomorrow's challenger: Bar Supplements.
End User:
Procurement patterns diverge sharply between institutional buyers targeting acute malnutrition and retail channels serving preventive nutrition.
- Children:Severe acute malnutrition protocols demand lipid-dense, peanut-based pastes with precise micronutrient ratios per WHO specifications. Ethiopia and Nigeria are scaling domestic production quotas for pediatric therapeutic foods.
- Elderly:Dysphagia-compatible textures and high-protein formulations address sarcopenia and micronutrient deficiencies in long-term care facilities. Japan's aging population drives formulation innovation.
- Athletes:Protein-fortified bars and powders target endurance and strength training segments with rapid glycogen replenishment profiles.
- Pregnant Women:Iron and folate-enriched supplements address maternal anemia in South Asian public health programs.
Institutional procurement concentrates on Children. Retail expansion targets Elderly.
Formulation:
Raw material sourcing geography determines cost structure and regulatory compliance burden for nutrient delivery systems.
- Protein-Fortified:Dairy, soy, and pea protein isolates deliver 10-15g protein per 100g serving. EFSA novel food approvals for alternative proteins face 18-24 month timelines.
- Vitamin-Enriched:Lipid-soluble vitamins A, D, E, K require oleogel carriers for bioavailability in low-fat matrices. REACH registration tightens documentation for imported lipid ingredients.
- Mineral-Supplemented:Iron, zinc, and calcium fortification addresses deficiency burdens in sub-Saharan African and South Asian populations.
- Herbal Extract:Ayurvedic and traditional medicine integrations target Indian domestic markets under FSSAI regulatory frameworks.
Current volume leader: Protein-Fortified. Steepest expansion trajectory: Vitamin-Enriched.
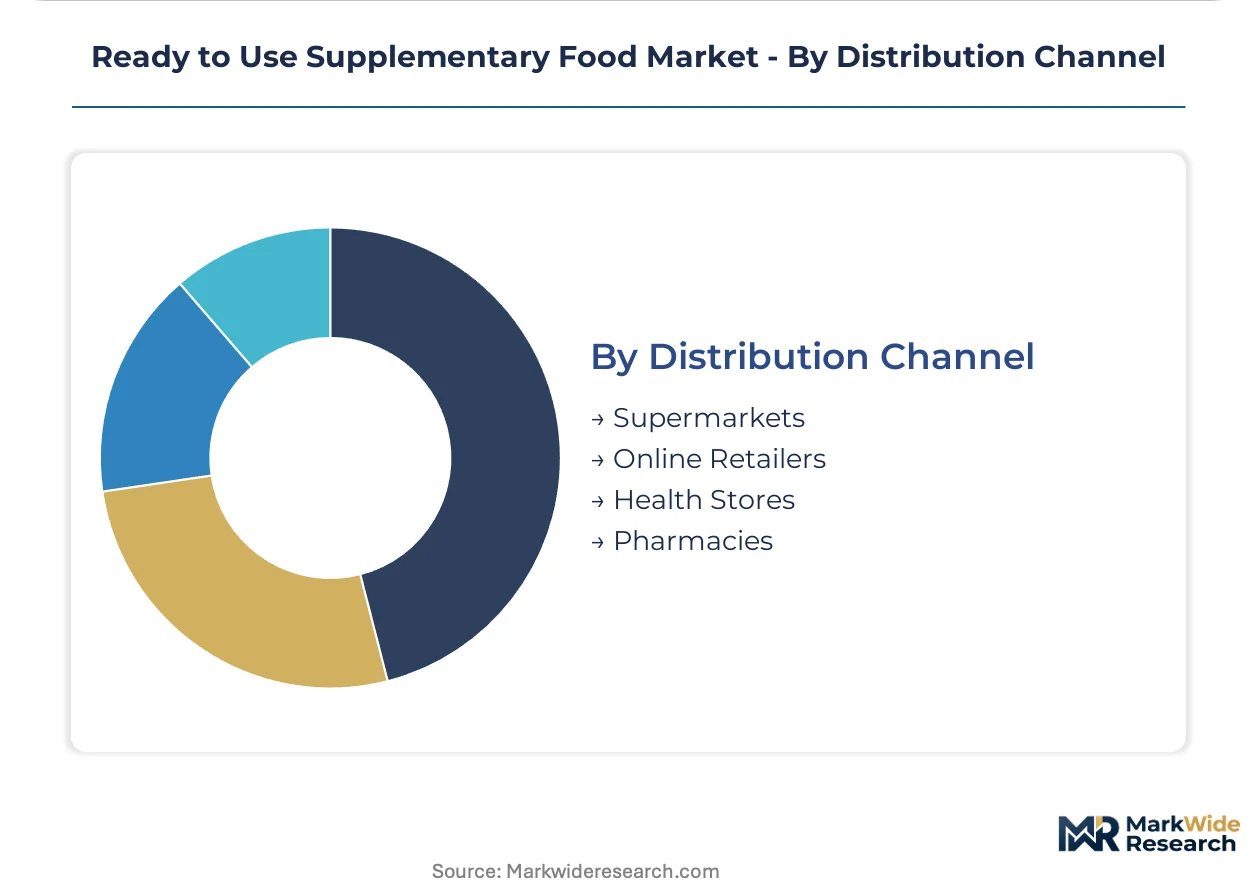
Distribution Channel:
Channel selection dictates packaging format, margin structure, and cold chain requirements.
- Supermarkets:Mass-market retail placement requires consumer-facing branding and competitive unit economics. Long payment cycles strain working capital for manufacturers.
- Online Retailers:Direct-to-consumer platforms enable subscription models and personalized nutrition bundles. Last-mile delivery costs erode margins in remote geographies.
- Health Stores:Premium positioning and educated staff recommendations support higher price points for specialized formulations.
- Pharmacies:Clinical credibility and insurance reimbursement pathways drive pediatric and geriatric product placement. Pharmacist recommendation influence sustains loyalty.
Established dominance: Pharmacies. Gaining share fastest: Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food technologists and nutrition scientists cluster in manufacturing hubs across France, the United States, India, Ethiopia, and Norway. These talent concentrations anchor production capacity for lipid-based nutrient supplements and compressed food formulations.
France
Normandy hosts the dominant patent-controlled production facility supplying over half of global RUTF volumes. ANSM oversees manufacturing standards for nutritional content and allergen labeling. The Caen industrial corridor concentrates lipid-paste formulation expertise serving UNICEF and Médecins Sans Frontières procurement.
United States
FDA regulations govern nutritional content standards and peanut-processing safety for therapeutic food exports. Rhode Island-based production facilities specialize in Plumpy'Nut-type formulations. The Providence metro area anchors North American supply relationships with humanitarian agencies.
India
FSSAI harmonization with Codex Alimentarius standards positions domestic manufacturers for WHO prequalification. Gujarat and Maharashtra industrial corridors offer cost-competitive infrastructure for powder supplement production. Mumbai-Pune belt manufacturers are scaling capacity to meet African procurement demand.
Ethiopia
Government nutrition programs mandate domestic production quotas for therapeutic food purchases. Ethiopian Food and Drug Authority aligns facility audits with WHO prequalification timelines. Addis Ababa industrial zones host pilot oleogel formulation facilities reducing French import dependency.
Norway
GC Rieber Compact anchors Nordic production capacity for compressed food bars and nutrient-dense pastes. Norwegian Food Safety Authority enforces EFSA-aligned sustainability disclosures for imported shea butter and palm oil alternatives. Bergen-area manufacturing serves military and outdoor recreation buyers seeking five-year stability windows.
Ready to Use Supplementary Food Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across formulation and distribution. The market structures around concentrated supply-side control in lipid-paste manufacturing alongside fragmented regional powder production. Three archetypes dominate: patent-holding integrated manufacturers, government-contract specialists, and military-recreation diversifiers. Competitive moves center on local production mandates compliance and blockchain supply chain traceability investments.
Among French-origin integrated manufacturers, Nutriset exemplifies patent-anchored supply relationships with multilateral procurement agencies. Edesia Nutrition occupies a position within the government-contract specialist tier, representing U.S.-based production dedicated to peanut-based therapeutic formulations. GC Rieber Compact sits within the military-recreation diversifier archetype, anchoring Nordic capacity for compressed nutrient bars with extended stability profiles.
| Leading Market Players |
|---|
| Nutriset |
| Mani |
| Edesia Nutrition |
| Valid Nutrition |
| GC Rieber Compact |
| Hilina Enriched Foods |
| Candyland |
| Compact India |
| Diva Nutritional Products |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between WHO-prequalified formulations and non-prequalified commodity alternatives manifests in both pricing power and supply chain configuration. Premium-tier manufacturers command procurement preference through UNICEF Supply Division relationships while commodity producers face margin compression from peanut price volatility and localization mandates in Ethiopia and Nigeria.
Pricing Analysis
Bundled service contracts combining formulation supply with technical assistance and training command procurement preference from Médecins Sans Frontières and Save the Children, while unbundled transactional pricing dominates spot purchases from smaller NGOs. Price differentiation rests on WHO prequalification status and domestic production quota compliance in sub-Saharan African markets. Pricing pressure intensifies in powder supplement tiers as Indian manufacturers scale Gujarat and Maharashtra capacity for African export. Humanitarian agencies exhibit highest price sensitivity due to fixed programmatic budgets, whereas military procurement offices in Australia and the UK accept premium positioning for five-year stability specifications.
Supply Chain Analysis
Dual-sourcing requirements from UNICEF and WHO procurement guidelines mandate multi-supplier qualification, forcing manufacturers to maintain redundant production lines across Normandy, Rhode Island, and Addis Ababa industrial zones. Raw material dependencies center on West African peanut clusters, Indian dairy protein isolates, and Nordic shea butter cooperatives. Supply chain risk concentrates in single-source vulnerability around Nutriset's patent-controlled lipid-paste formulations. Distribution runs through centralized UN Global Marketplace platforms that disintermediate traditional distributor networks in Kenya and Bangladesh.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in oleogel-based formulations that reduce peanut dependency while qualifying for EU Green Deal sustainable sourcing incentives. Local production scale-up in Ethiopia and India captures procurement localization mandates that redirect volume from French import dependency.
For Market Incumbents: To counter oleogel formulation disruption from Ethiopian manufacturers, Nutriset and GC Rieber Compact should accelerate backward integration into West African shea butter supply chains and expand Addis Ababa technical licensing agreements. Patent portfolio defense combined with regional production joint ventures preserves procurement relationships as WHO prequalification timelines compress. For New Entrants and Emerging Players: Military and outdoor recreation channel partners represent the most penetrable white-space target, with defense procurement offices in Australia and the UK piloting compressed nutrient bars for field ration displacement. Indian manufacturers should pursue FSSAI-Codex harmonization to access WHO prequalification for African humanitarian contracts, using powder supplement formats to bypass peanut supply constraints. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-size manufacturers lack EDI compliance infrastructure for UN Global Marketplace integration. Long-term viability favors asset-light formulators with regional production licensing models over capital-heavy integrated manufacturers. The signal to watch is REACH registration timeline compression for novel lipid carriers, which would accelerate oleogel adoption and reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into West African Shea Butter | Secures deforestation-free supply chains qualifying for EU Green Deal procurement scoring. |
| WHO Prequalification Fast-Track Investment | Compresses 14-18 month facility audit timelines to capture Ethiopian localization mandates. |
| Oleogel Formulation R&D Partnership | Reduces peanut dependency while enabling Ethiopian and Indian regional oil sourcing. |
| UN Global Marketplace EDI Compliance | Maintains procurement access as Médecins Sans Frontières shifts to pooled purchasing. |
| Military Channel Certification Program | Opens five-year stability specification contracts with Australian and UK defense offices. |
Research Methodology
Bottom-up humanitarian procurement modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with UNICEF Supply Division procurement officers, Ethiopian Food and Drug Authority regulators, FSSAI compliance leads, and Norwegian military ration program managers combined with secondary validation from WHO prequalification databases, ECHA REACH registration filings, and EU Green Deal sustainability disclosure frameworks. Triangulation across formulation patent filings, customs trade records for peanut and shea butter imports, and humanitarian agency programmatic expenditure reports anchored volume estimates.
Historical trendline analysis of RUTF procurement volumes from UNICEF Supply Division and Médecins Sans Frontières established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product type, end-user population, formulation architecture, and distribution channel dimensions. CAGRs derived from regression analysis of procurement localization mandate implementation timelines, peanut commodity price cycles, and WHO guideline revision frequencies. Forecast inputs included Ethiopian domestic production quota enforcement rates and FSSAI regulatory harmonization progress with Codex Alimentarius standards.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to West African drought frequency, EFSA novel food authorization timelines for alternative proteins, and REACH registration burden escalation for imported lipid ingredients. Deviation in WHO community-based management of acute malnutrition protocol revisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Growing Up Formula Market
Baby Food and Infant Formula
Hydrolyzed Formula Milk Powder Market
Baby Food and Infant Formula
Organic Follow Up Formula Market
Baby Food and Infant Formula
North America Baby Food Market
Baby Food and Infant Formula
Functional Milk Replacers Market
Baby Food and Infant Formula
Asia-Pacific Prebiotics for Infant Formula Market
Baby Food and Infant Formula
Global DHA Algae Oil for Infant Formula Market
Baby Food and Infant Formula
Baby Cereal-Based Complementary Food Market
Baby Food and Infant Formula
Baby Food Products Market
Baby Food and Infant Formula
Parenteral Formula Market
Baby Food and Infant Formula
Japan Baby Food and Infant Formula Market
Baby Food and Infant Formula
Infant Nutrition Market
Baby Food and Infant Formula
Baby Fruit Puree Market
Baby Food and Infant Formula
Global Oligosaccharides in Infant Nutrition Market
Baby Food and Infant Formula
Pureed Food Market
Baby Food and Infant Formula
Baby Formula Ingredients Market