
 BRIC Organic Baby Food Market | 2026-2036
BRIC Organic Baby Food Market Size, Share, and Industry Trends Forecast 2026-2036
BRIC Organic Baby Food Market Outlook
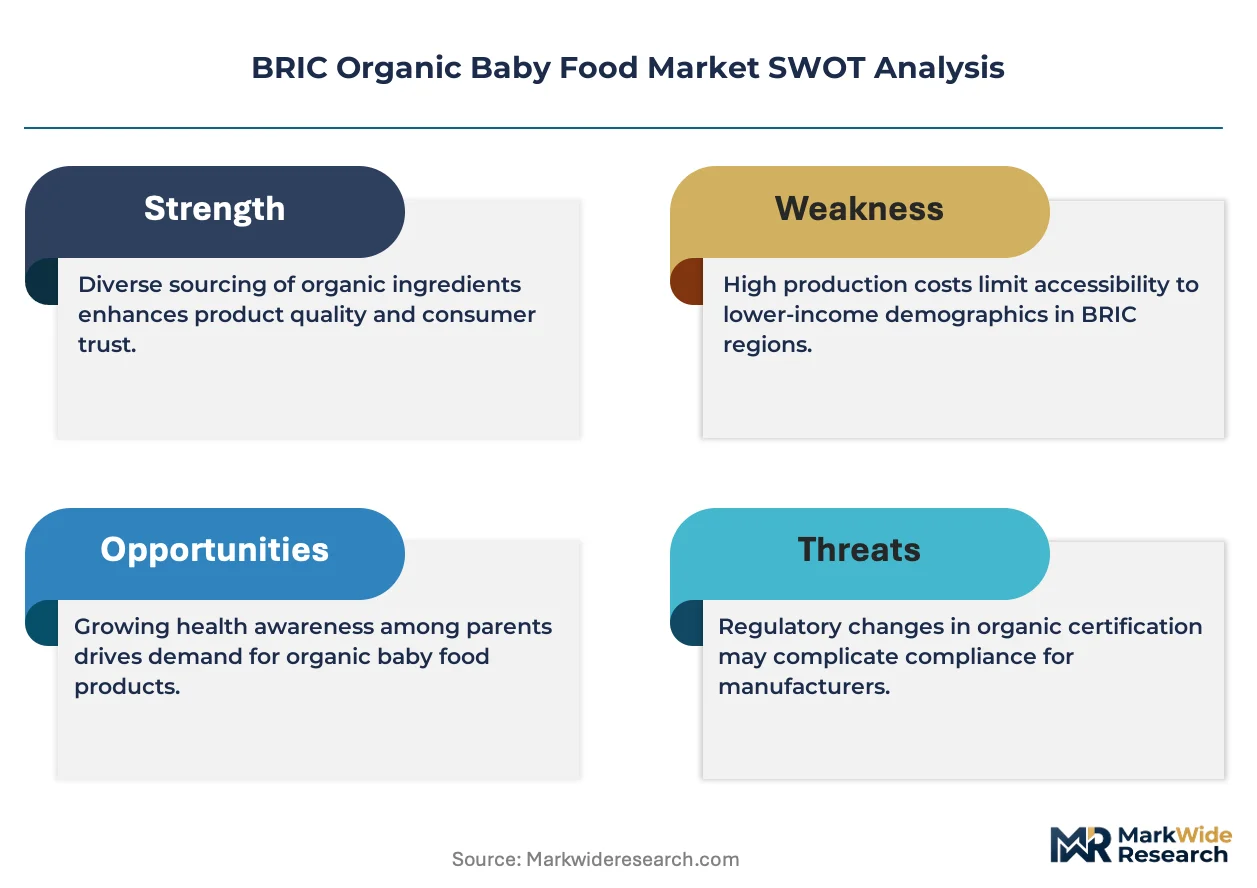
Brazil's domestic organic ingredient sourcing is narrowing as local agricultural cooperatives expand certified hectarage for baby food-grade produce. Nestle leverages its dairy supply network across Minas Gerais to secure raw material traceability. Danone anchors its competitive position through specialized fermentation capabilities for organic infant formula. Abbott Laboratories differentiates via clinical nutrition research partnerships with pediatric institutions in São Paulo and Rio de Janeiro.
BRIC organic baby food comprises minimally processed, certified organic formulations designed for infants and toddlers, typically free from synthetic pesticides, GMOs, and artificial additives, with protein content and micronutrient profiles calibrated to WHO infant feeding guidelines. The category serves parents seeking reduced chemical exposure during critical neurodevelopmental windows. Purees occupy the largest volume share due to extended shelf stability and lower per-unit price points accessible to mass-market Brazilian and Indian consumers. Online retail represents the fastest-expanding distribution channel, driven by direct-to-parent subscription models and tele-pediatrician recommendations in China's urban centers. Formula commands premium margin pools where organic certification and hypoallergenic positioning justify substantial price elevation over conventional alternatives.
FSSAI in India mandates organic label verification through accredited certifying bodies, while China's SAMR enforces GB 10765 infant formula standards with stringent contaminant thresholds. Brazil's MAPA organic certification program and ANVISA's updated infant food microbiological criteria collectively elevate compliance costs for new entrants. Stakeholders must monitor evolving pesticide residue limits and cross-border e-commerce duty structures that determine pricing accessibility across the four-nation bloc.
Market Dynamics
Urban millennial parents across São Paulo and Mumbai are rewriting procurement patterns through e-commerce subscription models that lock in recurring revenue streams and reduce customer acquisition costs for organic baby food manufacturers.
Growth Catalysts
- FSSAI organic certification mandates:India's mandatory verification through accredited bodies is accelerating formal market entry and displacing informal suppliers who cannot meet documentation requirements.
- Tele-pediatrician recommendations:China's urban healthcare digitization is funneling new parents toward verified organic brands through clinician-endorsed digital platforms.
- Certified hectarage expansion:Brazilian agricultural cooperatives in Minas Gerais are scaling baby food-grade organic produce cultivation, tightening raw material security for domestic processors.
Market Restraints
- Organic ingredient cost premiums:Baby food-grade certified produce commands input cost multiples over conventional alternatives, compressing gross margins for mass-market positioning.
- Cross-border e-commerce duty volatility:Unpredictable tariff structures between Brazil, Russia, India and China fragment pricing consistency and complicate inventory planning.
- GB 10765 contaminant thresholds:China's SAMR-enforced infant formula standards impose technical barriers that exclude smaller processors lacking laboratory infrastructure.
Strategic Opportunities
- Tier-two city penetration in China:Organic baby food household penetration remains concentrated in Beijing, Shanghai, Shenzhen and Guangzhou, leaving Chengdu, Hangzhou and Wuhan as expansion targets.
- Specialized fermentation capabilities:Organic infant formula with hypoallergenic protein structures represents a technical differentiation vector for processors investing in bioprocessing infrastructure.
- Direct-to-parent subscription models:Tele-pediatrician-integrated digital platforms enable recurring revenue capture and reduce price sensitivity through convenience lock-in.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous compliance with FSSAI, MAPA, SAMR and EAEU organic standards extends product launch cycles and strains regulatory affairs capacity.
- Cold chain integrity for fresh purees:Temperature-controlled distribution infrastructure gaps in Indian and Russian secondary cities limit shelf-stable format diversification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BRIC Organic Baby Food Market |
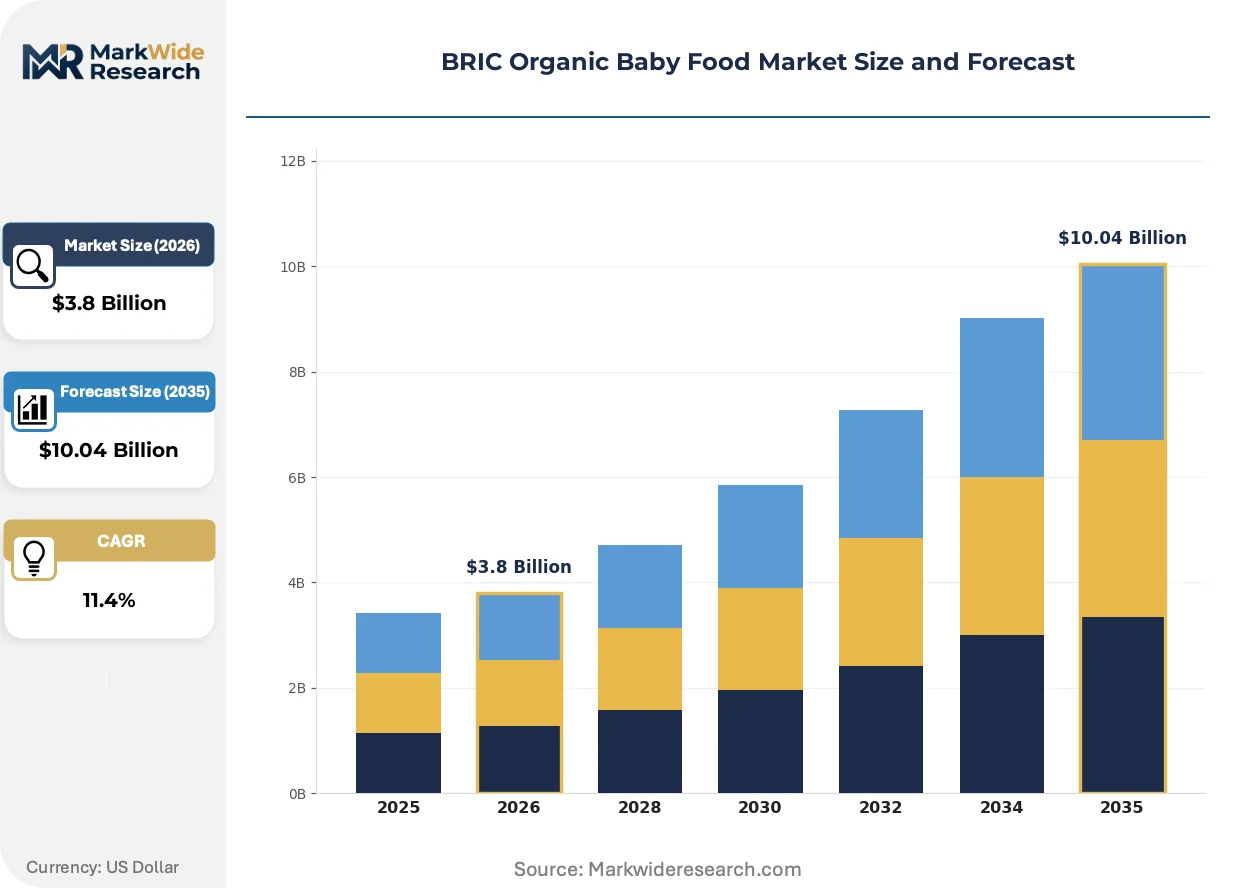
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purees, Snacks, Cereals, Formula Ingredient Type: Fruits, Vegetables, Grains, Meat Distribution Channel: Supermarkets, Online Retail, Health Stores, Baby Specialty Shops Age Group: Infants, Toddlers, Preschoolers, Newborns |
| Companies Covered | Nestle, Danone, Abbott Laboratories, The Kraft Heinz Company, Hain Celestial Group, Hero Group, Bellamy’s Organic, Campbell Soup Company, British Biologicals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BRIC Organic Baby Food Market Strategic Shifts
Digital health integration and precision fermentation are compressing traditional boundaries between clinical nutrition science and mass-market organic positioning across the BRIC bloc.
High-pressure processing is collapsing the shelf-life gap between fresh and preserved organic purees without thermal nutrient degradation. Premium-positioned parents in São Paulo and Mumbai are adopting HPP-treated products at subscription velocities previously reserved for ambient formats. This technology is collapsing the traditional trade-off between nutritional integrity and distribution reach that has constrained fresh organic expansion.
FSSAI's updated organic label verification protocols are forcing documentation standardization across Indian supply chains. Domestic processors must now maintain batch-level traceability records that were previously voluntary. The pureed fruit and vegetable segment faces the steepest compliance cost escalation as informal ingredient sourcing networks prove incompatible with accredited body audits.
Subscription bundling with pediatric telehealth services is displacing standalone product purchasing in China's tier-one cities. New parents in Beijing and Shanghai are prioritizing platforms that combine organic formula delivery with 24-hour clinician access over traditional retail price comparison. This behavior shift concentrates volume with vertically integrated providers capable of healthcare partnership negotiations.
BRIC Organic Baby Food Market Segmentation
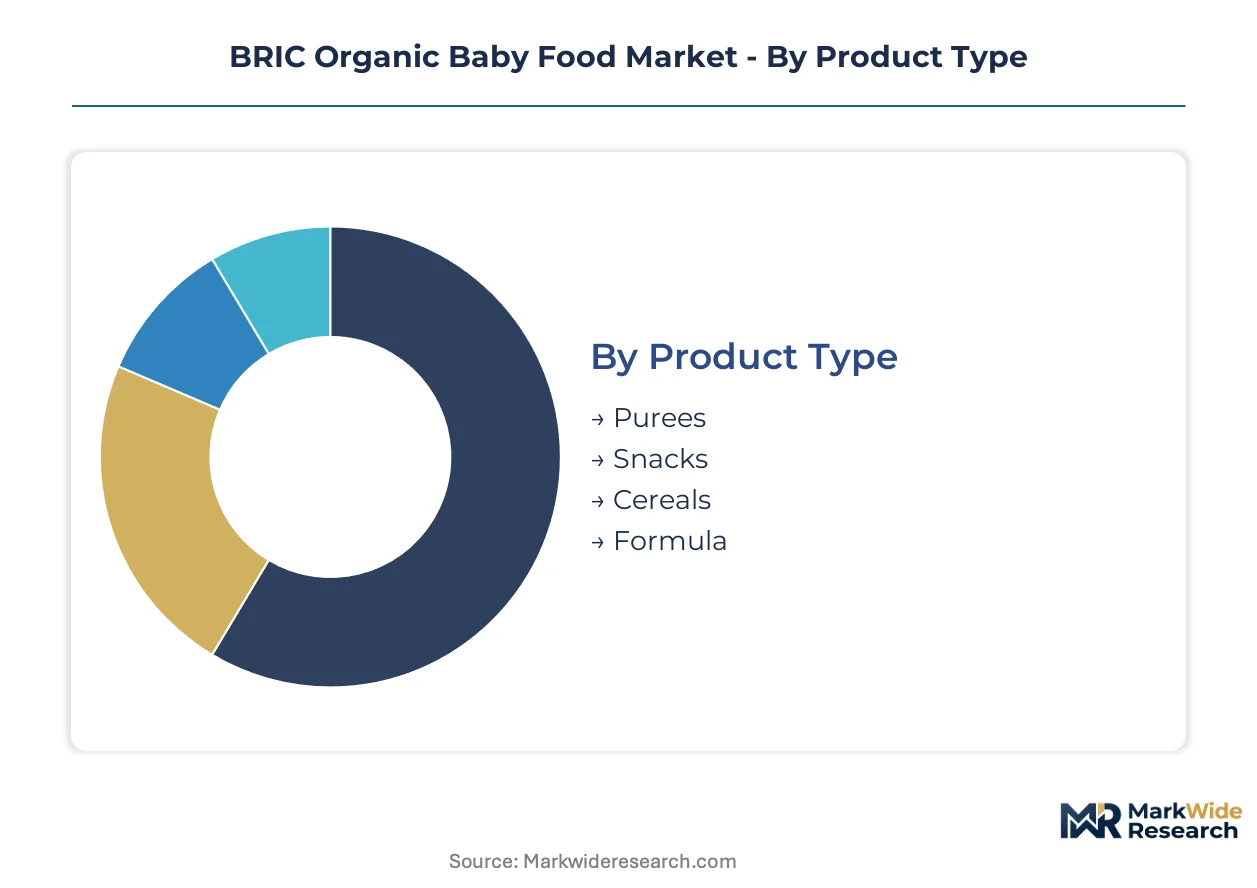
Segmentation in the BRIC organic baby food market reveals how procurement patterns diverge across income tiers, feeding stages, and retail infrastructures. Manufacturers calibrate formulation, packaging, and channel strategy against these divides to capture recurring purchase occasions.
Product Type:
Cost tier differentiation separates mass-accessible formats from premium-positioned nutritional solutions across Brazilian and Chinese households.
- Formula:Hypoallergenic protein structures and organic certification command substantial price elevation over conventional alternatives. Demand concentrates in China's tier-one cities where SAMR-enforced GB 10765 standards filter out smaller competitors lacking laboratory infrastructure.
- Purees:Minimally processed fruit and vegetable blends with extended shelf stability anchor volume share. Mass-market Brazilian and Indian consumers access these through lower per-unit price points, though FSSAI batch-level traceability mandates now displace informal ingredient networks.
- Snacks:Finger-food formats for toddler self-feeding stages.
- Cereals:Iron-fortified grain blends targeting complementary feeding transitions.
Formula holds installed capacity. Purees are rotating up the share rankings.
Ingredient Type:
Application-specific sourcing requirements determine which agricultural cooperatives qualify for baby food-grade certification.
- Fruits:High-pressure processed purees without thermal degradation dominate premium positioning. São Paulo and Mumbai parents subscribe to HPP-treated products at velocities previously reserved for ambient formats.
- Vegetables:Root and leafy varieties face steepest FSSAI compliance cost escalation as informal sourcing networks fail accredited body audits.
- Grains:Cereal base ingredients for iron-fortified complementary foods.
- Meat:Protein concentrates for specialized formula applications.
Vegetables hold installed capacity. Fruits are climbing the fastest.
Distribution Channel:
Customer type and purchasing occasion split between planned stock-up trips and convenience-driven digital replenishment.
- Online Retail:Direct-to-parent subscription models with tele-pediatrician integration capture recurring revenue and reduce price sensitivity through convenience lock-in. Beijing and Shanghai parents prioritize platforms combining organic formula delivery with 24-hour clinician access.
- Supermarkets:Mass-market penetration depends on shelf-stable formats and promotional bundling for price-conscious Brazilian consumers.
- Health Stores:Curated organic assortments targeting certification-focused parents.
- Baby Specialty Shops:Personalized consultation environments for first-time parents navigating feeding transitions.
Supermarkets hold installed capacity. Online Retail is gaining share fastest.
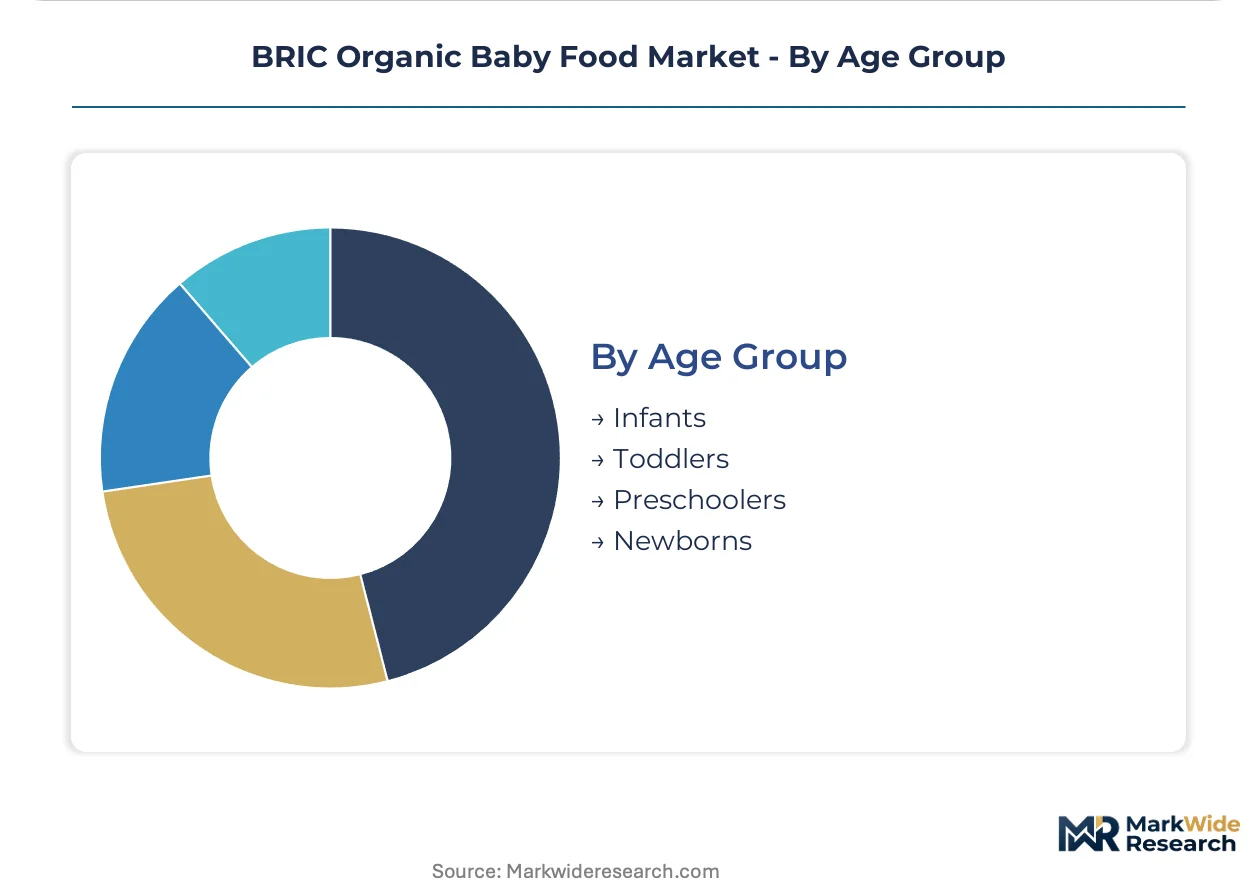
Age Group:
Volume concentration tracks birth cohort sizes and feeding stage durations across the four-nation bloc.
- Infants:Formula and early complementary foods calibrated to WHO feeding guidelines. China's urban healthcare digitization funnels new parents toward verified organic brands through clinician-endorsed platforms.
- Toddlers:Expanded texture ranges and self-feeding formats. São Paulo and Mumbai millennial parents drive adoption through e-commerce subscriptions for this stage.
- Preschoolers:Continued organic snacking occasions beyond core feeding windows.
- Newborns:Colostrum-transition and early formula feeding requiring highest safety verification.
Infants hold installed capacity. Toddlers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Nhava Sheva Port container terminal underwrites India's import-export capacity for certified organic ingredients, while São Paulo's Guarulhos cargo hub anchors Brazilian distribution networks for temperature-sensitive formulations.
Brazil
Minas Gerais agricultural cooperatives expand certified hectarage for baby food-grade produce, tightening domestic sourcing security. ANVISA's updated infant food microbiological criteria elevate compliance barriers for imported formulations. São Paulo's urban millennial parents drive e-commerce subscription adoption through tele-pediatrician-integrated platforms.
Russia
Moscow and St. Petersburg concentrate household penetration for premium organic formula despite import substitution pressures. The EAEU technical regulations for food safety harmonize certification requirements across member states. Cold chain infrastructure gaps in secondary cities constrain fresh puree distribution beyond shelf-stable formats.
India
FSSAI organic label verification mandates displace informal suppliers lacking accredited body documentation. Maharashtra and Karnataka urban clusters show strongest subscription model uptake among dual-income professional households. Domestic processors face batch-level traceability cost escalation as voluntary sourcing networks fail audit compliance.
China
SAMR-enforced GB 10765 infant formula standards filter competitors lacking laboratory infrastructure for contaminant testing. Tier-one cities Beijing, Shanghai, Shenzhen and Guangzhou concentrate premium positioning penetration. Tele-pediatrician recommendation platforms funnel new parents toward verified organic brands through clinician-endorsed digital channels.
BRIC Organic Baby Food Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying certified organic ingredients and specialized fermentation inputs. The vendor base stratifies across multinational nutrition conglomerates with dairy supply network control, mid-scale regional processors leveraging local agricultural cooperative partnerships, and niche organic specialists competing on hypoallergenic positioning. Dominant competitive moves include backward integration into certified organic ingredient sourcing and geographic expansion through e-commerce subscription platform partnerships.
Among the multinational nutrition conglomerates, Nestle, Danone and Abbott Laboratories occupy positions defined by supply network scale and clinical research partnerships. Nestle leverages its Minas Gerais dairy infrastructure for raw material traceability. Danone exemplifies the specialized fermentation capability archetype for organic infant formula differentiation. Abbott Laboratories represents the clinical nutrition research vector through pediatric institution partnerships in São Paulo and Rio de Janeiro.
| Leading Market Players |
|---|
| Nestle |
| Danone |
| Abbott Laboratories |
| The Kraft Heinz Company |
| Hain Celestial Group |
| Hero Group |
| Bellamy's Organic |
| Campbell Soup Company |
| British Biologicals |
| Others |
Value Chain & Pricing Dynamics
Minas Gerais dairy cooperative concentration anchors raw material security for Brazilian processors, concentrating margin pools with manufacturers who control certified organic hectarage rather than those dependent on spot ingredient markets. Nestle's captive supply network exemplifies how upstream control translates to pricing power in formula segments where SAMR contaminant thresholds filter smaller competitors.
Pricing Analysis
GB 10765 dictates the pricing tier structure across China's organic infant formula segment, with SAMR-enforced laboratory infrastructure requirements creating a dual-tier market. Three-tier pricing structure across premium, standard, and economy levels separates hypoallergenic protein formulations from conventional organic lines and basic certified products. Cost compression in the economy tier is intensifying because FSSAI batch-level traceability mandates escalate compliance burdens for mass-market Indian processors. Dual-income professional households in Maharashtra and Karnataka show lowest price sensitivity, while mass-market Brazilian consumers remain most responsive to per-unit promotional bundling.
Supply Chain Analysis
Tariff exposure between Brazil and China dominates supply chain risk planning for multinational processors sourcing baby food-grade organic produce across the BRIC bloc. Certified ingredient sourcing draws from Minas Gerais dairy cooperatives, Maharashtra fruit cultivation clusters, and Heilongjiang grain production zones. Single-source vulnerability concentrates in high-pressure processing equipment and specialized fermentation inputs where European and Japanese suppliers hold technical leadership. Distribution runs through São Paulo's Guarulhos cargo hub for temperature-sensitive formulations and Nhava Sheva Port for Indian ingredient import-export capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The BRIC organic baby food market sits in a cyclical upswing driven by birth cohort recovery in India's urban clusters and China's tier-two city expansion, creating favorable conditions for capacity deployment and margin defense.
For Market Incumbents: Harden certified organic hectarage control through cooperative equity stakes in Minas Gerais and Maharashtra, neutralizing raw material cost volatility that compresses mass-market positioning. Deepen tele-pediatrician platform partnerships in Beijing and São Paulo to lock in subscription recurring revenue against emerging direct-to-consumer specialists. For New Entrants and Emerging Players: Build out tier-two city distribution in Chengdu, Hangzhou and Wuhan where organic baby food penetration lags Beijing-Shanghai benchmarks by substantial household adoption gaps. Target HPP-treated fresh puree segments where shelf-life technology collapses the traditional trade-off between nutritional integrity and distribution reach. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale regional processors with existing FSSAI or MAPA certification infrastructure and underutilized fermentation capacity suitable for hypoallergenic formula pivot. Long-term viability hinges on regulatory compliance scalability rather than brand equity alone. Watch SAMR pesticide residue limit revisions as the signal indicating margin compression or expansion for import-dependent formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Hectarage | Minas Gerais cooperative partnerships secure traceability required by ANVISA microbiological criteria. |
| Tele-Pediatrician Platform Integration | Beijing and Shanghai parents prioritize clinician-endorsed organic formula delivery over retail price comparison. |
| High-Pressure Processing Capacity Expansion | HPP technology collapses shelf-life gaps between fresh and preserved purees without thermal nutrient degradation. |
| Tier-Two City Distribution Buildout | Chengdu and Wuhan household penetration trails tier-one benchmarks, creating expansion white space. |
| Hypoallergenic Protein Structure R&D | Specialized fermentation capabilities differentiate organic infant formula in SAMR-regulated China markets. |
Study Parameters
Desk research of FSSAI certification databases, SAMR GB standard filings, and ANVISA regulatory updates preceded structured interviews with organic baby food brand managers, agricultural cooperative procurement leads, pediatric telehealth platform operators, and cold chain logistics specialists. Secondary validation drew from customs trade records, e-commerce subscription platform disclosures, and accredited organic certifying body audit reports. Bottom-up volume modeling triangulated against top-down macroeconomic consumption projections across the analysis window.
Assumptions held fixed include current FSSAI organic label verification protocols, SAMR contaminant threshold enforcement intensity, and EAEU technical regulation harmonization scope; variables stress-tested include cross-border e-commerce duty volatility, birth cohort fluctuations, and cold chain infrastructure buildout pace in Indian and Russian secondary cities. Segmentation dimensions encompassed product type, ingredient category, distribution channel, and age group feeding stages. CAGRs derived from regression analysis against historical premium food category adoption curves and urban income elasticity coefficients, with pediatric recommendation platform penetration rates and certified organic hectarage expansion serving as key forecast inputs.
Stress conditions across tariff structures, birth rate trajectories, and regulatory compliance cost escalation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding tele-pediatrician adoption velocity and cooperative certification scalability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
United States Baby Food and Infant Formula Market
Baby Food and Infant Formula
Baby Fruit Puree Market
Baby Food and Infant Formula
Canned Baby Food Market
Baby Food and Infant Formula
Middle-Aged and Elderly Milk Powder Market
Baby Food and Infant Formula
Hypo Anti Allergic Baby Food Market
Baby Food and Infant Formula
Japan Baby Food and Infant Formula Market
Baby Food and Infant Formula
Infant Food Compliance Ready Fertility Input Market
Baby Food and Infant Formula
Parenteral Formula Market
Baby Food and Infant Formula
Middle East and Africa Baby Food Market
Baby Food and Infant Formula
Organic Follow Up Formula Market
Baby Food and Infant Formula
Pet Milk Replacement Products Market
Baby Food and Infant Formula
Organic Baby Food Market
Baby Food and Infant Formula
Global Oligosaccharides in Infant Nutrition Market
Baby Food and Infant Formula
Asia-Pacific Prebiotics for Infant Formula Market
Baby Food and Infant Formula
Ready to Use Supplementary Food Market
Baby Food and Infant Formula
Baby Food Market