
 Infant Nutritional Premix Market | 2026-2036
Infant Nutritional Premix Market Size, Share, and Industry Trends Forecast 2026-2036
Infant Nutritional Premix Market Outlook
EU MDR alignment for nutritional fortification is repositioning the cost-of-entry calculus for premix suppliers seeking European market access. DSM leverages backward integration into vitamin synthesis to sustain margin control across its premix portfolio. Glanbia PLC anchors its competitive stance through specialized dairy-protein premix capabilities. BASF SE differentiates via technology leadership in micronutrient encapsulation systems.
An infant nutritional premix is a precisely blended matrix of vitamins, minerals, probiotics, and amino acids manufactured through spray-drying or liquid homogenization to achieve uniform particle distribution and bioavailability in infant formula applications. Powdered premixes dominate current volume due to extended shelf stability and lower logistics costs, while liquid premixes capture faster growth in ready-to-drink formula lines where dissolution speed determines processing economics. The ingredient dimension shows vitamins and minerals commanding established margin pools, whereas probiotic premixes attract premium positioning from healthcare provider channels seeking digestive health claims.
FDA infant formula regulations, EFSA health claim frameworks, and China's SAMR national food safety standards collectively tighten compositional verification requirements and traceability obligations across supply chains. These frameworks elevate demand for third-party certified premixes while filtering out non-compliant regional blenders. Stakeholders must monitor evolving maximum-limit protocols for iron and vitamin D across jurisdictions to preempt reformulation cycles.
Market Dynamics
China's SAMR national food safety standards are compressing supplier margins while elevating traceability requirements across infant formula supply chains, forcing premix manufacturers to absorb certification costs or exit the market entirely.
Growth Catalysts
- China's SAMR standards:Tighter compositional verification mandates filter out non-compliant regional blenders, consolidating procurement toward certified suppliers capable of third-party documentation.
- Probiotic premix formats:Healthcare provider channels seeking digestive health claims drive premium positioning for live-culture formulations with documented CFU stability through shelf life.
- Powdered premix logistics:Extended shelf stability and lower cold-chain requirements enable domestic brands to achieve import substitution without infrastructure overhaul.
Market Restraints
- Vitamin raw material concentration:Backward integration into vitamin synthesis limits viable supply sources to a handful of chemical producers, exposing formulators to input cost volatility.
- Iron and vitamin D maximum limits:Jurisdictional variation in permissible fortification levels forces parallel inventory SKUs and complicates cross-border formula exports.
- Liquid premix substitution:Ready-to-drink formula lines favor liquid homogenization over spray-dried powders, threatening volume share in convenience-oriented segments.
Strategic Opportunities
- EU MDR alignment:Premix suppliers achieving European medical device regulation certification access premium hospital-channel contracts with higher margin retention.
- Micronutrient encapsulation:Advanced coating technologies protecting heat-sensitive vitamins during thermal processing open contract manufacturing relationships with mid-tier formula brands.
- South Asian expansion:Underdeveloped premix infrastructure in India and Bangladesh creates first-mover positioning for suppliers with FSSAI-compliant documentation systems.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in bioavailability optimization and particle-size distribution control commands premium compensation, constraining R&D throughput at mid-size blenders.
- Legacy ERP integration:Batch-level traceability requirements under evolving FDA infant formula regulations force expensive system overhauls for established manufacturers with dated infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infant Nutritional Premix Market |
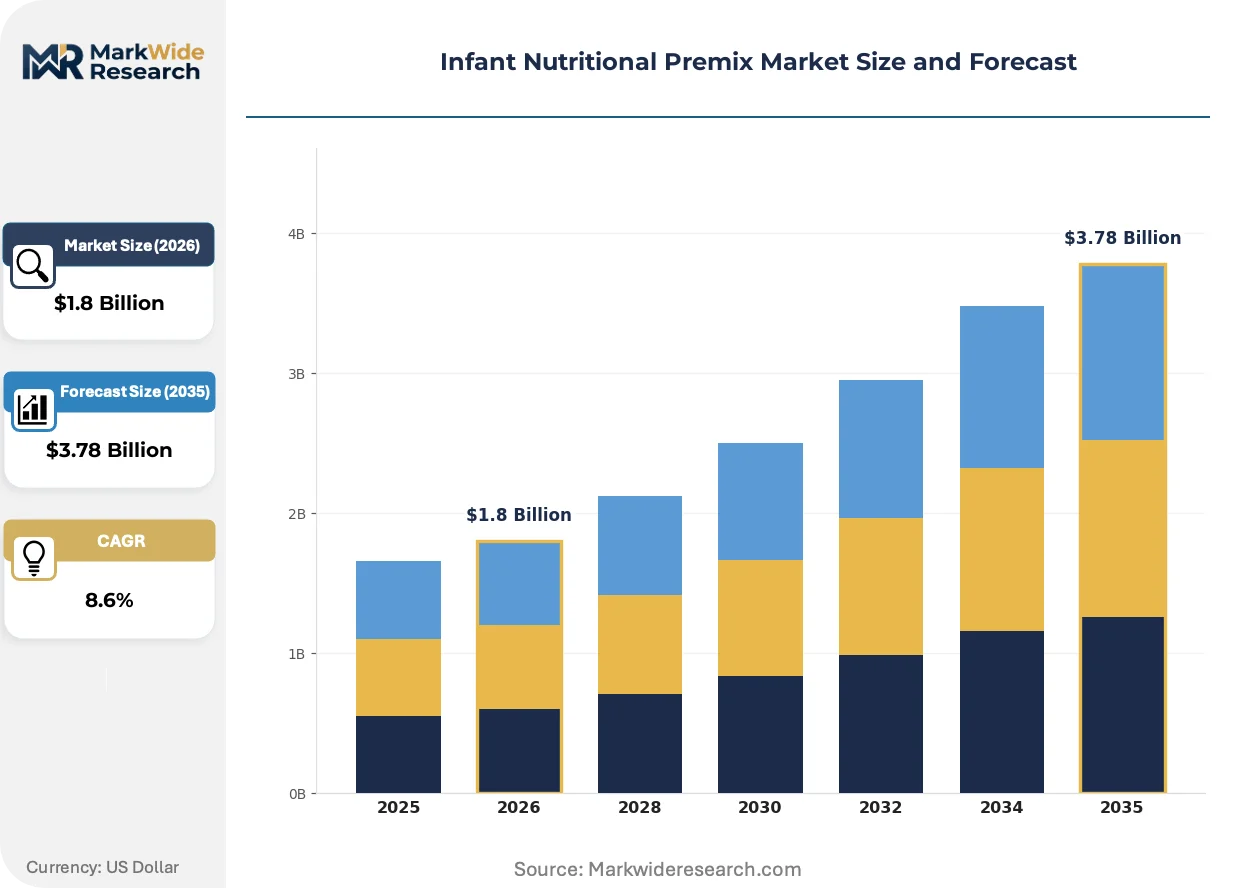
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Premixes, Liquid Premixes, Ready-to-Use Products, Fortified Formulas Ingredient Type: Vitamins, Minerals, Probiotics, Amino Acids Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores End User: Parents, Healthcare Providers, Pediatricians, Childcare Facilities |
| Companies Covered | Nestle, Prinova, BASF SE, Vitablend, Barentz International, Glanbia PLC, Royal FrieslandCampina, Watson Inc., DSM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infant Nutritional Premix Market Strategic Shifts
Spray-drying equipment upgrades and encapsulation chemistry advances are compressing unit economics while regulatory harmonization efforts reshape competitive access across major consuming regions.
Microencapsulation technology using lipid-shell matrices is consolidating quality differentiation in vitamin-mineral premixes. Large-scale formula manufacturers in Germany and the Netherlands are adopting these systems to reduce overage requirements and improve dissolution uniformity. The technology is consolidating supplier tiers by raising minimum viable scale for R&D investment.
EFSA health claim frameworks are tightening evidentiary standards for probiotic strain-specific marketing. Infant formula brands must now submit clinical trial data to support digestive health positioning, elevating documentation costs for premix partners. European manufacturers are responding by consolidating strain portfolios around well-documented cultures with existing dossiers.
Direct procurement relationships between formula brands and vitamin synthesis houses are displacing traditional distributor intermediaries in high-volume contracts. Chinese domestic brands with SAMR certification are negotiating captive supply arrangements to secure input cost visibility. This pattern is most visible in vitamin A and D3 sourcing, where backward integration offers margin defense against commodity swings.
Infant Nutritional Premix Market Segmentation
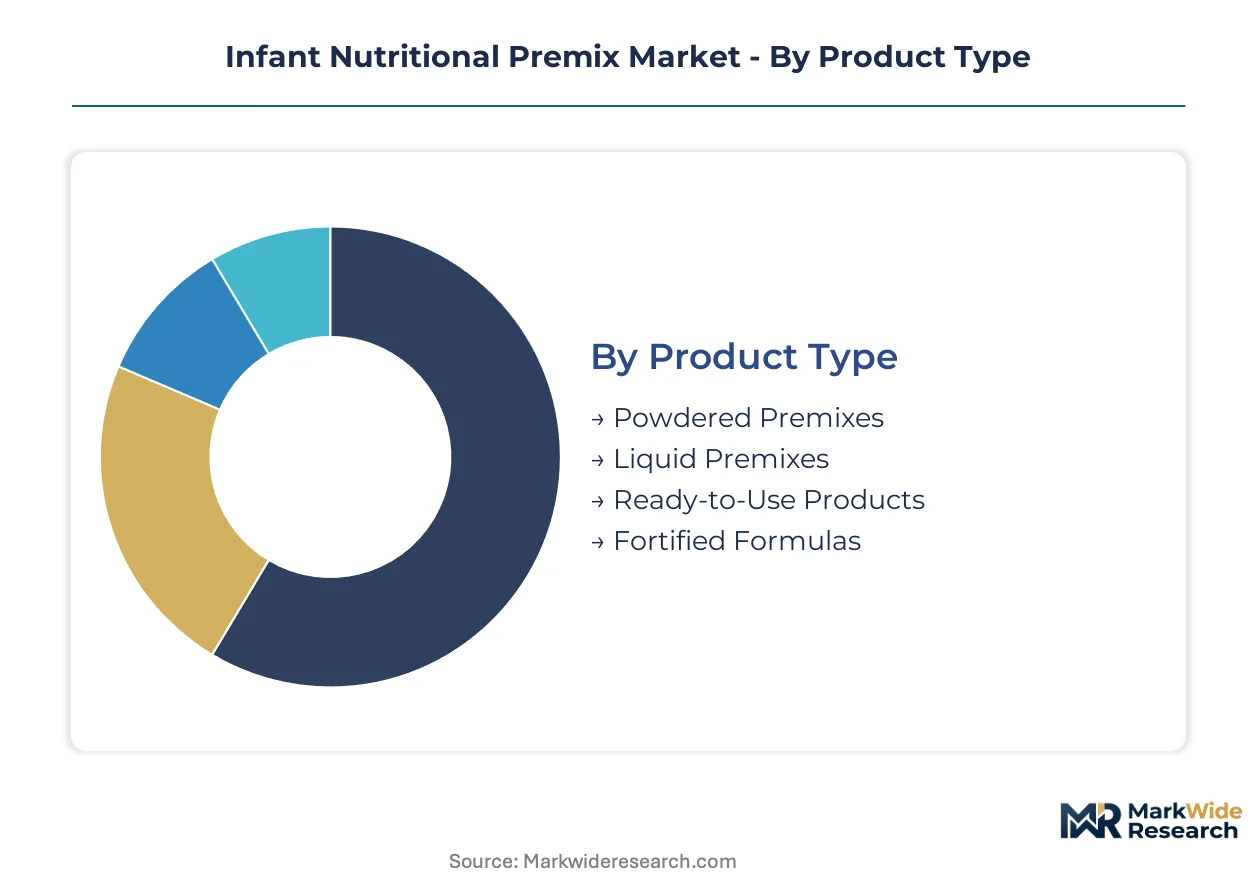
Segmentation in infant nutritional premixes reveals how regulatory complexity fragments procurement patterns across product formats and ingredient classes. Certification requirements from SAMR, FDA, and EFSA create divergent margin structures that reshape supplier prioritization.
Product Type:
Powdered premixes carry lighter cold-chain documentation burdens than liquid alternatives, while ready-to-use formats trigger stricter medical-device scrutiny in European hospital channels.
- Powdered Premixes:Spray-dried matrices of micronutrients achieve 24-36 month stability through moisture-controlled packaging. Domestic Chinese brands under SAMR compliance mandates concentrate procurement here to bypass import infrastructure costs.
- Liquid Premixes:Homogenized suspensions dissolve instantly in ready-to-drink processing lines. German and Dutch formula manufacturers adopt these systems despite higher logistics overhead, driven by dissolution-speed economics in premium convenience segments.
- Ready-to-Use Products:Pre-blended complete nutrition solutions requiring sterile manufacturing protocols.
- Fortified Formulas:Base powders with embedded micronutrient layers for downstream blending flexibility.
Powdered premixes sit at the top of the volume ranking, with liquid premixes climbing the fastest.
Ingredient Type:
Margin concentration follows bioavailability complexity, with heat-sensitive compounds commanding premium positioning over commodity minerals.
- Vitamins:Lipid-soluble and water-soluble compounds requiring encapsulation for thermal stability. Vitamin A and D3 sourcing concentrates among backward-integrated synthesis houses in China and Switzerland, squeezing independent blenders on input costs.
- Probiotics:Live-culture formulations with documented CFU stability through shelf life. Healthcare provider channels in Europe and North America drive premium positioning here, though EFSA health claim frameworks now demand strain-specific clinical dossiers.
- Minerals:Elemental iron, zinc, and calcium compounds with established compendial standards.
- Amino Acids:Protein hydrolysates and free-form building blocks for specialized metabolic needs.
Vitamins dominate current revenue pools, while probiotics gain share fastest on clinical positioning.
Distribution Channel:
Channel selection determines traceability depth, with pharmacy and specialty retail imposing batch-level documentation that online platforms currently escape.
- Online Retail:Direct-to-consumer platforms expanding in Southeast Asian markets with lighter regulatory friction. Cross-border e-commerce channels in China bypass traditional import licensing for small-package premix sales.
- Supermarkets:Mass-market shelf placement requiring standardized packaging and multilingual labeling. Domestic brand penetration concentrates here in India and Bangladesh as FSSAI compliance becomes mandatory.
- Pharmacies:Professional recommendation channels with formulary inclusion requirements.
- Specialty Stores:Premium positioning venues for organic and allergen-free positioning.
Supermarkets anchor volume throughput, with online retail expanding most quickly in emerging markets.
End User:
User-type segmentation splits between clinical decision-makers with institutional purchasing power and individual caregivers prioritizing convenience and price transparency.
- Parents:Individual purchasers responding to pediatrician recommendations and digital health content. Chinese millennial parents demonstrate strongest willingness to pay for third-party certified premixes following domestic formula safety incidents.
- Healthcare Providers:Hospital systems and clinics with formulary committees and contract manufacturing relationships. EU MDR alignment opens premium hospital-channel contracts for certified premix suppliers in Germany, France, and the Netherlands.
- Pediatricians:Specialist prescribers influencing parental brand selection through clinical guidance.
- Childcare Facilities:Institutional bulk purchasers with standardized nutrition protocols.
Parents represent the largest addressable base, with healthcare providers delivering the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists with micronutrient blending expertise cluster in Germany, Switzerland, and the Netherlands, anchoring European premix innovation. Chinese manufacturers now rival this talent concentration through state-funded food science institutes in Beijing and Shanghai.
China
Domestic infant formula brands under SAMR compliance mandates are consolidating procurement toward certified premix suppliers with third-party documentation capabilities. The national food safety standards now require batch-level traceability from vitamin synthesis through finished product. Yangtze River Delta manufacturing clusters around Shanghai host the fastest-growing premix blending capacity serving domestic import substitution strategies.
Germany
Large-scale formula manufacturers in Bavaria and North Rhine-Westphalia drive demand for microencapsulated vitamin systems that reduce thermal processing losses. EFSA health claim frameworks now require strain-specific clinical dossiers for probiotic premix positioning. Frankfurt and Munich serve as regulatory compliance hubs where premix suppliers align documentation with EU MDR hospital-channel requirements.
United States
FDA infant formula regulations are forcing legacy manufacturers toward ERP system overhauls for batch-level traceability compliance. Pediatrician-recommended brands concentrate procurement through pharmacy and specialty retail channels with formulary inclusion requirements. Greater Boston and Research Triangle Park host the densest concentration of bioavailability optimization R&D serving contract manufacturing relationships.
India
FSSAI compliance mandates are filtering out non-compliant regional blenders as domestic brands expand supermarket shelf placement. Underdeveloped premix infrastructure creates first-mover positioning for suppliers with documented quality systems. Maharashtra and Gujarat industrial corridors attract the initial wave of multinational premix manufacturing investments targeting South Asian market expansion.
Switzerland
Backward-integrated vitamin synthesis houses in Basel and Geneva anchor global supply for lipid-soluble compounds used in premium premix formulations. Swissmedic regulatory alignment opens premium hospital-channel contracts across European markets. Zurich-based technical service teams support formula manufacturers with particle-size distribution optimization and dissolution uniformity testing.
Infant Nutritional Premix Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered supplier categories. The market structure shows concentration at the vitamin synthesis level and fragmentation among downstream blenders. Three archetypes dominate: backward-integrated chemical producers, specialized dairy-protein premix fabricators, and micronutrient encapsulation technology leaders. Competitive moves center on captive supply arrangements with formula brands and certification investments for SAMR and EU MDR alignment.
Within the technology-leadership tier, BASF SE and DSM exemplify the backward-integrated model controlling vitamin synthesis inputs. Glanbia PLC occupies a position representing specialized dairy-protein premix capabilities. Among European encapsulation specialists, Vitablend and Barentz International sit within the contract manufacturing service layer serving mid-tier formula brands seeking technical differentiation without in-house R&D investment.
| Leading Market Players |
|---|
| Nestle |
| Prinova |
| BASF SE |
| Vitablend |
| Barentz International |
| Glanbia PLC |
| Royal FrieslandCampina |
| Watson Inc. |
| DSM |
| Others |
Value Chain & Pricing Dynamics
Premium-mid-economy pricing differentiation across infant nutritional premixes maps directly onto certification ladder rungs and input sourcing depth, with SAMR-compliant suppliers commanding substantial markups over regional blenders while absorbing parallel inventory costs from jurisdictional iron and vitamin D limit variations.
Pricing Analysis
Service bundling separates contract manufacturing relationships with technical support from commodity vitamin-mineral transactions, with encapsulation chemistry and dissolution uniformity testing packaged into per-kilogram premiums. Price differentiation rests on certification grade—SAMR, FDA, and EU MDR tiers—and volume scale, with large formula manufacturers negotiating captive supply arrangements. Pricing pressure stems from direct procurement between Chinese domestic brands and vitamin synthesis houses displacing distributor margins. Mid-tier blenders exhibit highest price sensitivity due to R&D throughput constraints, while hospital-channel suppliers with EU MDR alignment maintain pricing power.
Supply Chain Analysis
Regional distribution centers in Shanghai, Basel, and Frankfurt anchor hub-and-spoke patterns serving formula manufacturers with batch-level traceability documentation. Vitamin A and D3 synthesis concentrates in Switzerland and China, with probiotic strain cultivation clustering in Germany and the Netherlands. Raw material dependencies span lipid-soluble vitamin precursors, live-culture fermentation substrates, and encapsulation shell matrices. Single-source vulnerability runs through backward-integrated vitamin synthesis houses. Distribution runs through direct procurement relationships and third-party certified blender networks serving pharmacy and specialty retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Infant nutritional premix demand functions as a regulatory compounder, with China's SAMR national food safety standards mandating batch-level traceability that filters procurement toward certified suppliers.
For Market Incumbents: Deploy micronutrient encapsulation technology leadership to defend margin pools against liquid premix substitution in ready-to-drink segments. BASF SE and DSM sustain advantage through captive vitamin synthesis control. Consolidate contract manufacturing relationships with mid-tier formula brands seeking technical differentiation without in-house R&D investment. Absorb certification costs for EU MDR alignment to access premium hospital-channel contracts in Germany, France, and the Netherlands. For New Entrants and Emerging Players: Enter via South Asian expansion targeting underdeveloped premix infrastructure in India and Bangladesh, where FSSAI compliance mandates are filtering out non-compliant regional blenders. Concentrate procurement documentation capabilities and sterile manufacturing protocols for ready-to-use products. Pursue first-mover positioning through technical service teams supporting particle-size distribution optimization. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation chemist scarcity constrains R&D throughput at mid-size blenders. Long-term viability favors suppliers with backward integration into vitamin synthesis or specialized dairy-protein premix capabilities. Target acquisition archetypes include encapsulation technology specialists serving European hospital channels. Watch for SAMR certification completion rates among Chinese domestic brands as inflection indicator for import substitution momentum.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Opens premium hospital-channel contracts in Germany, France, and Netherlands with higher margin retention. |
| Backward Integration into Vitamin Synthesis | DSM and BASF SE defend input cost visibility against commodity swings in vitamin A and D3 sourcing. |
| Micronutrient Encapsulation Technology Deployment | Reduces thermal processing losses for Bavarian and Dutch formula manufacturers seeking dissolution uniformity. |
| South Asian Manufacturing Footprint Expansion | Maharashtra and Gujarat corridors attract multinational investment targeting FSSAI-compliant supermarket placement. |
| Direct Procurement Relationship Formation | Chinese domestic brands negotiate captive supply arrangements with synthesis houses, displacing distributor intermediaries. |
Study Parameters
Bottom-up infant formula manufacturer modeling reconciled against top-down vitamin synthesis capacity tracking forms the analytical core of this study. Primary interviews with formulation chemists, regulatory affairs leads at premix suppliers, procurement managers at domestic Chinese brands, and hospital formulary committees were combined with secondary validation. Secondary sources include SAMR batch-level traceability filings, EFSA health claim dossier submissions, FDA infant formula regulation updates, and customs data on vitamin-mineral premix trade flows. Triangulation across these inputs ensures segmentation integrity across product format, ingredient class, and distribution channel dimensions.
Input-output matrices map vitamin and mineral consumption coefficients per ton of finished infant formula against regional production capacity buildouts. Segmentation dimensions modeled span powdered versus liquid premix formats, vitamins versus probiotics versus minerals, online retail versus pharmacy channels, and parent versus healthcare provider end users. CAGRs were derived from slope analysis of procurement volume trajectories adjusted for regulatory compliance lag effects. Forecast inputs include SAMR certification completion timelines and EFSA strain-specific clinical dossier submission rates.
Inputs from SAMR batch traceability filings and EFSA health claim frameworks were available through the study window; gaps in real-time probiotic CFU stability data introduce uncertainty bands around live-culture premix growth projections. Forecasts reflect documented assumptions on regulatory harmonization pace and import substitution momentum in Chinese domestic brands. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Baby Infant Formula Market
Baby Food and Infant Formula
Human Milk Oligosaccharides in Infant Formula Market
Baby Food and Infant Formula
Kids Food and Beverages Market
Baby Food and Infant Formula
Asia-Pacific Baby Food Market
Baby Food and Infant Formula
A2 Infant Formula Market
Baby Food and Infant Formula
Baby Formula Market
Baby Food and Infant Formula
Canned Baby Food Market
Baby Food and Infant Formula
South America Organic Baby Food Market
Baby Food and Infant Formula
Cow Milk Infant Formula Market
Baby Food and Infant Formula
Vietnam Pet Food Market
Baby Food and Infant Formula
Second Stage Organic Infant Formula Market
Baby Food and Infant Formula
Hypo Anti Allergic Baby Food Market
Baby Food and Infant Formula
GCC Baby Food and Infant Formula Market
Baby Food and Infant Formula
Pureed Food Market
Baby Food and Infant Formula
BRIC Organic Baby Food Market
Baby Food and Infant Formula
Middle East and Africa Baby Food Market