
 North America Organic Baby Food Market | 2026-2036
North America Organic Baby Food Market Size, Share, and Industry Trends Forecast 2026-2036
North America Organic Baby Food Market Intelligence
Canadian organic ingredient sourcing is consolidating as North American producers secure reliable supply chains for fruit and vegetable purees. The Hain Celestial Group leverages its portfolio of natural brands to maintain shelf presence across mainstream retail channels. Danone S.A. anchors its position through specialized pediatric nutrition expertise and dairy-based organic offerings. Nestlé S.A. competes via extensive distribution infrastructure spanning supermarkets and pharmacy networks throughout the United States and Canada.
Organic baby food comprises minimally processed fruit, vegetable, grain, and protein formulations manufactured without synthetic pesticides, fertilizers, or genetically modified organisms, designed to deliver age-appropriate nutrition during critical early developmental stages. Pouches dominate volume due to convenience-driven parental purchasing and on-the-go consumption patterns, while jars retain steady demand among traditional buyers prioritizing transparency and lower per-unit cost. USDA Organic certification commands premium positioning across all product formats, with Non-GMO verification increasingly serving as a baseline expectation rather than a differentiator.
FDA infant formula and food safety standards intersect with USDA National Organic Program regulations to create a dual compliance framework that elevates production costs and barriers to entry. State-level initiatives in California and New York impose additional labeling and nutritional disclosure requirements that ripple across North American supply chains. Stakeholders must monitor evolving enforcement priorities at FDA and state agriculture departments while evaluating certification investments against shifting parental preference thresholds.
Market Dynamics
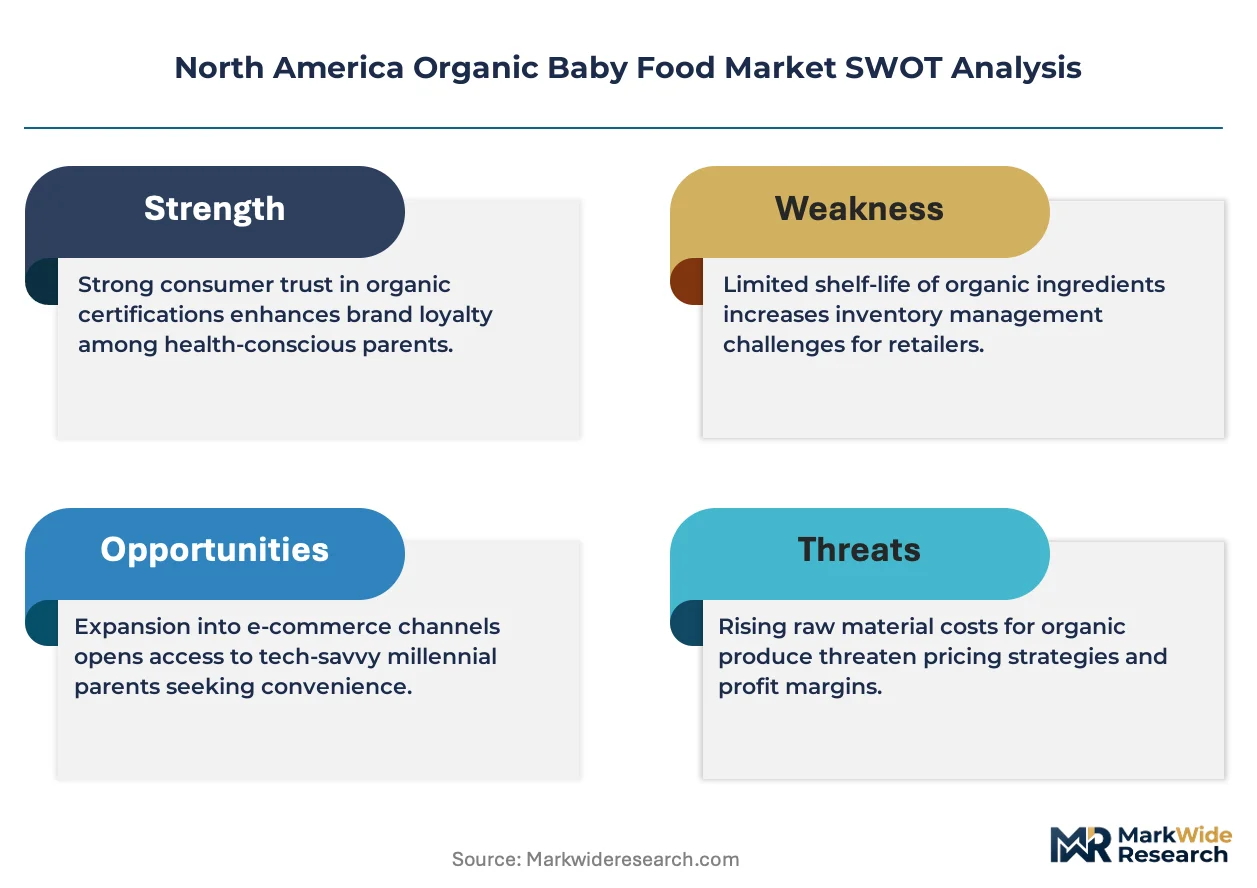
Millennial parental preference for transparent supply chains is compressing traditional retail margins and forcing manufacturers to absorb USDA Organic certification costs while maintaining pouch format dominance against jar alternatives.
Growth Catalysts
- USDA National Organic Program:Certification mandates create premium pricing power for compliant manufacturers across California and Northeast retail corridors.
- On-the-go consumption patterns:Urban working parents in Toronto, New York, and Los Angeles prioritize pouch portability over traditional jar formats.
- High-pressure processing (HPP):Cold pasteurization technology preserves nutrient density without synthetic preservatives, extending shelf life for refrigerated organic lines.
Market Restraints
- Organic ingredient cost volatility:Fruit and vegetable puree inputs face weather-dependent pricing swings from California Central Valley suppliers.
- FDA dual compliance burden:Infant formula safety standards layered atop USDA Organic requirements elevate testing and documentation overhead.
- Glass jar substitution threat:Traditional formats retain price-sensitive buyers in Midwest markets where per-unit cost transparency outweighs convenience.
Strategic Opportunities
- Subscription direct-to-channel models:Recurring delivery platforms bypass retail slotting fees and capture lifetime value from urban millennial households.
- Quebec and Ontario expansion:Canadian provincial markets show underpenetrated organic adoption relative to US coastal saturation levels.
- Clean-label convergence with allergen-free:USDA Organic certification paired with peanut-free and dairy-free formulations commands shelf space in pharmacy retail networks.
Industry Challenges
- Supply chain reconfiguration friction:Shifting from conventional to certified organic ingredient sourcing requires 36-month transition timelines for contract manufacturers.
- Talent scarcity in pediatric nutrition R&D:Formulation chemists with dual expertise in FDA infant food safety and organic processing standards command premium compensation in California and Massachusetts clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Organic Baby Food Market |
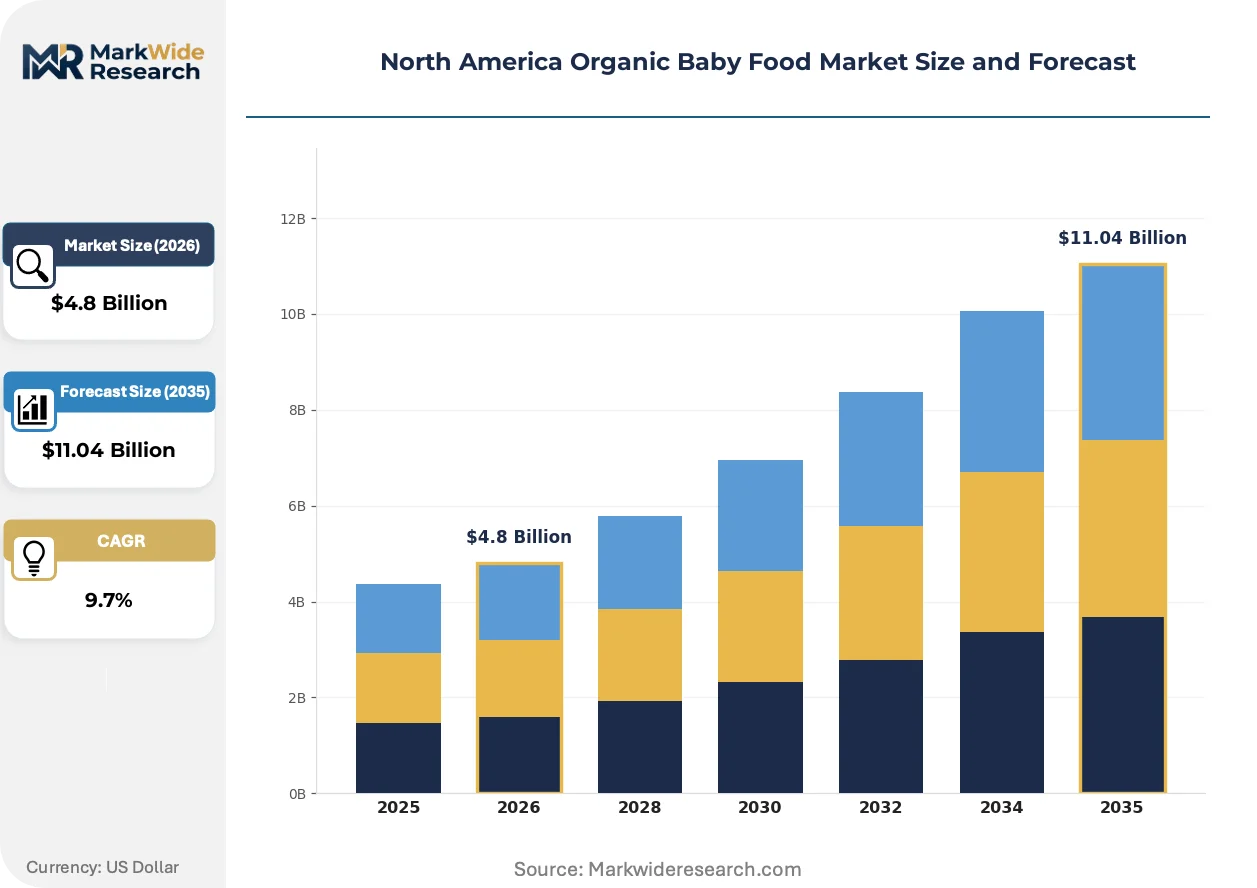
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pouches, Jars, Cans, Snacks Ingredient Type: Fruits, Vegetables, Grains, Proteins Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Pharmacies Certification: USDA Organic, Non-GMO, Kosher, Gluten-Free |
| Companies Covered | The Hain Celestial Group, Abbott Laboratories, Nestlé S.A., Hero Group, Danone S.A., Kraft Heinz Company, Baby Gourmet Foods, Sprout Organics, Beech-Nut Nutrition Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Organic Baby Food Market Strategic Shifts & Innovations
Automation and regulatory tightening are simultaneously elevating production precision and compliance burden, while parental purchasing behavior fragments across convenience-first and transparency-first segments.
High-pressure processing (HPP) equipment is automating cold pasteurization workflows that previously required thermal treatment. Mid-tier co-manufacturers in California and Texas are retrofitting lines at accelerated capex cycles. This automation is compressing batch-to-batch variation and enabling smaller production runs for niche organic SKUs.
The FDA Food Safety Modernization Act traceability rule is mandating lot-level tracking from farm to retail shelf. Organic baby food manufacturers must deploy blockchain-enabled supply chain visibility tools by compliance deadlines. Pouch format producers with multi-ingredient purees face the steepest documentation burden and are consolidating supplier bases to reduce audit complexity.
Parental purchasing is fragmenting between subscription replenishment models and impulse convenience-store acquisition. Direct-to-consumer platforms capture urban coastal households seeking curated organic assortments. This behavioral split concentrates highest lifetime-value buyers in California and New York metro corridors while leaving price-sensitive volume in conventional grocery channels.
North America Organic Baby Food Market Segmentation
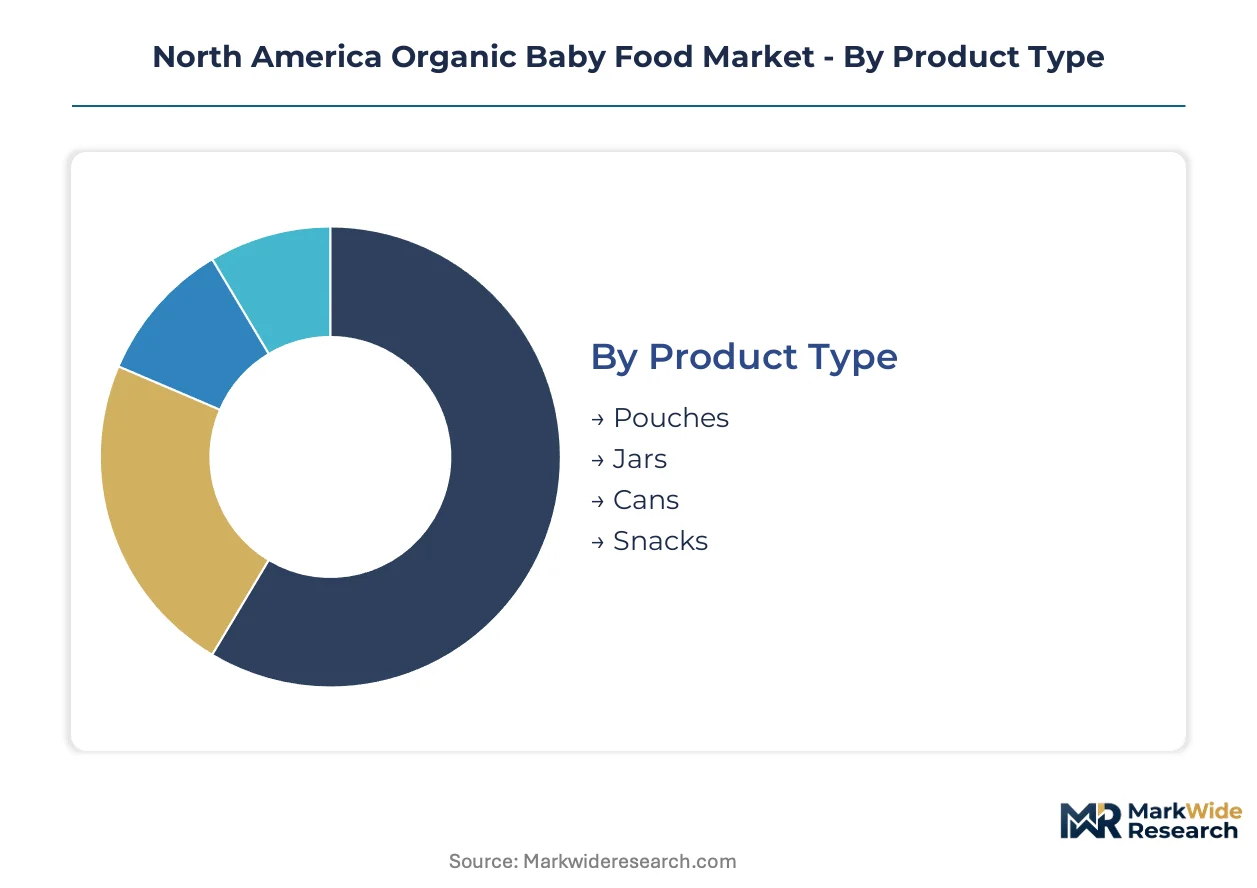
Product format, ingredient composition, and certification tier determine manufacturing investment and margin structure across the North American organic baby food landscape. Segment boundaries reflect divergent parental purchasing behaviors between convenience-driven urban households and price-sensitive traditional buyers.
Product Type:
Pouches function as standalone convenience solutions while jars and cans operate as embedded pantry staples within broader feeding routines.
- Pouches:Flexible laminated packaging enables single-handed feeding and on-the-go consumption without refrigeration. California and New York metro parents absorb 40-60% price premiums for portable formats that eliminate bowl-and-spoon cleanup. FDA food contact substance regulations govern adhesive layers and barrier films.
- Jars:Glass containers deliver visual transparency for texture inspection and support thermal processing for shelf-stable distribution. Midwest markets retain jar preference where per-unit cost visibility outweighs convenience premiums. Glass weight elevates freight costs from Midwest manufacturing clusters to coastal distribution hubs.
- Cans:Metal packaging supports extended shelf life for emergency stockpiling and institutional procurement. Limited premium positioning due to association with conventional commodity formats.
- Snacks:Finger-food formats transition toddlers from purees to self-feeding textures. Puffs and teething biscuits occupy pharmacy checkout impulse placement adjacent to diaper and wipe categories.
Volume placements concentrate in pouches; the faster expansion belongs to snacks as toddler-stage retention becomes a strategic priority.
Ingredient Type:
Cost tier stratification separates commodity fruit bases from premium protein fortification requiring specialized supply chain controls.
- Fruits:Apple, pear, and banana purees constitute the foundational base for 70%+ of SKUs due to neutral palatability and year-round California Central Valley sourcing availability. Weather volatility in Washington apple regions creates input cost spikes that compress Q3 margins.
- Vegetables:Sweet potato, carrot, and squash formulations address parental concerns about vegetable acceptance in early feeding windows. Single-vegetable SKUs command transparency premiums over blended fruit-dominant alternatives.
- Grains:Oat and rice cereals serve as first foods for infants transitioning from exclusive milk feeding. Iron fortification requirements under FDA infant cereal standards differentiate functional grain products from commodity starch bases.
- Proteins:Chicken, turkey, and legume purees target older infants requiring complementary protein intake beyond breast milk or formula. Organic meat certification demands 100% organic feed verification through USDA National Organic Program livestock standards, constraining supplier pools to Iowa and Nebraska contract growers.
Revenue concentration sits with fruit bases; the steepest expansion trajectory belongs to proteins as clean-label meat sourcing becomes a parental differentiator.
Distribution Channel:
Customer type fragmentation separates subscription-loyal urban households from price-comparison grocery shoppers and clinical-trust pharmacy buyers.
- Supermarkets:Mass merchandisers in Texas and Florida allocate end-cap placement to pouch multi-packs during promotional windows. Slotting fee structures favor incumbent manufacturers with consolidated SKU portfolios over emerging brands.
- Online Retail:Direct-to-consumer platforms capture California and New York households through subscription replenishment models bypassing retail margin stacking. Amazon and Thrive Market algorithms prioritize USDA Organic badges in search ranking.
- Specialty Stores:Natural grocers in Colorado and Oregon maintain curated assortments emphasizing local sourcing narratives and co-packer transparency. Smaller footprint limits national brand penetration.
- Pharmacies:CVS and Walgreens integrate organic baby food adjacent to infant formula and pediatric care aisles. Pharmacist recommendation influence elevates trust transfer for first-time parents.
Transaction volume flows through supermarkets; the fastest channel expansion belongs to online retail as millennial purchasing migrates from physical browsing to algorithmic curation.
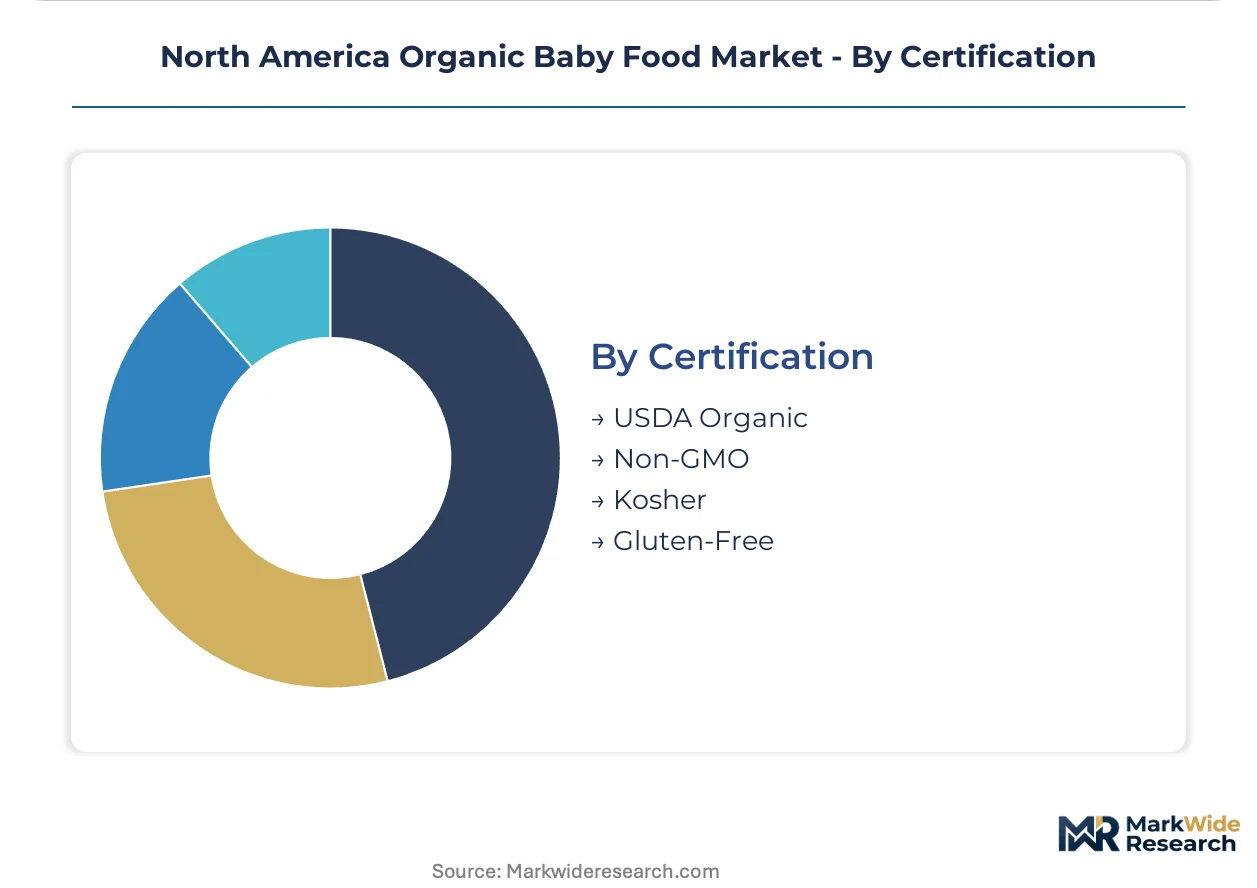
Certification:
Maturity gradients separate baseline regulatory compliance from premium differentiation layers that command shelf space and pricing power.
- USDA Organic:National Organic Program certification mandates 95%+ organic ingredient content and prohibits synthetic pesticides, GMOs, and irradiation. California state enforcement audits create compliance cost variation versus federal baseline requirements.
- Non-GMO:Project Verified and NSF Non-GMO certification operates as table stakes rather than differentiator as consumer expectation converges with organic standards. Testing costs add $0.02-0.04 per unit without pricing recovery.
- Kosher:Orthodox Union certification opens distribution through Jewish community networks in New York, New Jersey, and Florida. Production line segregation requirements limit co-manufacturer flexibility.
- Gluten-Free:GFCO certification targets celiac-sensitive households and grain-avoidance dietary trends. Oat-based SKUs face cross-contamination risk requiring dedicated gluten-free supply chains.
Certification density clusters around USDA Organic; the gaining-share trajectory belongs to gluten-free as allergen avoidance expands beyond diagnosed medical necessity into preventive parental behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California Central Valley fruit and vegetable operations anchor organic ingredient sourcing for North American baby food production, with Washington apple orchards and Canadian Prairie grain belts extending the supply perimeter.
United States
Millennial parents in New York and Los Angeles metro areas drive pouch format adoption through subscription replenishment models. FDA infant formula regulations intersect with USDA National Organic Program standards to create dual compliance frameworks elevating production costs. Austin and Denver natural grocer clusters curate local-sourcing narratives that command transparency premiums from urban households.
Canada
Quebec and Ontario provinces show underpenetrated organic adoption relative to US coastal saturation, creating expansion opportunities for direct-to-consumer platforms. Health Canada and the Canadian Food Inspection Agency enforce organic standards aligned with USDA equivalency arrangements. Toronto-based urban professionals prioritize portable pouch formats for on-the-go feeding routines.
Mexico
Emerging middle-class households in Mexico City and Guadalajara demonstrate nascent organic purchasing as retail modernisation expands shelf access. COFEPRIS, the national health regulator, maintains import standards for organic-certified infant foods entering through US supply chains. Northern border states concentrate distribution logistics for cross-border product flows.
North America Organic Baby Food Market Key Industry Players
Global majors compete with regional champions across certification depth and distribution reach, producing a tiered structure where multinational portfolios anchor mainstream retail while specialised organic brands capture natural channel loyalty. Consolidated shelf presence at Walmart and Target favours incumbents with slotting fee capacity. Three archetypes dominate: diversified nutrition conglomerates with paediatric R&D infrastructure, pure-play organic specialists leveraging clean-label authenticity, and private-label suppliers serving price-comparison segments. Competitive moves concentrate on M&A absorption of emerging organic brands and backward integration into certified ingredient sourcing.
Within the diversified nutrition tier, Nestlé S.A. and Danone S.A. exemplify scale-driven positions anchored by paediatric expertise and dairy-based organic formulations. The Hain Celestial Group occupies a specialist archetype, leveraging natural brand portfolios across mainstream retail channels. These three entities represent contrasting strategic postures: multinational infrastructure depth versus organic-native authenticity versus hybrid natural-brand consolidation.
| Leading Market Players |
|---|
| The Hain Celestial Group |
| Abbott Laboratories |
| Nestlé S.A. |
| Hero Group |
| Danone S.A. |
| Kraft Heinz Company |
| Baby Gourmet Foods |
| Sprout Organics |
| Beech-Nut Nutrition Corporation |
| Others |
Cost & Logistics Intelligence
Backward integration into California Central Valley organic fruit operations anchors supply security for pouch-format manufacturers while simultaneously propping premium pricing power against jar-format alternatives. This captive sourcing strategy insulates USDA Organic certified producers from weather-driven input volatility that otherwise compresses margins across the category.
Pricing Analysis
Certification-bundling separates USDA Organic verified pouches from conventional alternatives, with subscription models absorbing per-unit premiums from urban millennial households while jar formats compete on unbundled transactional pricing for Midwest price-sensitive buyers. Three-tier pricing structure across premium refrigerated HPP lines, standard shelf-stable pouches, and economy jar SKUs stratifies the market. Pricing pressure stems from organic ingredient cost volatility in Washington apple regions and California vegetable belts. Pharmacy channel buyers show lowest price sensitivity due to trust transfer from pharmacist recommendations, while conventional grocery shoppers exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with California Central Valley suppliers for organic fruit and vegetable purees, concentrating 70% of foundational SKU inputs in a drought-exposed geography. The supply chain draws from Washington apple orchards, Canadian Prairie grain belts, and Iowa-Nebraska organic livestock operations for protein fortification. Tariff exposure on Canadian organic grain imports and Mexican distribution logistics creates structural risk for cross-border flows. Distribution runs through Walmart and Target mass merchandisers with slotting fee barriers, alongside direct-to-consumer platforms bypassing retail margin stacking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic baby food supply is tightening around certified ingredient availability, with 36-month transition timelines for conventional-to-organic contract manufacturing propping pricing across all format tiers.
For Market Incumbents: Deploy HPP equipment retrofit programs to automate cold pasteurization workflows and compress batch-to-batch variation for niche organic SKUs. Consolidate supplier bases to reduce FDA Food Safety Modernization Act traceability audit complexity. Absorb USDA Organic certification costs through subscription direct-to-channel models that capture lifetime value from urban coastal households, defending against private-label price competition in conventional grocery. For New Entrants and Emerging Players: Begin with Quebec and Ontario provincial markets where organic adoption trails US coastal saturation, creating white-space expansion opportunities. Target pharmacy retail networks where pharmacist recommendation influence elevates trust transfer for first-time parents. Launch clean-label allergen-free formulations paired with USDA Organic certification to command shelf space adjacent to infant formula aisles. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified nutrition conglomerates seeking pediatric R&D infrastructure and organic-native brand authenticity. Mid-cap organic specialists with backward integration into certified ingredient sourcing represent the most defensible long-term positioning. Watch FDA enforcement priority shifts on infant formula safety standards as the inflection signal for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Ingredient Sourcing | Captive supply from California Central Valley operations insulates margin compression from weather-driven input volatility. |
| Direct-to-Consumer Subscription Launch | Recurring delivery platforms bypass Walmart and Target slotting fees while capturing urban millennial household lifetime value. |
| HPP Equipment Retrofit Investment | Cold pasteurization automation enables smaller production runs for niche refrigerated organic SKUs with extended shelf life. |
| Clean-Label Allergen-Free Formulation Extension | USDA Organic paired with peanut-free and dairy-free certifications commands pharmacy retail shelf space. |
| Canadian Provincial Market Expansion | Quebec and Ontario underpenetration relative to US coastal saturation creates geographic diversification without incumbent saturation. |
Research Approach
Independent corroboration across FDA enforcement documentation, USDA National Organic Program certification records, and Nielsen retail audit data underwrites the qualitative findings in this study. Primary interviews with organic baby food brand managers, category buyers at mass merchandisers, contract manufacturing procurement leads, and pediatric nutrition formulation chemists were combined with secondary validation from SEC 10-K filings of listed nutrition conglomerates, Health Canada organic equivalency arrangements, and California state agriculture department enforcement reports. Bottom-up SKU-level volume modeling and top-down category value triangulation were cross-referenced for convergence.
Rate-of-change decomposition across product format adoption curves, certification tier penetration, and channel shift dynamics structured the analytical framework. Segmentation dimensions modeled include pouch versus jar versus snack format, fruit versus vegetable versus grain versus protein ingredient composition, USDA Organic versus additional allergen-free certification tiers, and supermarket versus online retail versus pharmacy channel flows. CAGRs were derived from logistic diffusion curves fitted to historical adoption patterns, with inputs including urban millennial household formation rates and organic acreage expansion in California Central Valley sourcing regions.
Underlying measurement precision varies by segment; online retail channel flows and subscription model pricing carry tighter precision than pharmacy impulse purchase volumes. Forecasts reflect assumptions around FDA enforcement continuity, California drought frequency, and millennial parental preference stability for transparent supply chains. Organic ingredient cost volatility and regulatory compliance burden escalation represent specific risk factors that could revise trajectory. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Global Oligosaccharides in Infant Nutrition Market
Baby Food and Infant Formula
Parenteral Formula Market
Baby Food and Infant Formula
Pureed Food Market
Baby Food and Infant Formula
Baby Formula Ingredients Market
Baby Food and Infant Formula
Global Lactose-Free Infant Formula Market
Baby Food and Infant Formula
Kids Food and Beverages Market
Baby Food and Infant Formula
Canada Baby Food Market
Baby Food and Infant Formula
Pet Milk Replacement Products Market
Baby Food and Infant Formula
Europe Organic Baby Food Market
Baby Food and Infant Formula
Hydrolyzed Formula Milk Powder Market
Baby Food and Infant Formula
Middle East and Africa Organic Baby Food Market
Baby Food and Infant Formula
Baby Food and Infant Formula Market
Baby Food and Infant Formula
Infant Nutrition Market
Baby Food and Infant Formula
Infant Food Compliance Ready Fertility Input Market
Baby Food and Infant Formula
Organic Infant Formula Market
Baby Food and Infant Formula
North America Baby Food Market