
 Japan Baby Food and Infant Formula Market | 2026-2036
Japan Baby Food and Infant Formula Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Baby Food and Infant Formula Market Intelligence
Japan's declining pediatric nursing workforce is unwinding traditional feeding support structures and redirecting parents toward shelf-stable, nutritionally complete alternatives. Meiji Co., Ltd. leverages its domestic dairy supply chain to dominate powder formula manufacturing. Kewpie Corporation specializes in fruit and vegetable purees with reduced additive profiles. Pigeon Corporation controls pharmacy and maternity clinic channels through nurse-education programs.
Japan baby food and infant formula encompasses processed, nutritionally fortified consumables designed for children from birth through thirty-six months, manufactured under aseptic conditions with specified protein, lipid, and micronutrient densities per 100 kilocalories. These products serve as partial or total breast milk substitutes and complementary feeding solutions during dietary transition phases. Ready-to-feed liquid formats capture expanding margin pools as convenience premiums widen, while cereals retain volume leadership through pediatrician endorsement and pharmacy placement. Online retail channels are accelerating fastest among distribution pathways, though supermarkets still anchor bulk purchasing behavior for standard SKUs.
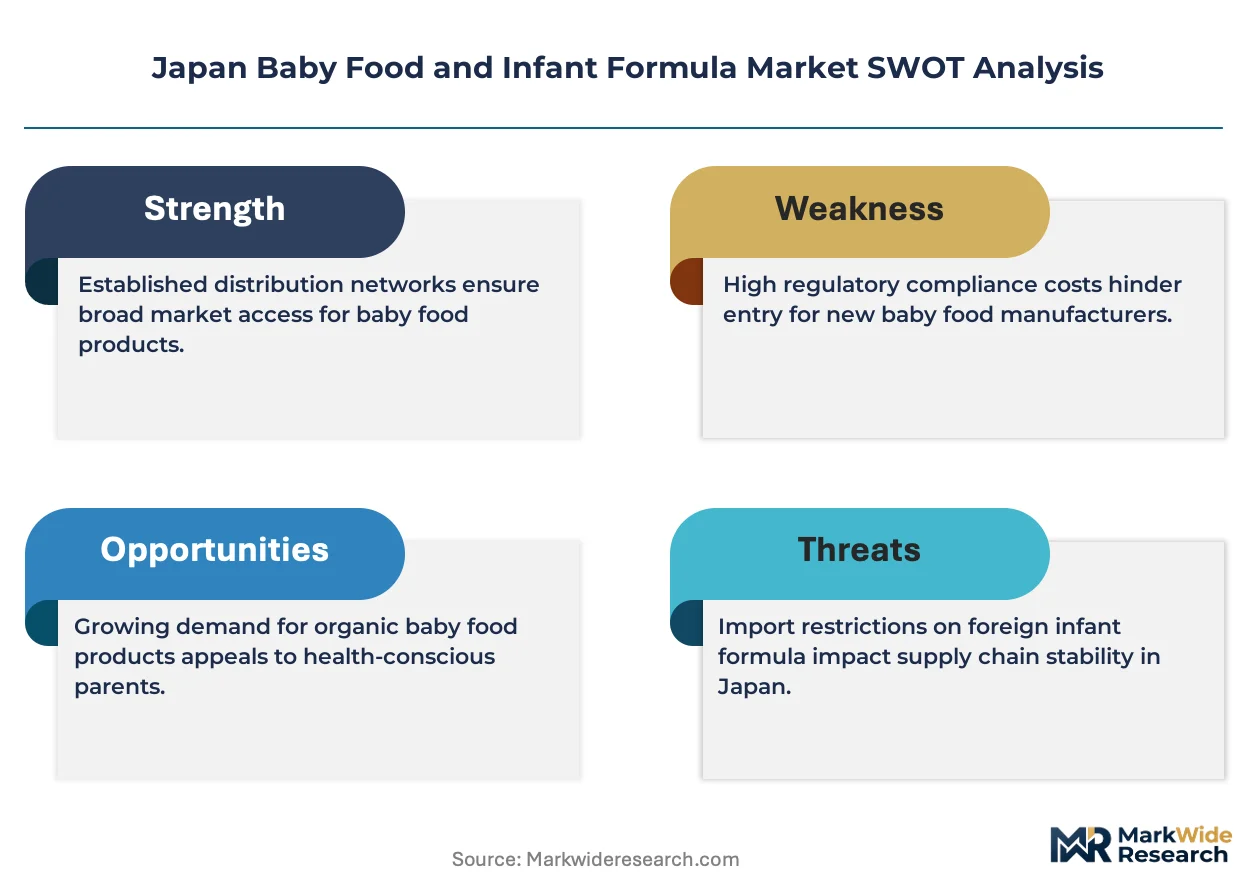
PMDA compositional standards, Consumer Affairs Agency labeling mandates, and JIS food safety protocols collectively determine ingredient eligibility, nutrient claim permissibility, and import clearance timelines for all marketed products. Manufacturers must navigate pre-market notification requirements and periodic facility inspections that elevate compliance costs for smaller entrants. Stakeholders should monitor evolving METI sustainability guidelines for packaging materials and traceability systems as these will reshape procurement criteria and consumer trust metrics.
Market Dynamics
PMDA compositional standards and METI sustainability guidelines are compressing formulation flexibility while elevating compliance costs across domestic manufacturing facilities. Working parents in Tokyo and Osaka are simultaneously pulling demand toward convenience formats that bypass traditional preparation steps.
Growth Catalysts
- Dual-income household expansion:Labor force participation among Japanese mothers with infants under one year has climbed steadily, eliminating time for homemade complementary feeding and expanding ready-to-feed liquid purchases.
- PMDA safety review acceleration:Streamlined pre-market notification pathways for domestically sourced dairy proteins are shortening product development cycles for manufacturers with captive Hokkaido supply chains.
- Pharmacy channel densification:Maternity clinic co-location with dispensing pharmacies in Kanto prefecture is capturing prescription-adjacent trust transfers at point of pediatric consultation.
Market Restraints
- Domestic dairy supply concentration:Hokkaido raw milk procurement pools under JA Group cooperatives limit price negotiation leverage for formula manufacturers outside vertical dairy arrangements.
- PMDA import clearance friction:Foreign-sourced novel ingredients face extended safety evaluation timelines that delay product launches versus domestic competitors with established ingredient dossiers.
- Pediatrician endorsement dependency:Powder cereal and formula categories require clinical validation investments that smaller entrants cannot amortize across limited SKU portfolios.
Strategic Opportunities
- Kansai underpenetration:Osaka and Kyoto prefectures maintain lower pharmacy-channel density than Kanto, creating whitespace for direct-to-clinic distribution partnerships with independent pediatric practices.
- METI packaging circularity mandates:Biodegradable pouch formats and mono-material structures will receive preferential retail placement under forthcoming sustainability scoring systems.
- Online subscription convergence:Auto-replenishment algorithms tied to developmental stage transitions are capturing recurring revenue pools that supermarket bulk purchasing cannot replicate.
Industry Challenges
- Pediatric nutritionist scarcity:Declining nursing school enrollment is constraining manufacturer field education teams that historically trained maternity clinic staff on feeding protocol integration.
- Legacy ERP integration:Batch-level traceability requirements under revised JIS food safety protocols demand middleware investments that mid-tier manufacturers have deferred.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Baby Food and Infant Formula Market |
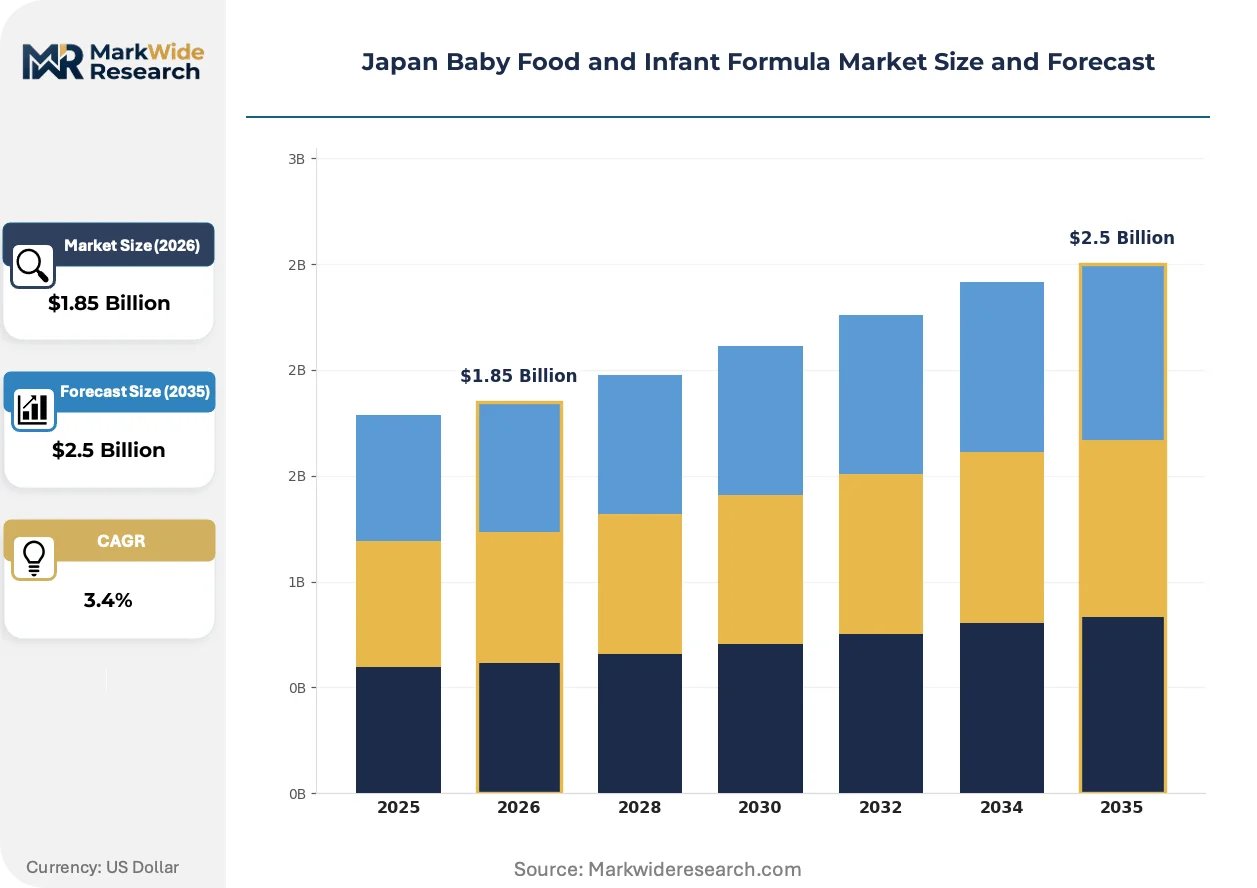
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereals, Purees, Snacks, Ready-to-Feed Packaging Type: Jars, Pouches, Cans, Boxes Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Pharmacies End User: Infants, Toddlers, Caregivers, Pediatricians |
| Companies Covered | Nestlé Japan Ltd., Kewpie Corporation, Meiji Co., Ltd., Abbott Japan Co., Ltd., Bean Stalk Snow Co., Ltd., Morinaga Milk Industry Co., Ltd., Pigeon Corporation, Danone Japan Co., Ltd., Asahi Group Foods Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Baby Food and Infant Formula Market Strategic Shifts & Innovations
Formulation science and channel architecture are diverging simultaneously as manufacturers respond to divergent parent priorities across convenience, clean-label, and clinical validation dimensions.
Aseptic cold-fill processing for fruit and vegetable purees is fragmenting production asset deployment across the industry. Domestic manufacturers with legacy retort tunnel investments face stranded capacity risk as Kewpie Corporation and entrants adopt high-pressure processing for nutrient retention. Tokyo-based parents are paying premiums for chilled distribution chains that bypass shelf-stable alternatives.
METI's forthcoming sustainable packaging guidelines are mandating mono-material or compostable structures for all infant food containers by 2027. Manufacturers are reformulating barrier layers and retooling filling lines eighteen months ahead of enforcement to secure retail shelf placement. Powder formula tins and pouch formats face disproportionate redesign pressure given their higher material complexity versus glass jar alternatives.
Subscription-based auto-replenishment is displacing supermarket bulk purchasing among Osaka dual-income households. Platform algorithms tied to pediatric growth charts are predicting developmental transitions and pre-shipping stage-appropriate SKUs. This model concentrates customer lifetime value with early-stage entrants while eroding pharmacy foot traffic for standard-format purchases.
Japan Baby Food and Infant Formula Market Segmentation
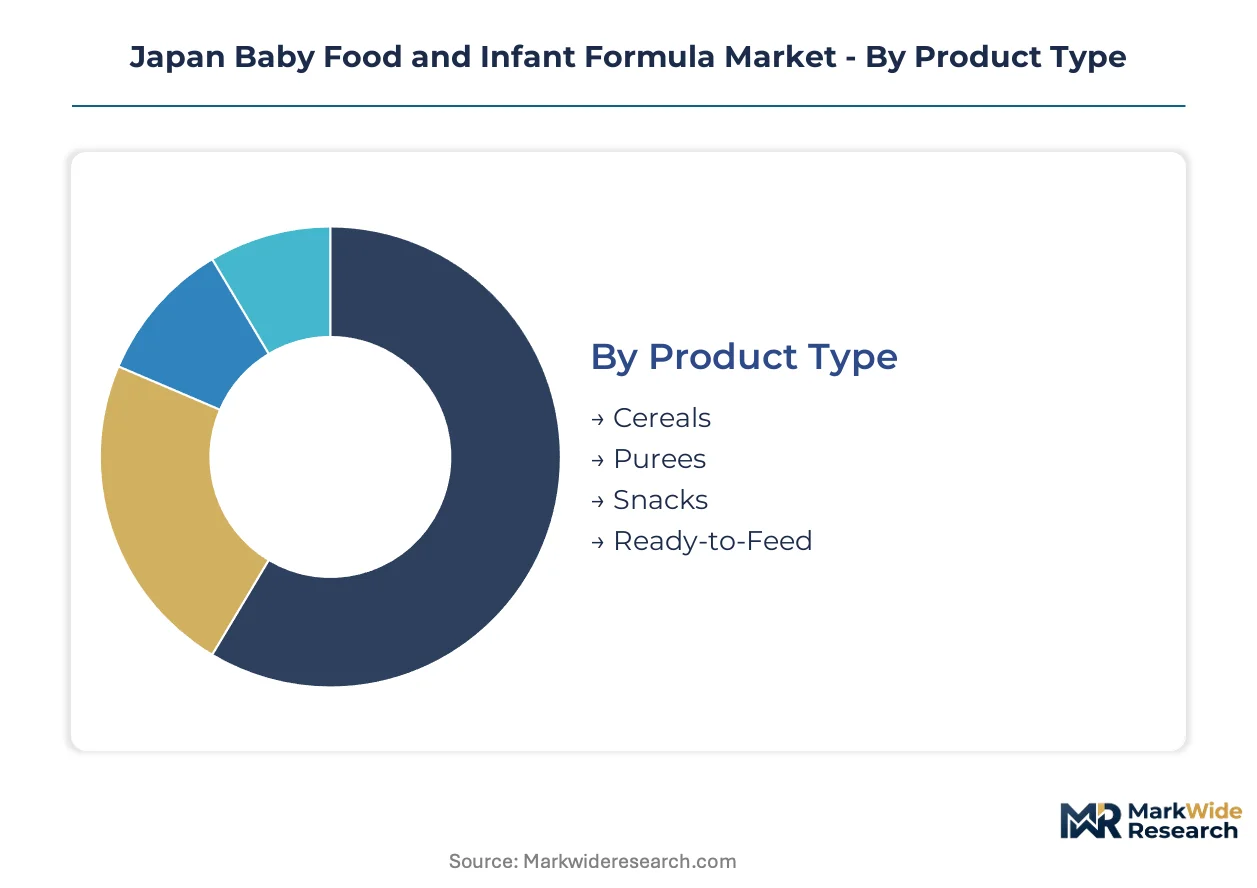
Japan's baby food and infant formula market fragments across four intersecting dimensions that determine pricing power, shelf placement, and regulatory exposure. Manufacturers must align formulation investments with packaging technology and channel-specific trust mechanisms to capture value across Tokyo's convenience-driven households and Osaka's price-sensitive segments.
Product Type:
Domestic manufacturing concentrates on powder-based formats leveraging Hokkaido dairy supply chains, while import-dependent categories face PMDA clearance friction that advantages local incumbents.
- Cereals:Iron-fortified rice and wheat blends formulated to JIS micronutrient density standards. Pharmacy placement in Kanto prefecture anchors volume, with pediatrician endorsement requirements creating formulation lock-in for established manufacturers.
- Purees:Aseptically processed fruit and vegetable compositions with reduced additive profiles. Chilled distribution chains through Tokyo's premium retail channels command margin premiums over shelf-stable alternatives, though cold-fill infrastructure requirements constrain entrant expansion.
- Snacks:Bite-sized finger foods targeting teething phases with controlled sodium and sugar thresholds. Convenience store distribution in Osaka and Nagoya drives impulse purchasing behavior among working parents.
- Ready-to-Feed:Sterile liquid formulations in single-serve formats eliminating preparation steps. Dual-income household penetration in Tokyo and Yokohama is expanding most quickly as time scarcity overrides cost sensitivity.
Cereals command the established base. The steepest expansion runs through Ready-to-Feed.
Packaging Type:
Cost tier stratification separates premium convenience formats from economy bulk purchasing, with METI sustainability mandates reshaping material selection across all tiers.
- Jars:Glass containers with vacuum-sealed lids enabling retort sterilization and extended ambient shelf life. Traditional pharmacy channel placement in Kanto maintains volume leadership despite handling weight disadvantages.
- Pouches:Flexible mono-material or laminate structures with spout-fitment for self-feeding toddlers. Biodegradable format development is accelerating fastest as manufacturers pre-position for METI circularity scoring implementation.
- Cans:Metal containers for powder formula with nitrogen-flush preservation. Hokkaido dairy supply chain proximity determines manufacturing cost structure for domestic producers.
- Boxes:Carton-based secondary packaging for multi-unit cereal assortments. Supermarket bulk purchasing in Osaka favors this format for household inventory stocking.
Jars retain the volume anchor. Pouch formats are gaining share fastest through premium channel expansion.
Distribution Channel:
Customer type divergence separates trust-driven pharmacy purchasers from convenience-seeking online subscribers, with channel-specific regulatory compliance requirements fragmenting operational investments.
- Supermarkets:Mass-merchandise shelf space for standard SKUs with promotional pricing cycles. Bulk purchasing behavior in Osaka and Nagoya sustains volume throughput despite declining foot traffic in Tokyo.
- Online Retail:Platform-based auto-replenishment with algorithmic developmental stage matching. Subscription concentration among Tokyo dual-income households is displacing pharmacy loyalty through predictive logistics.
- Specialty Stores:Curated assortments emphasizing organic certification and clean-label positioning. Premium positioning in Tokyo's central wards captures margin pools from health-conscious first-time parents.
- Pharmacies:Prescription-adjacent placement with nurse-education support programs. Maternity clinic co-location in Kanto prefecture sustains trust transfer at pediatric consultation points.
Supermarkets anchor the volume base. Online retail is expanding most quickly through subscription algorithm deployment.
End User:
Application specificity determines formulation complexity, with clinical validation requirements escalating across pediatrician-influenced categories.
- Infants:Birth-to-twelve-month consumers requiring breast milk substitutes and early complementary foods. PMDA compositional standards mandate precise protein and lipid ratios per 100 kilocalories.
- Toddlers:Twelve-to-thirty-six-month consumers transitioning to family table foods with continued micronutrient supplementation. Texture progression requirements drive multi-stage SKU development.
- Caregivers:Purchasing decision-makers prioritizing convenience and preparation time reduction. Working parent labor force participation in Tokyo shapes format preferences toward ready-to-serve solutions.
- Pediatricians:Influential gatekeepers whose endorsement determines pharmacy channel placement and parental trust formation. Clinical validation investments required for formula category entry create structural barriers.
Infant-directed formulations command the established base. Toddler-stage nutrition is climbing the fastest as complementary feeding periods extend.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PMDA compositional standards and METI sustainability guidelines anchor regulatory oversight across Japan's prefectural markets, with demand concentration varying sharply between urban cores and peripheral regions.
Kanto/Tokyo
Dual-income household density in Tokyo and Yokohama drives ready-to-feed liquid demand, with time-scarce parents paying convenience premiums. PMDA streamlined pre-market notifications for domestically sourced dairy proteins benefit manufacturers with captive supply chains. Maternity clinic co-location with dispensing pharmacies in central wards sustains prescription-adjacent trust transfers.
Kansai/Osaka
Price-sensitive bulk purchasing behavior in Osaka and Kyoto sustains supermarket cereal volumes despite lower pharmacy-channel density. METI packaging circularity mandates are pressuring mid-tier manufacturers to retool filling lines ahead of 2027 enforcement. Independent pediatric practices in Osaka Prefecture present whitespace for direct-to-clinic distribution partnerships.
Chubu/Nagoya
Convenience store distribution networks in Aichi Prefecture capture impulse snack purchases from working parents during commute hours. JIS food safety protocol compliance costs disproportionately burden smaller entrants without legacy ERP integration. Nagoya's industrial corridor hosts powder formula manufacturing facilities leveraging proximate Hokkaido dairy logistics.
Hokkaido
JA Group cooperative raw milk procurement pools concentrate upstream supply control, limiting price negotiation leverage for non-vertically integrated formula manufacturers. PMDA facility inspection requirements elevate compliance costs for dairy processing assets. Sapporo's cold-chain infrastructure supports chilled puree distribution to premium Tokyo retail channels.
Kyushu
Lower urban household density in Fukuoka Prefecture sustains traditional jar-format purchasing through regional pharmacy chains. Pediatrician endorsement dependency constrains cereal category entry for new market participants. Kumamoto's agricultural processing clusters supply fruit and vegetable inputs for domestic puree manufacturers.
Japan Baby Food and Infant Formula Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with domestic dairy-backed manufacturers commanding formulation flexibility against import-dependent competitors. The market structure reflects PMDA clearance advantages for established ingredient dossiers versus extended safety evaluations faced by foreign-sourced novel inputs. Two strategic archetypes dominate: Hokkaido supply chain-integrated powder formula producers and pharmacy channel-controlled puree specialists. Competitive moves concentrate on cold-fill infrastructure deployment for nutrient retention and subscription algorithm development for auto-replenishment capture.
Within the integrated dairy tier, Meiji Co., Ltd. and Morinaga Milk Industry Co., Ltd. occupy positions reflecting Hokkaido raw milk procurement proximity. Kewpie Corporation exemplifies the clean-label puree specialist archetype through reduced additive positioning. Pigeon Corporation anchors the pharmacy channel control vector via maternity clinic education programs. Nestlé Japan Ltd. and Danone Japan Co., Ltd. represent multinational entrants navigating PMDA import clearance timelines.
| Leading Market Players |
|---|
| Nestlé Japan Ltd. |
| Kewpie Corporation |
| Meiji Co., Ltd. |
| Abbott Japan Co., Ltd. |
| Bean Stalk Snow Co., Ltd. |
| Morinaga Milk Industry Co., Ltd. |
| Pigeon Corporation |
| Danone Japan Co., Ltd. |
| Asahi Group Foods Ltd. |
| Others |
Cost & Logistics Intelligence
Hokkaido dairy processing scale economies concentrate powder formula manufacturing cost advantages among vertically integrated producers, compressing price floors for import-dependent competitors while elevating margin capture for domestic incumbents with captive raw milk access. This concentration simultaneously tightens procurement leverage for mid-tier manufacturers and widens Tokyo-Osaka price spreads across convenience-format premiums.
Pricing Analysis
Tokyo's ready-to-feed liquid formats command 15-25% premiums over Osaka bulk cereal pricing, reflecting dual-income household time scarcity in Kanto versus price-sensitive inventory stocking in Kansai. Three-tier pricing structure across premium, standard, and economy levels separates chilled distribution purees from ambient shelf-stable alternatives and pharmacy-channel endorsed powders. Pricing pressure stems from METI packaging circularity compliance costs pressuring mid-tier manufacturers to absorb retooling investments. Osaka supermarket shoppers exhibit highest price sensitivity, while Tokyo specialty store purchasers show least elasticity for clean-label certification.
Supply Chain Analysis
Strategic stockpiling of Hokkaido raw milk dominates inventory strategy, with JA Group cooperative procurement pools forcing just-in-time alternatives to absorb seasonal volatility premiums. Domestic supply concentrates in Japan, with limited offshore sourcing for novel ingredients facing PMDA clearance friction. Raw material dependencies center on Hokkaido dairy proteins, domestic rice and wheat cereals, and Kumamoto-sourced fruit and vegetable inputs. Single-source vulnerability runs through JA Group cooperative concentration, with tariff exposure minimal but regulatory restriction risk elevated for foreign-sourced ingredient dossiers. Distribution runs through pharmacy-maternity clinic co-location in Kanto, supermarket bulk channels in Kansai, and accelerating online subscription platforms in Tokyo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in Kansai underpenetration and chilled distribution infrastructure gaps, as dual-income household expansion across Osaka and Kyoto creates demand niches unmet by Kanto-centric pharmacy channel incumbents.
For Market Incumbents: Secure Hokkaido dairy supply chain lock-in through extended cooperative procurement agreements before JA Group consolidation tightens access. Defend pharmacy channel control by accelerating nurse-education program deployment in Kansai independent pediatric practices, countering subscription algorithm displacement threats from online retail platforms. Prioritize cold-fill infrastructure investment for nutrient retention premiums in Tokyo premium retail.
For New Entrants and Emerging Players: Differentiate on biodegradable pouch format readiness ahead of METI circularity scoring implementation, capturing preferential retail placement as incumbents lag retooling timelines. Target Kansai direct-to-clinic distribution partnerships, exploiting lower pharmacy-channel density in Osaka and Kyoto versus saturated Kanto markets. Pursue clean-label puree positioning through Kumamoto agricultural processing cluster proximity, bypassing PMDA import clearance friction facing foreign ingredient competitors.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cold-fill infrastructure specialists with nutrient retention capabilities and subscription algorithm development competencies. Long-term viability across the projection horizon rests on capturing recurring revenue pools through developmental stage-matched auto-replenishment, displacing transactional pharmacy purchasing. Acquisition target archetype: regional puree manufacturers with chilled distribution assets and untapped Kansai clinic networks. Signal to watch: PMDA pre-market notification pathway streamlining for domestically sourced novel ingredients, indicating regulatory arbitrage closure timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Fill Infrastructure Deployment | High-pressure processing adoption by Kewpie Corporation fragments retort tunnel capacity values industry-wide. |
| Biodegradable Pouch Format Transition | Mono-material structure development secures METI circularity scoring preferential placement ahead of 2027 enforcement. |
| Direct-to-Clinic Distribution Partnership | Osaka independent pediatric practice penetration captures whitespace from Kanto-centric pharmacy channel incumbents. |
| Subscription Algorithm Development | Developmental stage-matched auto-replenishment concentrates customer lifetime value with early-stage platform entrants. |
| Hokkaido Supply Chain Integration | JA Group cooperative procurement proximity determines powder formula manufacturing cost structure against import-dependent rivals. |
Research Approach
Cross-validation between primary interviews with brand managers, category buyers at Tokyo and Osaka retailers, PMDA regulatory affairs specialists, and maternity clinic nursing directors anchors the qualitative findings against secondary validation from PMDA pre-market notification filings, Consumer Affairs Agency labeling mandate records, METI sustainability guideline drafts, and Nielsen retail audit data for pharmacy and supermarket channels. Bottom-up SKU-level volume aggregation triangulates against top-down macroeconomic household expenditure projections.
Sensitivity analysis across infant versus toddler formulation demand splits, ready-to-feed versus powder format penetration scenarios, and Kanto versus Kansai regional growth differentials informs the analytical framework throughout the forecast period. Segmentation dimensions modeled include product type, packaging technology tier, distribution channel structure, and end-user developmental stage. CAGRs derive from weighted average of historical trajectory analysis and demand driver elasticity estimates, with specific inputs from dual-income household labor force participation trends and PMDA regulatory pathway efficiency indices.
Material uncertainties — PMDA compositional standard revisions, JA Group cooperative restructuring, METI packaging mandate enforcement timing — sit outside the modeled envelope. Forecasts reflect assumptions around sustained pharmacy channel trust transfer and online subscription platform penetration rates. Revision becomes warranted when PMDA import clearance timelines for foreign-sourced ingredients compress substantially or Hokkaido dairy supply concentration disperses through cooperative fragmentation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Infant Formula Milk Powder with A2 Beta-Casein Market
Baby Food and Infant Formula
Baby Food Products Market
Baby Food and Infant Formula
Organic Follow Up Formula Market
Baby Food and Infant Formula
Indonesia Infant Nutrition Market
Baby Food and Infant Formula
Growing Up Milk Market
Baby Food and Infant Formula
Asia-Pacific Baby Food Market
Baby Food and Infant Formula
Infant Food Compliance Ready Fertility Input Market
Baby Food and Infant Formula
Asia-Pacific Prebiotics for Infant Formula Market
Baby Food and Infant Formula
Ready to Use Supplementary Food Market
Baby Food and Infant Formula
Follow on Formula Milk Market
Baby Food and Infant Formula
Baby Juice Market
Baby Food and Infant Formula
Europe Baby Food Market
Baby Food and Infant Formula
Pureed Food Market
Baby Food and Infant Formula
West Africa Baby Food Market
Baby Food and Infant Formula
Standard Milk Formula Market
Baby Food and Infant Formula
North America Organic Baby Food Market