
 Follow on Formula Milk Market | 2026-2036
Follow on Formula Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Follow on Formula Milk Market Foresight
Premium nutritional specifications is unwinding commodity-grade positioning across the Follow on Formula Milk Market. Danone S.A. leverages its European dairy heritage to anchor medical nutrition credibility in hypoallergenic lines. Nestlé S.A. sustains manufacturing scale across multiple continents, controlling cost structures in powdered can formats. Abbott Laboratories specializes in clinical-grade formulations, differentiating through hospital and pharmacy channel relationships.
Follow on formula milk denotes cow's milk or plant-protein-based nutritional products formulated for infants aged six to twelve months, containing adjusted protein ratios, added iron, and docosahexaenoic acid to bridge the dietary gap between breast milk or infant formula and family foods. Its primary commercial purpose is to sustain growth velocity and neurodevelopment during the complementary feeding transition. Organic follow on formula commands margin concentration as clean-label premiums persist in pharmacy and specialty baby store channels. Powdered cans dominate volume throughput due to shelf stability and lower per-serve logistics costs, while ready-to-feed bottles capture the fastest expansion in online retail and convenience store networks.
The European Food Safety Authority sets compositional benchmarks that determine which formulations gain CE marking and market access across EU member states. China's National Medical Products Administration enforces GB standards registration, creating a dual-track compliance burden for exporters seeking entry through cross-border e-commerce versus domestic distribution. The US Food and Drug Administration and Infant Formula Act maintain nutrient floor and ceiling requirements that shape product architecture for American-market entrants. Stakeholders must monitor divergence between Codex Alimentarius revisions and national regulator implementations to anticipate reformulation costs and label claim adjustments.
Market Dynamics
The EU's updated Food for Specific Groups regulation is forcing reformulation across the Follow on Formula Milk Market, compressing legacy commodity-grade portfolios while elevating medical nutrition and organic-certified lines into margin-dominant positions.
Growth Catalysts
- Dual-income household expansion:Working parents in OECD economies are expanding purchases of ready-to-feed formats, compressing preparation time constraints and shifting volume toward convenience-oriented packaging.
- CE marking harmonization:The European Food Safety Authority's compositional benchmarks are streamlining cross-border market access across EU member states, reducing duplicate testing burdens for compliant exporters.
- Complementary feeding transition protocols:Pediatric nutrition guidelines emphasizing sustained neurodevelopment support are elevating DHA-fortified and iron-adjusted formulations into standard-of-care positioning.
Market Restraints
- Whey protein concentrate volatility:Dairy commodity input costs swing with New Zealand and EU milk powder auction cycles, compressing margin predictability for standard-grade producers.
- GB standards registration friction:China's National Medical Products Administration maintains separate domestic and cross-border e-commerce compliance tracks, doubling regulatory burden for market entrants.
- Breastfeeding promotion mandates:WHO Code-aligned marketing restrictions in emerging markets limit point-of-sale visibility and sampling programs for follow-on formula brands.
Strategic Opportunities
- Pharmacy channel premiumization:Specialty baby store and pharmacy networks in France and Germany are absorbing organic and hypoallergenic variants at price points 40-60% above standard formulations.
- Plant-protein convergence:Pea and rice protein hydrolysate technologies are opening formulation pathways for lactose-intolerant infant populations previously excluded from cow's milk-based products.
- Digital subscription models:Direct-to-consumer platforms are capturing recurring revenue streams through auto-replenishment algorithms calibrated to pediatric growth milestones.
Industry Challenges
- Clinical nutrition credentialing timelines:Hospital and pharmacy channel access requires extended safety documentation cycles that stretch 18-36 months for novel hypoallergenic ingredients.
- Legacy ERP integration friction:Batch-level traceability mandates under EU General Food Law are forcing manufacturing execution system overhauls at mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Follow on Formula Milk Market |
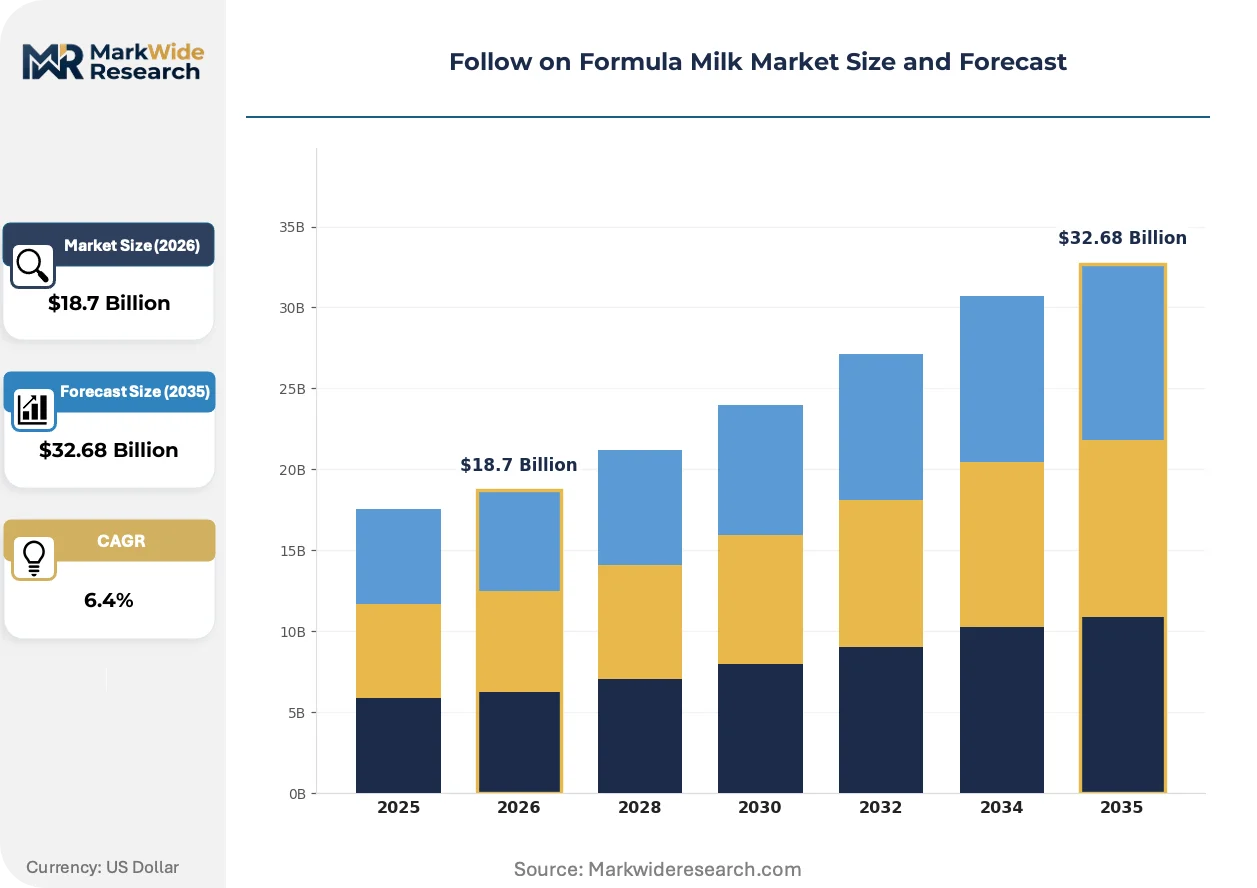
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Follow on Formula, Organic Follow on Formula, Hypoallergenic Follow on Formula, Soy-Based Follow on Formula, Lactose-Free Follow on Formula Packaging Type: Ready-to-Feed Bottles, Powdered Cans, Liquid Concentrates, Sachets, Tins Distribution Channel: Pharmacies, Supermarkets, Online Retail, Specialty Baby Stores, Convenience Stores Application: Infant Nutrition, Complementary Feeding, Growth and Development, Digestive Health, Allergy Management |
| Companies Covered | Nestlé S.A., Danone S.A., Abbott Laboratories, Reckitt Benckiser Group PLC, Perrigo Company plc, Arla Foods, Yili Group, FrieslandCampina, Bellamy’s Organic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Follow on Formula Milk Market Shifts & Advancements
Precision fermentation and enzymatic hydrolysis technologies are restructuring ingredient sourcing, while regulatory divergence between Codex Alimentarius and national implementations is fragmenting formulation strategies across export markets.
Precision fermentation-derived lactoferrin and human milk oligosaccharides are displacing conventional dairy-sourced bioactives in premium follow-on formulations. Specialty ingredient suppliers in the Netherlands and California are scaling capacity to serve organic-certified and hypoallergenic product lines. This biotechnology shift is displacing commodity whey fractionation as the dominant margin capture mechanism in medical nutrition segments.
The EU's updated Food for Specific Groups regulation tightens maximum iron and protein ceilings while mandating DHA minimums for CE-marked follow-on formulas. Manufacturers must reformulate existing SKUs or withdraw from EU member state markets, with reformulation costs concentrated among mid-tier brands lacking medical nutrition infrastructure. The compliance burden falls heaviest on exporters relying on Codex-aligned formulations that predate the 2023 EFSA scientific opinion.
Subscription-based replenishment models are capturing parent loyalty through predictive algorithms tied to pediatric growth curves and consumption velocity. Traditional retail and pharmacy channels are losing volume share to direct-to-consumer platforms offering personalized nutrition counseling and auto-ship convenience. This behavioral shift is most pronounced in urban China and South Korea, where dual-income households prioritize time savings over point-of-sale price comparison.
Follow on Formula Milk Market Segmentation
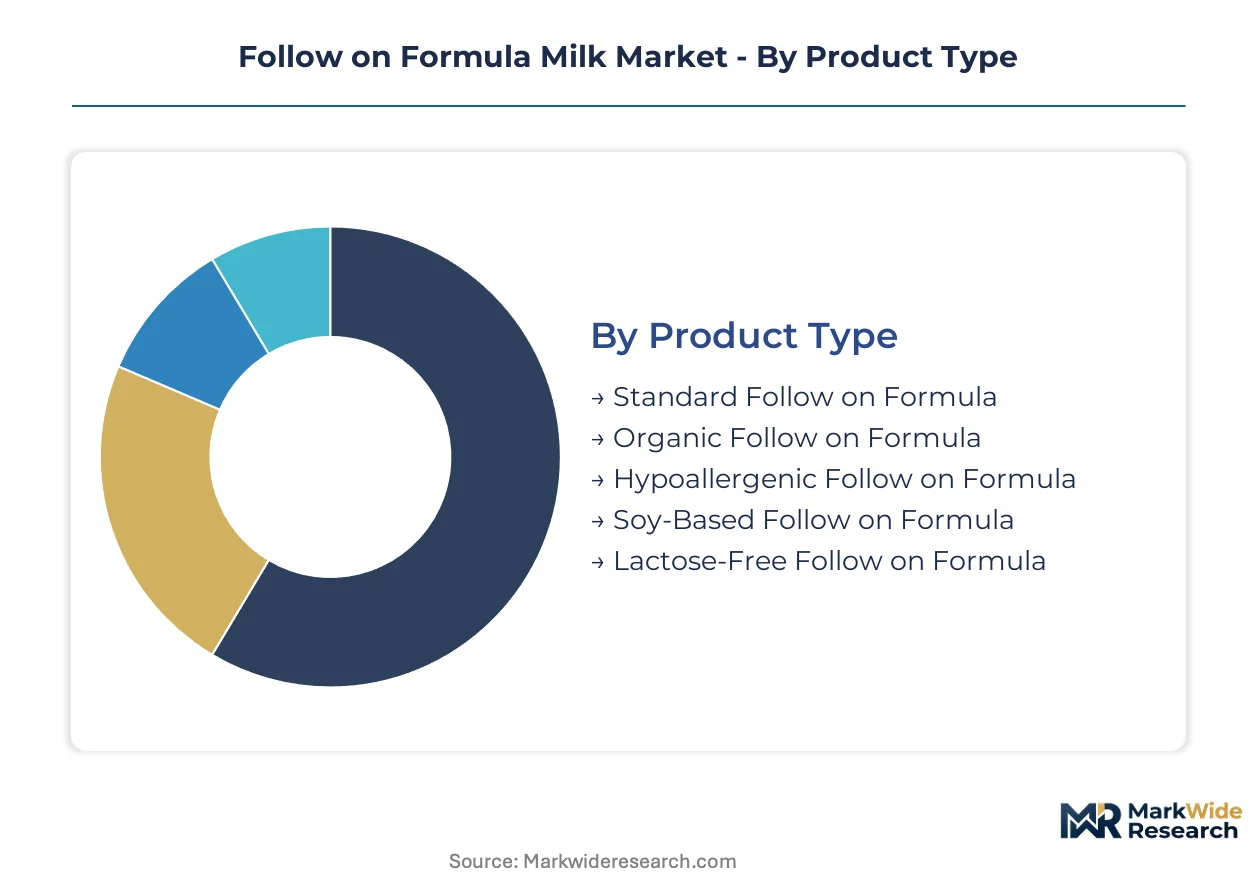
Segmentation in follow on formula milk reveals how regulatory frameworks, feeding protocols, and channel economics partition demand across distinct product architectures. Manufacturers must align formulation investments with the specific compliance and margin structures each segment imposes.
Product Type:
EFSA compositional benchmarks and national registration tracks create divergent compliance burdens that stratify product development priorities across formulation categories.
- Standard Follow on Formula:Cow's milk-based formulations with adjusted protein ratios and added iron serve as the baseline nutritional bridge for infants transitioning to complementary foods. Volume concentrates in supermarket and pharmacy channels across Germany, France, and the United Kingdom where price-sensitive household penetration remains highest.
- Organic Follow on Formula:Certified organic ingredient sourcing commands premium positioning through clean-label differentiation in specialty retail. Demand clusters in urban China and South Korea where dual-income households absorb 40-60% price premiums for pesticide-free dairy provenance and transparent supply chains.
- Hypoallergenic Follow on Formula:Extensively hydrolyzed protein structures address cow's milk protein allergy management under clinical supervision.
- Soy-Based Follow on Formula:Plant-protein formulations serve lactose-intolerant infant populations excluded from dairy-based nutrition.
- Lactose-Free Follow on Formula:Enzymatically treated dairy bases retain cow's milk protein while eliminating disaccharide content for primary lactase deficiency cases.
Standard formulations handle the majority of throughput; organic variants are expanding most quickly on share as clean-label premiums persist across pharmacy and specialty channels.
Packaging Type:
Cost structures and consumption velocity determine format selection, with shelf stability and preparation time operating as the primary trade-off variables.
- Ready-to-Feed Bottles:Pre-sterilized single-serve containers eliminate preparation steps entirely. Demand surges in online retail networks across China and convenience store channels in Japan where time-constrained parents prioritize immediate consumption.
- Powdered Cans:Dehydrated formulations in metal or composite containers offer extended shelf stability and lowest per-serve logistics costs. Volume dominates in traditional retail across the United States, Brazil, and Mexico where price-per-gram sensitivity shapes purchasing decisions.
- Liquid Concentrates:Dilution-required formats balance convenience with cost reduction for mid-tier positioning.
- Sachets:Single-serve powder pouches serve travel and trial-size applications.
- Tins:Bulk metal packaging retains presence in emerging market traditional trade.
Powdered cans anchor the volume base; ready-to-feed bottles are climbing the fastest as dual-income household expansion compresses preparation time tolerance.
Distribution Channel:
Channel selection determines margin capture and regulatory exposure, with pharmacy networks imposing distinct credentialing requirements versus mass retail.
- Pharmacies:Clinical channel access requires extended safety documentation and pharmacist recommendation protocols. Premium organic and hypoallergenic variants concentrate here in France, Germany, and Switzerland where medical credibility commands price elevation.
- Supermarkets:Mass retail placement maximizes household penetration for standard formulations. Volume concentrates in hypermarket chains across Spain, Italy, and Poland where promotional intensity and shelf visibility drive brand selection.
- Online Retail:Direct-to-consumer platforms capture recurring revenue through subscription algorithms. Growth concentrates in urban China and South Korea where predictive replenishment tied to pediatric milestones displaces point-of-sale purchasing.
- Specialty Baby Stores:Curated assortment and staff consultation support premium positioning.
- Convenience Stores:Impulse and emergency purchase occasions capture ready-to-feed format velocity.
Supermarkets maintain the broadest throughput; online retail is gaining share fastest as auto-replenishment models lock in parent loyalty.
Application:
Pediatric nutrition guidelines and feeding stage protocols segment demand by functional outcome rather than demographic characteristic.
- Infant Nutrition:Core caloric and micronutrient provision for six-to-twelve-month developmental windows. Demand concentrates where breastfeeding cessation protocols and maternal employment patterns intersect in OECD economies.
- Complementary Feeding:Nutritional bridge during family food introduction. Growth concentrates in China and India where traditional weaning practices integrate formula supplementation.
- Growth and Development:DHA and iron fortification targeting neurodevelopmental outcomes.
- Digestive Health:Prebiotic and probiotic formulations addressing gut microbiome establishment.
- Allergy Management:Clinical-grade hydrolysates for diagnosed protein intolerance cases.
Infant nutrition carries the volume foundation; complementary feeding applications show the steepest expansion trajectory as feeding protocol guidance evolves across pediatric associations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances reshape regional positioning across the Follow on Formula Milk Market, with regulatory divergence creating distinct compliance corridors for cross-border trade flows.
China
Urban dual-income households in Shanghai and Beijing drive premium organic and hypoallergenic absorption at 40-60% price elevation above standard formulations. The National Medical Products Administration enforces GB standards registration through separate domestic and cross-border e-commerce tracks, doubling compliance burden for foreign exporters. Manufacturing clusters concentrate in Inner Mongolia and Heilongjiang where Yili Group and local dairy cooperatives scale organic-certified powder production for domestic pharmacy networks.
Germany
Pharmacy channel premiumization in Munich and Hamburg absorbs medical nutrition variants with extended safety documentation protocols. The Federal Office of Consumer Protection and Food Safety implements EFSA compositional benchmarks under EU Food for Specific Groups regulation, mandating reformulation of legacy SKUs. Production gravity sits in North Rhine-Westphalia where FrieslandCampina operates dehydration facilities serving CE-marked export demand across Benelux and Scandinavia.
United States
Ready-to-feed format velocity concentrates in convenience store networks across California and Texas where time-constrained parents prioritize immediate consumption. The FDA and Infant Formula Act maintain nutrient floor and ceiling requirements that shape product architecture for domestic-market entrants. Manufacturing scale clusters in Ohio and Arizona where Abbott Laboratories and Nestlé S.A. control powdered can cost structures through multi-continent supply integration.
France
Specialty baby store networks in Paris and Lyon curate organic-certified assortments commanding pharmacist recommendation premiums. ANSM enforces clinical-grade credentialing timelines stretching 18-36 months for novel hypoallergenic ingredients seeking hospital channel access. Danone S.A. anchors medical nutrition credibility from its European dairy heritage base in Île-de-France, exporting hypoallergenic lines to Middle Eastern pharmacy networks.
Australia
Clean-label provenance demand from Chinese cross-border e-commerce platforms elevates organic powder exports from Victorian dairy regions. FSANZ maintains compositional standards aligned with Codex Alleviation revisions while monitoring divergence from EU EFSA benchmarks. Bellamy's Organic and local certified processors in Tasmania scale lactoferrin-enhanced formulations for Asia-Pacific specialty retail channels.
Follow on Formula Milk Market Competitive Landscape
Listed leaders compete with private specialists across formulation credibility and channel access dimensions, producing a tiered structure where medical nutrition infrastructure separates margin-capture tiers from commodity-grade positioning. Three archetypes dominate: European heritage dairy conglomerates with clinical-grade credibility, North American health science conglomerates with hospital channel relationships, and Asia-Pacific organic specialists with clean-label export positioning. Competitive moves concentrate on M&A for hypoallergenic ingredient pipelines and strategic partnerships for precision fermentation capacity scaling.
Within the European heritage tier, Danone S.A. and FrieslandCampina occupy positions anchored by decades of dairy fractionation expertise and CE-marking compliance infrastructure. Nestlé S.A. exemplifies the scale-driven multinational archetype with manufacturing dispersion across multiple continents controlling cost structures in high-volume powdered formats. Abbott Laboratories represents the clinical-grade specialist archetype, differentiated through extended safety documentation cycles and pharmacy channel credentialing that medical nutrition portfolios require.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Danone S.A. |
| Abbott Laboratories |
| Reckitt Benckiser Group PLC |
| Perrigo Company plc |
| Arla Foods |
| Yili Group |
| FrieslandCampina |
| Bellamy's Organic |
| Others |
Supply & Pricing Matrix
Dehydration facility scale economies in North Rhine-Westphalia and Inner Mongolia anchor cost floors across the Follow on Formula Milk Market, concentrating margin leverage among multi-continent producers while fragmenting pricing power among regional processors dependent on spot whey markets.
Pricing Analysis
Pharmacy channel buyers anchor premium-mid-economy pricing differentiation across the Follow on Formula Milk Market. Certification grade under EFSA benchmarks and organic provenance credentials drive 40-60% price elevation for hypoallergenic and clean-label variants. Cost compression in standard-grade formulations is intensifying because New Zealand milk powder auction volatility feeds into whey concentrate input costs. Mass retail purchasers in hypermarket chains exhibit highest price sensitivity, while hospital procurement committees accessing clinical-grade hydrolysates show lowest elasticity.
Supply Chain Analysis
Strait of Malacca transit underwrites lactoferrin and human milk oligosaccharide flows from Dutch specialty ingredient suppliers to Asia-Pacific formulation plants. Manufacturing gravity centers on Germany, the Netherlands, and China, with precision fermentation capacity scaling in California. Raw material dependencies include dairy whey fractions, plant-protein hydrolysates, and enzymatically treated bases. Single-source vulnerability concentrates in precision fermentation-derived bioactives where capacity lags demand expansion. Distribution runs through pharmacy networks in France and Germany, supermarket chains in Southern Europe, and direct-to-consumer platforms in urban China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Follow on Formula Milk Market functions as a regulatory-moat arena where CE marking infrastructure and extended safety documentation cycles create switching costs that entrench incumbents against commodity-grade challengers.
For Market Incumbents: Fortify medical nutrition credibility through backward integration into precision fermentation capacity for lactoferrin and human milk oligosaccharides. Expand dehydration facility footprint in Inner Mongolia to capture organic-certified powder demand from Chinese pharmacy networks. Plant-protein hydrolysate entrants threaten margin structure in lactose-free segments; defend through exclusive supply agreements with Dutch enzymatic technology specialists.
For New Entrants and Emerging Players: Subscription-based replenishment algorithms represent a service-layer gap where incumbents under-serve predictive auto-replenishment demand in South Korean dual-income households. Target direct-to-consumer platforms with pediatric milestone-calibrated auto-ship models. Penetrate plant-protein convergence segments for lactose-intolerant populations previously excluded from dairy-based nutrition. Go-to-market angle: partner with specialty baby store networks in France for pharmacist recommendation protocols.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision fermentation-enabled organic-certified specialists with pharmacy channel credentialing. Long-term viability favors acquisition targets possessing dual-track compliance infrastructure for EU CE marking and China GB standards registration. Signal to monitor: divergence between Codex Alimentarius revisions and EFSA benchmark implementations that would force reformulation cost spikes among mid-tier brands lacking medical nutrition portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Scaling | Biotechnology-derived lactoferrin displaces commodity whey fractionation in premium segments. |
| Dual-Track Regulatory Certification | CE marking plus China NMPA registration opens parallel EU and Asia-Pacific pharmacy channels. |
| Direct-to-Consumer Platform Launch | Auto-replenishment algorithms lock parent loyalty ahead of traditional retail displacement. |
| Plant-Protein Formulation Pipeline | Pea and rice hydrolysate technologies access lactose-intolerant populations excluded from dairy. |
| Pharmacy Channel Expansion | Hospital and pharmacist recommendation protocols command 40-60% price elevation for hypoallergenic variants. |
Research Methodology
Operator-level perspectives from brand managers at European heritage dairy conglomerates, category buyers at German pharmacy networks, procurement leads at Chinese cross-border e-commerce platforms, and regulatory affairs specialists navigating EFSA benchmarks anchored the qualitative base. Secondary validation drew from FDA Infant Formula Act filings, EFSA scientific opinions, China NMPA registration databases, and customs records tracking whey protein concentrate trade flows. Bottom-up SKU-level volume builds triangulated against top-down macroeconomic consumption models.
Sensitivity analysis tested forecast robustness across regulatory implementation timelines and dairy commodity price scenarios over the projection horizon. Segmentation dimensions modeled include formulation category, packaging format, distribution channel, and application by pediatric feeding protocol. CAGRs were derived from regression analysis against dual-income household expansion rates and pharmacy channel premiumization trends. Industry-specific inputs incorporated precision fermentation capacity buildout schedules and EFSA compositional benchmark compliance costs.
Forecasts assume regulatory continuity in EU Food for Specific Groups implementation and China GB standards registration tracks; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as Codex Alimentarius revision timelines and national regulator implementation divergences evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Hypo Anti Allergic Baby Food Market
Baby Food and Infant Formula
Pureed Food Market
Baby Food and Infant Formula
Asia Pacific Organic Baby Food Market
Baby Food and Infant Formula
Anti-Spit Up Formula Market
Baby Food and Infant Formula
Growing Up Formula Market
Baby Food and Infant Formula
Infant Formula Ingredients Market
Baby Food and Infant Formula
Baby Food Testing Market
Baby Food and Infant Formula
BRIC Organic Baby Food Market
Baby Food and Infant Formula
Infant Nutrition Market
Baby Food and Infant Formula
Infant Formula Market
Baby Food and Infant Formula
Europe Organic Baby Food Market
Baby Food and Infant Formula
Growing Up Milk Market
Baby Food and Infant Formula
Organic Follow Up Formula Market
Baby Food and Infant Formula
Baby Infant Formula Market
Baby Food and Infant Formula
Infant Formula Milk Powder Market
Baby Food and Infant Formula
South America Baby Food Market