
 South America Organic Baby Food Market | 2026-2036
South America Organic Baby Food Market Size, Share, and Industry Trends Forecast 2026-2036
South America Organic Baby Food Market Analytics
Organic quinoa and amaranth flour is recalibrating cost structures across puree formulations as these Andean grains replace conventional rice bases in premium SKUs. Nestle SA leverages its regional manufacturing footprint to secure consistent supply of certified organic inputs across Brazilian retail networks. Danone SA anchors its position through specialized dairy-free organic lines that address lactose-intolerance prevalence in Andean populations. HiPP GmbH & Co Vertrieb KG differentiates via stringent EU-equivalent organic protocols that exceed baseline regional requirements.
Organic baby food comprises minimally processed infant nutrition products manufactured from certified organic agricultural inputs, free from synthetic pesticides, genetically modified organisms, and artificial preservatives, with formulations typically meeting specific macronutrient density thresholds for infants aged four to twenty-four months. The category serves parents and caregivers seeking reduced chemical exposure during critical neurodevelopmental windows. Pouches dominate packaging type due to convenience-driven consumption patterns among working parents, while jars retain strength in gift-oriented and bulk-purchase occasions. Online retailers represent the fastest-expanding distribution channel as logistics networks improve same-day delivery reliability in metropolitan Brazil and Argentina.
ANVISA governs organic labeling and infant food safety standards in Brazil, while Argentina's national food safety authority enforces equivalent organic certification protocols; both frameworks elevate compliance costs for imported brands. The EU Green Deal's extraterritorial supply chain due diligence requirements increasingly shape sourcing decisions for multinational manufacturers operating in the region. Stakeholders must monitor evolving mercury and heavy-metal testing thresholds as regulatory convergence between Mercosur and European standards accelerates.
Market Dynamics
ANVISA's tightened organic traceability mandates are forcing manufacturers to reconfigure procurement networks around certified Andean grain suppliers, compressing legacy sourcing timelines and elevating compliance infrastructure spend across Brazilian formulation facilities.
Growth Catalysts
- Clean-label pediatric recommendations:São Paulo-based pediatricians increasingly prescribe organic puree regimens for infants with suspected chemical sensitivities, normalizing premium-tier purchases among insured families.
- EU Green Deal supply chain due diligence:Extraterritorial sourcing requirements are accelerating documentation standardization among Brazilian exporters seeking Mercosur-EU trade alignment.
- Organic quinoa substitution:Andean cooperative networks in Peru and Bolivia are displacing conventional rice bases in premium SKUs, reducing pesticide residue exposure while meeting macronutrient density thresholds.
Market Restraints
- Certified organic input cost volatility:Weather-driven amaranth harvest fluctuations in the Bolivian Altiplano create formulation cost instability for manufacturers dependent on single-origin grain contracts.
- Import dependency for specialized enzymes:Protease and lipase suppliers concentrate in European biotech clusters, exposing Brazilian processors to currency-driven input price spikes.
- ANVISA mercury testing thresholds:Accelerating regulatory convergence with EU heavy-metal standards is extending batch-release timelines and elevating third-party laboratory spend.
Strategic Opportunities
- Argentina's underpenetrated interior provinces:Córdoba and Mendoza present whitespace for direct-to-pediatrician distribution models bypassing modern-trade concentration in Buenos Aires.
- Subscription-based replenishment platforms:São Paulo logistics networks now enable same-day pouch delivery, unlocking recurring revenue models for working-parent segments.
- Dairy-free formulation expansion:Lactose-intolerance prevalence in Andean Colombian and Ecuadorian populations creates addressable demand for specialized organic lines.
Industry Challenges
- Organic chemist talent scarcity:Brazilian universities produce insufficient formulation specialists trained in both infant nutrition science and organic certification audit protocols.
- Legacy ERP integration with traceability blockchains:Mid-tier manufacturers struggle to reconcile ANVISA-mandated lot-tracking with existing inventory management architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Organic Baby Food Market |
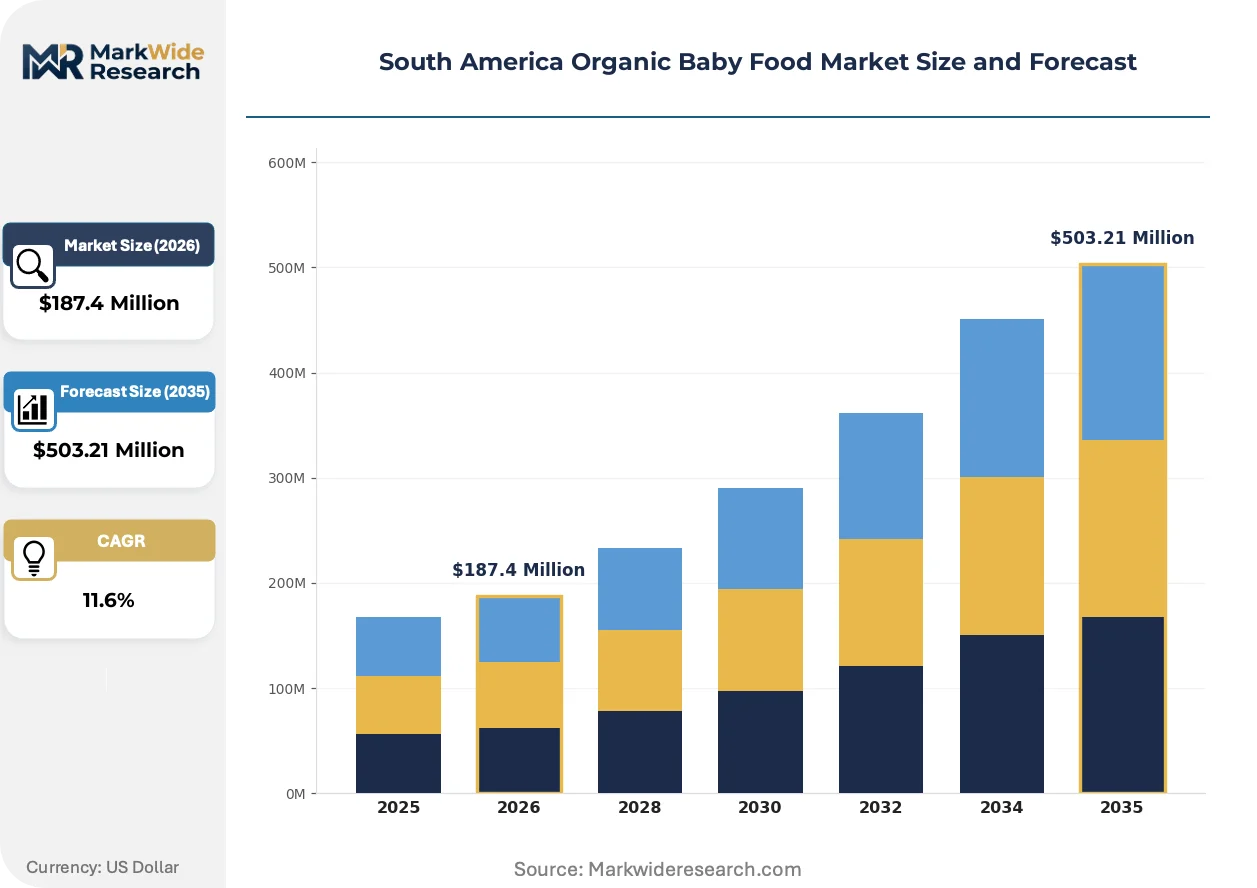
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Grains, Meats Packaging Type: Pouches, Jars, Tubs, Cans Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Convenience Stores End User: Parents, Caregivers, Health Professionals, Nutritionists |
| Companies Covered | Nestle SA, Danone SA, Abbott Laboratories, The Hain Celestial Group Inc, HiPP GmbH & Co Vertrieb KG, The Hero Group, Reckitt Benckiser Group plc, Holle baby food AG, Sun-Maid Growers of California, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Organic Baby Food Market Evolving Landscape
Refrigerated clean-label formats and blockchain-verified origin claims are compressing shelf-stable dominance while elevating transparency expectations among metropolitan millennial parents.
High-pressure processing is expanding into organic fruit and vegetable puree production, eliminating thermal degradation of heat-sensitive vitamins while extending refrigerated shelf life. São Paulo's premium supermarket chains are adopting these SKUs at pace, displacing retort-pouched alternatives in the refrigerated set. The technology is expanding into mid-tier price bands as equipment manufacturers localize service networks.
Argentina's national food safety authority is enforcing equivalent organic certification protocols that mirror EU baseline requirements, elevating documentation burdens for cross-border Brazilian suppliers. Industrial consequence includes mandatory third-party audit rotation and accelerated heavy-metal testing cadences. Andean-origin quinoa-based formulations face the steepest compliance cost escalation.
Subscription replenishment models are displacing traditional bulk-purchase occasions among dual-income households in metropolitan Brazil. Direct-to-consumer platforms bypass modern-trade slotting fees while capturing purchase-cycle data for personalized formulation recommendations. This channel rotation concentrates most visibly in São Paulo's Zona Sul and Pinheiros districts.
South America Organic Baby Food Market Segmentation
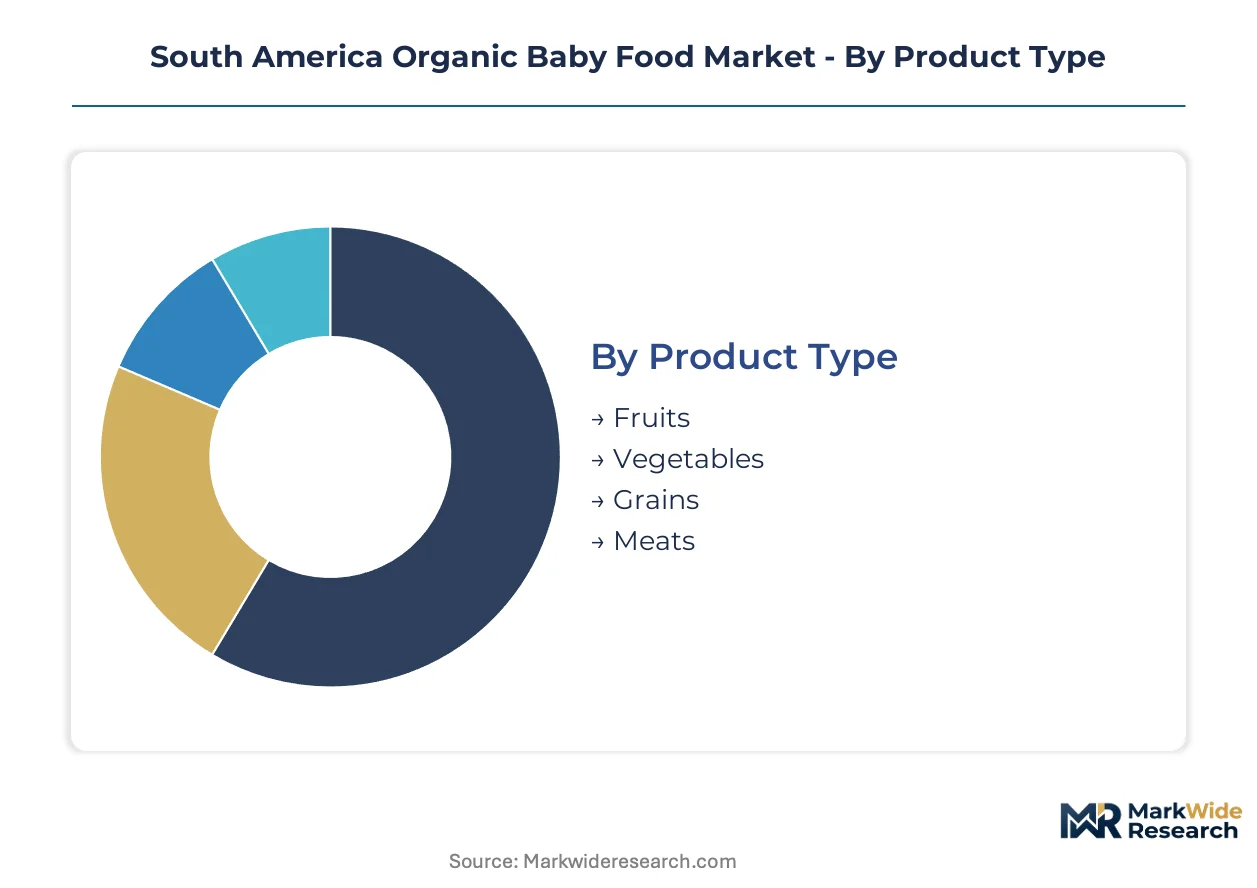
Segmentation in the South America organic baby food market reveals distinct procurement patterns across urban millennial parents, pediatric care networks, and institutional buyers. Understanding these divides exposes where pricing power concentrates and where formulation specialization unlocks premium positioning.
Product Type:
Parental purchasing decisions diverge sharply by neurodevelopmental stage and perceived chemical exposure risk, with Andean-origin grains commanding distinct loyalty among São Paulo's insured families.
- Fruits:Single-variety organic apple and pear purees dominate first-food introductions due to low allergenicity profiles. São Paulo pediatricians prescribe these as baseline regimens for infants aged four to six months, normalizing premium-tier entry points.
- Vegetables:Sweet potato and carrot formulations carry the highest repeat-purchase rates among working parents seeking vegetable-forward nutrition without preparation time. Demand concentrates in Buenos Aires metropolitan supermarkets where dual-income households prioritize convenience.
- Grains:Quinoa and amaranth-based cereals displace conventional rice bases in premium SKUs sourced from Peruvian and Bolivian cooperative networks.
- Meats:Organic beef and chicken purees remain niche, constrained by ANVISA's extended batch-release timelines for animal-derived infant foods.
Volume sits with Fruits; growth tilts toward Grains.
Packaging Type:
Format selection tracks consumption occasion and retail channel, with convenience-driven formats capturing metropolitan working-parent segments while traditional containers retain gift and bulk-purchase utility.
- Pouches:Retort-pouched single-serve formats enable on-the-go feeding without refrigeration, dominating São Paulo's Zona Sul and Pinheiros districts. Same-day delivery logistics from subscription platforms reinforce format lock-in among dual-income households.
- Jars:Glass containers retain strength in gift-oriented purchases and pediatrician sample programs across Buenos Aires, where perceived quality signaling outweighs portability concerns.
- Tubs:Multi-serve plastic containers serve price-sensitive buyers in Brazil's interior states seeking volume efficiency over premium positioning.
- Cans:Metal packaging persists in value-tier SKUs distributed through Brazil's Northeast informal retail networks, though declining in absolute share.
Consumption frequency concentrates in Pouches; format innovation targets Jars.
Distribution Channel:
Channel selection reflects urban density, insurance coverage penetration, and delivery infrastructure maturity, with digital platforms displacing traditional retail in Brazil's coastal metros.
- Supermarkets:São Paulo's premium chains anchor refrigerated clean-label sets, stocking high-pressure processed SKUs that displace shelf-stable alternatives. Modern-trade slotting fees compress margins for mid-tier manufacturers.
- Online Retailers:Direct-to-consumer platforms bypass traditional retail economics while capturing purchase-cycle data for personalized recommendations. Logistics networks now enable same-day pouch delivery reliability in metropolitan Brazil and Argentina.
- Specialty Stores:Organic-focused retailers in Córdoba and Mendoza serve as pediatrician referral destinations, bypassing Buenos Aires modern-trade concentration.
- Convenience Stores:Limited organic SKU penetration reflects margin constraints and inventory turnover requirements in small-format retail.
Transaction volume flows through Supermarkets; customer acquisition shifts toward Online Retailers.
End User:
Prescription authority and nutritional expertise create divergent influence patterns, with institutional gatekeepers driving initial trial while caregivers control repurchase decisions.
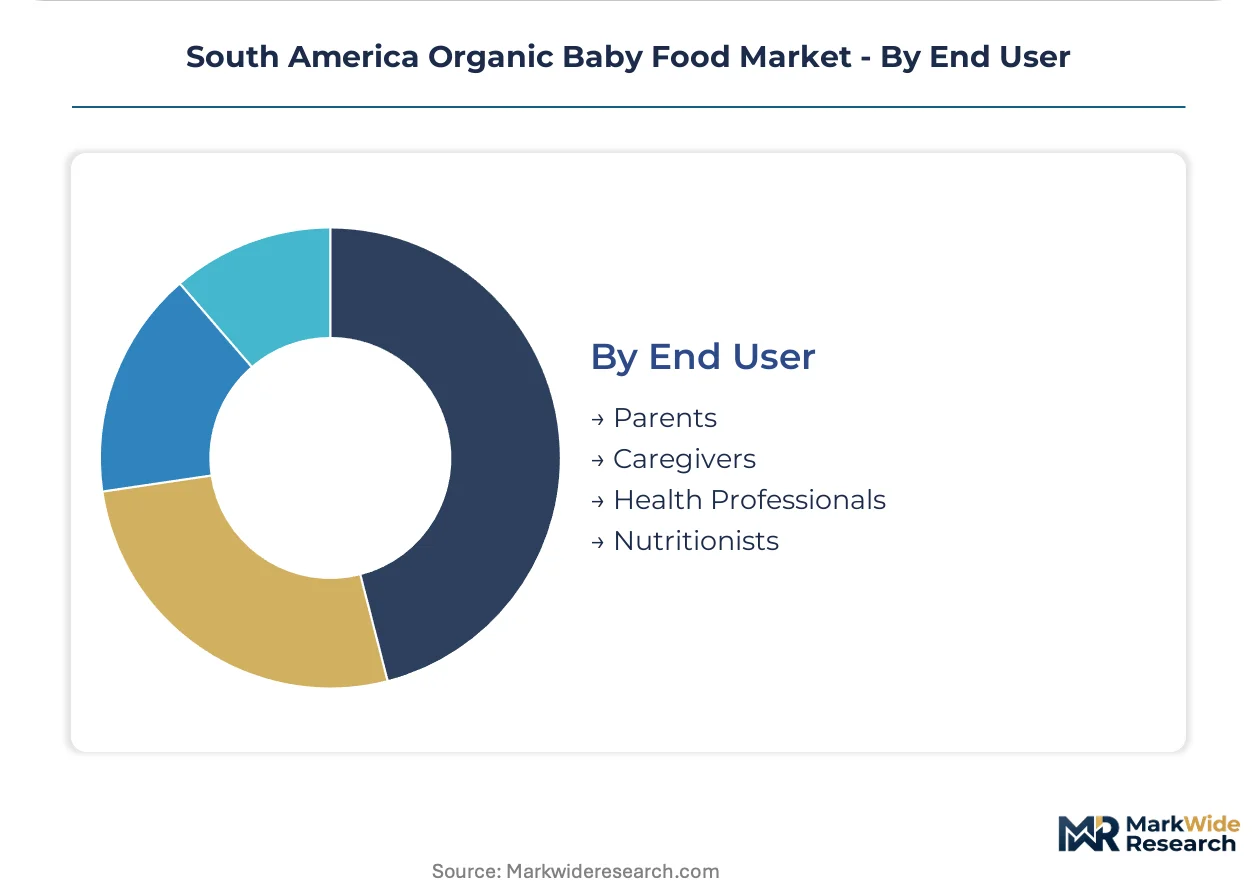
- Parents:Urban millennial buyers in São Paulo and Buenos Aires execute actual purchasing decisions, responding to clean-label claims and blockchain-verified origin transparency.
- Caregivers:Extended family members and professional child-care providers influence bulk-purchase occasions, particularly in multi-generational Brazilian households.
- Health Professionals:São Paulo-based pediatricians increasingly prescribe organic puree regimens for infants with suspected chemical sensitivities, normalizing premium-tier purchases among insured families.
- Nutritionists:Licensed practitioners in Argentina's national food safety framework guide specialized dietary interventions, though narrower reach than physician networks.
Decision authority rests with Parents; trial generation depends on Health Professionals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban millennial parents in São Paulo and Buenos Aires concentrate demand for premium organic infant nutrition, with metropolitan purchasing power dictating regional market trajectories across the continent.
Brazil
ANVISA's tightened organic traceability mandates force manufacturers to reconfigure procurement networks around certified Andean grain suppliers, compressing legacy sourcing timelines. São Paulo's Zona Sul and Pinheiros districts anchor pouch-format consumption as subscription platforms enable same-day delivery reliability.
Argentina
Buenos Aires metropolitan supermarkets drive vegetable-forward puree demand among dual-income households prioritizing convenience over preparation time. The national food safety authority enforces organic certification protocols mirroring EU baseline requirements, elevating documentation burdens for cross-border suppliers.
Chile
Santiago's premium retail chains are adopting high-pressure processed refrigerated SKUs at pace, displacing retort-pouched alternatives in the clean-label set. The country's national food safety regulator aligns testing cadences with accelerating Mercosur-EU regulatory convergence.
Colombia
Bogotá's insured families generate trial demand through pediatrician-prescribed organic regimens for infants with suspected chemical sensitivities. Lactose-intolerance prevalence in Andean populations creates addressable demand for specialized dairy-free organic lines.
Peru
Lima-based cooperative networks supply quinoa and amaranth flour that displaces conventional rice bases in premium SKUs across Brazilian formulation facilities. Weather-driven harvest fluctuations in the Altiplano create input cost instability for manufacturers dependent on single-origin grain contracts.
South America Organic Baby Food Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational nutrition conglomerates commanding modern-trade shelf space while regional cooperatives supply certified organic inputs. The market structure tilts toward consolidated control at the premium tier, where EU-equivalent certification protocols create entry barriers. Three archetypes dominate: vertically integrated multinationals with captive Andean sourcing, specialized organic pure-play brands with stringent protocol differentiation, and private-label contract manufacturers serving mid-tier price bands. Competitive moves center on strategic partnerships with Andean cooperative networks and portfolio diversification into refrigerated clean-label formats.
Within the multinational tier, Nestle SA and Danone SA exemplify scale-driven positioning through regional manufacturing footprints and specialized dietary lines. HiPP GmbH & Co Vertrieb KG occupies a distinct archetype as a European-origin pure-play organic specialist whose EU-equivalent protocols exceed baseline regional requirements, representing the premium-certification differentiation vector that compresses mid-tier competitor margins.
| Leading Market Players |
|---|
| Nestle SA |
| Danone SA |
| Abbott Laboratories |
| The Hain Celestial Group Inc |
| HiPP GmbH & Co Vertrieb KG |
| The Hero Group |
| Reckitt Benckiser Group plc |
| Holle baby food AG |
| Sun-Maid Growers of California |
| Others |
Value Network & Pricing Analysis
EU Green Deal extraterritorial due diligence requirements gate both qualified organic supply and premium-tier pricing access for South American manufacturers seeking Mercosur trade alignment. ANVISA's tightened traceability mandates compound compliance costs, compressing margins for mid-tier players while consolidating pricing power among certified incumbents.
Pricing Analysis
Volume concentrates in pouches and jars at standard tier; margins accrue to refrigerated clean-label SKUs and EU-equivalent certified lines. Price differentiation hinges on organic certification grade—ANVISA baseline versus EU-equivalent protocols—and Andean-origin grain sourcing transparency. Pricing pressure intensifies in value-tier metal cans as informal retail networks in Brazil's Northeast face input cost volatility from Bolivian Altiplano weather disruptions. Price sensitivity peaks among interior-state buyers seeking multi-serve tubs; least sensitivity sits with insured São Paulo families purchasing subscription-delivered premium pouches.
Supply Chain Analysis
ANVISA's local-content traceability rules are reshaping procurement toward certified Andean cooperative networks in Peru, Bolivia, and Ecuador. Raw material dependencies center on organic quinoa flour, amaranth flour, and specialized European-sourced protease enzymes. Supply chain risk concentrates in single-origin grain contracts exposed to Altiplano climate volatility. Distribution runs through São Paulo's modern-trade premium chains and direct-to-consumer subscription platforms, with specialty stores in Argentina's interior provinces gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ANVISA's mercury testing convergence with EU standards creates a barrier-to-entry moat for players with captive laboratory infrastructure and third-party audit rotation capabilities.
For Market Incumbents: Cement sourcing exclusivity with Peruvian and Bolivian cooperative networks before traceability mandates harden. Invest in high-pressure processing equipment localization to capture refrigerated clean-label margin expansion. Defend against private-label contract manufacturers by accelerating blockchain-verified origin claims that mid-tier competitors cannot replicate without ERP overhaul spend. For New Entrants and Emerging Players: Enter via Argentina's underpenetrated Córdoba and Mendoza provinces where direct-to-pediatrician distribution bypasses Buenos Aires modern-trade slotting fee concentration. Target dairy-free formulation whitespace in Andean Colombian and Ecuadorian populations where lactose-intolerance prevalence exceeds specialized SKU availability. Launch through subscription replenishment platforms capturing São Paulo purchase-cycle data for personalized recommendation engines. For Investors and Strategic Acquirers: ANVISA batch-release timeline extensions for animal-derived purees is the leading indicator that meat-based SKU manufacturers face working capital compression requiring consolidation capital. Long-term viability favors vertically integrated players with captive Andean grain supply and in-house organic certification audit capabilities. Acquisition targets should demonstrate EU-equivalent protocol compliance and refrigerated format production infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Andean Grain Supply | Captive quinoa and amaranth sourcing locks ANVISA traceability compliance ahead of competitor procurement reconfiguration. |
| High-Pressure Processing Equipment Localization | São Paulo service network expansion enables mid-tier price band penetration for refrigerated clean-label SKUs. |
| Blockchain-Verified Origin Platform Launch | Transparency infrastructure satisfies EU Green Deal due diligence while commanding premium pricing from millennial parents. |
| Direct-to-Pediatrician Distribution Buildout | Córdoba and Mendoza channel bypass captures prescription authority driving initial organic regimen trial. |
| Dairy-Free Formulation R&D Expansion | Specialized lines address Andean population lactose-intolerance prevalence exceeding current SKU availability. |
Research Methodology
ANVISA regulatory filings, EU Green Deal supply chain documentation requirements, and Mercosur trade alignment protocols formed the secondary backbone. Primary interviews with organic certification auditors, São Paulo pediatricians prescribing puree regimens, Andean cooperative network managers, and Brazilian modern-trade category buyers combined with secondary validation. Customs records tracking quinoa and amaranth flour movements, infant nutrition formulation databases, and refrigerated logistics capacity disclosures triangulated bottom-up and top-down approaches.
Bottom-up modeling built product-type, packaging format, distribution channel, and end-user segment volumes across the projection horizon. Top-down validation cross-checked against macroeconomic indicators and pediatric demographic shifts. CAGRs derived from segment-level growth trajectory analysis incorporating ANVISA compliance cost escalation curves and high-pressure processing adoption rates. Forecast inputs included organic grain harvest volatility indices and metropolitan delivery infrastructure maturity scores.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU-Mercosur regulatory convergence or prolonged Altiplano drought conditions disrupting single-origin grain contracts. Forecasts reflect assumptions regarding certification audit capacity expansion and refrigerated logistics network buildout timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Hypo Anti Allergic Baby Food Market
Baby Food and Infant Formula
Parenteral Formula Market
Baby Food and Infant Formula
Goat Milk Formula Market
Baby Food and Infant Formula
Baby Food and Infant Formula Market
Baby Food and Infant Formula
United States Baby Food and Infant Formula Market
Baby Food and Infant Formula
North America Organic Baby Food Market
Baby Food and Infant Formula
Baby Fruit Puree Market
Baby Food and Infant Formula
Europe Organic Baby Food Market
Baby Food and Infant Formula
India Baby Food Market
Baby Food and Infant Formula
Pet Milk Replacement Products Market
Baby Food and Infant Formula
Fortified Pet Food Market
Baby Food and Infant Formula
Infant Formula Milk Powder with A2 Beta-Casein Market
Baby Food and Infant Formula
Organic Follow Up Formula Market
Baby Food and Infant Formula
Middle East and Africa Baby Food Market
Baby Food and Infant Formula
Japan Baby Food and Infant Formula Market
Baby Food and Infant Formula
Infant Formula Milk Powder Market