
 Asia Pacific Organic Baby Food Market | 2026-2036
Asia Pacific Organic Baby Food Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Organic Baby Food Market Analysis
Urban millennial parent purchasing is realigning the Asia Pacific organic baby food landscape toward premium certified nutrition. Danone leverages its specialized nutrition division to dominate probiotic-enriched organic formulations across Southeast Asian pharmacy channels. Nestlé anchors its position through backward integration into organic dairy sourcing in Australia and New Zealand. Health and Happiness (H & H) International Holding Limited differentiates via biostime-branded synbiotic positioning in China's mother-and-baby store networks.
Asia Pacific organic baby food comprises infant and toddler nutrition products manufactured without synthetic pesticides, genetically modified organisms, or artificial additives, typically processed through cold-press pureeing or gentle dehydration below 45°C to preserve nutrient density. The category serves parents seeking reduced chemical exposure during critical neurodevelopmental windows. Pouch packaging controls margin pools due to convenience-driven urban consumption and reduced logistics cost versus glass jar alternatives. Online retail channels represent the fastest-growing distribution vector, though supermarkets sustain volume leadership through impulse placement in China's hypermarket chains. Cereal segments maintain maturity in developed Australasian markets while puree demand accelerates across India's emerging organic-conscious households.
FSSAI organic labeling rules in India, China's SAMR infant formula registration requirements, and Australia's FSANZ organic certification framework collectively elevate compliance costs while restricting gray-market import access. Australia's BFA and NASAA standards create dual-certification complexity for exporters targeting both domestic and pan-Asian channels. Stakeholders must monitor regulatory divergence between harmonized ASEAN organic standards and country-specific additive prohibitions as formulation strategies for cross-border portfolio deployment.
Market Dynamics
Millennial parental anxiety about synthetic chemical exposure during infant neurodevelopmental windows is compressing purchasing cycles toward certified organic SKUs across Asia Pacific metropolitan clusters.
Growth Catalysts
- FSSAI Organic Certification Mandate:India's food safety regulator enforces mandatory third-party organic verification, eliminating uncertified domestic competitors and elevating compliant brand shelf access in organized retail.
- Synbiotic Formulation Technology:Probiotic-prebiotic combinations in infant cereals are commanding 15-20% price premiums in China's mother-and-baby store networks.
- Urban Parent Density:Concentrated millennial households in Shanghai, Mumbai, and Sydney generate disproportionate trial rates for cold-pressed puree pouches versus traditional glass jar formats.
Market Restraints
- Organic Dairy Input Volatility:Australia's drought-prone pasture systems create 18-24 month lag in certified milk powder availability, constraining formula production scheduling.
- Dual-Certification Burden:Exporters targeting both Australian domestic and pan-Asian channels must simultaneously satisfy BFA and NASAA standards, doubling audit costs.
- Glass Jar Substitution:Premium-positioned glass packaging retains preference in Japan's gift-oriented baby food culture, limiting pouch format penetration in high-value segments.
Strategic Opportunities
- Vietnam's Emerging Middle Class:Ho Chi Minh City and Hanoi present underpenetrated demand for imported organic purees as modern trade expands.
- Cross-Border E-Commerce Channels:Tmall Global and Lazada cross-border fulfillment bypass domestic registration delays for niche European organic entrants.
- ASEAN Organic Standard Harmonization:Draft regional mutual recognition protocols would collapse redundant certification requirements across Thailand, Indonesia, and Philippines.
Industry Challenges
- Cold Chain Integrity Gaps:India's fragmented last-mile refrigeration infrastructure spoils 8-12% of temperature-sensitive probiotic formulations before retail.
- Organic Ingredient Traceability:Multi-tier supplier networks across China's interior provinces complicate pesticide residue documentation for SAMR infant formula registration dossiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Organic Baby Food Market |
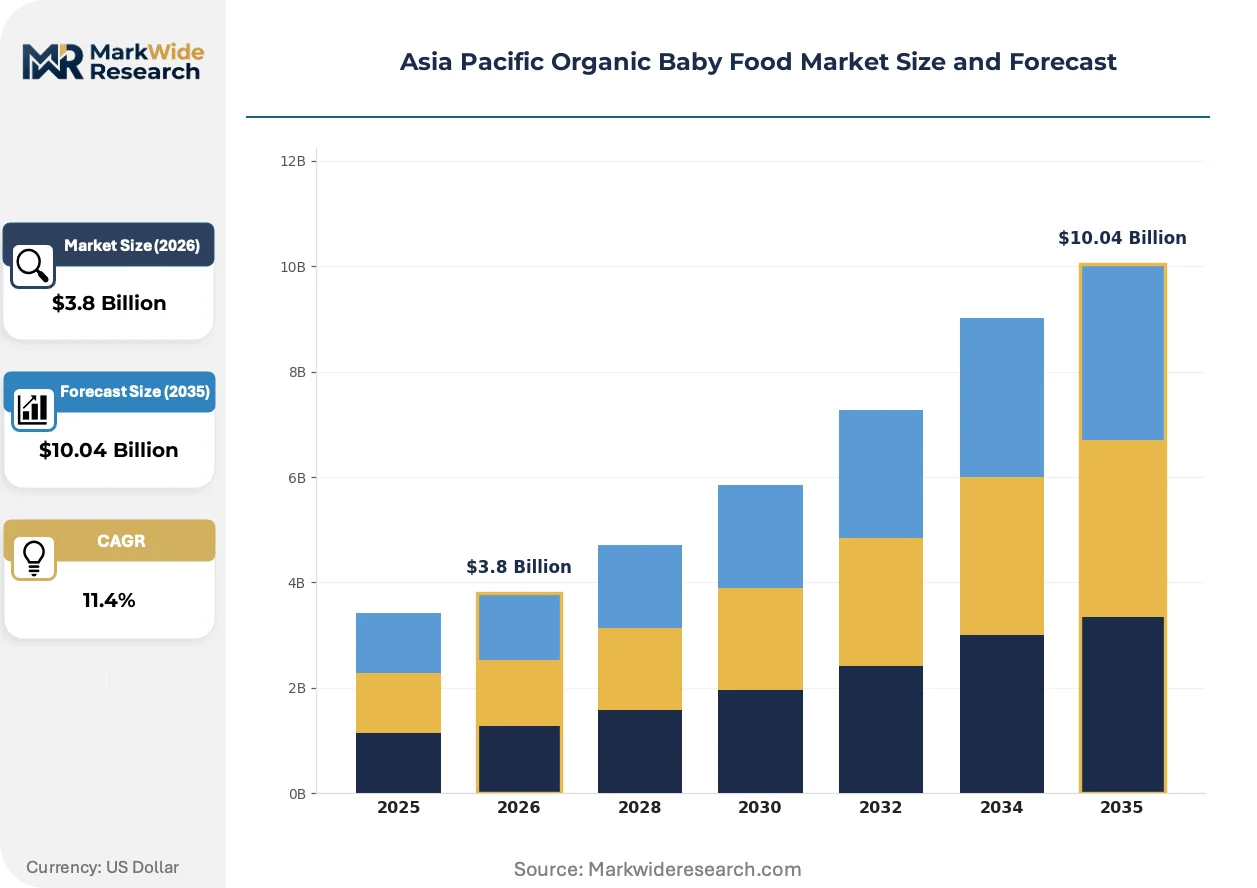
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereal, Snack, Puree, Beverage Packaging Type: Glass Jar, Pouch, Box, Tetrapak End User: Parents, Caregivers, Retailers, Healthcare Professionals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Danone, Health and Happiness (H & H) International Holding Limited, Nestlé, Kewpie Corporation, Bellamy's Australia Limited, Hero Group, Hipp GmbH & Co., Campbell Soup Company (Plum Organics), Abbott Laboratories, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Organic Baby Food Market Emerging Trajectories
Formulation science and packaging engineering are converging to extend organic shelf stability while preserving heat-sensitive nutrients. Three developments merit attention.
High-pressure processing (HPP) is automating pathogen elimination in fruit-vegetable purees without thermal degradation of vitamin C and polyphenols. Australian organic brands deploy HPP lines for export-ready pouch production. The technology is compressing the safety-versus-nutrition tradeoff that previously forced manufacturers toward aseptic thermal processing.
China's SAMR tightened residual pesticide testing protocols for imported organic infant cereals in 2024, requiring batch-level chromatography documentation. European exporters face 45-60 day customs clearance extensions while adapting laboratory reporting formats. Japanese organic rice cereal suppliers have absorbed compliance costs through dedicated Shanghai testing facilities.
Subscription-based replenishment models are displacing episodic supermarket purchasing among Seoul and Singapore dual-income households. Direct-to-consumer platforms capture consumption-pattern data that informs flavor rotation and portion sizing. This channel shift concentrates lifetime value in digitally native brands versus traditional retail-dependent incumbents.
Asia Pacific Organic Baby Food Market Segmentation
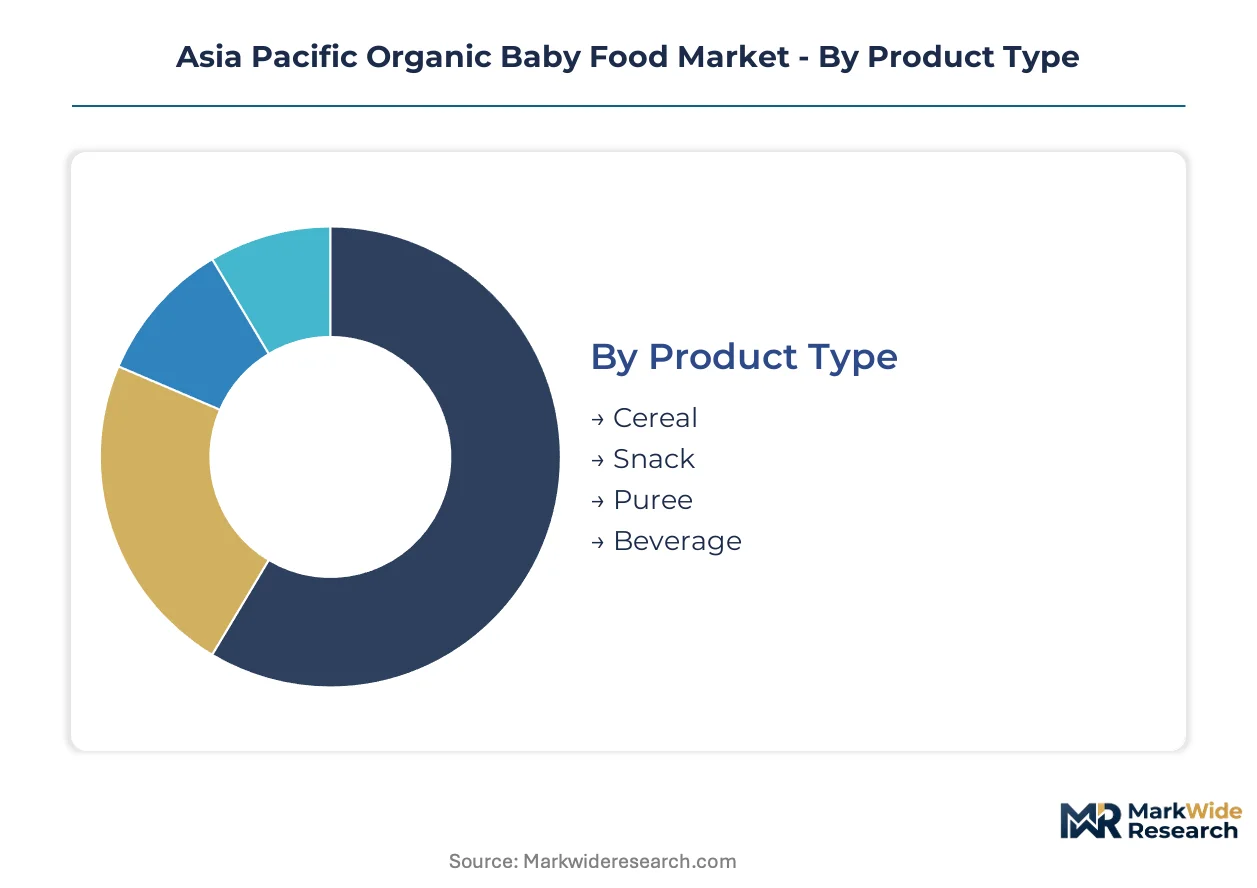
Segmentation in Asia Pacific organic baby food reveals distinct margin pools and channel strategies. Product format, packaging convenience, and distribution access determine competitive positioning across metropolitan China, India, and Southeast Asian markets.
Product Type:
Standalone consumption formats dominate shelf space, while embedded nutritional applications serve specialized dietary protocols.
- Cereal:Iron-fortified grain blends processed under certified organic protocols serve as first complementary foods. Demand concentrates in Australia's mature organic-conscious households where FSANZ labeling familiarity drives repeat purchase.
- Puree:Cold-pressed fruit-vegetable combinations packaged in single-serve formats preserve heat-sensitive vitamins. Shanghai and Mumbai millennial parents are compressing procurement cycles toward pouch-based puree SKUs for commuter convenience.
- Snack:Dehydrated organic finger foods for toddler self-feeding stages.
- Beverage:Ready-to-drink organic formulations targeting hydration and micronutrient supplementation.
Volume placements concentrate in Cereal; the faster expansion belongs to Puree.
Packaging Type:
Packaging economics split between premium shelf presentation and logistics efficiency, with format choice directly influencing channel access and margin retention.
- Pouch:Flexible multilayer laminates enable cold-fill processing and reduce shipping cube versus rigid alternatives. China's tier-one city hypermarkets are expanding pouch-facing planograms as urban parent density rises.
- Glass Jar:Inert material preserves flavor integrity and supports thermal sterilization. Japan's gift-oriented baby food culture sustains glass preference despite higher freight costs.
- Box:Carton-based formats for dry cereal and snack segments.
- Tetrapak:Aseptic carton technology for extended-shelf-life liquid formulations.
Pouch commands the densest urban distribution; Tetrapak is climbing the fastest in ambient-stable beverage applications.
End User:
Procurement authority fragments across household decision-makers, institutional gatekeepers, and retail intermediaries with divergent quality thresholds.
- Parents:Primary household purchasers exercising direct brand selection for infant nutrition. India's western states show concentrated organic trial rates among FSSAI-aware millennial households.
- Healthcare Professionals:Pediatricians and nutritionists influence formulation choices through recommendation authority. China's mother-and-baby store networks train staff to translate clinical guidance into shelf selection.
- Caregivers:Extended family and childcare providers executing proxy purchasing.
- Retailers:Category managers and buyers determining assortment depth and promotional placement.
Parent-driven segments anchor revenue stability; healthcare-influenced channels are gaining share fastest in premium-tier cities.
Distribution Channel:
Channel configuration determines registration burden, margin structure, and data capture depth for formulation feedback loops.
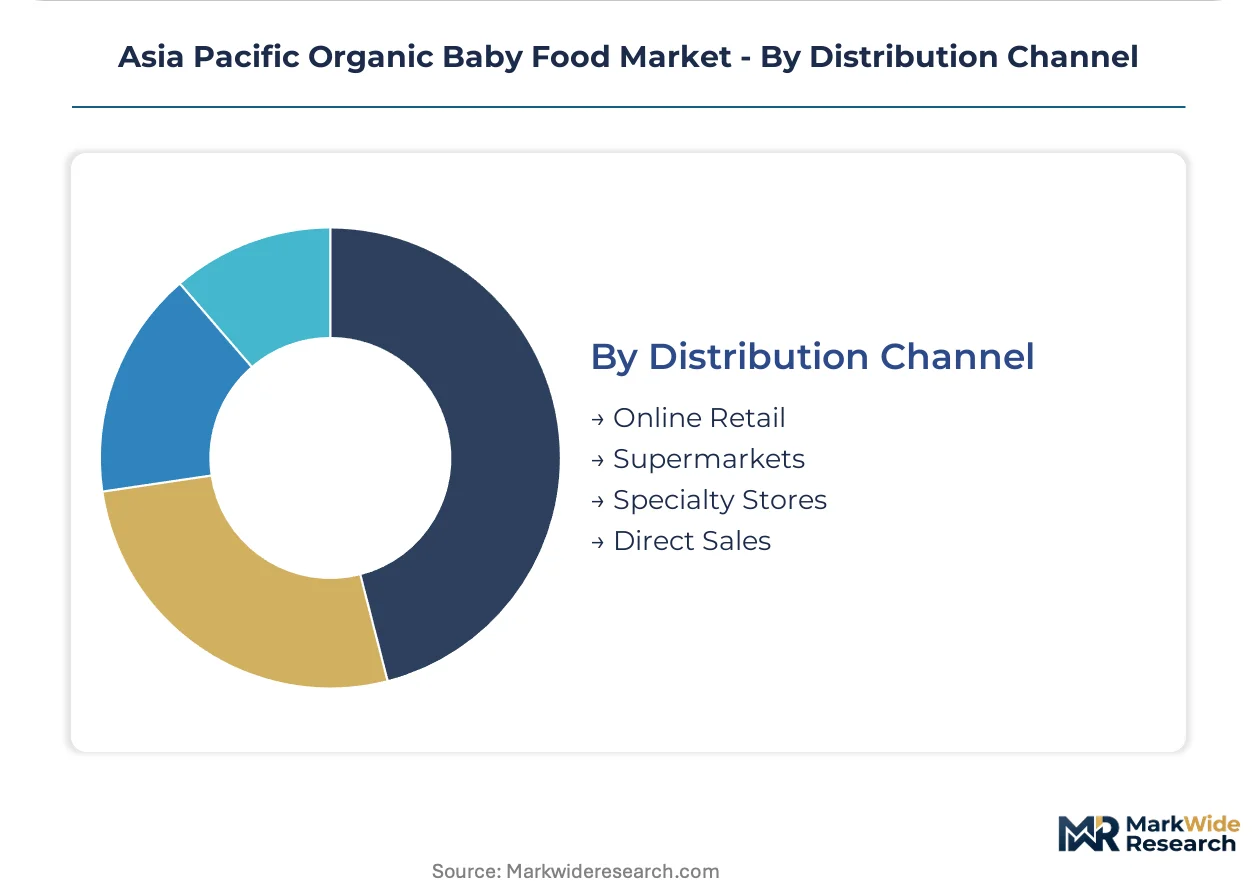
- Online Retail:Tmall Global and Lazada cross-border fulfillment bypass domestic registration delays for European organic entrants. Seoul and Singapore dual-income households are displacing episodic supermarket purchasing through subscription-based replenishment models.
- Supermarkets:China's hypermarket chains sustain volume leadership through impulse placement and promotional scale.
- Specialty Stores:Mother-and-baby focused retailers with trained consultation staff.
- Direct Sales:Manufacturer-controlled fulfillment bypassing wholesale intermediaries.
Supermarket placements dominate current volume; online retail shows the steepest expansion trajectory across metropolitan clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hainan Free Trade Port tax incentives are accelerating organic infant formula import consolidation through duty-exempt processing zones. This special-economic-zone mechanism concentrates cross-border fulfillment infrastructure for brands targeting tier-one city consumers.
China
Shanghai and Beijing millennial households drive synbiotic-enriched cereal demand through mother-and-baby store networks. SAMR tightened infant formula registration requirements in 2024, mandating batch-level pesticide residue documentation. Yangtze River Delta logistics clusters now host dedicated cold-chain facilities for HPP-processed organic puree exports.
India
Maharashtra and Gujarat urban centers show concentrated organic trial rates among FSSAI-aware millennial parents. India's food safety regulator enforces mandatory third-party organic verification, eliminating uncertified domestic competitors. Western state retail chains are expanding certified organic shelf space as compliance-driven assortment rationalization accelerates.
Australia
FSANZ organic certification familiarity sustains repeat purchase in mature organic-conscious households across Sydney and Melbourne. Drought-prone pasture systems create 18-24 month lag in certified milk powder availability, constraining formula production scheduling. Tasmanian dairy processing clusters now anchor backward integration strategies for pan-Asian organic dairy supply.
Japan
Tokyo and Osaka gift-oriented baby food culture sustains premium glass jar preference despite higher freight costs. METI-aligned organic labeling standards create dual-certification complexity for exporters targeting domestic and export channels. Kanto region retail networks maintain specialized organic infant nutrition sections with trained consultation staff.
Vietnam
Ho Chi Minh City and Hanoi present underpenetrated demand for imported organic purees as modern trade expands. Draft ASEAN organic standard harmonization would collapse redundant certification requirements across regional markets. Southern Vietnam logistics corridors are developing cross-border e-commerce fulfillment capacity for Tmall Global and Lazada channels.
Asia Pacific Organic Baby Food Market Vendor Landscape
Top-tier vendors anchor probiotic-enriched formulation segments, while mid-tier specialists compete on regional organic certification compliance. The market structure shows moderate consolidation around dairy-integrated nutrition conglomerates and Asia-Pacific organic pure-play entrants. Three archetypes dominate: backward-integrated dairy processors, synbiotic technology specialists, and cross-border e-commerce-native brands. Capacity expansion into cold-press processing lines and strategic partnerships with mother-and-baby retail chains represent the dominant competitive vectors.
Within the dairy-integrated tier, Danone and Nestlé exemplify multinational scale advantages through captive organic milk supply chains. Health and Happiness (H & H) International Holding Limited occupies a position among China-focused synbiotic specialists leveraging mother-and-baby store network penetration. These three entities represent contrasting archetypes: European conglomerate diversification, Australasian origin-brand authenticity, and domestic market digital-native positioning.
| Leading Market Players |
|---|
| Danone |
| Health and Happiness (H & H) International Holding Limited |
| Nestlé |
| Kewpie Corporation |
| Bellamy's Australia Limited |
| Hero Group |
| Hipp GmbH & Co. |
| Campbell Soup Company (Plum Organics) |
| Abbott Laboratories |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between NASAA-accredited premium tiers and uncertified commodity alternatives manifests in both pricing premiums and supply chain complexity across Asia Pacific organic baby food channels. FSSAI-mandated third-party verification in India and SAMR batch-level documentation in China force dual-track procurement strategies that inflate compliant product shelf prices while compressing margins for non-certified domestic competitors.
Pricing Analysis
Short lead-time premiums attach to cold-pressed puree pouches with HPP processing certification, while spot inventory of conventional thermal-sterilized formats trades at discounts. Three-tier pricing structure across premium synbiotic, standard organic, and economy conventional levels stratifies by certification depth and probiotic enrichment. Pricing pressure stems from Australia's drought-driven organic dairy input scarcity constraining formula production scheduling. Price-sensitive mass-market parents in India's emerging tier-two cities contrast with certification-insensitive buyers in Japan's gift-oriented glass jar segment.
Supply Chain Analysis
Organic dairy supply rests on Australia's drought-prone pasture systems and New Zealand's Fonterra-integrated processing clusters, with secondary concentration in China's Heilongjiang dairy belt. Raw material dependencies span certified organic milk powder, cold-pressed fruit purees, and synbiotic additive cultures. Single-source vulnerability concentrates in Tasmanian organic dairy processing capacity serving pan-Asian export demand. Distribution runs through China's Yangtze River Delta logistics clusters for HPP-processed pouches and India's fragmented cold-chain networks for probiotic formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific organic baby food operates as a supply-constrained market where Australia's 18-24 month certified milk powder availability lag props pricing power for backward-integrated incumbents with captive dairy supply.
For Market Incumbents: Acquire Tasmanian dairy processing capacity to anchor organic milk powder supply security against Australia's drought-prone pasture volatility. Secure mother-and-baby store network exclusivity in Shanghai and Mumbai to defend shelf access against cross-border e-commerce entrants exploiting Tmall Global registration bypasses. SAMR's tightened pesticide residue documentation requirements favor incumbents with established Shanghai testing infrastructure. For New Entrants and Emerging Players: FSSAI organic certification mandate in India opens a window for compliant European pure-play brands to capture shelf space vacated by eliminated uncertified domestic competitors. Vietnam's Ho Chi Minh City and Hanoi modern trade expansion presents underpenetrated demand for imported organic puree pouches. Direct-to-consumer subscription models in Seoul and Singapore bypass incumbent retail dependence while capturing consumption-pattern data for flavor optimization. For Investors and Strategic Acquirers: Re-rating potential sits with synbiotic technology specialists given SAMR's probiotic-prebiotic combination premium validation in China's mother-and-baby store networks. Long-term viability over a multi-year horizon favors assets with dual BFA-NASAA certification capability and HPP processing infrastructure. Monitor ASEAN organic standard harmonization draft protocols as inflection signal for redundant certification cost collapse across Thailand, Indonesia, and Philippines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Dairy | Tasmanian processing clusters anchor pan-Asian supply security against Australian drought cycles. |
| HPP Processing Line Deployment | Australian export-ready pouch production captures vitamin C preservation premium in China. |
| Mother-and-Baby Store Network Exclusivity | Trained consultation staff in Shanghai translate clinical guidance into shelf selection authority. |
| Cross-Border E-Commerce Platform Launch | Tmall Global fulfillment bypasses SAMR domestic registration delays for European organic entrants. |
| Synbiotic Formulation R&D Investment | Probiotic-prebiotic combinations command validated price premiums in China's tier-one cities. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Asia Pacific organic baby food analysis. Primary interviews with brand managers at multinational nutrition conglomerates, category buyers at China's hypermarket chains, FSSAI compliance officers, and mother-and-baby store network operators combined with bottom-up and top-down triangulation. Secondary validation drew from SAMR infant formula registration databases, Australian BFA and NASAA certification registries, India customs organic import records, and ASEAN standard harmonization draft protocols.
Data-stream reconciliation across volume shipments, certification issuance rates, and channel inventory turns informed the analytical framework across the analysis window. Segmentation dimensions modeled include product format, packaging convenience tier, distribution channel access, and regional regulatory cluster. CAGRs were derived from trend extrapolation of urban millennial household formation rates and organic certification penetration curves, with specific inputs from cold-chain infrastructure development indices and HPP processing capacity expansion announcements.
The model assumes a particular technology adoption path; alternative pathways for high-pressure processing scale-up would alter the outlook if thermal sterilization cost compression accelerates. Forecasts reflect documented assumptions about FSSAI enforcement consistency and SAMR registration timeline stability. A small set of named triggers warrants ongoing watch: ASEAN harmonization protocol ratification, Australian pasture recovery cycles, and cross-border e-commerce tariff policy shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Goat Milk Formula Market
Baby Food and Infant Formula
South America Baby Food Market
Baby Food and Infant Formula
South America Organic Baby Food Market
Baby Food and Infant Formula
Infant Formula Market
Baby Food and Infant Formula
Baby Food and Infant Formula Market
Baby Food and Infant Formula
GCC Baby Food and Infant Formula Market
Baby Food and Infant Formula
Infant Formula Milk Powder Market
Baby Food and Infant Formula
Infant Nutritional Premix Market
Baby Food and Infant Formula
Baby Food Products Market
Baby Food and Infant Formula
Hydrolyzed Formula Milk Powder Market
Baby Food and Infant Formula
United States Baby Food and Infant Formula Market
Baby Food and Infant Formula
Canned Baby Food Market
Baby Food and Infant Formula
Baby Formula Market
Baby Food and Infant Formula
Baby Fruit Puree Market
Baby Food and Infant Formula
Pet Milk Replacement Products Market
Baby Food and Infant Formula
North America Baby Food and Infant Formula Market