
 Asia-Pacific Baby Food Market | 2026-2036
Asia-Pacific Baby Food Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Baby Food Market Outlook
Chinese contract manufacturers is expanding wet-mix processing capacity to serve pan-Asian private-label demand. Nestlé SA leverages its dairy ingredient networks across Yunnan and Hokkaido to anchor supply security for infant formula lines. Danone SA competes through specialized probiotic fortification protocols that differentiate its toddler cereal range. Morinaga Milk Industry Co Ltd dominates Japan's pharmacy channel with extended shelf-stable liquid formulations.
Asia-Pacific baby food comprises processed, nutritionally formulated products for infants and toddlers, typically manufactured through retort sterilization, spray-drying, or cold-press puree techniques to achieve microbiological safety while preserving vitamin stability. These products serve as transitional or supplementary nutrition during early childhood development when breast milk or standard dairy proves insufficient. Organic formulations lead margin pools as certification costs create pricing power for certified suppliers, while fortified variants sustain volume growth across India's government nutrition programs. Online retail channels represent the fastest-expanding distribution vector, though supermarkets still occupy the majority transaction value in Southeast Asian metropolitan zones.
China's National Medical Products Administration enforces GB 10765 infant formula standards that mandate compositional testing for imported products, while India's FSSAI operates parallel licensing for domestically manufactured cereals and purees. Japan's Ministry of Health, Labour and Welfare maintains positive-list systems for food additives in infant products, effectively filtering non-compliant foreign entrants. Australia's Food Standards Code, administered by FSANZ, imposes additional allergen disclosure thresholds that shape export labeling investments. Stakeholders must monitor divergent shelf-life claim regulations across these jurisdictions when optimizing regional SKU portfolios.
Market Dynamics
Urban millennial parents in Shanghai, Mumbai, and Jakarta are compressing purchase cycles toward premium organic and fortified formulations, forcing manufacturers to accelerate clean-label certification timelines and wet-mix processing investments across contract manufacturing networks.
Growth Catalysts
- Organic certification protocols:India's FSSAI tightened labeling requirements for infant cereals, creating pricing power for certified domestic suppliers who meet compositional transparency mandates.
- Pharmacy channel expansion:Japan's extended shelf-stable liquid formulations dominate pharmacy retail, anchoring margin pools through specialized distribution infrastructure in metropolitan zones.
- Fortification mandates:Government nutrition programs across India sustain volume demand for micronutrient-enriched variants, locking in procurement contracts with domestic cereal manufacturers.
Market Restraints
- Import testing regimes:China's NMPA enforces GB 10765 infant formula standards with mandatory compositional testing, creating regulatory friction that delays foreign product entry and extends compliance timelines.
- Additive positive-list systems:Japan's Ministry of Health, Labour and Welfare maintains restrictive food additive approvals, filtering non-compliant foreign entrants from pharmacy and convenience retail channels.
- Dairy ingredient concentration:Supply security depends on concentrated dairy ingredient networks across Yunnan and Hokkaido, exposing formula lines to geographic supply disruption risks.
Strategic Opportunities
- Online retail vector expansion:E-commerce channels represent the fastest-growing distribution mechanism, enabling direct-to-parent engagement in Southeast Asian metropolitan zones where supermarket saturation limits shelf access.
- Probiotic fortification convergence:Specialized probiotic protocols combined with cold-press puree techniques enable differentiated toddler cereal positioning against retort-sterilized commodity alternatives.
- Australian allergen disclosure leadership:FSANZ-administered Food Standards Code thresholds create export labeling investment opportunities for manufacturers targeting premium positioning through transparent allergen management.
Industry Challenges
- Retort sterilization capex intensity:Microbiological safety requirements demand continuous capital deployment into high-pressure processing equipment and spray-drying infrastructure, compressing free cash flow for mid-scale entrants.
- Divergent shelf-life claim harmonization:Jurisdictional variation in permissible shelf-life assertions across China, India, Japan, and Australia forces SKU proliferation and inventory fragmentation.
- Wet-mix processing skill scarcity:Technical expertise in emulsion stability and vitamin preservation during liquid formulation remains concentrated among established contract manufacturers, constraining new facility commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Baby Food Market |
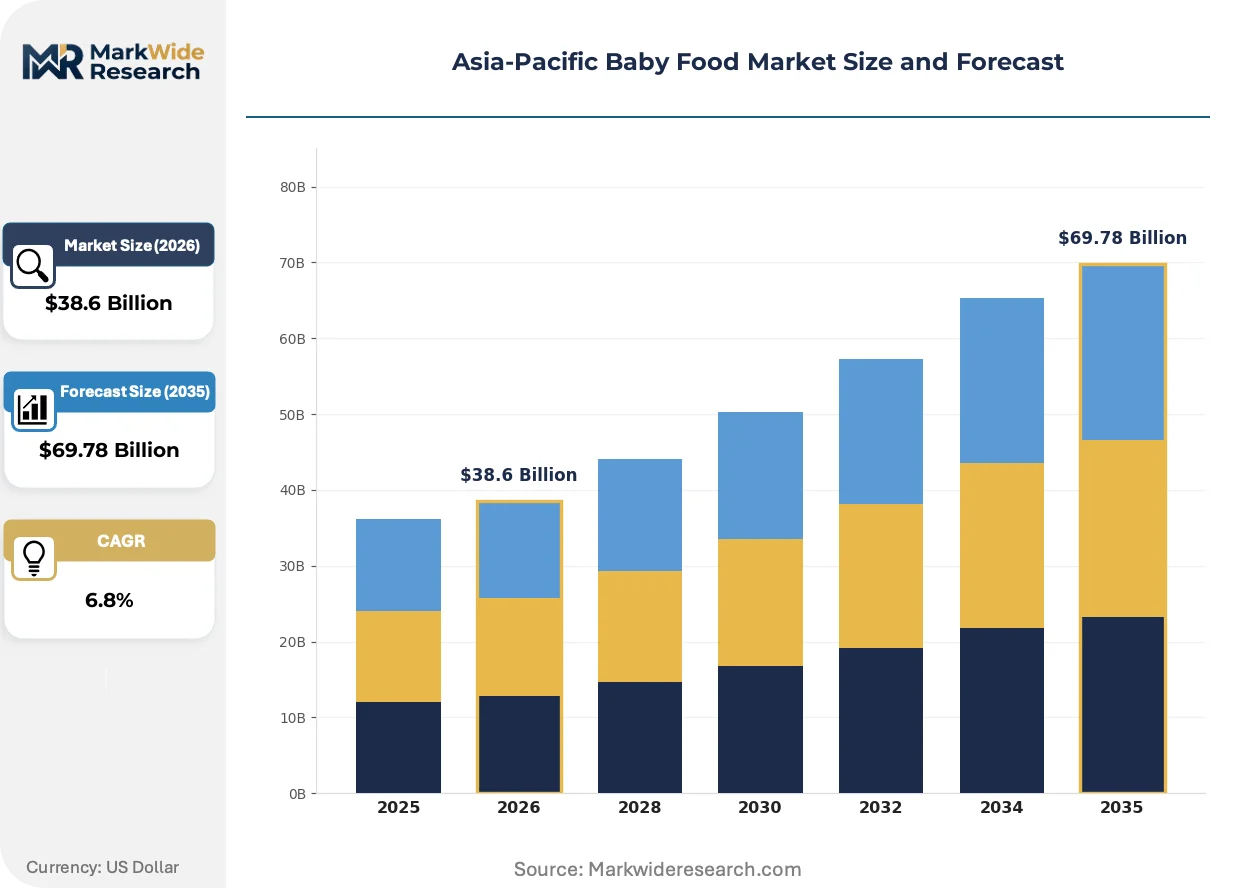
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purees, Cereals, Snacks, Liquids Formulation: Organic, Natural, Fortified, Conventional Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Pharmacies Age Group: Infants, Toddlers, Preschoolers, Others |
| Companies Covered | Reckitt Benckiser, Arla Foods amba, Nestlé SA, Morinaga Milk Industry Co Ltd, Perrigo Company plc, Abbott Laboratories, The Kraft Heinz Company, Bellamy's Organic, Danone SA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Baby Food Market Strategic Shifts
Cold-press puree techniques and probiotic fortification protocols are compressing traditional retort sterilization dominance, while regulatory divergence across NMPA, FSSAI, and FSANZ jurisdictions forces adaptive labeling investments.
HPP-assisted cold-press systems preserve heat-sensitive vitamins and native enzyme activity in fruit and vegetable purees. Premium organic brands in Shanghai and Sydney are adopting these systems at accelerated pace to meet compressed clean-label timelines. This technology is absorbing market share from conventional retort processing by enabling shorter ingredient lists without sacrificing shelf stability.
China's GB 10765 infant formula standards now mandate expanded compositional testing for imported products, including fatty acid profile verification and contaminant screening. Industrial consequence includes extended customs clearance periods and elevated third-party laboratory costs for foreign manufacturers. European and Oceanian exporters are responding by pre-certifying production batches through NMPA-recognized laboratories before shipment.
Parent purchasing behavior is fragmenting across channel types, with subscription-based direct delivery displacing traditional supermarket stock-up patterns in tier-one Chinese cities. Urban millennial buyers in Beijing and Guangzhou now expect personalized nutrition recommendations and automatic replenishment for specialized hypoallergenic variants. This behavioral shift is most visible among dual-income households with children under 24 months, where time compression outweighs price sensitivity.
Asia-Pacific Baby Food Market Segmentation
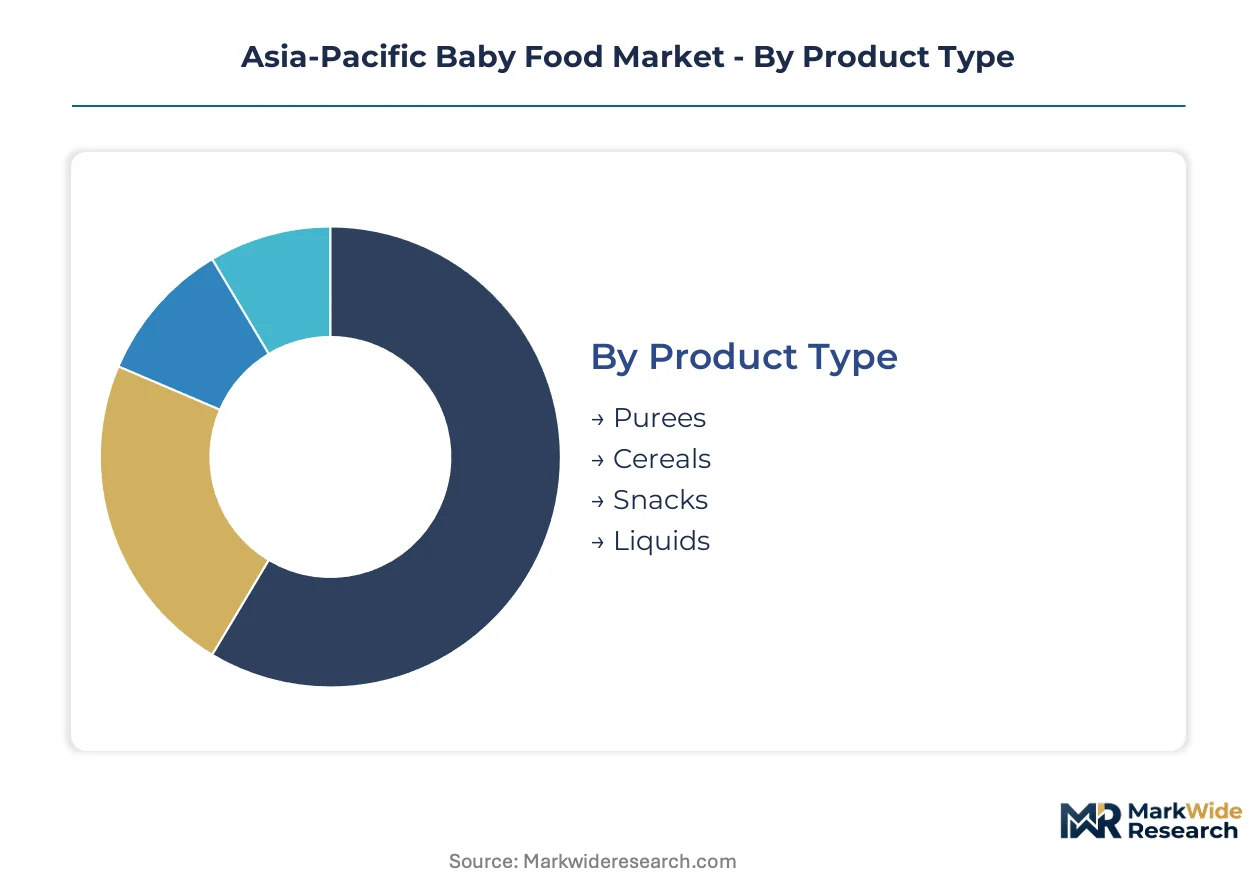
Segmentation in the Asia-Pacific baby food market reveals how regulatory divergence and parental purchasing behavior fragment demand across distinct technical and channel categories. Manufacturers must align SKU portfolios with specific formulation certifications, age-graded nutritional specifications, and jurisdiction-dependent distribution infrastructure to capture margin pools effectively.
Product Type:
Integration depth varies sharply across product types, with some formats functioning as standalone meal replacements while others embed into broader feeding routines as supplementary nutrition.
- Purees:Cold-press and retort-sterilized fruit and vegetable blends deliver micronutrient density for early-stage weaning. Demand clusters in Shanghai and Sydney where millennial parents prioritize clean-label ingredient transparency and shorter supply chains for perishable inputs.
- Cereals:Spray-dried grain formulations fortified with iron and B-vitamins serve as transitional staples from six months onward. India's government nutrition programs sustain procurement volume through FSSAI-compliant domestic manufacturers, though import dependency for specialized premixes creates supply friction.
- Snacks:Puffed rice and freeze-dried fruit pieces target toddler self-feeding development stages with portable formats.
- Liquids:Extended shelf-stable ready-to-feed formulations dominate Japan's pharmacy channel through specialized aseptic filling infrastructure.
Volume placements concentrate in Cereals; the faster expansion belongs to Purees.
Formulation:
Cost tier stratification separates premium-certified offerings from commodity-grade alternatives, with certification investments creating defendable pricing power at the upper end.
- Organic:Third-party certified products command sustained shelf space in China's tier-one cities where parental willingness-to-pay absorbs 40-60% price premiums. Certification costs and audit timelines filter mid-scale competitors from this segment.
- Fortified:Micronutrient-enriched variants align with India's national nutrition supplementation objectives, locking in institutional procurement contracts with domestic cereal processors. Iron, zinc, and vitamin A premix integration differentiates these formulations from baseline alternatives.
- Natural:Clean-label positioning without full organic certification occupies a mid-tier price position in Southeast Asian supermarkets.
- Conventional:Standard formulations without certification claims serve price-sensitive segments through high-volume retail channels.
Margin capture concentrates in Organic; the steepest volume trajectory belongs to Fortified.
Distribution Channel:
Channel selection determines customer touchpoint economics, with each vector demanding distinct packaging specifications, replenishment cadences, and regulatory compliance investments.
- Supermarkets:Traditional hypermarket and grocery formats retain majority transaction value across Southeast Asian metropolitan zones, particularly Jakarta and Bangkok. Shelf-space negotiations and promotional slotting fees compress net margins for emerging brands without established velocity records.
- Online Retail:E-commerce platforms enable direct-to-parent engagement with subscription-based replenishment models gaining traction in Beijing and Guangzhou. This channel absorbs the fastest-growing transaction volume as urban dual-income households prioritize convenience over in-store browsing.
- Convenience Stores:Small-format urban retail supports emergency replenishment and travel-sized packaging demand.
- Pharmacies:Japan's drugstore channel anchors specialized liquid formula distribution through pharmacist consultation requirements and insurance-adjacent purchasing patterns.
Transaction value concentrates in Supermarkets; the channel gaining share fastest is Online Retail.
Age Group:
Developmental stage segmentation dictates nutritional specification requirements, with each cohort presenting distinct texture, allergen, and micronutrient formulation needs.
- Infants:Products targeting 0-12 months face the most stringent compositional standards, including China's GB 10765 infant formula mandates and Japan's positive-list additive restrictions. NMPA pre-shipment testing requirements extend lead times for imported offerings.
- Toddlers:The 1-3 year cohort drives probiotic fortification and finger-food format innovation as self-feeding skills develop. Danone SA and domestic Chinese brands compete through specialized gut-health positioning in this segment.
- Preschoolers:Nutritionally positioned snacks for 3-5 year olds bridge into broader children's food categories with reduced regulatory scrutiny.
- Others:Specialty formulations for premature infants or metabolic conditions occupy niche prescription-access channels.
Regulatory intensity concentrates in Infants; the segment expanding most quickly is Toddlers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yunnan and Hokkaido dairy networks anchor ingredient security across the region, while wet-mix processing capacity concentrates in Chinese contract manufacturing zones serving pan-Asian private-label demand.
China
Urban millennial parents in Shanghai and Beijing compress purchase cycles toward premium organic purees. The National Medical Products Administration enforces GB 10765 infant formula standards with mandatory compositional testing for imports. Tier-one cities command sustained shelf space for certified organic formulations absorbing 40-60% price premiums.
Japan
Pharmacy channel dominance anchors specialized liquid formula distribution through pharmacist consultation requirements. The Ministry of Health, Labour and Welfare maintains positive-list systems for food additives in infant products. Morinaga Milk Industry Co Ltd leverages extended shelf-stable formulations across metropolitan drugstore networks.
India
Government nutrition programs sustain volume demand for micronutrient-enriched cereals through institutional procurement. The Food Safety and Standards Authority tightened labeling requirements for infant cereals, creating pricing power for certified domestic suppliers. Domestic manufacturers in Maharashtra and Gujarat lock in premix supply contracts for iron-fortified variants.
Australia
Premium organic brands in Sydney accelerate cold-press puree adoption to meet compressed clean-label timelines. Food Standards Australia New Zealand administers allergen disclosure thresholds shaping export labeling investments. Queensland and New South Wales processing facilities specialize in transparent allergen management for premium positioning.
South Korea
Dual-income households in Seoul prioritize subscription-based direct delivery for specialized hypoallergenic variants. The Ministry of Food and Drug Safety operates parallel infant formula registration systems. Metropolitan retail clusters absorb the fastest e-commerce penetration as time compression outweighs price sensitivity.
Asia-Pacific Baby Food Market Competitive Environment
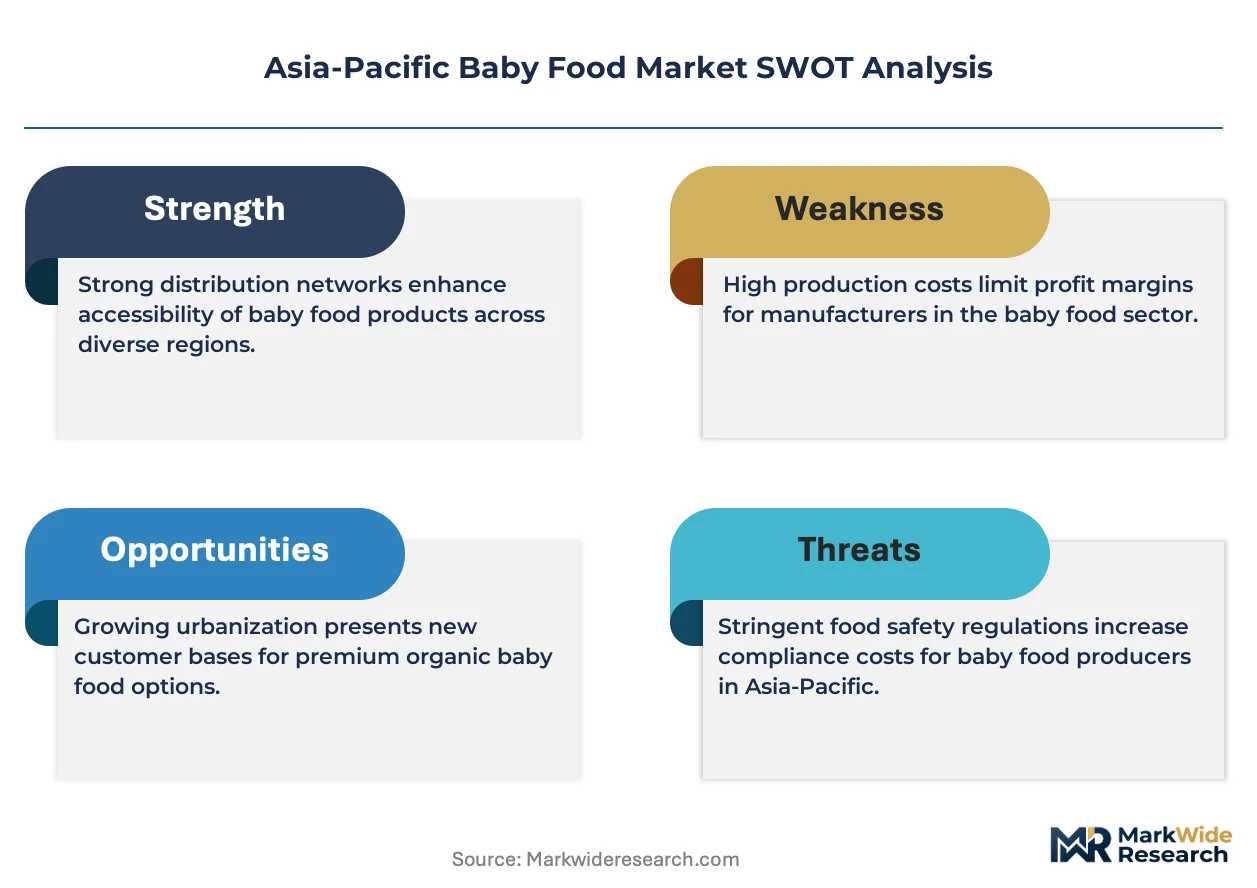
Established producers occupy the standard tier; emerging entrants pursue probiotic fortification and cold-press differentiation to compress traditional retort sterilization dominance. The market structures around three tiers: multinational dairy conglomerates with captive ingredient networks, specialized organic certifiers with audit-defended pricing power, and contract manufacturers scaling wet-mix capacity for private-label penetration. Dominant competitive moves include backward integration into dairy ingredient sourcing and adaptive labeling investments across NMPA, FSSAI, and FSANZ jurisdictions.
Among diversified nutrition conglomerates, Nestlé SA and Danone SA exemplify archetypes leveraging dairy ingredient networks and specialized fortification protocols respectively. Morinaga Milk Industry Co Ltd occupies a position within the pharmacy-channel specialist tier. These entities represent competitive positioning through supply security, probiotic differentiation, and distribution infrastructure depth rather than commodity scale alone.
| Leading Market Players |
|---|
| Reckitt Benckiser |
| Arla Foods amba |
| Nestlé SA |
| Morinaga Milk Industry Co Ltd |
| Perrigo Company plc |
| Abbott Laboratories |
| The Kraft Heinz Company |
| Bellamy's Organic |
| Danone SA |
| Others |
Value Chain & Pricing Dynamics
Urban millennial parents in Shanghai and Mumbai anchor demand concentration, compressing purchase cycles toward subscription-based replenishment models that bundle nutritional consultation with automatic delivery. This buyer archetype's preference for convenience over price comparison sustains premium pricing power for certified organic formulations.
Pricing Analysis
Service bundling separates consultation-inclusive subscription tiers from transactional supermarket purchases, with NMPA pre-certification costs embedded in import pricing. Three-tier pricing structure across premium organic, fortified standard, and economy conventional levels reflects certification investment recovery timelines. Cost compression in economy tiers intensifies because domestic contract manufacturers scale wet-mix capacity for private-label penetration. Government procurement programs in India exhibit highest price sensitivity; pharmacy-channel liquid formulations in Japan show lowest.
Supply Chain Analysis
Dairy ingredient supply rests on concentrated processing networks across Yunnan, Hokkaido, and Victoria. Spray-dried premixes, cold-press puree inputs, and aseptic filling equipment feed from distinct supplier bases. Single-source vulnerability in Hokkaido whey protein concentrate exposes formula lines to geographic disruption. Distribution runs through supermarket-hypermarket networks in Southeast Asia, with e-commerce platforms capturing fastest channel expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where India's FSSAI labeling mandates and China's GB 10765 testing requirements create barrier-to-entry moats for certified domestic suppliers and pre-cleared importers.
For Market Incumbents: To counter wet-mix processing skill scarcity among contract manufacturers, Nestlé SA and Danone SA should deepen backward integration into Yunnan dairy networks while accelerating NMPA-recognized laboratory pre-certification to compress customs clearance timelines. For New Entrants and Emerging Players: The 40-60% price premium gap between certified organic and conventional economy tiers creates white-space opportunity in mid-tier natural positioning for Southeast Asian supermarket channels, with direct-to-parent subscription models offering the most penetrable go-to-market angle in Beijing and Guangzhou dual-income households. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized probiotic fortification specialists with NMPA pre-clearance infrastructure in Shanghai processing zones, with long-term viability hinging on sustained pharmacy-channel access in Japan and institutional procurement lock-in across Indian government nutrition programs. Watch FSSAI audit timeline compression as inflection signal for domestic certification moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Press Processing Capacity Expansion | HPP-assisted systems preserve vitamin stability in Shanghai and Sydney premium puree lines. |
| Backward Integration into Dairy Networks | Yunnan and Hokkaido captive supply secures formula ingredient continuity against disruption. |
| NMPA Pre-Certification Laboratory Investment | Third-party testing infrastructure compresses import clearance timelines for European exporters. |
| Pharmacy Channel Distribution Partnership | Morinaga-style pharmacist consultation requirements anchor margin pools in Tokyo drugstore networks. |
| Subscription-Based Direct Delivery Launch | Automatic replenishment models capture Beijing dual-income households with time-compressed purchase behavior. |
Study Parameters
Multi-period observation of FSSAI audit timelines, NMPA clearance durations, and pharmacy-channel shelf velocity anchored the trend analysis, supplemented by interviews with infant cereal procurement officers at Indian government nutrition programs, brand managers at Australian organic certifiers, wet-mix processing engineers at Chinese contract manufacturers, and category buyers at Southeast Asian supermarket chains. Secondary validation drew from FSSAI labeling circulars, NMPA GB 10765 compliance bulletins, FSANZ Food Standards Code amendments, and Nielsen retail audit data across metropolitan zones. Bottom-up volume modeling and top-down value reconciliation ensured triangulation integrity.
Segment-weighting applied product type, formulation certification tier, distribution channel, and age-graded nutritional specification as core dimensions across the projection horizon. CAGRs derived from regression analysis of historical penetration rates and regulatory enforcement intensity. Forecast inputs incorporated wet-mix processing capacity expansion schedules and pharmacy-channel infrastructure investment pipelines.
Inputs from FSSAI compliance databases and NMPA import clearance records were available through the study window; gaps in real-time subscription-model pricing data introduce uncertainty bands around e-commerce channel value estimates. Forecasts reflect documented assumptions on regulatory enforcement continuity and dairy network stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Growing Up Milk Market
Baby Food and Infant Formula
India Baby Food Market
Baby Food and Infant Formula
Hydrolyzed Formula Milk Powder Market
Baby Food and Infant Formula
Growing Up Formula Market
Baby Food and Infant Formula
Russia Pet Food Market
Baby Food and Infant Formula
Japan Baby Food and Infant Formula Market
Baby Food and Infant Formula
Standard Milk Formula Market
Baby Food and Infant Formula
Europe Organic Baby Food Market
Baby Food and Infant Formula
Europe Baby Food Market
Baby Food and Infant Formula
Middle East and Africa Baby Food Market
Baby Food and Infant Formula
Middle East and Africa Organic Baby Food Market
Baby Food and Infant Formula
Canned Pet Food Market
Baby Food and Infant Formula
Baby Juice Market
Baby Food and Infant Formula
North America Organic Baby Food Market
Baby Food and Infant Formula
Organic Baby Food Market
Baby Food and Infant Formula
Pet Milk Replacement Products Market