
 Infant Formula Milk Powder Market | 2026-2036
Infant Formula Milk Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Infant Formula Milk Powder Market Outlook
New Zealand dairy cooperative processing capacity is pivoting toward high-value nutritional powders. Nestlé S.A. leverages its pharmaceutical-grade manufacturing infrastructure across European markets. Danone S.A. specializes in hypoallergenic and organic formulation lines. Abbott Laboratories anchors its competitive position through hospital and clinical channel relationships.
Infant formula milk powder comprises dried dairy or plant-based blends reconstituted with water, typically containing proteins, lipids, carbohydrates, vitamins, and minerals balanced to mimic human milk composition for infants aged zero to twelve months. Manufacturers employ spray-drying or roller-drying processes to achieve moisture levels below five percent, ensuring microbiological stability and extended shelf life. Standard powder occupies the largest volume position, though organic powder commands superior margin pools due to certified ingredient sourcing and limited supplier base. Specialty powder, including lactose-free and anti-reflux variants, attracts the fastest volume growth as diagnostic rates for infant digestive conditions rise. Metal cans dominate packaging for premium lines, while pouches gain traction in online retail channels.
FDA enforces infant formula nutrient specifications and Good Manufacturing Practice requirements under the Federal Food, Drug, and Cosmetic Act, while EFSA establishes compositional standards and safety assessments for European market access. China's NMPA and national food safety standards impose mandatory registration and formula quantity limits, directly constraining brand entry and portfolio breadth. Stakeholders must monitor evolving regulatory divergence between Codex-aligned and jurisdiction-specific nutrient ceilings as they evaluate regional manufacturing investments and label adaptation costs.
Market Dynamics
China's NMPA formula registration caps are compressing brand portfolios while redirecting R&D investment toward specialty nutritional claims and clinical validation studies that satisfy hospital procurement standards.
Growth Catalysts
- Urban dual-income households:Working parents in Chinese metropolitan clusters prioritize convenience-oriented feeding solutions that reduce preparation time and enable schedule flexibility.
- EFSA novel ingredient pathways:Accelerated safety assessments for human milk oligosaccharides and fermented dairy proteins enable faster European product differentiation.
- Diagnostic expansion:Pediatric gastrointestinal screening protocols in South Korea and Australia identify lactose intolerance and cow's milk protein allergy cases earlier, expanding addressable patient populations for specialty formulations.
Market Restraints
- Organic dairy input scarcity:Certified organic milk powder supply concentrates in New Zealand and select European cooperatives, creating procurement bottlenecks during seasonal production swings.
- FDA facility inspection backlogs:Extended pre-approval timelines for new manufacturing sites delay US market entry by 18-24 months for international applicants.
- Plant-based protein limitations:Amino acid profiles in soy and pea isolates fail to match whey protein digestibility scores, constraining formulation options for vegan-positioned products.
Strategic Opportunities
- German pharmacy channel expansion:Direct-to-pharmacist distribution bypasses grocery retail margin compression while accessing reimbursed prescription formula segments.
- Precision fermentation convergence:Recombinant lactoferrin and casein production via microbial hosts promises supply security independent of dairy herd fluctuations.
- Subscription direct-to-consumer models:Automated replenishment platforms capture recurring revenue and consumption data that inform personalized nutrition recommendations.
Industry Challenges
- Clinical trial recruitment bottlenecks:Infant feeding studies face ethical review complexity and parent consent barriers that extend development timelines beyond standard pediatric nutrition protocols.
- Legacy ERP integration friction:Track-and-trace serialization requirements for China and EU markets strain manufacturing execution systems not architected for unit-level genealogy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infant Formula Milk Powder Market |
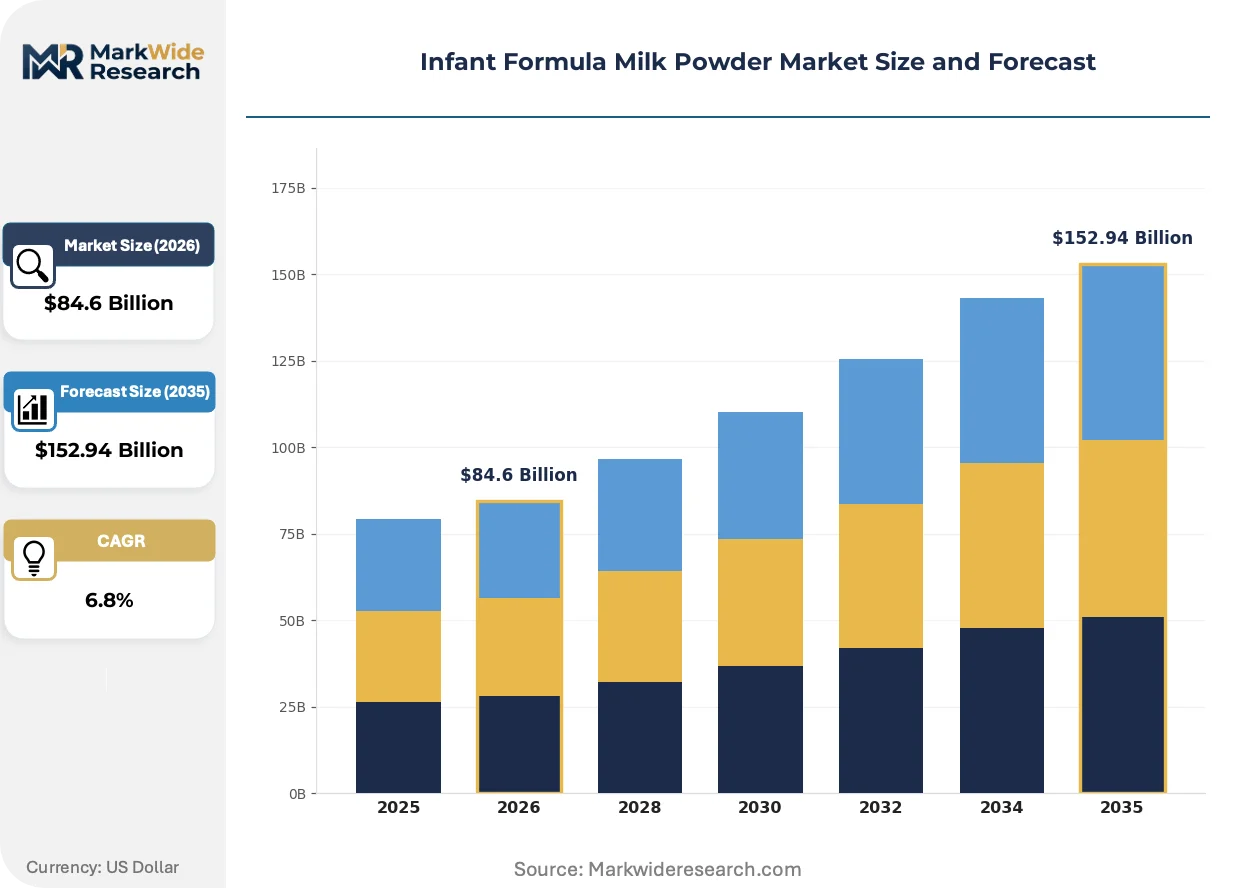
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $152.94 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Powder, Organic Powder, Lactose-Free Powder, Specialty Powder End User: Parents, Caregivers, Hospitals, Childcare Facilities Packaging Type: Metal Cans, Plastic Containers, Pouches, Tetra Packs Distribution Channel: Supermarkets, Online Retailers, Pharmacies, Convenience Stores |
| Companies Covered | FrieslandCampina, Arla Foods amba, Nestlé S.A., Ausnutria B.V., Fonterra Co-operative Group Limited, Abbott Laboratories, Reckitt Benckiser Group plc, The a2 Milk Company Limited, Danone S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infant Formula Milk Powder Market Strategic Shifts
Spray-drying optimization and cold-chain lipid preservation are redefining nutritional integrity benchmarks while regulatory divergence between Codex and national standards forces parallel formulation development tracks.
Aseptic liquid concentrate technology is overtaking traditional powder formats in premium segments. Urban Chinese parents with refrigeration access adopt ready-to-feed solutions that eliminate reconstitution error risks. This shift is compressing powder SKU proliferation in tier-one cities while concentrating manufacturing investment in aseptic filling capacity.
REACH microplastic restrictions and EU Single-Use Plastics Directive amendments are forcing packaging redesign across European markets. Metal can suppliers invest in recyclable polymer linings that maintain oxygen barrier performance. Premium organic lines in Germany and France absorb compliance costs through price repositioning rather than format abandonment.
Hospital discharge protocols increasingly specify branded specialty formulas for infants with diagnosed feeding intolerances. Pediatric gastroenterology departments in Australia and South Korea build preferred supplier relationships that lock out retail-channel competitors. This channel consolidation rewards manufacturers with dedicated medical affairs teams and clinical evidence libraries.
Infant Formula Milk Powder Market Segmentation
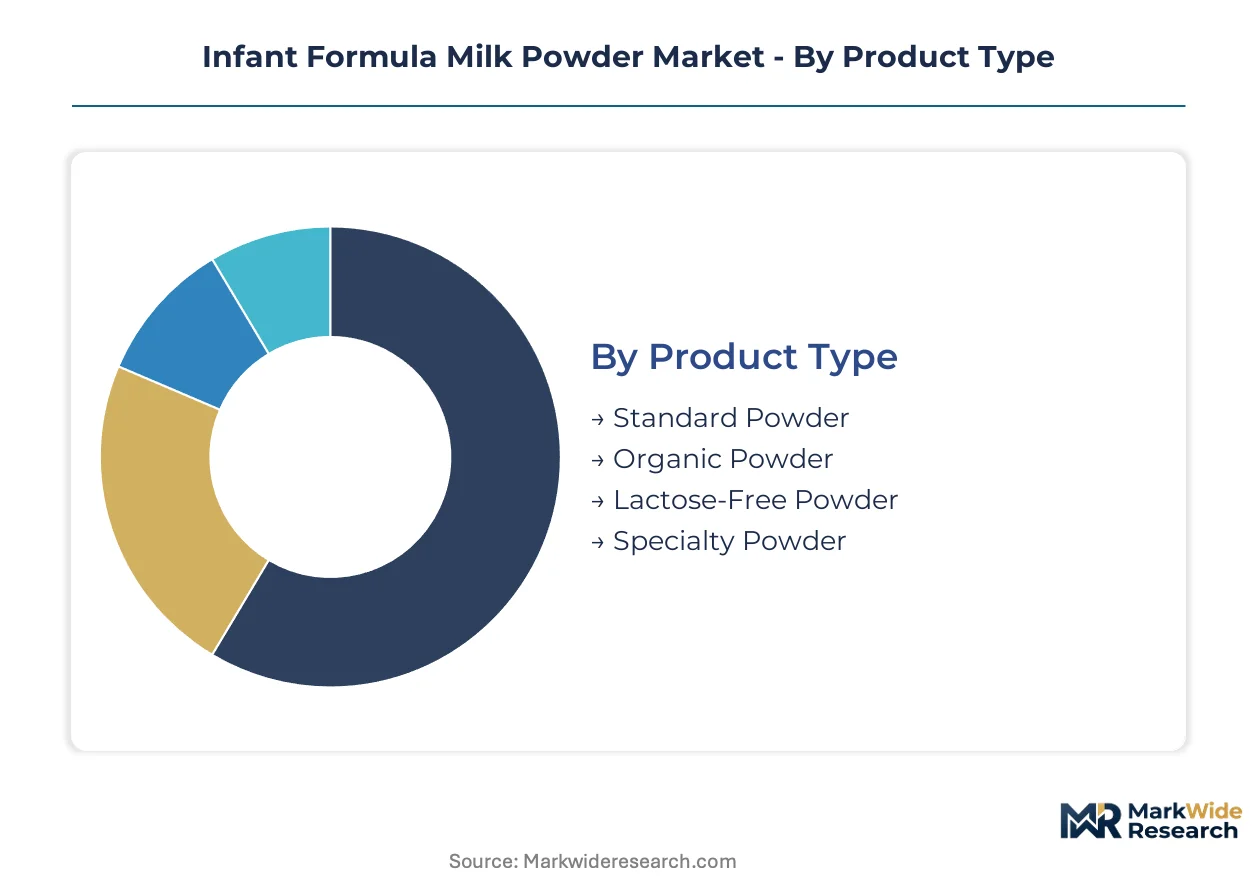
Product differentiation in infant formula milk powder hinges on nutritional positioning, clinical validation, and convenience-oriented packaging. Segmentation reveals how manufacturers allocate R&D investment across standard volume plays and premium specialty lines with superior margin capture.
Product Type:
Parents upgrade from standard to premium formulations as diagnostic awareness spreads and disposable incomes climb, creating replacement cycles that favor certified organic and clinical-grade specialty variants.
- Standard Powder:Whey-dominant protein blends with standardized vitamin-mineral fortification deliver baseline nutrition at accessible price points. Volume concentrates in Chinese provincial cities and Southeast Asian markets where cost sensitivity dominates purchase decisions and private-label competition intensifies.
- Organic Powder:Certified ingredient sourcing from New Zealand and select European cooperatives commands 40-60% price premiums over conventional equivalents. Demand clusters in German metropolitan households and Australian urban parents prioritizing residue-free feeding protocols.
- Lactose-Free Powder:Enzymatically hydrolyzed lactose formulations address diagnosed intolerance in pediatric populations.
- Specialty Powder:Anti-reflux, hypoallergenic, and metabolic disorder-specific variants require clinical validation.
Volume placements concentrate in Standard Powder; the faster expansion belongs to Specialty Powder.
End User:
Cost tier stratification separates at-home consumers from institutional procurement channels with divergent price elasticity and compliance requirements.
- Parents:Primary decision-makers seeking convenience and nutritional assurance drive premium segment adoption in dual-income Chinese households.
- Caregivers:Grandparents and professional nannies prioritize preparation simplicity and extended shelf stability in multi-generational living arrangements.
- Hospitals:Neonatal intensive care units and pediatric wards demand pharmaceutical-grade manufacturing with batch-level traceability. South Korean and Australian hospital networks increasingly specify branded specialty formulas through exclusive supply agreements.
- Childcare Facilities:Licensed centers face regulatory documentation burdens for formula storage and preparation that favor pre-measured single-serve formats.
Institutional channels capture lower unit volumes but yield superior margins through contracted pricing and reduced marketing expenditure.
Packaging Type:
Supply concentration in metal can manufacturing shapes format availability across premium and mass-market tiers.
- Metal Cans:Oxygen-barrier steel and aluminum containers preserve lipid integrity across 24-month shelf lives. European regulatory pressure on recyclability drives lining material innovation without format abandonment.
- Plastic Containers:Polypropylene wide-mouth jars enable scoop access and resealing for high-frequency users.
- Pouches:Flexible film formats with spout dispensing gain traction in Chinese e-commerce subscription models. Lightweight shipping economics and reduced breakage rates favor last-mile delivery optimization.
- Tetra Packs:Aseptic carton technology supports ready-to-feed liquid concentrate variants displacing powder in tier-one Chinese cities.
Format selection tracks refrigeration access and purchase channel preferences rather than nutritional differentiation.
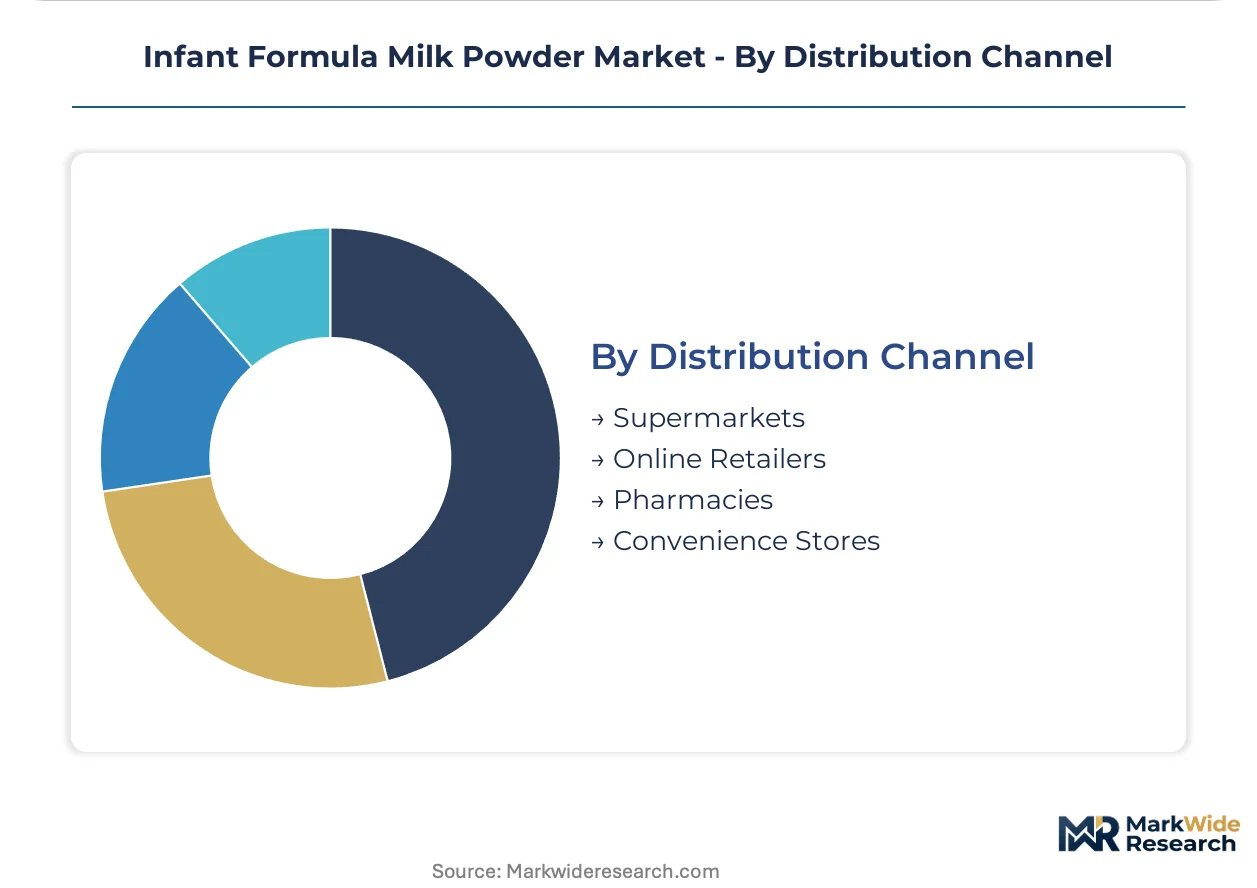
Distribution Channel:
Channel fragmentation creates parallel go-to-market investments with distinct margin structures and customer acquisition costs.
- Supermarkets:Mass-market volume placement depends on slotting fees and promotional calendar coordination. German and French hypermarkets retain significance for standard powder replenishment despite online share erosion.
- Online Retailers:Cross-border platforms enable Chinese consumers to access international formulations bypassing domestic registration caps. Subscription algorithms drive recurring revenue capture and consumption data accumulation.
- Pharmacies:German and Swiss pharmacy channels access reimbursed prescription formula segments with professional endorsement value.
- Convenience Stores:Emergency replenishment and travel-size formats address immediate-need scenarios with limited SKU depth.
Direct-to-consumer platforms are climbing the fastest; traditional retail retains defensive volume positions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand's dairy cooperative network supplies the foundational milk powder inputs that feed formulation plants across Asia-Pacific and European manufacturing corridors. Processing capacity concentrates in Waikato and Canterbury regions where spray-drying infrastructure scales to pharmaceutical-grade specifications. Seasonal production cycles in these southern hemisphere clusters create procurement timing pressures for northern hemisphere brands.
China
Urban dual-income households in Shanghai, Beijing, and Guangzhou drive premium organic adoption while provincial cities sustain standard powder volumes. NMPA registration caps limit brand portfolios to three formulas per manufacturer, compressing market entry and forcing R&D concentration on specialty nutritional claims. Yangtze River Delta manufacturing clusters absorb the bulk of foreign direct investment in aseptic filling capacity.
Germany
Pharmacy channel distribution bypasses grocery retail margin compression while accessing reimbursed prescription formula segments. EFSA compositional standards and novel ingredient pathways accelerate human milk oligosaccharide integration into premium lines. Bavaria and North Rhine-Westphalia host pharmaceutical-grade manufacturing infrastructure serving both domestic and export markets.
United States
FDA facility inspection backlogs delay new manufacturing site approvals by 18-24 months, constraining international applicant entry. Hospital and clinical channel relationships anchor competitive positioning for specialty formulations. Midwest dairy belt proximity to spray-drying plants reduces inbound logistics costs for standard powder production.
Australia
Pediatric gastrointestinal screening protocols identify lactose intolerance and cow's milk protein allergy cases earlier, expanding addressable patient populations for specialty formulations. TGA regulatory alignment with Codex standards enables streamlined export certification to Asian markets. Melbourne and Sydney medical affairs teams build preferred supplier relationships with hospital networks.
South Korea
MFDS enforcement of strict nutrient labeling and manufacturing practice requirements shapes product development priorities for domestic and import brands. Seoul metropolitan area demand concentrates in premium segments where diagnostic awareness spreads fastest. Busan-Ulsan logistics corridors handle bulk powder imports for domestic repackaging and formulation.
Infant Formula Milk Powder Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue precision fermentation and recombinant protein pathways that bypass dairy herd dependency. The market structure consolidates around pharmaceutical-grade manufacturers with hospital channel access and organic-certified cooperatives with limited supplier bases. Three archetypes dominate: dairy cooperative processors with backward integration into milk powder supply, multinational nutrition conglomerates with medical affairs capabilities, and precision biotechnology startups targeting recombinant lactoferrin production. Competitive moves concentrate on aseptic liquid concentrate capacity expansion and subscription direct-to-consumer platform acquisition.
Within the dairy cooperative tier, FrieslandCampina and Fonterra Co-operative Group Limited exemplify processing capacity pivot toward high-value nutritional powders. Nestlé S.A. and Danone S.A. occupy positions that leverage pharmaceutical-grade manufacturing infrastructure and hypoallergenic formulation specialization respectively. These named entities represent the spectrum from upstream milk powder supply control to downstream clinical channel penetration, illustrating how competitive positioning depends on regulatory compliance depth and manufacturing execution system sophistication.
| Leading Market Players |
|---|
| FrieslandCampina |
| Arla Foods amba |
| Nestlé S.A. |
| Ausnutria B.V. |
| Fonterra Co-operative Group Limited |
| Abbott Laboratories |
| Reckitt Benckiser Group plc |
| The a2 Milk Company Limited |
| Danone S.A. |
| Others |
Value Chain & Pricing Dynamics
Organic dairy input scarcity in New Zealand and select European cooperatives cascades through formulation tiers, concentrating procurement leverage among certified suppliers and compressing margin pools for brands dependent on spot-market milk powder sourcing.
Pricing Analysis
Warranty-backed clinical validation separates premium from mass-market positioning, with pharmaceutical-grade manufacturing certifications and hospital channel access bundled into specialty formula price points. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence and volume scale economies. Price erosion runs through standard powder segments as private-label competition intensifies in Chinese provincial cities. Parents in dual-income urban households exhibit lowest price sensitivity, while grandparents and professional caregivers in multi-generational arrangements prioritize preparation simplicity over brand premium.
Supply Chain Analysis
Skilled technician availability in Bavaria and North Rhine-Westphalia pharmaceutical manufacturing corridors underpins European aseptic filling capacity, while seasonal workforce fluctuations in Waikato and Canterbury spray-drying regions create production timing pressures. Supply concentrates in New Zealand dairy cooperatives, European certified organic producers, and Midwest US dairy belt processors. Raw material dependencies span whey protein concentrates, lactose hydrolysates, and human milk oligosaccharide precursors. Single-source vulnerability in certified organic milk powder supply creates procurement bottlenecks during southern hemisphere production swings. Distribution runs through hospital procurement networks, pharmacy channels, and cross-border e-commerce platforms with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over recombinant protein production and pharmaceutical-grade manufacturing infrastructure determines margin capture and channel access.
For Market Incumbents: To counter precision fermentation startups bypassing dairy herd dependency, Nestlé S.A. and Danone S.A. must deepen backward integration into microbial lactoferrin production and expand aseptic liquid concentrate capacity in Yangtze River Delta manufacturing clusters. Hospital channel exclusivity agreements in Australia and South Korea require dedicated medical affairs team expansion to defend against retail-channel competitors.
For New Entrants and Emerging Players: Launch via subscription direct-to-consumer platforms targeting tier-one Chinese cities where ready-to-feed format adoption compresses powder SKU proliferation. White-space opportunities concentrate in precision fermentation-derived recombinant casein for vegan-positioned formulations and German pharmacy channel distribution bypassing grocery retail margin compression. Go-to-market traction depends on clinical validation partnerships with pediatric gastroenterology departments.
For Investors and Strategic Acquirers: MFDS enforcement of stricter nutrient labeling requirements in South Korea is the leading indicator that regulatory compliance depth will separate viable acquisition targets from stranded assets. Long-term viability across the projection horizon favors pharmaceutical-grade manufacturers with hospital channel access and precision biotechnology startups with recombinant protein pathways. Target acquisition archetypes include aseptic filling capacity owners and certified organic cooperatives with limited supplier bases.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Recombinant lactoferrin production via microbial hosts reduces dependency on New Zealand dairy cooperative supply swings. |
| Aseptic Liquid Concentrate Capacity Expansion | Yangtze River Delta manufacturing clusters capture urban Chinese parent demand for ready-to-feed convenience formats. |
| Hospital Channel Exclusivity Agreements | Australian and South Korean pediatric gastroenterology departments lock out retail competitors through preferred supplier relationships. |
| Pharmacy Distribution Bypass | German and Swiss pharmacy channels access reimbursed prescription formula segments with professional endorsement value. |
| Subscription Platform Acquisition | Automated replenishment algorithms capture recurring revenue and consumption data for personalized nutrition recommendations. |
Study Parameters
Multi-period observation of NMPA registration cap enforcement, EFSA novel ingredient pathway approvals, and FDA facility inspection timelines anchored the trend analysis, supplemented by interviews with infant formula brand managers, pediatric nutrition specialists, hospital procurement directors, pharmacy category buyers, and dairy cooperative supply planners. Secondary validation drew from FDA facility inspection databases, EFSA scientific opinions, NMPA registration filings, and customs trade records for milk powder imports. Bottom-up volume modeling across product type, end user, packaging format, and distribution channel segments triangulated against top-down market sizing.
Input-output matrices mapped spray-drying capacity utilization, aseptic filling investment flows, and organic dairy input availability across the analysis window. Segmentation dimensions modeled include nutritional positioning tier, clinical validation status, convenience format, procurement channel, and regional regulatory cluster. CAGRs derived from trend extrapolation of volume placements and price point trajectories, with scenario weighting for precision fermentation commercialization timelines and hospital channel consolidation patterns.
Regulatory registration delays, organic dairy input seasonal volatility, and precision fermentation technology maturation are the dominant revision risks that could compress or extend forecast trajectories. Forecasts reflect assumptions about NMPA enforcement continuity, EFSA pathway accessibility, and hospital procurement standardization trends. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Middle East and Africa Baby Food Market
Baby Food and Infant Formula
Baby Fruit Puree Market
Baby Food and Infant Formula
Middle East and Africa Organic Baby Food Market
Baby Food and Infant Formula
Baby Food Market
Baby Food and Infant Formula
Goat Milk Formula Market
Baby Food and Infant Formula
Organic Baby Food Market
Baby Food and Infant Formula
Pet Milk Replacement Products Market
Baby Food and Infant Formula
India Baby Food Market
Baby Food and Infant Formula
Baby Juice Market
Baby Food and Infant Formula
United States Baby Food and Infant Formula Market
Baby Food and Infant Formula
Baby Food Products Market
Baby Food and Infant Formula
BRIC Organic Baby Food Market
Baby Food and Infant Formula
Europe Baby Food Market
Baby Food and Infant Formula
West Africa Baby Food Market
Baby Food and Infant Formula
Asia-Pacific Prebiotics for Infant Formula Market
Baby Food and Infant Formula
Growing Up Formula Market