
 Pet Milk Replacement Products Market | 2026-2036
Pet Milk Replacement Products Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Milk Replacement Products Market Insights
The EU Green Deal is realigning ingredient sourcing standards across European pet nutrition supply chains, pushing manufacturers toward lower-carbon dairy and plant-derived inputs. Cargill, Incorporated leverages its global agricultural procurement network to secure traceable raw materials for milk replacement formulations. Grober Nutrition, Inc. specializes in species-specific neonatal nutrition, dominating the veterinary and professional breeder channel across Canada and the United States.
Pet milk replacement products are nutritionally complete synthetic or modified dairy formulations designed to mirror the macronutrient profile of maternal milk, typically containing 25-35% crude protein and 15-25% fat on a dry matter basis for optimal neonatal development. Powder formulations sustain the largest volume share due to extended shelf stability and lower logistics costs, while liquid formats occupy the premium convenience tier in veterinary clinics and rescue centers. Plant-based and dairy-free formulations are accelerating fastest as allergen-conscious households and specialty rescue operations seek hypoallergenic alternatives for lactose-intolerant neonates.
The FDA Center for Veterinary Medicine governs ingredient safety and labeling claims for milk replacers distributed in the United States, while the European Food Safety Authority sets maximum residue limits and novel protein approval pathways under EU feed legislation. The USDA National Organic Program creates a parallel certification track that commands price premiums in the specialty retail channel. Stakeholders must monitor evolving novel protein approvals and organic certification thresholds to determine which formulation investments align with tightening regulatory and consumer expectations.
Market Dynamics
Veterinary clinics and professional breeders are consolidating purchasing power around species-specific neonatal nutrition protocols, compressing margins for generic milk replacer suppliers while rewarding formulation specialists with clinical validation data.
Growth Catalysts
- EU Green Deal sourcing mandates:The European Commission's sustainability framework is redirecting procurement toward lower-carbon dairy inputs and traceable plant-derived proteins, opening premium positioning for compliant suppliers.
- Millennial pet owner expenditure patterns:United States households aged 28-43 demonstrate disproportionate willingness to pay for veterinary-recommended neonatal nutrition, expanding the premium channel.
- Neonatal care protocol standardization:Emergency veterinary networks and rescue operations are adopting evidence-based feeding regimens that specify commercial milk replacers over homemade alternatives.
Market Restraints
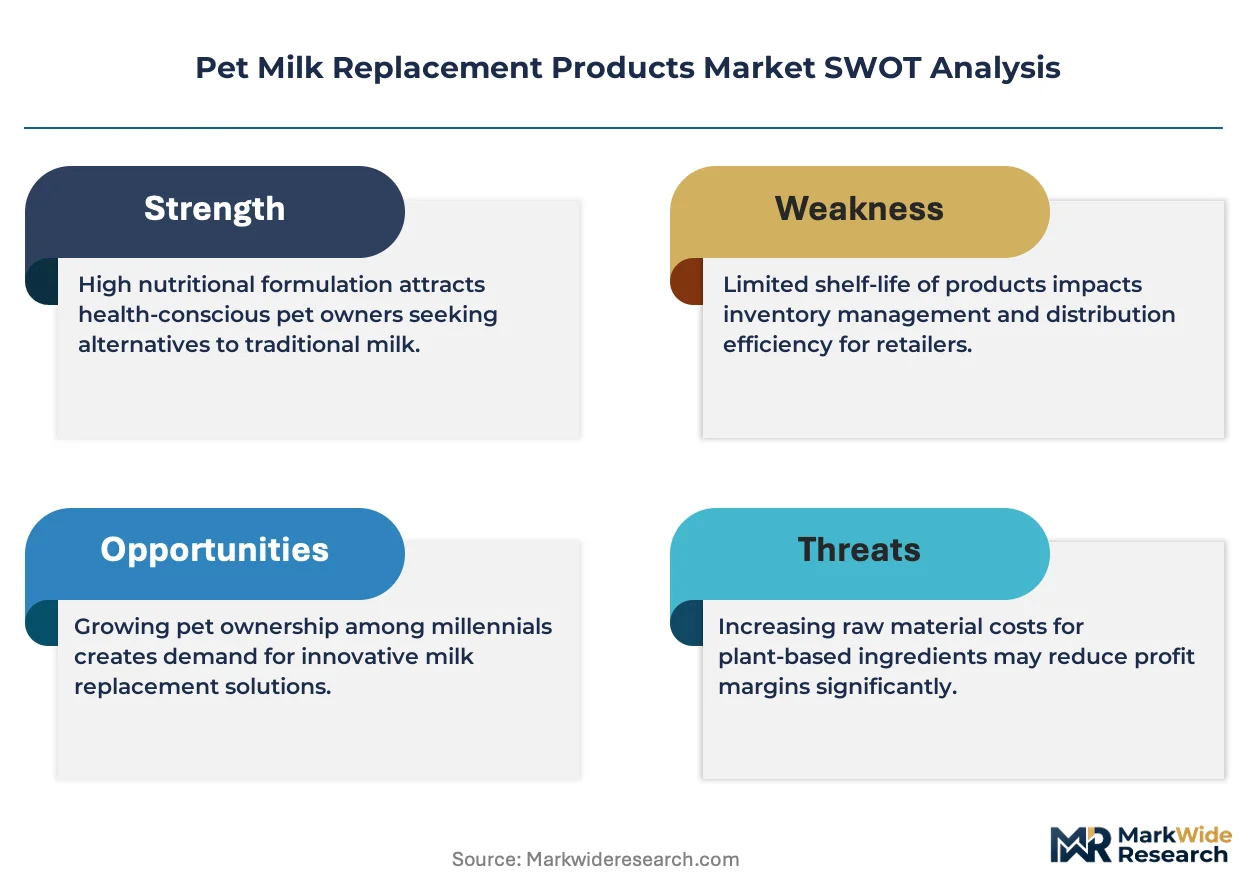
- Skim milk powder price volatility:Dairy commodity fluctuations directly compress formulation margins, particularly for mid-tier manufacturers lacking long-term supply contracts.
- Single-source whey protein concentration:North American and European suppliers dominate functional protein inputs, creating geographic concentration risk for Asian and Latin American formulators.
- Novel protein approval timelines:EFSA's extended safety evaluation pathways for insect and microbial proteins delay product launches by 18-36 months versus conventional dairy.
Strategic Opportunities
- Underpenetrated Southeast Asian veterinary channels:Thailand, Vietnam, and Indonesia maintain low commercial milk replacer adoption despite expanding small-animal veterinary infrastructure.
- USDA National Organic Program certification:Organic dairy input traceability commands 25-40% price premiums in specialty pet retail and direct-to-consumer channels.
- Precision fermentation convergence:Synthetic biology platforms combining recombinant protein production with AI-driven formulation optimization enable bio-identical maternal milk replication.
Industry Challenges
- Neonatal nutrition specialist scarcity:Veterinary schools produce insufficient clinical nutritionists to support product education and protocol development for manufacturer field teams.
- Multi-jurisdiction labeling compliance:Divergent FDA, EFSA, and Health Canada claim requirements force SKU proliferation and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Milk Replacement Products Market |
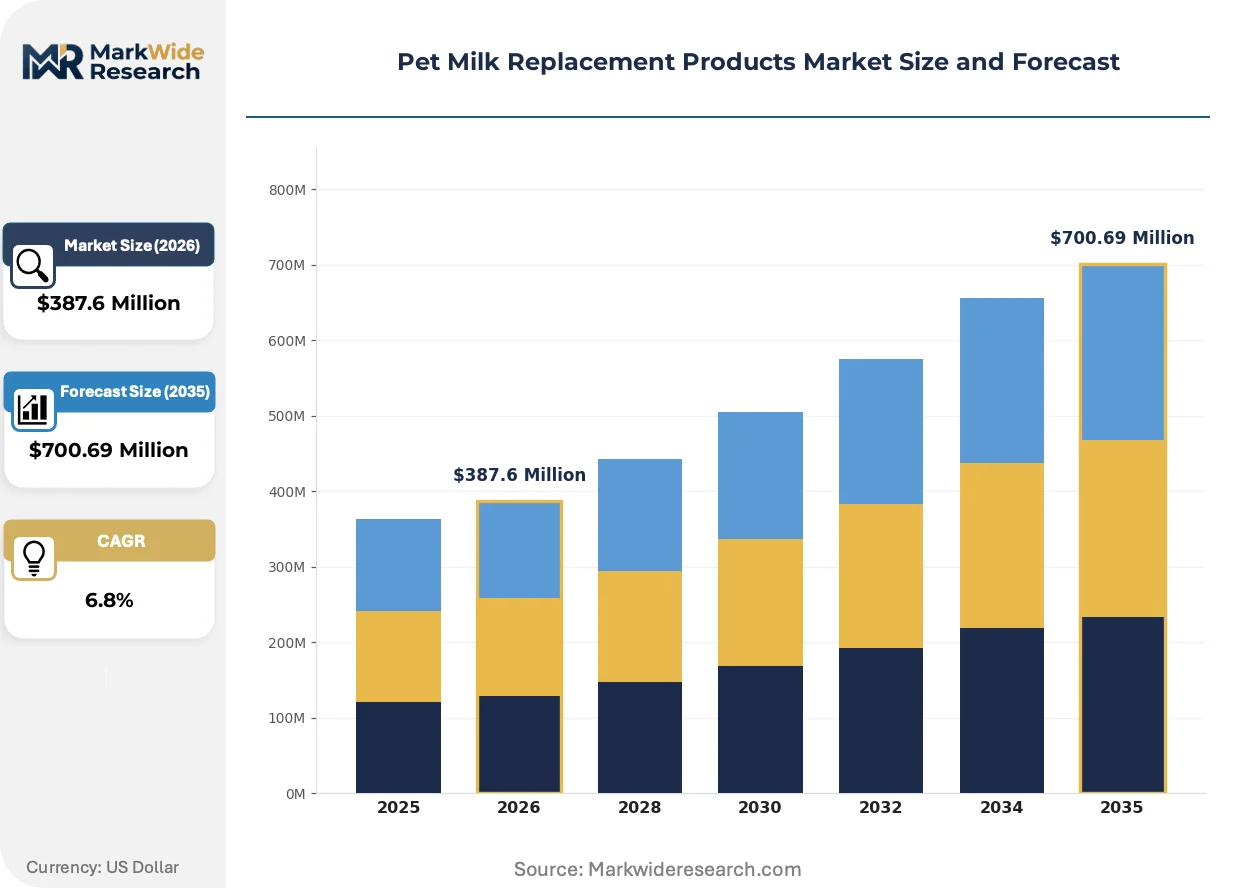
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Creamy, Concentrate Formulation: Dairy-Free, Lactose-Free, Plant-Based, Specialty Packaging Type: Carton, Sachet, Bottle, Tub End User: Households, Veterinary Clinics, Pet Shops, Rescue Centers |
| Companies Covered | Pet-Ag, Inc., CHS Inc., Cargill, Incorporated, Archer Daniels Midland Company, Land O’Lakes, Glanbia plc, Manna Pro Products, LLC, Grober Nutrition, Inc., Royal Canin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Milk Replacement Products Market Trends and Innovations
Formulation science is diverging along two paths: precision-engineered dairy analogs for species-specific metabolic needs, and bio-manufactured proteins that bypass agricultural supply chains entirely. Both trajectories demand new regulatory engagement strategies and capital deployment models.
Spray-dried colostrum replacers with standardized immunoglobulin concentrations are electrifying neonatal immunity protocols in large-scale breeding operations. Canine and feline reproductive specialists at major veterinary teaching hospitals have adopted these products for high-value litters. The technology is electrifying premium tier segmentation by collapsing the historical gap between maternal colostrum and commercial substitutes.
EFSA's 2023 updated guidance on novel protein safety assessments is compressing approval timelines for insect-based and precision-fermented ingredients. European formulators now face clearer toxicological data requirements but reduced regulatory uncertainty. The policy shift most directly affects mid-sized manufacturers seeking to differentiate through alternative protein positioning.
Subscription-based auto-replenishment models are displacing traditional distributor relationships in the United States companion animal sector. Millennial and Gen Z pet owners purchase milk replacers through Chewy, Amazon Subscribe & Save, and veterinary practice portals rather than farm supply retailers. This channel rotation concentrates volume with platforms possessing superior customer data infrastructure.
Pet Milk Replacement Products Market Segmentation
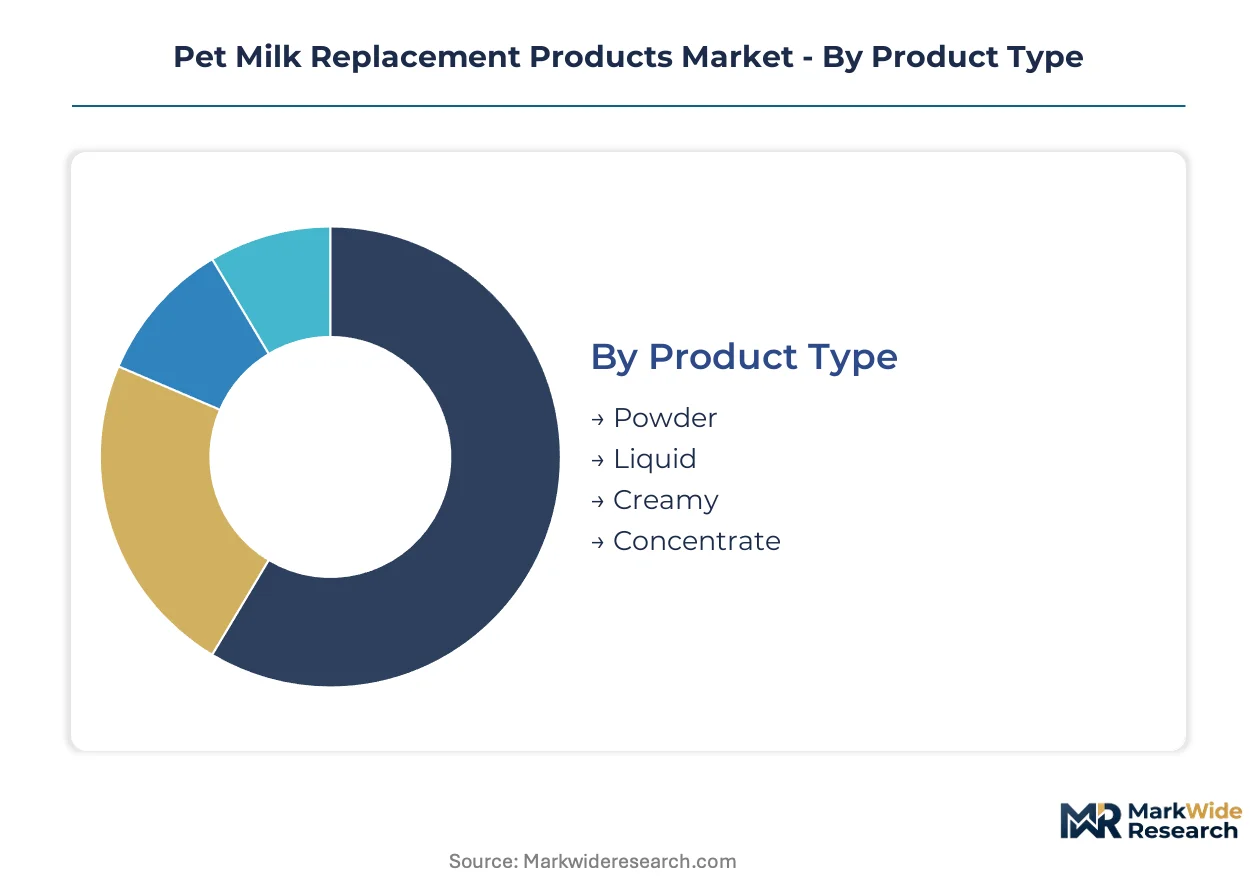
Pet milk replacement products fragment across formulation chemistry, physical state, and procurement channel. Each dimension carries distinct margin profiles and regulatory exposure, demanding targeted portfolio architecture.
Product Type:
Purchasing behavior splits between cost-conscious bulk buyers and convenience-seeking clinical users.
- Powder:Dehydrated formulations with 12-24 month shelf stability dominate volume procurement by professional breeders and multi-animal facilities. United States veterinary distributors report powder SKUs constitute the baseline stocking unit across farm supply and rescue networks, though reconstitution labor limits household penetration.
- Liquid:Ready-to-feed solutions command premium shelf positioning in emergency veterinary clinics and neonatal intensive care settings. Ready-to-use formats eliminate mixing errors during critical first 72-hour feeding windows, justifying 40-60% price elevation over equivalent powder protein content.
- Creamy:High-viscosity preparations target species with specialized nursing mechanics.
- Concentrate:Dilution-required formats balance shelf stability with reduced shipping weight for remote deployment.
Volume sits with Powder; growth tilts toward Liquid.
Formulation:
Ingredient sourcing decisions now incorporate carbon intensity metrics alongside nutritional adequacy.
- Dairy-Free:Synthetic lipid and protein assemblies bypass agricultural commodity cycles entirely. Precision fermentation platforms in California and the Netherlands are scaling bio-identical milk protein production, though EFSA novel food approvals remain the pacing constraint for European commercialization.
- Plant-Based:Pea, oat, and coconut protein isolates serve allergen-sensitive neonates and sustainability-positioned retailers. German and Dutch pet specialty chains have elevated plant-based replacers to dedicated planogram sections, reflecting EU Green Deal procurement pressures on their supply bases.
- Lactose-Free:Enzyme-treated dairy substrates retain casein bioavailability while eliminating digestive intolerance.
- Specialty:Species-optimized variants address metabolic peculiarities of exotic companion mammals.
Revenue concentrates in Dairy-Free; steepest expansion trajectory belongs to Plant-Based.
Packaging Type:
Channel economics dictate format selection more than end-user preference alone.
- Carton:Aseptic brick packaging extends ambient distribution reach for liquid formulations. Multi-unit cartons dominate Chewy and Amazon Subscribe & Save configurations, where auto-replenishment algorithms favor predictable dimensional weights.
- Sachet:Single-serve foil pouches eliminate contamination risk in field rescue operations. Wildlife rehabilitation centers and disaster response stockpiles specify sachet formats for portion control and inventory rotation compliance.
- Bottle:Reclosable containers support intermittent feeding schedules in household settings.
- Tub:Bulk rigid packaging serves high-volume breeding kennels and catteries.
Carton captures institutional volume; sachets gain share fastest in emergency response channels.
End User:
Decision authority and technical sophistication vary dramatically across procurement settings.
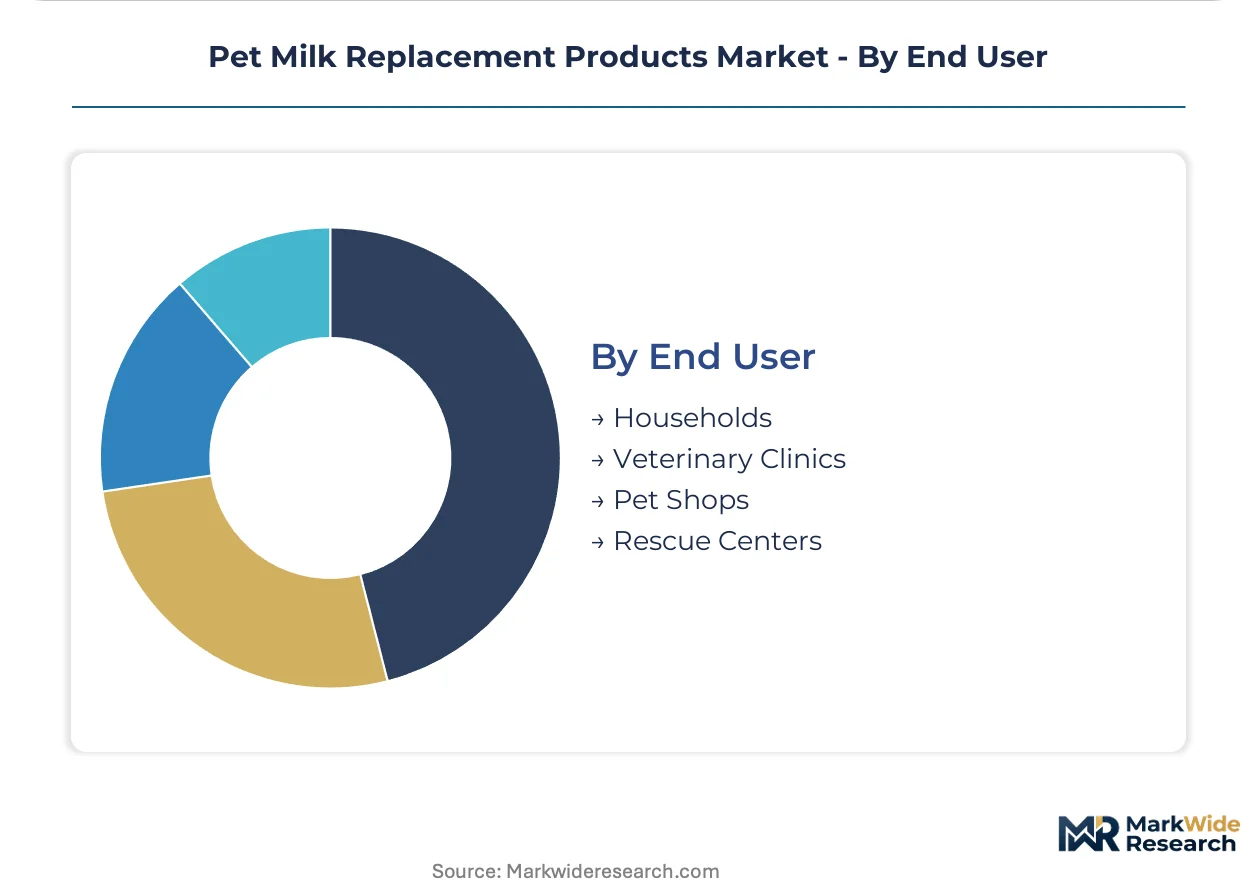
- Veterinary Clinics:Board-certified veterinary nutritionists specify species-specific protocols with documented clinical outcomes. University teaching hospitals and emergency networks maintain formularies that exclude generic alternatives, creating defensible revenue pools for validated manufacturers.
- Rescue Centers:High neonatal mortality environments prioritize ease of use and rapid staff training. Municipal shelter systems in Texas, California, and Florida represent concentrated annual volume through centralized procurement contracts.
- Households:Orphaned puppy and kitten fostering drives sporadic, education-intensive purchasing.
- Pet Shops:Retail floor staff influence selection with limited clinical training.
Veterinary Clinics anchor premium pricing; Rescue Centers drive volume scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kansas City metropolitan corridor anchors North American distribution networks for pet milk replacement products, with veterinary teaching hospitals in Manhattan and Columbia serving as protocol validation centers for neonatal nutrition formulations.
United States
Millennial pet owners in Austin, Denver, and Portland drive premium nutrition expenditure for orphaned puppies and kittens. The FDA Center for Veterinary Medicine governs ingredient safety and labeling claims for milk replacers distributed across all states. Emergency veterinary networks in Texas and Florida maintain centralized procurement contracts that specify commercial formulations over homemade alternatives.
Germany
German pet specialty chains in Munich and Hamburg have elevated plant-based milk replacers to dedicated retail sections. The EU Green Deal redirects procurement toward lower-carbon dairy inputs and traceable plant-derived proteins for compliant suppliers. Precision fermentation platforms in the Netherlands and Belgium supply bio-identical milk protein inputs to German formulators seeking EFSA novel food approvals.
China
Shanghai and Beijing veterinary clinics are expanding neonatal care protocols for purebred dogs and cats in high-value breeding operations. The country's national feed safety regulator establishes maximum residue limits for imported dairy ingredients used in companion animal nutrition. Yangtze River Delta manufacturing clusters produce powder formulations for domestic distribution and Southeast Asian export markets.
United Kingdom
London and Southeast England rescue centers specify single-serve sachet formats for portion control in high neonatal mortality environments. The country's veterinary medicines directorate aligns with EFSA guidance on novel protein safety assessments for insect-based ingredients. University teaching hospitals in Edinburgh and Glasgow maintain formularies that exclude generic milk replacer alternatives.
Canada
Professional breeders in Ontario and Quebec consolidate purchasing power around species-specific neonatal nutrition protocols validated by veterinary nutritionists. Health Canada governs feed safety and ingredient approval pathways for milk replacement products distributed nationwide. Grober Nutrition anchors manufacturing operations in Cambridge, Ontario, supplying veterinary and professional breeder channels across the province and into the United States.
Pet Milk Replacement Products Market Competitive Landscape
The competitive structure tilts toward formulation specialists with clinical validation data. Veterinary clinics and professional breeders compress margins for generic suppliers while rewarding manufacturers with documented neonatal outcomes. Three archetypes dominate: agricultural conglomerates leveraging procurement scale, species-specific nutrition specialists, and precision fermentation platforms. M&A activity concentrates on acquiring veterinary distribution relationships, while portfolio diversification moves target plant-based and hypoallergenic formulation lines.
Within the agricultural conglomerate tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify players with global raw material procurement networks that secure traceable dairy and plant-derived inputs for milk replacement formulations. Grober Nutrition, Inc. occupies a specialist position, with its Cambridge, Ontario base supporting dominance in veterinary and professional breeder channels across Canada and the United States. Royal Canin represents the veterinary-channel anchor archetype, leveraging relationships with board-certified nutritionists at university teaching hospitals to maintain defensible premium positioning.
| Leading Market Players |
|---|
| Pet-Ag, Inc. |
| CHS Inc. |
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Land O'Lakes |
| Glanbia plc |
| Manna Pro Products, LLC |
| Grober Nutrition, Inc. |
| Royal Canin |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between USDA Organic and conventional formulations splits pricing power along traceability lines, with organic dairy input premiums of 25-40% cascading through finished-product markups while conventional suppliers compete on skim milk powder contract leverage. This tiered structure concentrates margin capture with vertically integrated agricultural conglomerates holding captive dairy supply, whereas mid-tier formulators face margin compression from commodity volatility and single-source whey protein dependencies.
Pricing Analysis
Neonatal survival rates anchor value-based pricing in veterinary clinics, where ready-to-feed liquid formulations command 40-60% premiums over equivalent powder protein content due to elimination of mixing errors during critical 72-hour feeding windows. Three-tier pricing structure across premium, standard, and economy levels stratifies by clinical validation depth, with university teaching hospital formularies excluding generic alternatives entirely. Pricing pressure stems from skim milk powder commodity fluctuations that compress mid-tier manufacturer margins lacking long-term supply contracts. Rescue centers and municipal shelter systems exhibit highest price sensitivity through centralized procurement contracts, while emergency veterinary networks demonstrate lowest sensitivity due to protocol-driven specification authority.
Supply Chain Analysis
Single-source vulnerability sits with North American and European whey protein concentrate suppliers, creating geographic concentration risk for Asian and Latin American formulators seeking functional protein inputs. Manufacturing gravity draws from the United States, Canada, and Germany, with Kansas City distribution corridors anchoring North American logistics and Yangtze River Delta clusters serving Southeast Asian export markets. Raw material dependencies rest on skim milk powder, whey protein isolates, and precision-fermented bio-identical proteins scaling in California and the Netherlands. Tariff exposure on imported dairy ingredients threatens margin stability for Chinese and Southeast Asian manufacturers. Distribution runs through veterinary distributors, Chewy and Amazon Subscribe & Save platforms, and direct-to-clinic portals displacing traditional farm supply retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints on EFSA novel protein approvals and precision fermentation scale-up prop pricing premiums for compliant suppliers, with 18-36 month safety evaluation timelines limiting competitive entry and protecting validated incumbents. This bottleneck structure rewards early certification investments while penalizing late adopters facing capacity scarcity.
For Market Incumbents: Anchor defensible positioning through backward integration into traceable dairy supply chains and captive precision fermentation capacity in the Netherlands or California. Deepen clinical validation partnerships with university teaching hospitals to maintain formulary exclusion power against generic substitutes. Prioritize USDA National Organic Program certification investments to capture 25-40% specialty retail premiums. Counter subscription-platform disintermediation by building direct-to-clinic portal infrastructure with embedded auto-replenishment algorithms. For New Entrants and Emerging Players: The mid-tier price-point gap between premium veterinary-channel formulations and economy bulk powder offers white-space entry through plant-based and hypoallergenic positioning targeting allergen-conscious millennial households. Thailand, Vietnam, and Indonesia veterinary channels remain underpenetrated despite expanding small-animal infrastructure. Precision fermentation platforms bypassing agricultural commodity cycles present differentiation angle for synthetic lipid and protein assemblies. Target rescue center and wildlife rehabilitation sachet formats with disaster-response stockpile procurement contracts as volume anchor. For Investors and Strategic Acquirers: Re-rating potential sits with precision fermentation platforms possessing EFSA novel food approval pathways and AI-driven formulation optimization capabilities given EU Green Deal sourcing mandate acceleration. Long-term viability over the next decade hinges on synthetic biology convergence enabling bio-identical maternal milk replication. Acquisition target archetype: mid-sized manufacturers with veterinary distribution relationships and plant-based formulation pipelines. Signal to watch: EFSA approval timeline compression for insect-based and microbial proteins as inflection indicator for alternative protein competitive viability.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Bio-identical protein production in California and Netherlands bypasses agricultural commodity volatility entirely. |
| USDA Organic Certification Investment | Organic dairy traceability commands 25-40% price premiums in specialty pet retail channels. |
| Veterinary Distribution Acquisition | University teaching hospital formulary relationships create defensible revenue pools against generic substitutes. |
| Plant-Based Formulation Pipeline | Pea and oat protein isolates serve EU Green Deal procurement pressures and allergen-sensitive neonates. |
| Direct-to-Clinic Portal Development | Auto-replenishment algorithms counter Chewy and Amazon Subscribe & Save platform disintermediation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across veterinary nutritionists, professional breeder network coordinators, emergency clinic procurement managers, and pet specialty retail category buyers. FDA Center for Veterinary Medicine guidance documents, EFSA novel protein safety assessments, USDA National Organic Program standards, and Health Canada feed safety regulations provided regulatory boundary conditions. Bottom-up formulation volume estimates triangulated against top-down pet owner expenditure surveys and veterinary distributor shipment data.
Granularity-level modeling deployed product type, formulation chemistry, packaging format, and procurement channel dimensions across the analysis window, with species-specific metabolic requirements and regional regulatory clusters as cross-cutting variables. CAGRs derived from spline-interpolated annual growth assumptions calibrated to historical dairy commodity price elasticity and premium nutrition expenditure trends. Forecast inputs incorporated precision fermentation commercialization timelines, EU Green Deal implementation trajectories, and subscription-platform channel migration velocity.
Inputs from veterinary teaching hospitals, rescue center networks, and precision fermentation platforms were available through the study window; gaps in real-time EFSA approval pipeline data and proprietary formulation cost structures introduce uncertainty bands around alternative protein adoption curves. Forecasts reflect documented assumptions on regulatory timeline compression and commodity price stabilization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Asia-Pacific Prebiotics for Infant Formula Market
Baby Food and Infant Formula
Kids Food and Beverages Market
Baby Food and Infant Formula
North America Baby Food and Infant Formula Market
Baby Food and Infant Formula
Cow Milk Infant Formula Market
Baby Food and Infant Formula
North America Organic Baby Food Market
Baby Food and Infant Formula
Omega 3 Ingredients for Infant Food Market
Baby Food and Infant Formula
Europe Baby Food and Infant Formula Market
Baby Food and Infant Formula
West Africa Baby Food Market
Baby Food and Infant Formula
Vietnam Pet Food Market
Baby Food and Infant Formula
South America Organic Baby Food Market
Baby Food and Infant Formula
Baby Infant Formula Market
Baby Food and Infant Formula
Baby Food Products Market
Baby Food and Infant Formula
Middle-Aged and Elderly Milk Powder Market
Baby Food and Infant Formula
Canned Pet Food Market
Baby Food and Infant Formula
Asia Pacific Organic Baby Food Market
Baby Food and Infant Formula
Follow on Formula Milk Market