
 Cow Milk Infant Formula Market | 2026-2036
Cow Milk Infant Formula Market Size, Share, and Industry Trends Forecast 2026-2036
Cow Milk Infant Formula Market Analysis
Single-serve pouch packaging is realigning how parents purchase infant formula, shifting volume from bulk tins toward trial-sized and on-the-go formats. Nestlé leverages its dairy supply network across European sourcing regions to sustain cost advantages in powdered formula production. Danone anchors its competitive position through specialized nutrition R&D, while Yili Group dominates domestic distribution infrastructure within China.
Cow milk infant formula denotes a manufactured breast milk substitute produced by modifying bovine milk proteins, standardizing fat content through vegetable oil blends, and fortifying with iron, DHA, and ARA to meet infant nutritional requirements. The manufacturing process involves wet mixing, homogenization, spray drying, and precision nutrient dosing to achieve compositional parity with human milk. Powdered formula occupies the largest volume share due to shelf stability and lower logistics costs, though ready-to-feed formats command premium pricing in hospital and clinic channels. Liquid formula competes for pharmacy shelf space where convenience drives repeat purchases among working parents.
FDA enforces infant formula quality standards through its Food and Drug Administration Modernization Act framework, mandating nutrient specifications and manufacturing facility inspections. EFSA and China's NMPA impose parallel registration requirements that shape which products gain market access across their respective jurisdictions. Stakeholders must monitor evolving microbiological testing protocols and label claim restrictions as regulators tighten oversight on immune-support and cognitive-development marketing assertions.
Market Dynamics
China's evolving NMPA registration pathways and GB standards are compressing market access timelines for imported formulas while elevating quality benchmarks that reshape competitive positioning across Asia-Pacific sourcing corridors.
Growth Catalysts
- Urbanization in Southeast Asia:City-level retail infrastructure expansion in Vietnam and Indonesia brings modern trade channels to first-time formula buyers. Hypermarket penetration in Jakarta and Ho Chi Minh City accelerates brand trial among working parents.
- EFSA nutrient specifications:Harmonized compositional standards across EU member states reduce reformulation costs for manufacturers seeking multi-country registration. This regulatory convergence streamlines cross-border distribution logistics.
- Spray drying efficiency gains:Advanced atomization technologies cut energy consumption in powder production facilities. Dairy processors in New Zealand and the Netherlands deploy these systems to protect margin structures amid volatile milk powder input costs.
Market Restraints
- Skim milk powder volatility:Global dairy commodity auctions in New Zealand transmit price shocks directly to formula manufacturing cost bases. Futures market illiquidity limits hedging effectiveness for mid-scale producers.
- Chinese domestic capacity concentration:Yili Group and state-backed dairy consolidation control 60% of national liquid milk sourcing. Foreign brands face captive supply constraints and input cost premiums when localizing production.
- Human milk oligosaccharide synthesis limitations:Biotechnological production of HMOs remains capacity-constrained at industrial scale. This technical bottleneck restricts premium formulation differentiation for all but the largest R&D budgets.
Strategic Opportunities
- Sub-Saharan Africa pharmacy channels:Modern drugstore chains in Nigeria and Kenya expand refrigerated distribution for ready-to-feed formats. Cold chain investments by regional logistics providers enable premium positioning previously limited to powder.
- Organic certification tailwinds:EU Organic Regulation 2018/848 and parallel USDA National Organic Program standards create dual-labeling pathways. Manufacturers with integrated dairy farm control capture price premiums in German and French markets.
- Precision fermentation convergence:Microbial protein expression platforms intersect with lipid encapsulation technologies to produce bio-identical milk proteins. Early-stage facilities in Singapore and California target 2027 commercial scale for specialty formula ingredients.
Industry Challenges
- Clinical trial recruitment bottlenecks:Pediatric nutrition studies require extended follow-up protocols and ethical board approvals across multiple jurisdictions. NMPA and FDA parallel submission timelines stretch product development cycles to 48-60 months.
- Legacy ERP integration:Batch traceability mandates under FSMA and EU Food Law force upgrades to manufacturing execution systems. Smaller regional brands face six-figure software implementation costs to achieve lot-level genealogy tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cow Milk Infant Formula Market |
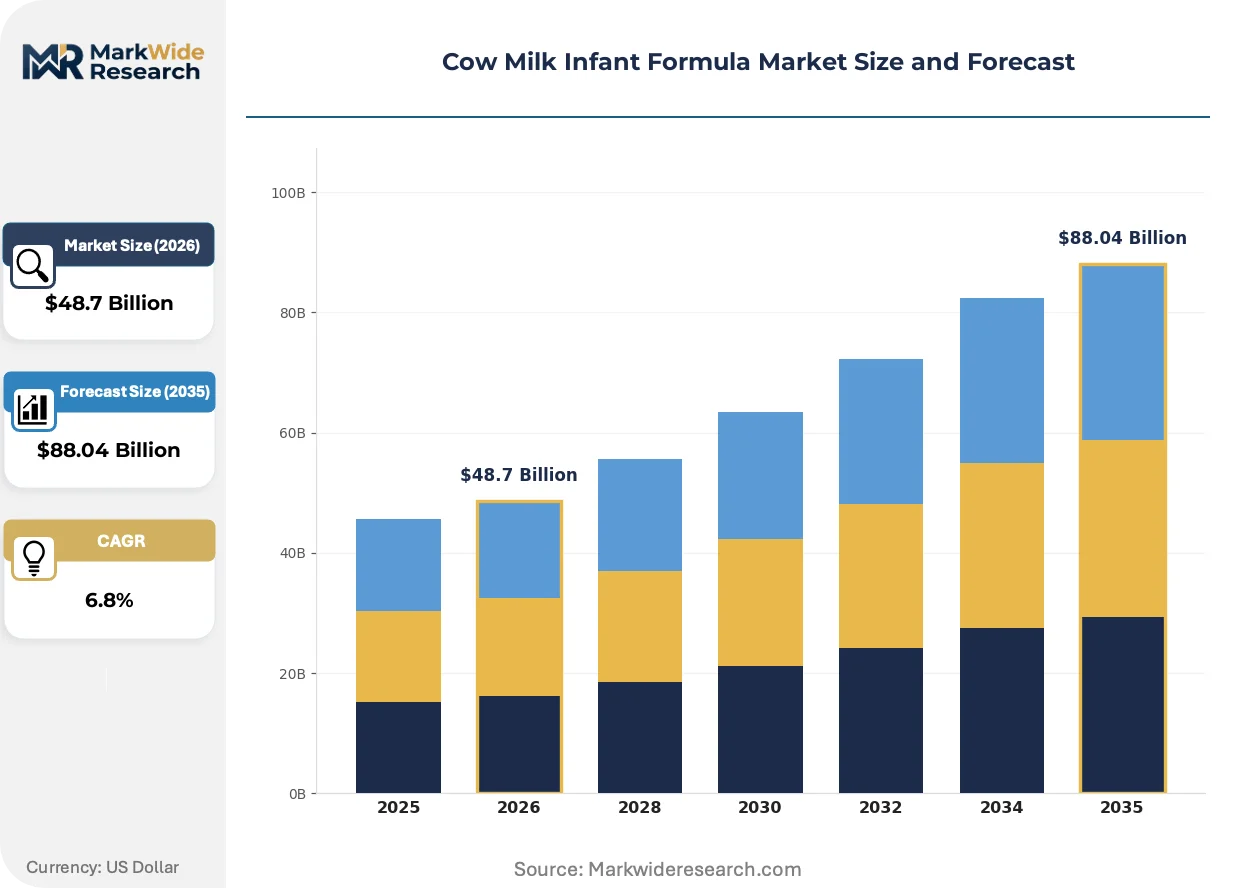
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Formula, Liquid Formula, Ready-to-Feed, Concentrated Liquid End User: Parents, Hospitals, Clinics, Caregivers Packaging Type: Tins, Pouches, Bottles, Cartons Distribution Channel: Supermarkets, Pharmacies, Online Retail, Specialty Stores |
| Companies Covered | Nestlé, Abbott, Danone, Arla Foods, FrieslandCampina, Fonterra, Reckitt Benckiser, Perrigo, Yili Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cow Milk Infant Formula Market Emerging Trajectories
Reformulation science and packaging engineering are compressing product development cycles while regulatory digitization reshapes how manufacturers demonstrate safety and nutritional equivalence across jurisdictions.
Precision fermentation for dairy protein production is decentralizing supply chain risk away from concentrated pasture-based milk sourcing. Biotech firms in California and Singapore express casein and whey proteins through engineered yeast strains. Infant formula manufacturers pilot these inputs to reduce exposure to climate-driven raw milk volatility.
China's SAMR has digitized formula registration dossier submissions through its online NMPA portal, compressing administrative review timelines by eliminating paper-based workflows. This procedural acceleration benefits multinational brands with established compliance infrastructure. Domestic Chinese manufacturers respond by hiring regulatory affairs specialists with cross-border submission experience.
Subscription-based replenishment models displace traditional retail stocking patterns among millennial parents in Seoul and Tokyo. Direct-to-consumer platforms capture recurring revenue through algorithmic feeding-stage progression. Pharmacy chains in South Korea counter by unbundling professional consultation services from product transactions.
Cow Milk Infant Formula Market Segmentation
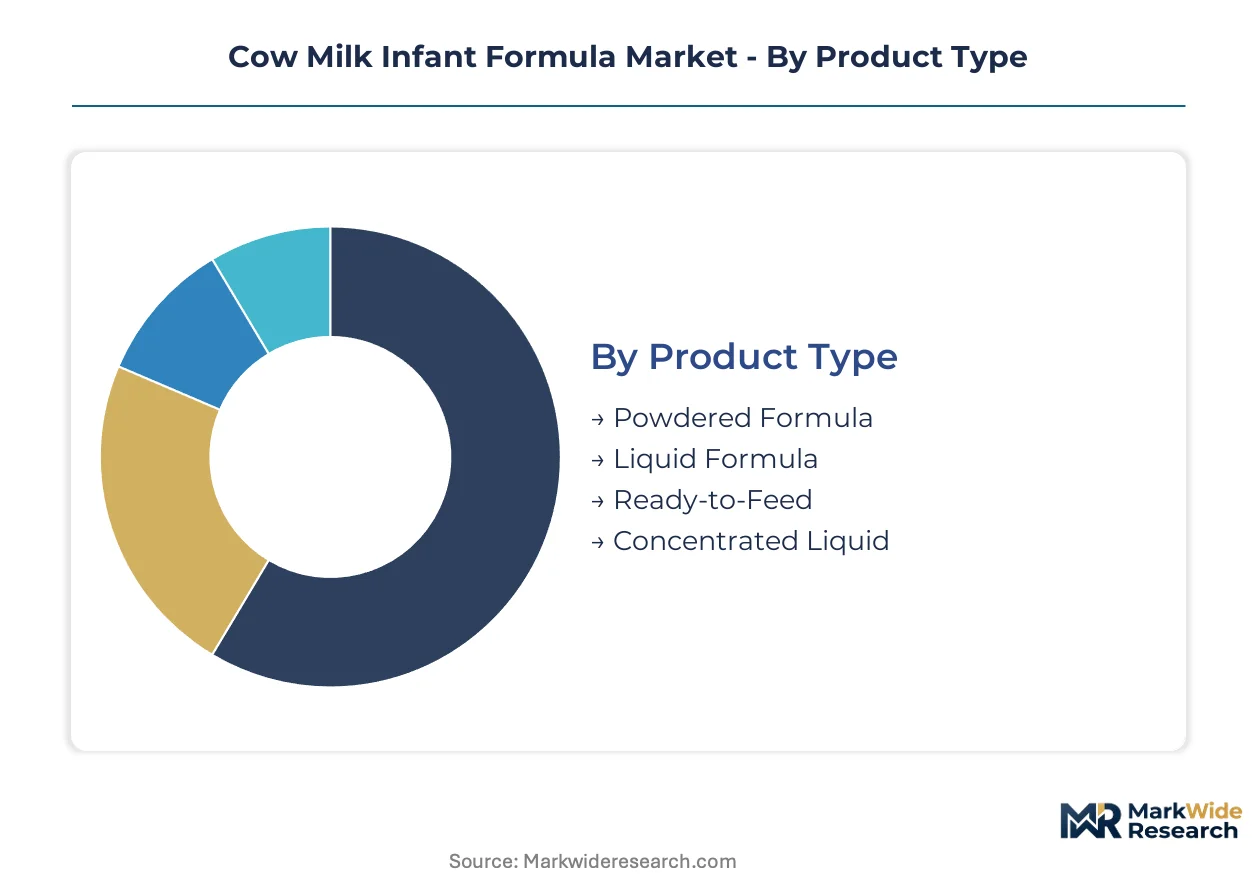
Segmentation in cow milk infant formula reveals how manufacturing economics, channel access, and feeding contexts fragment demand across distinct value propositions. Each dimension carries implications for shelf placement, pricing architecture, and regulatory submission pathways.
Product Type:
Parents select formats based on feeding convenience, storage constraints, and per-feed cost calculations that vary by household structure and workplace demands.
- Powdered Formula:Spray-dried granules reconstitute with water at point of use, delivering the lowest per-ounce cost base. Demand concentrates in Southeast Asian urban households where bulk purchasing at hypermarkets reduces weekly feeding expenditures. Shelf stability eliminates cold chain requirements, enabling distribution through traditional trade channels in Indonesia and Vietnam.
- Liquid Formula:UHT-sterilized ready-to-pour products target working parents with limited preparation time. Pharmacy channels in South Korea and Japan stock these formats for nighttime feeding convenience. Premium positioning reflects higher packaging and logistics costs versus powder alternatives.
- Ready-to-Feed:Pre-sterilized single-serve bottles eliminate mixing errors and contamination risk. Hospital discharge kits in the US and neonatal units in Germany specify these formats for immunocompromised infants.
- Concentrated Liquid:Dilution-required formats balance convenience with cost, finding niche adoption among caregivers seeking middle-ground solutions.
Powdered formula leads volumes today; ready-to-feed formats are gaining share fastest through pharmacy and hospital channel expansion.
End User:
Procurement authority and nutritional decision-making shift across these buyer types, reshaping how manufacturers structure clinical evidence and marketing claims.
- Parents:Primary purchase decision-makers responding to pediatrician recommendations and peer network influence. Digital-native cohorts in Seoul and Tokyo subscribe to replenishment platforms that automate stage-progression purchases.
- Hospitals:Institutional buyers specifying formula for maternity wards and neonatal intensive care units. FDA and EFSA registration requirements dominate vendor qualification processes.
- Clinics:Pediatric practices dispensing samples and prescribing specialized formulations for allergy management or premature infant catch-up growth.
- Caregivers:Grandparents and daycare providers executing purchases on behalf of working parents, often prioritizing preparation simplicity over cost optimization.
Parents dominate transaction volumes; hospital procurement is expanding most quickly through integrated health system contracting.
Packaging Type:
Material selection and format engineering directly influence shelf life, portion control, and retail channel compatibility across diverse shopping environments.
- Tins:Metal canisters with nitrogen flushing protect powder from moisture and oxidation during tropical storage. Traditional retail in India and Brazil relies on this format for its durability in high-humidity conditions.
- Pouches:Flexible single-serve sachets enable trial-sized purchasing and travel portability. Urban Chinese parents sample imported brands through e-commerce sampler packs before committing to bulk formats.
- Bottles:Plastic or glass containers for ready-to-feed and concentrated liquids, sized for single-session consumption. Pharmacy cold cases in Nigeria stock these for immediate-use scenarios.
- Cartons:Aseptic brick packs for liquid formula, leveraging existing UHT dairy infrastructure. European retailers favor this format for its rectangular stacking efficiency.
Tins retain volume leadership; pouches are climbing the fastest through e-commerce trial programs and airport retail expansion.
Distribution Channel:
Channel selection determines margin capture, brand control, and the depth of consumer relationship data available to manufacturers.
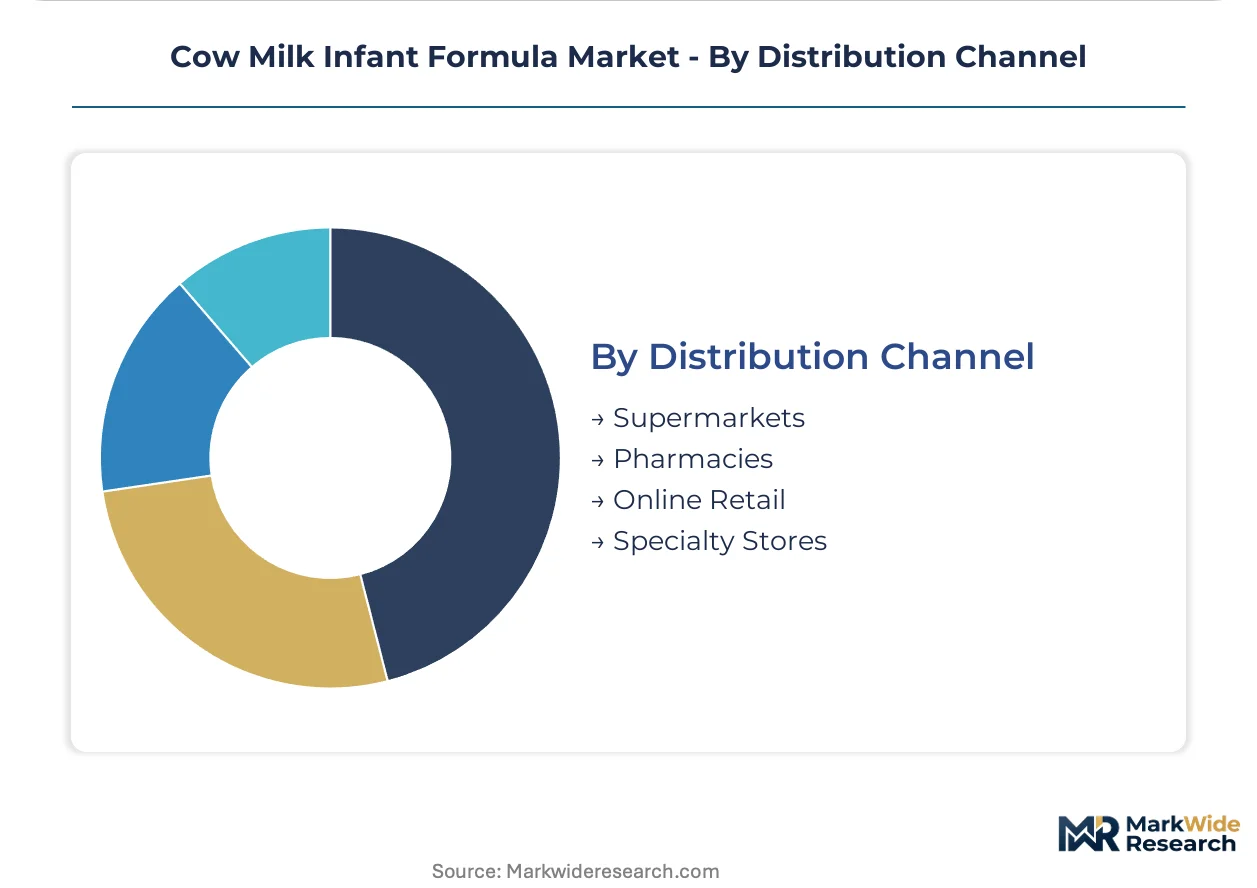
- Supermarkets:Hypermarket chains in Jakarta and Ho Chi Minh City drive brand discovery through end-cap displays and cross-promotion with complementary baby products. Private label pressure intensifies price competition in European markets.
- Pharmacies:Professional consultation attachment justifies premium pricing for specialized formulations. Modern drugstore chains in Kenya and Nigeria invest in refrigerated sections for liquid formula expansion.
- Online Retail:Direct-to-consumer platforms capture recurring revenue through subscription algorithms. China's Tmall and JD.com dominate cross-border import sales for foreign brands navigating NMPA registration timelines.
- Specialty Stores:Mother-and-baby boutiques in tier-two Chinese cities and organic-focused retailers in Germany curate premium and certified-organic assortments.
Supermarkets maintain the largest volume footprint; online retail shows the steepest expansion trajectory through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Infant formula manufacturing traces its industrial origins to nineteenth-century Europe, where Justus von Liebig's 1865 patent for soluble infant food established the scientific foundation for bovine milk modification. Commercial production scaled through Swiss and German dairy cooperatives before expanding into North American and Asian markets during the twentieth century.
China
Domestic demand for cow milk infant formula concentrates in tier-one and tier-two cities where dual-income households drive premium brand preference. NMPA registration pathways under GB standards impose stringent microbiological testing and label verification requirements on imported products. Yili Group anchors production capacity in Inner Mongolia and Hebei Province, leveraging state-backed consolidation to secure liquid milk supply advantages over foreign competitors.
United States
Hospital procurement contracts and WIC program participation shape volume distribution across maternity wards and retail channels. FDA enforces nutrient specifications and facility inspections through the Food and Drug Administration Modernization Act framework. Manufacturing clusters concentrate in Wisconsin and California, where dairy processing infrastructure supports both domestic consumption and export formulation for Latin American markets.
Germany
Organic certification penetration exceeds regional averages as parents prioritize EU Organic Regulation 2018/848 compliance in purchasing decisions. EFSA compositional standards enable seamless cross-border distribution across member states without reformulation costs. Production facilities in Bavaria and North Rhine-Westphalia serve as formulation hubs for Central and Eastern European export corridors.
Vietnam
Urbanization in Ho Chi Minh City and Hanoi expands hypermarket penetration among first-time formula buyers previously dependent on traditional trade. The country's national food safety authority implements parallel import registration requirements that extend market access timelines for non-ASEAN suppliers. Modern retail infrastructure in southern provinces enables cold chain distribution for liquid formula formats previously limited to powder.
Brazil
Pharmacy channel expansion in São Paulo and Rio de Janeiro elevates professional consultation attachment rates for specialized formulations. ANVISA registration mandates clinical evidence submission for immune-support and cognitive-development marketing claims. Domestic dairy cooperatives in Minas Gerais and Paraná supply skim milk powder inputs to regional blending facilities serving Mercosur distribution networks.
Cow Milk Infant Formula Market Vendor Landscape
The competitive structure tilts toward diversified nutrition conglomerates with captive dairy supply networks and established regulatory affairs infrastructure. Three to five multinational groups control majority value share through brand portfolio breadth and hospital channel relationships. Strategic archetypes include integrated dairy-protein processors, pharmaceutical-origin nutrition specialists, and regionally dominant domestic champions. Competitive moves concentrate on spray drying capacity expansion in low-cost sourcing regions and precision fermentation technology licensing for bio-identical protein production.
Within the integrated nutrition conglomerate tier, Nestlé and Danone occupy positions defined by multi-decade brand equity and cross-category dairy expertise. Yili Group exemplifies the domestic champion archetype through control of national liquid milk sourcing and distribution infrastructure. Among pharmaceutical-origin entrants, Abbott and Reckitt Benckiser represent heritage positions in clinical nutrition channels where hospital procurement relationships confer volume stability.
| Leading Market Players |
|---|
| Nestlé |
| Abbott |
| Danone |
| Arla Foods |
| FrieslandCampina |
| Fonterra |
| Reckitt Benckiser |
| Perrigo |
| Yili Group |
| Others |
Supply Flow & Price Mechanics
Hospital procurement consolidation around ready-to-feed sterilized formats is compressing powder price premiums and forcing manufacturers to rebalance spray-drying capacity toward liquid production lines. This demand pivot elevates cold chain infrastructure investments as a cost pass-through mechanism across Southeast Asian distribution networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels anchors transaction architecture, with EU Organic Regulation 2018/848 certification and NMPA registration status driving price differentiation between tiers. Powder formats face margin compression from skim milk powder auction volatility transmitted through New Zealand futures markets. Parents in Indonesian hypermarkets exhibit highest price sensitivity, while German pharmacy channels sustain premium positioning through professional consultation attachment.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore operate as hub-and-spoke coordination points for Asia-Pacific and European fulfillment. Manufacturing concentrates in New Zealand, the Netherlands, and Inner Mongolia, drawing from pasture-based dairy and precision fermentation feedstocks. Skim milk powder, vegetable oil blends, and HMO inputs anchor raw material dependencies. Single-source vulnerability in Chinese liquid milk sourcing creates structural risk. Distribution runs through pharmacy cold chains and hypermarket ambient networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality-grade specification escalation defines this market's late-cycle character, with precision fermentation-derived proteins and HMO fortification becoming baseline expectations among Seoul and Tokyo subscriber cohorts.
For Market Incumbents: Lock in spray-drying capacity expansion in low-cost sourcing corridors to defend margin structures against precision fermentation disruptors. Secure captive dairy supply through backward integration into New Zealand and Dutch cooperatives before Chinese domestic consolidation tightens liquid milk access further. Prioritize NMPA registration dossier digitization to compress administrative timelines versus domestic challengers hiring cross-border compliance specialists. For New Entrants and Emerging Players: Begin with Sub-Saharan Africa pharmacy channel white space, where modern drugstore cold chain investments in Nigeria and Kenya enable ready-to-feed premium positioning previously limited to powder. Target Vietnam's tier-two cities outside Ho Chi Minh City and Hanoi hypermarket saturation. Deploy direct-to-consumer subscription algorithms to capture millennial parent recurring revenue before incumbent platform migration completes. For Investors and Strategic Acquirers: Asymmetric upside sits with precision fermentation technology licensors holding microbial protein expression patents intersecting lipid encapsulation capabilities. Five-to-ten-year viability hinges on commercial scale achievement for bio-identical casein and whey production. Watch Singapore and California facility commissioning announcements as inflection indicators for specialty ingredient supply disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial protein expression in Singapore facilities reduces climate-driven raw milk exposure. |
| NMPA Registration Digitization | SAMR portal submission compression benefits multinationals with established compliance infrastructure. |
| Sub-Saharan Pharmacy Cold Chain | Refrigerated distribution investments in Nigeria enable ready-to-feed format expansion. |
| Organic Certification Dual-Labeling | EU Regulation 2018/848 and USDA NOP compliance captures German and French price premiums. |
| Subscription Platform Deployment | Algorithmic feeding-stage progression captures recurring revenue in Seoul and Tokyo markets. |
Methodological Framework
Bottom-up infant feeding stage modeling reconciled against top-down dairy ingredient supply tracking forms the analytical core of this study. Primary interviews with pediatric nutrition R&D directors, regulatory affairs specialists managing NMPA and FDA parallel submissions, pharmacy category buyers, and dairy cooperative procurement managers combined with secondary validation from EFSA compositional standards documentation, NMPA registration portal records, New Zealand GlobalDairyTrade auction data, and customs import filings. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of spray-drying capacity utilization, HMO synthesis batch yields, and channel shift velocities informed projection frameworks across the analysis window. Segmentation modeling incorporated product format, packaging type, end-user procurement authority, and distribution channel dimensions. CAGRs derived from regression analysis of urbanization rates, hypermarket penetration curves, and regulatory registration timeline compressions. Precision fermentation facility commissioning schedules and organic certification conversion rates served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including sudden shifts in Chinese domestic dairy consolidation policy, breakthroughs in HMO biotechnological production economics, and unanticipated microbiological testing protocol changes by FDA or EFSA. Forecasts reflect documented assumptions regarding NMPA administrative efficiency gains and Southeast Asian cold chain investment continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Hypo Anti Allergic Baby Food Market
Baby Food and Infant Formula
Global DHA Algae Oil for Infant Formula Market
Baby Food and Infant Formula
North America Baby Food and Infant Formula Market
Baby Food and Infant Formula
Pureed Food Market
Baby Food and Infant Formula
South America Organic Baby Food Market
Baby Food and Infant Formula
Baby Food Products Market
Baby Food and Infant Formula
Functional Milk Replacers Market
Baby Food and Infant Formula
Fortified Pet Food Market
Baby Food and Infant Formula
Infant Food Compliance Ready Fertility Input Market
Baby Food and Infant Formula
Baby Cereal-Based Complementary Food Market
Baby Food and Infant Formula
Goat Milk Formula Market
Baby Food and Infant Formula
Russia Pet Food Market
Baby Food and Infant Formula
Infant Formula Market
Baby Food and Infant Formula
Baby Food Testing Market
Baby Food and Infant Formula
Omega 3 Ingredients for Infant Food Market
Baby Food and Infant Formula
Baby Food and Infant Formula Market