
 Organic Baby Food Market | 2026-2036
Organic Baby Food Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Baby Food Market Analysis
USDA Organic certification is redrawing competitive boundaries as manufacturers reformulate recipes to meet stricter residue thresholds. Danone S.A. leverages its European dairy heritage to dominate premium chilled segments. HiPP GmbH & Co. Vertrieb KG anchors its position through three-generation brand equity in German-speaking markets. Nestlé S.A. extends its reach via controlled sourcing networks across Latin American organic farms.
Organic baby food comprises processed or minimally processed edible preparations manufactured from certified organic agricultural ingredients, with prohibited synthetic pesticides, genetically modified organisms, and artificial preservatives under standards such as USDA Organic or EU Regulation 2018/848. The product category serves the nutritional requirements of infants and toddlers during critical developmental windows from birth through thirty-six months. Pouches lead packaging innovation due to convenience-driven parental purchasing and reduced per-unit shipping costs, while glass jars retain loyalty among environmentally conscious consumers seeking fully recyclable formats. Purees occupy the largest volume share as first-food staples, though snacks accelerate fastest among toddlers transitioning to self-feeding.
The USDA National Organic Program and EU Organic Regulation enforce ingredient provenance and processing integrity, compelling manufacturers to maintain certified supply chains from farm to finished goods. FDA infant formula regulations and EFSA nutritional guidelines further constrain label claims and micronutrient fortification levels. Stakeholders must monitor evolving pesticide residue thresholds and emerging state-level organic standards that could fragment compliance requirements across priority markets.
Market Dynamics
Subscription-based direct-to-channel purchasing is restructuring how millennial parents in urban centers access certified organic nutrition, compressing traditional retail intermediaries while tightening ingredient traceability requirements under the USDA Organic seal and EU Regulation 2018/848.
Growth Catalysts
- EU Regulation 2018/848:The updated organic regulation mandates stricter residue thresholds and enhanced supply chain documentation, compelling manufacturers to upgrade certification protocols and locking in premium positioning for compliant producers across German-speaking markets.
- Pouch packaging technology:Flexible spouted pouches reduce per-unit shipping costs by sixty percent versus glass alternatives while enabling single-hand feeding convenience that urban parents prioritize during commute-heavy routines.
- China's tier-one cities:Shanghai and Beijing concentrate demand for imported organic infant nutrition, with premium retail distribution expansion creating dedicated shelf space that domestic brands struggle to access.
Market Restraints
- Organic ingredient cost volatility:Certified fruit and vegetable supply concentrates in California's Central Valley and select Mediterranean growing regions, exposing processors to climate-driven harvest fluctuations that compress margin structures.
- Three-year conversion requirement:Conventional farmland must undergo thirty-six months of organic management before certification, constraining rapid supply expansion and trapping manufacturers in long-term contracting relationships with limited supplier pools.
- Glass jar substitution threat:Environmentally conscious consumers in Germany and Scandinavia retain loyalty to fully recyclable glass formats, slowing pouch adoption in high-value chilled segments where premium positioning matters most.
Strategic Opportunities
- USDA Organic certification arbitrage:State-level organic standards in California and Washington are tightening beyond federal baselines, creating early-mover advantage for manufacturers that pre-empt stricter residue thresholds before national harmonization.
- Toddler snack convergence:Finger-food formats combining organic certification with allergen-free positioning capture self-feeding transitions, opening white space between purees and conventional children's snacks.
- Direct-to-consumer cold chain innovation:Chilled organic meals delivered through subscription models bypass ambient retail shelf limitations, enabling micronutrient retention that jarred alternatives sacrifice during thermal processing.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous USDA Organic, EU Organic, and China Organic Food certification requires parallel audit streams that extend product launch windows by fourteen to eighteen months.
- Legacy ERP integration friction:Lot-level ingredient traceability mandated by organic regulations conflicts with batch-oriented manufacturing software common among mid-tier processors, forcing costly system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Baby Food Market |
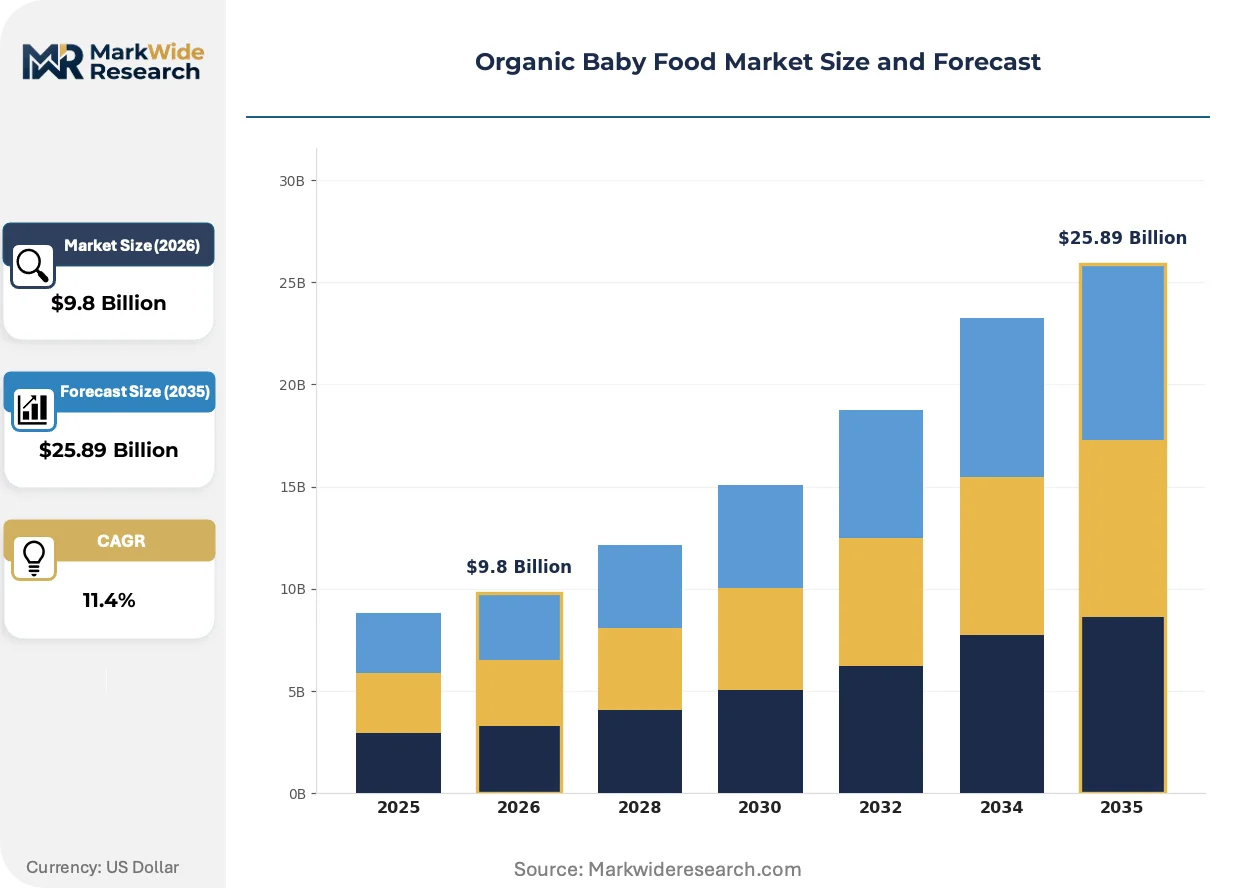
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $25.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purees, Snacks, Cereals, Beverages Age Group: Infants, Toddlers, Pre-School, Newborns Packaging Type: Glass jars, Pouches, Tetra packs, Plastic containers Distribution Channel: Supermarkets, Online Stores, Health Food Stores, Organic Markets |
| Companies Covered | Nestlé S.A., Danone S.A., The Hain Celestial Group, Abbott Laboratories, Hero Group, HiPP GmbH & Co. Vertrieb KG, Kraft Heinz Foods Company, Sprout Organic Foods Inc., Baby Gourmet Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Baby Food Market Emerging Trajectories
Active packaging technologies and regulatory digitization are compressing the gap between farm verification and parental purchase decisions, while channel fragmentation splits volume between subscription platforms and premium retail.
High-pressure processing (HPP) is supplanting conventional thermal sterilization for chilled organic purees. Premium chilled segment buyers in Germany and the United States are adopting HPP-treated products at accelerating rates. This technology is supplanting shelf-stable formats in the highest-margin product tiers by enabling clean-label positioning without the nutrient degradation associated with retort processing.
EU Regulation 2018/848's enhanced traceability requirements are mandating blockchain-verified supply chain documentation from farm to finished goods. Manufacturers must now maintain digital records of every organic input lot, with audit trails accessible to certification bodies within seventy-two hours. Chilled organic segments across German-speaking markets face the steepest compliance investments, driving consolidation among processors lacking dedicated regulatory technology infrastructure.
Subscription-based replenishment is capturing recurring revenue from millennial parents seeking convenience assurance. Direct-to-channel platforms are displacing conventional grocery purchase cycles, with urban clusters in the United States and China showing highest penetration. This shift concentrates customer data ownership with manufacturers, enabling predictive flavor preference algorithms that mass retail cannot replicate.
Organic Baby Food Market Segmentation
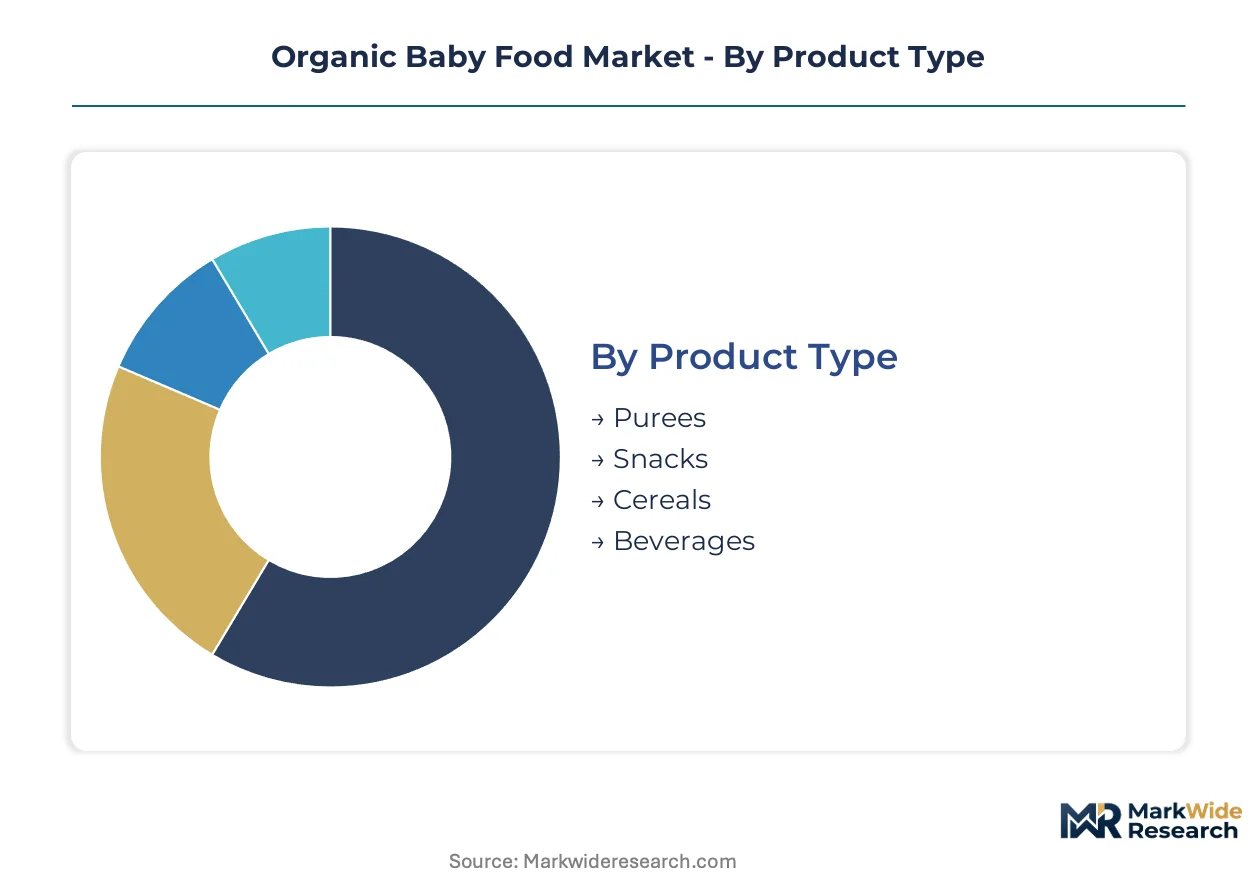
Organic baby food segmentation reveals how certification requirements and feeding-stage transitions fragment purchasing behavior. Manufacturers must align formulation complexity, packaging portability, and channel accessibility with distinct parental priorities across developmental milestones.
Product Type:
Snacks face the most acute substitution pressure from conventional children's finger foods, forcing organic brands to differentiate through allergen-free positioning and clean-label ingredient decks that justify price premiums.
- Purees:Single-ingredient and multi-vegetable blends processed through thermal or high-pressure methods serve as first-food introductions. Demand concentrates among infants aged four to twelve months in the United States and Germany, where pediatric dietary guidelines emphasize early vegetable exposure.
- Snacks:Puffs, teething biscuits, and fruit-based finger foods support self-feeding skill development. Toddlers aged twelve to thirty-six months in China's tier-one cities drive adoption, with parents prioritizing portability during urban commute routines.
- Cereals:Iron-fortified grain blends mixed with breast milk or formula address nutritional gaps in infants transitioning to solid foods.
- Beverages:Organic fruit juices and plant-based milk alternatives target hydration and nutritional supplementation for active toddlers.
Purees retain volume leadership; snacks hold the steepest expansion curve.
Age Group:
Cost tier stratification intensifies as parents trade up from economy-positioned newborn formulas to premium toddler snacks, creating margin compression for mid-tier infant offerings caught between commodity and specialty positioning.
- Infants:Four to twelve months represents the highest regulatory scrutiny segment, with FDA and EFSA micronutrient fortification mandates constraining formulation flexibility. USDA Organic certification commands strongest willingness-to-pay among first-time parents in California and New York.
- Toddlers:Twelve to thirty-six months unlocks the broadest product format diversity, from pouched purees to handheld snacks. German-speaking markets show particular concentration for chilled organic meals delivered through subscription platforms.
- Pre-School:Three to five years bridges into conventional children's nutrition, with organic positioning competing against established snack brands.
- Newborns:Birth to four months centers on formula and breast milk supplementation, with limited organic processed food penetration.
Infants anchor revenue concentration; toddlers are climbing the fastest.
Packaging Type:
Volume concentration favors formats that minimize per-unit shipping costs while maximizing retail shelf efficiency, with sustainability credentials increasingly influencing format selection in environmentally conscious markets.
- Pouches:Flexible spouted films reduce shipping weight by sixty percent versus glass alternatives and enable single-hand feeding. Urban millennial parents in the United States and China prioritize this format for commute-heavy routines.
- Glass jars:Fully recyclable rigid containers retain loyalty in Germany and Scandinavia, where environmental regulations and consumer preferences sustain demand despite higher logistics costs.
- Tetra packs:Aseptic cartons extend ambient shelf life for beverage and cereal applications.
- Plastic containers:Reusable rigid formats serve bulk cereal and snack storage needs.
Pouches dominate volume; glass jars sustain premium positioning in select markets.
Distribution Channel:
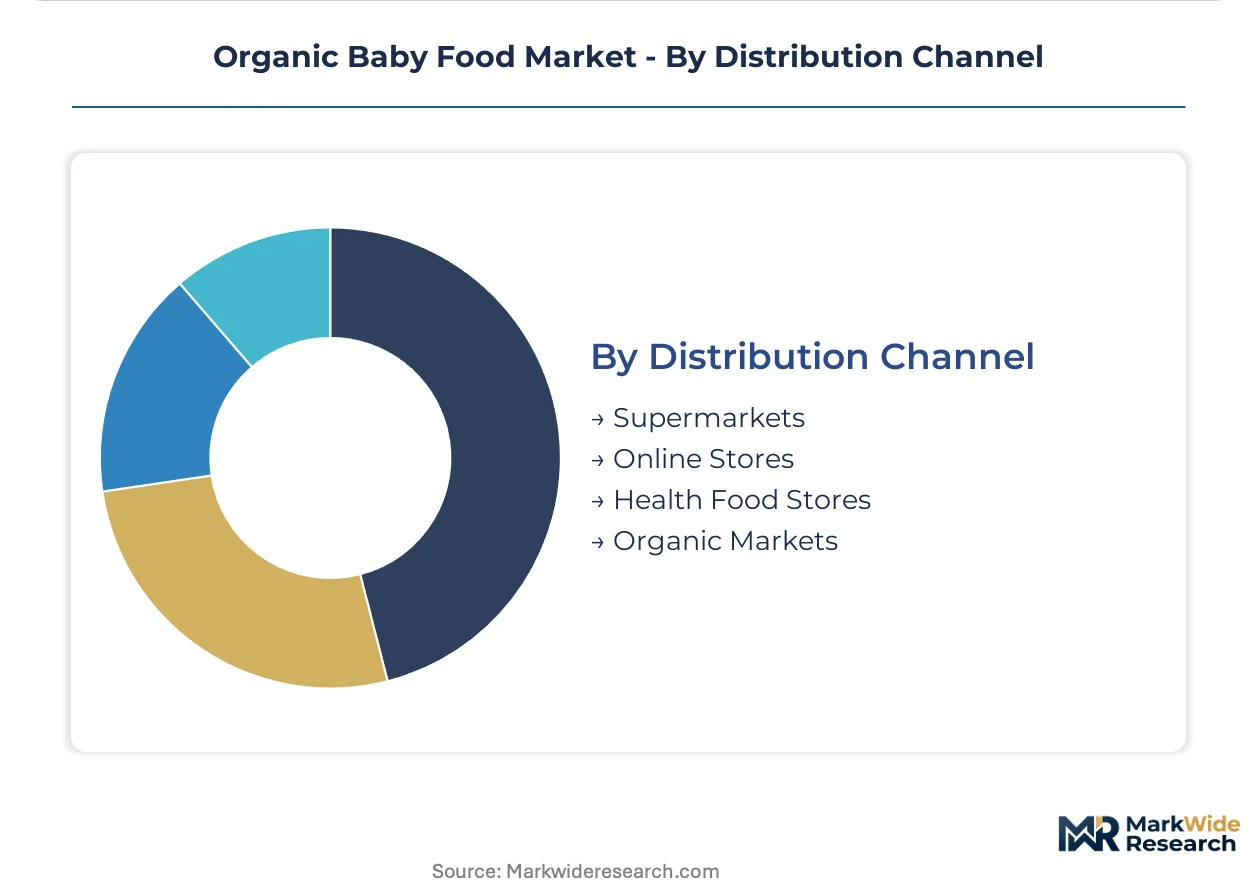
Customer data ownership is shifting toward manufacturers as direct-to-channel platforms displace conventional grocery intermediaries, fragmenting volume between mass retail and subscription-based replenishment.
- Online Stores:Subscription platforms and marketplace aggregators capture recurring revenue through predictive replenishment algorithms. Millennial parents in Shanghai and Beijing show highest penetration for imported organic brands.
- Supermarkets:Mass retail chains maintain volume leadership through dedicated baby food aisles and promotional velocity. Premium shelf space expansion in the United States concentrates organic offerings in coastal urban markets.
- Health Food Stores:Specialty retailers curate certified organic assortments for discerning parent segments.
- Organic Markets:Dedicated organic grocers reinforce provenance narratives through local sourcing partnerships.
Supermarkets retain volume leadership; online stores gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence defines competitive positioning across organic baby food markets. Germany and the United States maintain net export positions through certified supply chain infrastructure, while China absorbs premium imports to satisfy safety-conscious parent demand.
United States
Subscription platforms capture recurring revenue from millennial parents in coastal metros. USDA National Organic Program enforcement tightens residue thresholds beyond baseline requirements. California's Central Valley concentrates certified fruit and vegetable supply, exposing processors to climate-driven harvest volatility.
Germany
Three-generation brand loyalty sustains premium chilled segment demand in German-speaking markets. EU Regulation 2018/848 mandates blockchain-verified supply chain documentation accessible within seventy-two hours. Bavaria anchors production clusters where high-pressure processing adoption outpaces thermal sterilization.
China
Shanghai and Beijing concentrate demand for imported organic infant nutrition as safety scarring persists. SAMR organic food certification creates parallel compliance requirements for foreign entrants. Tier-one city premium retail expansion creates dedicated shelf space that domestic brands struggle to access.
United Kingdom
Online marketplace penetration accelerates fastest among London and Southeast England parent cohorts. EFSA nutritional guidelines constrain micronutrient fortification claims for infant formulations. Midlands distribution hubs process chilled organic meals for subscription cold chain networks.
France
Île-de-France parents trade up to premium organic positioning through pharmacy and specialty retail channels. ANSM oversight of infant nutrition maintains strict formulation registration requirements. Auvergne-Rhône-Alpes organic dairy cooperatives supply base ingredients for chilled puree production.
Organic Baby Food Market Vendor Landscape
Listed leaders compete with private specialists across certification depth and channel control. Consolidation pressures concentrate among mid-tier processors lacking dedicated regulatory technology infrastructure. Three archetypes dominate: multinational diversified nutrition conglomerates, European heritage organic specialists, and direct-to-consumer platform-native brands. Competitive moves center on backward integration into certified organic supply chains and predictive replenishment algorithm deployment.
Within the heritage organic tier, HiPP GmbH & Co. Vertrieb KG exemplifies three-generation brand equity accumulation. Among diversified nutrition conglomerates, Danone S.A. and Nestlé S.A. occupy positions spanning chilled and ambient segments through controlled sourcing networks. These three entities represent distinct strategic postures: family-owned certification depth versus scale-driven geographic reach versus Latin American farm network control.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Danone S.A. |
| The Hain Celestial Group |
| Abbott Laboratories |
| Hero Group |
| HiPP GmbH & Co. Vertrieb KG |
| Kraft Heinz Foods Company |
| Sprout Organic Foods Inc. |
| Baby Gourmet Foods Inc. |
| Others |
Supply Flow & Price Mechanics
Ninety-day ingredient lot traceability windows compress margin structures as California's Central Valley and select Mediterranean growing regions concentrate certified organic supply, amplifying processor exposure to climate-driven harvest volatility and reinforcing long-term contracting relationships with limited supplier pools.
Pricing Analysis
Subscription-first millennial parents anchor a three-tier pricing structure across premium, standard, and economy levels, with USDA Organic and EU Regulation 2018/848 certification tiers commanding substantial premiums over uncertified alternatives. Price differentiation rests on residue threshold compliance and single-origin provenance claims rather than formulation complexity alone. Cost compression in mid-tier pouches is intensifying because glass jar loyalty in German-speaking markets traps manufacturers in dual-format production overhead. First-time parents in coastal United States metros show least price sensitivity, while mass-market supermarket shoppers in China's tier-two cities exhibit highest elasticity.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes compound inbound logistics costs for processors sourcing organic fruit purees from Latin American farm networks. Certified ingredient supply draws from the United States, Germany, and select Mediterranean cooperatives, with base puree concentrates and spouted pouch films representing critical input dependencies. Single-source vulnerability concentrates in California's Central Valley organic vegetable supply, where three-year conversion requirements prevent rapid supplier diversification. Distribution runs through subscription cold chain networks and premium retail shelf space allocation, with direct-to-consumer platforms capturing customer data ownership from traditional grocery intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward subscription-platform aggregators as millennial parents consolidate purchasing decisions through predictive replenishment algorithms, fragmenting volume concentration that previously favored mass retail chains.
For Market Incumbents: Compound certification depth through preemptive investment in blockchain-verified supply chain documentation ahead of EU Regulation 2018/848 enforcement deadlines, while anchoring chilled segment positioning through high-pressure processing capacity additions in Bavaria and California production clusters. Direct-to-consumer channel control represents the critical defensive lever against platform-native entrants capturing customer data ownership. For New Entrants and Emerging Players: Lead with toddler snack convergence targeting allergen-free finger-food white space between purees and conventional children's snacks, where incumbent brand equity remains weakest. China's tier-one cities offer the most penetrable geography for imported organic positioning, with pharmacy and specialty retail channels providing credible go-to-market pathways that bypass domestic brand shelf dominance. For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because residue threshold tightening across USDA Organic, EU Organic, and China Organic Food regimes will consolidate compliant processor capacity while fragmenting non-compliant competitors. Acquisition targets should emphasize mid-tier processors with legacy ERP systems requiring regulatory technology infrastructure overlay. The signal to watch is state-level organic standard harmonization momentum in California and Washington, which would accelerate national baseline tightening and compress launch windows for non-compliant entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Farms | Captures three-year conversion timelines and locks in residue-compliant ingredient supply ahead of competitor entry. |
| High-Pressure Processing Capacity Expansion | Enables premium chilled segment positioning in German-speaking markets where thermal sterilization faces displacement. |
| Blockchain Supply Chain Documentation Deployment | Satisfies EU Regulation 2018/848 seventy-two-hour audit trail requirements for organic input lot traceability. |
| Direct-to-Consumer Subscription Platform Launch | Concentrates customer data ownership and enables predictive flavor preference algorithms mass retail cannot replicate. |
| State-Level Organic Standard Pre-Compliance | Creates early-mover advantage before California and Washington residue thresholds harmonize upward to national baselines. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with organic baby food brand managers, retail category buyers, supply chain planners, and certification body auditors; and secondary validation through USDA National Organic Program enforcement records, EU Regulation 2018/848 implementation guidance, FDA infant formula filings, and Nielsen retail audit data. Bottom-up volume modeling triangulated against top-down market sizing across product type, age group, packaging format, and distribution channel dimensions.
Across the analysis window, forecasts employed segmented growth rate derivation by feeding-stage transition intensity, certification penetration by geography, and channel shift velocity from mass retail to subscription replenishment. Modeled dimensions included puree versus snack versus cereal product types, infant versus toddler versus pre-school age groups, pouch versus glass jar versus tetra pack packaging formats, and online versus supermarket versus specialty retail channels. CAGRs were derived from historical trajectory analysis adjusted for regulatory enforcement phase-in schedules and cold chain infrastructure buildout rates.
Forecasts assume regulatory continuity in USDA Organic, EU Organic, and China SAMR organic food regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Indonesia Infant Nutrition Market
Baby Food and Infant Formula
Goat Milk Formula Market
Baby Food and Infant Formula
Anti-Spit Up Formula Market
Baby Food and Infant Formula
Baby Formula Market
Baby Food and Infant Formula
Infant Formula Ingredients Market
Baby Food and Infant Formula
South America Baby Food Market
Baby Food and Infant Formula
Europe Baby Food and Infant Formula Market
Baby Food and Infant Formula
Kids Food and Beverages Market
Baby Food and Infant Formula
India Baby Food Market
Baby Food and Infant Formula
Growing Up Milk Market
Baby Food and Infant Formula
Growing Up Formula Market
Baby Food and Infant Formula
Baby Food Testing Market
Baby Food and Infant Formula
Europe Organic Baby Food Market
Baby Food and Infant Formula
Vietnam Pet Food Market
Baby Food and Infant Formula
Infant Food Compliance Ready Fertility Input Market
Baby Food and Infant Formula
West Africa Baby Food Market