
 West Africa Baby Food Market | 2026-2036
West Africa Baby Food Market Size, Share, and Industry Trends Forecast 2026-2036
West Africa Baby Food Market Analytics
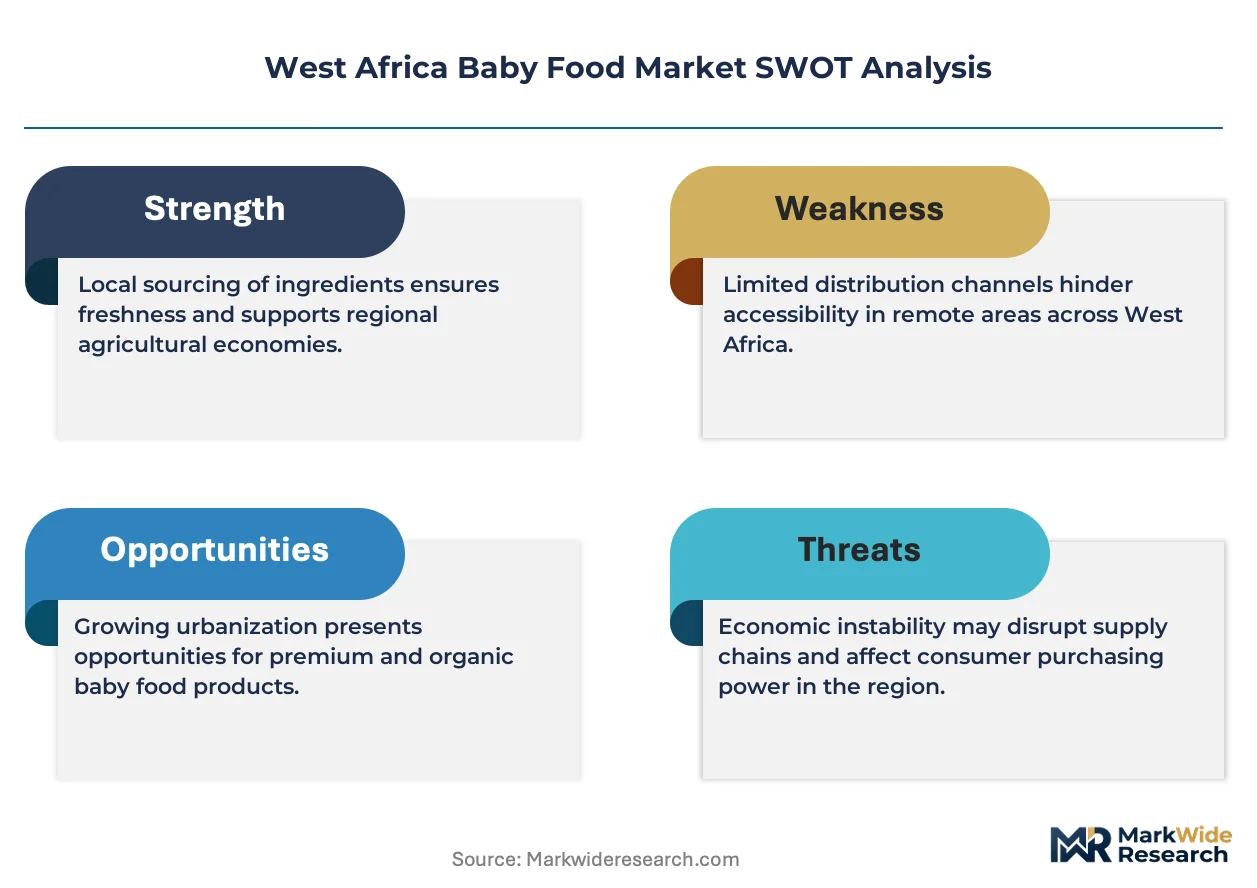
Codex Alimentarius HACCP certification for infant formula manufacturers is collapsing the supplier base to multinationals with in-house laboratory capacity. FrieslandCampina leverages its Nigerian dairy processing infrastructure to control raw milk sourcing for local production. Nestlé sustains brand trust through its NAN and Cerelac lines, which dominate pharmacy and modern trade channels across francophone and anglophone markets. Promasidor competes on price-accessibility with its Cowbell brand, extending powdered milk familiarity into infant nutrition segments.
West Africa baby food comprises nutritionally formulated products for infants and toddlers, typically fortified with iron, zinc, vitamin A, and essential fatty acids to bridge dietary gaps in cereal-based weaning diets. These products serve dual commercial purposes: preventing micronutrient deficiency in children under twenty-four months while offering convenience to time-constrained urban caregivers. The product type dimension shows cereals occupying the volume core due to cassava and maize raw material proximity, though pouches within packaging type command margin premiums through portability and extended shelf stability. Distribution channel dynamics favor supermarkets and convenience stores in coastal capitals, while sachet-based economy tiers penetrate inland via open-air markets and kiosk networks.
The Economic Community of West African States Commission harmonizes food fortification mandates through its Regional Standard for Infant Formula, while Nigeria's National Agency for Food and Drug Administration and Control enforces pre-market registration and factory inspections. Ghana's Food and Drugs Authority adds Ghana Standards Authority microbiological testing protocols that delay market entry for uncertified importers. Stakeholders must monitor ECOWAS tariff implementation timelines and local currency volatility against euro-denominated ingredient costs to calibrate pricing and sourcing commitments.
Market Dynamics
The Codex Alimentarius HACCP certification mandate is collapsing the supplier base toward multinationals with captive laboratory infrastructure, while working mothers in Lagos and Accra accelerate demand for ready-to-feed formats.
Growth Catalysts
- ECOWAS Regional Standard for Infant Formula:Harmonized fortification mandates across member states reduce regulatory fragmentation and accelerate cross-border product registration for compliant manufacturers.
- Urban pharmacy chain expansion:HealthPlus and MedPlus in Nigeria extend dedicated infant nutrition shelf space, creating premium positioning opportunities for certified brands.
- Cassava and maize raw material proximity:Local cereal processors in Ghana and Côte d'Ivoire exploit feedstock adjacency to compress production costs versus imported alternatives.
Market Restraints
- Euro-denominated ingredient cost volatility:Whey protein and specialized lipid concentrates expose margins to European Central Bank rate movements and currency mismatches.
- Laboratory infrastructure concentration:HACCP-compliant testing capacity clusters in South Africa and North Africa, creating bottlenecks for West African entrants seeking certification.
- Traditional complementary feeding persistence:Family-prepared porridges using fermented maize and sorghum retain cost advantages in rural hinterlands.
Strategic Opportunities
- Abidjan modern retail underpenetration:Carrefour and Casino expansion lags Lagos and Accra, creating first-mover shelf space for compliant entrants in Côte d'Ivoire.
- Sachet-based economy tier distribution:Open-air market networks in northern Nigeria and Burkina Faso remain unserved by pharmacy-centric multinationals.
- Nigeria's NAFDAC pre-market registration:Accelerated factory inspection protocols for ECOWAS-harmonized standards reward early compliance investments with faster approval timelines.
Industry Challenges
- Microbiological testing talent scarcity:Ghana Standards Authority protocols require specialized technicians that domestic universities fail to produce at sufficient scale.
- Cold chain capex for ready-to-feed pouches:Last-mile refrigeration infrastructure in humid coastal climates demands capital deployment that sachet competitors avoid.
- Label translation complexity:ECOWAS bilingual French-English requirements multiply packaging SKUs and complicate inventory management for regional distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | West Africa Baby Food Market |
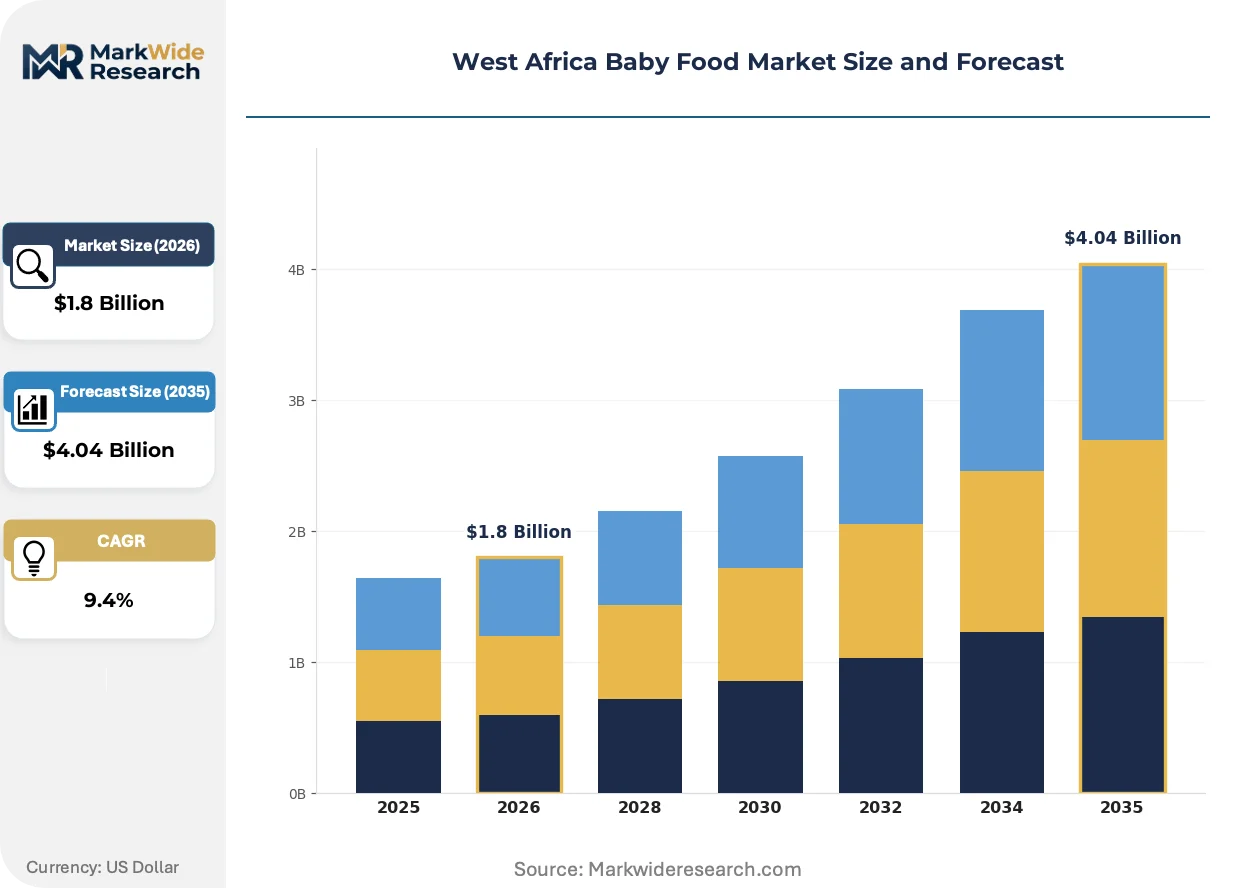
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereals, Purees, Snacks, Beverages Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Shops Packaging Type: Pouches, Jars, Tubs, Cans Price Tier: Premium, Mid-Range, Economy, Value Packs |
| Companies Covered | FrieslandCampina, PZ Cussons, Nestlé, Reckitt Benckiser Group plc, The Kraft Heinz Company, Danone S.A., Promasidor, Kendal Nutricare Limited, Abbott, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
West Africa Baby Food Market Evolving Landscape
Ready-to-feed packaging formats and micronutrient delivery systems are reshaping competitive positioning, while regulatory convergence and channel fragmentation create divergent investment requirements across the value chain.
Retort pouch technology is bifurcating the packaging landscape. This aseptic processing method enables ambient-stable complementary foods without refrigeration. Urban Nigerian caregivers in Lagos and Abuja adopt pouches for portability during commutes. The format compresses traditional canning economics while enabling margin premiums through convenience positioning.
Ghana's Food and Drugs Authority has tightened Ghana Standards Authority microbiological testing protocols for imported infant formula. This regulatory friction delays market entry for uncertified suppliers. Pharmacy chains in Accra and Tema now demand documented compliance certificates before contract negotiations, favoring established multinationals with regulatory affairs departments.
Modern trade procurement is consolidating shelf space decisions toward category managers with data analytics capabilities. Supermarket buyers in Abidjan and Dakar now require scan-data proof of velocity before allocating end-cap positioning. This behavior compresses traditional broker networks and rewards direct manufacturer relationships with measurable retail execution metrics.
West Africa Baby Food Market Segmentation
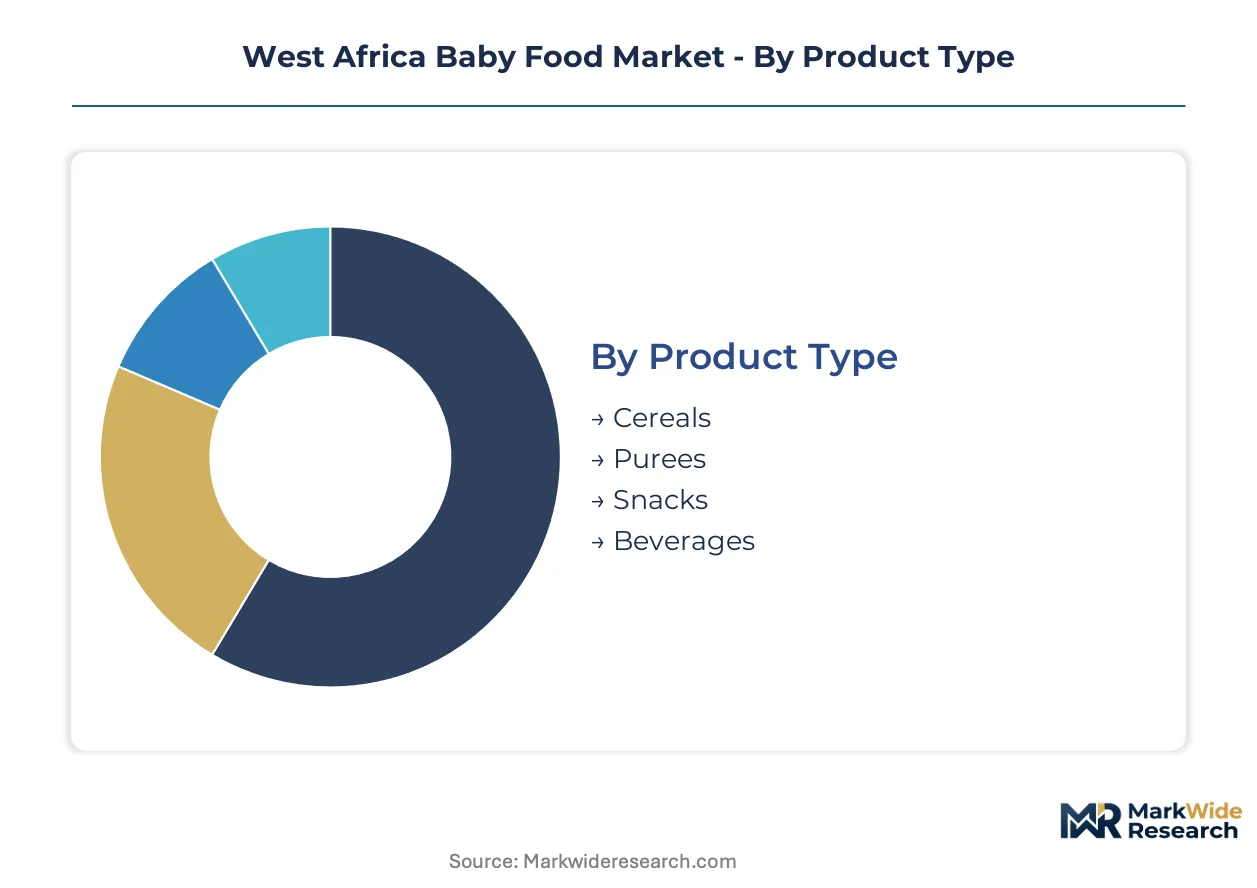
Segmentation in West Africa baby food reveals how regulatory compliance and channel access create divergent commercial outcomes across product formats. Each dimension carries distinct substitution pressures from traditional feeding practices and informal supply chains.
Product Type:
Family-prepared porridges using fermented maize and sorghum exert the strongest substitution pressure on packaged formats, with penetration varying sharply by urban density and maternal employment status.
- Cereals:Fortified grain-based formulations incorporating cassava, maize, and rice as primary substrates. Demand concentrates in Lagos and Accra pharmacy chains where working mothers seek iron-fortified weaning solutions that comply with ECOWAS Regional Standard for Infant Formula micronutrient mandates.
- Purees:Fruit and vegetable-based smooth preparations targeting complementary feeding stages. Adoption clusters in Abuja and Dakar modern trade channels where shelf-stable pouches displace home-blended alternatives for time-constrained urban caregivers.
- Snacks:Finger foods and teething biscuits for toddlers.
- Beverages:Ready-to-drink nutritional formulations for infants.
Cereals anchors the volume base while Purees gains share at the steepest rate.
Distribution Channel:
Channel selection directly determines margin capture, with modern trade extracting data-driven terms while informal networks preserve price accessibility in peri-urban zones.
- Supermarkets:Organized retail formats with category management protocols. HealthPlus and MedPlus in Nigeria now require scan-data velocity proof before allocating end-cap positioning for infant formula, compressing traditional broker networks.
- Convenience Stores:Small-format urban retailers with limited refrigeration. Penetration concentrates in Lagos Island and Accra Osu where sachet-based economy tiers reach working-class neighborhoods faster than pharmacy-centric multinationals.
- Online Retail:E-commerce platforms and direct-to-consumer delivery services.
- Specialty Shops:Dedicated mother-and-baby retailers with consultative service models.
Supermarkets dominate value capture while Convenience Stores expand most quickly into underserved catchments.
Packaging Type:
Packaging technology separates ambient-stable formats requiring capital-intensive retort lines from economy tiers that bypass cold chain infrastructure entirely.
- Pouches:Flexible laminated retort packaging enabling aseptic processing without refrigeration. Lagos commuters adopt these for portability during transit, though humid coastal climates challenge last-mile distribution economics.
- Jars:Glass containers with vacuum-sealed lids. Ghana Standards Authority microbiological testing protocols favor established suppliers with documented compliance certificates, delaying entry for uncertified importers.
- Tubs:Rigid plastic containers for powdered cereals.
- Cans:Metal packaging for liquid concentrates and follow-on formulas.
Jars retains the largest installed base while Pouches demonstrates the steepest expansion trajectory.
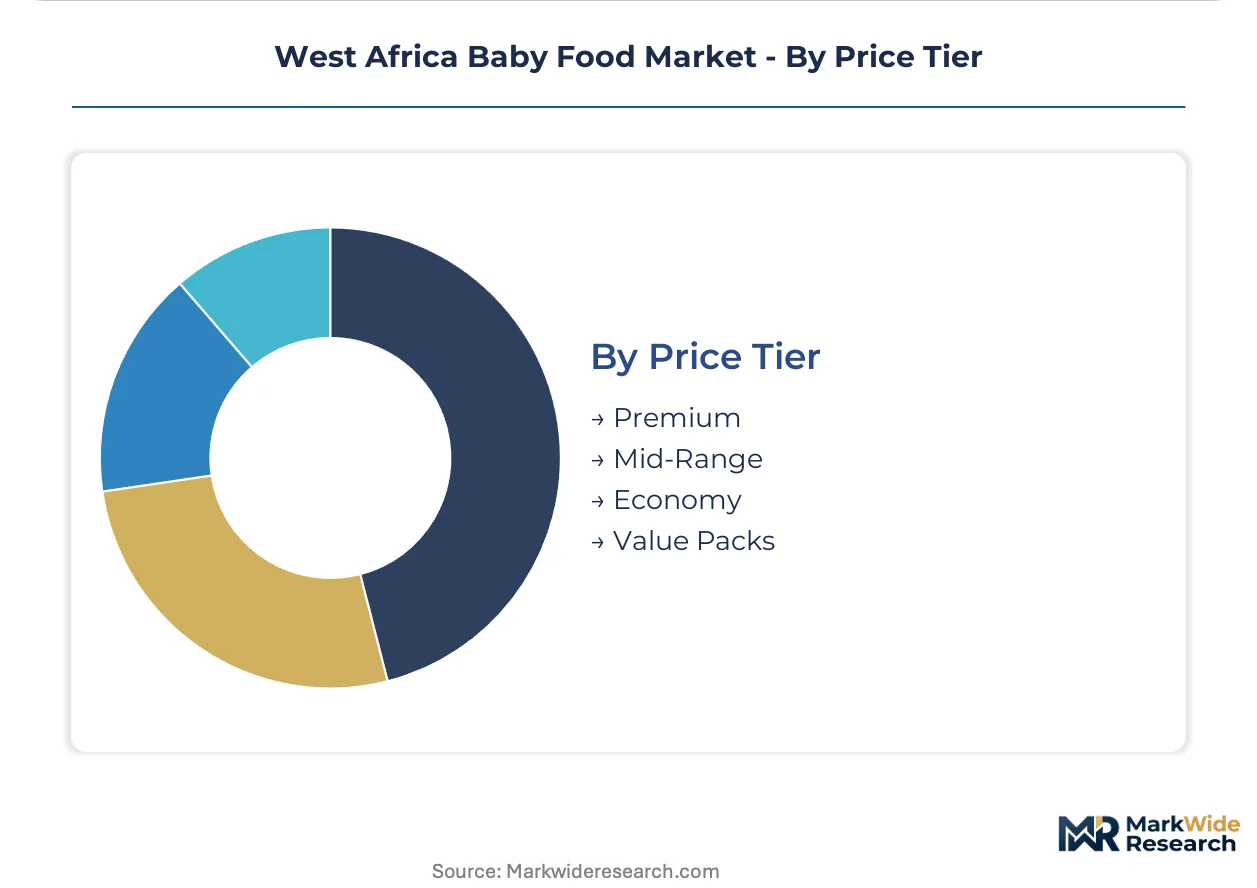
Price Tier:
Price stratification reflects certification grade and volume scale more than ingredient quality differentiation, with HACCP compliance costs filtering supplier participation at premium levels.
- Premium:HACCP-certified formulations with documented micronutrient testing. NAFDAC pre-market registration requirements and factory inspection protocols reward early compliance investments with faster approval timelines for Lagos and Abuja pharmacy chains.
- Mid-Range:Standard fortification meeting baseline ECOWAS standards. Distribution concentrates in Accra and Abidjan supermarket channels where private-label expansion pressures branded alternatives.
- Economy:Basic fortified cereals in sachet formats.
- Value Packs:Bulk packaging for multi-child households in northern Nigeria and Burkina Faso open-air markets.
Premium commands margin concentration while Economy reaches the broadest geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Working mothers in Lagos, Accra, and Abidjan anchor regional demand for ready-to-feed formats, while ECOWAS harmonization accelerates cross-border product registration for compliant manufacturers. Urban pharmacy chains and modern retail expansion concentrate purchasing power in coastal capitals with limited cold chain reach inland.
Nigeria
Lagos and Abuja working mothers drive adoption of iron-fortified cereals and retort pouches for commute convenience. NAFDAC enforces pre-market registration and factory inspection protocols that reward early HACCP compliance with faster approval timelines. Northern Nigeria open-air markets remain underserved by pharmacy-centric multinationals, creating sachet-tier opportunities.
Ghana
Accra and Tema urban caregivers seek shelf-stable complementary foods as pharmacy chains expand dedicated infant nutrition shelf space. The Food and Drugs Authority applies Ghana Standards Authority microbiological testing protocols that delay entry for uncertified importers. Cassava feedstock proximity enables local cereal processors to compress production costs versus imported alternatives.
Côte d'Ivoire
Abidjan modern retail penetration lags Lagos and Accra, leaving first-mover shelf space for compliant entrants at Carrefour and Casino locations. The country's national food regulator aligns with ECOWAS Regional Standard for Infant Formula fortification mandates. Pharmacy channel development in Cocody and Plateau districts favors documented compliance certificates from established suppliers.
Senegal
Dakar middle-class households adopt premium HACCP-certified formulations through expanding supermarket networks. The country's national pharmaceutical regulator enforces bilingual French-English labeling requirements that multiply packaging SKUs for regional distributors. Médina and Almadies districts concentrate modern trade procurement with scan-data velocity requirements.
Burkina Faso
Ouagadougou and Bobo-Dioulasso peri-urban zones retain traditional fermented maize porridges due to cost advantages and limited cold chain infrastructure. ECOWAS tariff implementation timelines create pricing volatility against euro-denominated ingredient costs. Open-air market networks in the Central Plateau remain penetration targets for sachet-based economy tiers.
West Africa Baby Food Market Competitive Landscape
Player mix skews toward multinational nutrition conglomerates with captive laboratory infrastructure and regional dairy processing assets. Market structure concentrates around three to four vertically integrated groups controlling raw milk sourcing and distribution networks. Two strategic archetypes dominate: HACCP-certified premium formulators with pharmacy chain relationships, and price-accessible powdered milk extenders leveraging existing brand familiarity. Competitive moves center on backward integration into local dairy processing and accelerated NAFDAC registration timelines.
Among the HACCP-certified tier, FrieslandCampina and Nestlé exemplify multinational archetypes with established regulatory affairs capacity, while Promasidor occupies a position within the price-accessible segment leveraging powdered milk brand recognition. These three anchors represent divergent competitive vectors: laboratory infrastructure investment versus distribution network density versus brand extension economics.
| Leading Market Players |
|---|
| FrieslandCampina |
| PZ Cussons |
| Nestlé |
| Reckitt Benckiser Group plc |
| The Kraft Heinz Company |
| Danone S.A. |
| Promasidor |
| Kendal Nutricare Limited |
| Abbott |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements with European whey protein suppliers lock in both supply access and price visibility for Nigerian infant formula manufacturers, insulating margins against euro volatility while committing capital to fixed-volume contracts.
Pricing Analysis
Cost-plus contracts indexed to European Central Bank rate movements dominate premium tier procurement, passing currency risk through to Lagos pharmacy chains. Certification grade and volume scale separate HACCP-compliant NAN and Cerelac positioning from Promasidor's sachet-tier Cowbell extensions. Pricing pressure stems from euro-denominated whey protein and specialized lipid concentrate exposure, compressing margins for importers without captive laboratory infrastructure. Rural peri-urban caregivers in northern Nigeria exhibit highest price sensitivity, while Accra and Lagos working mothers in formal employment show lowest elasticity for ready-to-feed pouch convenience.
Supply Chain Analysis
Port congestion at Apapa and Tema harbors elevates inbound logistics costs for retort pouch laminates and specialized lipid concentrates sourced from European chemical processors. Manufacturing concentrates in the Netherlands, Germany, and France for whey protein isolates, while Ghana and Côte d'Ivoire exploit cassava and maize feedstock proximity for local cereal processing. Single-source vulnerability runs through ECOWAS-harmonized laboratory testing capacity clustered in South Africa. Distribution runs through pharmacy chain procurement offices in Lagos and Accra, with open-air market networks bypassing formal cold chain entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ECOWAS regulatory harmonization is transforming West Africa baby food into a platform economy where NAFDAC pre-market registration and HACCP certification create interoperability barriers for non-compliant suppliers.
For Market Incumbents: Fortify laboratory infrastructure investments to maintain NAFDAC accelerated approval timelines against emerging local processors. Backward integration into Nigerian dairy processing, following FrieslandCampina's raw milk sourcing model, secures supply continuity. Channel control through HealthPlus and MedPlus shelf space contracts defends premium positioning against private-label expansion.
For New Entrants and Emerging Players: Differentiate on sachet-based economy tier distribution through open-air market networks in northern Nigeria and Burkina Faso, where pharmacy-centric multinationals remain absent. Target Abidjan modern retail underpenetration at Carrefour and Casino locations for first-mover shelf space. Go-to-market through regional distributors with ECOWAS bilingual packaging capabilities bypasses direct regulatory affairs investment.
For Investors and Strategic Acquirers: Local cereal processors with Ghana Standards Authority compliance certificates and cassava feedstock adjacency offer acquisition targets with cost-compressed production economics. Long-term viability hinges on regulatory convergence durability across the analysis window. Watch ECOWAS tariff implementation timelines against euro-denominated ingredient costs as margin inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| HACCP Certification Investment | NAFDAC accelerated approval timelines reward early compliance with faster market entry. |
| Backward Integration into Dairy Processing | FrieslandCampina's Nigerian infrastructure model secures raw milk sourcing control. |
| Sachet-Based Economy Tier Distribution | Open-air market networks in northern Nigeria bypass pharmacy-centric multinational dominance. |
| Retort Pouch Manufacturing Scale-Up | Aseptic processing enables ambient-stable formats for Lagos commuter convenience demand. |
| ECOWAS Bilingual Packaging Capability | French-English label compliance multiplies SKU reach across francophone and anglophone markets. |
Research Methodology
Operator-level perspectives from brand managers at multinational nutrition conglomerates, category buyers at HealthPlus and MedPlus pharmacy chains, NAFDAC regulatory affairs consultants, and supply planners at Ghanaian cereal processors anchored the qualitative base. Secondary validation drew from NAFDAC pre-market registration databases, Ghana Standards Authority microbiological testing protocols, ECOWAS Regional Standard for Infant Formula documentation, Nielsen retail audit data for Lagos and Accra modern trade channels, and customs records for whey protein concentrate imports. Bottom-up volume triangulation across product type, packaging format, and distribution channel segments converged with top-down macroeconomic anchoring.
Sensitivity analysis tested forecast robustness across euro volatility scenarios and ECOWAS tariff implementation timelines. The analytical framework modeled segmentation dimensions including product type, packaging technology, distribution channel, price tier, and urban density cluster across the projection horizon. CAGRs derived from regression-based trend extrapolation calibrated against historical pharmacy chain scan-data velocity and working mother labor force participation rates in Lagos, Accra, and Abidjan.
Forecasts assume regulatory continuity in NAFDAC pre-market registration protocols and ECOWAS harmonization implementation; material policy shifts would require re-modeling. Currency mismatch exposure against euro-denominated ingredient costs and cold chain infrastructure deployment delays in humid coastal climates represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Infant Formula Milk Powder with A2 Beta-Casein Market
Baby Food and Infant Formula
Baby Food Testing Market
Baby Food and Infant Formula
Baby Food and Infant Formula Market
Baby Food and Infant Formula
Follow on Formula Milk Market
Baby Food and Infant Formula
Fortified Pet Food Market
Baby Food and Infant Formula
Pureed Food Market
Baby Food and Infant Formula
Omega 3 Ingredients for Infant Food Market
Baby Food and Infant Formula
Russia Pet Food Market
Baby Food and Infant Formula
Europe Baby Food Market
Baby Food and Infant Formula
North America Baby Food and Infant Formula Market
Baby Food and Infant Formula
Baby Food Products Market
Baby Food and Infant Formula
Organic Baby Food Market
Baby Food and Infant Formula
Middle-Aged and Elderly Milk Powder Market
Baby Food and Infant Formula
Baby Food Market
Baby Food and Infant Formula
Hydrolyzed Formula Milk Powder Market
Baby Food and Infant Formula
Baby Infant Formula Market