
 Baby Food Market | 2026-2036
Baby Food Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Food Market Analysis
EU MDR is decoupling legacy product portfolios from shelf-ready compliance, forcing reformulation investments that smaller brands struggle to fund. Nestlé leverages its captive dairy supply chains to absorb margin pressure from stricter contaminant testing. Danone differentiates through specialized hypoallergenic lines that command premium positioning. HiPP anchors its competitive stance on biodynamic certification standards that exceed baseline regulatory floors.
Baby food comprises processed or prepared nutritional products formulated for infants and toddlers, typically manufactured through thermal treatment, homogenization, and aseptic packaging to achieve microbiological safety and nutrient stability. These products serve as transitional or supplementary feeding solutions designed to meet developmental caloric and micronutrient requirements during early childhood. Pouch formats are capturing volume share from glass jars due to portability advantages and reduced shipping weight, though jarred products retain preference among parents prioritizing chemical leaching avoidance. Organic ingredient claims concentrate margin pools in fruits and vegetables, while grain-based entries face commoditization from private-label competition. Freeze-dried segments attract R&D investment for nutrient preservation, yet powder formulations dominate cost-sensitive channels.
FDA infant formula regulations, EU MDR, and China's SAMR national food safety standards collectively elevate barrier costs for cross-border market entry and ongoing compliance. These frameworks mandate specific protein ratios, heavy metal limits, and labeling disclosures that reshape product development cycles and geographic rollout sequencing. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and anticipate where harmonization or fragmentation will determine competitive mobility.
Market Dynamics
Dual-income household proliferation is compressing meal preparation time windows while elevating nutritional scrutiny, forcing manufacturers to reconcile convenience engineering with clean-label ingredient sourcing across all price tiers.
Growth Catalysts
- EU MDR contaminant thresholds:Stricter residue limits for heavy metals in infant cereals are accelerating third-party testing adoption and creating compliance-based competitive moats for accredited producers.
- Freeze-drying technology:Nutrient preservation capabilities in ambient-stable formats are unlocking direct-to-consumer subscription channels previously inaccessible to thermal-processed entries.
- China urban middle-class:Premiumization demand for imported organic formulations is pulling cross-border e-commerce volumes and specialized cold-chain logistics investment.
Market Restraints
- Organic dairy input volatility:Pasture-based supply constraints in New Zealand and the Netherlands are transmitting price shocks through formula cost structures.
- Glass jar shipping density:Weight-to-volume inefficiency versus pouch alternatives is eroding margin on legacy SKUs in distant export markets.
- FDA infant formula recall protocols:Post-2022 enforcement tightening has extended batch release timelines and elevated liability insurance carry costs.
Strategic Opportunities
- India FSSAI organic certification:Emerging middle-class parents in Mumbai and Bangalore present first-mover advantage for imported brands establishing local blending facilities.
- Biodynamic ingredient premiums:Certification tiers exceeding EU organic baselines command shelf price multiples in German and Austrian specialty retail.
- Pharmacy channel integration:Pediatrician recommendation networks in France and Italy are converting clinical credibility into recurring purchase velocity.
Industry Challenges
- Microbiologist talent scarcity:Aseptic processing expertise concentrated in dairy heartlands limits geographic expansion of manufacturing footprints.
- SAMR registration timelines:China's national food safety standard approval cycles strand inventory and compress product lifecycle returns.
- Legacy ERP integration:Lot-traceability mandates under EU MDR clash with decades-old batch recording systems at mid-tier processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Food Market |
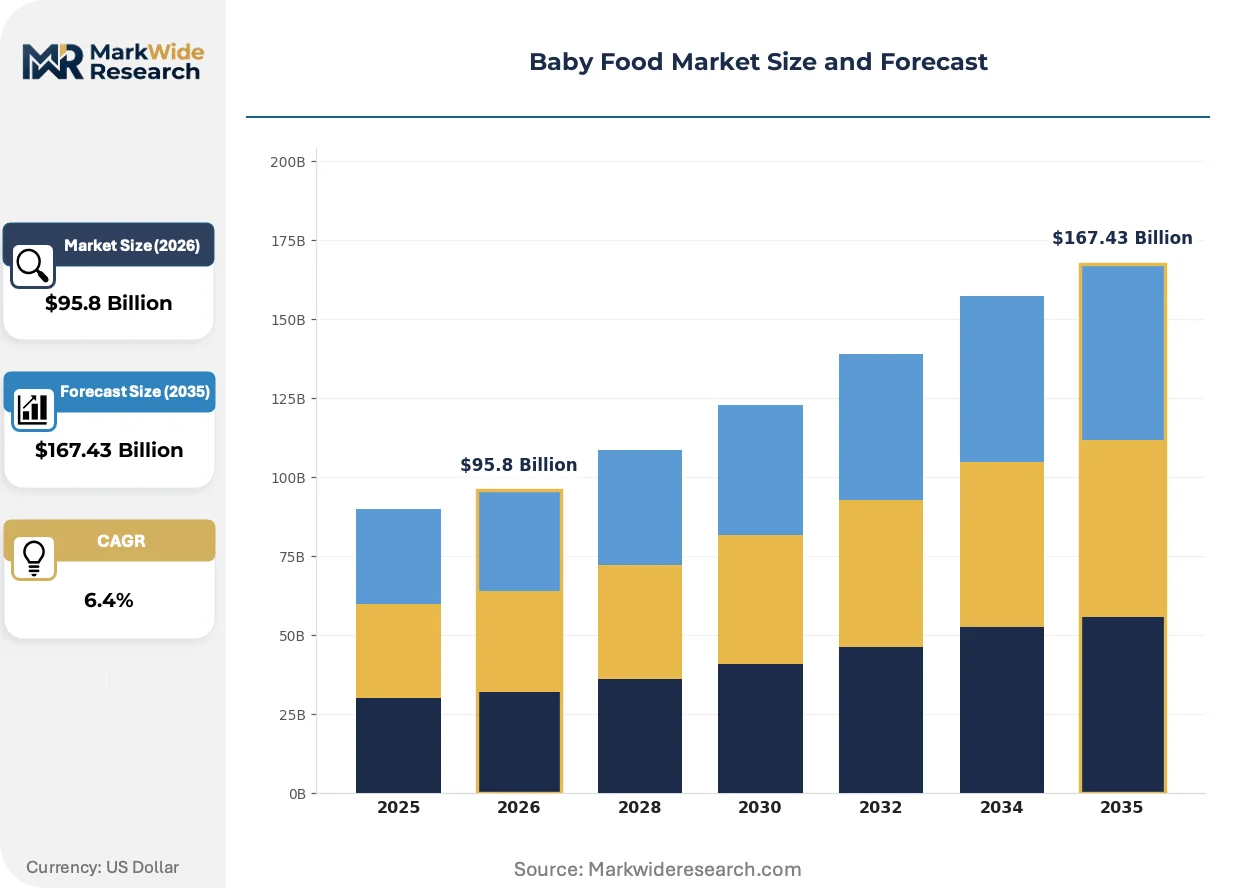
| Market Size in 2026 | $95.8 Billion |
| Market Size in 2035 | $167.43 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purees, Finger Foods, Snacks, Beverages Form: Jarred, Pouch, Powder, Freeze-Dried Ingredient: Fruits, Vegetables, Meat, Grains Packaging Type: Glass Jars, Plastic Containers, Flexible Pouches, Tetra Packs |
| Companies Covered | Reckitt Benckiser, HiPP, Nestlé, Gerber Products Company, The Hain Celestial Group, Danone, The Kraft Heinz Company, Beech-Nut Nutrition Corporation, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Food Market Emerging Trajectories
Reformulation imperatives are intersecting with packaging material science and procurement transparency demands to redefine competitive differentiation beyond traditional brand equity.
High-pressure processing is absorbing thermal degradation risks in fruit and vegetable purees while preserving enzyme activity valued by clean-label adherents. Premium-positioned parents in Seoul and Singapore are accepting refrigerated supply chain premiums for HPP-treated entries. This technology is absorbing volume share from retort pouches in the organic segment where nutrient density claims justify price elevation.
EU MDR device-classification spillover is extending to feeding accessories and nutrient delivery systems, compelling documentation upgrades previously confined to medical nutrition. Manufacturers serving both conventional and clinical channels face divergent compliance cost structures. Specialized hypoallergenic lines bear disproportionate burden from clinical evidence requirements.
Pediatric nutritionist consultation access is displacing unguided retail selection as the primary purchase trigger among first-time parents in Shanghai and Shenzhen. Subscription bundles integrating telehealth dietary guidance are capturing lifetime value through recurring shipment lock-in. This behavioral pivot is most visible in tier-one Chinese cities where premium import penetration already exceeds fifty percent.
Baby Food Market Segmentation
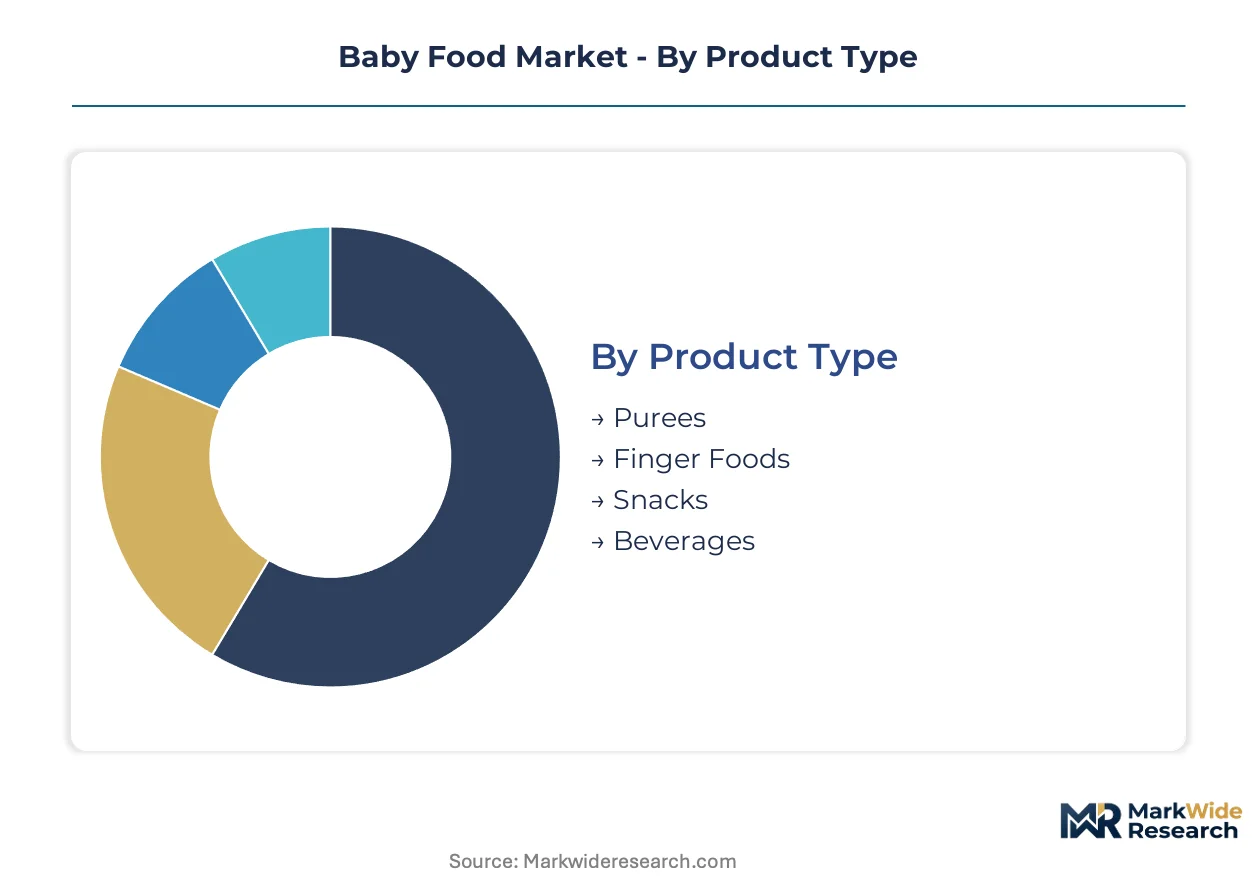
Baby food segmentation reveals divergent capital requirements across processing technologies and packaging formats. Manufacturers must align equipment investments with the shelf-stable versus fresh-prepared divide that separates mass-market from premium positioning.
Product Type:
Purees command the heaviest upfront investment in aseptic filling lines and thermal processing infrastructure.
- Purees:Thermally stabilized fruit and vegetable blends with controlled viscosity for developmental feeding stages. Demand concentrates in China's tier-one cities where SAMR-imported organic formulations attract dual-income households seeking convenience without nutritional compromise.
- Finger Foods:Textured solid formats designed for self-feeding skill development, typically baked or extruded with controlled moisture content. German and Austrian specialty retailers drive premiumization for clean-label entries with shortened ingredient decks.
- Snacks:Puffed or pressed portable formats targeting between-meal occasions.
- Beverages:Ready-to-drink nutritional formulations including follow-on milks and toddler smoothies.
Most installed capacity flows through Purees. Expansion is steepest in Finger Foods.
Form:
Jarred formats lock manufacturers into glass handling systems and retort infrastructure with limited flexibility.
- Jarred:Traditional glass-container presentations with vacuum-sealed thermal processing for extended ambient stability. Parents in France and Italy retain preference for chemical leaching avoidance, sustaining demand through pharmacy channel networks.
- Pouch:Flexible laminated film formats with spouted aseptic filling enabling single-hand feeding portability. Seoul and Singapore parents accept refrigerated supply chain premiums for HPP-treated organic entries with preserved enzyme activity.
- Powder:Dehydrated formulations requiring reconstitution, dominant in cost-sensitive retail channels.
- Freeze-Dried:Ambient-stable nutrient-preserving formats unlocking direct-to-consumer subscription channels previously inaccessible to thermal-processed entries.
Pouch formats capture volume share fastest from legacy glass. Freeze-dried segments attract concentrated R&D investment.
Ingredient:
Organic fruit sourcing requires the longest lead times and most stringent third-party certification investments.
- Fruits:Apple, pear, and tropical purees with natural sweetness profiles reducing added sugar requirements. Organic certification concentrates margin pools in this segment as New Zealand and Netherlands pasture-based supply constraints transmit price volatility.
- Vegetables:Root vegetable and leafy green formulations with bitter taste masking challenges. Indian FSSAI organic certification pathways attract first-mover investment for Mumbai and Bangalore middle-class expansion.
- Meat:Iron-fortified protein sources for complementary feeding transitions.
- Grains:Cereal-based entries facing commoditization pressure from private-label competition.
Fruit ingredient claims command the widest premium multiples. Vegetable segments show the steepest climb in organic penetration.
Packaging Type:
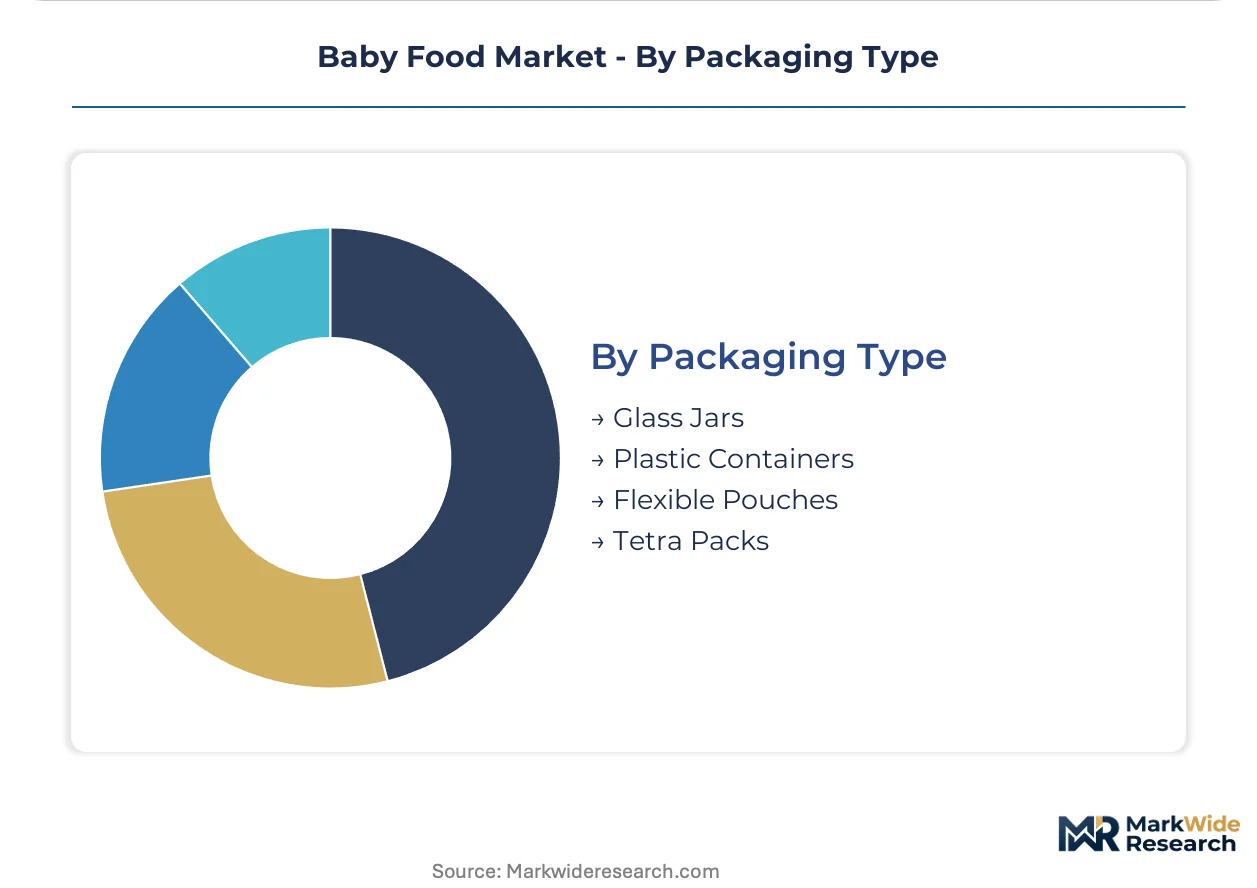
Flexible pouch conversion demands capital-intensive lamination and aseptic filling equipment with specialized barrier film specifications.
- Flexible Pouches:Multi-layer polymer laminates with spout fitments enabling portability and reduced shipping weight versus rigid alternatives. Cross-border e-commerce volumes into China pull specialized cold-chain logistics investment for temperature-sensitive organic formulations.
- Glass Jars:Inert container presentations with established recycling infrastructure but weight-to-volume inefficiency eroding margin in distant export markets.
- Plastic Containers:Polypropylene tubs for toddler-ready meals with resealable lids.
- Tetra Packs:Aseptic carton formats for beverage and liquid complementary feeding products.
Flexible pouch capacity dominates new installation. Glass jar lines face consolidation pressure from freight cost differentials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food technologists and pediatric nutrition specialists cluster in Switzerland, the Netherlands, and New Zealand, anchoring formulation innovation and quality assurance protocols that radiate outward through multinational supply chains.
China
Urban middle-class parents in Shanghai and Shenzhen drive premiumization for imported organic formulations through cross-border e-commerce channels. SAMR national food safety standards mandate extended registration timelines that compress product lifecycle returns for foreign entrants. Cold-chain logistics investment concentrates in Yangtze River Delta distribution hubs serving tier-one city demand.
Germany
Biodynamic certification premiums command shelf price multiples in specialty retail across Bavaria and Baden-Württemberg. EFSA and EU MDR frameworks tighten contaminant thresholds for infant cereals, accelerating third-party testing adoption. Manufacturing expertise clusters around dairy heartlands in Lower Saxony and North Rhine-Westphalia.
United States
FDA infant formula recall protocols tightened post-2022 enforcement, extending batch release timelines and elevating liability insurance carry costs. Working parents in dual-income households compress meal preparation windows while elevating nutritional scrutiny. Greater Boston and Pacific Northwest metro areas concentrate pediatric nutrition R&D facilities.
India
Emerging middle-class parents in Mumbai and Bangalore present first-mover advantage for imported brands establishing local blending facilities. FSSAI organic certification pathways attract concentrated investment from multinational entrants. Maharashtra and Karnataka states anchor distribution infrastructure for premium segment penetration.
France
Pediatrician recommendation networks convert clinical credibility into recurring purchase velocity through pharmacy channel integration. ANSM oversight extends to specialized hypoallergenic lines with disproportionate clinical evidence requirements. Paris and Lyon metropolitan areas concentrate formulation laboratories serving both conventional and medical nutrition channels.
Baby Food Market Vendor Landscape
The competitive structure tilts toward diversified nutrition conglomerates with captive dairy supply chains. Consolidation pressure operates at the mid-tier where legacy ERP systems clash with EU MDR lot-traceability mandates. Three archetypes dominate: integrated dairy processors, specialized hypoallergenic formulators, and biodynamic certification specialists. Capacity expansion and backward integration into organic ingredient sourcing represent the dominant competitive moves.
Within the diversified nutrition tier, Nestlé and Danone exemplify scale-driven positioning through supply chain control and specialized line differentiation. HiPP occupies a distinct position anchored on biodynamic certification standards that exceed baseline regulatory floors. Reckitt Benckiser represents the pharmaceutical-nutrition hybrid archetype with clinical channel integration capabilities.
| Leading Market Players |
|---|
| Reckitt Benckiser |
| HiPP |
| Nestlé |
| Gerber Products Company |
| The Hain Celestial Group |
| Danone |
| The Kraft Heinz Company |
| Beech-Nut Nutrition Corporation |
| Abbott Laboratories |
| Others |
Supply Flow & Price Mechanics
Premium-biodynamic-certification divergence from conventional organic baselines creates parallel pricing architectures that demand entirely separate ingredient sourcing, testing protocols, and cold-chain logistics configurations. This tier split concentrates margin extraction in German and Austrian specialty retail while compressing returns for standard organic entries facing private-label substitution.
Pricing Analysis
Bundled subscription services integrating telehealth dietary guidance command recurring revenue premiums in Shanghai and Shenzhen, while unbundled pouch formats compete on per-unit portability in mass-market channels. Three-tier pricing structure across premium biodynamic, standard organic, and economy conventional levels reflects certification depth and cold-chain investment intensity. Pricing pressure stems from New Zealand and Netherlands organic dairy input volatility transmitting through formula cost structures. Cost-sensitive buyers in India's emerging middle-class concentrate price sensitivity, while dual-income households in China's tier-one cities absorb premium multiples for imported SAMR-registered formulations.
Supply Chain Analysis
Reverse-logistics complexity for temperature-sensitive biodynamic ingredients requires specialized cold-chain recovery protocols that inflate working capital requirements. Manufacturing gravity centers on Switzerland, the Netherlands, and New Zealand where food technologists and pediatric nutrition specialists anchor formulation innovation. Raw material dependencies include pasture-based organic dairy, tropical fruit purees, and biodynamic grain inputs. Single-source vulnerability concentrates in New Zealand's seasonal dairy output fluctuations. Distribution runs through pharmacy channel networks in France and Italy, cross-border e-commerce platforms into China, and direct-to-consumer subscription models in Seoul and Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on freeze-drying technology adoption that preserves nutrient density while eliminating refrigerated distribution costs, enabling premium positioning at reduced operational overhead.
For Market Incumbents: Hedge against EU MDR lot-traceability mandates by accelerating ERP modernization ahead of compliance deadlines that will strand mid-tier competitors with legacy batch recording systems. Deepen backward integration into organic fruit sourcing to capture margin pools concentrating in apple and pear purees, while defending against biodynamic certification specialists eroding shelf price multiples in German specialty retail. For New Entrants and Emerging Players: High-pressure processing technology absorption presents a first-mover wedge for refrigerated organic entries in Seoul and Singapore where parents accept supply chain premiums for preserved enzyme activity. Target India's FSSAI organic certification pathway for Mumbai and Bangalore middle-class expansion before multinational blending facility saturation. Deploy pediatric nutritionist consultation bundles as the primary purchase trigger in tier-one Chinese cities where unguided retail selection is accelerating displacement. For Investors and Strategic Acquirers: Consolidation pressure builds where legacy ERP integration costs exceed standalone profitability for mid-tier processors facing EU MDR compliance cliffs. Long-term viability favors biodynamic certification specialists with captive ingredient sourcing and clinical channel integration capabilities. Watch SAMR registration timeline compression as the signal indicating when stranded inventory risk shifts from operational friction to existential threat for cross-border entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Freeze-Drying Capacity Expansion | Enables direct-to-consumer subscription channels previously inaccessible to thermal-processed entries. |
| Biodynamic Certification Investment | Commands shelf price multiples exceeding EU organic baselines in German and Austrian specialty retail. |
| Cold-Chain Logistics Partnership | Supports cross-border e-commerce volumes into China's Yangtze River Delta distribution hubs. |
| Pharmacy Channel Integration | Converts pediatrician recommendation networks in France and Italy into recurring purchase velocity. |
| ERP Modernization for EU MDR | Prevents lot-traceability mandate violations that strand inventory and compress product lifecycle returns. |
Methodological Framework
Multiple input streams — executive interviews with baby food brand managers and supply chain directors, regulatory filings with FDA and SAMR, Nielsen retail audit data — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured perspectives from category buyers at European pharmacy chains, cold-chain logistics operators in China, and pediatric nutrition specialists in Switzerland and the Netherlands. Secondary validation drew from customs records tracking organic ingredient flows, SEC filings of diversified nutrition conglomerates, and EFSA contaminant threshold documentation.
Data-stream reconciliation anchored volume and value outputs to segmentation dimensions spanning product type, packaging format, ingredient certification tier, and regional regulatory cluster across the projection horizon. CAGRs were derived from trend extrapolation of dual-income household proliferation, freeze-drying technology adoption curves, and cross-border e-commerce penetration rates in Chinese tier-one cities. Forecast inputs incorporated organic dairy input price volatility indices and SAMR registration timeline distributions.
The model holds under stable regulatory enforcement intensity and intact cold-chain infrastructure investment; deviation in EU MDR implementation timelines or China import tariff adjustments would shift competitive mobility and geographic rollout sequencing. Forecasts reflect documented assumptions regarding working parent time compression trends and premiumization velocity in urban middle-class segments. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Wet Cat Food Market
Baby Food and Infant Formula
Organic Infant Formula Market
Baby Food and Infant Formula
South America Baby Food Market
Baby Food and Infant Formula
Anti-Spit Up Formula Market
Baby Food and Infant Formula
Infant Nutrition Market
Baby Food and Infant Formula
United States Baby Food and Infant Formula Market
Baby Food and Infant Formula
Baby Food Products Market
Baby Food and Infant Formula
Organic Follow Up Formula Market
Baby Food and Infant Formula
Asia-Pacific Prebiotics for Infant Formula Market
Baby Food and Infant Formula
Infant Nutritional Premix Market
Baby Food and Infant Formula
Second Stage Organic Infant Formula Market
Baby Food and Infant Formula
Pet Milk Replacement Products Market
Baby Food and Infant Formula
Growing Up Milk Market
Baby Food and Infant Formula
Baby Formula Ingredients Market
Baby Food and Infant Formula
Organic Baby Food Market
Baby Food and Infant Formula
Hypo Anti Allergic Baby Food Market