
 United States Baby Food and Infant Formula Market | 2026-2036
United States Baby Food and Infant Formula Market Size, Share, and Industry Trends Forecast 2026-2036
United States Baby Food and Infant Formula Market Intelligence
The FDA's updated nutrient specifications for infant formula and strengthened FSMA enforcement is broadening the compliance burden across manufacturers. Abbott Laboratories leverages its vertically integrated nutrition science infrastructure to sustain domestic production capacity. Nestlé S.A. anchors its competitive position through specialized pediatric research partnerships. Danone S.A. differentiates via direct-to-consumer subscription channels that control pricing and capture recurring revenue.
United States baby food and infant formula encompasses commercially prepared products designed for infants and toddlers from birth through thirty-six months, formulated to precise macronutrient ratios with added iron, DHA, ARA, and probiotic strains that support neurodevelopment and immune function. These products serve as sole or supplementary nutrition sources during critical growth windows when dietary adequacy directly influences long-term health outcomes. The ingredient type dimension shows organic and fortified categories capturing premium margin pools as parents prioritize clean-label claims, while conventional formulations retain volume leadership through accessible price positioning and broad retail distribution. Packaging innovation concentrates in pouches and tubs, with flexible formats gaining shelf space against traditional glass jars due to convenience and reduced shipping weights.
FDA, USDA Organic certification, and state-level WIC program administrators collectively govern product standards, procurement eligibility, and shelf access across the United States market. FSMA preventive controls require hazard analysis and risk-based mitigation plans that elevate capital requirements for new entrants and reinforce incumbent manufacturing advantages. Stakeholders must monitor evolving state WIC contract bidding rules and organic certification audit intensities as these mechanisms determine which formulations secure institutional volume commitments and retail placement priority.
Market Dynamics
FSMA preventive controls and FDA nutrient specification updates are compressing manufacturing economics while concentrating production among vertically integrated operators with captive laboratory and quality infrastructure.
Growth Catalysts
- Clean-label preference:Millennial and Gen Z parents prioritize organic certification and ingredient transparency, pulling formulation toward single-source ingredient supply chains and third-party verified claims.
- WIC program procurement:State-level WIC contract bidding processes institutionalize volume commitments for compliant manufacturers, creating predictable offtake channels for iron-fortified and DHA-enhanced formulations.
- Neurodevelopment science:Clinical validation of ARA, DHA, and probiotic strains for cognitive and immune outcomes is expanding physician recommendation networks and premium positioning.
Market Restraints
- Input cost volatility:Organic dairy and plant-protein feedstock prices fluctuate with climate-driven crop yields, compressing margin stability for clean-label product lines.
- Supply concentration risk:Domestic manufacturing clusters in Michigan and Ohio create geographic single-point vulnerability for powder and ready-to-feed production capacity.
- Regulatory friction:FDA import alert protocols and facility registration requirements delay foreign supplier qualification timelines, limiting sourcing flexibility.
Strategic Opportunities
- Direct-to-consumer subscription:Recurring revenue models bypass retail slotting fees and capture lifetime value through automated replenishment of specialized pediatric formulas.
- Toddler nutrition extension:Formulations targeting 12-36 month developmental windows address underpenetrated segments beyond standard infant formula categories.
- USDA Organic certification tailwind:Federal procurement preferences and retailer shelf-space allocation increasingly favor dual-certified organic and non-GMO product lines.
Industry Challenges
- Quality assurance talent scarcity:FSMA-mandated preventive controls qualified individuals command premium compensation, constraining mid-tier manufacturer compliance capacity.
- Legacy system integration:Track-and-trace serialization requirements force incompatible enterprise software upgrades across contract manufacturing networks.
- Certification timeline compression:Organic and kosher audit backlogs delay new product launches by six to twelve months against competitive windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Baby Food and Infant Formula Market |
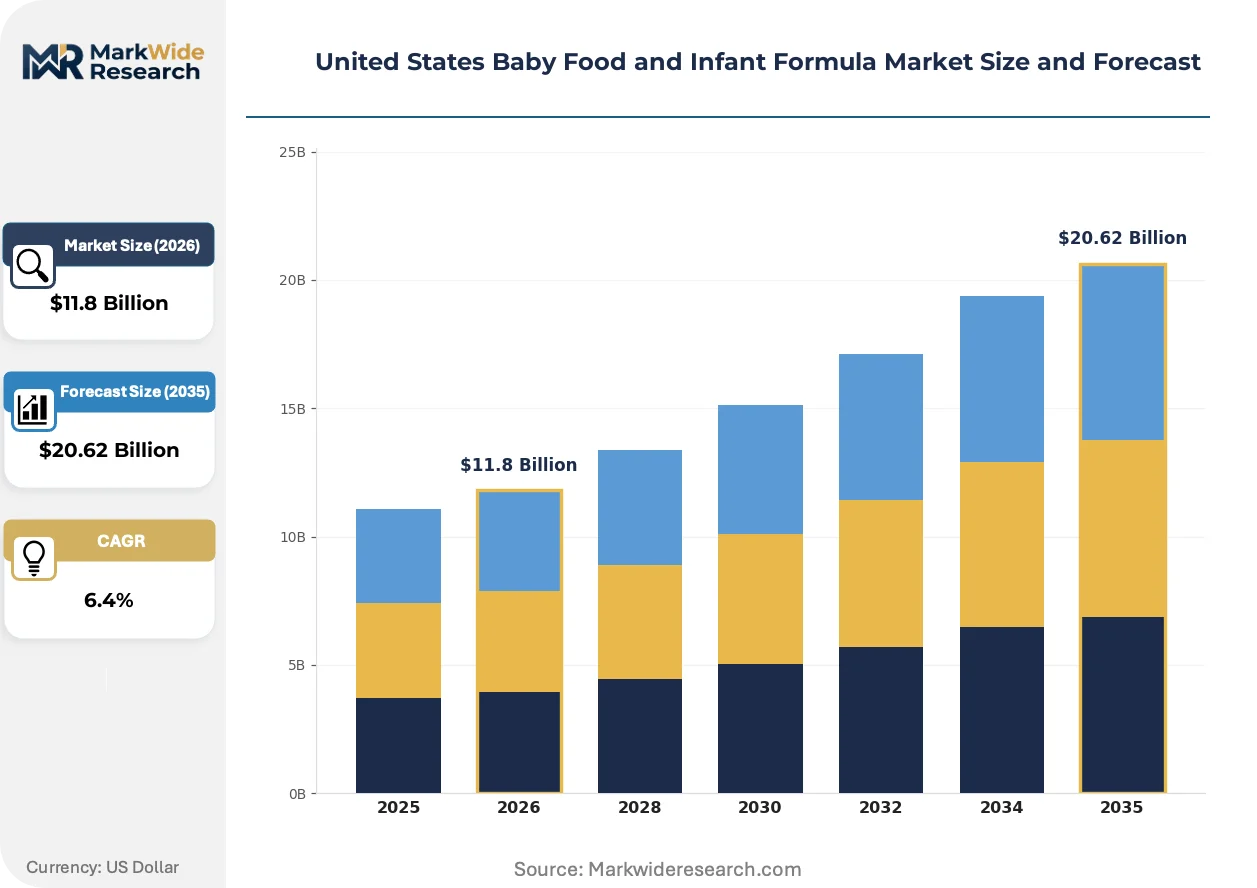
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purees, Cereal, Snacks, Beverages Packaging Type: Tubs, Pouches, Jars, Cans Ingredient Type: Organic, Non-GMO, Conventional, Fortified End User: Parents, Caregivers, Daycares, Hospitals |
| Companies Covered | Abbott Laboratories, Nestlé S.A., Danone S.A., Mead Johnson Nutrition Company, Reckitt Benckiser Group PLC, Perrigo Company plc, Hain Celestial Group Inc., Beech-Nut Nutrition Corporation, Bobbie Baby, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Baby Food and Infant Formula Market Strategic Shifts & Innovations
Aseptic processing and flexible packaging formats are displacing conventional manufacturing and glass jar distribution, while regulatory scrutiny of labeling claims intensifies formulation transparency requirements.
High-pressure processing and aseptic filling technology is consolidating shelf-stable infant nutrition production around extended ambient distribution capabilities. Premium organic brands adopt these systems to eliminate preservative dependencies while maintaining twelve-month stability windows. This consolidation is compressing the addressable market for regional processors lacking capital-intensive thermal processing infrastructure.
FDA enforcement of updated infant formula nutrient specifications and FSMA preventive controls is elevating documentation burdens across manufacturing facilities. The agency's strengthened inspection protocols now mandate hazard analysis plans with supply chain verification for all critical ingredients. Small and mid-sized manufacturers face disproportionate compliance costs, accelerating consolidation toward integrated quality systems.
Subscription-based replenishment models are displacing traditional retail purchasing cycles among digitally native parent demographics. Direct-to-consumer platforms capture purchase data to personalize formulation recommendations and automate delivery timing. California and New York metropolitan areas exhibit the highest penetration of these channels, driven by convenience prioritization and premium product access.
United States Baby Food and Infant Formula Market Segmentation
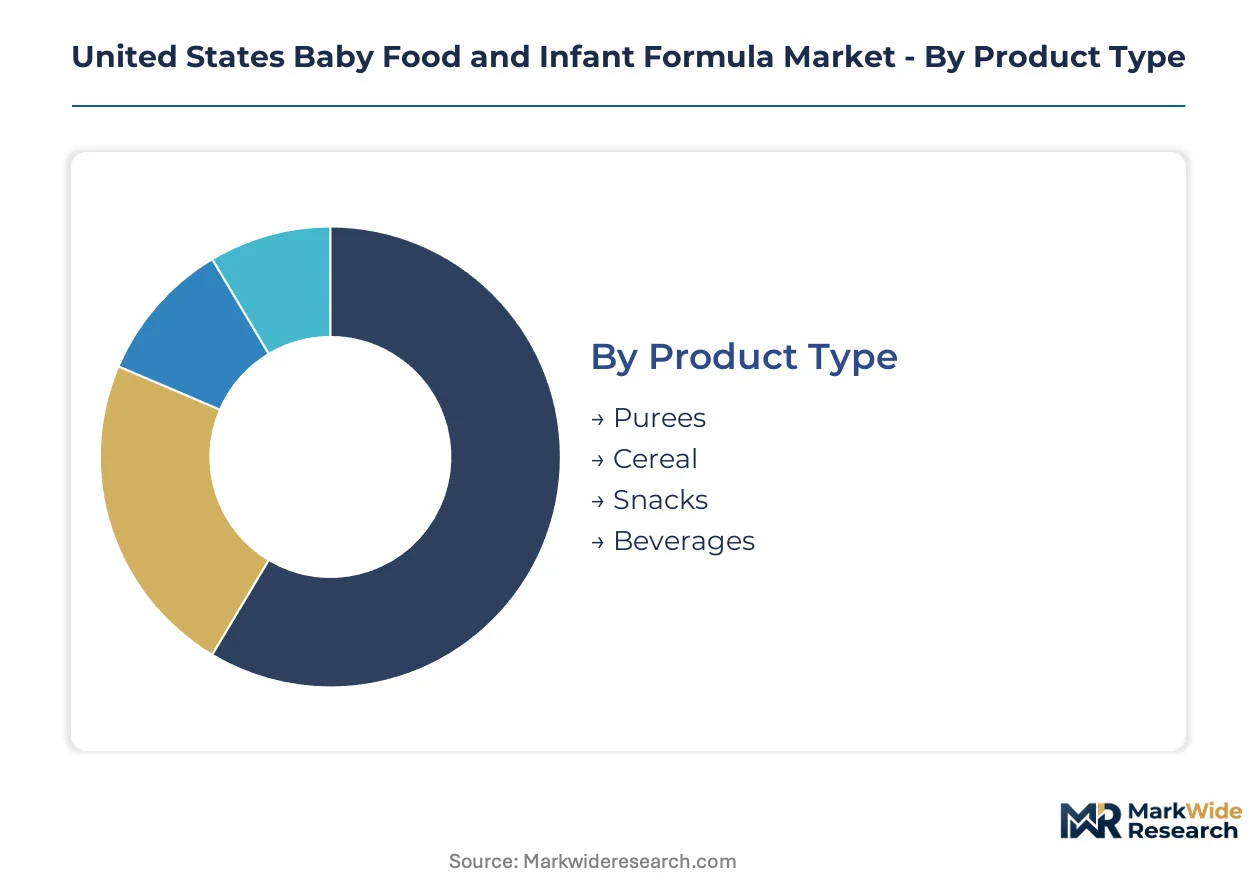
Segmentation in the United States baby food and infant formula market reveals how formulation choices, packaging formats, and procurement channels concentrate margin capture. Manufacturers align production assets against specific demand clusters defined by parental purchasing power and institutional procurement rules.
Product Type:
Supply concentration in ready-to-feed liquid and powder manufacturing favors segments with extended shelf stability and WIC program eligibility.
- Purees:Single-ingredient vegetable and fruit purees target 4-6 month introduction phases with texture-graded progression systems. California and New York metro parents drive organic puree demand through subscription channels that bypass retail slotting fees.
- Cereal:Iron-fortified rice and oatmeal cereals serve as first solid foods with standardized nutrient profiles meeting FDA infant formula specifications. WIC contract volumes concentrate in this segment due to low per-unit cost and long shelf stability.
- Snacks:Puffed rice and teething biscuits occupy convenience-oriented purchase occasions.
- Beverages:Toddler transition drinks and ready-to-feed bottles address 12-36 month hydration and nutrition gaps.
Cereal absorbs the bulk of installed capacity; purees are expanding most quickly.
Packaging Type:
Cost tier differentiation separates premium convenience formats from economy bulk packaging, with mid-tier options losing shelf space.
- Pouches:Flexible laminated pouches with spout closures reduce shipping weight and enable single-hand feeding. Texas and Florida distribution centers prioritize pouch formats for e-commerce fulfillment efficiency.
- Tubs:Plastic tubs with resealable lids dominate powder formula segments requiring moisture protection and scoop precision. Hospital discharge sample programs rely on tub formats for brand trial conversion.
- Jars:Glass jar formats retain organic puree positioning in conventional grocery.
- Cans:Metal cans serve bulk powder and ready-to-feed liquid production.
Tubs absorb the bulk of installed capacity; pouches are gaining share fastest.
Ingredient Type:
Margin concentration follows certification intensity, with dual-certified organic and non-GMO products commanding shelf-space allocation priority.
- Organic:USDA-certified formulations with single-source ingredient supply chains and third-party verified claims. Millennial parents in California, Texas, and New York drive demand despite climate-driven dairy feedstock price volatility.
- Fortified:DHA, ARA, iron, and probiotic-enhanced formulations backed by clinical validation for neurodevelopment outcomes. Physician recommendation networks reinforce premium positioning in hospital and pediatric clinic channels.
- Non-GMO:Verified non-genetically modified ingredient lines occupy mid-tier price positioning.
- Conventional:Standard formulations without certification claims retain volume leadership through accessible pricing.
Conventional absorbs the bulk of installed capacity; organic is climbing the fastest.
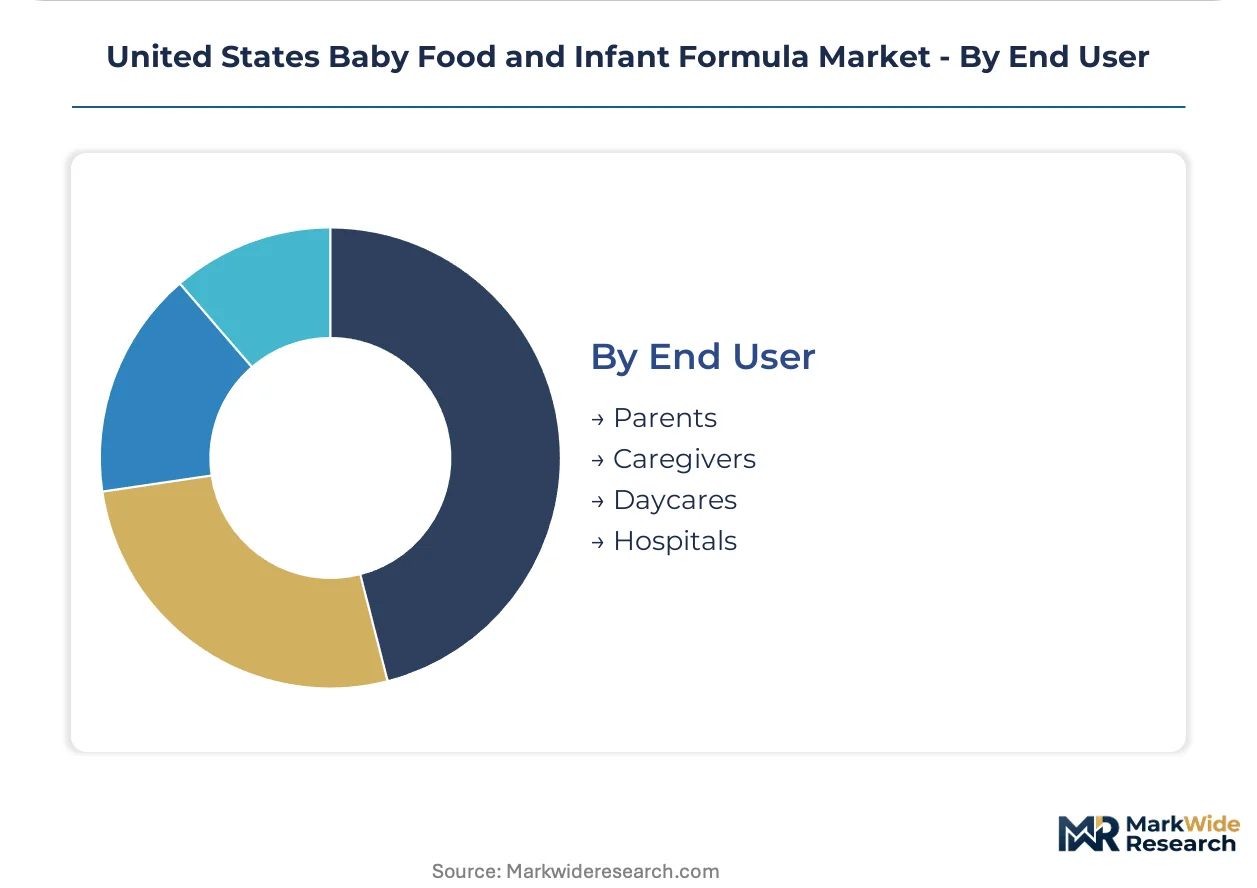
End User:
Application concentration splits between institutional procurement with predictable offtake and direct-to-consumer channels with higher lifetime value capture.
- Parents:Primary decision-makers prioritizing clean-label claims, convenience, and pediatrician recommendations. Digital-native demographics in metropolitan California and New York exhibit highest subscription platform penetration.
- Hospitals:Neonatal intensive care units and maternity wards requiring specialized preterm and metabolic disorder formulations. FDA nutrient specification compliance and FSMA preventive controls mandate captive quality infrastructure.
- Caregivers:Grandparents and non-parental guardians purchasing for occasional care situations.
- Daycares:Licensed facilities with state-level nutrition program compliance requirements.
Parents absorb the bulk of volume; hospitals are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's metropolitan corridors anchor domestic demand concentration for organic infant nutrition, with Los Angeles and San Francisco Bay Area distribution networks processing premium SKU volumes that exceed national per-capita averages by significant margins.
California
Millennial parents in Los Angeles and San Francisco drive organic puree subscription penetration through direct-to-consumer platforms. California's Department of Public Health enforces stricter heavy metal testing protocols than federal baselines. Sacramento Valley dairy cooperatives supply organic milk powder to regional contract manufacturers serving West Coast WIC programs.
Texas
Houston and Dallas-Fort Worth metroplexes absorb bulk powder formula volumes through hospital discharge programs and retail consolidation. Texas WIC administrators prioritize iron-fortified cereal procurement in state contract bidding. Port of Houston logistics clusters handle imported DHA and ARA lipid ingredients for regional blending facilities.
New York
New York City parents exhibit highest clean-label price tolerance, pulling Manhattan and Brooklyn retail toward dual-certified organic and non-GMO shelf allocations. New York State Department of Agriculture and Markets coordinates with FDA on imported formula inspection protocols. Finger Lakes dairy processing infrastructure supports organic fluid milk concentration for infant formula base stocks.
Michigan
Sturgis and Zeeland manufacturing corridors concentrate domestic powder production capacity for major brand portfolios. Michigan Department of Agriculture and Rural Development administers organic certification audits that create six-to-twelve-month product launch delays. Grand Rapids logistics hubs distribute ready-to-feed liquid formulations to Midwest hospital networks.
Ohio
Cincinnati and Columbus metropolitan statistical areas anchor retail trial conversion through pediatric clinic sampling programs. Ohio Department of Health WIC contracts institutionalize volume commitments for DHA-enhanced formulations. Dayton-area contract manufacturing facilities process specialized metabolic disorder formulas requiring captive quality infrastructure.
United States Baby Food and Infant Formula Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification intensity, with USDA Organic and clinical-validation-backed portfolios commanding shelf-space allocation priority while conventional formulations compete on accessible price positioning and WIC contract eligibility. The market exhibits consolidated production capacity among operators with captive laboratory infrastructure, while mid-tier manufacturers face disproportionate FSMA compliance burdens. Three archetypes dominate: vertically integrated nutrition science conglomerates, direct-to-consumer subscription specialists, and contract manufacturing-dependent private-label suppliers. Competitive moves concentrate on M&A for organic supply chain control and capacity expansion in aseptic processing infrastructure.
Within the vertically integrated tier, Abbott Laboratories and Nestlé S.A. exemplify archetypes that combine pediatric research partnerships with captive manufacturing infrastructure. Danone S.A. occupies a position representing direct-to-consumer channel innovation through subscription-based replenishment models. These three entities anchor competitive dynamics across premium, institutional, and digitally native demand segments respectively.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Nestlé S.A. |
| Danone S.A. |
| Mead Johnson Nutrition Company |
| Reckitt Benckiser Group PLC |
| Perrigo Company plc |
| Hain Celestial Group Inc. |
| Beech-Nut Nutrition Corporation |
| Bobbie Baby, Inc. |
| Others |
Cost & Logistics Intelligence
USDA Organic certification and FDA nutrient specification tiers create a three-rung ladder that splits both pricing power and sourcing complexity across the United States baby food and infant formula market. Premium organic formulations command shelf-space allocation priority through single-source ingredient supply chains, while conventional products compete on WIC contract eligibility and accessible price positioning.
Pricing Analysis
Value-based pricing anchored to neurodevelopment outcomes and clinical validation separates fortified DHA-ARA formulations from commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with organic and dual-certified non-GMO products capturing margin pools that conventional lines cannot access. Cost compression in organic dairy feedstocks is intensifying because climate-driven crop yield volatility squeezes margin stability. Price-sensitive buyers cluster in WIC-dependent households and bulk powder purchasers, while subscription-channel parents in California and New York metros exhibit lowest price elasticity.
Supply Chain Analysis
Certification and qualification gating through USDA Organic audits and FSMA preventive controls concentrates supply among operators with captive laboratory infrastructure. Domestic manufacturing clusters in Michigan and Ohio anchor powder and ready-to-feed production, while imported DHA and ARA lipid ingredients feed from European and Asian pharmaceutical-grade suppliers. Single-source vulnerability runs through concentrated organic dairy cooperative supply in the Sacramento Valley and Finger Lakes regions. Distribution runs through hospital discharge programs, WIC-contracted retail networks, and direct-to-consumer platforms with diverging margin capture profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic aseptic processing capacity constraints prop pricing power for incumbent operators with extended shelf-stable production infrastructure. Manufacturing qualification backlogs create six-to-twelve-month barriers that institutionalize incumbent advantages.
For Market Incumbents: Anchor market position through backward integration into organic dairy cooperative supply and captive aseptic processing capacity expansion in Michigan manufacturing corridors. FSMA-mandated preventive controls qualified individuals command premium compensation, constraining mid-tier competitor compliance capacity and reinforcing manufacturing concentration. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting toddler nutrition extension segments in California and New York metropolitan areas, where clean-label price tolerance and convenience prioritization create penetrable white space beyond institutional WIC contract channels. Physician recommendation networks for neurodevelopment-validated formulations offer alternative go-to-market positioning. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated nutrition science operators given FDA enforcement intensification and FSMA compliance burden acceleration. Long-term viability framing favors archetypes combining pediatric research partnerships with captive manufacturing infrastructure. The signal to watch is state WIC contract rebidding outcomes and organic certification audit backlogs as inflection indicators for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Captures lifetime value through automated replenishment in California and New York metros. |
| USDA Organic Certification Investment | Secures federal procurement preferences and retailer shelf-space allocation priority. |
| Aseptic Processing Capacity Expansion | Eliminates preservative dependencies while maintaining twelve-month stability windows. |
| Pediatric Research Partnership | Builds physician recommendation networks for neurodevelopment-validated formulations. |
| Backward Integration into Organic Supply | Controls climate-driven dairy feedstock volatility through captive cooperative supply. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this United States baby food and infant formula market analysis. Primary interviews with infant formula brand managers, USDA Organic certification auditors, WIC program administrators, hospital procurement directors, and retail category buyers combined with FDA enforcement action databases, state WIC contract bid documents, and Nielsen retail audit data. Bottom-up volume modeling and top-down value triangulation validated segment-level outputs.
Reconciliation of production capacity data, ingredient import manifests, and subscription platform transaction records informed the analytical framework across the analysis window. Segmentation dimensions modeled include product type, packaging format, ingredient certification tier, and end-user channel. CAGRs derived from fitted growth curves against historical WIC enrollment patterns and organic dairy supply expansion trajectories. Forecast inputs incorporated FSMA compliance cost trajectories and state-level procurement rule evolution.
Regulatory enforcement intensity shifts, organic certification audit backlogs, and climate-driven dairy feedstock volatility are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding WIC program stability and aseptic processing capacity expansion timelines. A model refresh is warranted upon material change in FDA preventive controls inspection protocols or state-level WIC contract bidding outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Europe Baby Food Market
Baby Food and Infant Formula
Follow on Formula Milk Market
Baby Food and Infant Formula
Infant Formula Ingredients Market
Baby Food and Infant Formula
Global Oligosaccharides in Infant Nutrition Market
Baby Food and Infant Formula
Global DHA Algae Oil for Infant Formula Market
Baby Food and Infant Formula
Baby Cereal-Based Complementary Food Market
Baby Food and Infant Formula
North America Organic Baby Food Market
Baby Food and Infant Formula
Baby Food and Infant Formula Market
Baby Food and Infant Formula
Baby Juice Market
Baby Food and Infant Formula
Baby Food Market
Baby Food and Infant Formula
Goat Milk Formula Market
Baby Food and Infant Formula
Infant Formula Milk Powder with A2 Beta-Casein Market
Baby Food and Infant Formula
Baby Fruit Puree Market
Baby Food and Infant Formula
Indonesia Infant Nutrition Market
Baby Food and Infant Formula
Infant Food Compliance Ready Fertility Input Market
Baby Food and Infant Formula
Baby Formula Ingredients Market