
 Middle East and Africa Organic Baby Food Market | 2026-2036
Middle East and Africa Organic Baby Food Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Organic Baby Food Market Foresight
EU Green Deal-aligned sustainability benchmarks for imported food products is consolidating procurement standards across Gulf retail chains. Nestle leverages its dairy supply infrastructure to anchor distribution across Saudi Arabia and the UAE. Almarai competes through backward integration into organic dairy farms in the Al-Kharj region. Hipp differentiates via biodynamic certification protocols that exceed baseline organic requirements.
Organic baby food comprises infant nutrition products manufactured without synthetic pesticides, genetically modified organisms, or artificial additives, typically processed through gentle heat treatment or cold-pressing to preserve micronutrient density. These formulations serve the zero-to-thirty-six-month demographic where parental concern about early-life chemical exposure drives premium positioning. Pouches dominate volume due to convenience-driven urban consumption patterns, while cereal formats capture higher per-unit margins through fortified positioning. Glass jars retain structural relevance in South African supermarkets where recycling infrastructure supports returnable packaging economics.
South Africa's Department of Health enforces infant food labeling regulations that mandate allergen disclosure and prohibit misleading nutritional claims. The UAE's Ministry of Industry and Advanced Technology applies GCC-standardized organic certification requirements for imported baby food products. Saudi Food and Drug Authority inspection protocols for imported infant formula are extending to complementary feeding categories. Stakeholders must monitor harmonization gaps between national organic standards and Gulf Cooperation Council unified regulations to preempt market access disruptions.
Market Dynamics
Urban millennial parents in Gulf cities are consolidating demand around traceable supply chains, forcing manufacturers to reconfigure procurement networks and certification protocols to match EU Green Deal-aligned sustainability benchmarks.
Growth Catalysts
- EU Green Deal benchmarks:Gulf retail chains now require imported organic baby food to meet consolidated sustainability standards, eliminating fragmented national requirements.
- Biodynamic certification protocols:Premium positioning through certification exceeding baseline organic requirements attracts high-income households in Dubai and Riyadh.
- Lagos-Ibadan corridor concentration:Nigeria's emerging demand zone outside South Africa and the UAE creates new distribution anchor points for regional expansion.
Market Restraints
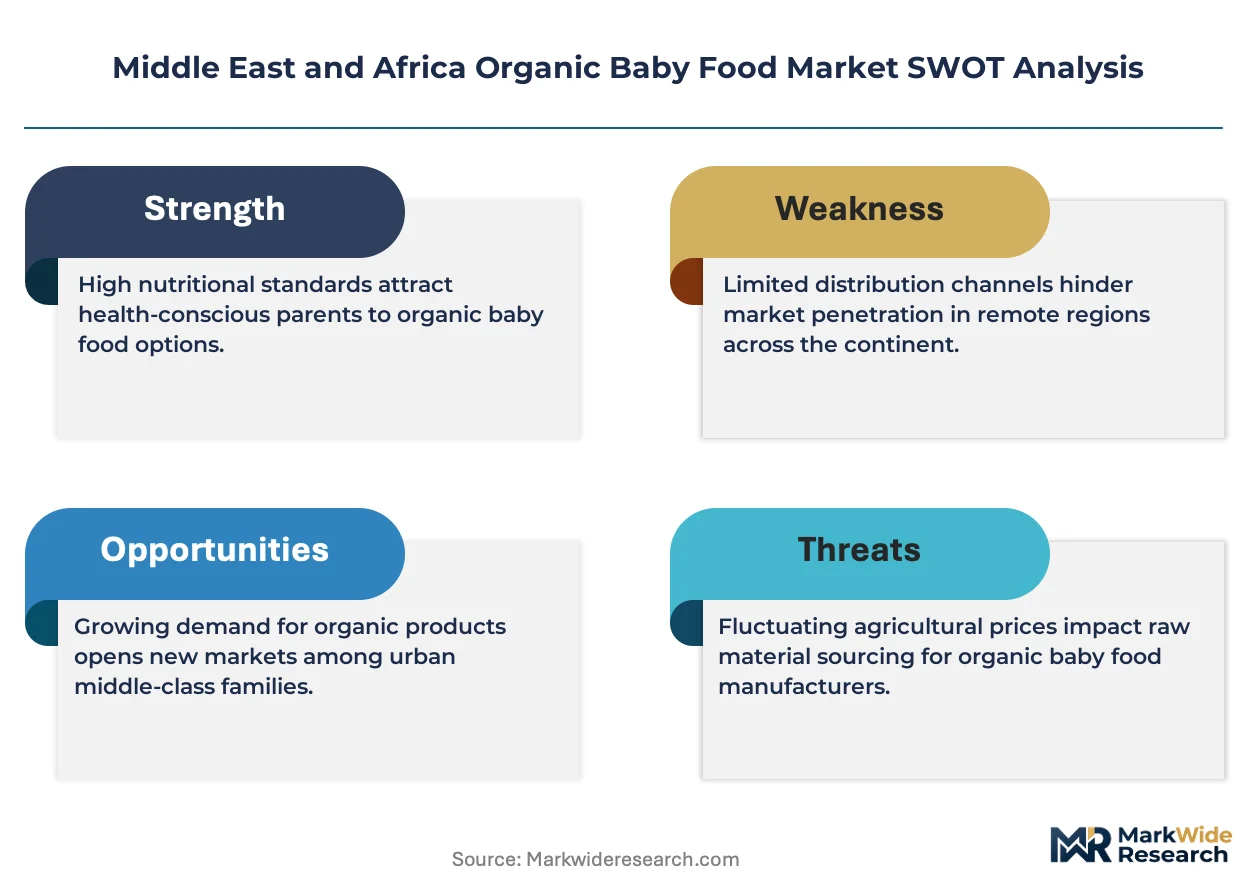
- Organic dairy input volatility:Al-Kharj region dairy farm output fluctuations constrain backward-integrated supply security for Saudi-based producers.
- Import inspection protocols:Saudi Food and Drug Authority extended infant formula inspection regimes to complementary feeding categories, lengthening customs clearance timelines.
- Glass jar packaging economics:Returnable packaging infrastructure limitations outside South Africa prevent margin recovery through recycling loops.
Strategic Opportunities
- Nigerian urban corridor penetration:Lagos-Ibadan demand concentration remains underserved by certified organic supply, creating first-mover positioning potential.
- Pouch format convenience premium:Urban consumption patterns in Gulf cities favor portable packaging, commanding price premiums over jar alternatives.
- GCC harmonization gaps:Divergent national organic standards against Gulf Cooperation Council unified regulations create advisory service opportunities for compliance navigation.
Industry Challenges
- Allergen disclosure compliance:South Africa's Department of Health labeling mandates require reformulation documentation and supply chain auditing capabilities.
- Cold-press micronutrient retention:Gentle heat treatment equipment capex demands strain mid-tier manufacturer balance sheets.
- Biodynamic certification timelines:Conversion periods for conventional farms to biodynamic status extend supply onboarding by multiple growing seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Organic Baby Food Market |
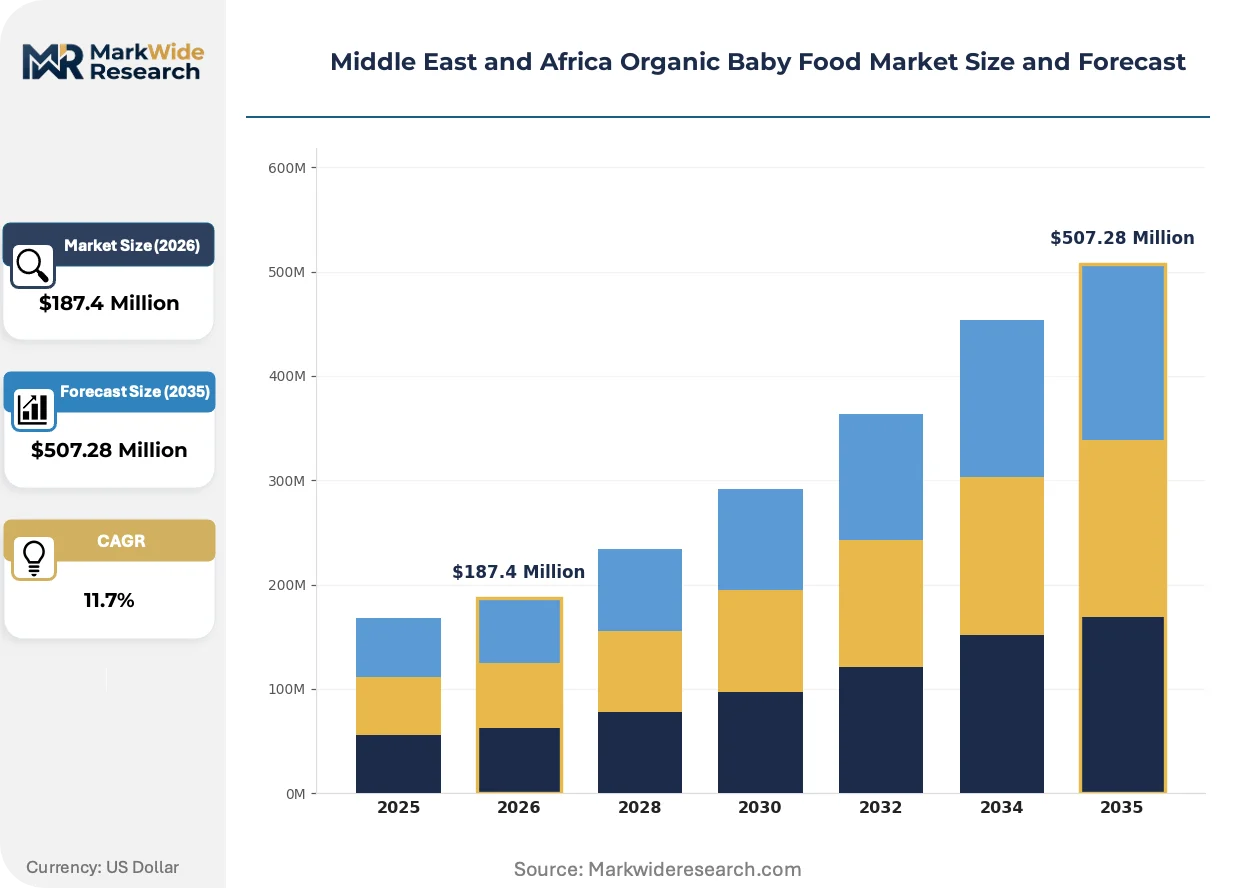
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jarred, Pouches, Cereal, Snacks Ingredient Source: Fruits, Vegetables, Grains, Proteins Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Baby Specialty Stores Packaging Type: Glass Jars, Plastic Pouches, Tetra Packs, Cans |
| Companies Covered | Arla Foods amba, Hipp, Nestle, Amara Organic Foods, Almarai, Abbott, Hero Group, The Baby Food Company, Danone, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Organic Baby Food Market Shifts & Advancements
Cold-pressing technology is compressing nutrient degradation windows while biodynamic certification protocols are fragmenting premium tiers. Distribution through pharmacy channels is gaining traction as parents seek clinician-validated feeding guidance.
High-pressure processing is expanding into organic baby food manufacturing as an alternative to thermal pasteurization. UAE-based manufacturers adopt this technology to preserve heat-sensitive vitamins in fruit and vegetable purees. The shift is expanding into premium pouch production, compressing the shelf-life gap between conventional and organic formats.
South Africa's updated food safety protocols for infant nutrition are tightening import and labeling requirements. The Department of Health now mandates explicit allergen disclosure and prohibits misleading nutritional claims on packaging. Complementary feeding categories face the strictest compliance burden, with manufacturers reformulating to eliminate cross-contamination risks.
Pharmacy channel penetration is accelerating as Gulf parents seek pediatrician-validated organic feeding recommendations. Retail pharmacy chains in Dubai and Abu Dhabi are displacing supermarket baby aisles as the primary purchase point for first-time buyers. This behavioral shift is most visible among expatriate households with employer-sponsored health coverage.
Middle East and Africa Organic Baby Food Market Segmentation
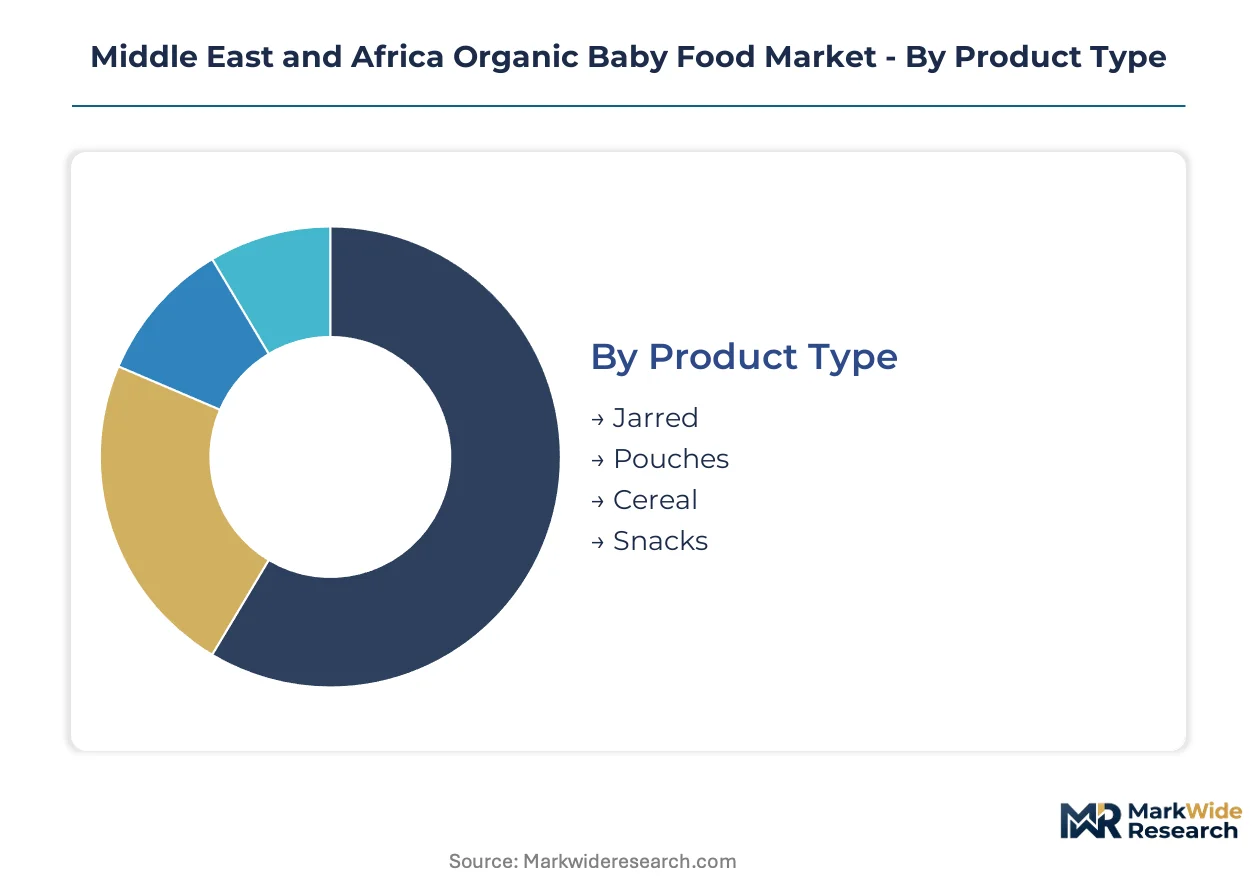
Segmentation in the Middle East and Africa organic baby food market reveals how parental purchasing decisions fragment across convenience priorities, ingredient provenance concerns, and retail channel preferences. Manufacturers must align formulation and packaging investments with these divergent demand patterns to capture premium positioning.
Product Type:
Pouch buyers prioritize portability and mess-free feeding, while jar purchasers emphasize transparency and recycling economics.
- Pouches:Flexible laminated packaging with spout closures enables single-hand feeding during transit. Demand concentrates among urban millennial parents in Dubai and Riyadh where dual-income households value on-the-go convenience despite per-gram cost premiums.
- Cereal:Fortified grain formulations with added iron and zinc address nutritional gaps in complementary feeding stages. South African supermarkets report strongest volume here, driven by pediatrician recommendations for iron-deficient infants.
- Jarred:Glass containers with vacuum-sealed lids preserve texture integrity for chunkier developmental stages.
- Snacks:Finger-food formats including puffs and teething biscuits extend organic positioning into toddler categories.
Volume sits with Pouches; growth tilts toward Cereal.
Ingredient Source:
Raw material traceability requirements diverge sharply between Gulf import-dependent supply chains and South African domestic agricultural networks.
- Fruits:Pureed apple, pear, and mango bases dominate introductory feeding stages. Cold-pressed processing preserves heat-sensitive vitamin C in UAE-manufactured formulations targeting pharmacy channel distribution.
- Vegetables:Root vegetable and leafy green combinations address parental concerns about early palate development. Lagos-Ibadan corridor demand clusters around sweet potato and carrot purees as first savory exposures.
- Grains:Rice, oat, and quinoa bases provide hypoallergenic carbohydrate sources.
- Proteins:Lentil, chicken, and fish purees serve protein introduction stages.
Grains anchor current volume; Proteins are expanding most quickly as complementary feeding protocols extend.
Distribution Channel:
Channel selection reflects trust calibration between clinician validation, price transparency, and assortment breadth.
- Supermarkets:Hypermarket chains in Saudi Arabia and the UAE consolidate shelf space for established organic brands. South African retailers leverage returnable glass jar infrastructure to recover packaging costs through deposit systems.
- Online Retail:E-commerce platforms aggregate subscription-based replenishment models for recurring purchases. Nigerian urban corridors show steepest digital adoption as traditional retail coverage gaps persist.
- Health Food Stores:Specialist retailers emphasize biodynamic and beyond-organic certification tiers.
- Baby Specialty Stores:Dedicated maternity and early childhood retailers provide trained staff guidance.
Supermarkets retain volume leadership; Online Retail is gaining share fastest among first-time Gulf parents.
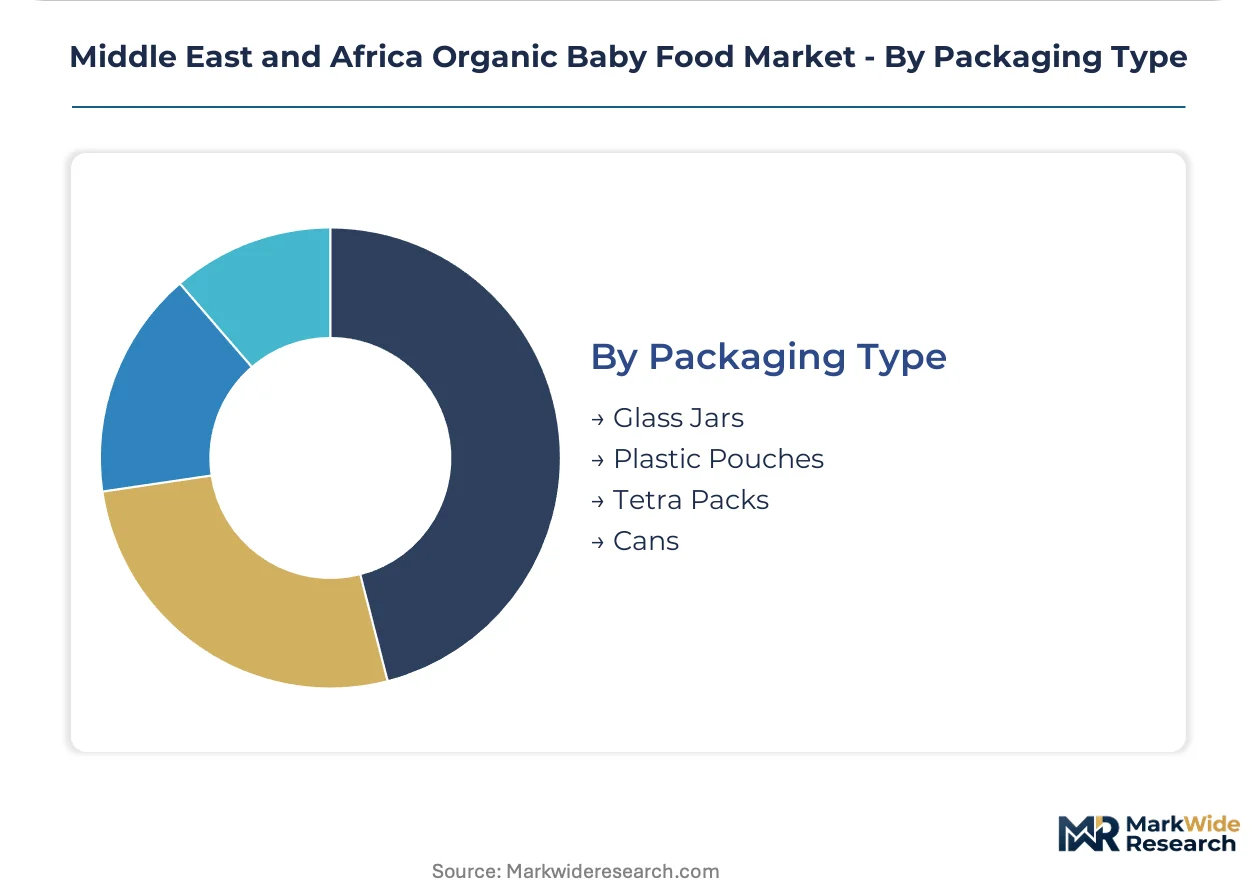
Packaging Type:
Material selection trade-offs between shelf stability, shipping economics, and end-of-life recovery shape procurement decisions.
- Plastic Pouches:Multi-layer polyethylene and aluminum laminates achieve 12-month ambient shelf life. Gulf retail chains favor this format for reduced freight weight versus glass alternatives.
- Glass Jars:Returnable container systems in South African supermarkets enable closed-loop economics. Al-Kharj region dairy-integrated producers prefer jars for premium yogurt-based formulations.
- Tetra Packs:Aseptic carton technology extends shelf life without refrigeration.
- Cans:Metal packaging retains relevance for export-ready concentrated purees.
Plastic Pouches dominate volume; Glass Jars hold positioning in South African premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai anchors organic baby food demand across the Gulf Cooperation Council, with pharmacy channel penetration and biodynamic certification premiums concentrating purchasing power in the emirate's retail corridors.
United Arab Emirates
Urban millennial parents in Dubai and Abu Dhabi drive traceable supply chain requirements, with pharmacy channels displacing supermarkets for first-time buyers. MOHAP applies GCC-standardized organic certification requirements for imported products. Dubai's retail corridors concentrate biodynamic-certified premium positioning.
Saudi Arabia
Backward integration into Al-Kharj region dairy farms secures organic input supply for domestic manufacturers. The Saudi Food and Drug Authority extends infant formula inspection protocols to complementary feeding categories. Riyadh's urban consumer base commands convenience-driven pouch format premiums.
South Africa
Returnable glass jar infrastructure supports recycling economics in supermarket channels, with pediatrician recommendations driving fortified cereal volume. The Department of Health enforces strict allergen disclosure mandates and prohibits misleading nutritional claims. Cape Town and Johannesburg retail clusters anchor domestic distribution networks.
Nigeria
The Lagos-Ibadan corridor emerges as the most concentrated demand zone outside South Africa and the UAE, with digital platforms filling traditional retail coverage gaps. The country's national food safety regulator tightens import documentation for infant nutrition products. Lagos metropolitan demand clusters around sweet potato and carrot puree introductions.
Middle East and Africa Organic Baby Food Market Competitive Landscape
The competitive structure tilts toward multinational nutrition conglomerates with dairy supply infrastructure and regional dairy-integrated players with backward-controlled organic input security. Three archetypes dominate: global infant nutrition specialists leveraging existing distribution networks, regional dairy giants with captive organic farm operations, and biodynamic-certified premium specialists commanding certification premiums. Capacity expansion in cold-press processing capabilities and strategic partnerships with pharmacy retail chains constitute the dominant competitive moves.
Among global nutrition conglomerates, Nestle and Danone represent scale-driven archetypes with established Gulf distribution infrastructure. Hipp exemplifies the biodynamic-certified premium specialist archetype, occupying a position where certification protocols exceed baseline organic requirements. Almarai anchors the regional dairy-integrated archetype through its Al-Kharj region farm operations, representing backward integration strategies that secure organic dairy input supply.
| Leading Market Players |
|---|
| Arla Foods amba |
| Hipp |
| Nestle |
| Amara Organic Foods |
| Almarai |
| Abbott |
| Hero Group |
| The Baby Food Company |
| Danone |
| Others |
Supply & Pricing Matrix
Organic dairy farm technicians concentrated in Saudi Arabia's Al-Kharj region command wage premiums that compress manufacturing margins and widen spreads between biodynamic-certified and conventional organic tiers.
Pricing Analysis
Value-based pricing anchored to pediatrician-validated nutritional outcomes separates pharmacy-channel premiums from supermarket baseline tiers. Certification grade—biodynamic versus baseline organic—drives price differentiation alongside cold-press processing claims. Pricing pressure stems from EU Green Deal-aligned sustainability benchmarks that raise input costs for Gulf importers. First-time urban millennial parents in Dubai show lowest price sensitivity; Nigerian digital-first buyers in the Lagos-Ibadan corridor exhibit highest elasticity.
Supply Chain Analysis
Freight cost differentials between glass jar and pouch formats reshape distribution economics across the Middle East and Africa. Organic dairy inputs concentrate in Saudi Arabia and the UAE; fruit and vegetable purees source from South African domestic networks and European import channels. Raw material dependencies include organic milk powder, cold-pressed fruit concentrates, and biodynamic-certified grains. Single-source vulnerability in Al-Kharj region dairy farm output threatens supply security for backward-integrated producers. Distribution runs through pharmacy chains in Gulf cities and supermarket networks with returnable packaging infrastructure in South Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where South Africa's Department of Health allergen disclosure mandates and the UAE's MOHAP organic certification requirements erect barrier-to-entry moats favoring incumbents with documented supply chain auditing capabilities.
For Market Incumbents: Deploy cold-press processing capacity additions in the UAE to defend pharmacy channel positioning against high-pressure processing substitutes. Nestle and Almarai should deepen backward integration into Al-Kharj region organic dairy farms to secure input supply against climate-driven output volatility. Biodynamic certification investment represents a second lever for Hipp to extend premium positioning beyond baseline organic competitors. For New Entrants and Emerging Players: South Africa's updated food safety protocols for infant nutrition open a window for compliance-focused entrants to capture reformulation service contracts from mid-tier manufacturers lacking allergen documentation capabilities. The Lagos-Ibadan corridor remains the most penetrable geography, with digital platform partnerships offering the lowest-friction go-to-market angle against traditional retail coverage gaps. For Investors and Strategic Acquirers: Re-rating potential sits with biodynamic-certified premium specialists given pharmacy channel displacement of supermarket baby aisles in Gulf cities. Long-term viability over a five-to-ten year window favors archetypes with captive organic farm operations and clinician-validated distribution relationships. The signal to watch is Saudi Food and Drug Authority inspection protocol harmonization with complementary feeding categories, which would accelerate customs clearance timelines for prepared entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Biodynamic Certification Investment | Hipp's certification protocols exceed baseline organic requirements, commanding Gulf pharmacy channel premiums. |
| Backward Integration into Organic Dairy | Almarai's Al-Kharj region farm operations secure input supply against climate-driven output fluctuations. |
| Cold-Press Processing Capacity Expansion | UAE manufacturers preserve heat-sensitive vitamins to compress shelf-life gaps with conventional formats. |
| Pharmacy Channel Partnership | Dubai and Abu Dhabi retail pharmacy chains displace supermarkets for first-time organic baby food buyers. |
| Digital Platform Distribution | Nigerian e-commerce aggregates subscription replenishment where traditional retail coverage gaps persist. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with organic dairy farm operations managers, Gulf retail pharmacy procurement leads, South African supermarket category buyers, Nigerian e-commerce platform supply heads, and infant nutrition regulatory affairs specialists. Secondary sources included SFDA inspection protocol documentation, South Africa Department of Health labeling guidelines, UAE MOHAP organic certification requirements, and GCC customs import records. Bottom-up volume modeling and top-down value triangulation reconciled segment-level outputs.
Data-stream reconciliation across product type, ingredient source, distribution channel, and packaging format dimensions generated volume and value projections across the analysis window. CAGRs derived from segment-level growth rate blending and macroeconomic adjustment factors. Industry-specific forecast inputs incorporated biodynamic certification conversion timelines and cold-press processing equipment deployment patterns.
The model assumes a particular technology adoption path; alternative pathways for high-pressure processing would alter the outlook if thermal pasteurization displacement accelerates beyond projected rates. Forecasts reflect assumptions about regulatory harmonization timelines and pharmacy channel penetration curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
South America Baby Food Market
Baby Food and Infant Formula
Ready to Use Supplementary Food Market
Baby Food and Infant Formula
Pureed Food Market
Baby Food and Infant Formula
Global Lactose-Free Infant Formula Market
Baby Food and Infant Formula
Human Milk Oligosaccharides in Infant Formula Market
Baby Food and Infant Formula
Kids Food and Beverages Market
Baby Food and Infant Formula
A2 Infant Formula Market
Baby Food and Infant Formula
Anti-Spit Up Formula Market
Baby Food and Infant Formula
Hypo Anti Allergic Baby Food Market
Baby Food and Infant Formula
GCC Baby Food and Infant Formula Market
Baby Food and Infant Formula
Infant Nutrition Market
Baby Food and Infant Formula
Infant Food Compliance Ready Fertility Input Market
Baby Food and Infant Formula
Omega 3 Ingredients for Infant Food Market
Baby Food and Infant Formula
Japan Baby Food and Infant Formula Market
Baby Food and Infant Formula
Indonesia Infant Nutrition Market
Baby Food and Infant Formula
Baby Formula Market