
 Asia-Pacific Prebiotics for Infant Formula Market | 2026-2036
Asia-Pacific Prebiotics for Infant Formula Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Prebiotics for Infant Formula Market Outlook
Premium private-label buyers is bifurcating from price-sensitive mass-market purchasers across the Asia-Pacific infant formula landscape. Nestlé S.A. leverages its Swiss R&D heritage to sustain clinical trial pipelines for oligosaccharide blends. Abbott Laboratories anchors its position through hospital channel partnerships in India and Vietnam. Danone S.A. differentiates via localized sourcing partnerships with Chinese prebiotic suppliers.
Prebiotics for infant formula comprise non-digestible oligosaccharides—primarily fructo-oligosaccharides and galacto-oligosaccharides—that selectively stimulate beneficial gut microbiota colonization in neonates. These compounds undergo enzymatic hydrolysis or transglycosylation during production, then integrate at precise concentrations to mimic human milk oligosaccharide functionality. Galacto-oligosaccharide formulations command structural priority due to their structural homology with breast milk oligosaccharides and broader regulatory acceptance across Asian jurisdictions. Organic formula applications attract premium positioning, while hypoallergenic specialty blends represent the fastest-margin expansion zone as amino acid-based carriers require higher prebiotic loading.
China's SAMR enforces infant formula registration requirements that mandate clinical evidence for prebiotic efficacy claims, compressing market access for unverified suppliers. Australia's TGA and FSANZ jointly oversee complementary medicine classifications that affect how prebiotic ingredients label health benefits. Japan's Consumer Affairs Agency monitors functional food claims under FOSHU guidelines, creating parallel compliance pathways for formula exporters. Stakeholders must track evolving substantiation standards across these three regulatory poles to avoid formulation redesign cycles.
Market Dynamics
China's SAMR registration mandates for clinical substantiation of prebiotic efficacy claims are compressing supplier access and forcing reformulation investments across the Asia-Pacific infant formula supply base.
Growth Catalysts
- Urban Premiumization:Tier-one Chinese cities and Southeast Asian metropolitan corridors exhibit concentrated demand for clinically validated oligosaccharide blends.
- SAMR Registration Framework:China's tightened infant formula rules push manufacturers toward substantiated prebiotic strains, elevating technical barriers that favor established suppliers.
- Galacto-oligosaccharide Homology:Structural similarity to human milk oligosaccharides drives regulatory acceptance across Asian jurisdictions, accelerating GOS adoption rates.
Market Restraints
- Enzymatic Input Cost Volatility:Transglycosylation enzymes and specialized carbohydrate feedstocks face price instability from bioindustrial supply fluctuations.
- Clinical Trial Capital Intensity:Neonatal gut microbiota studies require extended observation periods and substantial investment, limiting entry for mid-scale suppliers.
- Regulatory Fragmentation:Divergent substantiation standards between China's SAMR, Australia's TGA/FSANZ, and Japan's Consumer Affairs Agency force redundant compliance expenditure.
Strategic Opportunities
- Vietnam Hospital Channel Expansion:Maternity ward sampling programs remain underdeveloped relative to urban China, creating first-mover positioning potential.
- Hypoallergenic Specialty Loading:Amino acid-based formula carriers require elevated prebiotic concentrations, expanding margin capture in allergy-management segments.
- Organic Certification Premium:Australian and Chinese organic formula demand outpaces certified prebiotic supply, creating pricing power for compliant producers.
Industry Challenges
- Neonatal Microbiome Specialist Scarcity:Pediatric nutrition researchers with gut flora expertise command premium compensation, constraining R&D team scaling.
- Multi-Jurisdiction Label Harmonization:FOSHU-aligned claims in Japan conflict with SAMR clinical-evidence requirements, complicating pan-regional product architecture.
- Legacy Dairy Co-Manufacturer Integration:Traditional infant formula facilities lack enzymatic hydrolysis infrastructure, requiring substantial retrofit investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Prebiotics for Infant Formula Market |
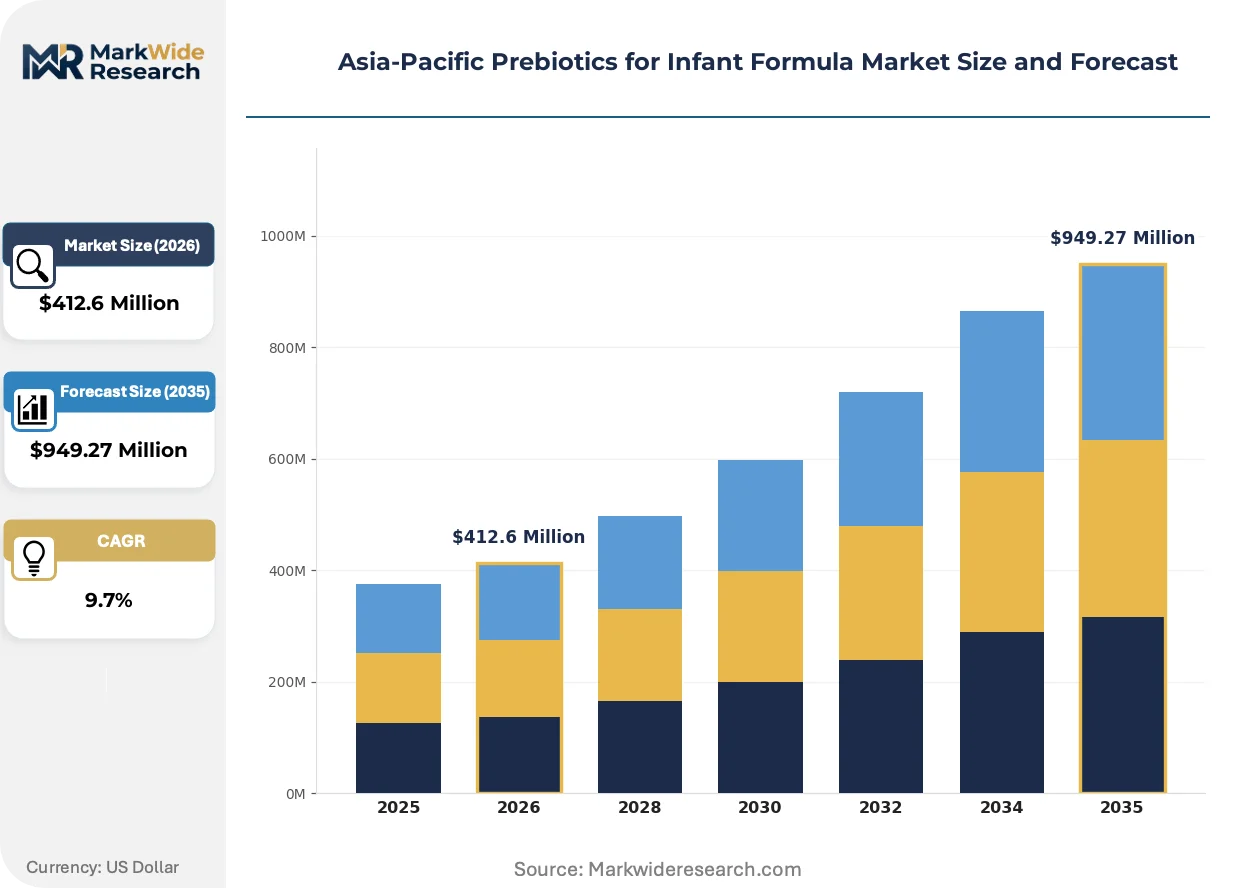
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $949.27 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FOS, GOS, Inulin, Agave Fiber Key Ingredient: Milk Powder, Soy Protein, Vegetable Oils, Nutraceuticals Application: Standard Formula, Hypoallergenic Formula, Organic Formula, Specialty Blends Distribution Channel: Online Retail, Supermarkets, Pharmacies, Health Stores |
| Companies Covered | Nestlé S.A., Abbott Laboratories, Danone S.A., Mead Johnson & Company, LLC, HiPP GmbH & Company Vertrieb KG, Bellamy's Organic, FrieslandCampina, Baolingbao Biology Co., Ltd., Quantum Hi-Tech (Guangdong) Biological Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Prebiotics for Infant Formula Market Strategic Shifts
Precision fermentation and biosynthetic oligosaccharide production are disrupting traditional extraction-based supply chains across the Asia-Pacific infant nutrition sector.
Enzymatic synthesis of human milk oligosaccharide analogs is fragmenting the incumbent galacto-oligosaccharide market structure. Premium organic brands in Australia and urban China are piloting 2'-fucosyllactose inclusion at commercial scale. This technological shift is compressing margins for conventional FOS-GOS blend suppliers while opening formulation differentiation for biosynthetic adopters.
SAMR's 2021 infant formula registration overhaul mandates clinical evidence packages for all functional ingredient claims. Manufacturers now submit neonatal gut microbiota colonization studies to secure formula registration numbers. This regulatory tightening disproportionately affects import-dependent suppliers lacking Chinese clinical trial infrastructure, accelerating localization partnerships.
Direct-to-hospital procurement contracts are displacing traditional distributor intermediaries in Vietnam and Indonesia. Maternity ward sampling programs now account for substantial first-feeding decisions in Ho Chi Minh City and Jakarta metropolitan clusters. This channel consolidation concentrates volume with suppliers possessing dedicated medical affairs teams and institutional relationship infrastructure.
Asia-Pacific Prebiotics for Infant Formula Market Segmentation
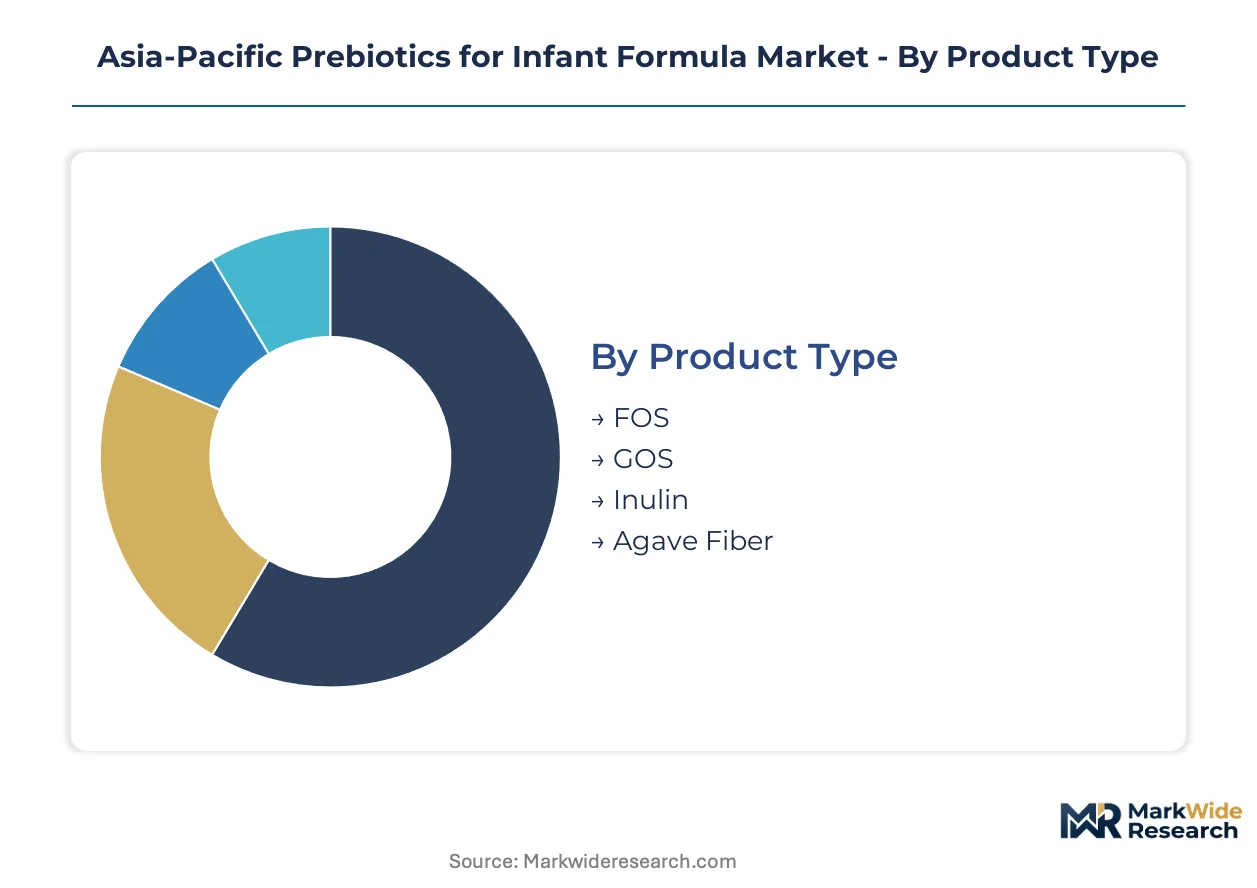
Prebiotic formulation strategies diverge sharply across the Asia-Pacific infant formula landscape based on raw material sourcing, clinical substantiation requirements, and channel access economics. Manufacturers must align segment-specific production capabilities with divergent regulatory demands from China's SAMR, Australia's TGA, and Japan's Consumer Affairs Agency.
Product Type:
Domestic production capacity for galacto-oligosaccharides concentrates in Chinese enzymatic processing hubs, while fructo-oligosaccharide supply chains remain more distributed across Southeast Asian agricultural processors.
- FOS:Fructo-oligosaccharides derive from sucrose hydrolysis using fungal β-fructofuranosidase enzymes. Chinese domestic brands favor FOS for cost-sensitive tier-two city formulations where SAMR clinical evidence requirements are less stringent than for novel oligosaccharides.
- GOS:Galacto-oligosaccharides command structural priority across the Asia-Pacific due to homology with human milk oligosaccharides. Australian organic formula exporters and premium Chinese brands specify GOS for SAMR registration submissions requiring neonatal gut colonization data.
- Inulin:Long-chain fructan extraction from chicory root supplies European-imported formula bases for Southeast Asian markets.
- Agave Fiber:Mexican-sourced agave inulin penetrates niche organic segments in Japan's FOSHU-aligned functional food channels.
GOS commands the established base. The steepest expansion runs through FOS as cost-engineered formulations penetrate Vietnam and Indonesia.
Key Ingredient:
Ingredient carrier selection determines prebiotic loading efficiency, with protein-lipid matrices requiring distinct enzymatic integration protocols.
- Milk Powder:Standard whole milk and demineralized whey bases dominate conventional formula production across China and Australia. Dairy-derived matrices accommodate higher GOS concentrations without viscosity complications during spray-drying operations.
- Soy Protein:Isolated soy protein isolates serve lactose-intolerant infant populations in Southeast Asian markets where dairy import costs constrain formulation economics. Prebiotic binding to soy polysaccharides requires modified enzymatic hydrolysis parameters.
- Vegetable Oils:Palm olein and coconut oil blends in lipid fractions affect prebiotic bioaccessibility through micellar interaction dynamics.
- Nutraceuticals:DHA and ARA co-encapsulation with oligosaccharides creates premium positioning in Chinese tier-one maternity hospital channels.
Milk powder anchors volume concentration. Soy protein gains share fastest where import dairy tariffs reshape local formulation economics.
Application:
Application-tier pricing spreads reflect clinical trial investment amortization and raw material certification grades.
- Standard Formula:Baseline FOS-GOS blends serve price-sensitive mass markets with established regulatory dossiers. Chinese domestic manufacturers concentrate production here for SAMR registration efficiency.
- Hypoallergenic Formula:Amino acid-based carriers require elevated prebiotic loading to compensate for absent dairy oligosaccharides. Australian and Japanese manufacturers command premium positioning through extensively hydrolyzed protein matrices with optimized GOS integration.
- Organic Formula:Certified organic prebiotic supply constraints create pricing power for compliant producers in Australian export markets and Chinese tier-one cities.
- Specialty Blends:Metabolic disorder-specific formulations incorporate targeted oligosaccharide ratios for neonatal gut dysbiosis management.
Standard formula maintains volume dominance. Hypoallergenic applications expand most quickly as amino acid technology costs decline.
Distribution Channel:
Channel selection determines customer acquisition economics and clinical credibility signaling.
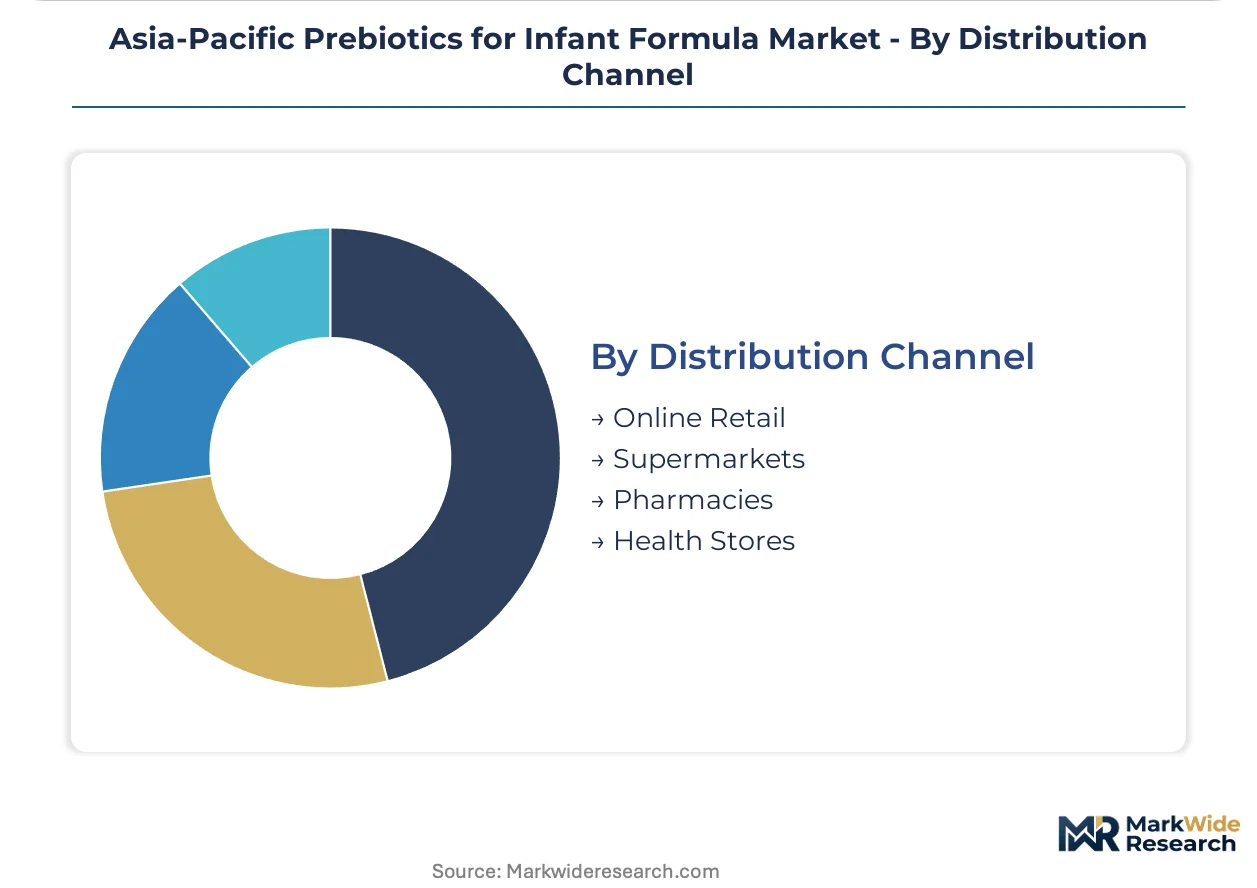
- Online Retail:Cross-border e-commerce platforms enable Australian and European brands to reach Chinese consumers outside SAMR registration requirements. Tmall Global and JD Worldwide concentrate prebiotic formula traffic for premium organic positioning.
- Supermarkets:Mass-market shelf presence in Woolworths, Coles, and Chinese hypermarket chains sustains volume for standard FOS-GOS formulations with established brand recognition.
- Pharmacies:Hospital-affiliated pharmacy networks in Vietnam and Indonesia concentrate hypoallergenic and specialty blend distribution where medical professional endorsement drives purchase decisions.
- Health Stores:Australian pharmacy chains and Japanese drugstores emphasize organic certification and FOSHU-aligned functional claims for discerning urban consumers.
Supermarkets retain the volume base. Online retail climbs the fastest as cross-border logistics infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian organic formula exporters channel prebiotic-enriched products through cross-border e-commerce into Shanghai and Guangzhou, while Vietnamese hospital procurement networks absorb specialty hypoallergenic shipments from regional manufacturing hubs.
China
Tier-one cities Shanghai, Beijing, and Shenzhen concentrate demand for clinically validated galacto-oligosaccharide blends. SAMR's infant formula registration overhaul mandates neonatal gut microbiota studies for all functional claims, forcing reformulation investments. Yangtze River Delta enzymatic processing clusters supply domestic GOS production for premium organic brands.
Australia
Organic certification premiums attract Chinese cross-border buyers through Tmall Global and JD Worldwide platforms. TGA and FSANZ jointly oversee complementary medicine classifications affecting prebiotic health benefit labeling. Victorian dairy processing corridors integrate enzymatic hydrolysis infrastructure for export-grade oligosaccharide synthesis.
Vietnam
Maternity ward sampling programs in Ho Chi Minh City and Hanoi metropolitan clusters drive first-feeding decisions for hypoallergenic specialty formulas. Hospital-affiliated pharmacy networks concentrate distribution where medical professional endorsement shapes purchase behavior. Local distributors lack dedicated medical affairs teams, creating positioning gaps for suppliers with institutional relationship infrastructure.
Japan
FOSHU-aligned functional food claims under Consumer Affairs Agency guidelines create parallel compliance pathways for formula exporters. Tokyo and Osaka urban consumers prioritize organic certification and documented gut health benefits. Kanto region pharmaceutical distributors emphasize premium positioning through drugstore channels.
Indonesia
Jakarta metropolitan corridors exhibit concentrated demand for standard FOS-GOS blends in mass-market formulations. Import dairy tariffs reshape local formulation economics, accelerating soy protein carrier adoption. Domestic manufacturers face SAMR-equivalent clinical evidence gaps for premium positioning.
Asia-Pacific Prebiotics for Infant Formula Market Competitive Environment
Listed leaders compete with private specialists across channel access and clinical substantiation capabilities. Swiss and French multinational corporations anchor premium positioning through hospital network partnerships and R&D heritage. Three archetypes dominate: diversified nutrition conglomerates with enzymatic synthesis capabilities, regional dairy processors with organic certification pipelines, and Chinese domestic specialists with SAMR registration expertise. Competitive moves concentrate on hospital channel expansion and biosynthetic oligosaccharide technology licensing.
Among diversified nutrition conglomerates, Nestlé S.A. and Danone S.A. exemplify archetypes leveraging clinical trial infrastructure for regulatory registration advantages. Abbott Laboratories occupies a position bridging hospital channel depth with neonatal specialty formulation. Chinese domestic specialists Baolingbao Biology Co., Ltd. and Quantum Hi-Tech (Guangdong) Biological Co., Ltd. represent the localization vector, anchoring SAMR-compliant supply within enzymatic processing clusters. FrieslandCampina and Mead Johnson & Company, LLC sit within the regional dairy processor tier, emphasizing organic certification pipelines for Australian and Southeast Asian export corridors.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Abbott Laboratories |
| Danone S.A. |
| Mead Johnson & Company, LLC |
| HiPP GmbH & Company Vertrieb KG |
| Bellamy's Organic |
| FrieslandCampina |
| Baolingbao Biology Co., Ltd. |
| Quantum Hi-Tech (Guangdong) Biological Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Australian organic formula exporters and Yangtze River Delta enzymatic processors lock in galacto-oligosaccharide supply access while capping price volatility for premium brands navigating SAMR registration requirements.
Pricing Analysis
Conventional extraction-based FOS-GOS blends trade at substantial discounts to next-generation biosynthetic human milk oligosaccharide analogs. Three-tier pricing structure across premium organic, clinically validated standard, and cost-engineered economy levels reflects certification grade and neonatal trial investment amortization. Pricing pressure stems from precision fermentation technology maturation compressing margins for legacy suppliers. Mass-market domestic Chinese brands exhibit highest price sensitivity, while Australian organic exporters serving cross-border e-commerce channels demonstrate lowest.
Supply Chain Analysis
Port congestion along Shanghai-Ningbo and Melbourne-Singapore trade lanes elevates inbound logistics costs for European chicory root inulin and Mexican agave fiber shipments. Enzymatic processing capacity concentrates in China, enzymatic synthesis technology clusters in Australia, and specialty amino acid carrier production anchors in Japan. Raw material dependencies include fungal β-fructofuranosidase enzymes, lactose feedstocks, and pharmaceutical-grade carbohydrate substrates. Single-source vulnerability around Chinese domestic GOS enzymatic hubs creates concentration risk. Distribution runs through hospital-affiliated pharmacy networks in Vietnam and Indonesia alongside cross-border e-commerce platforms for premium tier.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific prebiotics for infant formula market rewards organizations possessing neonatal microbiome research capabilities and multi-jurisdiction regulatory dossier expertise, assets that remain scarce relative to formulation demand.
For Market Incumbents: Shield margin position by deepening backward integration into enzymatic synthesis infrastructure within Yangtze River Delta processing corridors. Accelerate biosynthetic oligosaccharide technology licensing to outpace substitute technology threats from precision fermentation startups. Prioritize SAMR registration dossier maintenance as regulatory barriers compress access for import-dependent competitors. For New Entrants and Emerging Players: Anchor in Vietnam hospital channel expansion where maternity ward sampling programs remain underdeveloped relative to urban China penetration. Target hypoallergenic specialty loading applications where amino acid-based carriers command premium positioning and medical professional endorsement drives purchase decisions. Pursue direct-to-hospital procurement contracts displacing traditional distributor intermediaries. For Investors and Strategic Acquirers: Chinese domestic enzymatic specialists with SAMR registration expertise and established clinical trial infrastructure represent priority acquisition targets. Long-term viability hinges on regulatory compliance capabilities rather than commodity formulation scale. Watch for SAMR registration approval velocity as inflection indicator for premium tier access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Biosynthetic HMO Technology Licensing | Precision fermentation adoption fragments incumbent GOS market structure across Australian and Chinese premium tiers. |
| Hospital Channel Partnership Expansion | Direct-to-institution procurement in Ho Chi Minh City concentrates volume with medical affairs-equipped suppliers. |
| SAMR Registration Dossier Investment | Neonatal gut colonization studies secure formula registration numbers under tightened clinical evidence mandates. |
| Organic Certification Pipeline Buildout | Certified prebiotic supply constraints create pricing power in Australian export corridors and Chinese tier-one cities. |
| Enzymatic Processing Infrastructure Retrofit | Legacy dairy co-manufacturers require substantial capital deployment to integrate oligosaccharide synthesis capabilities. |
Study Parameters
Initial hypotheses were tested against primary input from pediatric nutrition R&D directors, regulatory affairs specialists at infant formula manufacturers, hospital pharmacy procurement managers, and enzymatic processing plant engineers, then refined through secondary validation against SAMR registration filings, FSANZ complementary medicine classifications, FOSHU functional food claim databases, and customs trade records for oligosaccharide feedstock movements. Bottom-up segment sizing triangulated with top-down market reconstruction across product type, application tier, and distribution channel dimensions.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within each segmentation layer. The analytical framework models enzymatic synthesis capacity expansion, regulatory registration approval timelines, and channel migration patterns alongside standard demand elasticity parameters. CAGRs derive from segment-level growth trajectory aggregation rather than single-point extrapolation.
Decision-makers should treat outputs as directional under assumptions of continued SAMR clinical evidence enforcement and stable enzymatic input cost structures; material deviation would warrant model refresh. Regulatory relaxation or biosynthetic technology disruption could accelerate substitution timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Infant Food Compliance Ready Fertility Input Market
Baby Food and Infant Formula
Baby Cereal-Based Complementary Food Market
Baby Food and Infant Formula
Europe Organic Baby Food Market
Baby Food and Infant Formula
North America Organic Baby Food Market
Baby Food and Infant Formula
GCC Baby Food and Infant Formula Market
Baby Food and Infant Formula
North America Baby Food and Infant Formula Market
Baby Food and Infant Formula
Baby Formula Market
Baby Food and Infant Formula
Functional Milk Replacers Market
Baby Food and Infant Formula
Asia Pacific Organic Baby Food Market
Baby Food and Infant Formula
Growing Up Milk Market
Baby Food and Infant Formula
Infant Nutritional Premix Market
Baby Food and Infant Formula
Organic Infant Formula Market
Baby Food and Infant Formula
Goat Milk Formula Market
Baby Food and Infant Formula
Infant Nutrition Market
Baby Food and Infant Formula
Pet Milk Replacement Products Market
Baby Food and Infant Formula
Global Lactose-Free Infant Formula Market