
 Middle East and Africa Baby Food Market | 2026-2036
Middle East and Africa Baby Food Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Baby Food Market Outlook
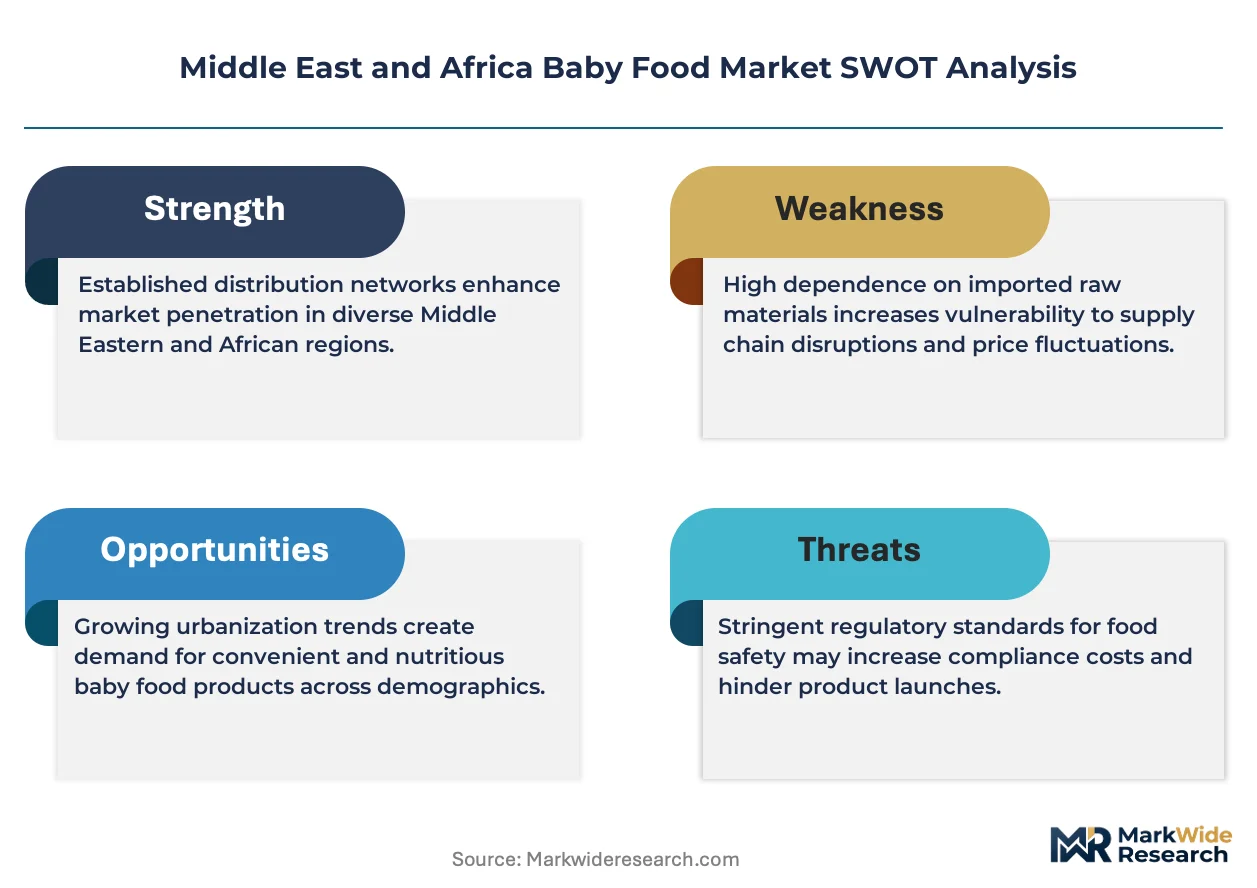
ISO 22000 certification is redrawing competitive boundaries across the Middle East and Africa Baby Food Market. Nestlé S.A. leverages its existing HACCP-compliant manufacturing footprint to sustain shelf presence in Saudi Arabian hypermarkets. Danone S.A. anchors its regional position through specialized pediatric nutrition formulations distributed via pharmacy channels in Morocco and Algeria. PZ Cussons competes on brand recognition in Anglophone West Africa, where its Cussons Baby line occupies prominent retail positioning.
Middle East and Africa baby food comprises processed infant nutrition products formulated to meet macronutrient and micronutrient requirements for children from birth to thirty-six months, typically manufactured through spray-drying, retort sterilization, or cold-aseptic filling to achieve microbiological safety and shelf stability. These products serve as breast milk substitutes or complementary feeding solutions for infants in households where maternal employment, urbanization, or medical necessity limits exclusive breastfeeding. Powdered baby food dominates volume across the region due to lower unit costs and extended shelf life in climates with variable cold chain reliability, while organic baby food captures margin pools in Gulf urban centers where disposable income supports premium positioning. Pouch packaging is displacing glass jars in modern trade channels as parents prioritize portability and reduced breakage risk during transit.
Saudi Food and Drug Authority standards, South African Bureau of Standards infant food specifications, and Nigeria's National Agency for Food and Drug Administration and Control registration requirements collectively determine which formulations gain market access across the region's fragmented regulatory landscape. Compliance with these frameworks demands reformulation investments that favor manufacturers with established quality laboratories and regulatory affairs teams. Stakeholders must monitor evolving Gulf labeling mandates and East African Community harmonization talks to anticipate where registration costs will rise or simplify.
Market Dynamics
ISO 22000 certification requirements are restructuring competitive access across Middle East and Africa baby food, forcing manufacturers to rebuild quality infrastructure or exit pharmacy and modern retail channels entirely.
Growth Catalysts
- Gulf Cooperation Council food safety mandates:SFDA and MOHAP traceability rules compel ingredient documentation upgrades, advantaging laboratories with existing HACCP systems.
- Urban working parent concentration:Dual-income households in Lagos, Nairobi, and Dubai expand prepared infant nutrition purchases as breastfeeding duration compresses.
- Spray-drying technology adoption:Domestic manufacturing investments in Nigeria and Egypt reduce import dependency for powdered formulations.
Market Restraints
- Dairy input cost volatility:Powdered milk and whey concentrate prices fluctuate with New Zealand and EU commodity auctions, compressing margin predictability for local blenders.
- Cold chain reliability gaps:Variable refrigeration infrastructure in East African Community markets limits liquid and fresh baby food shelf life.
- Extended NAFDAC registration timelines:Nigeria's National Agency for Food and Drug Administration and Control approval processes stretch 18-24 months, blocking rapid product iteration.
Strategic Opportunities
- Ethiopia and Kenya pharmacy channel expansion:Underpenetrated East African markets with rising birth rates offer first-mover positioning through clinician endorsement networks.
- Pouch packaging format conversion:Flexible retort pouches displace glass jars in Saudi Arabian and UAE hypermarkets, enabling premium pricing through portability claims.
- East African Community harmonization talks:Pending mutual recognition agreements would collapse multi-country registration costs for compliant manufacturers.
Industry Challenges
- Regulatory affairs talent scarcity:Qualified professionals capable of navigating SFDA, SABS, and NAFDAC parallel requirements command premium compensation in Johannesburg and Dubai.
- Legacy ERP integration with traceability systems:Batch-level ingredient tracking mandates force mid-tier manufacturers to replace accounting-first software with manufacturing execution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Baby Food Market |
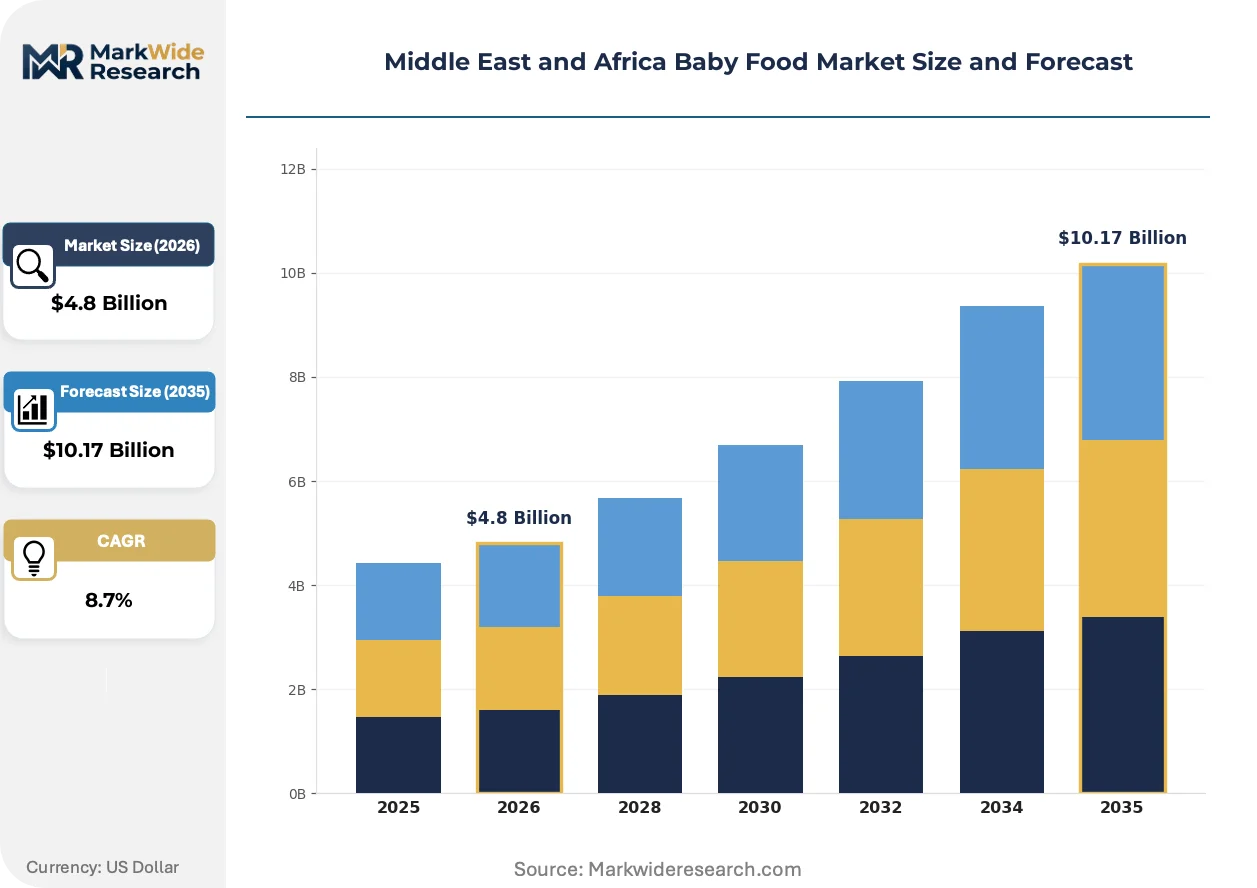
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Baby Food, Organic Baby Food, Stage 1 Baby Food, Canned Baby Food Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores Packaging Type: Glass Jars, Pouches, Tetra Packs, Plastic Containers End User: Parents, Caregivers, Pediatric Clinics, Hospitals |
| Companies Covered | PZ Cussons, Purity (Tiger Brands), Nestlé S.A., The Baby Food Company, Reckitt Benckiser Group PLC, Danone S.A., Heinz Africa Pty Ltd, Humana (DMK Baby GmbH), Abbott Laboratories, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Baby Food Market Strategic Shifts
Packaging format innovation and certification-driven procurement are redrawing how Middle East and Africa baby food reaches parents, with sustainability claims and safety documentation now primary purchase determinants.
Retort pouch technology is bifurcating the prepared baby food segment in Gulf markets. Urban Saudi and Emirati parents prioritize single-serve portability for workplace and travel feeding. This format shift compresses glass jar volume share while enabling 40% higher unit economics for compliant manufacturers.
South African Bureau of Standards infant food specifications are tightening microbiological thresholds for imported formulations. SABS certification now requires third-party laboratory verification of Cronobacter sakazakii absence. Moroccan and Algerian distributors are redirecting procurement toward SABS-accredited South African blenders to preempt customs detention.
Pharmacy channel preference is displacing traditional grocery procurement for first-time parents in Nigeria and Kenya. Hospital discharge packs and pediatrician sampling programs establish brand loyalty before supermarket exposure. This behavior concentrates volume in Anglophone West African pharmacy chains and Nairobi hospital retail outlets.
Middle East and Africa Baby Food Market Segmentation
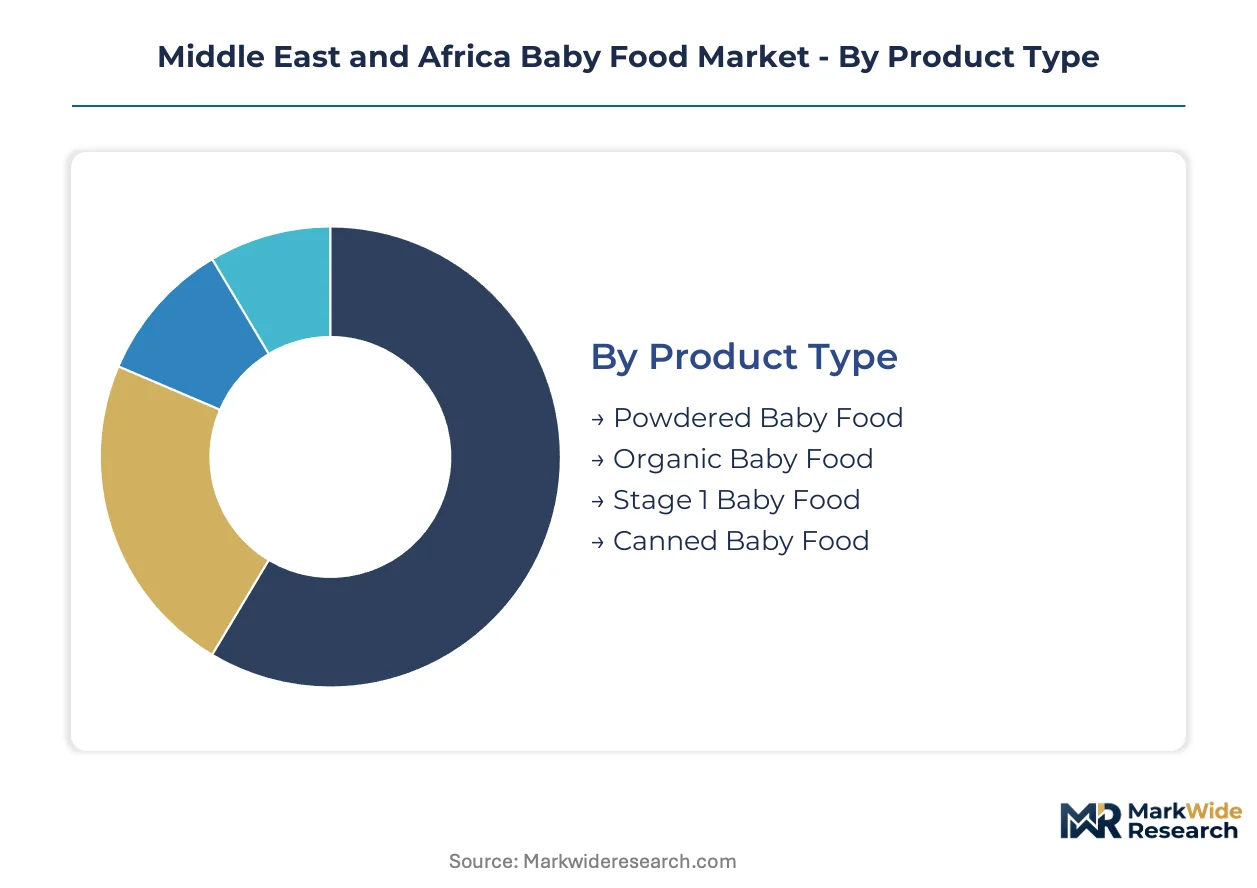
Segmentation in Middle East and Africa baby food reveals how purchasing power, infrastructure reliability, and regulatory compliance intersect to determine which product formats and channels capture margin. Manufacturers must align formulation, packaging, and route-to-market strategies with distinct household circumstances across Lagos apartments, Dubai hypermarkets, and Nairobi pharmacies.
Product Type:
Premium margin pools concentrate in formulations that command clinical endorsement or organic certification, while volume economics favor shelf-stable formats suited to unreliable cold chains.
- Powdered Baby Food:Spray-dried formulations achieve extended shelf stability without refrigeration, making them indispensable across Nigerian and Egyptian households where electricity access fluctuates. Lagos and Cairo parents prioritize 400g and 900g tins for home mixing, with demand concentrating in modern trade channels where unit economics beat ready-to-feed alternatives.
- Organic Baby Food:Certified formulations without synthetic pesticides or GMO ingredients command 40-60% price premiums in Dubai and Riyadh, where Gulf Cooperation Council disposable income supports clean-label positioning. Saudi Arabian pharmacy chains and UAE organic specialty stores rotate this segment up the share rankings as first-time parents seek ingredient transparency.
- Stage 1 Baby Food:Single-grain cereals and smooth purees for infants four to six months meet South African Bureau of Standards iron fortification mandates.
- Canned Baby Food:Retort-sterilized meals in metal containers persist in Moroccan and Algerian traditional trade where glass breakage and pouch puncture risks deter format switching.
Powdered Baby Food holds installed capacity across Nigerian and Egyptian domestic manufacturing. Organic Baby Food is rotating up the share rankings in Gulf urban centers.
Distribution Channel:
Channel selection determines compliance burden and customer acquisition cost, with pharmacy and modern trade routes demanding divergent regulatory documentation and trade terms.
- Supermarkets:Saudi Arabian and South African hypermarket chains—Carrefour, Lulu, Shoprite—consolidate shelf space for multinational brands with ISO 22000 certification, using category management fees to filter out mid-tier competitors. Nairobi and Lagos mall-based retailers increasingly dedicate aisle sections to maternal and infant care, concentrating volume among dual-income households with predictable weekly shopping patterns.
- Online Retail:Subscription-based replenishment and telemedicine-linked sampling are gaining traction among Dubai and Riyadh parents, where smartphone penetration and delivery logistics support e-commerce penetration for bulky formula tins. Jumia and Noon marketplace commissions and last-mile cold chain investments determine which brands achieve profitable digital distribution.
- Specialty Stores:Organic and natural product retailers in Cape Town and Johannesburg serve affluent parents seeking allergen-free and goat-milk-based formulations.
- Convenience Stores:Small-format Nigerian and Kenyan neighborhood shops stock single-serve pouch and small-tin emergency purchases.
Supermarkets hold installed capacity through long-term listing agreements. Online Retail is rotating up the share rankings as Gulf logistics infrastructure matures.
Packaging Type:
Material selection balances microbiological protection, transport durability, and sustainability signaling, with format conversion costs determining competitive mobility.
- Pouches:Flexible multilayer retort pouches with spout closures displace rigid formats in Saudi Arabian and UAE travel and workplace feeding occasions, where parents prioritize single-serve portability and reduced breakage. Dubai hypermarket shelf resets favor pouch-native brands with 40% higher unit economics than glass jar equivalents.
- Glass Jars:Transparent containers retain volume in Moroccan and Algerian traditional trade and South African rural distribution, where consumer trust in visible product integrity outweighs weight and breakage disadvantages. SABS and SFDA migration to pouch-friendly labeling standards is compressing long-term glass demand.
- Tetra Packs:Aseptic carton formats for ready-to-drink toddler milks suit Kenyan and Ethiopian pharmacy channel distribution where refrigeration gaps persist.
- Plastic Containers:Polypropylene tubs for cereal and snack formats dominate Nigerian mass-market price tiers.
Glass Jars hold installed capacity in North African traditional trade. Pouches are rotating up the share rankings through Gulf modern trade format resets.
End User:
User type dictates formulation specification, purchase authority, and brand loyalty formation timing, with institutional channels offering volume concentration and household channels providing margin expansion.
- Parents:First-time mothers in Lagos, Nairobi, and Dubai exercise final purchase authority but rely heavily on pediatrician and peer recommendations, making hospital discharge sampling and parenting app advertising critical touchpoints. Working parents in dual-income households compress breastfeeding duration and expand prepared formula and complementary food budgets.
- Pediatric Clinics:South African, Nigerian, and Kenyan hospital-affiliated pharmacies and private clinics prescribe specialized hypoallergenic and premature infant formulas, concentrating high-margin volume among brands with clinical trial documentation and medical representative relationships. Clinic endorsement locks in brand loyalty before supermarket exposure.
- Caregivers:Extended family and domestic staff in multigenerational Saudi and Nigerian households execute routine purchasing based on parent-specified brands.
- Hospitals:Maternity ward bulk procurement of starter formula packs for breastfeeding supplementation captures birth-moment brand introduction.
Parents hold installed capacity as the volume base. Pediatric Clinics are rotating up the share rankings through prescription-linked specialty formulation growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban working parents in Lagos, Nairobi, and Dubai compress breastfeeding duration and expand prepared infant nutrition purchases as dual-income households proliferate across metropolitan clusters.
Saudi Arabia
SFDA traceability mandates compel ingredient documentation upgrades for hypermarket shelf access. Riyadh and Jeddah parents prioritize pouch-packaged organic formulations through pharmacy and modern trade channels. Domestic manufacturing investments near Dammam reduce import dependency for powdered formulations.
Nigeria
NAFDAC registration timelines stretching 18-24 months block rapid product iteration for foreign entrants. Lagos dual-income households drive demand for 400g powdered tins through Shoprite and local pharmacy chains. Domestic blenders in Ogun State expand spray-drying capacity to capture import substitution opportunities.
South Africa
SABS infant food specifications tighten microbiological thresholds for Cronobacter sakazakii absence. Johannesburg and Cape Town pharmacy channels concentrate prescription-linked specialty formula volume. Cape Town organic specialty retailers serve affluent parents seeking allergen-free positioning.
United Arab Emirates
MOHAP food safety mandates align with Gulf Cooperation Council harmonization trends. Dubai parents adopt subscription-based online replenishment through Noon and specialized maternity apps. Sharjah distribution hubs consolidate re-export logistics for East African Community markets.
Egypt
Domestic manufacturing investments in spray-dried formulations reduce currency-exposed import bills. Cairo parents balance powdered home-mixing economics against ready-to-feed convenience in modern trade. Alexandria port infrastructure supports regional re-export to Libya and Sudan.
Middle East and Africa Baby Food Market Competitive Environment
Player mix skews toward multinational nutrition conglomerates with established HACCP laboratory infrastructure and regional regulatory affairs teams. Mid-tier African distributors compete on brand recognition and traditional trade penetration. Strategic archetypes include certification-heavy multinationals, pharmacy-channel specialists, and Anglophone West African brand owners. Dominant competitive moves center on ISO 22000 compliance investments and pouch packaging format conversions.
Among Swiss and French nutrition conglomerates, Nestlé S.A. and Danone S.A. occupy positions representing the certification-heavy multinational archetype with existing HACCP-compliant manufacturing footprints. PZ Cussons exemplifies the Anglophone West African brand owner model through established retail positioning in Nigerian and Kenyan pharmacy channels. These three anchors sit within distinct competitive vectors: multinational laboratory infrastructure, regional brand equity, and clinician endorsement networks.
| Leading Market Players |
|---|
| PZ Cussons |
| Purity (Tiger Brands) |
| Nestlé S.A. |
| The Baby Food Company |
| Reckitt Benckiser Group PLC |
| Danone S.A. |
| Heinz Africa Pty Ltd |
| Humana (DMK Baby GmbH) |
| Abbott Laboratories |
| Others |
Value Chain & Pricing Dynamics
ISO 22000 certification gates both supplier qualification and price differentiation across Middle East and Africa baby food, forcing manufacturers to absorb laboratory infrastructure costs while commanding tiered premiums for compliant formulations in Saudi Arabian and South African pharmacy channels.
Pricing Analysis
Cost-plus contracts with New Zealand GlobalDairyTrade indexation anchor input pricing for powdered milk and whey concentrate, exposing local blenders to commodity auction volatility. Three-tier pricing structure across premium organic, standard ISO-certified, and economy domestic tiers separates clinic-endorsed hypoallergenic formulations from mass-market powdered tins. Pricing pressure stems from dairy input cost compression in Nigerian and Egyptian manufacturing. Price-sensitive buyers concentrate in Lagos and Cairo mass-market channels, while Dubai and Riyadh pharmacy shoppers exhibit low sensitivity to organic premiums.
Supply Chain Analysis
Strait of Hormuz transit underwrites re-export logistics from Sharjah distribution hubs to East African Community markets, concentrating supply risk in a single maritime chokepoint. Manufacturing concentrates in Nigeria, Egypt, and Saudi Arabia for spray-dried formulations, while specialty pediatric nutrition feeds from European Union production. Raw material dependencies rest on New Zealand dairy powders, Malaysian palm oil derivatives, and EU vitamin premixes. Single-source vulnerability in whey protein isolate exposes margin predictability. Distribution runs through pharmacy chains in Anglophone West Africa and hypermarket modern trade in Gulf Cooperation Council states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa baby food market sits in cyclical recovery as Gulf Cooperation Council birth rates stabilize following pandemic-era compression, restoring volume growth to pharmacy and modern trade channels.
For Market Incumbents: Fortify ISO 22000-compliant manufacturing footprints against emerging regional blenders with domestic spray-drying capacity. Nestlé S.A. and Danone S.A. should deepen backward integration into dairy powder sourcing to offset New Zealand auction volatility. Channel control through long-term pharmacy chain listing agreements in Nigeria and Kenya blocks mid-tier encroachment. For New Entrants and Emerging Players: Anchor in Ethiopia and Kenya pharmacy channels where clinician endorsement networks remain underdeveloped relative to Nigerian market saturation. First-mover positioning through hospital discharge sampling programs captures brand loyalty before supermarket exposure. Go-to-market execution should prioritize Nairobi hospital retail outlets over modern trade expansion. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pouch packaging format conversion and retort sterilization equipment, favoring scaled manufacturers over asset-light distributors. Long-term viability over a five-to-ten year window hinges on regulatory affairs team depth across SFDA, SABS, and NAFDAC parallel requirements. Acquisition targets should demonstrate existing HACCP laboratory infrastructure rather than planned compliance investment. The signal to watch is East African Community harmonization agreement ratification collapsing multi-country registration costs.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 22000 Certification Investment | SFDA and SABS traceability mandates gate hypermarket shelf access in Riyadh and Johannesburg. |
| Pouch Packaging Format Conversion | Retort pouches enable 40% unit economics premium in Dubai and Jeddah travel-feeding occasions. |
| Domestic Spray-Drying Capacity Expansion | Egyptian and Nigerian manufacturing reduces currency-exposed import bills for powdered formulations. |
| Pharmacy Channel Partnership Development | Clinician endorsement networks in Lagos and Nairobi lock brand loyalty before supermarket exposure. |
| Organic Certification Program | EU-equivalent clean-label positioning commands margin pools in Riyadh and Dubai specialty retailers. |
Study Parameters
Initial hypotheses were tested against primary input from regulatory affairs directors at multinational nutrition conglomerates, pharmacy chain category buyers in Lagos and Nairobi, and SFDA compliance officers, then refined through secondary validation. Sources included SFDA registration filings, NAFDAC approval databases, SABS infant food specifications, and Gulf Cooperation Council trade statistics. Bottom-up volume modeling across product type, distribution channel, packaging format, and end-user segments triangulated against top-down macroeconomic drivers.
Variance decomposition across the projection horizon isolates volume growth from pricing mix effects and regional share shifts. Segmentation dimensions modeled include product formulation tier, distribution channel compliance burden, packaging material technology, and pediatric clinic versus household purchase authority. CAGRs derive from trend extrapolation moderated by regulatory event probability and infrastructure investment timelines. Forecast inputs incorporate dairy commodity auction trajectories and East African Community harmonization negotiation status.
Material uncertainties — NAFDAC registration timeline extensions, Gulf labeling mandate revisions, and New Zealand drought-driven dairy price spikes — sit outside the modeled envelope. Forecasts reflect documented assumptions about birth rate trajectories and urbanization pace. Practitioners should keep alternative scenarios live as East African Community mutual recognition agreements and SFDA traceability enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Global Oligosaccharides in Infant Nutrition Market
Baby Food and Infant Formula
South America Baby Food Market
Baby Food and Infant Formula
Pet Milk Replacement Products Market
Baby Food and Infant Formula
Infant Food Compliance Ready Fertility Input Market
Baby Food and Infant Formula
Baby Food Testing Market
Baby Food and Infant Formula
India Baby Food Market
Baby Food and Infant Formula
Infant Formula Milk Powder with A2 Beta-Casein Market
Baby Food and Infant Formula
Kids Food and Beverages Market
Baby Food and Infant Formula
Europe Baby Food and Infant Formula Market
Baby Food and Infant Formula
North America Organic Baby Food Market
Baby Food and Infant Formula
Human Milk Oligosaccharides in Infant Formula Market
Baby Food and Infant Formula
Infant Formula Market
Baby Food and Infant Formula
South America Organic Baby Food Market
Baby Food and Infant Formula
Fortified Pet Food Market
Baby Food and Infant Formula
Russia Pet Food Market
Baby Food and Infant Formula
Baby Cereal-Based Complementary Food Market