
 Baby Food Products Market | 2026-2036
Baby Food Products Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Food Products Market Outlook
Multi-source ingredient procurement is consolidating among leading manufacturers seeking supply security after pandemic-era disruptions. Nestlé S.A. leverages its vertically integrated dairy network across European alpine sourcing regions. Danone S.A. anchors its competitive position through specialized fermentation expertise in hypoallergenic formula development. HiPP GmbH & Co. Vertrieb KG differentiates via biodynamic farming contracts that sustain premium pricing in German and Austrian retail channels.
Baby food products comprise nutritionally formulated consumables designed for infants and toddlers, typically manufactured through thermal processing, aseptic filling, and controlled dehydration to achieve microbiological safety while preserving vitamin stability. These products serve the essential function of bridging nutritional gaps during developmental stages when solid food tolerance remains limited. Formula dominates value generation due to R&D intensity and clinical validation requirements, while pouches within packaging type represent the fastest-growing format driven by on-the-go feeding convenience and reduced spoilage claims. Organic ingredient type commands disproportionate margin pools as certification costs create defensible price architecture against private-label competition.
The FDA enforces infant formula quality standards under the Federal Food, Drug, and Cosmetic Act, requiring nutrient specifications and manufacturing facility registration that shape domestic market entry barriers. The EU's EFSA and EMA jointly govern novel ingredient approvals and health claim substantiation, creating a dual-track compliance burden for brands seeking European distribution. China's SAMR and NMPA administer formula registration requirements mandating local clinical trials, a provision that redirects foreign investment toward domestic production partnerships. Stakeholders must monitor evolving precision nutrition claims and microbiome science validation as the next frontier of product differentiation and regulatory scrutiny.
Market Dynamics
Dual-income household expansion is compressing feeding preparation time, forcing manufacturers to prioritize convenience formats and subscription delivery models that bypass traditional retail shelf competition.
Growth Catalysts
- EU Farm to Fork Strategy:Mandatory pesticide residue reductions and organic certification harmonization are creating premium price tiers that domestic European brands exploit against commodity imports.
- Precision fermentation:Cell-cultured dairy proteins and human-identical milk oligosaccharides are reducing allergen exposure while maintaining nutritional parity with conventional formulas.
- Urban Chinese demand:Post-2008 scandal trust rebuilding through blockchain traceability systems is accelerating domestic brand preference over foreign labels.
Market Restraints
- Organic input cost volatility:Biodynamic dairy and vegetable supply contracts carry 40-60 month price lock exposure to alpine pasture land scarcity and climate yield variance.
- Clinical trial concentration:Formula novel ingredient validation requires SAMR-mandated local infant studies in China, creating geographic lock-in for foreign R&D budgets.
- Aluminum and flexible film supply:Aseptic pouch laminate production clusters in German and Austrian specialty converters, creating single-source vulnerability for format expansion.
Strategic Opportunities
- Microbiome science validation:HMO and probiotic strain-specific health claims under EFSA novel food pathways offer first-mover margin protection against private-label replication.
- Direct-to-parent subscription:Bypassing retail slotting fees through pediatrician partnership programs and app-based replenishment locks in lifetime value across toddler transitions.
- Biodynamic certification extension:Austrian and German retail channel premium positioning creates exportable credential demand in Swiss and Benelux markets.
Industry Challenges
- Infant nutrition toxicologist scarcity:Specialized reproductive and developmental safety assessment expertise concentrates in Basel and Boston regulatory consulting clusters, inflating study design costs.
- Legacy ERP integration:Batch-level traceability requirements for EU digital product passports force mid-tier manufacturers into multi-year SAP or Oracle migration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Food Products Market |
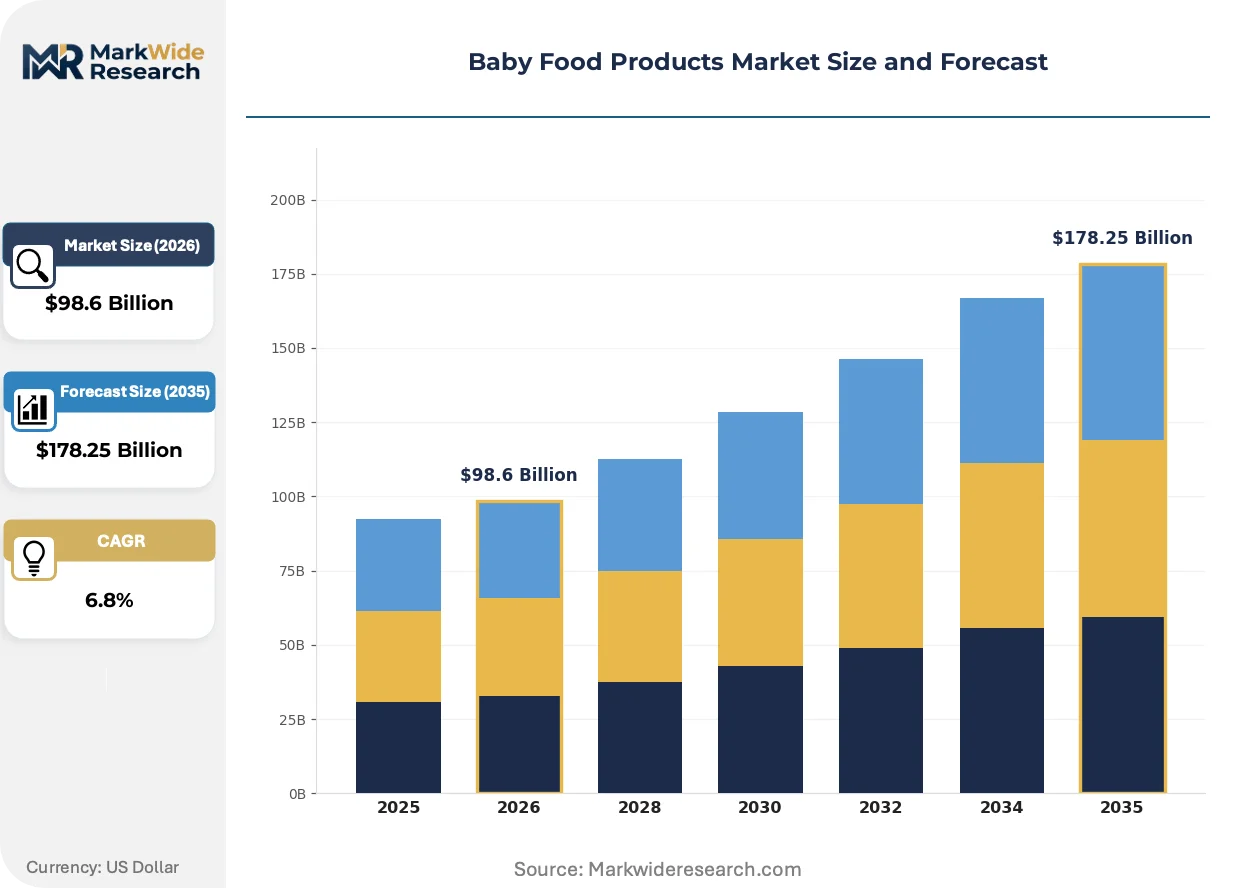
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purees, Cereal, Snacks, Formula Ingredient Type: Organic, Non-Organic, Artificial, Whole Food Packaging Type: Jar, Pouch, Box, Tray Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Stores |
| Companies Covered | Reckitt Benckiser Group PLC, The Kraft Heinz Company, Nestlé S.A., HiPP GmbH & Co. Vertrieb KG, Feihe International Inc., Danone S.A., Hero Group, Perrigo Company PLC, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Food Products Market Strategic Shifts
Active nutrition personalization and packaging sustainability mandates are forcing parallel investment in bioactive ingredient pipelines and circular material science, compressing capital allocation flexibility.
Cold-pressed HPP (high-pressure processing) technology is decentralizing thermal degradation risk in fruit and vegetable puree manufacturing. Premium organic specialists in California and Provence regions are adopting HPP lines at 18-24 month payback cycles. This shift is decentralizing shelf-stable dominance toward refrigerated fresh segments that command 2-3x price multiples.
China's SAMR formula registration renewal requirements now mandate domestic clinical trial data for all foreign-manufactured products. This policy is redirecting R&D facility investment toward Shanghai and Guangzhou biotech parks. European and North American brands are responding through joint venture structures that license formulation IP to local production partners.
Subscription-based replenishment apps with pediatrician chat integration are displacing pharmacy and hypermarket bulk purchasing among millennial parents. Direct channels capture 15-20 percentage point margin improvements versus retail. This behavioral pivot concentrates most visibly in Seoul and Singapore urban districts where smartphone penetration and delivery infrastructure density enable same-day fulfillment guarantees.
Baby Food Products Market Segmentation
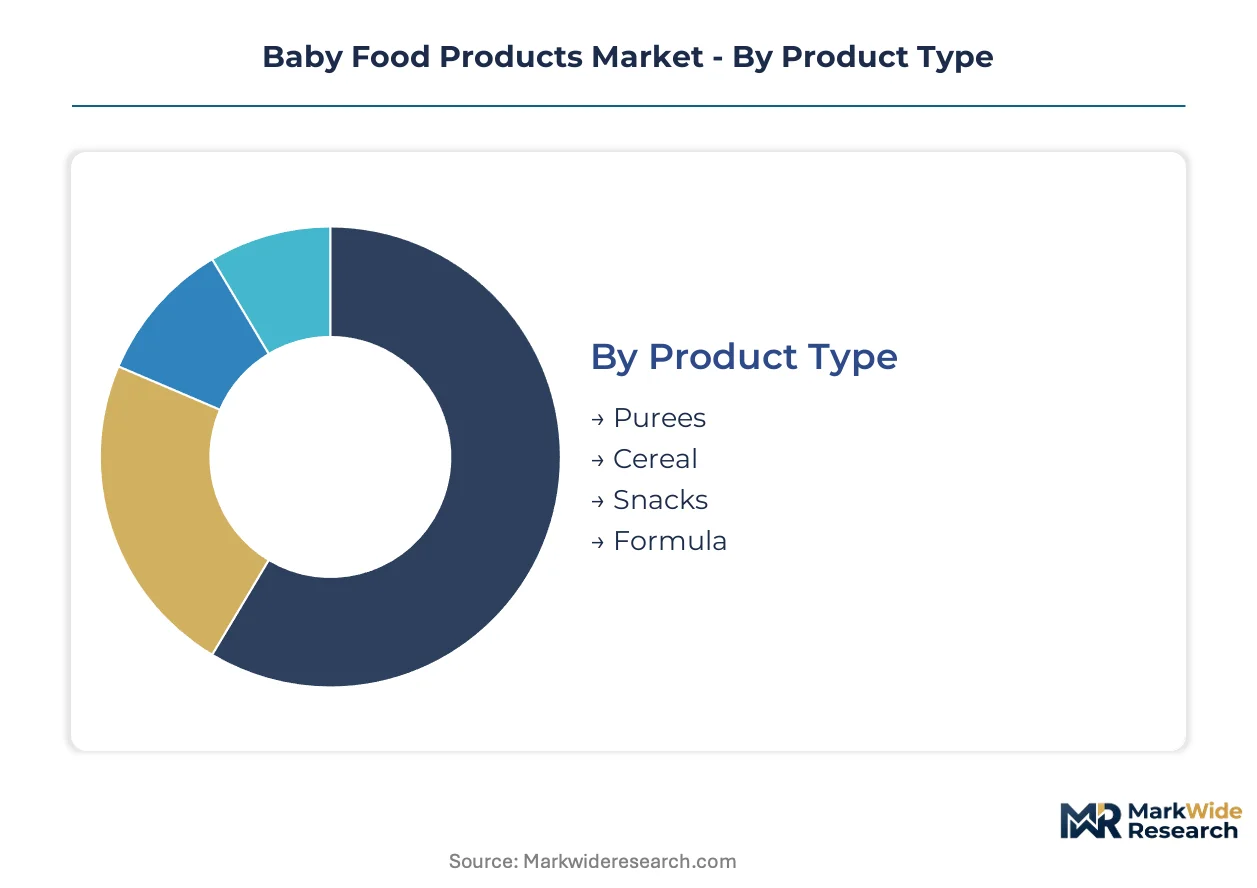
Segmentation in baby food products reveals how manufacturers align formulation complexity, certification tiers, and format convenience with distinct parental workflows and retail channel economics. Each dimension carries divergent margin structures and regulatory exposure that shape portfolio prioritization.
Product Type:
Formula operates as a standalone nutritional system requiring complete macronutrient coverage, while purees and cereals function as embedded complements within broader feeding routines.
- Formula:Clinically validated breast milk substitutes requiring precise protein, fat, and micronutrient ratios per FDA and EFSA standards. Demand concentrates among dual-income households in Chinese tier-1 cities where SAMR registration mandates local clinical validation. R&D intensity and manufacturing facility registration create steep barriers against private-label replication.
- Purees:Thermally processed fruit and vegetable blends delivering controlled texture introduction for infants transitioning to solids. Cold-pressed HPP adoption in California and Provence is displacing shelf-stable dominance toward refrigerated fresh segments commanding premium multiples.
- Cereal:Iron-fortified grain-based first foods designed for spoon-feeding readiness. Rice and oat variants dominate retail shelf space in German and Austrian organic channels.
- Snacks:Finger-food formats targeting toddler self-feeding development and portability. Puffed rice and teething biscuit demand is climbing fastest in Seoul and Singapore subscription channels.
Formula leads volumes today; snacks are gaining share fastest.
Ingredient Type:
Cost tier stratification separates certification-intensive premium positioning from commodity-accessible mass market entry points.
- Organic:USDA or EU organic certified ingredients with full supply chain traceability and prohibited synthetic inputs. Biodynamic farming contracts in Austrian alpine regions sustain 40-60 month price locks against pasture land scarcity.
- Non-Organic:Conventionally produced ingredients meeting baseline safety standards without certification premiums. Volume concentration in private-label supermarket lines across North American big-box retail.
- Artificial:Synthetic additives including colors, flavors, and preservatives now facing EU Farm to Fork Strategy phase-out mandates. Regulatory pressure is accelerating formulation reformulation toward clean-label alternatives.
- Whole Food:Minimally processed single-ingredient formats emphasizing ingredient transparency. Parental demand in Brooklyn and East London neighborhoods is driving pouch format innovation.
Non-organic maintains volume leadership; organic is expanding most quickly.
Packaging Type:
Application context determines format selection — at-home feeding tolerates traditional containers while mobility demands drive flexible format adoption.
- Pouch:Flexible laminate aseptic packaging enabling one-handed feeding and reduced spoilage claims. German and Austrian specialty converter concentration creates single-source vulnerability for format expansion.
- Jar:Traditional glass containers with established recycling infrastructure and premium perception in European retail. Glass supply chain stability supports organic brand positioning.
- Box:Dry cereal and snack formats utilizing cardboard with inner barrier liners. Shelf efficiency advantages in warehouse club and hypermarket environments.
- Tray:Rigid plastic or aluminum containers for prepared meal segments. Limited penetration outside institutional and foodservice channels.
Jar formats dominate current shelf presence; pouches show the steepest expansion trajectory.
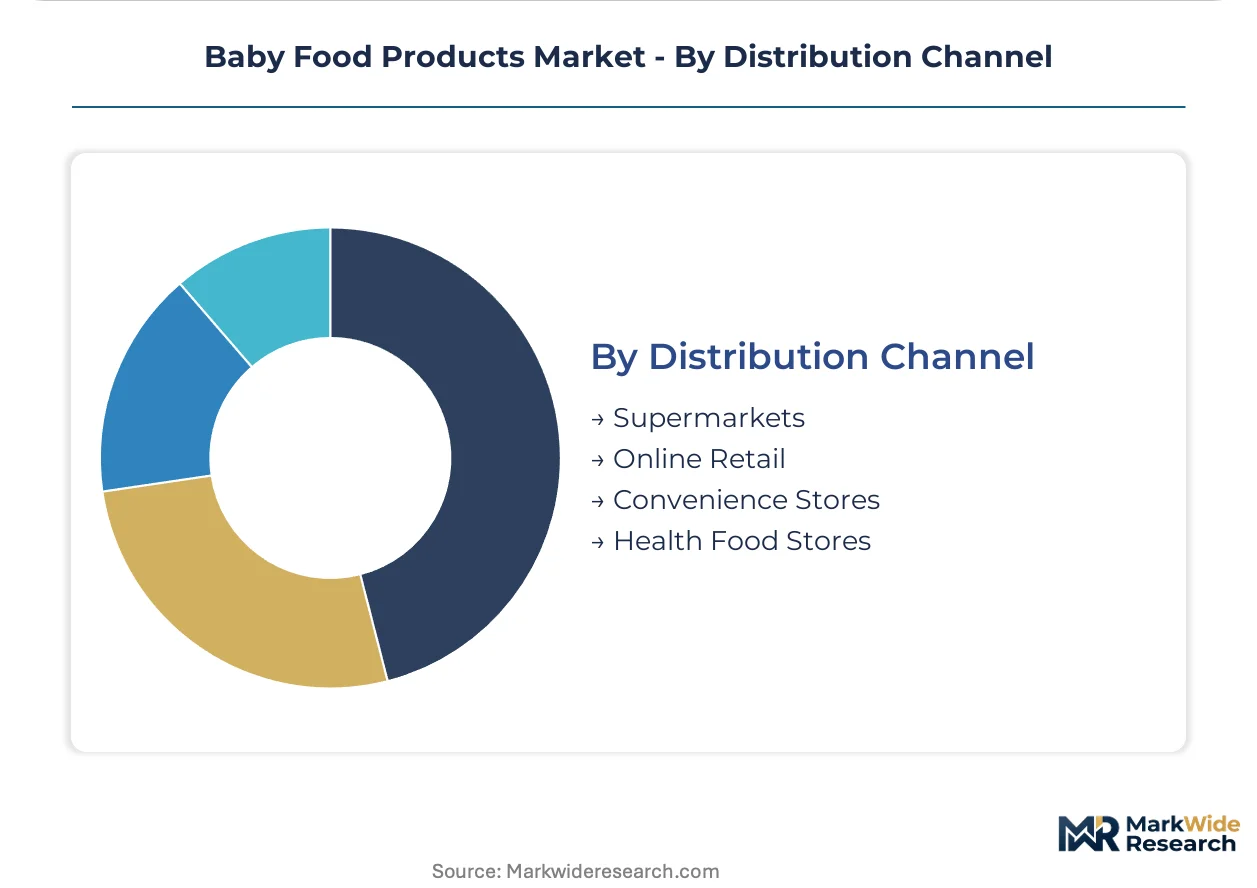
Distribution Channel:
Customer acquisition economics diverge sharply between high-touch digital subscription models and traditional retail slotting fee structures.
- Online Retail:Direct-to-parent subscription platforms with pediatrician chat integration and app-based replenishment. Seoul and Singapore urban districts concentrate same-day fulfillment infrastructure enabling 15-20 percentage point margin capture versus retail.
- Supermarkets:Traditional brick-and-mortar with slotting fee burdens and bulk purchasing behavior. Pharmacy and hypermarket concentration persists in suburban North American markets.
- Convenience Stores:Emergency replenishment and travel-oriented single-serve purchases. Limited to shelf-stable formats with extended ambient stability.
- Health Food Stores:Curated organic and specialty diet assortments with educated staff consultation. Austrian and Swiss retail channel premium positioning creates exportable credential demand.
Supermarkets retain volume dominance; online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vevey anchors formula innovation through captive dairy networks and alpine sourcing contracts that sustain premium positioning across European retail channels.
United States
FDA facility registration mandates and dual-income household expansion compress feeding preparation time, forcing manufacturers toward subscription delivery models. The agency enforces infant formula quality standards under the Federal Food, Drug, and Cosmetic Act. Greater Boston concentrates pediatric nutrition toxicology expertise that inflates study design costs for novel ingredient validation.
China
SAMR-mandated local clinical trials redirect foreign R&D investment toward Shanghai and Guangzhou biotech parks. The National Medical Products Administration administers formula registration requirements that favor domestic production partnerships. Blockchain traceability systems in tier-1 cities accelerate post-2008 scandal trust rebuilding for domestic brands.
Germany
EFSA novel food pathways for HMO and probiotic health claims create first-mover margin protection against private-label replication. The EU Farm to Fork Strategy tightens pesticide residue limits and organic certification requirements. Bavarian specialty converters cluster aseptic pouch laminate production, creating single-source vulnerability for format expansion.
Switzerland
Swissmedic governs novel ingredient approvals alongside EMA coordination for cross-border distribution. Basel concentrates infant nutrition toxicologist expertise that supports reproductive and developmental safety assessments. The country's biodynamic farming contracts sustain 40-60 month price locks against alpine pasture land scarcity.
South Korea
MFDS administers formula standards while smartphone penetration enables same-day fulfillment guarantees in Seoul urban districts. Subscription-based replenishment apps with pediatrician chat integration displace pharmacy bulk purchasing among millennial parents. Direct channels capture 15-20 percentage point margin improvements versus traditional retail slotting fees.
Baby Food Products Market Competitive Environment
Global majors compete with regional champions across certification tiers and distribution channel economics. The vendor base stratifies between vertically integrated dairy networks, specialized fermentation experts, and biodynamic farming contractors. Three archetypes dominate: scale-driven multinationals with captive supply chains, premium organic specialists with extended certification contracts, and domestic champions leveraging regulatory proximity. Capacity expansion and direct-to-parent subscription models represent the dominant competitive moves reshaping customer acquisition economics.
Within the scale-driven tier, Nestlé S.A. and Danone S.A. exemplify multinational positioning through European alpine sourcing networks and specialized formulation expertise. HiPP GmbH & Co. Vertrieb KG anchors the premium organic archetype via biodynamic farming contracts that sustain defensible price architecture in German and Austrian retail channels. Feihe International Inc. occupies a position among domestic champions rebuilding consumer trust through blockchain traceability and SAMR-aligned local production partnerships in Chinese tier-1 cities.
| Leading Market Players |
|---|
| Reckitt Benckiser Group PLC |
| The Kraft Heinz Company |
| Nestlé S.A. |
| HiPP GmbH & Co. Vertrieb KG |
| Feihe International Inc. |
| Danone S.A. |
| Hero Group |
| Perrigo Company PLC |
| Abbott Laboratories |
| Others |
Value Chain & Pricing Dynamics
Cold-pressed HPP technology adoption in California and Provence regions is compressing shelf-stable cost advantages while fragmenting supply concentration toward refrigerated fresh networks that command premium positioning. This production-method transition simultaneously elevates input costs for organic certification compliance and concentrates pouch laminate sourcing among German and Austrian specialty converters.
Pricing Analysis
Input-cost pass-through from biodynamic dairy and alpine vegetable contracts sustains premium tier elevation against commodity alternatives. Three-tier pricing structure across organic-certified, conventional, and private-label tiers separates certification investment levels from volume scale efficiencies. Pricing pressure stems from EU Farm to Fork Strategy compliance costs accelerating reformulation expenses. Dual-income households in Chinese tier-1 cities show lowest price sensitivity for clinically validated formulas, while North American big-box retail channels concentrate volume-driven private-label substitution.
Supply Chain Analysis
EU organic certification and SAMR formula registration requirements gate supplier qualification across European and Chinese production corridors. Geographic concentration clusters in Germany, Austria, and Switzerland for aseptic pouch laminates and biodynamic dairy inputs. Raw material dependencies center on alpine pasture milk, cold-pressed fruit purees, and human-identical milk oligosaccharide precursors. Single-source vulnerability in Bavarian specialty converters threatens format expansion timelines. Distribution runs through direct-to-parent subscription platforms in Seoul and Singapore alongside traditional pharmacy and hypermarket channels in suburban North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The baby food products market operates as a regulatory compounder where EU Farm to Fork Strategy pesticide reduction mandates and SAMR clinical trial requirements continuously elevate compliance barriers that favor incumbent scale.
For Market Incumbents: Anticipate precision fermentation disruption from cell-cultured dairy protein specialists by accelerating HMO and probiotic strain patent filings through EFSA novel food pathways. Deepen backward integration into biodynamic farming contracts across Austrian alpine regions to lock input costs against pasture land scarcity. Prioritize direct-to-parent subscription platform development in Seoul and Singapore to capture margin expansion from bypassing retail slotting fees.
For New Entrants and Emerging Players: Microbiome science validation capabilities offer entry wedge against legacy formulation portfolios through pediatrician partnership programs and app-based health claim substantiation. Target refrigerated fresh segments in Brooklyn and East London neighborhoods where parental demand for ingredient transparency outpaces incumbent shelf-stable dominance. Pursue white-label manufacturing partnerships with Chinese domestic brands rebuilding trust through blockchain traceability systems.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier organic specialists with extended biodynamic certification contracts but underdeveloped direct channel infrastructure. Long-term viability over the next decade hinges on regulatory compliance automation and precision nutrition IP portfolios. Monitor SAMR formula registration renewal patterns as inflection signal for foreign brand market access contraction versus domestic partnership acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Cell-cultured dairy proteins reduce allergen exposure while maintaining EFSA nutritional parity standards. |
| Biodynamic Certification Extension | Austrian and German retail channel positioning creates exportable credential demand in Swiss markets. |
| Direct-to-Consumer Platform Launch | Pediatrician chat integration in Seoul and Singapore captures 15-20 percentage point margin improvements. |
| Blockchain Traceability Implementation | Domestic Chinese brands leverage tier-1 city infrastructure to rebuild post-2008 scandal consumer trust. |
| HMO Novel Food Approval Pathway | EFSA strain-specific health claims offer first-mover margin protection against private-label replication. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with brand managers, category buyers at retailers, supply planners, and regulatory affairs specialists alongside secondary validation from FDA filings, EFSA submissions, SAMR registration databases, and Nielsen retail audit data. Bottom-up segment modeling triangulates against top-down macroeconomic indicators.
Rate-of-change decomposition across the analysis window isolates volume and value drivers through product type, ingredient certification tier, packaging format, and distribution channel segmentation. CAGRs derive from regression analysis against dual-income household expansion rates, organic input cost indices, and precision fermentation technology adoption curves. Infant nutrition toxicologist consulting rates and alpine pasture land lease data inform cost structure projections.
The model holds under stable regulatory enforcement timelines; deviation in SAMR clinical trial mandate expansion or EU Farm to Fork Strategy acceleration would shift foreign investment patterns toward domestic partnership structures. A model refresh is warranted upon material change in precision fermentation cost parity achievement or biodynamic certification harmonization across European markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Baby Formula Ingredients Market
Baby Food and Infant Formula
A2 Infant Formula Market
Baby Food and Infant Formula
Infant Formula Market
Baby Food and Infant Formula
Japan Baby Food and Infant Formula Market
Baby Food and Infant Formula
Second Stage Organic Infant Formula Market
Baby Food and Infant Formula
Baby Cereal-Based Complementary Food Market
Baby Food and Infant Formula
BRIC Organic Baby Food Market
Baby Food and Infant Formula
Asia-Pacific Baby Food Market
Baby Food and Infant Formula
Baby Fruit Puree Market
Baby Food and Infant Formula
Canned Pet Food Market
Baby Food and Infant Formula
Growing Up Milk Market
Baby Food and Infant Formula
Parenteral Formula Market
Baby Food and Infant Formula
Functional Milk Replacers Market
Baby Food and Infant Formula
Baby Food Testing Market
Baby Food and Infant Formula
Canada Baby Food Market
Baby Food and Infant Formula
Standard Milk Formula Market