
 Europe Baby Food Market | 2026-2036
Europe Baby Food Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Baby Food Market Foresight
Subscription-based replenishment services for powdered formula and organic purees is shifting how European parents purchase baby food, locking in recurring revenue streams. Nestlé SA leverages its direct-to-consumer platforms to sustain repeat orders across Western Europe. Danone SA anchors its competitive edge through specialized medical nutrition products for infants with dietary sensitivities. HiPP GmbH & Co. Vertrieb KG differentiates via biodynamic farming certifications that command premium shelf positioning.
Europe baby food comprises processed or prepared nutritional products formulated for infants and toddlers, typically meeting strict compositional standards for protein, fat, carbohydrate, and micronutrient profiles with shelf stability achieved through thermal processing or aseptic packaging. These products serve as transitional or supplementary feeding solutions when breast milk or home-prepared foods prove insufficient. Organic products within the jarred and ready-to-eat categories capture expanding margin pools as EFSA labeling requirements and parental clean-label preferences converge. The dietary preference segment shows structural momentum, with gluten-free and dairy-free formulations outpacing conventional variants in specialty retail channels.
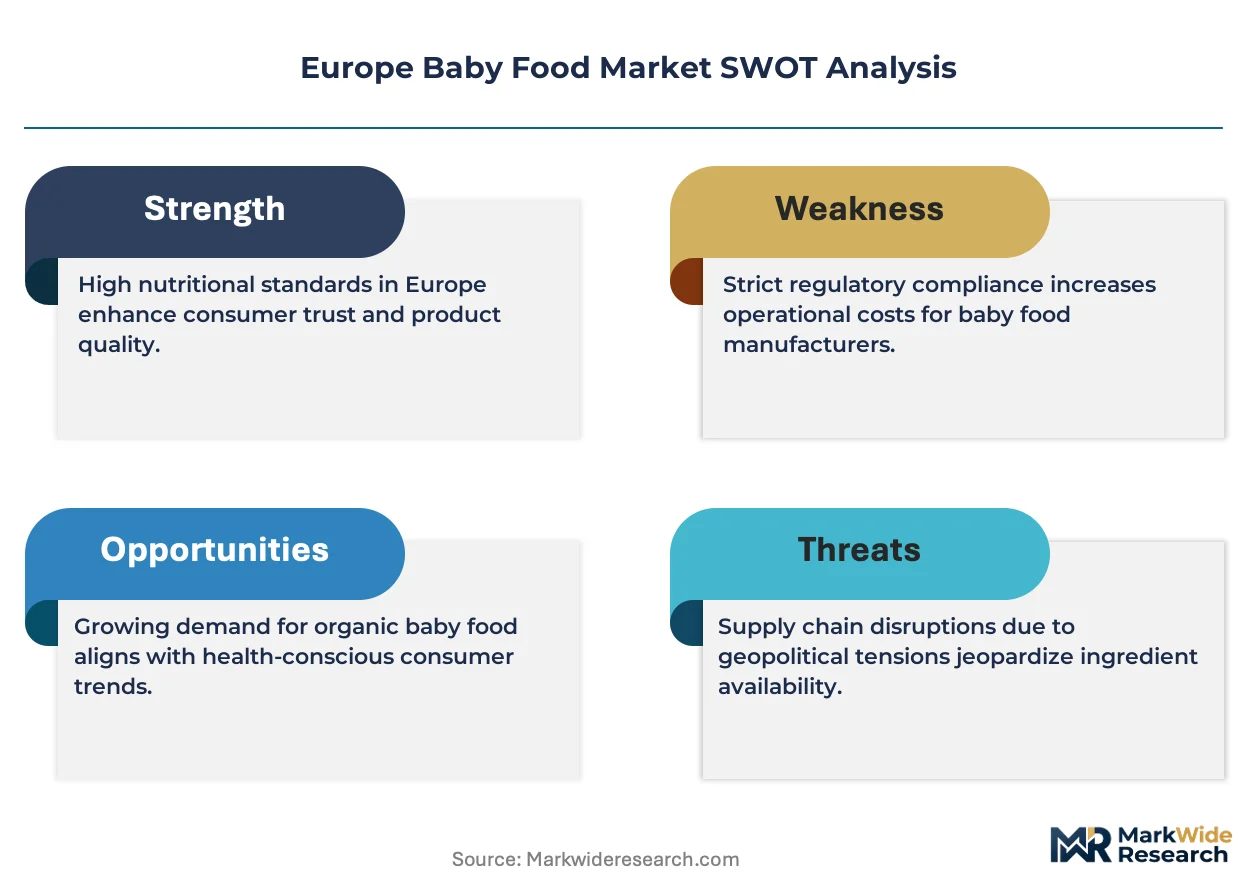
EFSA nutrient profile criteria, EU Organic Regulation 2018/848, and national food safety frameworks enforced by BfR in Germany and ANSES in France constrain formulation flexibility while elevating compliance costs for new entrants. REACH chemical safety standards and the EU Green Deal's pesticide reduction targets further tighten raw material specifications across the supply base. Stakeholders must monitor evolving ECHA substance restrictions and member-state enforcement disparities to anticipate reformulation mandates and sourcing disruptions.
Market Dynamics
EFSA compositional standards and EU Organic Regulation 2018/848 are compressing formulation flexibility while elevating compliance thresholds, forcing manufacturers to restructure supply chains around certified biodynamic ingredient sourcing and aseptic packaging investments.
Growth Catalysts
- EU Green Deal pesticide reduction targets:Regulatory pressure on conventional agriculture is accelerating certified organic acreage expansion, securing downstream supply for premium formula producers.
- Millennial parental cohorts:First-time parents born between 1981 and 1996 demonstrate disproportionate willingness to pay for clean-label jarred purees and specialized medical nutrition.
- Germany:The BfR's stringent contaminant monitoring protocols create competitive moats for domestic producers with established laboratory infrastructure and traceability systems.
Market Restraints
- Organic dairy input volatility:Biodynamic milk powder contracts trade at significant premiums to conventional alternatives, compressing gross margins for formula manufacturers.
- Supply concentration in Alpine dairy cooperatives:Three processing collectives control majority organic milk powder capacity, creating single-source vulnerability for mid-tier brands.
- REACH substance restrictions:ECHA's evolving chemical safety standards force iterative reformulation of vitamin premixes and mineral fortificants.
Strategic Opportunities
- Poland and Romania:Underpenetrated retail channels in Eastern European markets offer first-mover positioning before modern trade consolidation accelerates.
- Direct-to-consumer subscription platforms:Recurring replenishment models for powdered formula capture lifetime value while bypassing slotting fee pressure at major retailers.
- Farm to Fork Strategy traceability mandates:Blockchain-enabled ingredient provenance systems differentiate premium positioning while satisfying impending EU transparency requirements.
Industry Challenges
- Biodynamic certification timelines:Demeter and EU Organic dual accreditation requires minimum 24-month conversion periods for contract farmers, constraining rapid capacity scaling.
- Aseptic packaging line capex:Cold-fill retort systems for ready-to-feed liquid formula demand eight-figure capital commitments with extended depreciation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Baby Food Market |
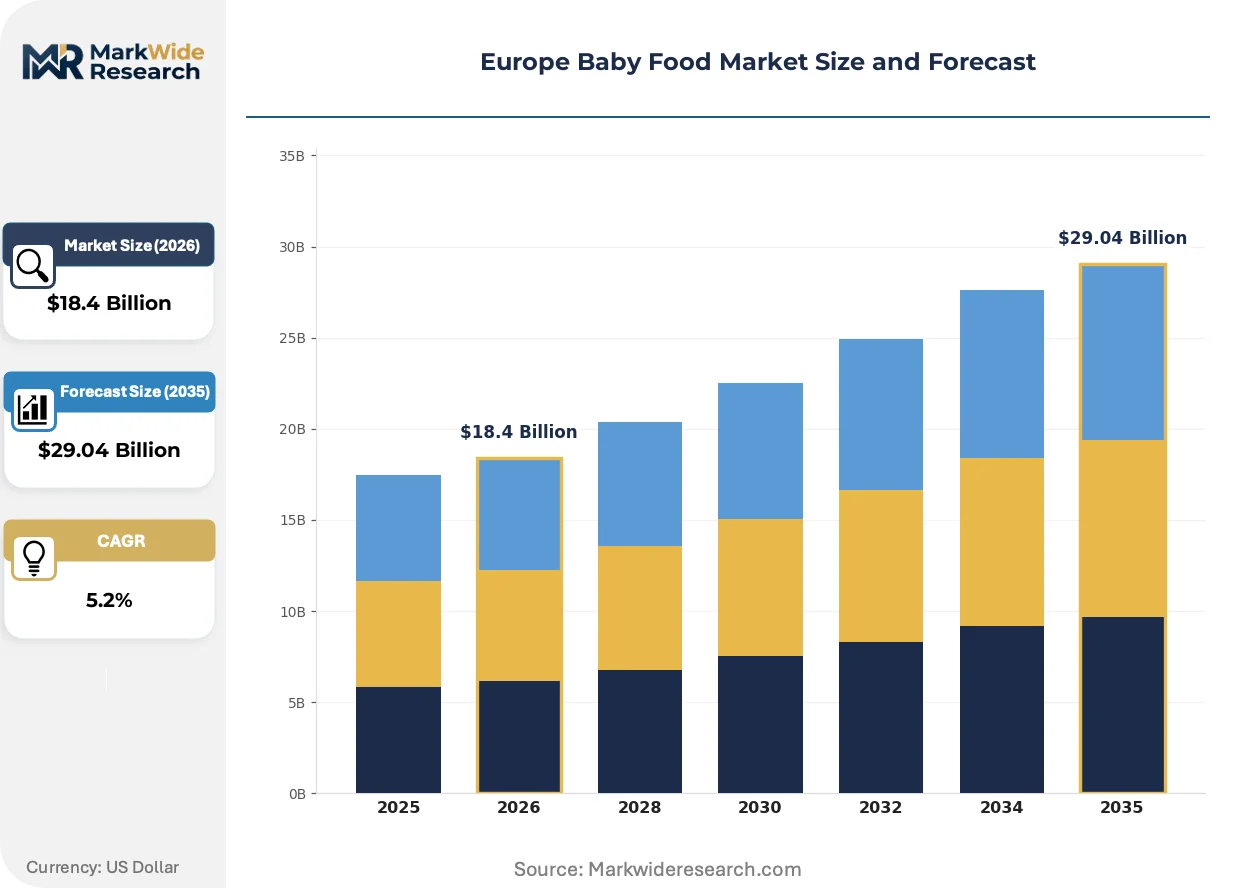
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $29.04 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered, Jarred, Organic, Ready-to-Eat Distribution Channel: Supermarkets, E-commerce, Health Food Stores, Specialty Retailers Age Group: Infants, Toddlers, Preschoolers, Mixed Age Dietary Preference: Gluten-Free, Dairy-Free, Vegetarian, Others |
| Companies Covered | Hain Celestial Group, Holle baby food GmbH, Nestlé SA, Organix Brands Company, Hero Group, Danone SA, Abbott Laboratories, Reckitt, HiPP GmbH & Co. Vertrieb KG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Baby Food Market Shifts & Advancements
Clean-label formulation pressures and precision nutrition capabilities are converging to reshape product architecture across jarred purees, powdered formulas, and specialized medical foods.
High-pressure processing (HPP) is decentralizing thermal dependency in ready-to-eat infant meals. Premium private-label manufacturers in France and the Netherlands adopt HPP lines to achieve extended refrigerated shelf life without nutrient-degrading heat treatment. This technology is decentralizing production geography by enabling smaller-batch regional facilities near urban consumption centers rather than centralized retort operations.
EU Organic Regulation 2018/848's tightened residue limits and group certification requirements took full effect in 2022. The regulation forces reformulation of conventional vitamin D and iron fortificants previously derived from synthetic sources. Specialized medical nutrition segments face disproportionate compliance burden as micronutrient density requirements conflict with natural-source availability.
Subscription-based replenishment for powdered formula and organic purees is displacing traditional stock-up purchasing at hypermarkets. Young parents in the United Kingdom and Scandinavia prioritize convenience and automatic delivery over promotional bulk buying. This behavioral pivot concentrates customer data assets with direct-to-consumer platforms while eroding traditional retailer negotiating leverage.
Europe Baby Food Market Segmentation
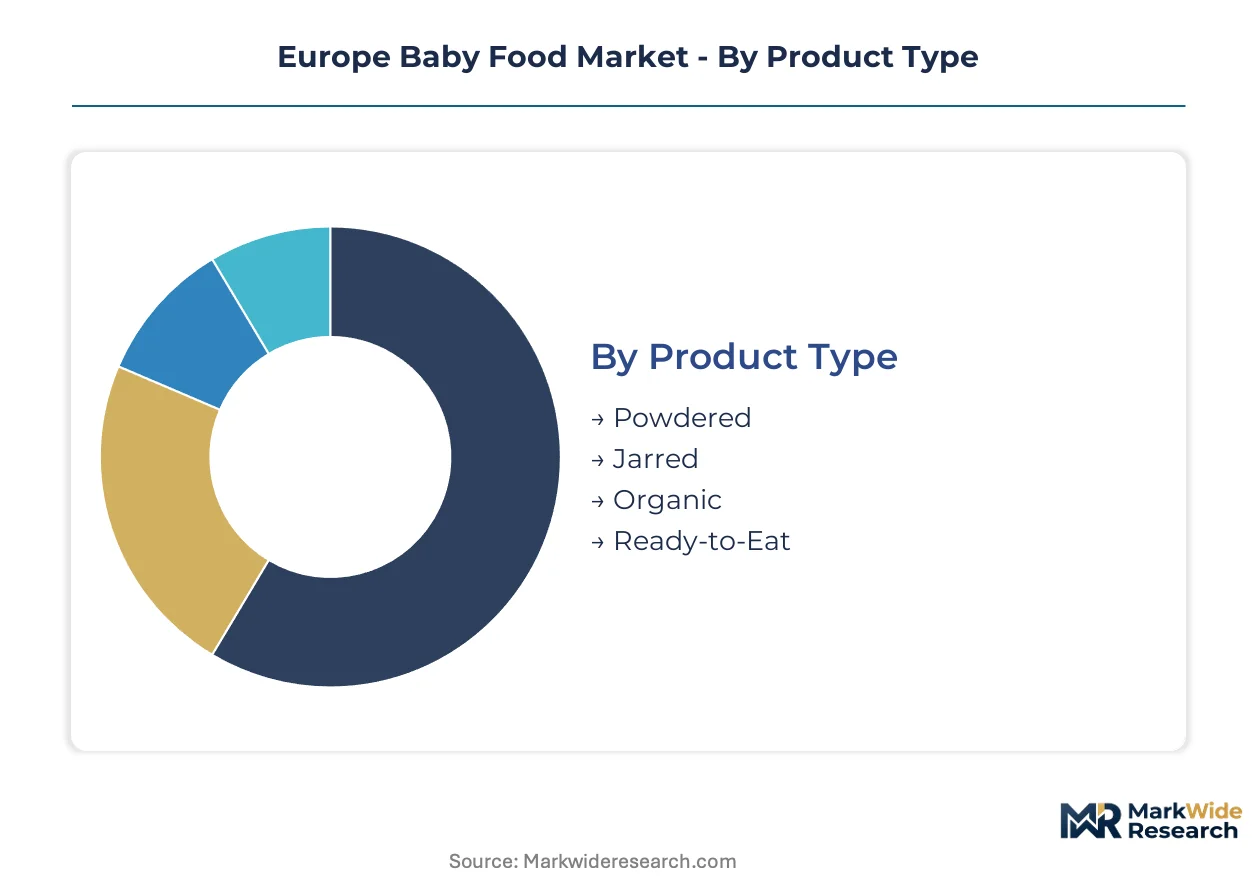
European baby food manufacturers configure production assets around distinct formulation and packaging requirements. Each segment demands specialized thermal processing lines, aseptic filling systems, or cold-chain infrastructure that locks in capital allocation decisions for multi-year depreciation cycles.
Product Type:
Powdered formula production commands the heaviest upfront investment, with spray-drying towers and nitrogen-flushing packaging lines requiring eight-figure capital commitments before first commercial batches.
- Powdered:Spray-dried milk and plant-based bases dominate hospital discharge gifting programs and WIC-equivalent subsidy schemes across France and Italy. Manufacturers in Ireland and the Netherlands concentrate capacity here to serve export demand into Middle Eastern markets.
- Jarred:Retort sterilization systems for glass and polypropylene containers achieve 18-24 month shelf stability without refrigeration. German parents in Bavaria and Baden-Württemberg purchase these formats most intensively for home pantry stocking.
- Organic:EU Organic Regulation 2018/848 mandates residue testing and traceability documentation that adds 15-20% to per-unit production costs. French retailers Carrefour and E.Leclerc allocate premium shelf positioning to certified biodynamic variants.
- Ready-to-Eat:Tetra Pak and aseptic pouch formats target travel and daycare convenience use cases. Urban parents in London and Stockholm subscribe to chilled delivery services for these perishable lines.
Powdered production absorbs the bulk of installed capacity; ready-to-eat formats are expanding most quickly.
Distribution Channel:
Channel selection determines working capital intensity, with e-commerce platforms demanding inventory flexibility while supermarket contracts impose slotting fee burdens and promotional fund obligations.
- Supermarkets:Hypermarket chains in Germany and France negotiate annual trade terms that consume 12-18% of manufacturer gross margins. Rewe Group and Auchan wield particular leverage over jarred puree assortment decisions.
- E-commerce:Direct-to-consumer subscription models for powdered formula capture recurring revenue with customer acquisition costs below traditional retail. Amazon.de and dedicated platforms like HiPP's own storefront aggregate purchase data for predictive replenishment.
- Health Food Stores:Independent retailers in Denmark and Austria stock specialized medical nutrition and biodynamic certified lines that command 40-60% price premiums over mass-market equivalents.
- Specialty Retailers:Pharmacy chains in Italy and Spain dispense prescription-required hypoallergenic formulas under national healthcare reimbursement frameworks.
Supermarket channels still move the majority of volume value; e-commerce is climbing the fastest as millennial parents abandon bulk purchasing patterns.
Age Group:
Formulation complexity escalates with developmental stage, as micronutrient density requirements and texture specifications diverge sharply between infants and older children.
- Infants:First-stage formulas replicate breast milk macronutrient profiles with whey-dominant protein ratios and added DHA/ARA fatty acids. EFSA compositional standards constrain ingredient innovation most tightly in this segment.
- Toddlers:Growing-up milks and textured purees transition children toward family table foods. UK parents show particular willingness to purchase premium-positioned variants with added prebiotic fibers.
- Preschoolers:Snack formats and fortified beverages address nutritional gaps as dietary variety expands. Convenience-focused products in pouch formats dominate this category.
- Mixed Age:Family-sized jars and multi-serve formats target households with siblings of varying ages, common in Polish and Romanian extended family structures.
Infant-focused production lines represent the largest fixed asset base; toddler formats are gaining share fastest as manufacturers extend customer lifetime value.
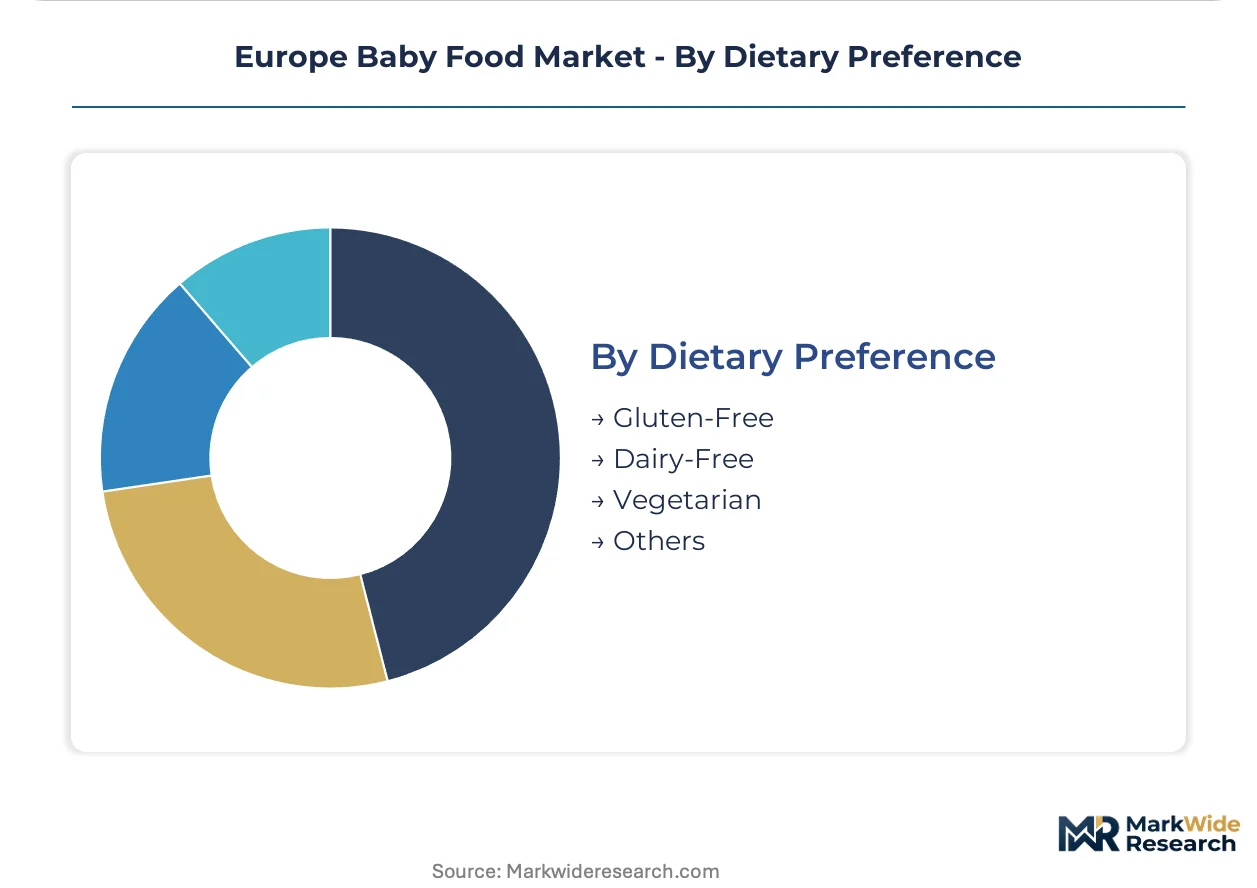
Dietary Preference:
Specialized formulations require segregated production lines and ingredient sourcing to prevent cross-contamination, elevating capital costs and constraining batch flexibility.
- Gluten-Free:Oat-based and rice-based cereals substitute for wheat and barley in early weaning products. Celiac disease screening protocols in Italian pediatric care drive disproportionate demand concentration there.
- Dairy-Free:Hydrolyzed rice protein and amino acid-based formulas serve infants with cow's milk protein allergy. ANSM in France maintains strict post-market surveillance of these medical nutrition categories.
- Vegetarian:Plant-based purees and soy or oat-based growing-up milks align with parental ethical commitments in Scandinavian markets. Stockholm and Copenhagen urban parents over-index on these purchases.
- Others:Low-protein formulations for metabolic disorders and kosher/halal certified lines serve niche religious and medical requirements across Belgium and the Netherlands.
Dairy-free production absorbs substantial dedicated capacity investment; vegetarian lines show the steepest expansion trajectory as plant-based dietary patterns diffuse from Nordic markets southward.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European baby food production through its dense cluster of organic dairy processors and biodynamic certification laboratories serving Alpine supply chains.
Germany
Millennial parents in Bavaria and Baden-Württemberg purchase jarred purees at rates exceeding European averages. The BfR enforces contaminant monitoring protocols that domestic producers with established laboratory infrastructure navigate more efficiently than importers. Stuttgart hosts specialized aseptic packaging engineering firms supplying retort sterilization systems across the Rhine corridor.
France
ANSES maintains strict post-market surveillance of hypoallergenic formulas while pharmacy chains dispense prescription-required medical nutrition. The EU Organic Regulation 2018/848's tightened residue limits force reformulation of conventional vitamin fortificants. Paris and Lyon concentrate demand for biodynamic certified lines commanding premium shelf positioning at Carrefour and E.Leclerc.
United Kingdom
Subscription-based replenishment models capture recurring revenue as London parents abandon promotional bulk buying at hypermarkets. The Competition and Markets Authority scrutinizes direct-to-consumer pricing transparency. Manchester and Birmingham distribution centers serve predictive replenishment algorithms aggregating purchase data from Amazon.de and dedicated brand storefronts.
Italy
Celiac disease screening protocols in pediatric care drive disproportionate demand for gluten-free oat-based cereals. ANSM surveillance frameworks apply to hydrolyzed rice protein formulas serving infants with cow's milk protein allergy. Milan and Bologna host regional production facilities for textured weaning products transitioning children toward family table foods.
Netherlands
High-pressure processing adoption enables smaller-batch regional facilities near urban consumption centers rather than centralized retort operations. The Dutch Food and Consumer Product Safety Authority enforces EFSA compositional standards that constrain ingredient innovation in first-stage formulas. Rotterdam port infrastructure supports spray-dried milk powder export demand into Middle Eastern markets.
Europe Baby Food Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across formulation and packaging vectors. The market structure consolidates around diversified nutrition conglomerates with captive dairy supply chains and specialized organic specialists with biodynamic certification moats. Three archetypes dominate: multinational packaged goods houses with medical nutrition divisions, family-owned organic specialists with generational farmer relationships, and private-label manufacturers serving retail consolidation. Competitive moves concentrate on direct-to-consumer platform construction and aseptic packaging line acquisition.
Within the multinational tier, Nestlé SA and Danone SA exemplify scale-driven positioning through specialized medical nutrition portfolios and direct-to-consumer infrastructure. HiPP GmbH & Co. Vertrieb KG anchors the family-owned organic specialist archetype with biodynamic farming certifications. These three entities occupy positions reflecting divergent capital allocation strategies across subscription platforms, retail channel leverage, and certified ingredient sourcing depth.
| Leading Market Players |
|---|
| Hain Celestial Group |
| Holle baby food GmbH |
| Nestlé SA |
| Organix Brands Company |
| Hero Group |
| Danone SA |
| Abbott Laboratories |
| Reckitt |
| HiPP GmbH & Co. Vertrieb KG |
| Others |
Supply & Pricing Matrix
Biodynamic-versus-conventional certification splits the European baby food market into parallel pricing universes, with Demeter-accredited organic lines commanding shelf premiums that reflect both input scarcity and the 24-month farm conversion timelines embedded in EU Organic Regulation 2018/848. This bifurcation concentrates pricing power among Alpine dairy cooperatives while forcing mid-tier brands into spot-market volatility for organic milk powder.
Pricing Analysis
Margin tightening in powdered formula reflects biodynamic milk powder contracts trading at structural premiums to conventional alternatives, compressing gross margins for manufacturers lacking captive dairy supply. Three-tier pricing structure across premium, standard, and economy levels separates Demeter-certified biodynamic lines from EU Organic equivalents and conventional formulations. Cost-down pressure on jarred purees accelerates as German hypermarket chains negotiate trade terms consuming 12-18% of manufacturer gross margins. Pharmacy-dispensed hypoallergenic formulas in France and Italy show least price sensitivity due to national healthcare reimbursement frameworks.
Supply Chain Analysis
Dual-sourcing requirements for organic dairy inputs mandate qualification across multiple Alpine cooperatives, though three processing collectives still control majority organic milk powder capacity in Germany, Austria, and Switzerland. Spray-dried milk powder production draws from lactose, whey protein concentrate, and vegetable oil inputs subject to REACH substance restrictions on vitamin premixes. Single-source vulnerability concentrates in biodynamic certification timelines, where Demeter dual accreditation demands 24-month conversion periods constraining rapid capacity scaling. Distribution runs through supermarket hypermarket chains, direct-to-consumer subscription platforms, and pharmacy networks with diverging working capital intensity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-pressure processing technology is displacing centralized retort sterilization systems, enabling smaller-batch regional facilities near urban consumption centers and rewriting capital allocation logic across jarred puree and ready-to-eat segments.
For Market Incumbents: To counter subscription-based replenishment models eroding traditional retailer negotiating leverage, Nestlé SA and Danone SA should deepen direct-to-consumer platform construction while securing captive biodynamic dairy supply through backward integration into Alpine cooperative equity stakes. Aseptic packaging line acquisition in Eastern European markets provides defensive positioning before modern trade consolidation accelerates in Poland and Romania. For New Entrants and Emerging Players: Capture underpenetrated pharmacy channels in Italy and Spain where prescription-required hypoallergenic formulas operate under national healthcare reimbursement frameworks with lower slotting fee burdens than hypermarket contracts. Specialized medical nutrition for infants with cow's milk protein allergy offers the most penetrable white-space target, with hydrolyzed rice protein formulations qualifying for ANSM post-market surveillance pathways that create regulatory moats against commodity competition. For Investors and Strategic Acquirers: Re-rating potential sits with family-owned organic specialists possessing generational farmer relationships and existing Demeter certification infrastructure, given EU Green Deal pesticide reduction targets accelerating certified organic acreage expansion. Long-term viability over the projection horizon hinges on traceability technology deployment satisfying impending Farm to Fork Strategy blockchain mandates. The signal to watch is ECHA substance restriction announcements forcing iterative reformulation of mineral fortificants.| Strategic Initiative | Industry Significance |
|---|---|
| Biodynamic Certification Investment | Demeter dual accreditation secures premium shelf positioning at Carrefour and E.Leclerc while locking in 24-month supply constraints. |
| Direct-to-Consumer Platform Launch | Subscription replenishment for powdered formula captures recurring revenue with customer acquisition costs below Rewe Group slotting fees. |
| Aseptic Packaging Line Acquisition | Cold-fill retort systems for ready-to-feed liquid formula demand eight-figure capital commitments with extended depreciation schedules. |
| Blockchain Traceability Deployment | Farm to Fork Strategy transparency requirements differentiate premium positioning while satisfying impending EU provenance mandates. |
| Eastern European Distribution Expansion | First-mover positioning in Poland and Romania before modern trade consolidation accelerates captures underpenetrated retail channels. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with brand managers at multinational nutrition conglomerates, category buyers at German and French hypermarket chains, supply planners at organic dairy cooperatives, and regulatory affairs leads navigating EFSA compositional standards. Bottom-up volume modeling across product type, distribution channel, age group, and dietary preference segments triangulated against top-down expenditure flows from national statistical offices and EU agricultural databases.
Granularity-level modeling deployed country-specific regulatory cluster assumptions for Germany, France, the United Kingdom, Italy, and the Netherlands, with formulation complexity and packaging format driving segment-level CAGRs across the analysis window. Price elasticity parameters incorporated millennial parental willingness-to-pay surveys and pharmacy reimbursement framework variations. Biodynamic certification penetration curves and high-pressure processing adoption rates served as technology-transition inputs.
The model holds under stable EU Organic Regulation 2018/848 enforcement and continued Alpine dairy cooperative supply availability; deviation in ECHA substance restriction timelines or REACH chemical safety standard revisions would shift reformulation cost assumptions materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
BRIC Organic Baby Food Market
Baby Food and Infant Formula
Asia-Pacific Prebiotics for Infant Formula Market
Baby Food and Infant Formula
Global DHA Algae Oil for Infant Formula Market
Baby Food and Infant Formula
Canned Pet Food Market
Baby Food and Infant Formula
Vietnam Pet Food Market
Baby Food and Infant Formula
Baby Juice Market
Baby Food and Infant Formula
West Africa Baby Food Market
Baby Food and Infant Formula
Cow Milk Infant Formula Market
Baby Food and Infant Formula
Indonesia Infant Nutrition Market
Baby Food and Infant Formula
Middle East and Africa Organic Baby Food Market
Baby Food and Infant Formula
A2 Infant Formula Market
Baby Food and Infant Formula
Baby Food Products Market
Baby Food and Infant Formula
GCC Baby Food and Infant Formula Market
Baby Food and Infant Formula
Europe Baby Food and Infant Formula Market
Baby Food and Infant Formula
Organic Infant Formula Market
Baby Food and Infant Formula
Organic Follow Up Formula Market