
 Growing Up Formula Market | 2026-2036
Growing Up Formula Market Size, Share, and Industry Trends Forecast 2026-2036
Growing Up Formula Market Foresight
Urban pediatric nutrition demand is shifting toward premium convenience formats as dual-income households expand across Asia and the Middle East. Nestlé leverages its dairy sourcing networks to sustain organic powder output in European and Latin American markets. Danone anchors its competitive position through specialized hypoallergenic formulation capabilities. Abbott differentiates via pharmacy-channel penetration and clinical endorsement strategies in North American and Gulf markets.
Growing up formula denotes nutrient-dense milk-based or plant-derived preparations designed for children aged one to twelve years, typically containing fortified proteins, vitamins D and K, iron, DHA, and prebiotic fibers processed through spray-drying or wet-mix evaporation to support cognitive and physical development during early childhood. Powdered formulations occupy the dominant volume position due to extended shelf stability and lower logistics costs, while ready-to-feed liquid variants capture premium margin pools among time-constrained urban consumers. The lactose-free and hypoallergenic formulation segments expand fastest as pediatric allergy diagnoses rise and parents seek digestive comfort solutions.
FDA nutrition labeling requirements and China's SAMR registration mandates for imported formulas shape product composition standards and market access timelines for international suppliers. The EU's EFSA novel food evaluations and REACH-compliant packaging rules add compliance layers for European-sourced ingredients and materials. Stakeholders must monitor evolving national protein ratio standards and digital labeling requirements as regulatory divergence between major import markets intensifies sourcing complexity.
Market Dynamics
Dual-income household expansion across Asia is compressing feeding preparation time and elevating convenience-oriented purchasing criteria for pediatric nutrition formats. This structural demand shift is redistributing volume toward ready-to-drink liquid variants and single-serve powder sachets while pressuring traditional bulk canister economics.
Growth Catalysts
- China's SAMR Registration Mandates:Tightened GB standards for protein ratios and additive limits are filtering substandard suppliers and consolidating shelf access for compliant multinationals in tier-one cities.
- Spray-Drying Equipment Modernization:Advanced nozzle atomization and inline microbiological detection are extending powder shelf stability and reducing contamination risk for export-oriented manufacturers.
- Urban Southeast Asia:Jakarta, Bangkok, and Ho Chi Minh City are concentrating demand for hypoallergenic variants as pediatric allergy diagnosis rates climb among middle-class households.
Market Restraints
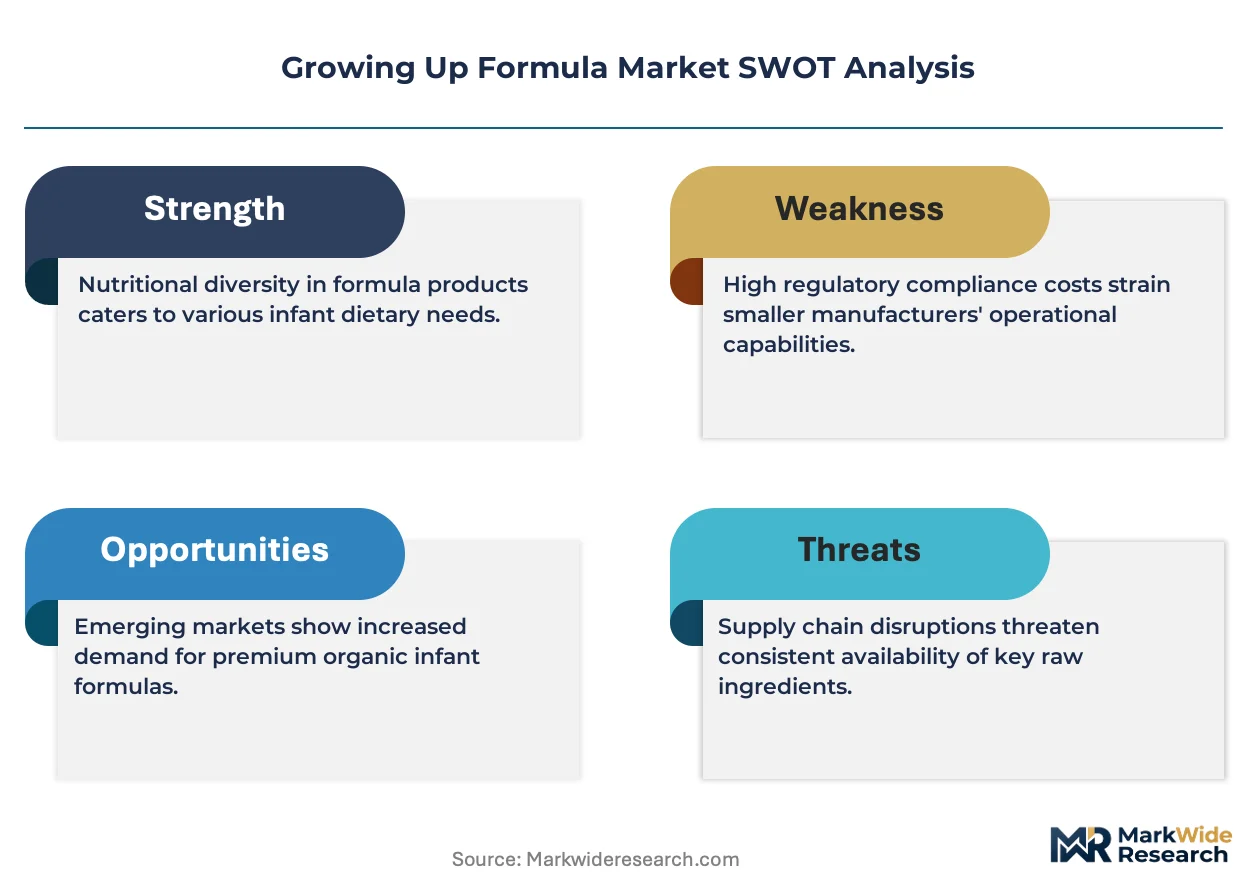
- Dairy Protein Input Volatility:Whey and casein concentrate prices fluctuate with New Zealand and EU milk powder auction cycles, compressing margin predictability for standard formulation tiers.
- Supply Concentration Risk:Organic dairy sourcing clusters in the Netherlands and Ireland create single-origin dependency for premium line extensions targeting Gulf and East Asian markets.
- Technical Limitation:Heat-sensitive bioactive compounds including certain probiotic strains degrade during standard UHT processing, constraining functional claim substantiation.
Strategic Opportunities
- Vietnam and Philippines:Modern trade penetration remains below thirty percent in secondary cities, creating whitespace for pharmacy-channel distribution partnerships and nurse endorsement programs.
- Plant-Based Protein Convergence:Pea and oat protein hydrolysates combined with precision fermentation-derived lipids are enabling vegan formulation platforms that bypass dairy supply constraints.
- EU Green Deal Packaging Rules:REACH-compliant recyclable mono-material pouches are receiving preferential retail placement in German and French hypermarkets, rewarding early compliance investment.
Industry Challenges
- Formulation Scientist Talent Scarcity:Pediatric nutrition-specific expertise in protein stabilization and micronutrient bioavailability competes with pharmaceutical and adult sports nutrition recruitment pools.
- Dual Registration Timelines:Parallel FDA GRAS self-affirmation and China's SAMR blue-hat certification processes extend product launch cycles by eighteen to thirty-six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Growing Up Formula Market |
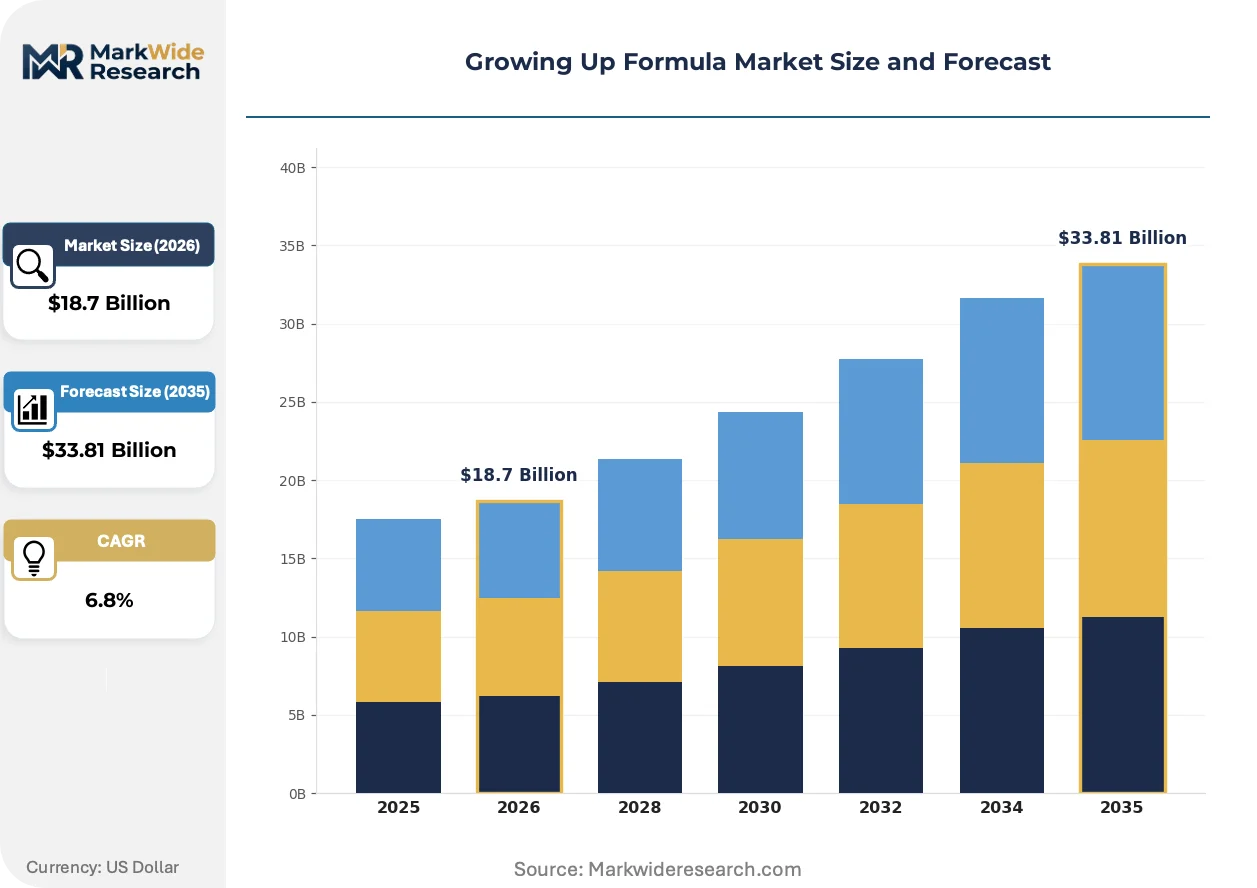
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered, Liquid, Ready-to-Feed, Organic Target Age Group: 1-3 Years, 3-5 Years, 5-7 Years, 7-12 Years Formulation Type: Standard, Lactose-Free, Soy-Based, Hypoallergenic Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Nestlé, Danone, Abbott, Reckitt, FrieslandCampina, Perrigo Nutritionals, Almarai, Novalac, Bellamy’s Organic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Growing Up Formula Market Shifts & Advancements
Precision fermentation and enzymatic hydrolysis are redefining ingredient sourcing economics while digital traceability systems reshape consumer trust mechanisms. These technical and transparency innovations are compressing traditional supply advantages and enabling new competitive entry points.
Precision fermentation for dairy-identical proteins is decentralizing organic certification dependency for premium positioning. Mid-size manufacturers in Singapore and California are adopting this technology to bypass constrained pasture-based milk supplies. The resulting ingredient flexibility is compressing geographic sourcing monopolies that historically anchored multinational cost structures.
China's evolving GB standards for infant and young child formula are mandating stricter protein ratio ceilings and additive disclosure thresholds. These rules are forcing reformulation of legacy portfolios and extending registration timelines for imported products. European and Oceanian suppliers are responding by pre-emptively adjusting composition to dual-comply with both SAMR and EFSA guidelines.
Subscription-based replenishment models are displacing traditional retail stock-up behavior among time-constrained urban parents. Direct-to-consumer platforms and pharmacy loyalty programs are capturing recurring revenue streams previously held by supermarket chains. This channel shift is most visible in Shanghai, Seoul, and Dubai where delivery infrastructure density supports just-in-time nutrition logistics.
Growing Up Formula Market Segmentation
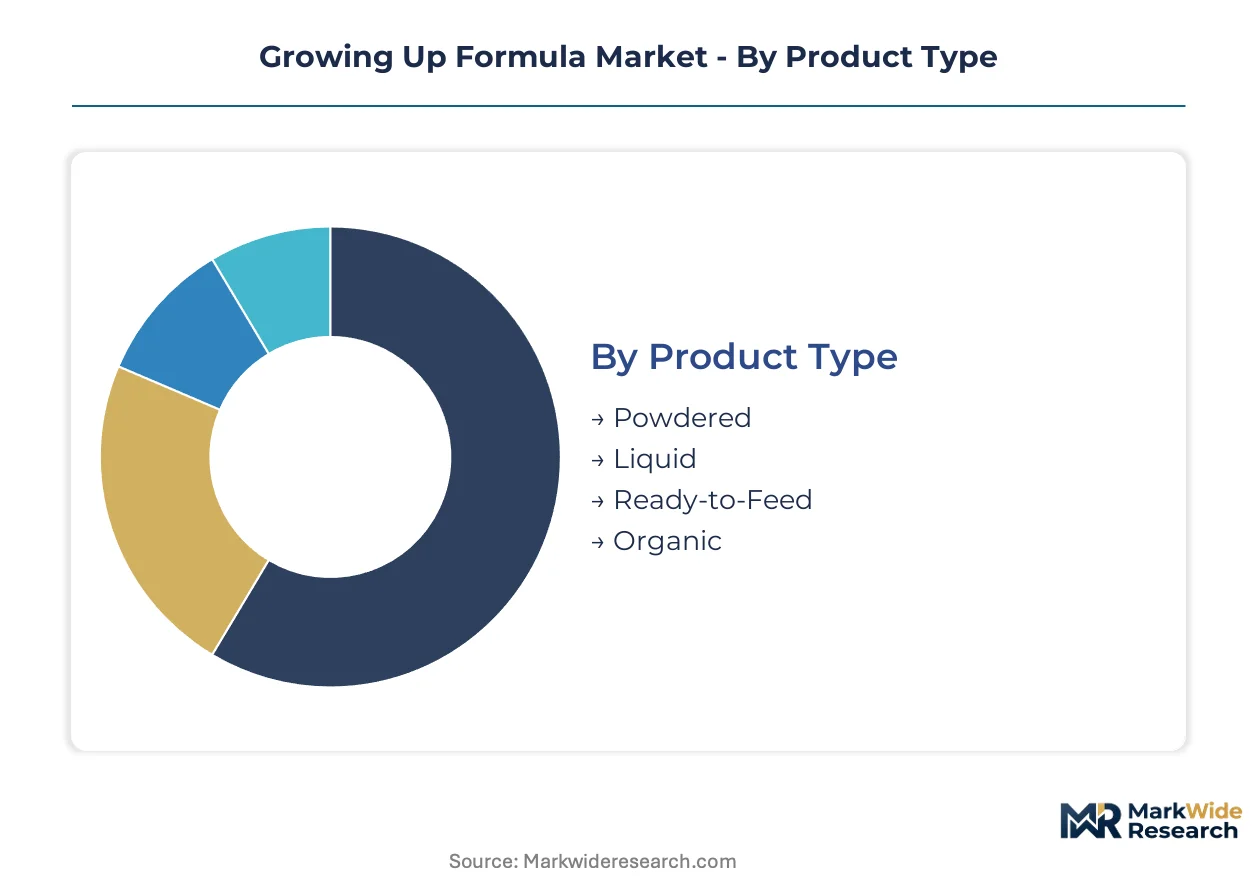
Pediatric nutrition purchasing splits sharply across preparation formats and allergen sensitivity profiles. Manufacturers calibrate production lines and shelf placement strategies around these divides.
Product Type:
Spray-drying capacity concentrates among Dutch and Irish dairy processors, dictating powder availability for export markets.
- Powdered:Spray-dried formulations with 18-24 month shelf stability dominate manufacturing economics. Urban Chinese parents in Shanghai and Beijing stock bulk canisters for cost efficiency despite longer preparation time.
- Liquid:UHT-processed ready-to-drink cartons command premium positioning through convenience. Time-constrained dual-income households in Seoul and Dubai drive demand for single-serve formats.
- Ready-to-Feed:Aseptic bottled preparations eliminate mixing steps entirely. Pharmacy channels in Riyadh and Jeddah prioritize these for travel and nighttime feeding scenarios.
- Organic:Pasture-based milk sourcing constraints limit output to premium tiers. German and French hypermarkets award preferential placement to REACH-compliant organic packaging.
Powdered formulations absorb the bulk of installed capacity; hypoallergenic-ready liquid variants are expanding most quickly.
Target Age Group:
Protein ratio requirements from China's SAMR reshape composition across developmental stages.
- 1-3 Years:Iron-fortified preparations with DHA and ARA support rapid neurological development. SAMR registration mandates filter imported products for this sensitive cohort.
- 3-5 Years:Reduced fat content aligns with transitioning diets. Southeast Asian kindergartens in Jakarta and Bangkok incorporate these into meal programs.
- 5-7 Years:Calcium and vitamin D emphasis supports bone density formation. School-based distribution pilots in Ho Chi Minh City test this segment.
- 7-12 Years:Sports-oriented protein fortification targets active pre-adolescents. Gulf markets show emerging interest for specialized athletic positioning.
The 1-3 year bracket captures dominant volume; 5-7 year applications show steepest expansion trajectory as school nutrition programs proliferate.
Formulation Type:
Clinical diagnosis rates for pediatric allergies redirect R&D investment toward modified protein structures.
- Standard:Full-lactose dairy-based formulations maintain cost leadership through conventional whey-casein ratios. Mass-market penetration remains deepest in established retail channels.
- Lactose-Free:Lactase-treated or naturally low-lactose preparations address digestive sensitivity. Urban Southeast Asian demand climbs as diagnosis awareness spreads.
- Soy-Based:Plant-derived protein isolates serve dairy-restricted diets. Formulation scientists face taste masking challenges that constrain premium positioning.
- Hypoallergenic:Extensively hydrolyzed proteins and amino acid-based preparations serve diagnosed cow's milk protein allergy. EFSA novel food evaluations govern ingredient approval timelines for European market entry.
Standard formulations retain volume leadership; hypoallergenic variants gain share fastest on rising allergy diagnosis rates.
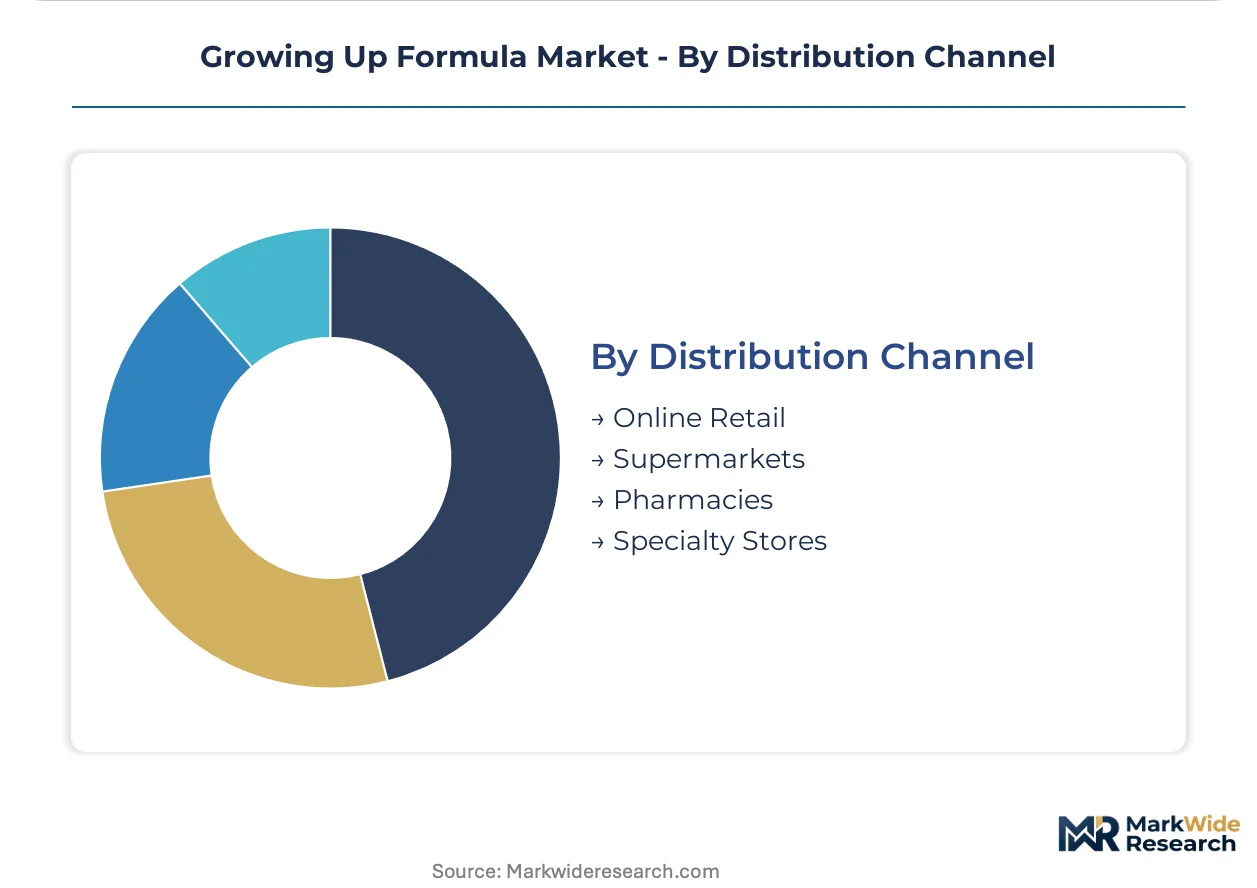
Distribution Channel:
Channel economics fragment as subscription models displace traditional stock-up behavior.
- Online Retail:Direct-to-consumer platforms capture recurring revenue through auto-replenishment algorithms. Shanghai and Seoul delivery density supports just-in-time logistics.
- Supermarkets:Hypermarket chains in tier-one Chinese cities consolidate shelf space for SAMR-registered multinationals. Bulk canister promotions face pressure from convenience-oriented formats.
- Pharmacies:Clinical endorsement channels dominate hypoallergenic and specialty formulation sales. Nurse recommendation programs drive conversion in Vietnam and Philippines secondary cities.
- Specialty Stores:Maternity and organic-focused boutiques curate premium assortments. REACH-compliant packaging requirements shape product selection in German and French specialty retail.
Supermarkets and pharmacies together hold installed channel capacity; online retail climbs fastest as urban delivery infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hainan's duty-free zones and Yangshan Free Trade Port concentrate pediatric nutrition import processing for Asia-Pacific distribution networks.
China
Shanghai and Beijing dual-income households compress feeding preparation time and elevate convenience-oriented purchasing criteria. SAMR registration mandates filter imported products through tightened GB standards for protein ratios and additive disclosure. Yangtze River Delta logistics clusters process bulk powder imports for redistribution across tier-one cities.
United States
FDA nutrition labeling requirements and GRAS self-affirmation processes extend product launch cycles for international suppliers. Pharmacy-channel penetration dominates hypoallergenic formulation sales through clinical endorsement networks. Greater Boston biotech corridors host precision fermentation startups targeting dairy-identical protein production.
Germany
REACH-compliant packaging rules and EU Green Deal sustainability mandates reshape retail placement criteria in hypermarket channels. EFSA novel food evaluations govern ingredient approval timelines for modified protein structures. Bavarian dairy processing clusters supply spray-dried formulations for premium organic line extensions.
Saudi Arabia
SFDA registration requirements and halal certification standards filter market access for imported pediatric nutrition products. Riyadh and Jeddah pharmacy channels prioritize ready-to-feed liquid formats for travel and nighttime feeding scenarios. Eastern Province distribution hubs consolidate Gulf Cooperation Council re-exports.
Vietnam
Modern trade penetration below thirty percent in secondary cities creates whitespace for pharmacy-channel distribution partnerships. Nurse endorsement programs drive conversion in Ho Chi Minh City and Da Nang metropolitan areas. Mekong Delta logistics corridors support just-in-time delivery infrastructure for subscription-based replenishment models.
Growing Up Formula Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational nutrition conglomerates anchoring premium-tier positioning through regulatory compliance scale while regional dairy cooperatives capture standard-formulation volume through cost efficiency. The market structure concentrates around three archetypes: vertically integrated dairy processors with captive ingredient supply, specialized pediatric nutrition laboratories with clinical endorsement networks, and private-label contract manufacturers serving pharmacy and retail channels. M&A activity targets precision fermentation capabilities and SAMR-registered distribution assets. Portfolio diversification into plant-based protein platforms accelerates as dairy supply constraints intensify.
Among Swiss and French nutrition conglomerates, Nestlé and Danone exemplify vertically integrated archetypes with established dairy sourcing networks. Abbott occupies a position within the clinical-channel specialist tier through pharmacy penetration strategies. These three entities represent the dominant competitive anchors shaping formulation standards and regulatory compliance benchmarks across their respective home markets and export corridors.
| Leading Market Players |
|---|
| Nestlé |
| Danone |
| Abbott |
| Reckitt |
| FrieslandCampina |
| Perrigo Nutritionals |
| Almarai |
| Novalac |
| Bellamy's Organic |
| Others |
Supply & Pricing Matrix
Global Dairy Trade auction prices for whole milk powder anchor cost structures across formulation tiers, compressing margins for standard variants while organic pasture-based inputs sustain premium positioning through constrained supply. New Zealand and EU milk powder cycles cascade into manufacturer procurement costs, forcing tiered pricing responses that separate bulk canister economics from single-serve convenience premiums.
Pricing Analysis
Lead-time-driven pricing separates just-in-time subscription replenishment from spot retail purchases, with pharmacy-channel ready-to-feed formats commanding convenience premiums over bulk powder stock-ups. Three-tier pricing structure across premium organic, standard fortified, and economy base formulations reflects certification grade and protein sourcing intensity. Cost compression in standard tiers intensifies because dairy concentrate auction volatility feeds through formulation costs. Mass-market retail buyers exhibit highest price sensitivity; clinical-channel purchasers of hypoallergenic preparations show lowest elasticity due to limited substitution options.
Supply Chain Analysis
Organic dairy sourcing rests on Netherlands and Ireland pasture-based clusters, creating geographic concentration for premium line extensions. Whey and casein concentrates draw from New Zealand auction markets; spray-drying capacity anchors in Dutch and Irish processing hubs. Single-origin dependency for organic certification creates vulnerability to pasture yield fluctuations. Distribution runs through Yangtze River Delta logistics clusters for China redistribution, with pharmacy-channel direct delivery expanding in Southeast Asian secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's SAMR registration consolidation functions as a forced exit mechanism, filtering substandard suppliers and compressing viable competitor counts to compliance-scaled multinationals. Regulatory burden escalation favors capital-deep incumbents with parallel FDA-EFSA-SAMR filing capabilities.
For Market Incumbents: To counter precision fermentation entrants disrupting organic certification premiums, Nestlé and Danone should deepen backward integration into spray-drying capacity in Ireland and the Netherlands while accelerating SAMR-registered SKU expansion across tier-one Chinese cities. Captive control over pasture-based milk supplies preserves premium tier pricing power against lab-grown protein substitutes.
For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest barrier entry point, bypassing hypermarket slotting fees that consolidate shelf access for established multinationals. Vietnam and Philippines pharmacy channels present penetrable whitespace where nurse endorsement programs convert at lower customer acquisition cost than saturated Chinese tier-one cities. Plant-based protein convergence enables differentiation without dairy supply dependency.
For Investors and Strategic Acquirers: Distressed-cycle entries favor SAMR-registered distribution assets in China's Yangtze River Delta logistics corridor, where registration timeline compression creates scarcity value for compliant import platforms. Long-term viability centers on dual-registration capability spanning FDA GRAS and SAMR blue-hat certification. Watch precision fermentation cost curves as the inflection signal for organic premium erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Investment | Decentralizes organic certification dependency for premium positioning against pasture supply constraints. |
| SAMR Registration Acceleration | Compresses market access timelines for imported formulations in Shanghai and Beijing retail channels. |
| Pharmacy Channel Expansion | Captures hypoallergenic conversion through clinical endorsement networks in Vietnam secondary cities. |
| Subscription Platform Launch | Displaces traditional retail stock-up behavior among time-constrained dual-income urban households. |
| Plant-Based Formulation Development | Bypasses dairy protein input volatility through pea and oat hydrolysate sourcing. |
Research Methodology
Document review covered SAMR registration filings, FDA GRAS determinations, and Global Dairy Trade auction records, complemented by interviews with pediatric nutrition formulation scientists, pharmacy channel procurement managers, and dairy processing plant operators. Secondary validation drew from EFSA novel food evaluation databases, EU REACH packaging compliance registries, and Southeast Asian modern trade penetration reports. Bottom-up SKU-level volume estimates triangulated against top-down category spend analyses across the analysis window.
Cross-referencing historical registration timeline data against expert panel input shaped the analytical framework across product format, target age group, formulation type, and distribution channel dimensions. CAGRs derived from segmented growth rate blending incorporated spray-drying capacity expansion schedules and precision fermentation cost curve trajectories throughout the forecast period. Modeled inputs included China's evolving GB protein ratio standards and urban household dual-income expansion rates.
Inputs from SAMR and FDA regulatory databases were available through the study window; gaps in real-time precision fermentation production cost data introduce uncertainty bands around plant-based formulation penetration assumptions. Forecasts reflect documented assumptions regarding registration timeline compression and dairy auction price volatility. Regulatory divergence between major import markets and bioactive compound stability under UHT processing warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
South America Organic Baby Food Market
Baby Food and Infant Formula
Global Oligosaccharides in Infant Nutrition Market
Baby Food and Infant Formula
BRIC Organic Baby Food Market
Baby Food and Infant Formula
Infant Nutrition Market
Baby Food and Infant Formula
Middle East and Africa Baby Food Market
Baby Food and Infant Formula
Organic Baby Food Market
Baby Food and Infant Formula
Europe Organic Baby Food Market
Baby Food and Infant Formula
Human Milk Oligosaccharides in Infant Formula Market
Baby Food and Infant Formula
Pet Milk Replacers Market
Baby Food and Infant Formula
Baby Infant Formula Market
Baby Food and Infant Formula
Baby Fruit Puree Market
Baby Food and Infant Formula
Vietnam Pet Food Market
Baby Food and Infant Formula
Canada Baby Food Market
Baby Food and Infant Formula
Infant Food Compliance Ready Fertility Input Market
Baby Food and Infant Formula
Organic Infant Formula Market
Baby Food and Infant Formula
Second Stage Organic Infant Formula Market