
 Baby Juice Market | 2026-2036
Baby Juice Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Juice Market Outlook
EU pesticide residue regulations for processed infant foods is realigning the cost-of-entry calculus for new entrants, forcing reformulation investments that favor established operators with in-house laboratories. Nestlé leverages its vertically integrated European supply chain to preempt compliance costs across multiple jurisdictions. Danone anchors its competitive position through specialized organic sourcing partnerships that lock in premium-grade fruit supplies. HiPP sustains market presence by dominating the German-speaking organic baby food channel with decades of brand equity in residue-free cultivation standards.
Baby juice comprises pasteurized, diluted fruit or vegetable extracts formulated for infants transitioning from breast milk or formula, typically standardized to lower acidity and reduced natural sugar concentrations than conventional juices. The manufacturing process relies on cold-aseptic filling and high-pressure processing to preserve vitamin content while eliminating pathogens without chemical preservatives. Organic juice commands disproportionate margin pools as certification barriers limit supplier proliferation and sustain price premiums across European and North American retail channels. Pouches represent the fastest-growing packaging format, displacing traditional bottles in on-the-go consumption scenarios through reduced weight and improved portion control for caregivers.
The FDA governs acidified food regulations and infant food labeling requirements in the United States, while EFSA sets maximum residue thresholds and nutritional claim standards across European member states. BIS certification requirements in India add another compliance layer for imported formulations seeking access to emerging middle-class consumers. Stakeholders must monitor divergence between regional additive approval lists, as a preservative permitted under FDA guidelines may face automatic exclusion under EFSA's stricter precautionary principle for infant-targeted products.
Market Dynamics
EU pesticide residue limits for processed infant foods are compressing formulation flexibility and elevating laboratory infrastructure from cost center to competitive barrier, forcing new entrants to absorb compliance investments that established operators amortize across multi-jurisdictional volumes.
Growth Catalysts
- Clean-label purchasing:Parents of infants aged six to thirty-six months prioritize ingredient transparency, expanding addressable demand for certified organic formulations with simplified supply chains.
- EFSA maximum residue thresholds:Tightened standards for pesticides in processed baby foods create regulatory differentiation that rewards operators with in-house testing capabilities and residue-free cultivation partnerships.
- Pouch packaging adoption:Flexible, lightweight formats displace rigid bottles in on-the-go consumption scenarios, unlocking incremental retail shelf space and portion-control value propositions for caregivers.
Market Restraints
- Organic input cost volatility:Premium-grade fruit supply concentrates in contracted grower networks, exposing margins to weather-driven yield fluctuations and certification maintenance expenses.
- Cold-aseptic filling capex intensity:Pathogen elimination without chemical preservatives demands high-pressure processing equipment that compresses returns for sub-scale manufacturers.
- Regional additive approval divergence:Preservatives permitted under FDA acidified food regulations face automatic exclusion under EFSA's precautionary principle, fragmenting formulation standardization.
Strategic Opportunities
- Indian middle-class expansion:BIS certification requirements filter import competition, creating first-mover advantage for compliant operators targeting emerging urban consumers.
- Vegetable extract diversification:Carrot, beet, and spinach formulations remain underdeveloped relative to fruit-dominant portfolios, offering white space in micronutrient positioning.
- Specialized organic sourcing partnerships:Long-term contracts with residue-free cultivators lock in supply security and preempt competitor access to premium-grade inputs.
Industry Challenges
- Multi-jurisdictional compliance talent:Navigating simultaneous FDA, EFSA, and BIS requirements demands regulatory specialists with cross-border infant food expertise that commands premium compensation.
- High-pressure processing integration:Retrofitting legacy thermal pasteurization lines with cold-aseptic systems triggers extended downtime and throughput disruption during transition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Juice Market |
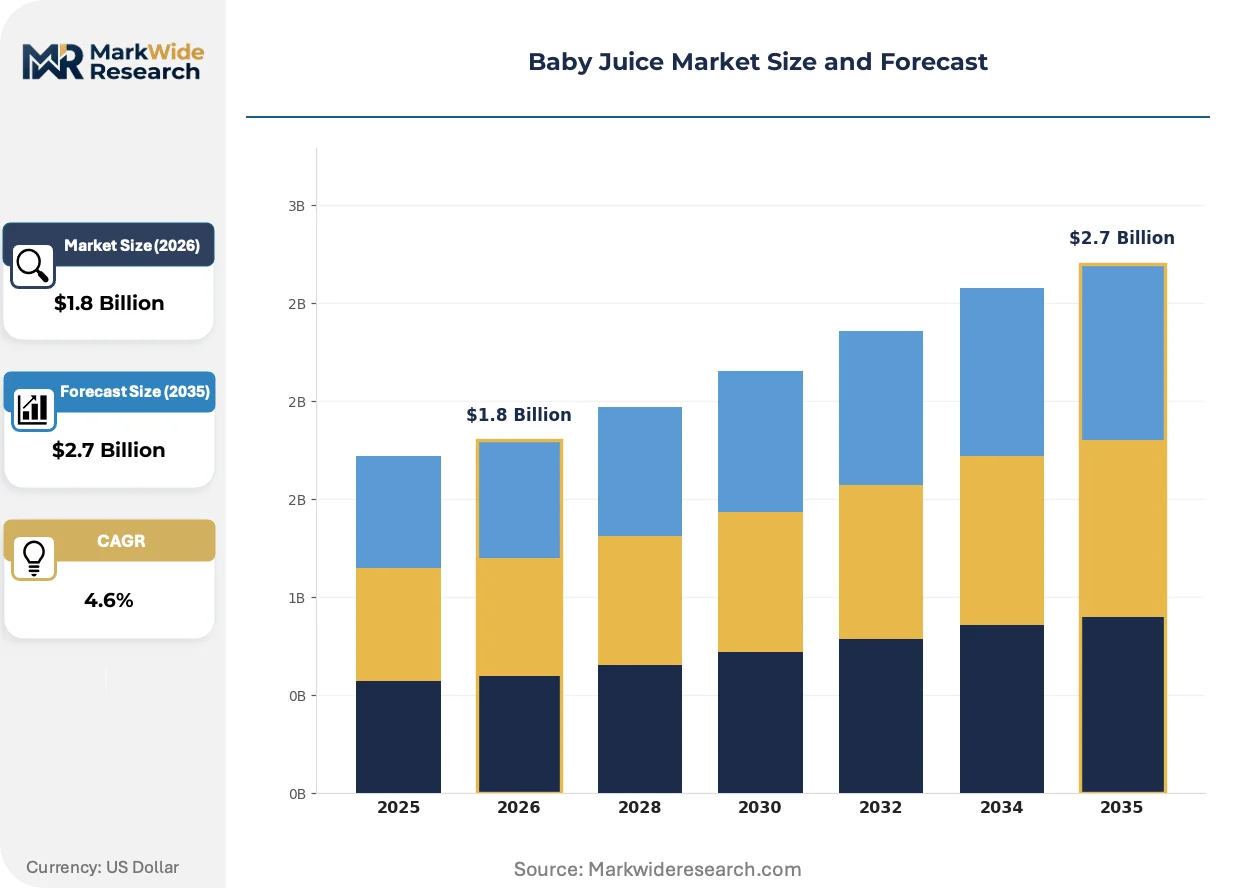
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Juice, Vegetable Juice, Mixed Juice, Organic Juice Packaging Type: Bottles, Pouches, Tetra Packs, Cans Flavor Profile: Apple, Mango, Carrot, Banana Distribution Channel: Supermarkets, Online Retail, Health Stores, Convenience Stores |
| Companies Covered | Nestlé, Danone, The Kraft Heinz Company, HiPP, Hero Group, Hain Celestial Group, Abbott Laboratories, Mead Johnson Nutrition Company, FrieslandCampina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Juice Market Strategic Shifts
Formulation science and packaging engineering are converging to preserve nutritional integrity without chemical preservatives, while regulatory divergence between major jurisdictions forces parallel compliance architectures.
High-pressure processing technology is unifying pathogen elimination with vitamin retention in cold-aseptic filling lines. Premium organic manufacturers deploy these systems to eliminate thermal degradation of heat-sensitive compounds. The technology is compressing the shelf-life gap between conventional and organic formulations, eroding a traditional trade-off that constrained clean-label penetration.
REACH and RoHS frameworks in Europe are extending substance restriction requirements into food-contact materials for infant packaging. Manufacturers must now validate pouch film compositions against evolving chemical migration thresholds. German retailers are responding by demanding third-party certification documentation prior to listing approval, accelerating compliance investment timelines.
Caregivers are compressing purchase decision cycles through digital channel research prior to retail conversion. E-commerce platforms and subscription services are displacing traditional grocery aisle discovery for first-time parents. This behavioral shift concentrates most visibly in North American urban markets where direct-to-consumer sampling programs capture trial before shelf commitment.
Baby Juice Market Segmentation
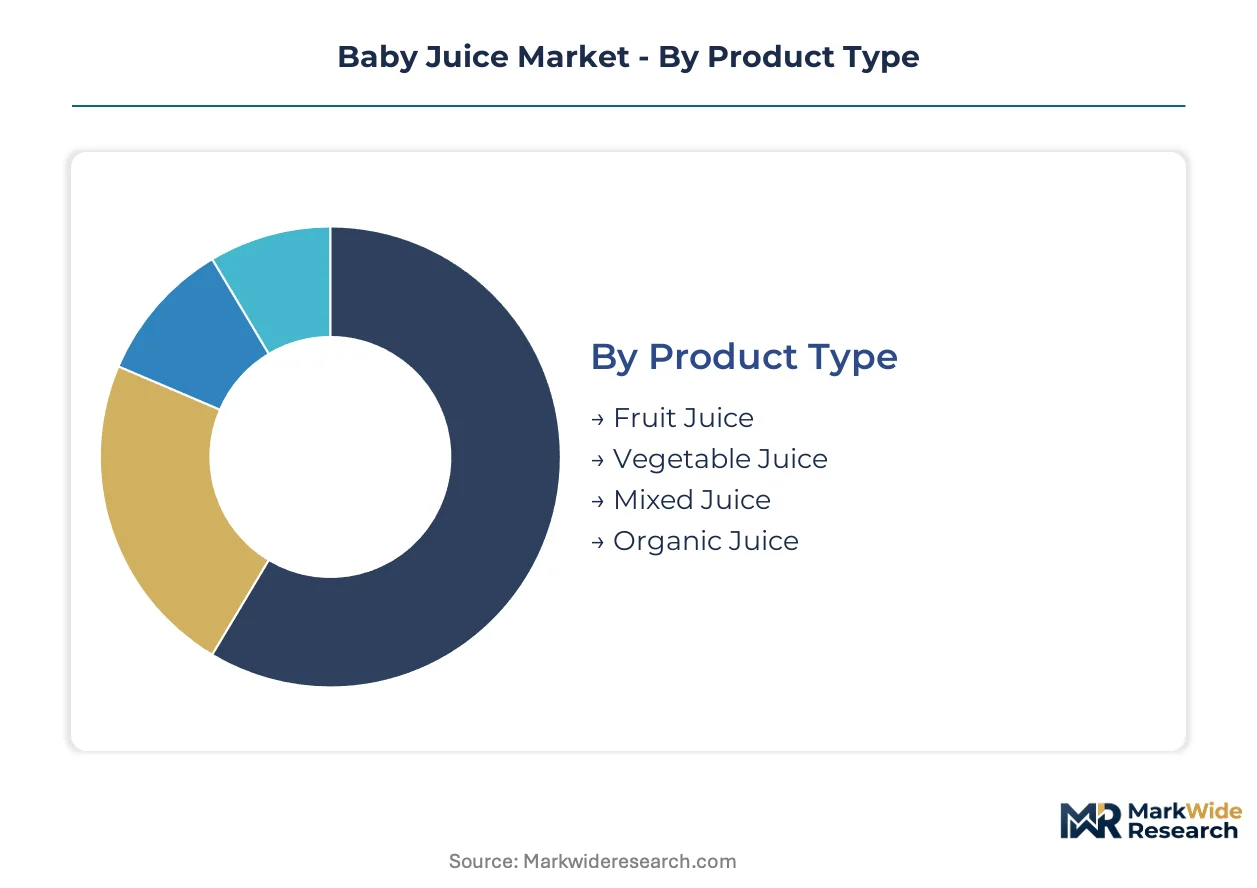
Baby juice segmentation reflects divergent supply chain configurations across formulation types, packaging formats, and channel access tiers. Each dimension carries distinct margin profiles and regulatory exposure that reshape competitive positioning for manufacturers targeting infant nutrition segments.
Product Type:
Supply concentration varies sharply across formulation categories, with organic certification requirements fragmenting supplier bases while conventional fruit processing maintains scale economies.
- Fruit Juice:Pasteurized apple and pear extracts dominate volume, standardized to reduced acidity for infant digestive tolerance. German retailers concentrate demand for residue-tested formulations that preempt EFSA threshold scrutiny.
- Vegetable Juice:Carrot and beetroot extracts deliver micronutrient density with lower natural sugar content than fruit alternatives. Supply concentrates in contracted organic grower networks across Central Europe where residue-free cultivation commands premium pricing.
- Mixed Juice:Blended fruit-vegetable formulations balance palatability with nutritional breadth.
- Organic Juice:Certified formulations with audited supply chains and third-party residue documentation.
Fruit juice absorbs the bulk of installed capacity; organic juice is expanding most quickly.
Packaging Type:
Cost tier differentiation separates rigid formats with established filling infrastructure from flexible systems requiring capital-intensive cold-aseptic lines.
- Pouches:Lightweight flexible films with spout closures enable portion-controlled dispensing and reduced transport weight. North American urban caregivers are displacing bottle purchases through subscription-based direct-to-consumer channels that prioritize convenience.
- Bottles:Traditional rigid PET or glass containers with established recycling infrastructure and familiar handling characteristics. Retail shelf presence remains strongest in European supermarkets where visible branding influences first-time parent selection.
- Tetra Packs:Aseptic carton systems with extended ambient shelf stability.
- Cans:Metal packaging for extended shelf-life applications.
Bottles retain the majority of legacy production assets; pouches are climbing the fastest as caregivers prioritize portability.
Flavor Profile:
Volume concentration tracks ingredient cost structures and cultivation geography, with apple sourcing scalability contrasting tropical fruit import dependency.
- Apple:European cultivation concentration delivers supply security and cost predictability for base formulations. Processing infrastructure in Poland and Germany enables residue-controlled supply at scale for private-label and branded portfolios.
- Carrot:Root vegetable extracts provide beta-carotene positioning with lower sugar content than fruit alternatives. German organic channel concentration rewards residue-free cultivation partnerships that preempt competitor access to premium-grade inputs.
- Mango:Tropical fruit extracts with vitamin A density and distinct taste differentiation.
- Banana:Creamy texture base for mixed formulations and allergy-sensitive positioning.
Apple captures the greatest share of formulation volume; carrot is gaining share fastest on clean-label vegetable positioning.
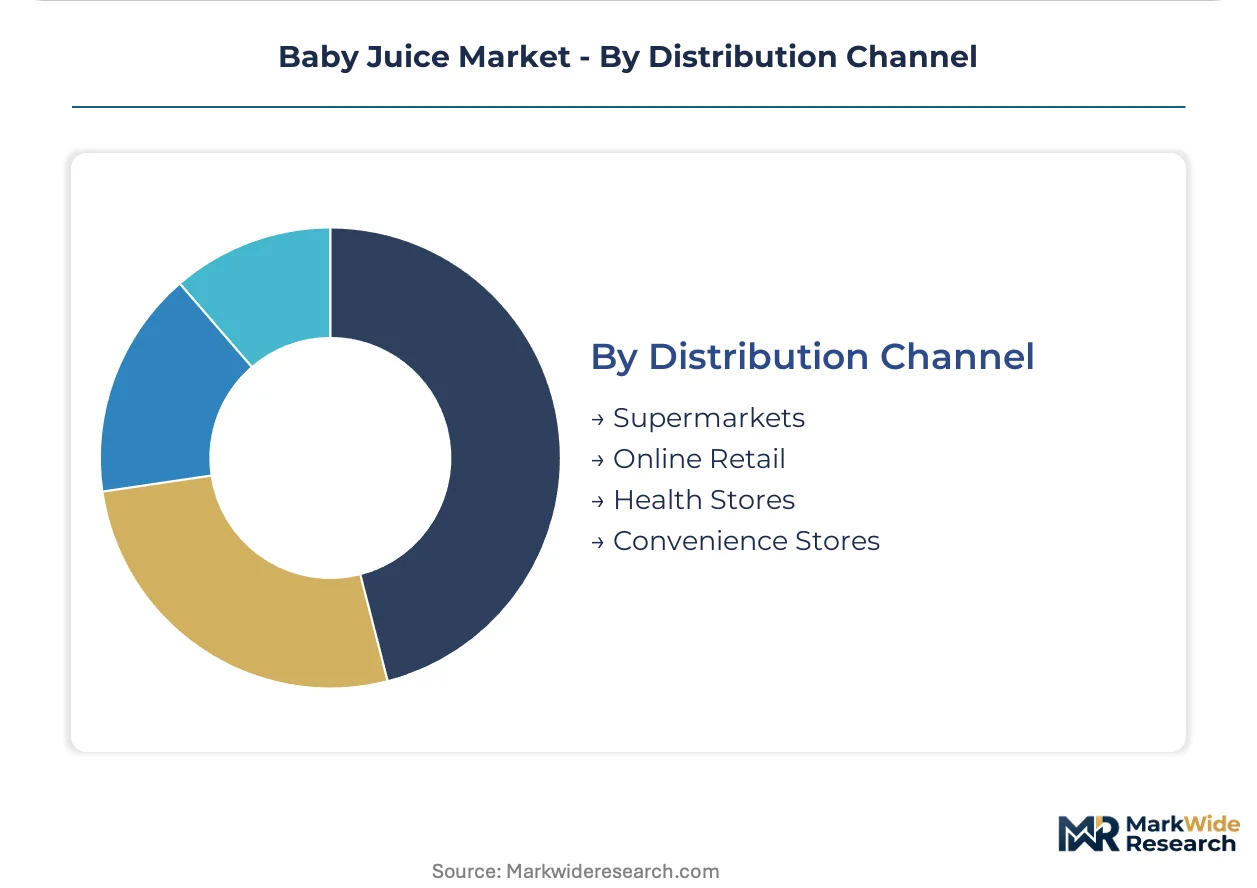
Distribution Channel:
Customer type fragmentation separates institutional purchasers seeking audit transparency from individual caregivers prioritizing convenience and discovery.
- Supermarkets:Mass retail with established baby food aisle placement and promotional visibility. German chains concentrate volume through organic-certified private-label expansion that pressures branded margin structures.
- Online Retail:E-commerce platforms and subscription services with direct-to-consumer sampling and automated replenishment. Urban North American markets show the steepest channel shift as digital research precedes purchase commitment.
- Health Stores:Specialized retail with certified organic focus and educated staff consultation.
- Convenience Stores:Impulse-oriented small-format retail for emergency replenishment.
Supermarkets maintain the largest transaction volume; online retail shows the steepest expansion trajectory on subscription adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Poland and Bavaria concentrate cold-aseptic filling infrastructure for EU-bound organic formulations. These tax-advantaged manufacturing clusters attract residue-free fruit processors seeking streamlined EFSA compliance pathways.
Germany
Clean-label purchasing among parents of infants aged six to thirty-six months concentrates demand in organic-certified channels. EFSA maximum residue thresholds for processed infant foods elevate laboratory infrastructure to competitive necessity. Bavarian processing clusters around Munich leverage proximity to contracted organic apple growers across southern Germany.
United States
Urban caregivers compress purchase decision cycles through digital channel research preceding retail conversion. FDA acidified food regulations govern formulation standards while creating divergence from European additive approval lists. Pacific Northwest organic fruit suppliers anchor supply security for pouch-format direct-to-consumer brands targeting subscription adoption.
India
Emerging middle-class expansion in metropolitan centers drives demand for imported infant nutrition formulations. BIS certification requirements filter import competition and extend compliance timelines for foreign operators. Maharashtra's Mumbai-Pune industrial corridor concentrates cold-chain distribution infrastructure for premium imported baby food access.
France
Specialized organic sourcing partnerships lock in supply security for residue-free cultivation networks across the Loire Valley. ANSM and DGCCRF oversight extends EFSA-aligned precautionary principles into national enforcement frameworks. Paris-region retail chains demand third-party certification documentation prior to organic baby juice listing approval.
United Kingdom
Post-regulatory divergence from EU frameworks creates parallel compliance architectures for operators serving both markets. Health and Safety Executive guidelines maintain residue thresholds comparable to EFSA standards. London-centric e-commerce platforms accelerate subscription-based direct-to-consumer sampling for first-time parents.
Baby Juice Market Competitive Environment
European producers anchor the premium organic tier; North American operators hold scale-driven conventional positions. Market structure consolidates around vertically integrated multinationals with in-house laboratory infrastructure and contracted grower networks. Three archetypes dominate: residue-free cultivation specialists, pouch-format engineering leaders, and multi-jurisdictional compliance aggregators. Dominant competitive moves include specialized organic sourcing partnerships locking in premium-grade fruit supplies and cold-aseptic filling capacity expansion preempting regulatory barrier elevation.
Within the premium organic tier, HiPP exemplifies residue-free cultivation archetype dominance through decades of German-speaking channel presence. Nestlé occupies a position as multi-jurisdictional compliance aggregator leveraging vertically integrated European supply chains. Danone represents specialized organic sourcing partnership strategy through locked premium-grade fruit supply security.
| Leading Market Players |
|---|
| Nestlé |
| Danone |
| The Kraft Heinz Company |
| HiPP |
| Hero Group |
| Hain Celestial Group |
| Abbott Laboratories |
| Mead Johnson Nutrition Company |
| FrieslandCampina |
| Others |
Value Chain & Pricing Dynamics
EU REACH and RoHS substance restriction frameworks for food-contact materials gate qualified pouch film supply and premium-tier pricing access for organic baby juice manufacturers seeking German retail listing approval. Bavarian processing clusters absorb elevated certification costs that filter sub-scale competitors from residue-free cultivation partnerships.
Pricing Analysis
Short lead-time premiums for cold-aseptic filled pouches command pricing power over spot inventory from conventional thermal pasteurization lines. Three-tier pricing structure across premium organic, certified conventional, and private-label economy levels tracks certification grade and laboratory documentation depth. Pricing pressure stems from organic input cost volatility as weather-driven yield fluctuations compress margins across contracted grower networks. First-time parents in urban North American markets show lowest price sensitivity through subscription commitment, while European supermarket private-label expansion intensifies cost compression in standard tiers.
Supply Chain Analysis
Domestic-content mandates under India's BIS certification framework reshape sourcing for imported formulations seeking metropolitan middle-class access. Premium-grade organic apple concentrate draws from Poland and southern Germany, with carrot and beetroot extracts anchored in Central European residue-free cultivation networks. Single-source vulnerability concentrates in tropical fruit supply for mango formulations dependent on import channels. Distribution runs through cold-chain logistics from Bavarian processing clusters to EU retail networks, with direct-to-consumer subscription platforms displacing traditional wholesale tiers in North American urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EFSA maximum residue thresholds for processed infant foods create a barrier-to-entry moat that rewards operators with amortized laboratory infrastructure across multi-jurisdictional volumes.
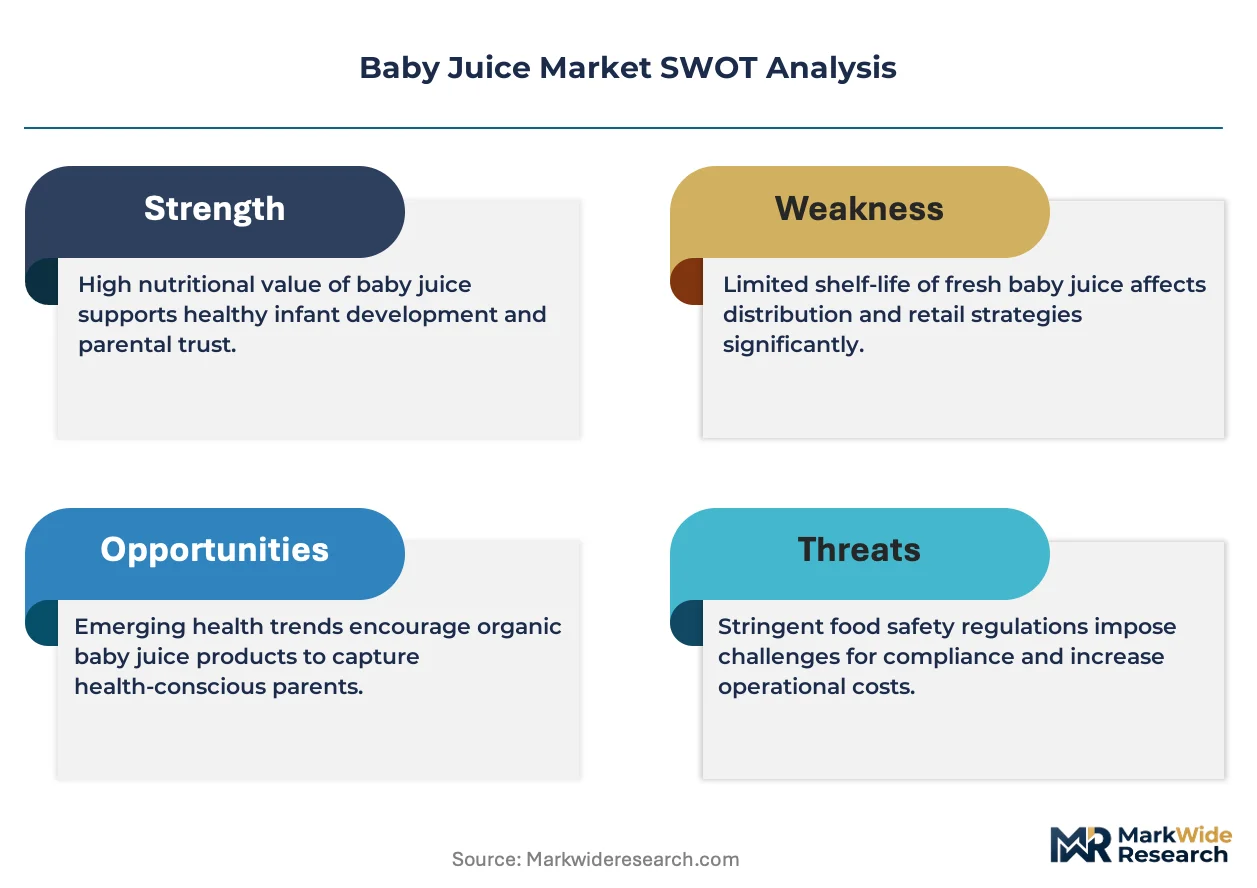
For Market Incumbents: Anticipate pouch-format engineering leaders consolidating cold-aseptic filling capacity as regulatory barrier elevation accelerates. Preempt emerging direct-to-consumer subscription entrants by locking specialized organic sourcing partnerships that secure residue-free cultivation networks. Channel control through Bavarian processing cluster proximity defends margin position against import competition. For New Entrants and Emerging Players: High-pressure processing technology integration offers a technology-first wedge into vegetable extract diversification where carrot, beet, and spinach formulations remain underdeveloped against fruit-dominant portfolios. Target Indian metropolitan centers where BIS certification requirements filter established import competition and extend first-mover advantage timelines. Deploy direct-to-consumer sampling programs to capture trial commitment before retail shelf investment. For Investors and Strategic Acquirers: Consolidation of cold-aseptic filling assets among mid-cap specialists is the leading indicator that laboratory infrastructure scarcity will deepen competitive moats for compliant operators. Long-term viability favors acquisition targets with backward integration into residue-free cultivation networks and established EFSA documentation protocols. Monitor German retailer third-party certification documentation demands as inflection signal for premium-tier pricing power concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Specialized Organic Sourcing Partnership | Locks premium-grade fruit supply security and preempts competitor access under EFSA residue thresholds. |
| Cold-Aseptic Filling Capacity Expansion | Captures pouch-format growth while meeting REACH and RoHS food-contact material compliance requirements. |
| Direct-to-Consumer Subscription Launch | Bypasses supermarket private-label pressure through automated replenishment and digital-first parent acquisition. |
| Vegetable Extract Portfolio Diversification | Exploits white space in micronutrient positioning where carrot and beet formulations lag fruit alternatives. |
| BIS Certification Compliance Investment | Unlocks Indian metropolitan middle-class demand while filtering import competition through extended timelines. |
Study Parameters
Independent corroboration across regulatory affairs directors at infant nutrition manufacturers, category buyers at German retail chains, and organic certification auditors underwrites the qualitative findings in this study. Primary interviews with supply chain planners, cold-aseptic equipment engineers, and residue-testing laboratory managers combined with secondary validation from EFSA guidance documents, BIS technical regulations, FDA acidified food filings, and EU customs trade data. Bottom-up volume triangulation across formulation types, packaging formats, and distribution channels intersects with top-down market sizing.
Rate-of-change decomposition across the analysis window separates volume growth from price-mix effects in organic versus conventional tiers. Segmentation modeling incorporates product type, packaging format, flavor profile, and distribution channel dimensions with regional regulatory cluster differentiation. CAGRs derive from trend extrapolation moderated by input cost elasticity assumptions and penetration saturation curves for pouch adoption. Forecast inputs include organic certification rate projections and cold-aseptic equipment installation pipelines.
Several conditions sit outside the modeled scope, including abrupt EFSA threshold revisions, trade disruption in tropical fruit supply corridors, and technological substitution of high-pressure processing. Forecasts reflect documented assumptions about caregiver preference stability and retailer listing fee structures. Weather-driven organic yield volatility and input cost pass-through limitations represent primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Omega 3 Ingredients for Infant Food Market
Baby Food and Infant Formula
Pet Milk Replacement Products Market
Baby Food and Infant Formula
Baby Formula Market
Baby Food and Infant Formula
Middle East and Africa Organic Baby Food Market
Baby Food and Infant Formula
Functional Milk Replacers Market
Baby Food and Infant Formula
Asia-Pacific Prebiotics for Infant Formula Market
Baby Food and Infant Formula
BRIC Organic Baby Food Market
Baby Food and Infant Formula
Asia-Pacific Baby Food Market
Baby Food and Infant Formula
Canned Baby Food Market
Baby Food and Infant Formula
Fortified Pet Food Market
Baby Food and Infant Formula
Human Milk Oligosaccharides in Infant Formula Market
Baby Food and Infant Formula
Japan Baby Food and Infant Formula Market
Baby Food and Infant Formula
Middle East and Africa Baby Food Market
Baby Food and Infant Formula
Anti-Spit Up Formula Market
Baby Food and Infant Formula
Baby Formula Ingredients Market
Baby Food and Infant Formula
South America Baby Food Market