
 India Baby Food Market | 2026-2036
India Baby Food Market Size, Share, and Industry Trends Forecast 2026-2036
India Baby Food Market Insights
FSSAI's fortification certification cycle is reorganizing competitive entry in the India baby food sector. Nestlé India Ltd leverages its pan-India cold-chain infrastructure to sustain distribution reach in tier-two cities. Abbott India Ltd anchors its position through specialized clinical nutrition pipelines tied to pediatric hospital networks. Raptakos Brett & Co Ltd differentiates via regional manufacturing scale that controls cost structures in western India.
India baby food comprises nutritionally formulated products for infants and young children, typically meeting protein density benchmarks between 1.5–3.5 grams per 100 kcal and micronutrient profiles calibrated to ICMR dietary guidelines. These products serve as supplementary or transitional feeding solutions bridging maternal milk and family diets. Cereal-based formulations occupy the largest volume pool due to price accessibility and cultural familiarity with porridge-style feeding. Organic variants represent the fastest-expanding margin segment as urban households prioritize residue-free ingredient sourcing. Online distribution channels are capturing disproportionate growth velocity, driven by subscription models and direct-to-parent nutritional counseling.
FSSAI fortification directives, BIS packaging standards, and CDSCO oversight of specialized clinical nutrition products collectively determine formulation compliance and market access thresholds in India. The PLI scheme for food processing incentivizes domestic manufacturing upgrades that align with these regulatory benchmarks. Stakeholders must monitor how state-level anganwadi procurement policies and evolving FSSAI labeling requirements reshape channel economics and brand positioning strategies.
Market Dynamics
FSSAI's fortification certification cycle is compressing product development timelines across India's baby food sector, forcing manufacturers to revalidate formulations against micronutrient density benchmarks before market release.
Growth Catalysts
- Anganwadi procurement expansion:State-level Integrated Child Development Services programs in Maharashtra and Karnataka are institutionalizing volume purchase agreements for fortified cereals, creating predictable offtake channels.
- PLI scheme for food processing:The Production Linked Incentive scheme subsidizes domestic manufacturing upgrades that align with BIS packaging standards and FSSAI quality thresholds.
- Metropolitan dual-income households:Working parents in Mumbai, Bangalore, and Delhi are driving adoption of convenience-oriented prepared purees and ready-to-feed formats.
Market Restraints
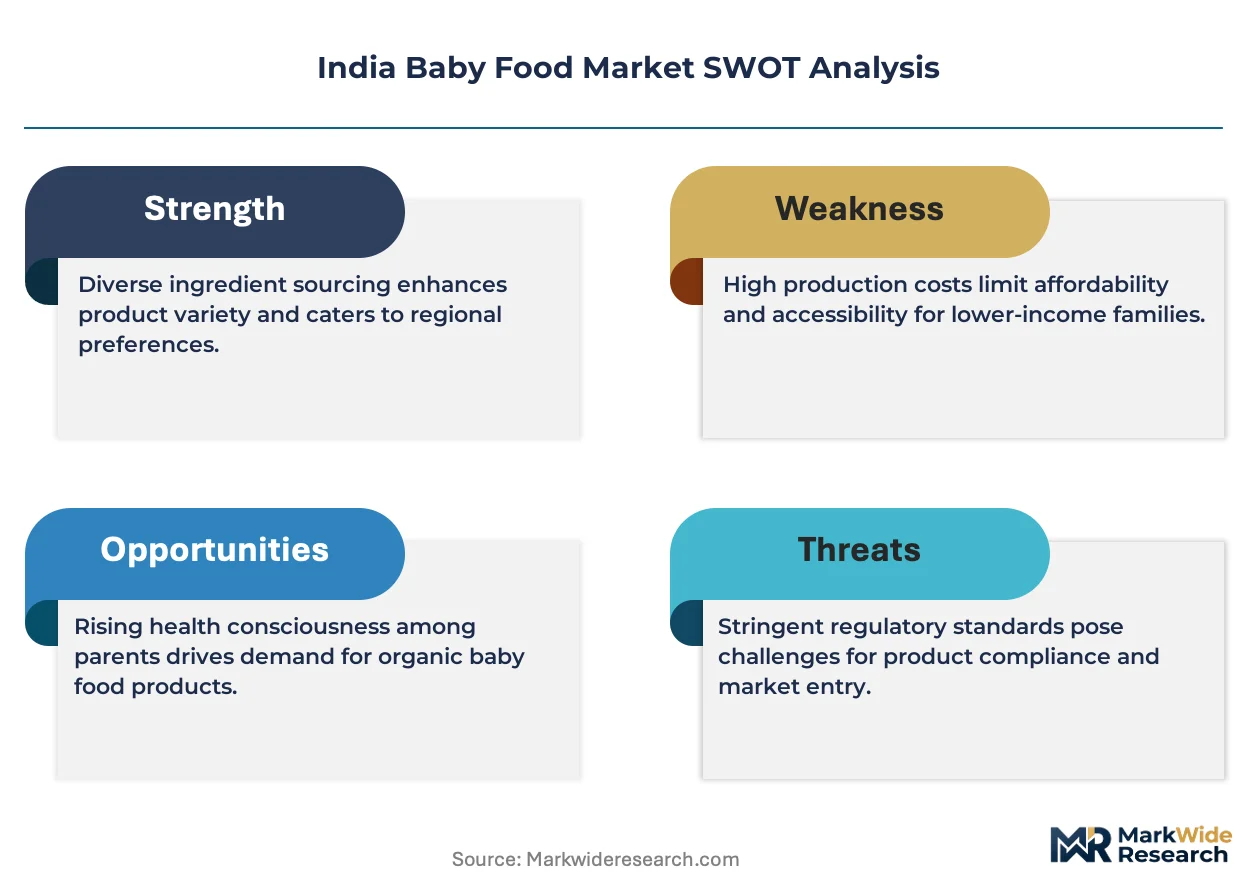
- Milk powder input volatility:Global dairy commodity fluctuations compress margin predictability for whey-based and milk-cereal formulations.
- Cold-chain infrastructure gaps:Tier-three cities and rural hinterlands lack temperature-controlled distribution networks required for probiotic and fresh-puree segments.
- Substitution by home-prepared foods:Grandmother-mediated feeding traditions in joint-family households limit penetration of commercial complementary foods.
Strategic Opportunities
- Organic certification pipelines:APEDA's organic export standards and domestic Jaivik Bharat accreditation create premium positioning pathways for residue-free ingredient sourcing.
- Subscription-based direct-to-parent models:E-commerce platforms are deploying AI-driven nutritional counseling interfaces that personalize product recommendations.
- Tier-two city pediatric clinic networks:Underpenetrated markets in Pune, Ahmedabad, and Hyderabad offer first-mover advantages through specialist channel partnerships.
Industry Challenges
- FSSAI label compliance timelines:Evolving front-of-pack disclosure requirements for sugar and salt content are forcing packaging redesigns and inventory write-downs.
- Pediatric nutritionist talent scarcity:Formulation science expertise calibrated to ICMR dietary guidelines remains concentrated in Mumbai and Delhi institutional clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Baby Food Market |
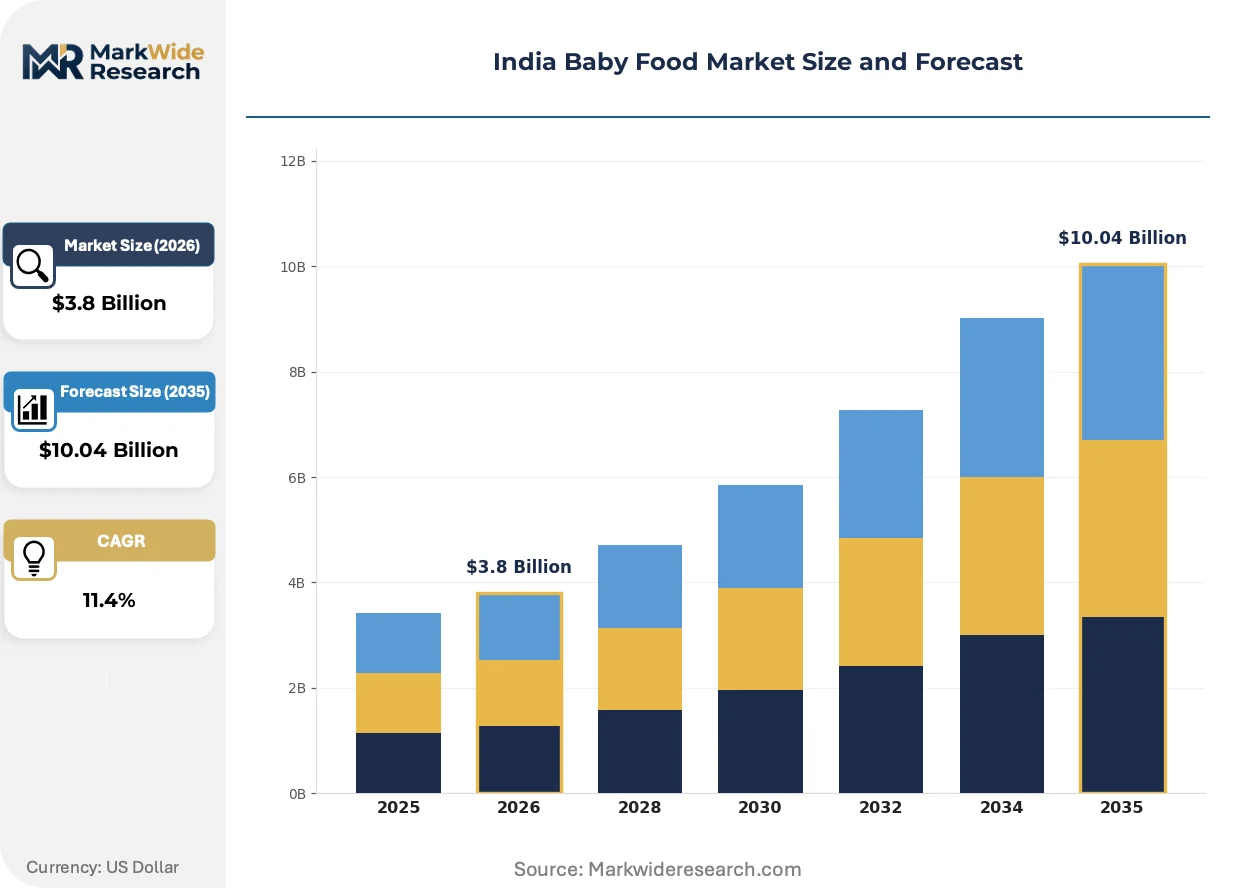
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prepared Purees, Cereal-based, Organic, Snacks Distribution Channel: Online, Supermarkets, Specialty Stores, Pharmacy Age Group: Infants, Toddlers, Preschoolers, Young Children Ingredient Type: Fruits, Vegetables, Grains, Protein Sources |
| Companies Covered | Nestlé India Ltd, Abbott India Ltd, Nutricia International Pvt Ltd, Danone, Mead Johnson Nutrition India Pvt Ltd, Raptakos Brett & Co Ltd, Gujarat Cooperative Milk Marketing Federation Ltd, Reckitt Benckiser Group PLC, Pristine Organics Pvt Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Baby Food Market Trends and Innovations
Product formulation and distribution architecture in India's baby food sector are being restructured by regulatory precision mandates, packaging technology advances, and parental purchasing behavior migration toward digital channels.
Retort pouch technology with extended ambient shelf stability is miniaturizing the cold-chain dependency for prepared fruit and vegetable purees. Tier-two city retailers are adopting these formats at accelerating velocity, compressing the historical urban-rural distribution gap that previously constrained market expansion.
FSSAI's 2024 notification on mandatory micronutrient fortification for all cereal-based complementary foods is forcing reformulation across the sector. Manufacturers must now recalibrate protein density and iron-zinc profiles to maintain market access, with cereal-milk hybrid products facing the steepest compliance adaptation requirements.
Subscription-based replenishment models are displacing traditional stock-up purchasing patterns among metropolitan households. Direct-to-parent platforms with integrated pediatrician chat support are capturing disproportionate growth velocity in Bangalore and Mumbai, where smartphone penetration and nuclear family structures concentrate demand.
India Baby Food Market Segmentation
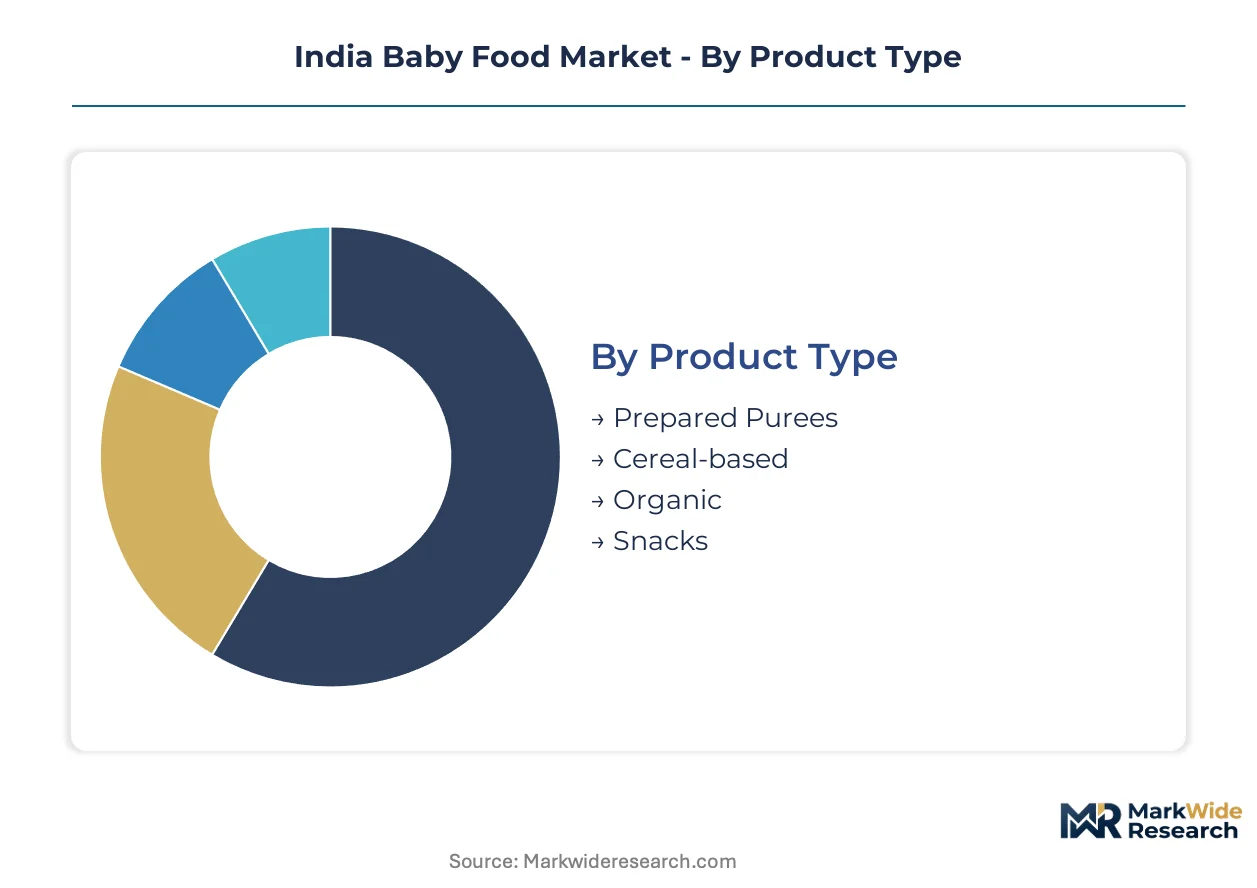
Segmentation in the India baby food market reveals where home-prepared substitutes exert strongest pressure and where commercial formulations secure durable positioning. Understanding these fault lines guides resource allocation across product development and channel investment.
Product Type:
Cereal-based formulations face the most intense substitution pressure from traditional household porridges, while prepared purees and organic variants build defensible differentiation through convenience and residue-free positioning.
- Cereal-based:Rice-wheat-milk formulations meeting FSSAI protein density benchmarks of 1.5–3.5 grams per 100 kcal. Demand concentrates in Maharashtra and Karnataka anganwadi procurement programs, though grandmother-mediated home porridges limit premium pricing headroom in joint-family households.
- Prepared Purees:Retort-pouched fruit and vegetable blends with extended ambient shelf stability. Working parents in Mumbai and Bangalore drive adoption as nuclear family structures erode traditional meal preparation support systems.
- Organic:APEDA-certified and Jaivik Bharat-accredited products with residue-free ingredient sourcing. Urban households prioritize traceability over price.
- Snacks:Finger-food formats for toddler self-feeding transition. Limited cold-chain requirements enable tier-two city penetration.
Cereal-based retains volume leadership; organic holds the steepest expansion curve.
Distribution Channel:
Channel economics in India diverge sharply between subscription-driven digital platforms and infrastructure-heavy physical retail, with pharmacy networks offering unique clinical credibility.
- Online:AI-driven subscription models with integrated pediatrician chat support. Bangalore and Mumbai households show disproportionate replenishment velocity through direct-to-parent platforms.
- Supermarkets:Organized retail density in metropolitan clusters enables brand visibility and impulse trial. FSSAI front-of-pack labeling compliance requirements reshape shelf presentation strategies.
- Specialty Stores:Curated organic and imported product assortments. Premium positioning depends on Jaivik Bharat accreditation display.
- Pharmacy:Pediatric clinic-adjacent dispensing with clinical nutritionist endorsement. Abbott India Ltd anchors this channel through hospital network partnerships.
Supermarkets dominate current transaction volume; online is climbing the fastest.
Age Group:
Nutritional specification requirements intensify toward younger cohorts, while older segments permit broader formulation flexibility and price tiering.
- Infants:Complementary feeding transition products with ICMR-mandated micronutrient profiles. FSSAI fortification directives impose strictest compliance burden on cereal-based entries for this cohort.
- Toddlers:Texture-modified foods supporting chewing skill development. Convenience demand from working parents peaks in this segment.
- Preschoolers:Expanded flavor range acceptance enables cost-optimized formulations. Home-prepared food substitution pressure intensifies.
- Young Children:School-ready portable formats with reduced regulatory scrutiny. Price competition from unorganized sector concentrates here.
Infants command premium formulation investment; toddlers show the steepest volume trajectory.
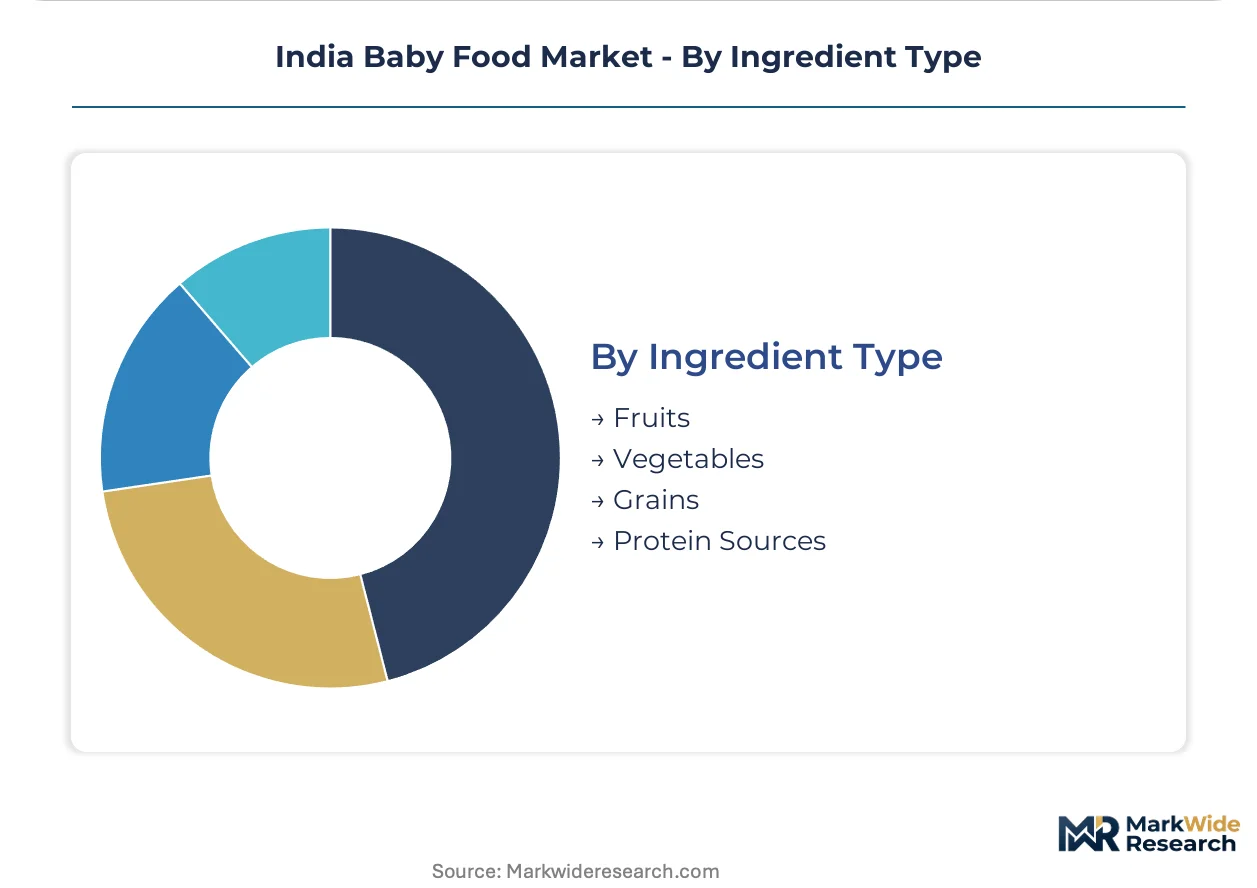
Ingredient Type:
Input sourcing strategies determine margin structure and certification eligibility, with protein sources facing volatile dairy commodity exposure.
- Fruits:Mango, banana, and apple purees with regional sourcing from Maharashtra and Karnataka orchards. Retort processing enables ambient distribution without cold-chain dependency.
- Vegetables:Carrot, spinach, and pumpkin blends. Seasonal price volatility requires forward contracting with farmer producer organizations.
- Grains:Rice and wheat bases with BIS packaging standard compliance. PLI scheme subsidies support domestic milling infrastructure upgrades.
- Protein Sources:Whey and milk powder formulations facing global dairy commodity price swings. CDSCO oversight applies to specialized clinical nutrition claims.
Grains anchor volume throughput; protein sources face the steepest margin compression risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level procurement programs and PLI scheme subsidies are concentrating manufacturing investment in western and southern India. Maharashtra and Karnataka anchor volume throughput through anganwadi networks and organized retail density.
Maharashtra
Mumbai's dual-income households drive prepared puree adoption through subscription platforms. ICDS anganwadi procurement in Pune and Nagpur institutionalizes fortified cereal offtake. Nestlé India Ltd leverages its cold-chain infrastructure to sustain distribution reach across tier-two cities.
Karnataka
Bangalore's nuclear family structures accelerate online replenishment velocity for convenience formats. FSSAI fortification mandates reshape formulation requirements for Bengaluru-based manufacturers. Pediatric clinic networks in Mysore and Mangalore channel clinical nutrition products.
Gujarat
Amul's cooperative dairy infrastructure anchors milk-cereal formulation supply chains. BIS packaging standards compliance concentrates in Anand and Vadodara processing clusters. Regional manufacturing scale controls cost structures for western India distribution.
Delhi-NCR
Pharmacy-adjacent dispensing peaks in Gurugram and Noida hospital corridors. CDSCO oversight of specialized clinical nutrition products shapes Abbott India Ltd's channel strategy. Premium organic positioning concentrates in South Delhi specialty retail.
Tamil Nadu
Chennai's metropolitan households sustain demand for retort-pouched fruit purees. Jaivik Bharat accreditation pathways enable premium pricing for Coimbatore-sourced organic ingredients. Cold-chain gaps in tier-three cities constrain probiotic segment penetration.
India Baby Food Market Competitive Landscape
Player mix skews toward multinational nutrition conglomerates with domestic manufacturing arms and regional dairy cooperatives with backward integration into ingredient supply. Tier-one positions concentrate around clinical nutrition pipelines and pan-India cold-chain reach. Tier-two slots hold regional manufacturers with cost-optimized cereal formulations. Dominant competitive moves include capacity expansion under PLI scheme subsidies and portfolio diversification into organic certification pipelines.
Within the multinational conglomerate tier, Nestlé India Ltd and Abbott India Ltd exemplify divergent channel strategies—one leveraging mass-market distribution density, the other anchoring hospital network partnerships. Raptakos Brett & Co Ltd occupies a position among regional specialists with western India manufacturing concentration. Gujarat Cooperative Milk Marketing Federation Ltd represents the cooperative archetype with captive dairy supply integration.
| Leading Market Players |
|---|
| Nestlé India Ltd |
| Abbott India Ltd |
| Nutricia International Pvt Ltd |
| Danone |
| Mead Johnson Nutrition India Pvt Ltd |
| Raptakos Brett & Co Ltd |
| Gujarat Cooperative Milk Marketing Federation Ltd |
| Reckitt Benckiser Group PLC |
| Pristine Organics Pvt Ltd |
| Others |
Pricing and Supply Chain Analysis
Home-prepared porridge substitution in joint-family households simultaneously compresses premium pricing headroom in cereal-based segments and redirects manufacturer investment toward retort-pouched formats that escape grandmother-mediated feeding traditions. This input displacement reshapes procurement geography toward Maharashtra and Karnataka fruit processing clusters while elevating ambient-stable packaging to a cost-critical specification.
Pricing Analysis
Cost-plus contracts with global dairy commodity indexation govern whey-based and milk-cereal formulation pricing. Three-tier pricing structure across premium organic, fortified standard, and anganwadi economy levels separates Jaivik Bharat-accredited products from FSSAI-baseline fortified cereals and state-procurement generics. Pricing pressure stems from milk powder input volatility that compresses margin predictability. Anganwadi procurement buyers exhibit highest price sensitivity; metropolitan subscription households show lowest.
Supply Chain Analysis
Container availability constraints on the Asia-Europe trade lane elevate inbound logistics costs for specialized probiotic cultures and imported organic ingredients. Domestic supply concentrates in Maharashtra, Karnataka, and Gujarat processing clusters. Raw material dependencies include Amul cooperative dairy infrastructure, Maharashtra orchard fruit bases, and imported whey concentrates. Single-source vulnerability sits with global dairy commodity markets. Distribution runs through Nestlé's pan-India cold-chain network for tier-two reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. FSSAI fortification certification cycles create switching costs that lock validated formulations into sustained market access.
For Market Incumbents: Fortify anganwadi procurement relationships through volume guarantee mechanisms that preempt state-level competitive bidding. Deepen backward integration into Maharashtra fruit processing and Gujarat dairy cooperatives to control input cost volatility against global commodity swings. For New Entrants and Emerging Players: Pediatric nutritionist chat support as a service-layer gap offers white-space penetration where Abbott and Nestlé under-serve direct-to-parent relationships. Target tier-two city clinic networks in Pune, Ahmedabad, and Hyderabad through specialist channel partnerships with AI-driven subscription onboarding. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors regional manufacturing specialists with PLI scheme qualification and organic certification pipelines. Long-term viability hinges on regulatory compliance infrastructure rather than brand equity alone. Watch FSSAI label compliance timeline extensions as inflection signal for inventory write-down risk exposure.| Strategic Initiative | Industry Significance |
|---|---|
| PLI Scheme Capacity Expansion | Domestic manufacturing upgrades align with BIS packaging standards and FSSAI quality thresholds. |
| Organic Certification Pipeline | Jaivik Bharat and APEDA accreditation unlock premium positioning in traceability-focused urban households. |
| Subscription Platform Launch | Direct-to-parent models with pediatrician chat support capture replenishment velocity in nuclear family structures. |
| Tier-Two Distribution Expansion | Retort pouch technology enables ambient distribution without cold-chain dependency in underpenetrated cities. |
| Anganwadi Procurement Partnership | State-level ICDS volume agreements institutionalize predictable offtake channels for fortified cereals. |
Research Methodology
Initial hypotheses were tested against primary input from pediatric nutritionists, anganwadi procurement officers, retail category managers, and food processing plant engineers and refined through secondary validation. Sources included FSSAI fortification compliance filings, BIS packaging standard records, ICDS procurement databases, and customs trade data for dairy ingredient imports. Bottom-up volume estimates from state-level anganwadi offtake and top-down macroeconomic triangulation anchored the analytical framework.
Variance decomposition across product type, distribution channel, age group, and ingredient sourcing dimensions structured the forecast architecture. CAGRs were derived from segmented growth trajectory modeling throughout the projection horizon. Industry-specific inputs incorporated PLI scheme subsidy uptake rates and FSSAI certification cycle timelines.
Material uncertainties — global dairy commodity price shocks, FSSAI label requirement revisions, and state-level anganwadi procurement policy shifts — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and infrastructure investment continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Baby Food Products Market
Baby Food and Infant Formula
Functional Milk Replacers Market
Baby Food and Infant Formula
Global Oligosaccharides in Infant Nutrition Market
Baby Food and Infant Formula
Middle East and Africa Baby Food Market
Baby Food and Infant Formula
South America Baby Food Market
Baby Food and Infant Formula
Baby Juice Market
Baby Food and Infant Formula
Russia Pet Food Market
Baby Food and Infant Formula
Ready to Use Supplementary Food Market
Baby Food and Infant Formula
Infant Nutritional Premix Market
Baby Food and Infant Formula
Follow on Formula Milk Market
Baby Food and Infant Formula
Growing Up Milk Market
Baby Food and Infant Formula
Baby Formula Ingredients Market
Baby Food and Infant Formula
Middle East and Africa Organic Baby Food Market
Baby Food and Infant Formula
Infant Formula Market
Baby Food and Infant Formula
Omega 3 Ingredients for Infant Food Market
Baby Food and Infant Formula
Canned Pet Food Market