
 Malignant Pleural Effusion Market | 2026-2036
Malignant Pleural Effusion Market Size, Share, and Industry Trends Forecast 2026-2036
Malignant Pleural Effusion Market Foresight
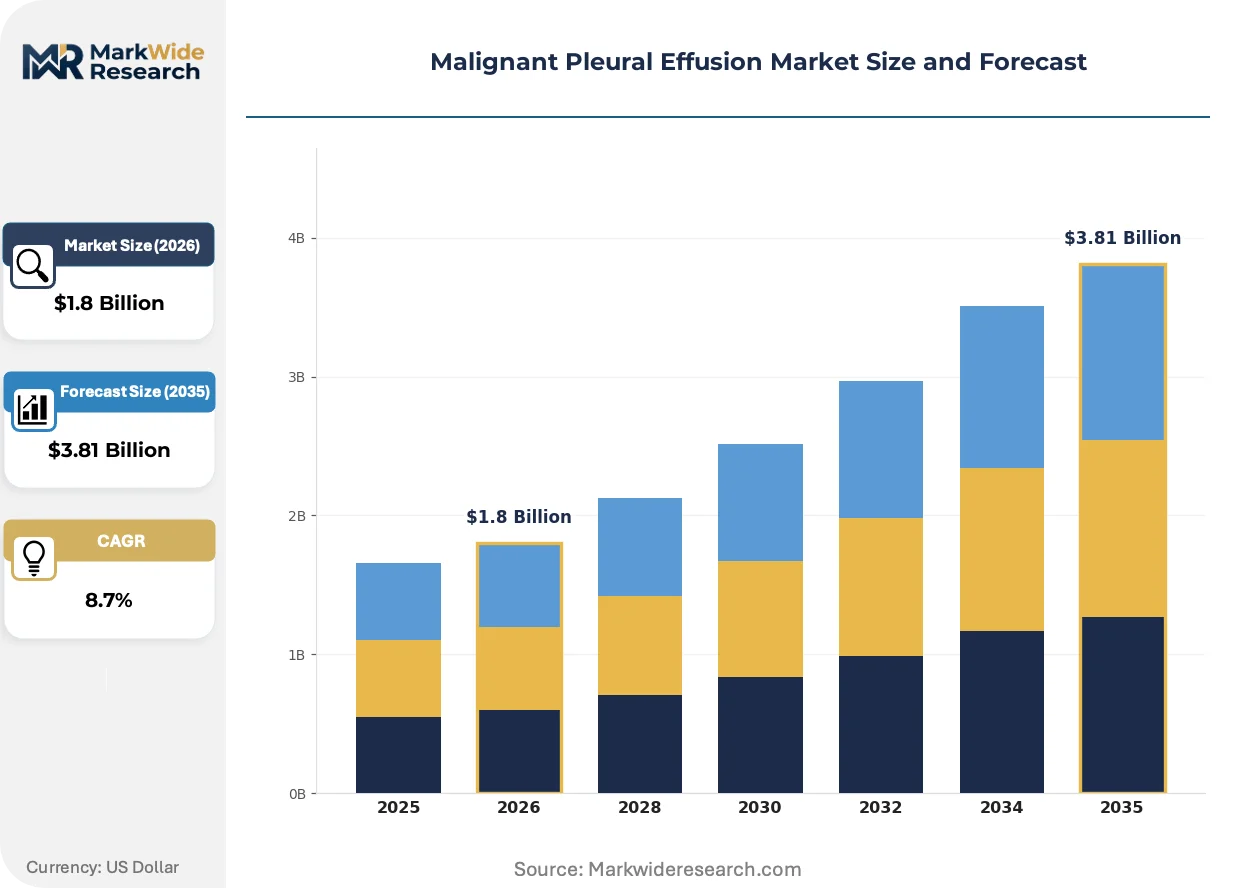
Minimally invasive image-guided intervention is reshaping how malignant pleural effusion therapies reach patients. Novartis AG leverages its oncology portfolio depth to sustain leadership in systemic chemotherapy integration with local palliative procedures. Bristol-Myers Squibb Company anchors its position through immuno-oncology platforms that address underlying malignancies driving recurrent effusions. Roche Diagnostics differentiates through diagnostic biomarker development that streamlines patient selection for targeted interventions.
Malignant pleural effusion denotes pathological accumulation of fluid in the pleural space secondary to metastatic cancer, typically presenting with lactate dehydrogenase elevation, protein content exceeding 30 g/L, and positive cytology in diagnostic thoracentesis. The condition demands palliative intervention to relieve dyspnea and restore functional capacity in advanced cancer patients. Chemotherapy agents and pleurodesis agents command the largest current revenue pools, reflecting established reimbursement pathways and repeat-treatment requirements in recurrent disease. Ultrasound-guided technology is expanding fastest among procedural categories, driven by point-of-care accessibility and reduced radiation exposure relative to CT-guided alternatives.
The FDA oversees drug-device combination products through its Office of Combination Products, while the EMA's MDR framework governs CE-marked drainage devices and catheters in European markets. These regulatory structures shape clinical evidence requirements and market access timelines, with FDA breakthrough designations accelerating novel pleurodesis agent development. Stakeholders must monitor evolving reimbursement policies for outpatient interventional procedures, as site-of-care economics increasingly determine adoption velocity for image-guided palliative interventions.
Market Dynamics
Image-guided pleural intervention is consolidating previously fragmented procedural workflows into standardized, reproducible protocols that reduce operator dependence and expand treatment access beyond specialized academic centers.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review pathways for combination pleurodesis-delivery systems compress development timelines and incentivize investment in palliative device innovation.
- Oncology Center Expansion:Dedicated pleural disease programs at tertiary cancer centers create institutional demand for integrated diagnostic-therapeutic platforms.
- Ultrasound-Guided Thoracentesis:Point-of-care lung imaging technology enables same-day diagnosis and intervention, reducing patient throughput time and radiation exposure.
Market Restraints
- Silicone Supply Concentration:Indwelling pleural catheter manufacturing depends on concentrated Asian polymer suppliers, exposing device makers to input volatility and geopolitical disruption.
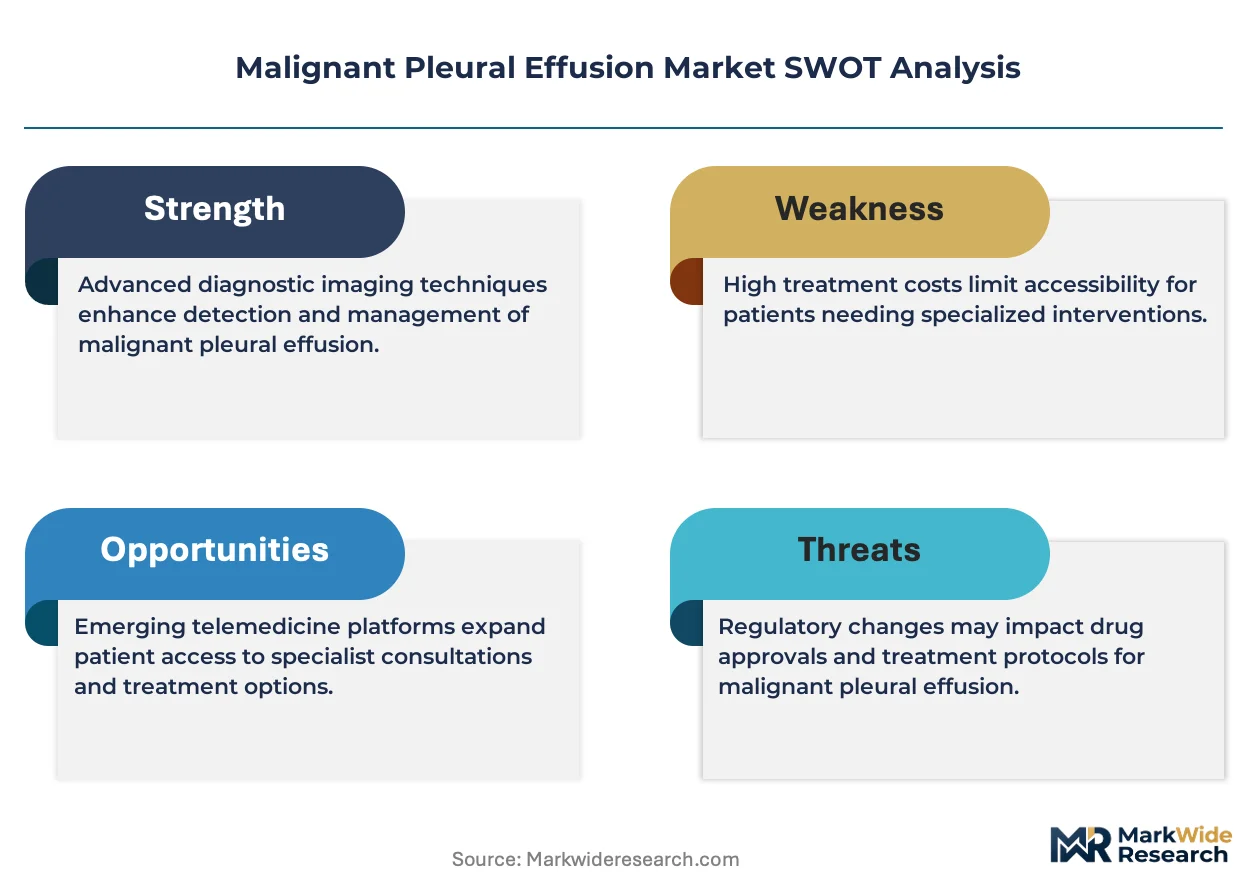
- EMA MDR Compliance Burden:Stricter clinical evidence requirements for CE-marked drainage devices extend market access timelines and elevate regulatory costs for European market entry.
- Recurrence Limitations:Chemical pleurodesis fails in approximately one-third of malignant effusion cases, driving repeat procedures and limiting durable reimbursement justification.
Strategic Opportunities
- Outpatient Procedure Migration:Ambulatory surgical centers in the United States capture shifting site-of-care economics as payers favor same-day pleural intervention over inpatient admission.
- Tunneled Catheter Home Drainage:Patient-managed fluid evacuation systems reduce hospital dependency and create recurring consumable revenue streams.
- Biomarker-Guided Patient Selection:Diagnostic stratification using pleural fluid proteomics identifies candidates most likely to respond to specific pleurodesis agents, improving outcomes and justifying premium positioning.
Industry Challenges
- Interventional Pulmonology Training Pipeline:Fellowship programs produce insufficient specialists to meet procedural demand, constraining adoption velocity for advanced image-guided techniques.
- Legacy EMR Integration:Procedural documentation and outcomes tracking require manual bridging between proprietary imaging platforms and hospital information systems, fragmenting data continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malignant Pleural Effusion Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drainage Devices, Chemotherapy Agents, Pleurodesis Agents, Catheters Technology: Ultrasound-Guided, Fluoroscopy-Guided, CT-Guided, Standard Techniques End User: Hospitals, Outpatient Clinics, Oncology Centers, Palliative Care Treatment Approach: Symptomatic Management, Interventional Procedures, Surgery, Chemotherapy |
| Companies Covered | Gongwin Biopharm Holdings, Novartis AG, RS Oncology, Bristol-Myers Squibb Company, AstraZeneca plc, LIPAC Oncology, Simcere Pharmaceutical Group, Roche Diagnostics, Clover Biopharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malignant Pleural Effusion Market Shifts & Advancements
Convergence between diagnostic biomarker platforms and interventional delivery systems is redefining how malignant pleural effusion care stratifies patients and selects therapeutic intensity.
Digital pleural drainage systems is hybridizing conventional gravity-dependent evacuation with continuous pressure monitoring and automated occlusion detection. Community oncology practices in the United States are piloting these connected devices to reduce nursing labor and enable remote patient surveillance. The technology is compressing the traditional inpatient observation window and shifting economic value toward device manufacturers from hospital bed-day revenue.
EMA's Medical Device Regulation (MDR) is elevating post-market surveillance requirements for permanently implanted pleural catheters. Manufacturers must now maintain active safety registries and submit periodic clinical evidence updates to retain CE marking. European thoracic surgery units are responding by consolidating procurement around suppliers with established MDR technical documentation and notified body relationships.
After-sales service unbundling is separating device placement from ongoing catheter maintenance and patient education. Independent home health agencies and specialized nursing networks are capturing the longitudinal care component previously bundled within hospital contracts. This fragmentation is most pronounced in United States Medicare Advantage populations where risk-bearing entities seek to decouple acute procedural reimbursement from chronic disease management costs.
Malignant Pleural Effusion Market Segmentation
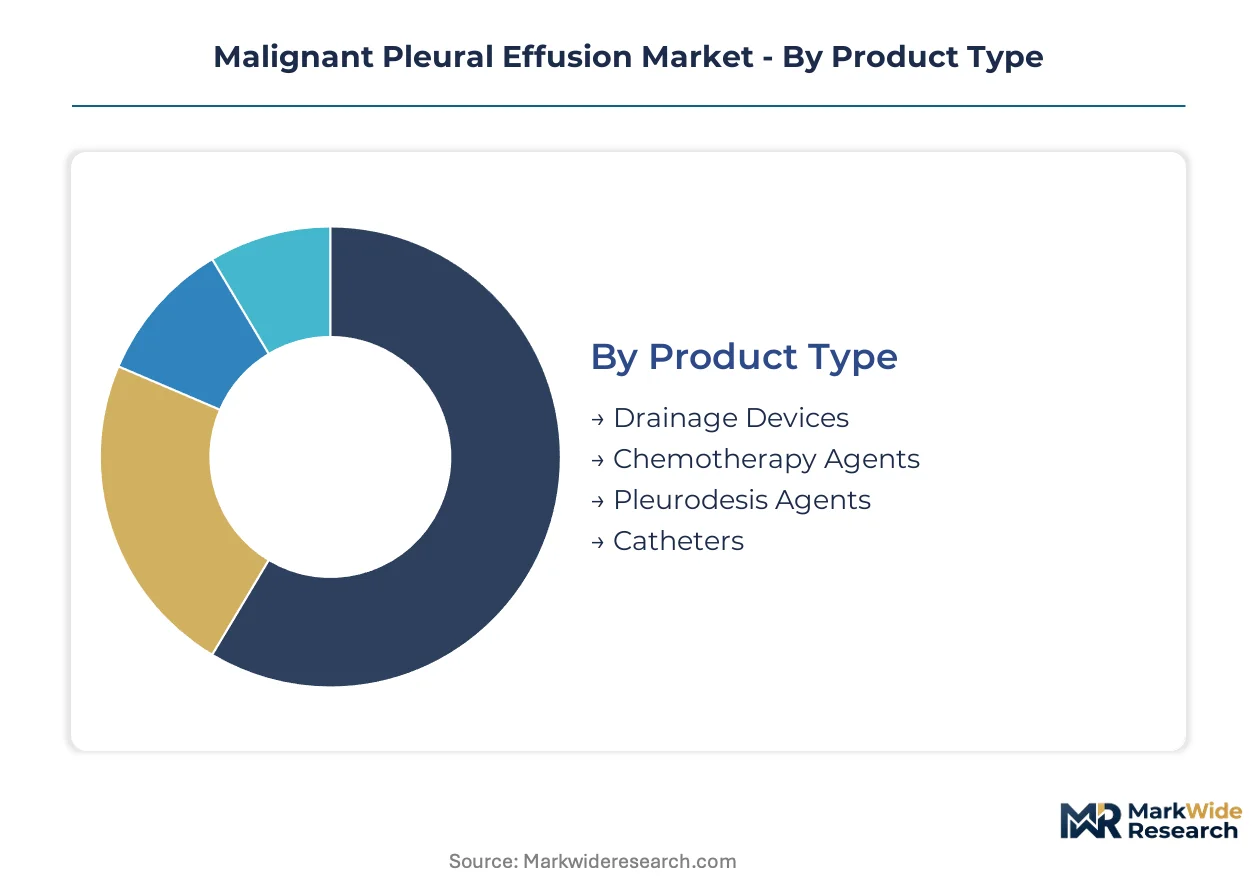
Therapeutic complexity in malignant pleural effusion care demands precise segmentation to match intervention intensity with patient prognosis. Product categories, procedural technologies, and care settings each carry distinct reimbursement profiles and after-sales service requirements that shape vendor economics.
Product Type:
After-sales service intensity varies dramatically across product categories, with indwelling catheters demanding longitudinal patient support while chemical agents require minimal follow-on engagement.
- Drainage Devices:Closed-system evacuators with vacuum-assisted suction mechanisms enable controlled fluid removal in acute care settings. Demand concentrates in tertiary oncology centers across the United States where interventional pulmonology programs manage high procedure volumes; reimbursement bundling with thoracentesis codes sustains placement frequency despite capital equipment constraints.
- Pleurodesis Agents:Talc slurry and doxycycline formulations induce pleural symphysis through inflammatory fibrosis cascades. Oncology centers in Germany and France prioritize these agents for ambulatory protocols that minimize inpatient bed utilization; EMA MDR documentation requirements for combination drug-device presentations extend commercialization timelines.
- Chemotherapy Agents:Intrapleural cisplatin and bleomycin target underlying malignancy within the pleural cavity. Systemic oncology protocols dominate utilization patterns.
- Catheters:Silicone-based tunneled pleural catheters permit intermittent home drainage through one-way valve mechanisms. Polymer supply chain vulnerabilities from concentrated Asian manufacturers constrain production flexibility.
Pleurodesis agents hold the largest share; momentum sits with tunneled catheters as home drainage protocols expand.
Technology:
Procedural technology selection directly determines capital deployment requirements and operator training intensity across care settings.
- Ultrasound-Guided:Real-time sonographic visualization enables point-of-care needle guidance without ionizing radiation exposure. Outpatient clinics in the United States and United Kingdom deploy portable ultrasound systems to compress diagnosis-to-intervention intervals; reduced radiation burden appeals to repeat-procedure populations with limited life expectancy.
- CT-Guided:Computed tomography navigation provides superior spatial resolution for loculated effusions and complex pleural anatomy. Academic medical centers in Japan and South Korea maintain CT-guided capabilities for salvage procedures after ultrasound failure; capital intensity and radiation dosing restrict community adoption.
- Fluoroscopy-Guided:C-arm fluoroscopy supports catheter placement and pleurodesis agent instillation under dynamic visualization. Interventional radiology suites favor this modality for combined diagnostic-therapeutic workflows.
- Standard Techniques:Blind thoracentesis and gravity-dependent drainage persist in resource-constrained environments without imaging infrastructure.
Ultrasound-guided intervention commands current volume leadership; CT-guided approaches are gaining share fastest in complex salvage indications.
End User:
Site-of-care economics reshape procurement patterns as payers shift reimbursement toward lower-acuity settings with equivalent clinical outcomes.
- Oncology Centers:Dedicated thoracic oncology programs integrate diagnostic thoracentesis, pleural fluid analysis, and therapeutic intervention within single-visit protocols. United States tertiary cancer centers in Houston and New York City anchor demand for integrated device-drug platforms; bundled payment models incentivize same-day completion.
- Hospitals:General acute care facilities manage malignant effusion as part of broader cancer-related admission patterns. Inpatient pleural service lines face margin pressure from outpatient migration.
- Outpatient Clinics:Ambulatory surgical centers capture shifting procedural volume through reduced facility fees and faster patient throughput.
- Palliative Care:Hospice-integrated programs prioritize symptom relief over disease-modifying intervention with minimal hospital dependency.
Hospitals retain the largest installed base; oncology centers are climbing the fastest as dedicated pleural disease programs proliferate.
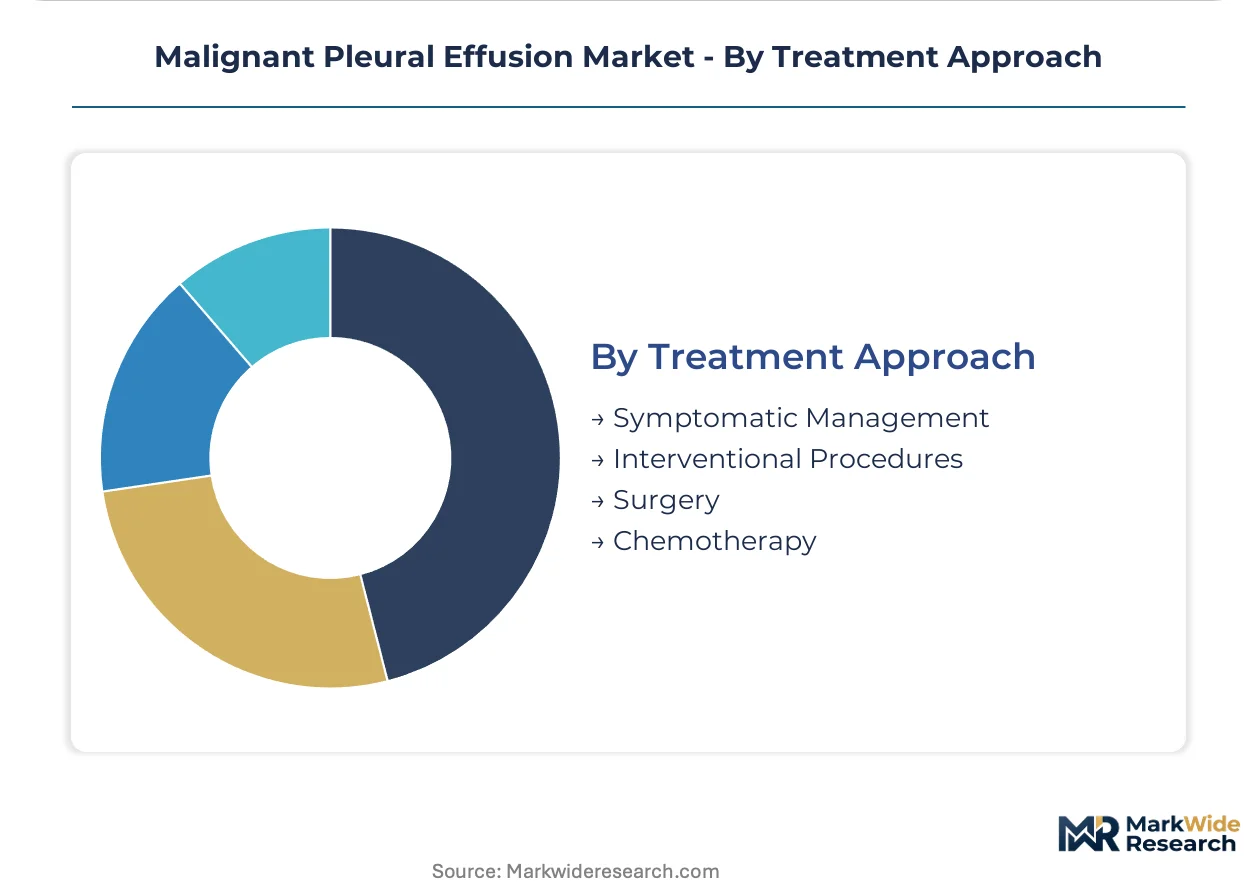
Treatment Approach:
Clinical intent stratification separates curative-aimed interventions from pure palliation, with profound implications for regulatory pathway and evidence requirements.
- Interventional Procedures:Image-guided drainage, pleurodesis, and catheter placement constitute the procedural backbone of malignant effusion management. United States interventional pulmonology fellowship expansion in Philadelphia, Boston, and Los Angeles creates specialist supply to meet procedural demand; Medicare reimbursement for tunneled catheter placement sustains ambulatory revenue models.
- Chemotherapy:Systemic and intracavitary cytotoxic therapy addresses underlying malignancy driving fluid accumulation. Oncology practices integrate pleural response assessment into standard disease monitoring protocols.
- Symptomatic Management:Oxygen supplementation and opioid-based dyspnea control provide non-invasive palliation for non-procedure candidates.
- Surgery:Pleurectomy and decortication reserve for select patients with trapped lung physiology and reasonable performance status.
Interventional procedures dominate current utilization; chemotherapy integration shows steepest expansion trajectory as systemic-local combination protocols advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports pleurodesis agents and drainage devices to oncology centers across France, Italy, and the Netherlands, anchoring intra-European trade in palliative interventional products.
United States
Interventional pulmonology fellowship expansion in Philadelphia, Boston, and Houston drives procedural capacity growth. FDA breakthrough device designations accelerate review timelines for combination drug-device pleurodesis systems. Tertiary cancer centers in New York City and Houston anchor demand for integrated diagnostic-therapeutic platforms.
Germany
Ambulatory pleurodesis protocols minimize inpatient bed utilization at oncology centers in Munich and Heidelberg. EMA MDR documentation requirements extend commercialization timelines for permanently implanted pleural catheters. The Rhine-Ruhr and Bavarian medical technology clusters concentrate catheter manufacturing and notified body relationships.
Japan
Academic medical centers in Tokyo and Osaka maintain CT-guided capabilities for salvage procedures after ultrasound failure. PMDA regulatory pathways shape clinical evidence requirements for novel pleurodesis agents. The Kanto region anchors interventional radiology training and device procurement.
United Kingdom
Portable ultrasound deployment in outpatient clinics compresses diagnosis-to-intervention intervals. NHS reimbursement policies favor same-day pleural procedures over inpatient admission. London and Manchester oncology networks pilot digital drainage systems with remote patient surveillance.
China
NMPA oversight of drug-device combination products shapes market access timelines for imported pleurodesis systems. Domestic manufacturers in Shanghai and Beijing expand production of silicone-based tunneled catheters. The Yangtze River Delta concentrates interventional pulmonology training and tertiary cancer center capacity.
Malignant Pleural Effusion Market Competitive Landscape
Channel-controlling players compete with product-specialist players across the malignant pleural effusion market, creating a tiered structure where integrated oncology portfolios face focused interventional device portfolios. Large pharmaceutical conglomerates leverage systemic therapy relationships to bundle palliative procedures, while mid-cap device specialists capture procedural revenue through catheter and drainage platforms. Three archetypes dominate: diversified oncology giants with pleural disease programs, interventional device specialists with imaging integration capabilities, and regional biopharmaceutical developers with localized pleurodesis formulations. Competitive moves center on strategic partnerships between drug and device developers, plus geographic expansion into outpatient clinic channels.
Among the diversified oncology tier, Novartis AG and Bristol-Myers Squibb Company exemplify channel-controlling players that integrate systemic immuno-oncology with local palliative intervention. Roche Diagnostics occupies a position within the diagnostic-stratification archetype, anchoring biomarker-guided patient selection for targeted pleurodesis. These three companies represent contrasting strategic postures: pharmaceutical portfolio breadth, immuno-oncology platform depth, and diagnostic-therapeutic convergence.
| Leading Market Players |
|---|
| Gongwin Biopharm Holdings |
| Novartis AG |
| RS Oncology |
| Bristol-Myers Squibb Company |
| AstraZeneca plc |
| LIPAC Oncology |
| Simcere Pharmaceutical Group |
| Roche Diagnostics |
| Clover Biopharmaceuticals |
| Others |
Supply & Pricing Matrix
Silicone supply concentration in Asian polymer manufacturing clusters exposes device makers to tariff volatility and input cost spikes, compressing margin structures across standard-grade drainage systems while amplifying premium-tier pricing power for suppliers with captive polymer sourcing or MDR-compliant European documentation.
Pricing Analysis
Next-generation digital pleural drainage systems command substantial premiums over gravity-dependent evacuators and manual catheter platforms. Pricing stratifies across premium, standard, and economy tiers based on FDA breakthrough designation status and after-sales service bundling intensity. Cost compression in standard-grade catheters is intensifying because of polymer feedstock volatility and Asian manufacturing competition. Oncology centers in the United States exhibit lowest price sensitivity due to bundled reimbursement models, while outpatient clinics in resource-constrained markets prioritize economy-tier procurement.
Supply Chain Analysis
Tariff exposure between United States and Chinese silicone suppliers dominates supply chain risk planning for catheter manufacturers. Production gravity centers on Shanghai and Beijing for domestic Chinese consumption, with Rhine-Ruhr and Bavarian clusters handling European MDR-compliant manufacturing. Raw material dependencies span medical-grade silicone polymers, one-way valve mechanisms, and radiopaque catheter markers. Distribution runs through tertiary cancer center procurement offices in the United States, hospital system tenders in Germany, and government tenders in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The malignant pleural effusion market is entering a cyclical recovery phase as FDA breakthrough designations accelerate novel combination product approvals and interventional pulmonology fellowship expansion rebuilds procedural capacity.
For Market Incumbents: Insulate margin structures by securing backward integration into medical-grade silicone polymer sourcing or establishing dual-source supply agreements with notified body-certified European manufacturers. Invest in MDR technical documentation capabilities to defend European market position against emerging Asian competitors lacking CE-marking infrastructure.
For New Entrants and Emerging Players: Establish a beachhead in outpatient clinic digital drainage systems where incumbent service bundling remains underdeveloped. Target ambulatory surgical center channels in United States Medicare Advantage networks where site-of-care economics favor same-day intervention models over hospital-based alternatives.
For Investors and Strategic Acquirers: FDA's evolving framework for combination drug-device products reshapes the acquisition landscape toward platform companies with integrated diagnostic-therapeutic capabilities. Long-term viability favors targets with biomarker-guided patient selection platforms and established interventional pulmonology training partnerships. Monitor CMS reimbursement policy shifts for outpatient pleural procedures as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Pathway | Accelerated review timelines compress development cycles for combination pleurodesis-delivery systems. |
| Hospital System Partnership | Integrated procurement agreements with tertiary cancer centers lock in device placement volume and consumable recurring revenue. |
| Biomarker Companion Development | Pleural fluid proteomics platforms enable diagnostic stratification that justifies premium agent positioning. |
| CE Marking Pathway | EMA MDR compliance documentation creates European market access barriers protecting technical-file holders. |
| Reimbursement Strategy | Medicare coding alignment for tunneled catheter placement sustains ambulatory revenue models in United States oncology networks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA MDR technical documentation, ClinicalTrials.gov entries, and hospital procurement databases. Interviews with interventional pulmonologists, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at combination product manufacturers informed demand-side and supply-side assessments. Bottom-up procedure volume estimates triangulated against top-down market value reconstructions.
Forecast inputs span product type segmentation, procedural technology adoption curves, end-user site-of-care migration patterns, and regional regulatory cluster differentiation. CAGRs were derived from modeled procedure volume growth and average selling price trajectories across the analysis window. Treatment approach stratification and biomarker-guided patient selection penetration served as industry-specific demand modifiers.
Stress conditions across silicone polymer supply disruption, EMA MDR enforcement intensity, and CMS outpatient reimbursement revision were modeled; outcomes outside those bands fall beyond the analytical envelope. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
CARD9 Deficiency Treatment Market
Specialty Medicine
Cutaneous B-Cell Lymphoma Treatment Market
Specialty Medicine
Hereditary Angioedema Market
Specialty Medicine
Vertigo Market
Specialty Medicine
Central Nervous System (CNS) Biomarkers Market
Specialty Medicine
Toxic Epidermal Neurolysis Market
Specialty Medicine
Global Epilepsy Market
Specialty Medicine
Bipolar Disorders Treatment Market
Specialty Medicine
Fatty Liver Treatment Market
Specialty Medicine
Global Photodynamic Therapy Market
Specialty Medicine
Japan Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
North America Alopecia Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Market
Specialty Medicine
Europe Precision Medicine Market
Specialty Medicine
Intussusception Market
Specialty Medicine
Psychedelic Medicine Market