
 Spinal Stenosis Implant Market | 2026-2036
Spinal Stenosis Implant Market Size, Share, and Industry Trends Forecast 2026-2036
Spinal Stenosis Implant Market Analytics
Implant maintenance and long-term surveillance service contracts is rebalancing how vendors monetize spinal stenosis hardware beyond the initial procedure. Medtronic plc leverages its integrated surgical ecosystem to bundle navigation-enabled implants with ongoing software updates. Stryker Corporation anchors its competitiveness through scale manufacturing of titanium interbody devices. NuVasive, Inc. differentiates via specialized lateral access platforms that reduce operative time in degenerative conditions.
Spinal stenosis implants are load-bearing orthopedic devices, typically machined from titanium alloys or PEEK composites, designed to restore neural canal diameter and segmental stability in degenerative lumbar or cervical narrowing. Their primary commercial purpose is to sustain decompression outcomes while permitting controlled motion or rigid fusion depending on construct selection. Interspinous spacers occupy the fastest-expanding procedural niche among product types as clinicians seek motion-preserving alternatives in elderly patients with comorbidities. Minimally invasive delivery modes command premium positioning relative to open surgery due to reduced hospitalization and faster ambulatory recovery trajectories.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape implant development timelines and clinical evidence thresholds for market access. ISO 10993 biocompatibility testing standards govern material qualification protocols for permanent implantable metals and polymers. Stakeholders must monitor evolving CMS national coverage determinations for lumbar interspinous fixation with decompression, as reimbursement parity between inpatient and outpatient settings will determine site-of-service economics and vendor contracting leverage.
Market Dynamics
The migration of spinal stenosis procedures to ambulatory surgical centers is compressing implant procurement cycles and forcing vendors to restructure their commercial organizations around outpatient account management rather than traditional hospital contracting.
Growth Catalysts
- CMS reimbursement expansion:Medicare coverage determinations for minimally invasive lumbar decompression with interspinous fixation now extend to freestanding surgery centers, accelerating site-of-service migration.
- PEEK composite advancement:Radiolucent polymer cages with titanium plasma spray coatings reduce subsidence rates in osteoporotic bone, expanding addressable patient populations.
- Germany's early ambulation protocols:Bundesärztekammer guidelines incentivize motion-preserving constructs to shorten rehabilitation stays and reduce postoperative complication costs.
Market Restraints
- Titanium sponge supply concentration:Russian and Ukrainian feedstock disruptions have tightened aerospace-medical alloy allocation, pressuring spot prices for Ti-6Al-4V ELI bar stock.
- EU MDR clinical evidence thresholds:Legacy implant families without prospective registry data face notified body re-certification delays and market withdrawal risk.
- Conservative management substitution:Epidural steroid injection protocols and neurostimulation trials delay surgical intervention in mild-to-moderate stenosis cases.
Strategic Opportunities
- Japan's super-aging prefectures:Hokkaido and rural Honshu regions show surgical undersupply relative to degenerative spine prevalence, creating whitespace for mobile C-arm equipped clinics.
- Navigation-robotics convergence:Optical tracking systems paired with drill guides enable percutaneous pedicle screw placement through 15mm incisions, collapsing the learning curve for MIS adoption.
- India's PLI medical device scheme:Production-linked incentives for Class C implantables reduce effective tax burden for domestic titanium machining operations serving ASEAN export markets.
Industry Challenges
- Biostatistician talent scarcity:Premarket notification submissions require dedicated clinical data managers familiar with FDA 510(k) predicate equivalence arguments, a skill set concentrated among former notified body auditors.
- Legacy ERP integration friction:Ambulatory surgery center procurement platforms demand EDI connectivity and consignment inventory visibility that incumbent implant vendors struggle to retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spinal Stenosis Implant Market |
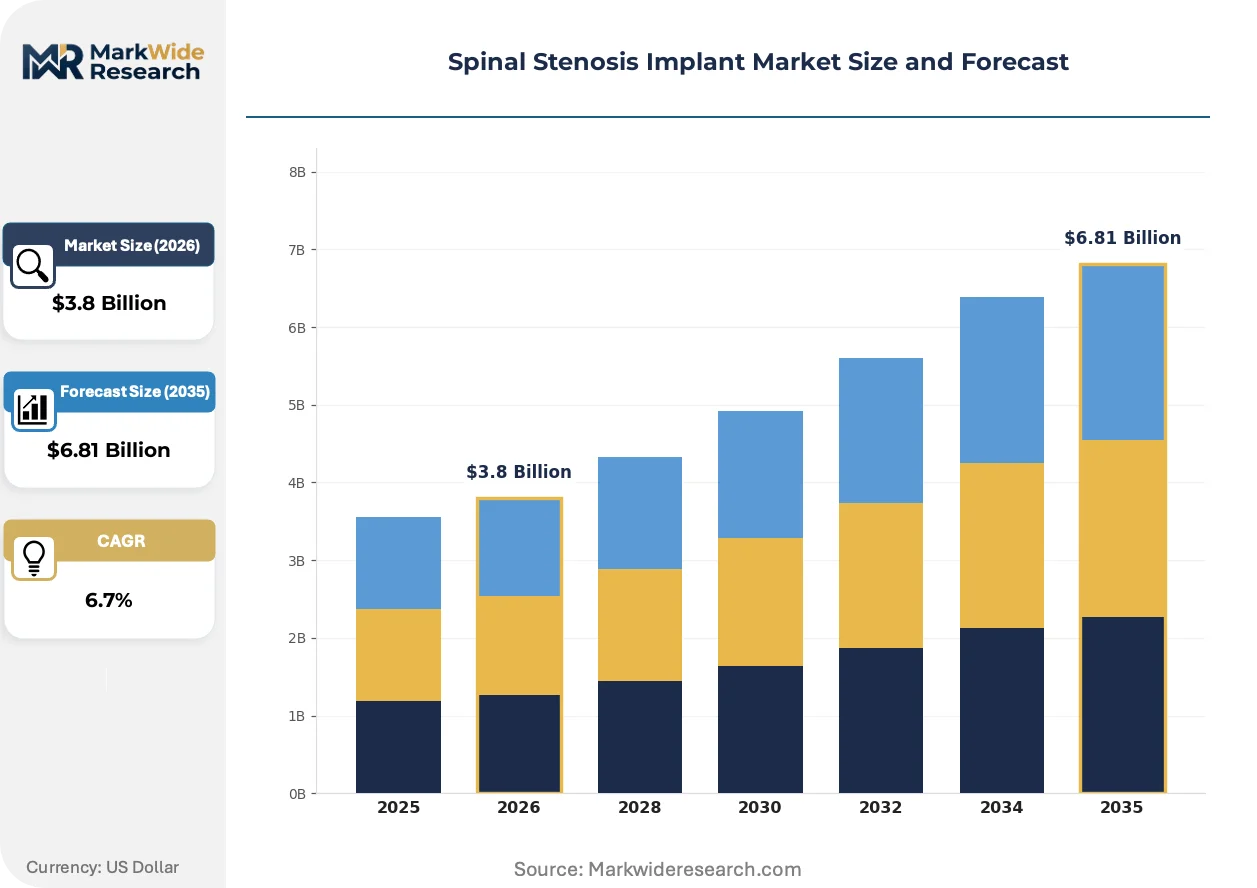
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interspinous Spacers, Dynamic Stabilization Implants, Pedicle Screws, Cages Delivery Mode: Open Surgery, Minimally Invasive Techniques, Robotic-Assisted Procedures, Endoscopic Approaches End User: Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics, Rehabilitation Facilities Technology: 3D Printing, Bioabsorbable Materials, Navigation Systems, Imaging Technologies |
| Companies Covered | Medtronic plc, Stryker Corporation, Johnson & Johnson, Zimmer Biomet Holdings Inc., Globus Medical, Inc., NuVasive, Inc., Orthofix Holdings, Inc., Vertiflex Inc., Premia Spine, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spinal Stenosis Implant Market Evolving Landscape
Spinal implant engineering is pivoting from mechanical fixation toward biologic integration and procedural efficiency, with material science and digital surgical planning compressing the gap between preoperative templating and intraoperative execution.
Additive manufacturing of porous titanium interbodies is converging with patient-specific anatomical modeling to produce lattice structures with 80% porosity and modulus-matched elasticity. Academic medical centers in the United States and Switzerland are adopting these constructs for complex revision fusions. This convergence is collapsing the traditional separation between implant manufacturing and surgical planning software, forcing device firms to acquire or partner with segmentation algorithm developers.
The EU MDR's requirement for post-market clinical follow-up data is extending surveillance obligations from two years to the implant's lifetime, compelling manufacturers to fund national spine registries or risk certificate suspension. German and Dutch notified bodies are interpreting this most strictly for cervical total disc replacements. Smaller implant portfolios without dedicated clinical affairs infrastructure are withdrawing from European markets rather than absorbing compliance costs.
Hospital purchasing cooperatives are consolidating implant contracts into single-source agreements with performance guarantees on infection rates and reoperation indices. This behavior concentrates procurement leverage among multi-hospital systems in Texas and Florida while displacing independent distributor relationships. The shift is most visible in Medicare Advantage–dominated markets where payers directly contract with implant vendors for episode-of-care bundles.
Spinal Stenosis Implant Market Segmentation
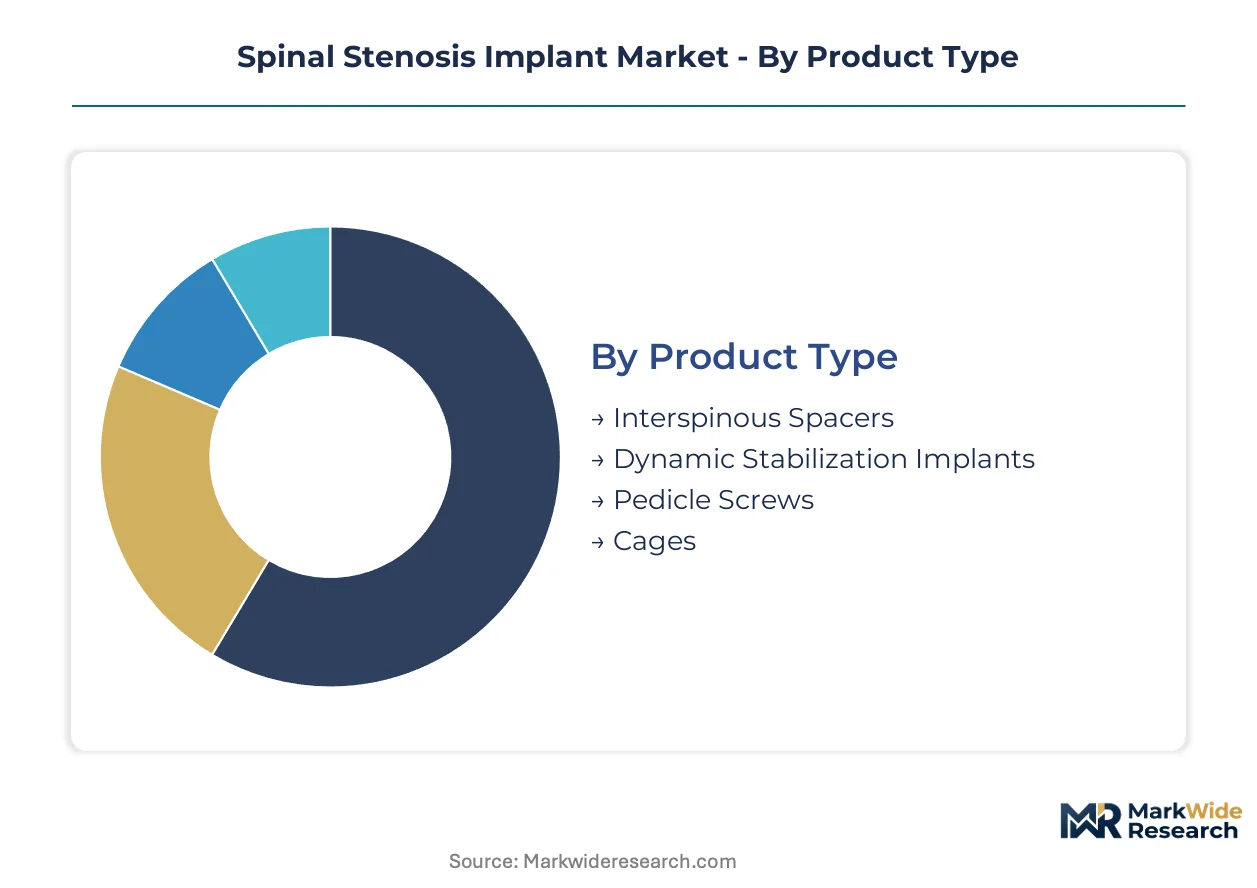
Segmentation in spinal stenosis implants determines regulatory pathway complexity and reimbursement coding precision. Product type and delivery mode classifications directly map to FDA 510(k) predicate requirements and CMS procedure payment tiers.
Product Type:
FDA 510(k) clearance timelines stretch longest for dynamic stabilization implants requiring fatigue testing data, while interspinous spacers navigate abbreviated pathways through established predicate families.
- Interspinous Spacers:Titanium or PEEK constructs inserted between spinous processes to maintain foraminal height without fusion. Demand concentrates in Medicare Advantage networks across Florida and Texas, where outpatient decompression with interspinous fixation commands bundled episode payments.
- Dynamic Stabilization Implants:Pedicle screw-based systems with flexible rods or polymer tethers permitting controlled segmental motion. German orthopedic clinics drive procurement following Bundesärztekammer ambulation protocol incentives that reduce rehabilitation costs.
- Pedicle Screws:Ti-6Al-4V ELI titanium screws for posterior fixation in fusion constructs.
- Cages:Interbody fusion devices machined from PEEK or porous titanium for anterior or lateral column support.
Leading the category by volume: Cages. Growing fastest: Interspinous Spacers.
Delivery Mode:
Cost tiering separates premium robotic-assisted placements from standard open approaches, with reimbursement differentials of 40-60% between inpatient and outpatient settings.
- Minimally Invasive Techniques:Tubular retractor systems and percutaneous screw placement through 15-20mm incisions. Ambulatory surgical centers in the United States are expanding MIS capacity to capture CMS reimbursement for same-day lumbar decompression.
- Robotic-Assisted Procedures:Optical navigation platforms with drill guidance for sub-millimeter pedicle screw accuracy. Academic medical centers in Switzerland and the United States deploy these systems for complex revision cases requiring preoperative templating integration.
- Open Surgery:Traditional midline approaches with direct visualization for multilevel decompression.
- Endoscopic Approaches:Uniportal or biportal visualization systems for targeted discectomy and decompression.
Highest margin capture: Robotic-Assisted Procedures. Steepest expansion trajectory: Minimally Invasive Techniques.
End User:
Customer type determines procurement contract structure, with hospital systems demanding consignment inventory and ambulatory centers requiring just-in-time delivery.
- Ambulatory Surgical Centers:Freestanding facilities performing outpatient lumbar decompression with interspinous fixation. CMS national coverage determinations now extend to these sites, compressing vendor sales cycles from 90-day hospital negotiations to 30-day ASC procurement.
- Hospitals:Inpatient and outpatient departments within integrated delivery networks. Texas and Florida multi-hospital systems are consolidating implant contracts into single-source agreements with infection rate guarantees.
- Orthopedic Clinics:Physician-owned facilities with limited procedure volume.
- Rehabilitation Facilities:Post-acute settings managing non-surgical stenosis patients.
Fastest volume shift: Ambulatory Surgical Centers. Largest absolute spend: Hospitals.
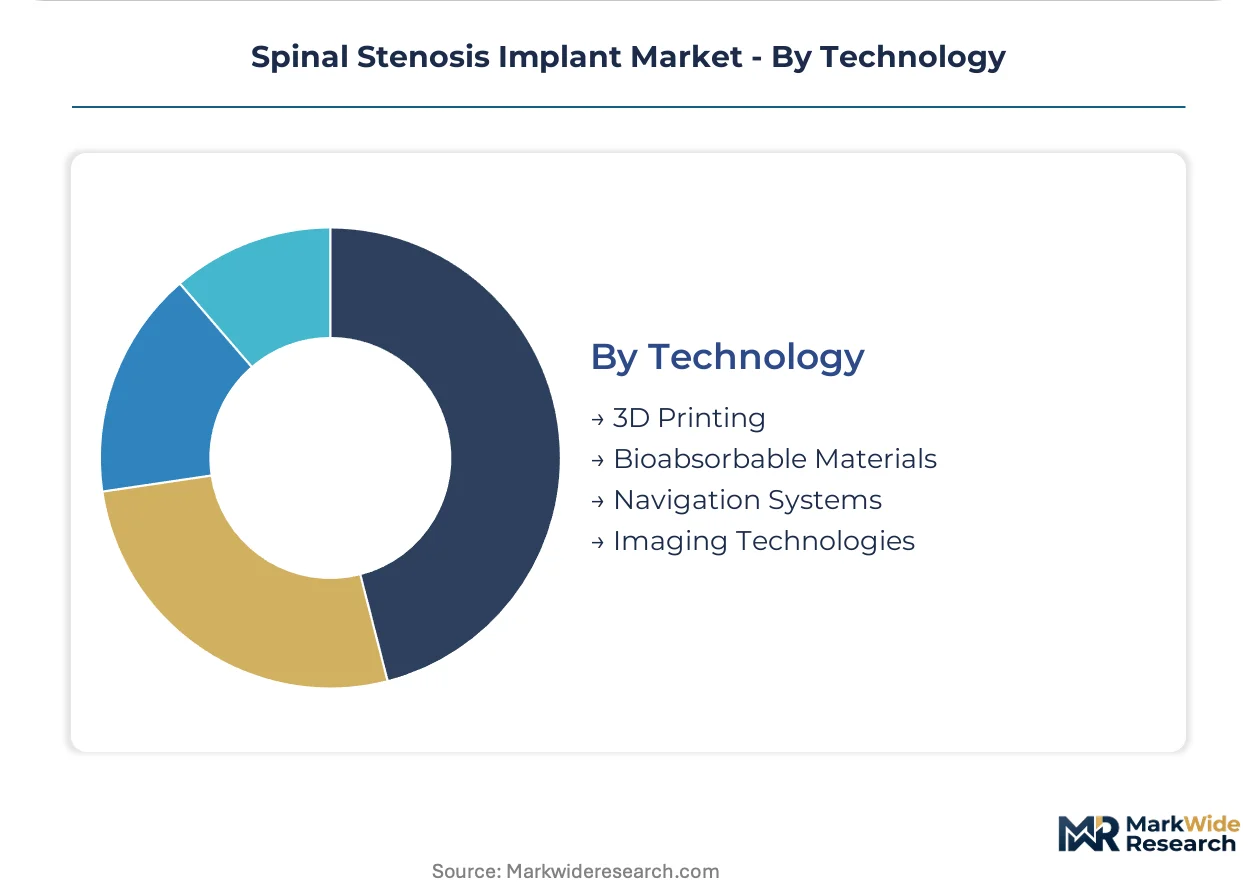
Technology:
Supply concentration clusters additive manufacturing equipment among North American and Swiss contract manufacturers, constraining 3D-printed implant availability.
- 3D Printing:Electron beam melting of porous titanium lattices with 80% porosity and modulus-matched elasticity. Academic centers in the United States and Switzerland adopt these for osteoporotic revision fusions where subsidence risk limits conventional cage options.
- Navigation Systems:Optical tracking with patient-specific anatomical modeling for screw trajectory planning. EU MDR post-market surveillance requirements now mandate lifetime implant tracking, extending software update obligations from two years to device end-of-life.
- Bioabsorbable Materials:Poly-lactic acid constructs for temporary fixation in younger patients.
- Imaging Technologies:Intraoperative CT and 3D fluoroscopy for real-time implant positioning verification.
Widest clinical adoption: Navigation Systems. Narrowest regulatory pathway: 3D Printing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium alloy machining capacity concentrates in aerospace corridors while implant demand clusters in aging metropolitan regions. This geographic mismatch forces vendors to manage transcontinental supply chains for biocompatible bar stock.
United States
Medicare Advantage networks in Florida and Texas drive outpatient interspinous spacer utilization through bundled episode payments. FDA 510(k) clearance pathways govern predicate equivalence requirements for motion-preserving constructs. The Dallas-Fort Worth metro anchors ambulatory surgical center expansion, with freestanding facilities capturing same-day decompression cases previously routed to inpatient wards.
Germany
Bundesärztekammer ambulation protocols incentivize motion-preserving implants to compress rehabilitation stays. EU MDR notified bodies in Berlin and Munich enforce lifetime post-market surveillance for cervical disc replacements. The Rhine-Ruhr industrial belt hosts precision titanium machining operations serving both medical device and aerospace alloy demand.
Switzerland
Academic medical centers in Zurich and Geneva adopt patient-specific porous titanium constructs for complex revision fusions. Swissmedic coordinates with EU MDR conformity assessment procedures despite non-member status. The Basel-Zurich corridor concentrates additive manufacturing equipment for lattice-structured interbodies with modulus-matched elasticity.
Japan
Super-aging prefectures including Hokkaido and rural Honshu exhibit surgical undersupply relative to degenerative spine prevalence. PMDA oversees biocompatibility documentation for titanium alloy permanent implants under harmonized ISO 10993 standards. The Kanto region around Tokyo maintains concentration of navigation-robotics surgical platforms for percutaneous pedicle screw placement.
India
Production-linked incentive schemes for Class C implantables reduce effective tax burdens for domestic titanium machining serving ASEAN export markets. CDSCO regulates premarket import licensing for spinal fixation devices manufactured abroad. The Pune-Ahmedabad corridor in Maharashtra and Gujarat states develops contract manufacturing capacity for porous titanium interbody cages.
Spinal Stenosis Implant Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the spinal stenosis implant sector. Vertically integrated titanium alloy processors maintain cost advantages in interbody cage manufacturing while specialized navigation software firms capture premium positioning in robotic-assisted placement systems. Three archetypes dominate: diversified orthopedic conglomerates with integrated surgical ecosystems, pure-play spine specialists focused on lateral access platforms, and contract manufacturers leveraging India's PLI medical device incentives. Consolidation pressure intensifies through hospital purchasing cooperative single-source agreements and ambulatory surgery center procurement platform standardization.
Among diversified orthopedic conglomerates, Medtronic plc and Stryker Corporation exemplify scale-driven positioning through integrated surgical ecosystems and titanium interbody manufacturing volume respectively. NuVasive, Inc. occupies a specialist tier focused on lateral access platforms that reduce operative time in degenerative conditions. These three entities represent contrasting strategic postures: ecosystem bundling, manufacturing scale, and procedural specialization.
| Leading Market Players |
|---|
| Medtronic plc |
| Stryker Corporation |
| Johnson & Johnson |
| Zimmer Biomet Holdings Inc. |
| Globus Medical, Inc. |
| NuVasive, Inc. |
| Orthofix Holdings, Inc. |
| Vertiflex Inc. |
| Premia Spine, Ltd. |
| Others |
Value Network & Pricing Analysis
Ti-6Al-4V ELI bar stock costs cascade through spinal implant pricing tiers as Russian and Ukrainian titanium sponge disruptions tighten aerospace-medical alloy allocation, forcing vendors to absorb spot price volatility or pass through to ambulatory surgery centers with compressed procurement cycles.
Pricing Analysis
Cost-down pressure on interbody cages accelerates because hospital purchasing cooperatives in Texas and Florida are consolidating contracts into single-source agreements with infection rate guarantees. Three-tier pricing structure across premium navigation-enabled systems, standard titanium constructs, and economy PEEK spacers reflects FDA 510(k) predicate complexity and brand equity. Price differentiation hinges on EU MDR certificate status and ambulatory center volume commitments. Medicare Advantage networks show lowest price sensitivity for bundled episode payments, while independent orthopedic clinics face acute margin compression.
Supply Chain Analysis
Dual-sourcing mandates from German and Swiss notified bodies require titanium alloy qualification across at least two bar stock suppliers, complicating procurement for porous interbody manufacturers. Feedstock concentrates in the United States, Russia, and Ukraine, with aerospace-medical grade sponge drawing from Ukrainian extraction operations. Supply chain risk centers on geopolitical disruption to Ti-6Al-4V ELI allocation. Distribution runs through hospital GPO consignment inventory and ambulatory surgery center just-in-time platforms with EDI connectivity requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spinal stenosis implant market functions as a cost-of-compliance arena where EU MDR lifetime surveillance obligations and FDA 510(k) predicate equivalence thresholds erect regulatory moats favoring incumbents with dedicated clinical affairs infrastructure.
For Market Incumbents: Cement market position by acquiring segmentation algorithm developers to collapse the gap between implant manufacturing and surgical planning software. Deepen backward integration into titanium alloy bar stock processing to offset Russian-Ukrainian feedstock volatility. Prioritize EU MDR certificate maintenance for cervical disc portfolios facing notified body re-certification delays. For New Entrants and Emerging Players: Direct-to-ambulatory-center digital procurement platforms offer the most penetrable route around entrenched hospital GPO relationships. Target Japan's Hokkaido and rural Honshu prefectures where surgical undersupply relative to degenerative spine prevalence creates whitespace for mobile C-arm equipped clinics. Lead with interspinous spacer offerings that navigate abbreviated FDA 510(k) pathways. For Investors and Strategic Acquirers: CMS national coverage determinations extending to ambulatory surgical centers is the leading indicator that site-of-service economics will concentrate procurement leverage among outpatient-focused vendors. Five-to-ten year viability favors asset-light designers with navigation-robotics convergence capabilities over capital-heavy titanium processors. Watch for EU MDR certificate suspensions forcing smaller portfolios into distressed sale scenarios.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Expansion | Abbreviated clearance pathways for interspinous spacers accelerate time-to-revenue in Medicare Advantage networks. |
| EU MDR Lifetime Surveillance Investment | Post-market clinical follow-up data infrastructure prevents certificate suspension for cervical disc replacements in Germany. |
| Ambulatory Surgery Center Partnership | Consignment inventory visibility and EDI connectivity capture CMS reimbursement for same-day lumbar decompression. |
| Navigation-Robotics Convergence | Optical tracking with patient-specific modeling collapses the learning curve for percutaneous pedicle screw placement. |
| Additive Manufacturing Scale-Up | Electron beam melting capacity for 80% porosity titanium lattices serves osteoporotic revision fusion demand in Swiss academic centers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this spinal stenosis implant analysis, combining primary interviews with spine surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. FDA 510(k) clearance databases, EU MDR notified body certificates, CMS national coverage determinations, and titanium alloy import records provided validation layers. Bottom-up implant volume modeling and top-down market sizing triangulated across these sources.
Granularity-level modeling disaggregated projections by product type, delivery mode, end user, and technology across the analysis window, with CAGRs derived from procedure volume trajectories and reimbursement policy shifts. Segmentation captured interspinous spacer versus dynamic stabilization demand, minimally invasive versus robotic-assisted placement economics, and ambulatory surgery center versus hospital procurement cycle differences. Titanium alloy price elasticity and EU MDR compliance cost curves informed supply-side constraints.
The model holds under stable CMS reimbursement parity between inpatient and outpatient settings; deviation in Medicare Advantage bundled payment structures or EU MDR notified body interpretation strictness would shift vendor contracting leverage and market access timelines materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Nerve Monitoring Devices Market
Medical Devices
Global Hip Implant Market
Medical Devices
Smart Patches Market
Medical Devices
Brain-On-Chip Model Market
Medical Devices
Global Digital Therapeutic Devices Market
Medical Devices
Small Bowel Enteroscopes Market
Medical Devices
Japan Respiratory Devices Market
Medical Devices
Medical Cyclotron Market
Medical Devices
Radiotherapy Devices Market
Medical Devices
Global Medical Devices Market
Medical Devices
Dynamic Spinal Tethering Systems Market
Medical Devices
Organ Transport Devices Market
Medical Devices
Global Artificial Organ Market
Medical Devices
Surgical Devices Market
Medical Devices
Global Transcatheter Pulmonary Valve Market
Medical Devices
Diode Laser Aesthetic Medical Device Market