
 Handheld Backscatter X-Ray Devices Market | 2026-2036
Handheld Backscatter X-Ray Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld Backscatter X-Ray Devices Market Foresight
CMOS sensor miniaturization is fragmenting the traditional detector supply chain for handheld backscatter X-ray devices. Rapiscan Systems leverages in-house radiation sensor fabrication to control component costs across its portable scanner portfolio. Nuctech Company Limited anchors its competitive stance through integrated manufacturing spanning tube sources to detection algorithms. Smiths Detection differentiates via hardened imaging units engineered for military field deployment.
Handheld backscatter X-ray devices employ low-energy X-ray beams that scatter upon contact with surfaces, enabling single-sided inspection of vehicles, cargo, and personnel without fixed portal infrastructure. These systems typically operate at 50-150 keV with real-time image reconstruction through proprietary detection algorithms, serving customs departments and military units requiring rapid mobility. The technology segment shows detection algorithms commanding premium pricing due to AI-enhanced threat classification development, while backscatter imaging remains the volume foundation across security applications. End-user concentration tilts toward customs departments in mature markets, whereas law enforcement represents the fastest-expanding procurement channel as municipal agencies adopt portable scanners for urban screening operations.
The US FDA regulates radiation-emitting product safety under 21 CFR 1020.40, while the NRC governs radioactive materials licensing for device operators, creating dual compliance pathways that shape vendor certification investments. The EU AI Act's risk classification framework for automated threat detection is beginning to influence algorithm transparency requirements across export-bound equipment. Stakeholders must monitor how evolving radiological security standards in major procurement markets reshape hardware-software integration roadmaps and service contract structures.
Market Dynamics
Dual compliance pathways under US FDA and NRC jurisdiction are fragmenting vendor certification investments while CMOS sensor miniaturization disrupts traditional detector supply chains. Equipment refresh cycles at US Transportation Security Administration checkpoints are compressing replacement timelines.
Growth Catalysts
- Customs Modernization Programs:India's DGFT-led port infrastructure upgrades are scaling procurement of portable scanners for single-sided cargo inspection across Mumbai, Chennai, and Visakhapatnam facilities.
- AI-Enhanced Detection Algorithms:Machine learning classification models trained on threat libraries are commanding premium pricing as security agencies prioritize automated screening accuracy.
- Urban Law Enforcement Expansion:Municipal agencies in high-density metropolitan areas are adopting handheld units for rapid deployment screening operations without fixed portal requirements.
Market Restraints
- Radiation Licensing Burden:NRC operator certification requirements create prolonged deployment timelines and recurring compliance costs for agency procurement budgets.
- Detector Component Concentration:CMOS sensor fabrication capacity clusters among Asian foundries, exposing supply continuity risks to single-source dependencies.
- Fixed Portal Substitution:Conveyor-based transmission X-ray systems retain cost advantages for high-volume checkpoint environments, limiting handheld penetration in established facilities.
Strategic Opportunities
- Military Field Deployment:Hardened imaging units engineered for expeditionary logistics represent underpenetrated demand as defense agencies prioritize mobility over fixed infrastructure.
- EU AI Act Algorithm Transparency:Risk classification frameworks for automated threat detection are creating first-mover advantages for vendors with documented explainability protocols.
- Integrated Manufacturing Convergence:Captive production spanning tube sources to detection algorithms enables margin compression against modular competitors dependent on external component sourcing.
Industry Challenges
- Cross-Functional Talent Scarcity:Radiation physics expertise combined with embedded software development skills remains concentrated among legacy nuclear instrumentation specialists.
- Legacy System Integration Friction:Proprietary image reconstruction protocols create interoperability barriers when agencies attempt to unify handheld data with centralized security operations centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld Backscatter X-Ray Devices Market |
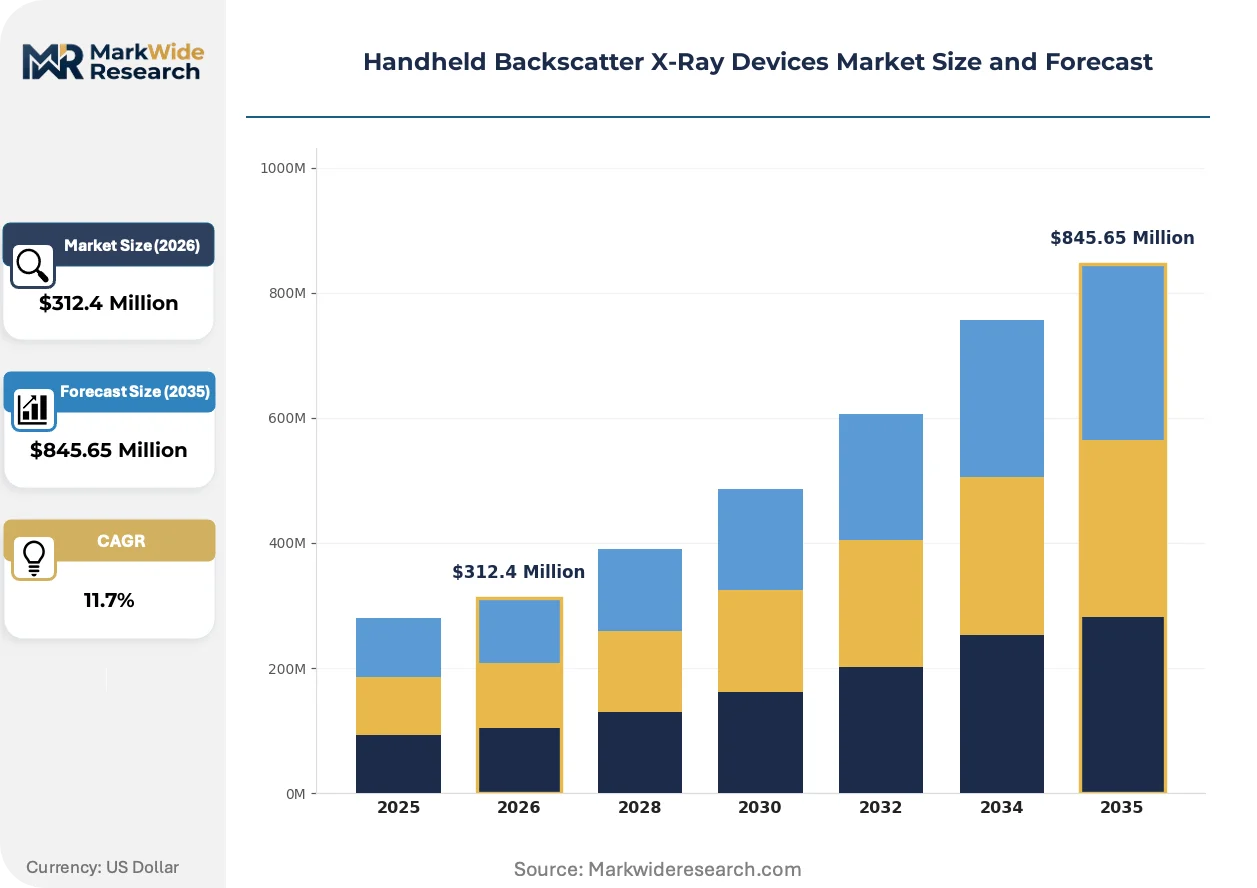
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Scanners, Inspection Systems, Security Devices, Imaging Units Technology: Backscatter Imaging, X-Ray Diffraction, Detection Algorithms, Radiation Sensors End User: Security Agencies, Customs Departments, Military Units, Law Enforcement Application: Threat Detection, Cargo Inspection, Personnel Screening, Smuggling Prevention |
| Companies Covered | Rapiscan Systems, Nuctech Company Limited, Viken Detection, Smiths Detection, Videray Technologies, Tek84, Inc., Scanna MSC, Autoclear, ADANI Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld Backscatter X-Ray Devices Market Shifts & Advancements
Software-defined detection architectures are virtualizing hardware functions that previously required dedicated radiation sensor arrays. This shift is compressing equipment form factors while expanding algorithmic upgrade pathways.
Silicon photomultiplier arrays paired with scintillator crystals are virtualizing the photon-counting functions historically performed by vacuum photomultiplier tubes. Customs departments in Germany and the Netherlands are piloting these solid-state configurations for reduced power consumption in mobile screening vehicles. The technology is virtualizing detector maintenance schedules and enabling field-replaceable sensor modules without factory recalibration.
The EU AI Act's risk classification framework for biometric and automated threat detection systems is mandating algorithmic transparency documentation for export-bound equipment. Vendors must now submit conformity assessments demonstrating explainable classification logic to notified bodies under MDR-equivalent scrutiny. This regulatory architecture is accelerating investments in interpretable machine learning architectures among European-bound product lines.
Service contract unbundling is separating hardware acquisition from algorithm licensing and training support. Law enforcement agencies in Texas and Florida are negotiating standalone software subscription terms independent of initial capital expenditure. This procurement pattern shift is most visible in municipal budgets where operating expenditure approval pathways face lower political friction than capital appropriations.
Handheld Backscatter X-Ray Devices Market Segmentation
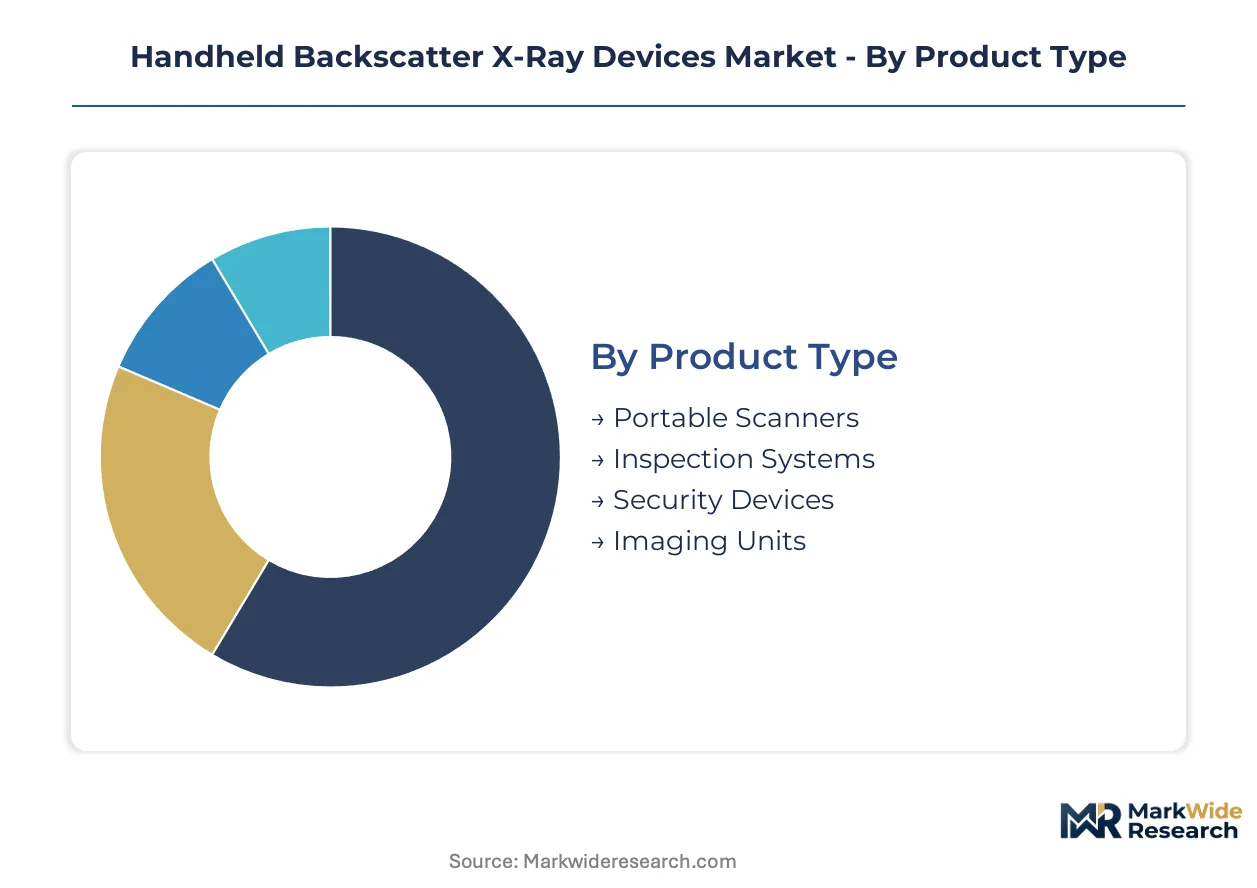
Segmentation in handheld backscatter X-ray devices reveals how procurement priorities diverge across security missions and operational environments. Understanding these divides helps vendors align product roadmaps with the specific mobility, imaging resolution, and threat library requirements that dominate each channel.
Product Type:
The use-case spectrum spans from rapid-deployment field units to vehicle-integrated screening platforms, with form factor and power autonomy determining deployment feasibility across border checkpoints and urban operations.
- Portable Scanners:Battery-operated units weighing under 15 kg enable single-operator deployment for vehicle-side inspection at remote border crossings. Customs departments in India prioritize these for port modernization programs across Mumbai and Chennai facilities where fixed infrastructure remains incomplete.
- Inspection Systems:Modular configurations with swappable detector arrays support extended screening operations in mobile command vehicles. Military units in expeditionary logistics roles drive demand for hardened variants with MIL-STD-810G environmental certification.
- Security Devices:Compact handheld units optimized for personnel screening at event venues and transport hubs. Law enforcement agencies in Texas and Florida are expanding municipal procurement for rapid-deployment urban operations.
- Imaging Units:High-resolution detector assemblies with proprietary reconstruction algorithms for forensic documentation. Security agencies use these for evidentiary-grade imaging in smuggling prosecutions.
The dominant share belongs to Portable Scanners, while Inspection Systems are gaining share fastest as defense agencies prioritize mobility over fixed infrastructure.
Technology:
Cost tier differentiation separates volume hardware from premium algorithmic capabilities, with AI-enhanced classification commanding substantial price premiums over baseline imaging functions.
- Backscatter Imaging:Core technology employing 50-150 keV X-ray beams that scatter from surfaces to enable single-sided inspection without portal infrastructure. This remains the volume foundation across customs and security applications where penetration depth requirements are moderate.
- Detection Algorithms:Machine learning models trained on threat libraries for automated classification of anomalies in scanned imagery. These command premium pricing as the EU AI Act mandates algorithmic transparency documentation for export-bound equipment.
- X-Ray Diffraction:Crystallographic analysis for material identification in concealed substances. Customs laboratories deploy these for forensic confirmation of narcotics and explosives.
- Radiation Sensors:CMOS and silicon photomultiplier arrays converting scattered X-rays into digital signals. Sensor miniaturization is fragmenting traditional supply chains as Asian foundries concentrate fabrication capacity.
Backscatter Imaging holds the installed base majority, though Detection Algorithms are climbing the fastest as procurement shifts toward automated screening accuracy.
End User:
Customer type concentration varies sharply by procurement authority, with federal agencies dominating capital budgets while municipal law enforcement expands through operating expenditure channels.
- Customs Departments:Federal border agencies with mandate-driven refresh cycles and multi-year procurement frameworks. India's DGFT-led modernization is scaling orders across Visakhapatnam and other major port facilities.
- Security Agencies:National-level organizations with centralized threat intelligence integration requirements. These agencies prioritize interoperability with existing security operations center architectures.
- Military Units:Expeditionary forces requiring hardened equipment for field deployment in contested logistics environments. Procurement emphasizes MIL-STD compliance and rapid emplacement capability.
- Law Enforcement:Municipal and state agencies with fragmented budgets and event-driven deployment patterns. These units are driving service contract unbundling to separate hardware acquisition from algorithm licensing.
Customs Departments retain the largest procurement volume, while Law Enforcement represents the steepest expansion trajectory as urban screening operations proliferate.
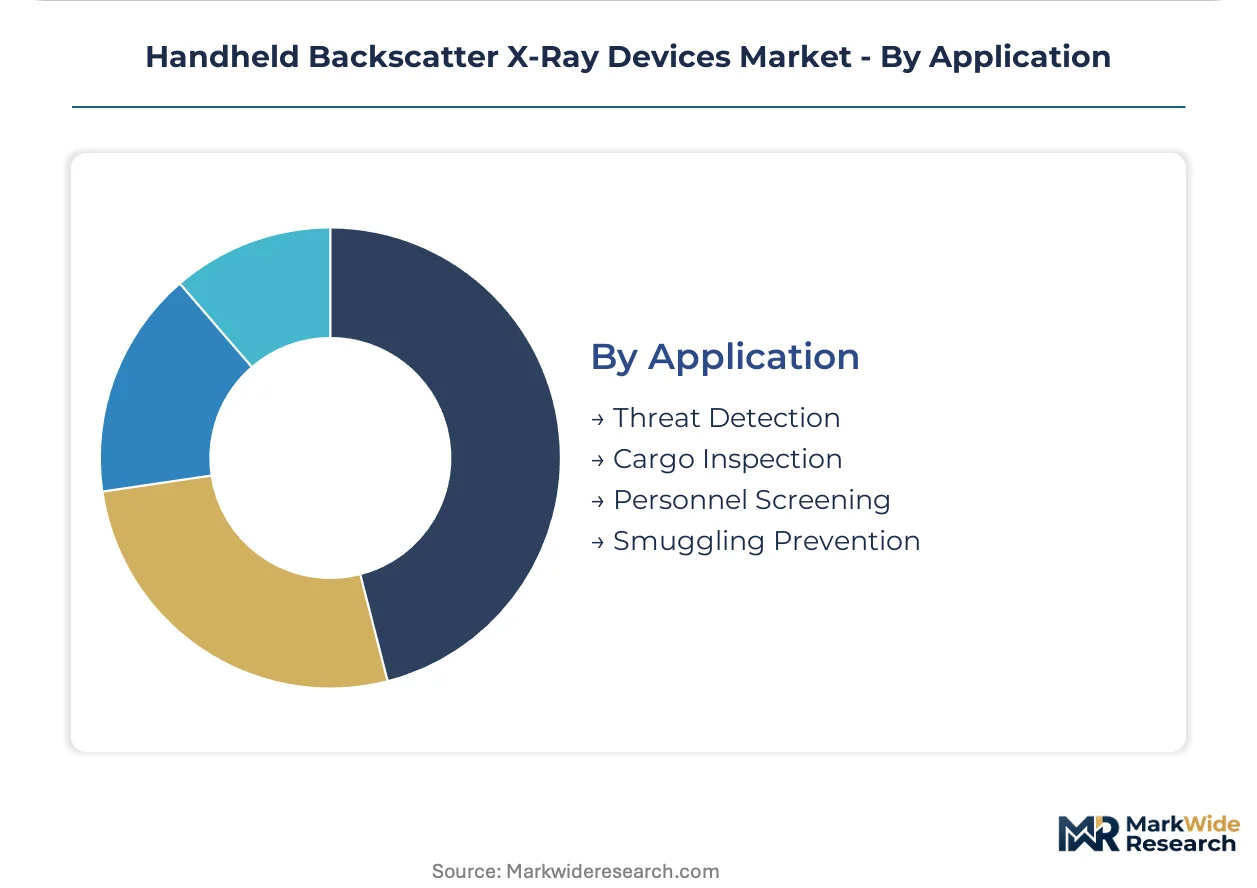
Application:
Application maturity correlates with regulatory standardization, with threat detection protocols more codified than emerging use cases in personnel screening where privacy frameworks remain unsettled.
- Threat Detection:Automated identification of weapons, explosives, and improvised devices in scanned imagery. Security agencies prioritize this application for checkpoint throughput optimization.
- Cargo Inspection:Single-sided scanning of containerized and vehicular loads at border crossings and port facilities. This application dominates customs procurement with established operational protocols.
- Personnel Screening:Backscatter imaging of individuals for concealed item detection. Privacy regulations and radiation exposure limits create deployment friction in civilian environments.
- Smuggling Prevention:Detection of contraband including narcotics, currency, and undeclared goods. Customs departments integrate these operations with risk-based targeting systems.
Cargo Inspection commands the dominant application share, while Personnel Screening is expanding most quickly as privacy-compliant protocols mature for transport hub deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports handheld backscatter X-ray devices to customs agencies across Southeast Asia and the Middle East, with domestic port modernization driving parallel import substitution for critical detector components.
United States
The Transportation Security Administration compresses equipment refresh cycles at domestic checkpoints. FDA radiation-emitting product regulations under 21 CFR 1020.40 intersect with NRC operator licensing requirements. Texas and Florida municipal law enforcement agencies in Houston and Miami expand procurement for urban screening operations.
India
The Directorate General of Foreign Trade scales customs modernization across major port facilities. DGFT-led infrastructure upgrades prioritize single-sided cargo inspection capabilities. Mumbai, Chennai, and Visakhapatnam facilities concentrate procurement of portable scanners for incomplete fixed infrastructure environments.
Germany
Customs departments pilot silicon photomultiplier arrays in mobile screening vehicles for reduced power consumption. EU AI Act risk classification frameworks mandate algorithmic transparency documentation for automated threat detection systems. The Netherlands and Germany coordinate pilot programs across Rotterdam and Hamburg port corridors.
China
CMOS sensor fabrication capacity concentrates among domestic foundries, exposing supply continuity dependencies for detector components. MIIT standards govern radiation-emitting equipment certification pathways. Shenzhen and Shanghai industrial clusters anchor component manufacturing for export-bound portable scanner assemblies.
United Arab Emirates
Border security agencies prioritize rapid-deployment screening for trade corridor protection. MOHAP and federal customs authorities coordinate equipment standards for radiological safety compliance. Dubai and Abu Dhabi logistics hubs drive procurement of hardened units for high-throughput cargo inspection environments.
Handheld Backscatter X-Ray Devices Market Competitive Landscape
On the supply side, the industry is consolidating around integrated manufacturing capabilities that span tube sources through detection algorithms. Tiered competitive positioning separates captive producers from modular assemblers dependent on external component sourcing. Three archetypes dominate: vertically integrated system houses, specialized detector fabricators, and algorithm-centric software vendors. M&A activity targets radiation sensor fabrication assets, while strategic partnerships concentrate on AI-enhanced threat classification development.
Among integrated manufacturing specialists, Rapiscan Systems and Nuctech Company Limited exemplify the captive production archetype spanning hardware through software layers. Smiths Detection occupies a position within the hardened equipment tier engineered for expeditionary deployment requirements. These three anchors illustrate how control over detector supply chains differentiates pricing power against competitors reliant on external CMOS sensor procurement.
| Leading Market Players |
|---|
| Rapiscan Systems |
| Nuctech Company Limited |
| Viken Detection |
| Smiths Detection |
| Videray Technologies |
| Tek84, Inc. |
| Scanna MSC |
| Autoclear |
| ADANI Systems |
| Others |
Supply & Pricing Matrix
The Dubai-Jebel Ali freight corridor's container handling cost dynamics compress margins for detector component shipments while amplifying price differentiation between integrated manufacturers and modular assemblers. Asian foundry concentration for CMOS sensors feeds upstream pricing power into downstream equipment tiers, with customs procurement budgets absorbing differential cost structures across single-source and dual-source supply configurations.
Pricing Analysis
Prior-generation portable scanners trade at substantial discounts to current-generation AI-enhanced units, while next-generation silicon photomultiplier configurations command laboratory-grade premiums. Three-tier pricing structure across premium, standard, and economy levels separates MIL-STD-certified military variants from municipal law enforcement configurations and basic customs inspection units. Pricing pressure stems from service contract unbundling as Texas and Florida agencies negotiate standalone software subscriptions independent of capital expenditure. Municipal law enforcement exhibits highest price sensitivity due to operating expenditure approval constraints, while military procurement demonstrates lowest sensitivity given mission-critical deployment requirements.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for detector component sourcing. CMOS sensor fabrication concentrates in China, Taiwan, and South Korea, with scintillator crystal processing anchored in Japan and Germany. Raw material dependencies span high-purity silicon substrates, rare-earth phosphors, and precision-machined tungsten collimators. Single-source vulnerability concentrates in Asian foundry capacity for radiation-hardened sensor arrays. Distribution runs through authorized security equipment distributors with NRC licensing compliance requirements, bypassing general industrial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The handheld backscatter X-ray market approaches a platform-economics inflection as proprietary image reconstruction protocols fragment interoperability with centralized security operations centers. Algorithm licensing unbundling from hardware acquisition creates ecosystem lock-in dynamics reminiscent of enterprise software transitions.
For Market Incumbents: Insulate captive manufacturing advantages by deepening in-house radiation sensor fabrication capacity before CMOS foundry consolidation accelerates. Prioritize FDA 21 CFR 1020.40 certification investments as a defensive moat against modular competitors dependent on external component sourcing. Threat substitution from software-defined detection architectures demands accelerated R&D in interpretable machine learning architectures for EU AI Act compliance. For New Entrants and Emerging Players: India's DGFT-led port modernization programs represent the most penetrable geographic entry point, with incomplete fixed infrastructure creating demand for portable scanners without entrenched vendor relationships. Military field deployment specifications remain underpenetrated by cost-optimized configurations, offering white-space for hardened equipment at standard-tier pricing. Go-to-market positioning should emphasize algorithm transparency documentation for EU-bound export qualification ahead of established competitors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with orphaned radiation detection divisions lacking security market focus. Long-term viability hinges on vertical integration depth spanning tube sources through detection algorithms, with five-to-ten year windows favoring captive producers over modular assemblers. Signal to monitor: EU AI Act conformity assessment submission rates by vendor as inflection indicator for algorithmic competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Manufacturing Expansion | Captive CMOS sensor fabrication insulates Rapiscan and Nuctech from Asian foundry concentration risks. |
| EU AI Act Compliance Investment | Algorithm transparency documentation creates first-mover advantage for German and Dutch customs pilot programs. |
| Military Hardening Certification | MIL-STD-810G qualification opens expeditionary logistics procurement channels for Smiths Detection. |
| Service Contract Unbundling | Standalone software subscriptions align with Texas and Florida municipal budget approval pathways. |
| Silicon Photomultiplier Migration | Solid-state detector virtualization reduces power consumption for mobile screening vehicle deployments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 21 CFR filings, NRC licensing databases, EU AI Act conformity assessments, and customs procurement records. Primary interviews engaged radiation safety officers at US port facilities, DGFT procurement leads in India, biomedical engineers at German customs laboratories, and security operations center architects at federal agencies. Secondary validation drew from MIIT equipment certification disclosures, SEC 10-K filings of listed security equipment manufacturers, and trade flow data for detector component imports. Bottom-up unit shipment estimates triangulated against top-down addressable market calculations across customs, military, and law enforcement end-user segments.
Forecast inputs span equipment refresh cycle compression at TSA checkpoints, DGFT infrastructure upgrade timelines, and EU AI Act implementation phasing across member states. Segmentation dimensions modeled include product type, technology tier, end-user procurement authority, and application mission profile. CAGRs derived from logistic diffusion curves fitted to adoption patterns in comparable security equipment categories, with cross-validation against customs modernization budget appropriations and defense mobility investment trends.
Macroeconomic conditions sit as an overlay; deviation in freight corridor costs, semiconductor fabrication capacity utilization, or radiological security regulatory stringency would shift the trajectory. Forecasts embed assumptions regarding NRC operator certification timeline stability and CMOS foundry geographic concentration persistence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Smartphone with Periscope Lens Market
Imaging
Vintage Cameras Market
Imaging
Global Backscatter X-Ray Devices Market
Imaging
US Near Infrared Imaging Market
Imaging
Specific Imaging Solution Market
Imaging
Europe Industrial Computed Tomography Market
Imaging
Global Cell Imagers Market
Imaging
Photo Kiosk Market
Imaging
High-Resolution 3D X-Ray Microscopy Market
Imaging
X-Ray Photoelectron Spectroscopy Market
Imaging
Biophotonics Market
Imaging
Industrial Camera Market
Imaging
Ingaas Image Sensor Market
Imaging
Global Microbolometer Market
Imaging
Image Based Barcode Reader Market
Imaging
Infrared Imaging Market