
 IR and Thermal Imaging Systems Market | 2026-2036
IR and Thermal Imaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
IR and Thermal Imaging Systems Market Outlook
Defense procurement agencies is rotating toward commercial-industrial buyers as uncooled sensor costs fall and predictive maintenance adoption spreads across utilities and manufacturing. Teledyne FLIR leverages its vertically integrated sensor-to-system pipeline to dominate commercial channel access. L3Harris Technologies anchors military demand through classified program relationships and cooled sensor specialization. Seek Thermal competes aggressively on price in the prosumer and small-contractor segment with smartphone-integrated form factors.
IR and thermal imaging systems detect infrared radiation emitted by objects and convert thermal energy into visible images using focal plane arrays operating across short-wave, mid-wave, and long-wave spectral bands, with resolution parameters spanning 320x240 to 1280x1024 pixels and thermal sensitivity below 50 millikelvin. These systems serve industrial inspection, security surveillance, medical diagnostics, and firefighting by revealing temperature differentials invisible to standard cameras. Fixed-mounted systems for continuous process monitoring command the highest margin pools in industrial settings, while uncooled sensors in handheld cameras represent the fastest-expanding volume category as silicon wafer-level packaging reduces die costs. Cooled sensors retain technology leadership in long-range military targeting applications where sensitivity and frame rate requirements exclude uncooled alternatives.
FDA regulates medical thermal imaging devices under 21 CFR 892.2050, requiring 510(k) clearance for clinical diagnostic applications and shaping product development roadmaps for healthcare entrants. EPA energy audit protocols and OSHA electrical inspection standards mandate periodic thermal surveys in commercial buildings and industrial facilities, embedding recurring demand for certified imagers. The EU AI Act and CE marking under MDR for diagnostic devices add compliance layers for multinational vendors. Stakeholders must monitor evolving export control classifications under Wassenaar Arrangement updates that could restrict cooled sensor transfers to emerging defense customers.
Market Dynamics
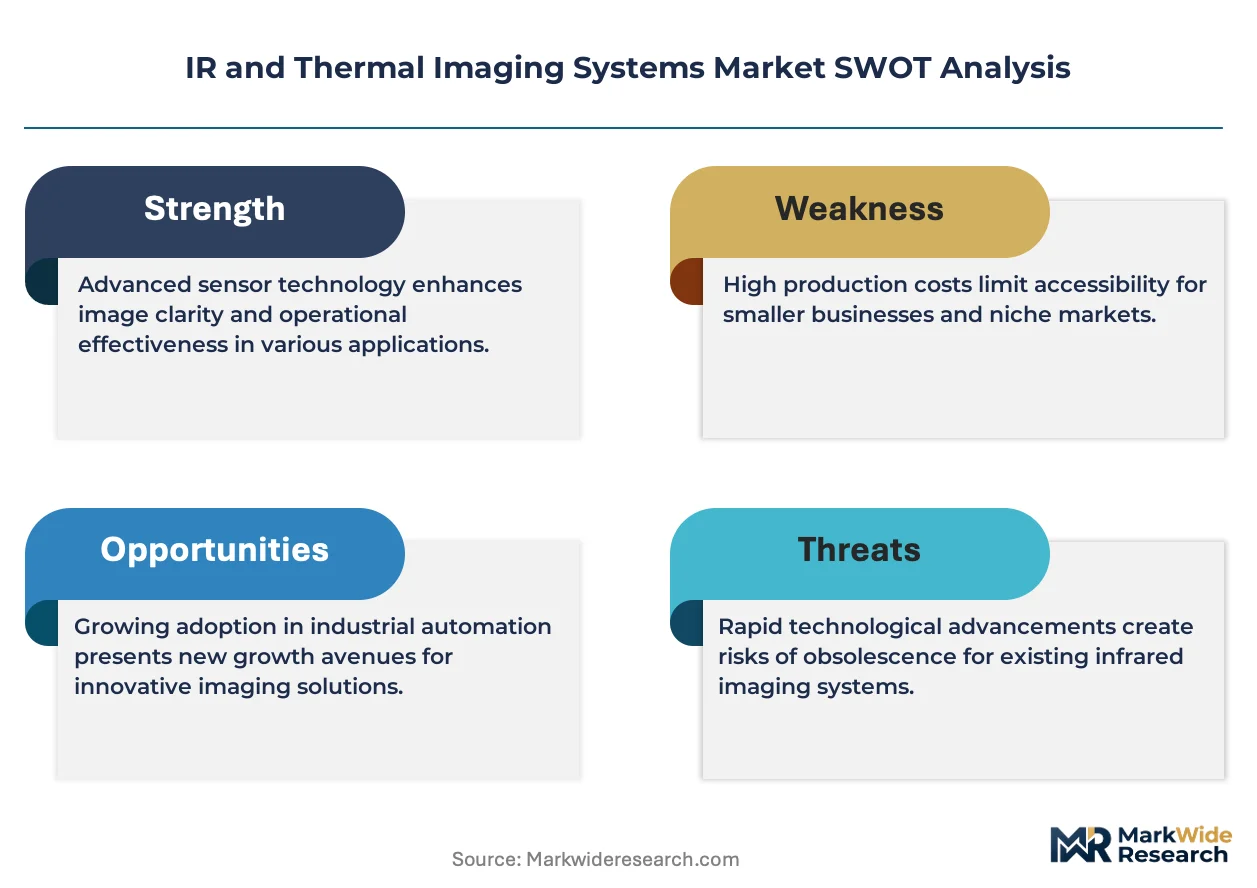
Uncooled sensor wafer-level packaging is compressing die costs below fifty dollars, eroding the historical price floor that confined thermal imaging to defense and high-end industrial buyers. This cost collapse is redrawing competitive boundaries between cooled and uncooled architectures.
Growth Catalysts
- OSHA electrical inspection mandates:Periodic thermal surveys for arc flash prevention create recurring replacement cycles for certified handheld imagers in US commercial facilities.
- Silicon wafer-level packaging:Semiconductor process migration from ceramic to wafer-scale assembly cuts sensor fabrication costs by eliminating wire bonding steps.
- Border surveillance procurement:NATO member states are expanding fixed-mount thermal allocations for perimeter monitoring and night vision operations.
Market Restraints
- Indium antimonide supply concentration:Cooled sensor reliance on this III-V semiconductor creates vulnerability to mining disruptions in China and Russia.
- Export control friction:Wassenaar Arrangement updates restrict cooled focal plane array transfers to emerging defense customers, limiting addressable markets.
- SWIR silicon alternatives:Short-wave infrared sensors using standard CMOS processes threaten traditional InGaAs detector applications in machine vision.
Strategic Opportunities
- EU AI Act compliance services:Diagnostic device vendors can bundle algorithmic transparency documentation with thermal cameras for European healthcare deployment.
- Predictive maintenance penetration:Utilities and manufacturing facilities under FERC reliability standards represent untapped demand for continuous process monitoring systems.
- Smartphone-integrated form factors:USB-C and Lightning thermal camera attachments open prosumer segments previously blocked by dedicated hardware costs.
Industry Challenges
- NETD calibration expertise:Noise-equivalent temperature difference specification and validation requires scarce metrology talent familiar with blackbody reference standards.
- MDR technical documentation:EU medical device regulation demands extensive clinical evidence for thermal diagnostic claims, extending time-to-revenue for healthcare entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IR and Thermal Imaging Systems Market |
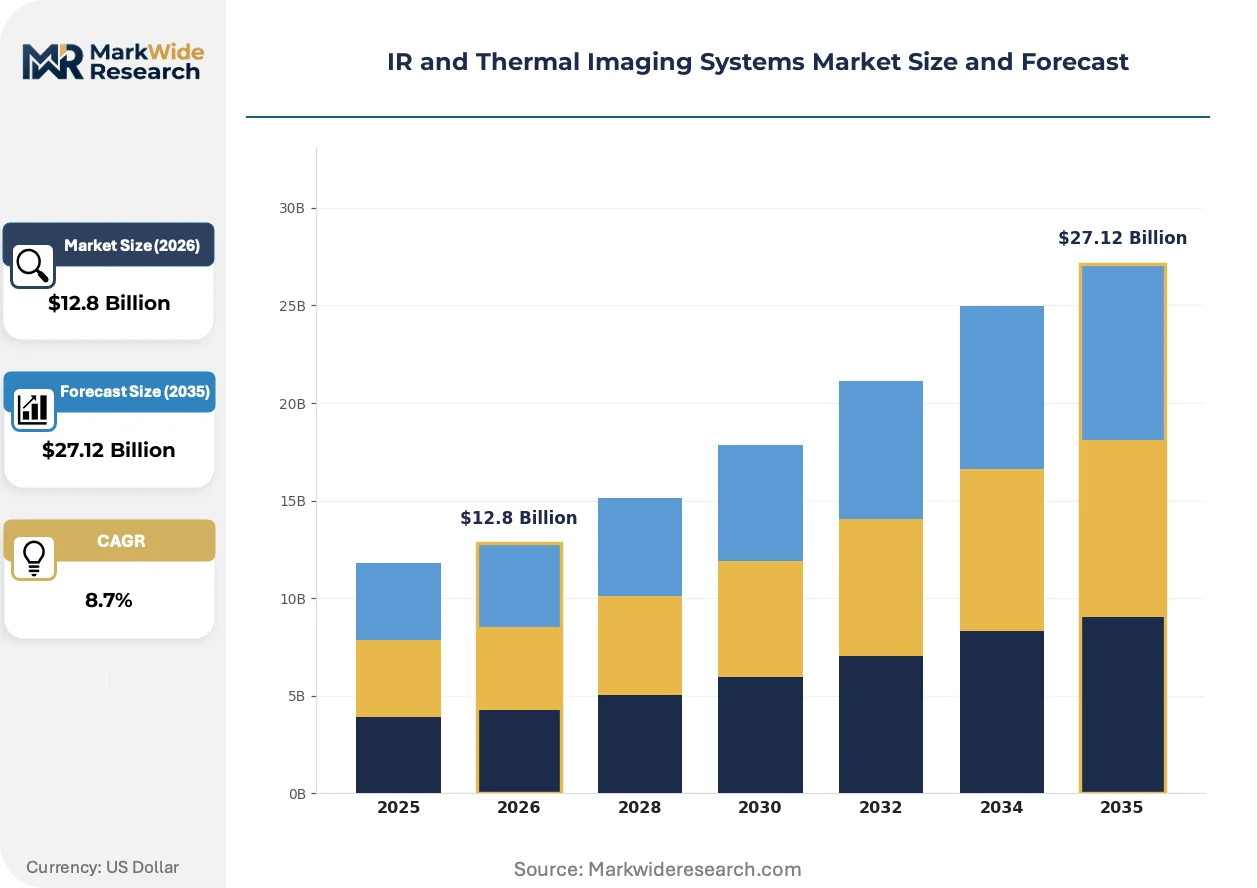
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Cameras, Fixed-Mounted Systems, Scanning Systems, Thermal Sensors End User: Industrial Applications, Military & Defense, Healthcare, Building & Construction Technology: Infrared Thermography, Uncooled Sensors, Cooled Sensors, Hybrid Sensors Application: Predictive Maintenance, Surveillance, Energy Audits, Fire Detection |
| Companies Covered | Teledyne FLIR, L3Harris Technologies, Raytheon Technologies, BAE Systems, Leonardo S.p.A., Fluke Corporation, Opgal Optronic Industries, Leonardo DRS, Seek Thermal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IR and Thermal Imaging Systems Market Strategic Shifts
Sensor architecture convergence and regulatory digitization are compressing product lifecycles while expanding addressable use cases beyond traditional thermal imaging boundaries.
Wafer-level vacuum packaging for uncooled microbolometers is supplanting traditional ceramic vacuum-sealed assemblies in mid-resolution applications. Industrial automation integrators are adopting these sensors for conveyor-mounted quality inspection at frame rates previously requiring cooled alternatives. The technology is supplanting legacy pyrometers in steel and glass manufacturing temperature monitoring, collapsing the price-performance frontier between contact and non-contact measurement.
EPA energy audit protocols now mandate thermal imaging for building envelope leakage detection in commercial property transactions. This regulatory embedding creates recurring certification requirements for HVAC contractors and energy auditors. The mandate is most visible in US metropolitan compliance markets where municipal green building codes reference federal audit standards.
Equipment-as-a-service contracts are displacing capital purchase models for high-end cooled systems in research and defense applications. Leasing structures bundle maintenance, calibration, and upgrade pathways, reducing buyer technical risk. This shift concentrates most visibly in US national laboratory procurement and European research infrastructure grants requiring operational expenditure accounting.
IR and Thermal Imaging Systems Market Segmentation
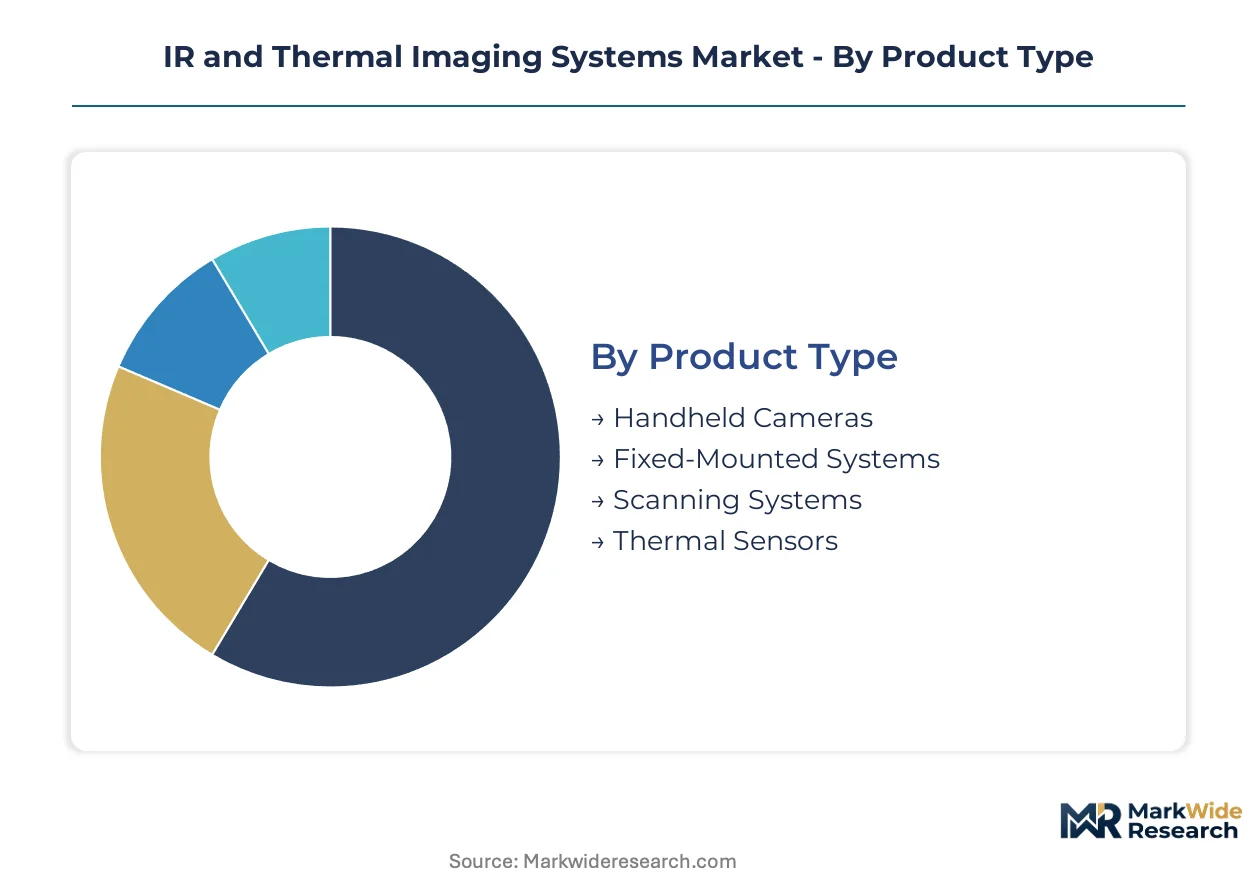
Segmentation in thermal imaging reveals how regulatory mandates, cost trajectories, and end-use requirements fragment demand across incompatible sensor architectures and deployment models. Buyers face distinct compliance pathways depending on product form factor and target application.
Product Type:
FDA 510(k) clearance requirements for clinical diagnostic handhelds create regulatory moats absent in industrial fixed-mount deployments, while OSHA electrical inspection mandates drive replacement cycles specifically for certified portable units.
- Handheld Cameras:Portable units with 320x240 to 640x480 resolution dominate electrical inspection and firefighting applications. OSHA arc flash prevention mandates in US commercial facilities sustain recurring replacement demand for certified models with sub-50 millikelvin sensitivity.
- Fixed-Mounted Systems:Continuous monitoring installations for process control and perimeter surveillance command premium pricing through integration complexity. NATO border surveillance procurement concentrates demand in long-range cooled configurations for night operations.
- Scanning Systems:Conveyor-mounted thermal arrays for automated quality inspection in steel and glass manufacturing.
- Thermal Sensors:Bare die and module-level components for OEM integration into smartphones and industrial automation.
Established volume favors Fixed-Mounted Systems; emerging adoption favors Handheld Cameras.
End User:
Cost tier differentiation separates military-grade cooled sensor programs from commercial uncooled alternatives, with healthcare occupying a mid-tier position defined by FDA diagnostic claims rather than performance specifications alone.
- Industrial Applications:Predictive maintenance and process monitoring drive the largest commercial volume. FERC reliability standards for US utilities embed recurring demand for continuous thermal monitoring of electrical substations and transmission infrastructure.
- Military & Defense:Classified targeting and night vision programs require cooled InSb and MCT sensors with frame rates exceeding uncooled alternatives. Wassenaar Arrangement export controls restrict focal plane array transfers to emerging defense customers.
- Healthcare:Clinical diagnostic applications under FDA 21 CFR 892.2050 require 510(k) clearance and clinical evidence substantiation.
- Building & Construction:EPA energy audit protocols mandate thermal imaging for envelope leakage detection in commercial property transactions.
Margin concentration sits with Military & Defense; volume expansion concentrates in Industrial Applications.
Technology:
Wafer-level packaging economics are collapsing the historical price floor that confined uncooled sensors to high-volume commercial markets, redrawing competitive boundaries against cooled architectures.
- Infrared Thermography:Broad category encompassing passive thermal detection across all spectral bands. Standard measurement protocols in industrial non-destructive testing and building diagnostics.
- Uncooled Sensors:Microbolometer arrays fabricated on silicon wafers with vacuum packaging. Wafer-level assembly cuts fabrication costs below fifty dollars, expanding addressable markets beyond traditional military buyers into prosumer and small-contractor segments.
- Cooled Sensors:InSb and MCT focal plane arrays operating at cryogenic temperatures. Indium antimonide supply concentration in China and Russia creates vulnerability to mining disruptions.
- Hybrid Sensors:Multi-spectral architectures combining thermal and visible imaging for enhanced situational awareness.
Technology leadership remains with Cooled Sensors; steepest expansion trajectory belongs to Uncooled Sensors.
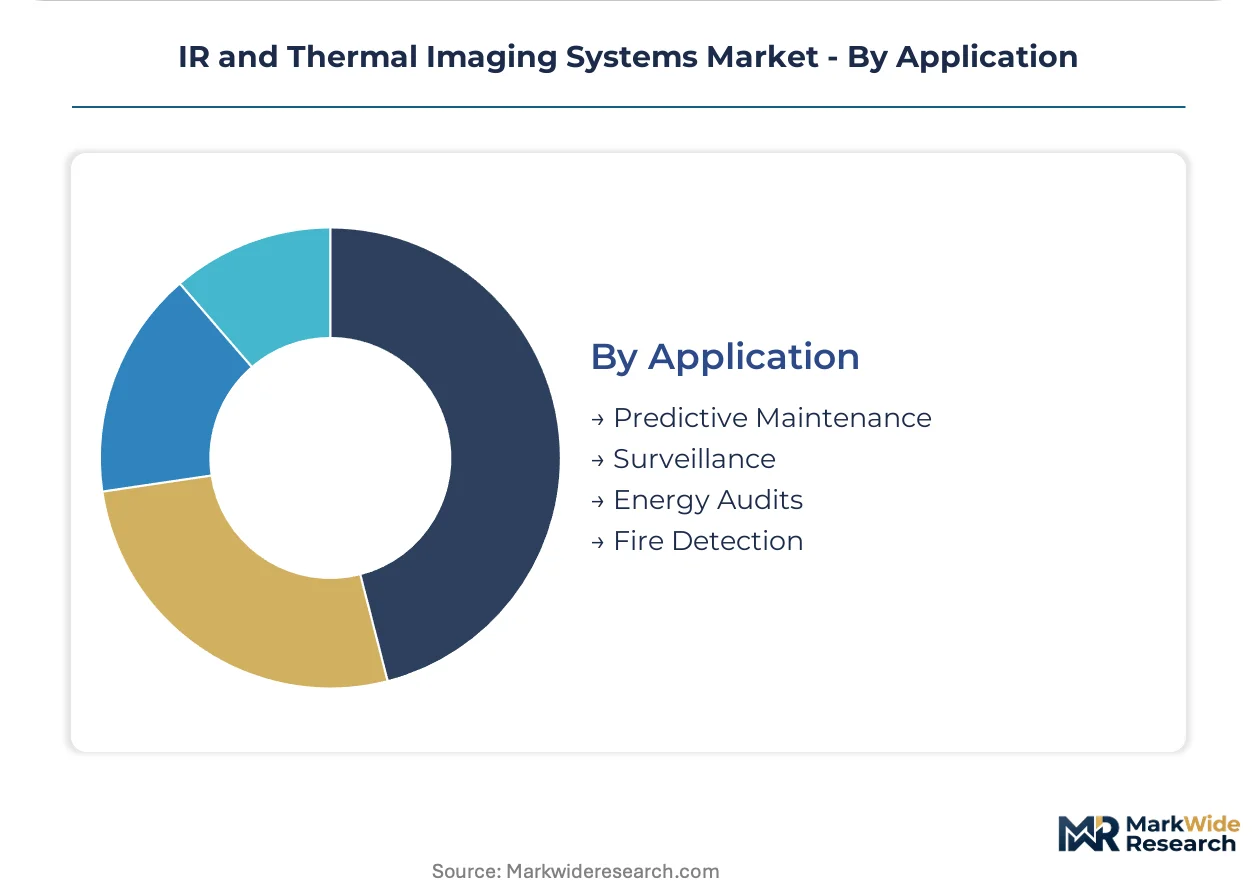
Application:
Customer type fragmentation separates recurring compliance-driven demand from discretionary capital investment, with regulatory embedding determining replacement cycle predictability.
- Predictive Maintenance:Continuous monitoring of rotating equipment and electrical infrastructure. Manufacturing facilities under FERC reliability standards represent untapped demand for process monitoring systems with automated anomaly detection.
- Surveillance:Perimeter monitoring and night vision operations across military and critical infrastructure. NATO member state procurement concentrates in fixed-mount thermal allocations for border security.
- Energy Audits:Building envelope and HVAC system thermal assessment. Municipal green building codes in US metropolitan markets reference federal EPA audit standards.
- Fire Detection:Early warning systems for industrial facilities and wildland-urban interface zones.
Regulatory embedding favors Energy Audits; technology upgrade cycles concentrate in Predictive Maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German thermal sensor exports supply NATO border surveillance programs across Eastern Europe, while US wafer-level packaging innovations feed Asian industrial automation demand. Trade corridors concentrate cooled sensor flows from Western suppliers to defense customers in the Middle East and Asia-Pacific.
United States
Department of Defense modernization programs and domestic manufacturing incentives under federal industrial policy drive procurement concentration. OSHA electrical inspection mandates for arc flash prevention create recurring replacement cycles for certified handheld imagers. Greater Boston hosts precision optics clusters serving national laboratory and defense contractor supply chains.
Germany
Industrial automation integrators adopt wafer-level packaged sensors for conveyor-mounted quality inspection in steel and glass manufacturing. CE marking under MDR for diagnostic devices adds compliance layers for healthcare entrants targeting European markets. Bavaria's precision engineering corridor anchors sensor-to-system integration for automotive predictive maintenance.
China
Domestic manufacturing scale and dual carbon goals accelerate thermal imaging deployment for building energy audits and industrial process monitoring. GB standards and MIIT semiconductor policies shape local sensor fabrication roadmaps. Yangtze River Delta electronics clusters drive volume production of microbolometer arrays for export markets.
Japan
METI industrial efficiency programs embed thermal monitoring into manufacturing facility upgrades. JIS standards certification requirements filter market entry for foreign sensor vendors. Kanto region precision instrument manufacturers supply hybrid sensor architectures combining thermal and visible imaging.
United Kingdom
Border Force procurement for port and airport perimeter surveillance sustains fixed-mount system demand. UK Research and Innovation grants fund cooled sensor development for defense and research applications. Scotland's photonics corridor specializes in focal plane array design for export to European NATO partners.
IR and Thermal Imaging Systems Market Competitive Environment
Player mix skews toward vertically integrated defense contractors and specialized sensor fabricators. The vendor base separates into three tiers: prime contractors managing classified programs, commercial-industrial specialists with sensor-to-system pipelines, and price-focused module suppliers. Dominant competitive moves include strategic partnerships for wafer-level packaging scale and geographic expansion into predictive maintenance service contracts.
Within the defense-prime tier, Teledyne FLIR and L3Harris Technologies exemplify divergent strategic positions. Teledyne FLIR occupies a position spanning sensor fabrication through integrated system delivery. L3Harris Technologies anchors military demand through cooled sensor specialization. Among commercial-industrial specialists, Fluke Corporation represents the calibrated instrumentation archetype serving compliance-driven replacement cycles.
| Leading Market Players |
|---|
| Teledyne FLIR |
| L3Harris Technologies |
| Raytheon Technologies |
| BAE Systems |
| Leonardo S.p.A. |
| Fluke Corporation |
| Opgal Optronic Industries |
| Leonardo DRS |
| Seek Thermal |
| Others |
Value Chain & Pricing Dynamics
Wafer-level packaging scale economies in the Yangtze River Delta and Greater Boston precision optics clusters compress sensor fabrication costs below fifty dollars, redrawing competitive boundaries between cooled and uncooled architectures while collapsing price floors that historically confined thermal imaging to defense and high-end industrial buyers.
Pricing Analysis
Current-generation uncooled microbolometer arrays undercut prior-generation cooled InSb sensors by an order of magnitude, while next-generation SWIR silicon alternatives threaten traditional InGaAs detector price positions. Three-tier pricing structure across premium cooled military configurations, standard industrial fixed-mount systems, and economy prosumer handhelds stratifies by certification grade and thermal sensitivity specification. Cost compression in uncooled tiers intensifies as silicon wafer-level packaging eliminates wire bonding steps. Small contractors and prosumer segments exhibit highest price sensitivity, while classified defense programs demonstrate lowest elasticity due to performance requirements excluding uncooled alternatives.
Supply Chain Analysis
Inventory lead times for indium antimonide substrates stretch eighteen to twenty-four months, constraining cooled sensor output and amplifying spot-market volatility for military-grade focal plane arrays. Supply concentrates in the United States, Germany, and China, with Yangtze River Delta electronics clusters feeding volume microbolometer production and Bavaria's precision engineering corridor anchoring sensor-to-system integration. Raw material dependencies include indium antimonide for cooled arrays, germanium lenses for long-wave transmission, and vacuum packaging ceramics. Single-source vulnerability in Chinese and Russian indium mining creates supply chain risk. Distribution runs through defense prime contractor channels for military applications and industrial automation integrators for commercial deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of NETD calibration expertise familiar with blackbody reference standards concentrates competitive advantage among established metrology houses, creating defensive moats for incumbents with captive validation capabilities while raising entry barriers for new sensor vendors.
For Market Incumbents: Fortify captive metrology capabilities and backward integration into vacuum packaging substrates to defend against wafer-level packaging cost compression eroding traditional ceramic assembly margins. Anchor certification investment in FDA 510(k) pathways and EU MDR technical documentation to lock out unqualified entrants from healthcare diagnostic claims. For New Entrants and Emerging Players: Anchor in smartphone-integrated form factors for prosumer electrical inspection segments where OSHA arc flash prevention mandates sustain replacement demand but dedicated hardware costs previously blocked participation. Target municipal green building code compliance markets in US metropolitan areas where EPA energy audit protocols embed recurring thermal imaging requirements for HVAC contractors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sensor fabricators with wafer-level packaging scale and established defense prime contractor relationships over pure-play system integrators lacking upstream control. Long-term viability hinges on dual-use technology transfer flexibility under evolving Wassenaar Arrangement classifications. Monitor cooled focal plane array export license approval velocity as inflection indicator for defense revenue predictability.| Strategic Initiative | Industry Significance |
|---|---|
| Wafer-Level Packaging Scale-Up | Eliminates wire bonding costs and expands addressable markets beyond traditional military buyers. |
| Defense Prime Contractor Partnership | Secures classified program access and insulates against Wassenaar Arrangement export friction. |
| FDA 510(k) Clearance Pathway | Creates regulatory moats for clinical diagnostic handhelds in healthcare applications. |
| Predictive Maintenance Service Contracts | Displaces capital purchase models with recurring revenue under FERC reliability standards. |
| EU MDR Technical Documentation Investment | Enables European healthcare market entry through algorithmic transparency bundling. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of defense procurement databases, SEC 10-K filings, EPA regulatory dockets, and Wassenaar Arrangement control lists. Interviews with thermal sensor engineering directors, defense procurement officers, industrial automation integrators, and biomedical device regulatory consultants inform demand-side validation. Bottom-up unit shipment estimates triangulate against top-down defense budget allocation analysis and industrial capital expenditure surveys.
Segmentation dimensions modeled span sensor technology architecture, product form factor, end-use industry vertical, and regional regulatory cluster across the projection horizon. CAGRs derive from shipment volume trajectories and average selling price erosion curves calibrated to wafer-level packaging cost reduction schedules. Forecast inputs include NATO border surveillance procurement pipelines, FERC reliability standard enforcement intensity, and municipal green building code adoption rates.
Material uncertainties — indium supply disruption, Wassenaar Arrangement reclassification, and SWIR silicon substitution acceleration — sit outside the modeled envelope and could revise trajectory assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Industrial Camera Market
Imaging
Wearable IP Camera Market
Imaging
Holotomographic Imaging Market
Imaging
Wide Field Imaging Devices Market
Imaging
Global Image Processing Systems Market
Imaging
Brazil Surveillance Analog Camera Market
Imaging
Industrial Computed Tomography Market
Imaging
Medical X-Ray Detectors Market
Imaging
Global in Ceiling Camera Market
Imaging
Global Broadcast Cameras Market
Imaging
Mobile Imaging Services Market
Imaging
Global 4K Camera Market
Imaging
Micro-Magnetic Resonance Imaging Market
Imaging
Europe Industrial Computed Tomography Market
Imaging
Global CMOS Image Sensors Market
Imaging
Handheld Retinal Scanners Market