
 Sedimentation and Centrifugation Market | 2026-2036
Sedimentation and Centrifugation Market Size, Share, and Industry Trends Forecast 2026-2036
Sedimentation and Centrifugation Market Analytics
Asset-light leasing and performance-based service contracts is reshaping competitive entry in sedimentation and centrifugation equipment, lowering capital barriers for mid-sized water treatment operators. Alfa Laval AB leverages its aftermarket service network to sustain recurring revenue streams across European industrial facilities. Thermo Fisher Scientific dominates laboratory-scale centrifugation through precision speed control and biocontainment engineering. GEA Group AG anchors large-scale decanter supply to dairy and brewing processors with customized bowl geometries.
Sedimentation and centrifugation encompasses mechanical separation processes that exploit density differentials to isolate solids from liquids or immiscible liquid phases, with centrifugal systems achieving gravitational forces exceeding 20,000 g for particle sizes below one micron. Decanters command the largest installed base in wastewater and minerals processing due to continuous throughput and automated discharge, while batch centrifuges retain premium positioning in pharmaceutical crystallization where cGMP validation and containment integrity justify higher capital outlay. Hydrocyclones gain traction in oilfield water management and mining tailings recovery where footprint constraints and absence of moving parts reduce operational expenditure.
EPA effluent limitation guidelines and EU Urban Wastewater Treatment Directive revisions mandate tertiary solids removal, directly stimulating decanter and centrifuge replacements across municipal plants. FDA cGMP and EMA Annex 1 sterility requirements compel pharmaceutical end users to validate centrifuge cleanability and bioburden control, favoring suppliers with documented qualification protocols. Stakeholders must monitor how evolving PFAS destruction regulations redirect capital from conventional separation toward integrated treatment trains that combine sedimentation with advanced oxidation or thermal destruction stages.
Market Dynamics
EPA effluent limitation guidelines and EU Urban Wastewater Treatment Directive revisions are forcing simultaneous replacement cycles across municipal infrastructure and industrial process lines, compressing equipment procurement timelines while elevating technical specifications for solids removal efficiency.
Growth Catalysts
- Pharmaceutical biologics expansion:FDA cGMP and EMA Annex 1 sterility mandates compel validated centrifuge cleanability protocols, driving premium equipment procurement for monoclonal antibody purification workflows.
- German precision engineering clusters:Chemical processing density and automotive coating operations sustain concentrated demand for decanter centrifuges with customized bowl geometries and automated discharge systems.
- PFAS regulatory pressure:Emerging destruction requirements for per- and polyfluoroalkyl substances redirect capital toward integrated treatment trains combining sedimentation with advanced oxidation stages.
Market Restraints
- Stainless steel and specialty alloy volatility:Decanter bowl and scroll component fabrication depends on austenitic grades subject to nickel and molybdenum price swings, compressing OEM margins on fixed-price contracts.
- High-speed centrifuge bearing supply concentration:Precision ceramic hybrid bearings for ultracentrifugation applications source from limited European and Japanese suppliers, creating vulnerability to export control disruptions.
- Sub-10-micron particle separation ceiling:Conventional centrifugal force limits in standard decanter configurations face displacement from membrane filtration and dissolved air flotation in tertiary wastewater polishing.
Strategic Opportunities
- India municipal water infrastructure:Central government AMRUT scheme allocations for sewage treatment plant upgrades create procurement windows for continuous-flow decanter systems in tier-2 urban centers.
- Convergence of IoT condition monitoring with predictive maintenance:Vibration analysis and oil particle counting integration enables service contract transitions from time-based to reliability-centered frameworks.
- Brewing and dairy processor sustainability targets:Scope 3 emission reduction commitments accelerate interest for energy-recovery decanter configurations with optimized differential speed control.
Industry Challenges
- Field service technician scarcity:Specialized alignment and balancing expertise for high-speed centrifuge rotor assemblies concentrates with aging workforces in Midwest US and Ruhr industrial regions.
- Legacy DCS integration complexity:Brownfield municipal plants with proprietary distributed control architectures face protocol translation barriers when connecting modern centrifuge PLCs to centralized SCADA networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sedimentation and Centrifugation Market |
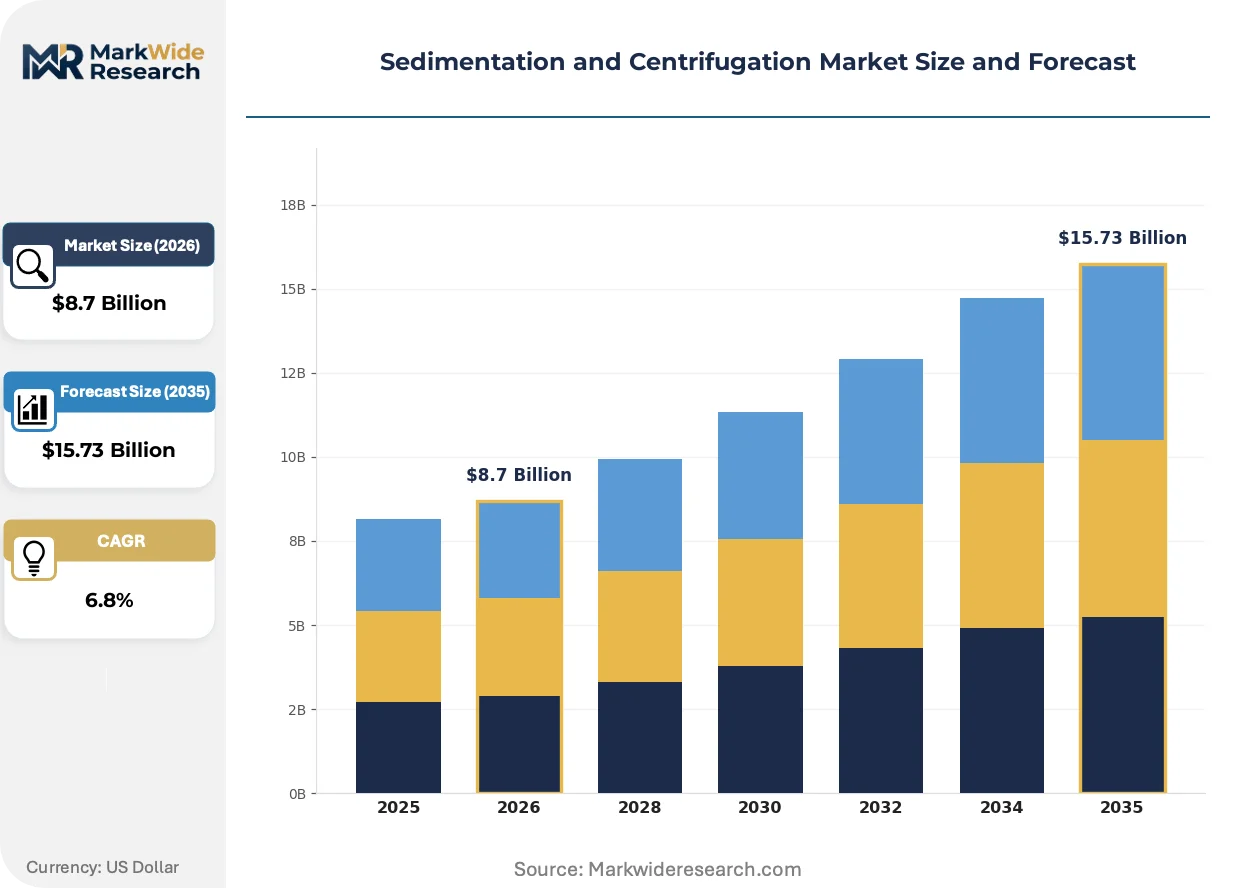
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Decanters, Batch Centrifuges, Continuous Centrifuges, Sedimentation Tanks Application: Wastewater Treatment, Chemical Processing, Food & Beverage Production, Pharmaceuticals End User: Industrial Facilities, Research Laboratories, Water Treatment Plants, Oil & Gas Sector Technology: Centrifugal Force, Gravity Separation, Hydrocyclones, Filtration |
| Companies Covered | Flottweg SE, Thermo Fisher Scientific, Alfa Laval AB, Rousselet Robatel, HAUS Centrifuge Technologies, Andritz AG, Evoqua Water Technologies LLC, Eppendorf AG, GEA Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sedimentation and Centrifugation Market Evolving Landscape
Equipment architectures are fragmenting between continuous-duty industrial workhorses and modular, containerized units for remote deployment, while digital layer integration redefines aftermarket value capture beyond hardware margins.
Decanter centrifuge technology is hybridizing sedimentation mechanics with real-time torque and differential speed automation, enabling adaptive bowl pool depth adjustment during fluctuating feed solids loading. Mining tailings and oilfield water management operators in Alberta and the Permian Basin are deploying these configurations for variable-rate processing without manual operator intervention. This convergence is compressing the performance gap between standard decanters and traditional batch centrifuges in applications previously reserved for discontinuous operation.
REACH substance restriction proposals for per- and polyfluoroalkyl substances in industrial process equipment are compelling seal and gasket material reformulation across European-manufactured centrifuge lines. Component suppliers are qualifying hydrogenated nitrile and perfluoroelastomer alternatives to maintain chemical resistance ratings without restricted fluoropolymer content. Pharmaceutical and fine chemical end users in Germany and Switzerland face accelerated validation timelines to document extractables profiles for revised elastomer specifications ahead of enforcement windows.
Asset-light leasing structures are displacing outright purchase for mid-capacity municipal operators facing constrained capital budgets and uncertain future flow rate requirements. European water utilities in the Netherlands and Denmark are piloting performance-based contracts where equipment vendors retain ownership and charge per dry ton of solids recovered. This reconfiguration shifts technical risk toward OEMs while compressing traditional distributor margins and accelerating direct manufacturer-to-operator relationship development.
Sedimentation and Centrifugation Market Segmentation
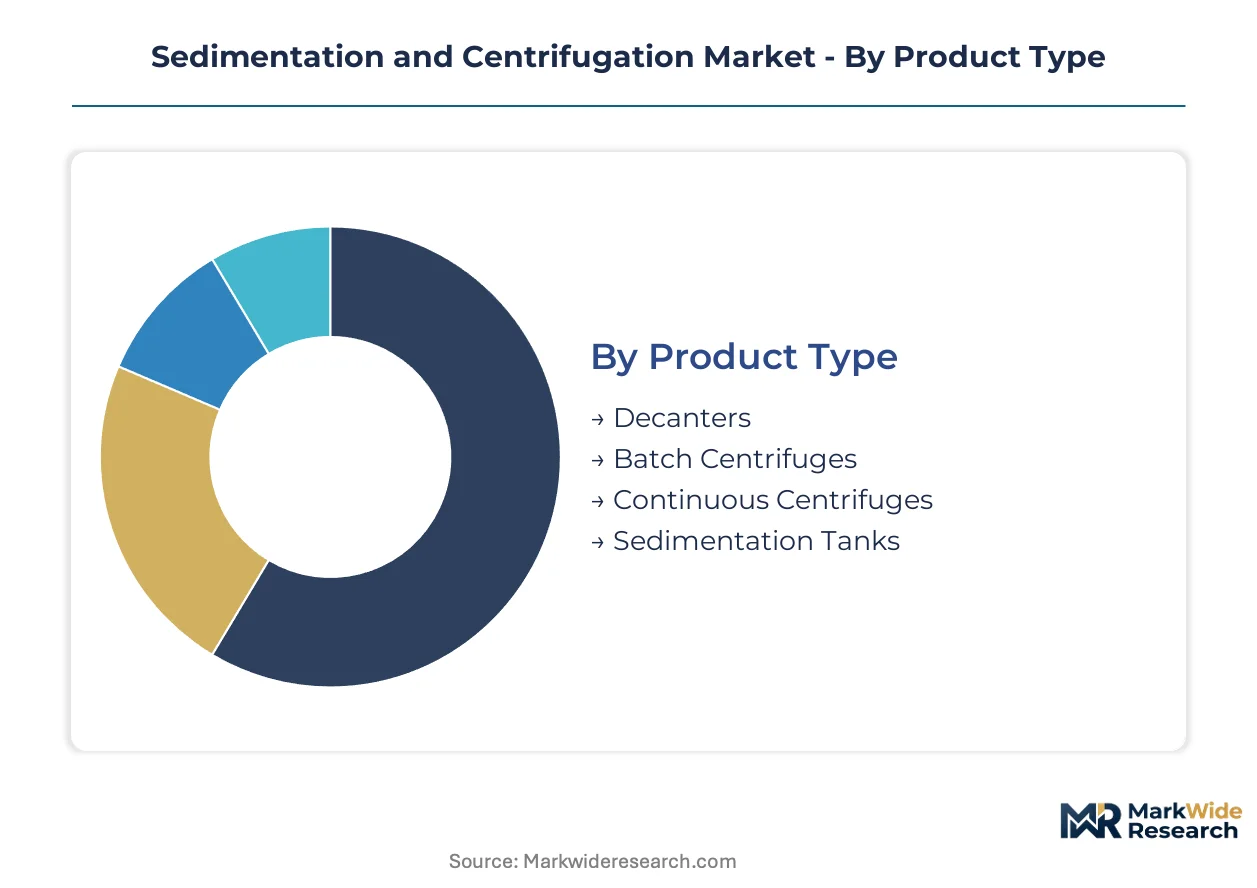
Equipment replacement cycles and validation requirements vary dramatically across sedimentation and centrifugation segments. Understanding these temporal patterns reveals where capital concentrates versus where recurring revenue opportunities emerge for suppliers.
Product Type:
Decanters operate on 15-20 year municipal infrastructure cycles, while batch centrifuges face 5-7 year pharmaceutical validation-driven refresh timelines.
- Decanters:Continuous-feed horizontal bowl systems with helical scroll discharge mechanisms process slurries at rates exceeding 100 cubic meters hourly. German chemical processors and Alberta oil sands operators specify hardened scrolls and tungsten carbide tiles for abrasive tailings duty.
- Batch Centrifuges:Discontinuous vertical basket or tubular bowl configurations achieve gravitational forces above 20,000 g for biologics isolation. FDA cGMP and EMA Annex 1 sterility mandates force Swiss and German pharmaceutical manufacturers into documented cleanability validation protocols.
- Continuous Centrifuges:Disc stack separators with self-cleaning bowl ejectors handle dairy clarification and edible oil refining at throughputs matching decanter economics.
- Sedimentation Tanks:Gravity-driven clarifiers and thickeners with rake mechanisms serve primary wastewater settling where energy constraints favor passive separation.
Decanters dominate installed base. Batch centrifuges are where expansion concentrates for premium-margin suppliers.
Application:
Cost tier stratification separates commodity municipal procurement from validated pharmaceutical systems commanding 4-5x capital multiples.
- Wastewater Treatment:Tertiary solids removal under EPA effluent guidelines and EU Urban Wastewater Treatment Directive revisions compels decanter upgrades across US Midwest and Netherlands municipal plants.
- Chemical Processing:Aggressive media handling in German Ruhr Valley and Louisiana Gulf Coast petrochemical corridors demands duplex stainless bowls and ceramic-lined scrolls.
- Food & Beverage Production:Sanitary disc stack separators with CIP capability recover cream and clarify beer in Denmark and Czech brewing operations.
- Pharmaceuticals:Containment-integrity ultracentrifuges with biocontainment engineering isolate viral vectors and monoclonal antibodies under FDA and EMA scrutiny.
Wastewater treatment absorbs volume. Pharmaceuticals command margin.
End User:
Customer type determines service intensity, with research laboratories demanding rapid response and water treatment plants prioritizing parts availability over speed.
- Industrial Facilities:Mining tailings and automotive coating operations in Germany and Michigan run decanters on 24/7 schedules with predictive maintenance contracts.
- Research Laboratories:Thermo Fisher Scientific and Beckman Coulter ultracentrifuges in Boston and Cambridge biotech clusters require sub-4-hour service response for high-value sample protection.
- Water Treatment Plants:Netherlands and Denmark utilities pilot performance-based solids-recovery contracts shifting ownership risk to OEMs.
- Oil & Gas Sector:Permian Basin produced water management deploys containerized hydrocyclone-decanter trains for variable-rate field processing.
Industrial facilities anchor replacement parts revenue. Research laboratories drive steepest expansion trajectory for service contracts.
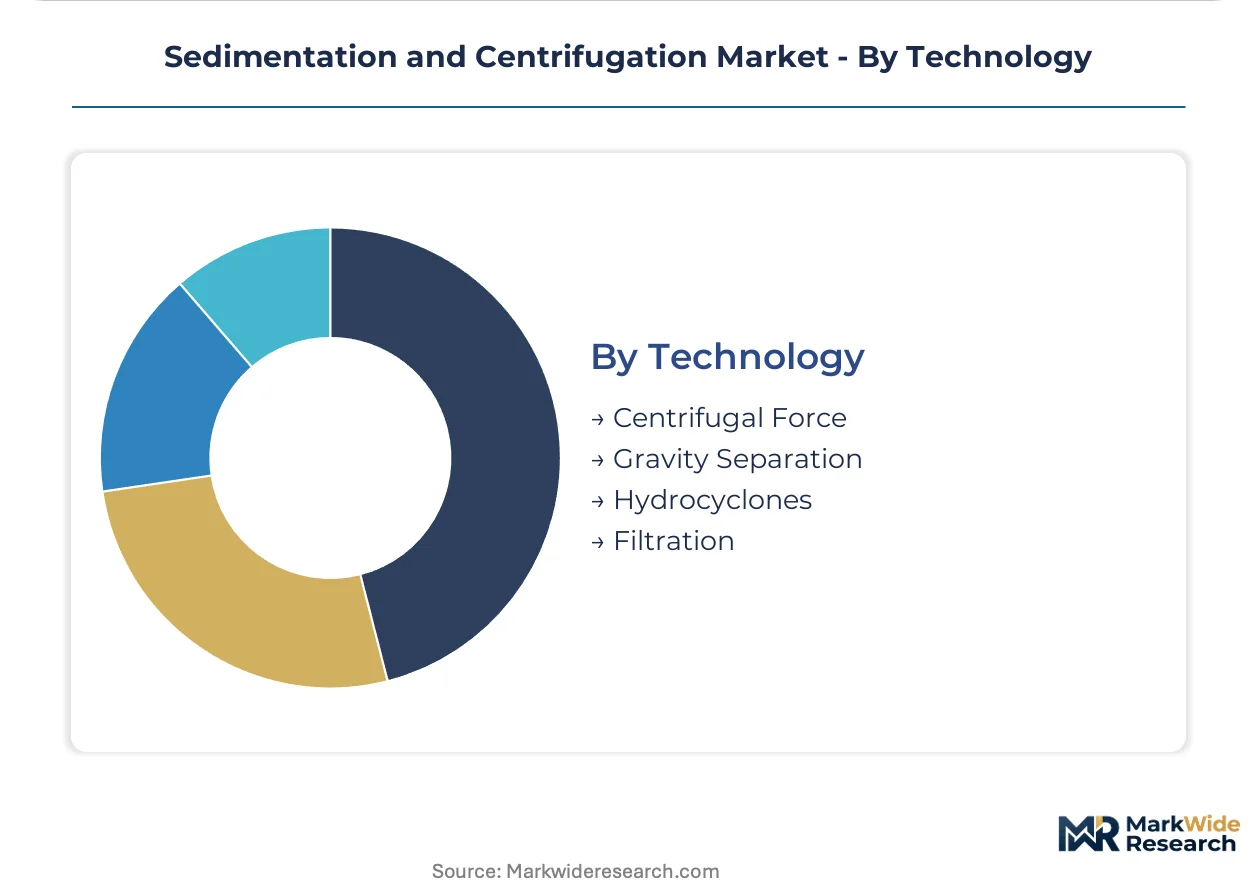
Technology:
Supply concentration for ceramic hybrid bearings and precision drive systems favors centrifugal force applications over passive gravity methods.
- Centrifugal Force:Rotating bowl systems generating 1,000-20,000 g separate sub-micron particles in pharmaceutical and fine chemical workflows.
- Gravity Separation:Clarifier basins and lamella settlers serve primary municipal treatment where land availability permits hydraulic retention times exceeding 4 hours.
- Hydrocyclones:Static cone separators without moving parts reduce OPEX in Alberta oilfield water loops and Chilean copper tailings recovery.
- Filtration:Membrane and media systems displace centrifugation below 10-micron cut points in tertiary wastewater polishing applications.
Centrifugal force commands technology investment. Hydrocyclones gain share fastest in remote and unmanned installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA effluent limitation guidelines and EU Urban Wastewater Treatment Directive revisions are compressing procurement timelines across municipal infrastructure while elevating technical specifications for solids removal efficiency.
Germany
Chemical processing density in the Ruhr Valley and automotive coating operations sustain concentrated demand for decanter centrifuges with customized bowl geometries. REACH substance restriction proposals for per- and polyfluoroalkyl substances compel seal and gasket material reformulation across European-manufactured equipment lines. Precision engineering clusters in Baden-Württemberg validate centrifuge cleanability protocols for pharmaceutical applications under EMA Annex 1 scrutiny.
United States
Midwest municipal plants face simultaneous replacement cycles under EPA effluent limitation guidelines for tertiary solids removal. PFAS destruction requirements redirect capital toward integrated treatment trains combining sedimentation with advanced oxidation stages. Permian Basin produced water management deploys containerized hydrocyclone-decanter trains for variable-rate field processing.
India
Central government AMRUT scheme allocations for sewage treatment plant upgrades create procurement windows for continuous-flow decanter systems. Municipal water infrastructure expansion concentrates in tier-2 urban centers across Maharashtra and Gujarat. Field service technician scarcity complicates high-speed centrifuge rotor assembly maintenance in emerging industrial corridors.
Netherlands
Water utilities pilot performance-based contracts where equipment vendors retain ownership and charge per dry ton of solids recovered. EU Urban Wastewater Treatment Directive revisions mandate tertiary solids removal across Randstad municipal networks. Dairy clarification operations deploy disc stack separators with CIP capability throughout Brabant processing facilities.
China
Dual carbon goals accelerate interest for energy-recovery decanter configurations with optimized differential speed control in Yangtze River Delta chemical processing zones. Mining tailings recovery operations in Sichuan-Chongqing deploy hydrocyclones where footprint constraints and absence of moving parts reduce operational expenditure. National environmental standards tighten discharge requirements for industrial wastewater treatment infrastructure.
Sedimentation and Centrifugation Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement environments. Equipment vendors with aftermarket service networks sustain recurring revenue streams through predictive maintenance contracts. Three archetypes dominate: precision-engineering specialists with documented qualification protocols, scale-driven fabricators of continuous-duty industrial workhorses, and modular-system integrators for remote deployment. M&A activity concentrates on technology licensing arrangements and geographic expansion into municipal water infrastructure markets.
Among European precision-engineering specialists, Flottweg SE and GEA Group AG exemplify the archetype of customized bowl geometry providers for abrasive duty applications. Thermo Fisher Scientific occupies a position within laboratory-scale centrifugation through precision speed control engineering. Alfa Laval AB anchors the aftermarket service network tier, sustaining recurring revenue across industrial facilities through performance-based contracting structures.
| Leading Market Players |
|---|
| Flottweg SE |
| Thermo Fisher Scientific |
| Alfa Laval AB |
| Rousselet Robatel |
| HAUS Centrifuge Technologies |
| Andritz AG |
| Evoqua Water Technologies LLC |
| Eppendorf AG |
| GEA Group AG |
| Others |
Value Network & Pricing Analysis
Nickel and molybdenum price volatility in austenitic stainless grades compresses OEM margins on fixed-price contracts while simultaneously widening spreads between premium decanter configurations and standard municipal equipment. This commodity exposure forces tiered pricing responses that track alloy surcharge mechanisms and regional fabrication capacity.
Pricing Analysis
Certification level (FDA-grade, CE-marked, standard industrial) creates the primary spread between pharmaceutical ultracentrifuges and municipal decanters. Three-tier pricing structure across premium, standard, and economy levels reflects validation documentation depth, with biocontainment engineering adding substantial premiums. Pricing pressure stems from stainless steel volatility squeezing fixed-contract profitability. Municipal water treatment operators exhibit highest price sensitivity, while German pharmaceutical manufacturers accept premium positioning for documented EMA Annex 1 compliance.
Supply Chain Analysis
Extended payment terms from European water utilities now stretch to 180 days, forcing OEMs to deploy supply-chain finance facilities with component vendors. Precision ceramic hybrid bearings for high-speed applications draw from limited Japanese and European suppliers, creating single-source vulnerability. Tungsten carbide tiles and duplex stainless scrolls rest on German and Austrian specialty foundries. Distribution runs through direct manufacturer-to-operator channels for large decanters, with distributor networks retaining laboratory-scale equipment flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sedimentation and centrifugation market sits at a regulatory inflection where PFAS destruction mandates and EPA effluent revisions are compressing replacement cycles. This disruption favors suppliers with integrated treatment train capabilities over pure-play separation equipment vendors.
For Market Incumbents: Insulate aftermarket revenue streams by embedding IoT condition monitoring into existing installed bases, converting time-based service contracts to reliability-centered frameworks. Deepen captive supply of precision ceramic hybrid bearings to offset Japanese supplier concentration risk. Prioritize validation protocol investments for EMA Annex 1 pharmaceutical compliance as the defensive moat against modular-system integrators.
For New Entrants and Emerging Players: Tier-2 urban centers in Maharashtra and Gujarat under India's AMRUT scheme present procurement windows where established European OEMs lack localized service density. Containerized hydrocyclone-decanter trains for Permian Basin produced water management offer white-space entry with lower capital intensity than continuous-duty municipal decanters. Pursue performance-based contracting structures that shift ownership risk and differentiate from incumbent capital-sale models.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision-engineering specialists with documented qualification protocols over scale-driven fabricators. Long-term viability hinges on service revenue attachment rates rather than equipment shipment volumes. Monitor REACH substance restriction enforcement timelines as the signal for accelerated seal and gasket material validation spending across European pharmaceutical installations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Bearing Supply | Mitigates ceramic hybrid sourcing concentration from limited Japanese and European vendors. |
| Performance-Based Contracting Transition | Shifts technical risk to OEMs while capturing recurring revenue per dry ton of solids recovered. |
| IoT Condition Monitoring Platform Deployment | Enables predictive maintenance contracts and compresses distributor margins in aftermarket capture. |
| Containerized System Development for Remote Deployment | Addresses Permian Basin and Alberta oilfield water management footprint constraints. |
| Seal Material Reformulation for REACH Compliance | Qualifies hydrogenated nitrile alternatives ahead of per- and polyfluoroalkyl substance restrictions. |
Research Methodology
A spread of perspectives from plant engineers at municipal water treatment facilities, procurement leads at pharmaceutical manufacturers, aftermarket service heads at industrial OEMs, and regulatory affairs specialists at equipment vendors converged on the working assumptions. Primary interview findings were cross-checked against EPA effluent limitation guidelines, EU Urban Wastewater Treatment Directive documentation, SEC filings from listed equipment manufacturers, and trade flow data for stainless steel and specialty alloy inputs. Bottom-up equipment shipment tallies and top-down industrial capital expenditure estimates were reconciled to establish baseline market sizing.
Demand-supply balance modeling across the analysis window segmented volume and value projections by equipment type, application intensity, end-user service requirements, and regional regulatory enforcement patterns. Pharmaceutical validation timelines, municipal infrastructure replacement cycles, and industrial sustainability target adoption curves fed into CAGR derivation through iterative scenario testing. Mining tailings recovery rates and brewing energy-recovery decanter interest provided industry-specific demand elasticity inputs.
Practitioners should monitor nickel and molybdenum price trajectories, REACH enforcement windows for fluoropolymer restrictions, and AMRUT scheme disbursement pacing for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
United Kingdom Water Treatment Chemicals Market
Water & Sludge Treatment
Global Wet Waste Management Market
Water & Sludge Treatment
Salt Water Softeners Market
Water & Sludge Treatment
Water Treatment Polymers Market
Water & Sludge Treatment
North America Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
North America Industrial Water Treatment Market
Water & Sludge Treatment
India Water and Wastewater Treatment (WWT) Technology Market
Water & Sludge Treatment
North America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Enzymes for Water Treatment Market
Water & Sludge Treatment
Anionic Flocculants Market
Water & Sludge Treatment
Saudi Arabia Industrial Hazardous Waste Management Market
Water & Sludge Treatment
Africa Water Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Water Treatment Chemicals Market
Water & Sludge Treatment
Sludge Heater Market
Water & Sludge Treatment
Global Electrodeionization Market
Water & Sludge Treatment
India Water Treatment Market