
 India Polyacrylamide Copolymer Market | 2026-2036
India Polyacrylamide Copolymer Market Size, Share, and Industry Trends Forecast 2026-2036
India Polyacrylamide Copolymer Market Outlook
Buyer concentration among municipal wastewater utilities is hardening as state-level Jal Jeevan Mission implementation consolidates procurement pools. SNF Floerger leverages its Indian manufacturing footprint to anchor supply contracts for metropolitan treatment plants. BASF SE competes through specialized emulsion grades tailored to high-salinity industrial effluent. Black Rose Industries dominates regional distribution networks across western India.
Polyacrylamide copolymers are high-molecular-weight water-soluble polymers synthesized through free-radical polymerization of acrylamide with charged comonomers such as acrylic acid or diallyldimethylammonium chloride, engineered to molecular weights exceeding ten million Daltons for efficient flocculation and rheology modification. The powder form sustains the largest volume share due to extended shelf stability and lower freight costs for inland distribution. Emulsion grades are capturing faster growth in oil recovery applications where rapid hydration kinetics offset higher unit costs. Water treatment applications anchor value generation, while mining tailings management represents an emerging margin pool as environmental compliance tightens.
BIS mandates residual acrylamide monomer limits below 0.05 percent for potable water contact grades, forcing reformulation investments across domestic blenders. CDSCO oversight of polyacrylamide in pharmaceutical excipient applications creates additional certification barriers for cross-sector suppliers. The CEA's effluent discharge norms for thermal power plants are expanding polymer demand for flue gas desulfurization wastewater. Stakeholders must monitor state-level Jal Shakti Department tender aggregation and the pace of zero-liquid-discharge mandates in textile clusters to calibrate capacity additions.
Market Dynamics
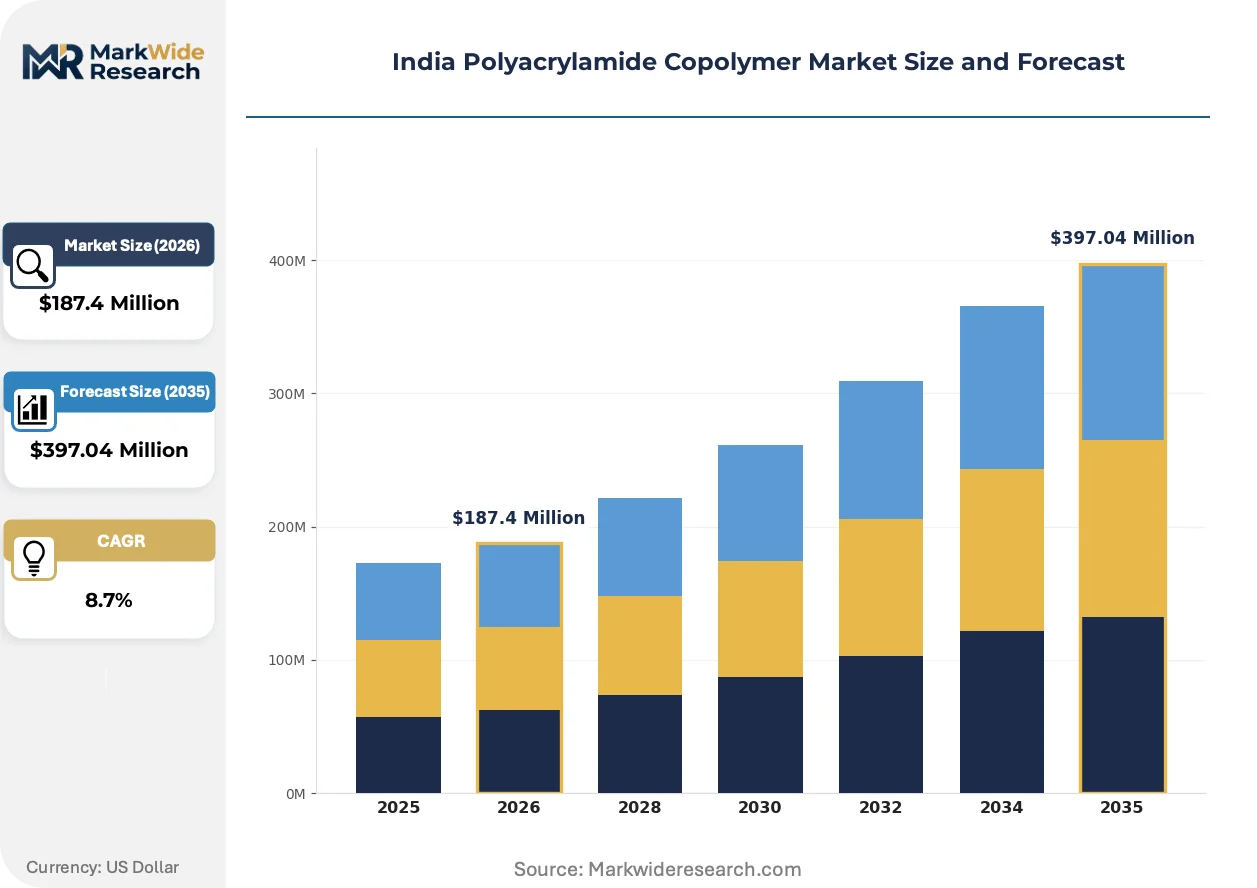
Jal Jeevan Mission procurement aggregation is consolidating municipal wastewater utility buyers into state-level tender pools, compressing supplier margins while expanding volume commitments for polyacrylamide copolymer manufacturers serving India's water treatment infrastructure.
Growth Catalysts
- CEA effluent norms:Thermal power plant flue gas desulfurization wastewater mandates are expanding polymer dosing requirements for heavy metal precipitation and sludge conditioning.
- Zero-liquid-discharge clusters:Textile processing hubs in Tamil Nadu and Rajasthan are retrofitting evaporator systems with high-charge cationic polymers for color removal and COD reduction.
- Enhanced oil recovery:ONGC and private operators are injecting hydrophobically modified polyacrylamides into mature Bombay High reservoirs to improve sweep efficiency.
Market Restraints
- Acrylonitrile feedstock volatility:Domestic acrylonitrile supply depends on Reliance Industries' petrochemical output, exposing blenders to import parity pricing swings.
- BIS monomer thresholds:Residual acrylamide limits below 0.05 percent for potable water grades force capital-intensive purification retrofits at domestic synthesis plants.
- Natural flocculant substitution:Chitosan and starch-based alternatives are capturing niche applications in food-processing wastewater where synthetic polymer discharge faces scrutiny.
Strategic Opportunities
- Jharkhand mining belt:Coal washeries and iron ore beneficiation plants lack qualified polymer suppliers, creating first-mover potential for technical service partnerships.
- Pharmaceutical excipient grade:CDSCO registration pathways for tablet binder applications open premium pricing corridors separate from industrial commoditization.
- Drone-based polymer dosing:Tailings dam remediation in Goa and Karnataka is testing remote-controlled application systems for inaccessible mine voids.
Industry Challenges
- Anionic-cationic blending expertise:Municipal operators lack trained chemists to optimize charge density for variable influent turbidity, causing overdosing and contract penalties.
- Emulsion storage infrastructure:Bulk liquid polymer requires temperature-controlled tankage that small utilities in Bihar and Uttar Pradesh cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Polyacrylamide Copolymer Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Emulsion, Liquid, Granular Application: Water Treatment, Oil Recovery, Mining, Paper Making End User: Agriculture, Wastewater Treatment, Textile, Construction Form: Solid, Aqueous Solution, Slurry, Gel |
| Companies Covered | Ashland Global Holdings Inc., Nippon Shokubai Co., Ltd., BASF SE, China National Petroleum Corporation, Shandong Polymer Bio-chemicals Co., Ltd., SNF Floerger, Solvay SA, Black Rose Industries, Kemira Oyj, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Polyacrylamide Copolymer Market Strategic Shifts
Digitization of dosing control systems and tightening purity mandates are forcing simultaneous investment in automation hardware and monomer removal chemistry across India's polyacrylamide value chain.
Dry polymer dispersing equipment is modularizing field deployment for remote mining and oilfield locations. Caterers to ONGC's Assam and Rajasthan assets are specifying containerized make-down systems that reduce civil works and commissioning timelines. This architecture is compressing the addressable market for permanent installed plants in frontier basins.
BIS certification timelines for drinking water contact grades have extended from eighteen to twenty-four months following 2023 purity threshold revisions. Domestic blenders are responding by captive laboratory investments to accelerate in-house monomer testing rather than queuing at third-party facilities. Gujarat-based manufacturers face the tightest compliance burdens given their concentration of potable water-grade output.
State Jal Shakti Departments are aggregating polymer procurement into two-year framework agreements with pre-qualified suppliers. Maharashtra and Madhya Pradesh have shifted from spot tenders to annual rate contracts, displacing spot-market distributors with direct manufacturer relationships. Metropolitan treatment plants in these states now negotiate technical service inclusion alongside material supply.
India Polyacrylamide Copolymer Market Segmentation
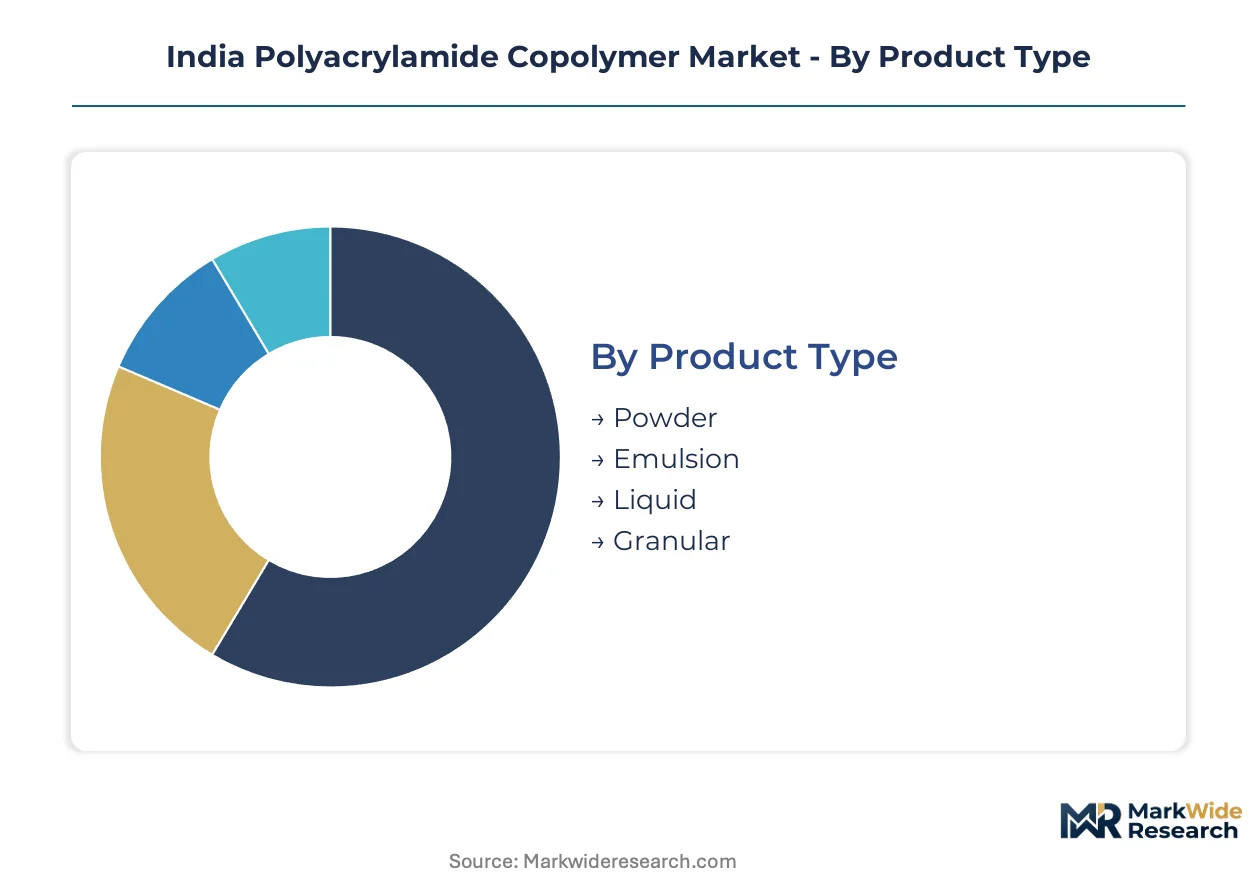
Polyacrylamide copolymer specifications vary sharply across Indian industrial applications. Product form determines logistics costs and hydration kinetics, while end-use chemistry dictates charge density and molecular weight requirements.
Product Type:
Capital intensity concentrates in emulsion manufacturing, where continuous polymerization reactors and temperature-controlled storage infrastructure demand significant upfront investment versus powder processing.
- Powder:Spray-dried polymer with particle sizes optimized for pneumatic conveying and bulk silo storage. Extended shelf stability drives preference among inland municipal utilities in Madhya Pradesh and Uttar Pradesh where cold-chain logistics remain underdeveloped.
- Emulsion:Inverse-phase polymerization yields rapid-hydrating dispersions for oilfield and mining applications. ONGC's Bombay High operations specify these grades despite higher unit costs, as hydration speed offsets dosing equipment requirements at offshore platforms.
- Liquid:Pre-hydrated solutions eliminate make-down equipment for small-scale textile processors in Surat and Tiruppur clusters.
- Granular:Intermediate particle size reduces dusting versus powder while retaining dry handling advantages for construction site dewatering.
Powder absorbs the bulk of installed capacity; emulsion is expanding most quickly.
Application:
Application selection correlates directly with charge chemistry investment, as anionic, cationic, and nonionic synthesis trains require separate reactor configurations.
- Water Treatment:Municipal sludge dewatering and potable water clarification dominate volume. Jal Jeevan Mission procurement aggregation across Maharashtra and Gujarat treatment plants is consolidating specifications toward high-molecular-weight anionic grades for turbidity removal.
- Oil Recovery:Hydrophobically modified polyacrylamides for enhanced oil recovery command premium pricing. Private operators in Rajasthan's Barmer basin are piloting these polymers to improve sweep efficiency in mature carbonate reservoirs.
- Mining:Tailings flocculation and process water recycling in Jharkhand coal washeries and Goa iron ore beneficiation plants.
- Paper Making:Retention and drainage aids for integrated pulp mills in Andhra Pradesh and Tamil Nadu.
Water treatment absorbs the bulk of installed capacity; oil recovery is climbing the fastest.
End User:
End-user concentration patterns reveal margin stratification, with pharmaceutical and food-grade certification requirements creating pricing tiers distinct from industrial commoditization.
- Wastewater Treatment:State-level Jal Shakti Department tenders in Karnataka and Telangana are shifting from spot procurement to two-year framework agreements, compressing distributor margins while expanding manufacturer-direct relationships.
- Agriculture:Soil conditioning and irrigation water management in Punjab and Haryana paddy cultivation districts.
- Textile:Zero-liquid-discharge compliance in Tamil Nadu dyeing clusters is retrofitting evaporator trains with high-charge cationic polymers for color removal.
- Construction:Tunnel boring and foundation dewatering projects in Mumbai and Delhi metro expansions.
Wastewater treatment absorbs the bulk of installed capacity; textile is gaining share fastest.
Form:
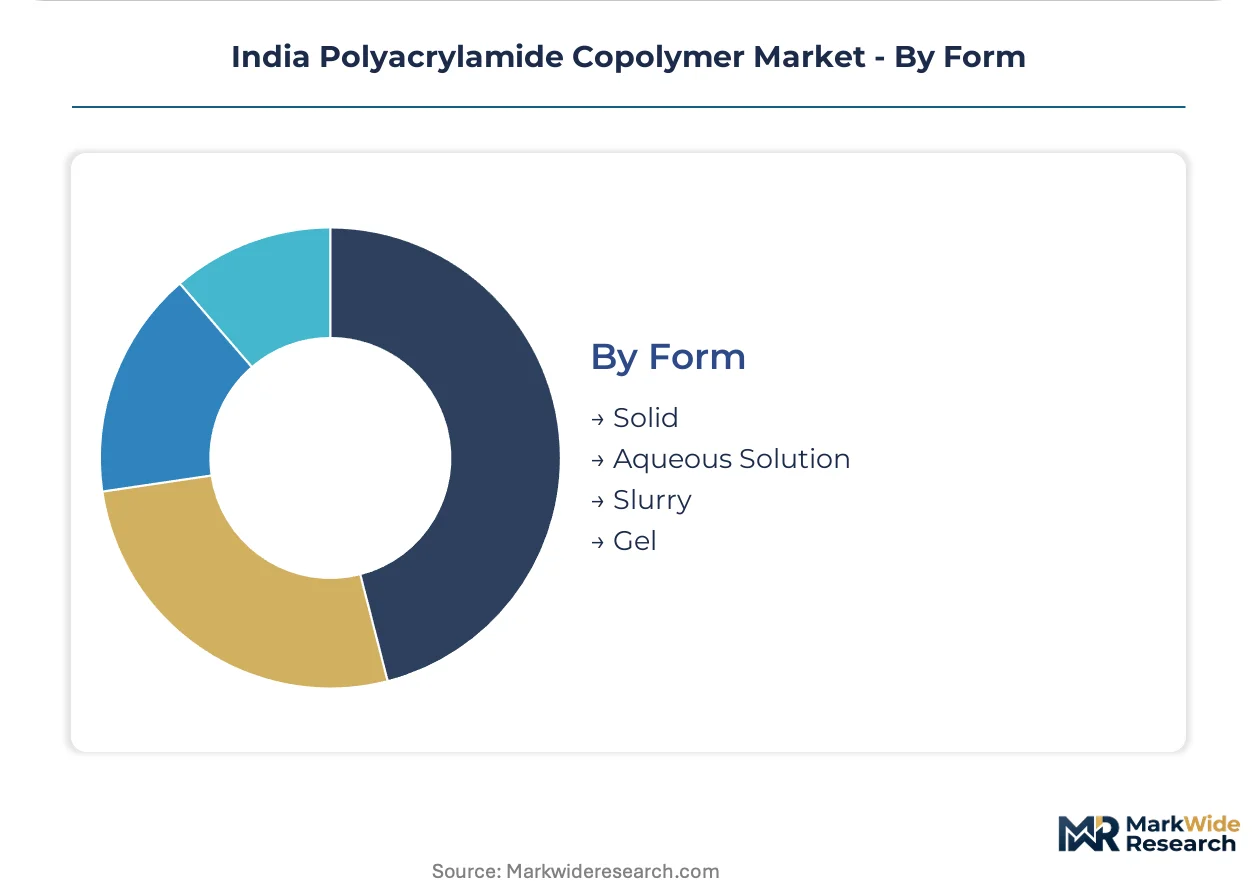
Form selection determines downstream capital requirements, with aqueous solutions eliminating field equipment but constraining shelf life and transportation economics.
- Solid:Powder and granular forms dominate inland distribution where temperature-controlled tankage remains scarce. BIS certification for potable water contact grades extends to twenty-four months, forcing captive laboratory investments at Gujarat-based manufacturers.
- Aqueous Solution:Pre-dissolved polymers for small utilities lacking make-down infrastructure. Bihar and Uttar Pradesh municipalities favor these despite freight cost penalties.
- Slurry:Concentrated dispersions for mining tailings applications where water availability constraints favor low-moisture feedstocks.
- Gel:Specialized crosslinked formulations for conformance control in oilfield profile modification.
Solid absorbs the bulk of installed capacity; aqueous solution is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for polyacrylamide copolymers concentrates in western and southern India, where industrial effluent regulations and municipal water infrastructure investments intersect with established chemical manufacturing bases.
Maharashtra
Municipal wastewater utilities in Mumbai and Pune are expanding polymer dosing capacity under Jal Jeevan Mission implementation. The state Jal Shakti Department has shifted procurement to two-year framework agreements with pre-qualified suppliers. Metropolitan treatment plants in the Mumbai-Pune corridor now negotiate technical service inclusion alongside material supply contracts.
Gujarat
Chemical manufacturing clusters near Ahmedabad and Vadodara host the densest concentration of domestic polyacrylamide synthesis capacity. BIS certification timelines for drinking water contact grades have extended to twenty-four months, forcing captive laboratory investments at local manufacturers. The state's potable water-grade output faces the tightest compliance burdens under revised purity thresholds.
Tamil Nadu
Textile processing hubs in Tiruppur and Coimbatore are retrofitting zero-liquid-discharge systems with high-charge cationic polymers for color removal and COD reduction. State-level effluent enforcement has accelerated evaporator train upgrades across dyeing clusters. These retrofit projects are expanding demand for rapid-hydrating emulsion grades despite higher unit costs.
Rajasthan
Enhanced oil recovery operations in the Barmer basin are piloting hydrophobically modified polyacrylamides to improve sweep efficiency in mature carbonate reservoirs. Private operators are testing polymer injection protocols alongside ONGC's established Bombay High programs. The state's oilfield chemical demand remains tethered to reservoir maturity and tertiary recovery economics.
Jharkhand
Coal washeries and iron ore beneficiation plants in the eastern mining belt lack qualified polymer suppliers for tailings flocculation applications. Environmental compliance tightening around tailings dam management is creating first-mover potential for technical service partnerships. Remote mine locations favor containerized dry polymer dispersing equipment to reduce civil works requirements.
India Polyacrylamide Copolymer Market Competitive Environment
European and Japanese producers anchor the premium formulation tier; Indian regional specialists hold distribution density advantages in western industrial corridors. The vendor structure splits between multinational synthesis plants with BIS-certified potable water grades and domestic blenders serving industrial effluent applications. Two strategic archetypes dominate: technical service-integrated manufacturers and commodity distributors with regional logistics networks. Competitive moves center on Jal Jeevan Mission tender pre-qualification and captive laboratory investments to compress certification timelines.
Among France-based manufacturers, SNF Floerger exemplifies the technical service-integrated archetype through its Indian manufacturing footprint. BASF SE represents the specialized emulsion grade segment, while Black Rose Industries anchors regional distribution networks across western India. These three occupy distinct competitive positions without overlapping core capabilities.
| Leading Market Players |
|---|
| Ashland Global Holdings Inc. |
| Nippon Shokubai Co., Ltd. |
| BASF SE |
| China National Petroleum Corporation |
| Shandong Polymer Bio-chemicals Co., Ltd. |
| SNF Floerger |
| Solvay SA |
| Black Rose Industries |
| Kemira Oyj |
| Others |
Value Chain & Pricing Dynamics
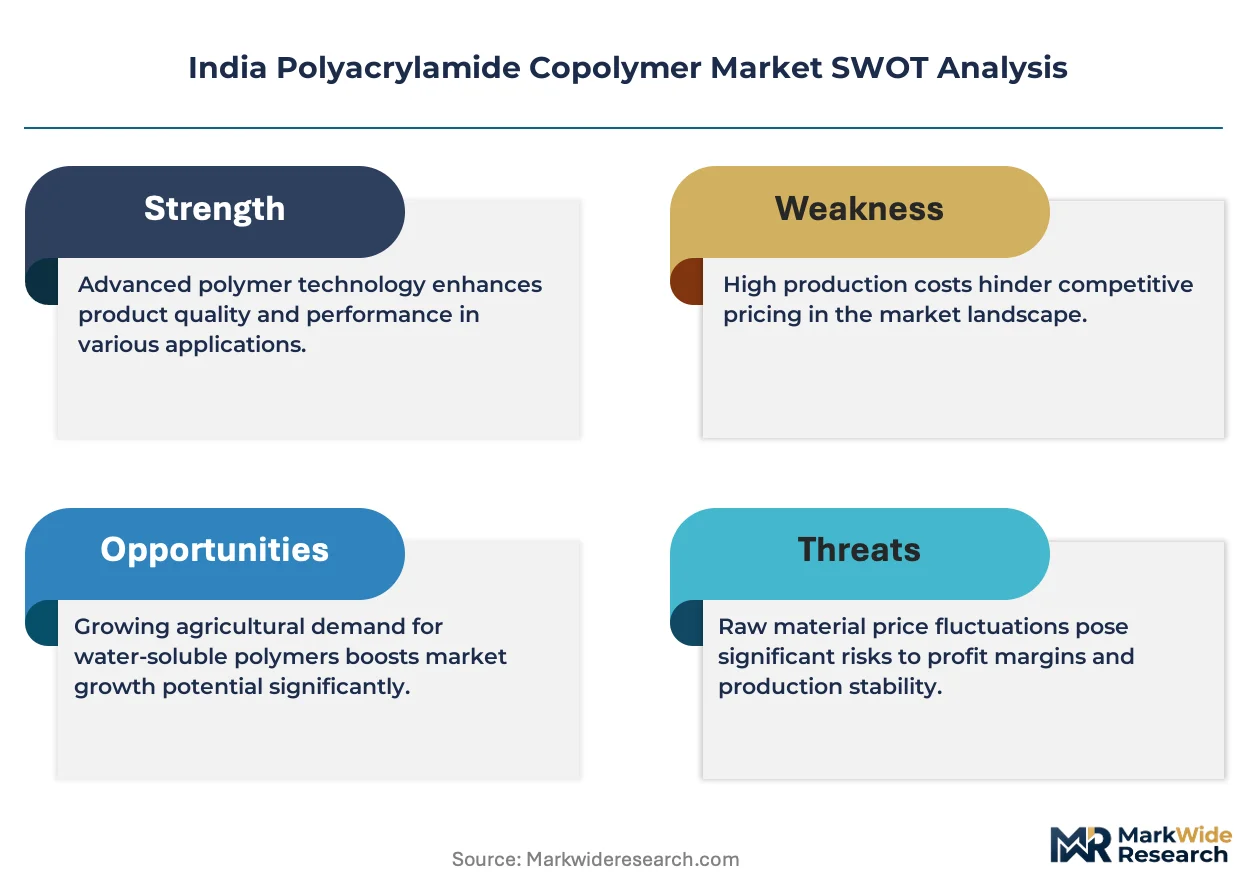
Captive laboratory investments at Gujarat-based manufacturers anchor supply positioning for BIS-certified potable water grades while simultaneously compressing pricing power for uncertified industrial blenders facing extended twenty-four-month certification timelines.
Pricing Analysis
Volume-margins split sharply across the Jal Jeevan Mission tender pool versus spot-market industrial sales. Three-tier pricing structure separates BIS-certified drinking water grades from industrial effluent specifications and uncertified commodity blends. Pricing pressure stems from state-level procurement aggregation consolidating municipal buyers into framework agreements with pre-qualified suppliers. Small utilities in Bihar and Uttar Pradesh exhibit highest price sensitivity due to emulsion storage infrastructure gaps forcing aqueous solution premiums.
Supply Chain Analysis
Freight cost differentials between powder and emulsion forms drive inland distribution economics toward spray-dried grades across Madhya Pradesh and Uttar Pradesh. Domestic acrylonitrile supply draws from Reliance Industries' petrochemical output, exposing blenders to import parity pricing swings. Single-source feedstock vulnerability concentrates risk at the monomer input stage. Distribution runs through regional specialists with temperature-controlled tankage in western India and bulk silo networks for powder inland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BIS residual acrylamide thresholds below 0.05 percent function as a cost-of-compliance moat, forcing capital-intensive purification retrofits that screen out undercapitalized domestic blenders from potable water-grade participation.
For Market Incumbents: Acquire captive testing infrastructure to compress BIS certification timelines from twenty-four months toward eighteen. Defend municipal tender positions by embedding technical service teams within metropolitan treatment plants in Maharashtra and Gujarat. Natural flocculant substitution in food-processing wastewater poses emerging substitution threat requiring specialized emulsion grade differentiation. For New Entrants and Emerging Players: Drone-based polymer dosing systems for tailings dam remediation represent a technology-first wedge into Goa's inaccessible mine voids and Karnataka's abandoned pits. Jharkhand coal washeries lack qualified suppliers for tailings flocculation applications. Partner with mining contractors on containerized dry polymer dispersing equipment to bypass permanent plant capital requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in technical service-integrated manufacturers with BIS-certified potable water grades and Jal Jeevan Mission pre-qualification status. Five-to-ten-year viability favors Gujarat-based synthesis plants with backward integration into acrylonitrile handling infrastructure. Monitor state-level Jal Shakti Department tender aggregation velocity as inflection indicator for manufacturer-direct relationship expansion versus distributor displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Laboratory Investment | Accelerates BIS certification timelines for potable water-grade output amid purity threshold tightening. |
| Technical Service Integration | Embeds polymer optimization expertise within Jal Jeevan Mission metropolitan treatment plant contracts. |
| Containerized Dispersing Equipment | Reduces civil works requirements for remote mining locations in Jharkhand and Goa. |
| Emulsion Storage Infrastructure | Enables rapid-hydrating grade penetration in Tamil Nadu textile zero-liquid-discharge retrofits. |
| Backward Integration into Acrylonitrile | Insulates blenders from Reliance Industries supply volatility and import parity pricing swings. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with polymer plant managers, Jal Shakti Department procurement officers, textile processing technical directors, and mining tailings engineers. BIS certification databases, CDSCO pharmaceutical excipient registrations, and CEA thermal power plant effluent compliance records provided regulatory validation. Bottom-up volume estimates from state-level tender aggregation combined with top-down chemical industry consumption benchmarks.
Data-stream reconciliation across product form, charge chemistry, and end-use application dimensions shaped the analytical framework over the projection horizon. CAGRs derived from slope-log regression against infrastructure investment trajectories. Modeled inputs included Jal Jeevan Mission implementation pacing, zero-liquid-discharge mandate adoption in textile clusters, and Bombay High enhanced oil recovery polymer injection volumes.
Several conditions sit outside the modeled scope, including unforeseen BIS purity threshold revisions, abrupt acrylonitrile supply disruptions, and natural flocculant technology breakthroughs. Forecasts reflect documented assumptions about state procurement aggregation continuity and oilfield operator polymer adoption rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
MDI, TDI, and Polyurethane Market
Polymers & Resins
Polystyrene (PS) and Expanded Polystyrene (EPS) Market
Polymers & Resins
Cross-Linked Polyethylene (XLPE) Market
Polymers & Resins
United Kingdom Engineering Plastics Market
Polymers & Resins
Global Nylon Market
Polymers & Resins
Geopolymer Market
Polymers & Resins
Europe Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Middle East Polyamide Market
Polymers & Resins
Polymer Modifiers Market
Polymers & Resins
Global Corrosion Resistant Resin Market
Polymers & Resins
Semi-Crystalline Polymers Market
Polymers & Resins
Global Barrier Resins Market
Polymers & Resins
Ethylene Acrylic Acid (EAA) Copolymers Market
Polymers & Resins
Bio-Based PU Market
Polymers & Resins
Indonesia Flooring Resins Market