
 Aquarium Water Treatment Market | 2026-2036
Aquarium Water Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Aquarium Water Treatment Market Outlook
Asian chemical manufacturers is rebalancing output toward aquarium-grade water conditioners after years of serving industrial water treatment. Pentair leverages its North American distribution network to sustain premium positioning in canister filtration systems. Seachem differentiates through concentrated dosing formulations that reduce shipping volumes for marine aquarium specialists.
Aquarium water treatment encompasses chemical and mechanical processes that maintain nitrogenous waste below toxic thresholds, typically requiring ammonia levels below 0.25 ppm and nitrite below 0.5 ppm for ornamental fish survival. Filters and water conditioners command the largest product share, though UV sterilization is gaining traction among marine hobbyists managing ich and dinoflagellate outbreaks. Biological filtration anchors freshwater applications where established colonies process continuous ammonia loads, while reverse osmosis units dominate marine segments demanding near-zero total dissolved solids for sensitive coral propagation.
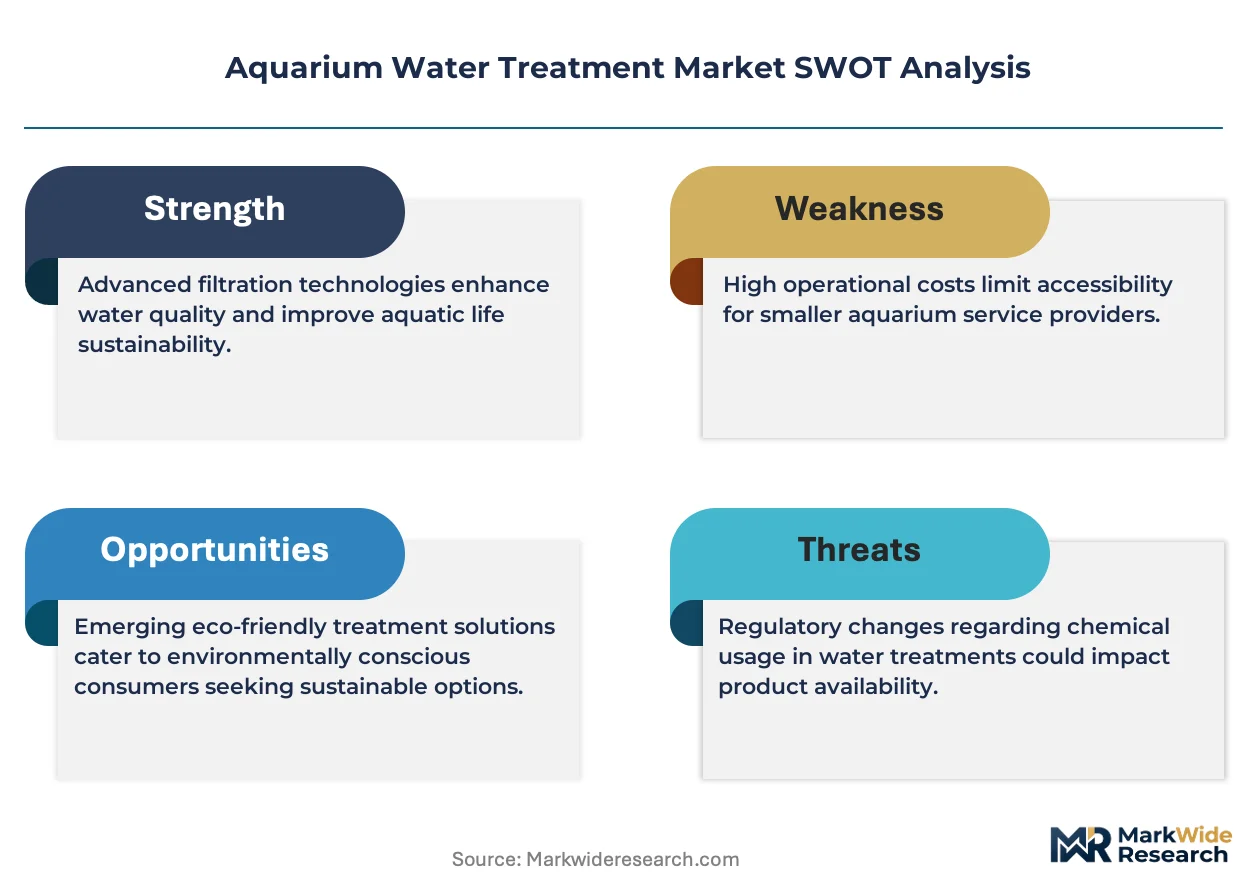
EPA discharge standards shape formulation choices for algaecides sold into pond systems and aquatic farms, restricting copper sulfate concentrations in runoff-prone installations. The EU REACH framework governs biocide registration for dechlorinators and antibacterial additives, extending compliance timelines for suppliers seeking cross-border access. Stakeholders must weigh regulatory divergence between jurisdictions when prioritizing R&D pipelines and regional manufacturing footprints.
Market Dynamics
Recirculating aquaculture system adoption in Southeast Asia is compressing replacement cycles for biological filtration media while elevating demand for automated water quality monitoring. Commercial shrimp and finfish operators now treat water as a continuously managed input rather than a disposable commodity.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on hydrofluorocarbon refrigerants in climate-controlled aquaculture facilities force operators toward passive cooling and geothermal temperature management, expanding demand for chemical buffers that stabilize water parameters without mechanical chilling.
- Indonesia's shrimp farming belt:Concentrated commercial aquaculture around Java and Sulawesi generates sustained bulk purchasing of dechlorinators and ammonia-neutralizing formulations as producers scale intensive pond systems.
- UV-C LED technology:Solid-state ultraviolet sterilization is displacing mercury-vapor lamps in marine hobbyist applications, reducing warm-up times and enabling precise dosing against ich and dinoflagellate outbreaks.
Market Restraints
- Iodine and activated carbon input costs:Volatility in specialty chemical feedstocks constrains margin flexibility for concentrated water conditioner manufacturers serving price-sensitive freshwater segments.
- Biological media supply concentration:Ceramic and sintered glass filtration substrates depend heavily on Chinese kiln operations, exposing distributors to freight cost swings and customs processing delays.
- Reverse osmosis membrane technical limits:Current polyamide thin-film composites struggle with boron rejection in coastal marine aquarium applications, forcing hobbyists into multi-stage systems that elevate total cost of ownership.
Strategic Opportunities
- Vietnam's emerging commercial aquaculture:Underpenetrated Mekong Delta operations present first-mover potential for suppliers offering bundled water treatment and aeration packages to transitioning extensive pond farms.
- EU REACH biocide registration:Extended compliance timelines for dechlorinator formulations create defensive moats for suppliers with existing dossiers, locking out smaller competitors from cross-border sales.
- IoT sensor convergence:Integration of ammonia probes with cloud-based alerting platforms enables subscription revenue models for equipment vendors previously dependent on hardware margins.
Industry Challenges
- Specialized aquaculture engineering talent:Shortage of technicians capable of calibrating multi-parameter probes in high-humidity environments slows deployment of automated monitoring at commercial sites.
- EPA discharge certification timelines:Algaecide formulations for pond systems face extended review cycles for copper sulfate restrictions, delaying product launches in runoff-sensitive watersheds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aquarium Water Treatment Market |
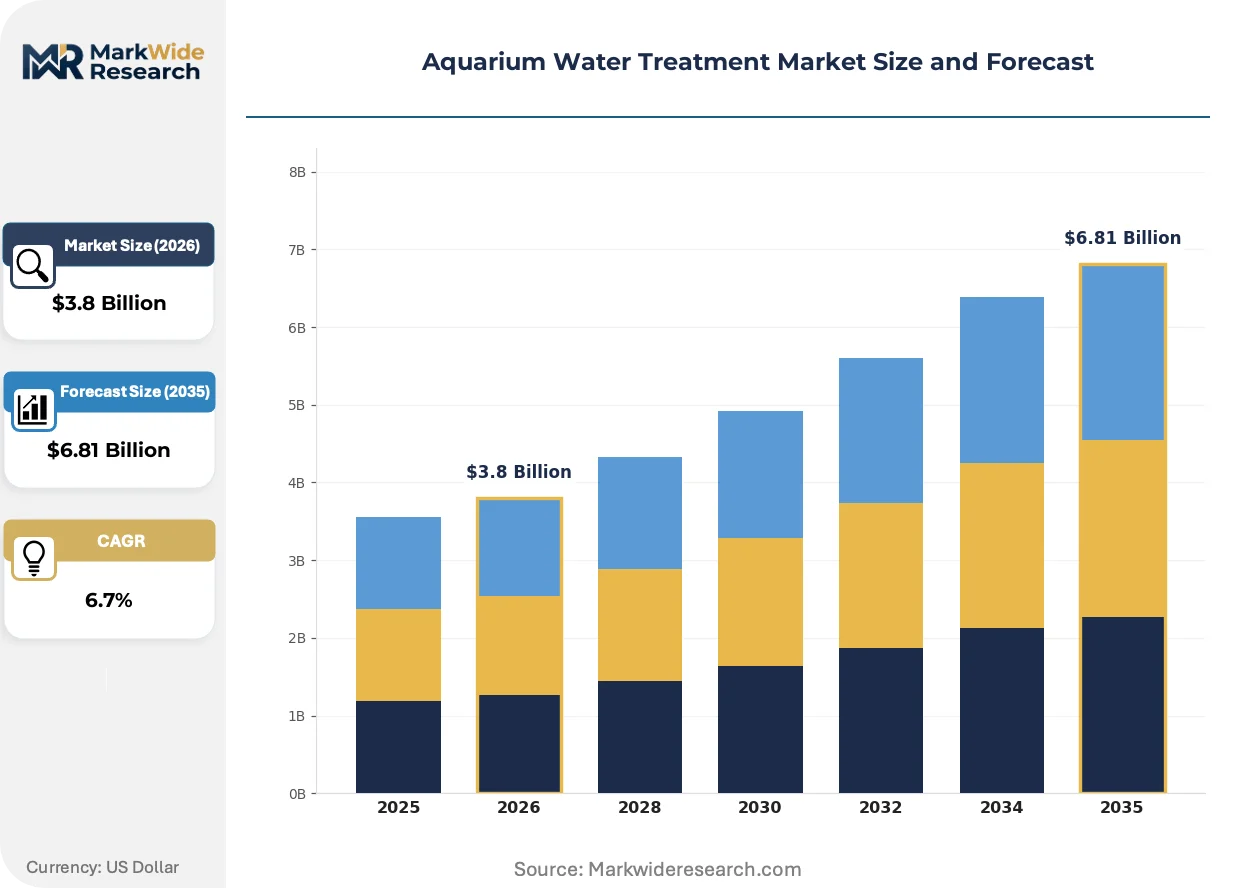
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filters, Dechlorinators, Algaecides, Water Conditioners Application: Freshwater Aquariums, Marine Aquariums, Pond Systems, Aquaculture Technology: Biological Filtration, Chemical Filtration, UV Sterilization, Reverse Osmosis End User: Individual Hobbyists, Pet Shops, Research Institutions, Aquatic Farms |
| Companies Covered | Red Sea, Eheim, Pentair, Fluval, JBL, Tetra, Seachem, Aquarium Pharmaceuticals, API, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aquarium Water Treatment Market Strategic Shifts
Equipment architecture is fragmenting into interoperable subsystems as operators demand flexibility to upgrade individual components without full system replacement. This shift favors suppliers with open-platform designs over vertically integrated legacy offerings.
Canister filtration hardware is modularizing around standardized hose diameters and media basket dimensions. Marine aquarium specialists in Germany and the Netherlands now mix components from multiple vendors, compressing brand loyalty and forcing incumbents to compete on individual cartridge performance rather than ecosystem lock-in.
EPA discharge standards for copper-based algaecides are tightening enforcement in Florida and California pond installations. Formulators are responding with chelated copper alternatives and peroxide-based substitutes, though efficacy gaps persist in heavy algae-bloom scenarios requiring rapid knockdown.
After-sales service unbundling is disrupting traditional distribution channels in North American reef-keeping communities. Hobbyists now source replacement media through direct-to-consumer subscription platforms, bypassing brick-and-mortar retailers that previously captured recurring revenue through foot traffic dependency.
Aquarium Water Treatment Market Segmentation
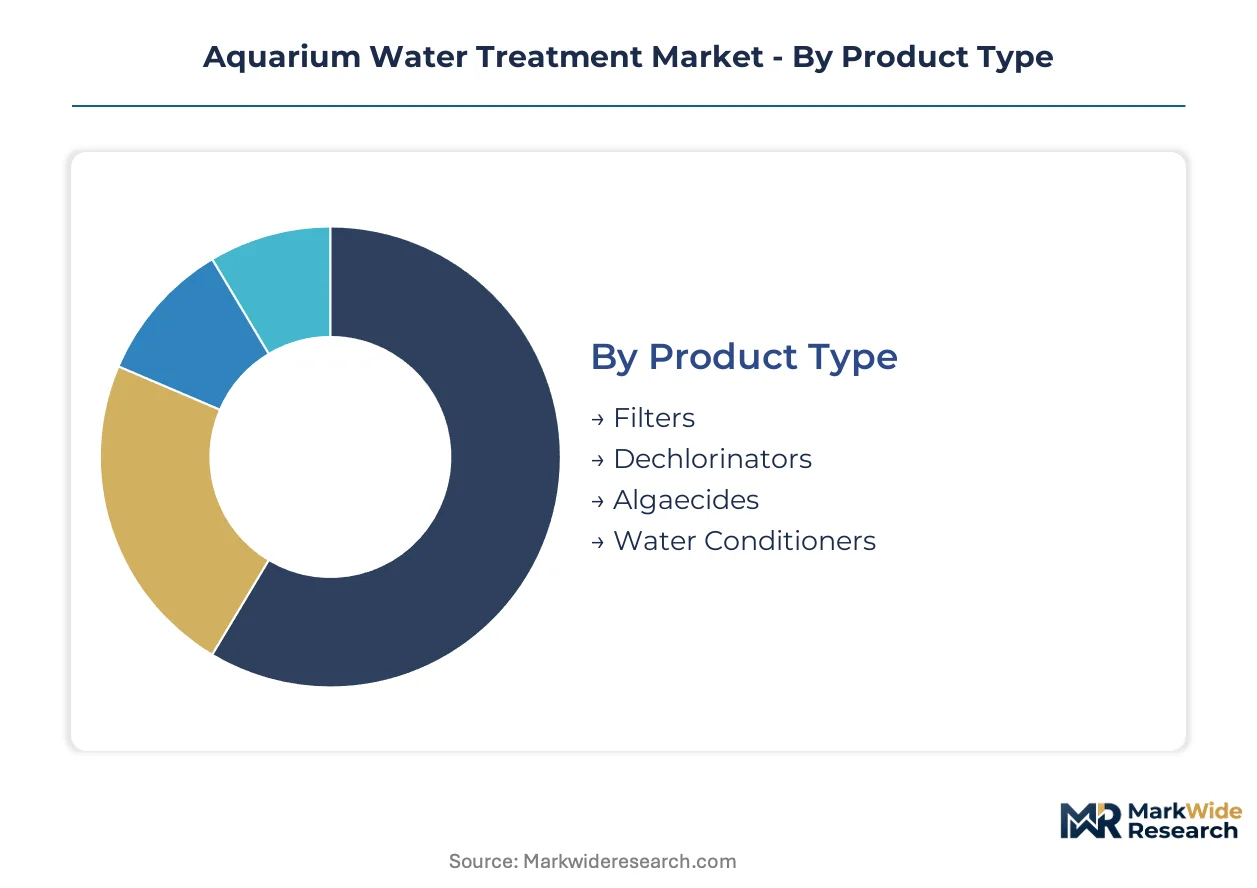
Product architecture and treatment protocols diverge sharply across ornamental versus commercial installations. Upgrade cycles and replacement intensity vary by segment, creating distinct margin profiles for suppliers serving hobbyist versus industrial buyers.
Product Type:
Replacement frequency and upgrade intensity differ materially across hardware versus consumable categories, conditioning how suppliers structure recurring revenue.
- Filters:Canister and hang-on-back units anchor freshwater setups with standardized media baskets. Hobbyists in Germany and the Netherlands now mix components across vendors, eroding brand loyalty. Commercial aquaculture operators in Indonesia's Java and Sulawesi belt compress replacement cycles for biological media as recirculating system adoption accelerates.
- Dechlorinators:Sodium thiosulfate-based formulations neutralize municipal chlorine and chloramine before tank introduction. EU REACH biocide registration timelines extend compliance burdens, favoring incumbents with existing dossiers. Pet shops and aquatic farms in Vietnam's Mekong Delta generate bulk purchasing as extensive pond operations transition to intensive systems.
- Algaecides:Chelated copper and peroxide-based formulations address bloom outbreaks in pond systems.
- Water Conditioners:Concentrated dosing formulations reduce shipping volumes for marine specialists managing sensitive coral propagation.
Volume placements concentrate in Filters; the faster expansion belongs to Dechlorinators.
Application:
Water chemistry requirements and regulatory exposure create tiered margin structures across ornamental and food-production environments.
- Freshwater Aquariums:Established biological filtration colonies process continuous ammonia loads in community tank setups. Hobbyists prioritize ammonia levels below 0.25 ppm and nitrite below 0.5 ppm for ornamental fish survival. North American retail channels sustain premium positioning for canister systems through distributor relationships.
- Marine Aquariums:Near-zero total dissolved solids requirements drive reverse osmosis adoption for coral propagation. UV-C LED technology displaces mercury-vapor lamps, reducing warm-up times and enabling precise dosing against ich and dinoflagellate outbreaks.
- Pond Systems:EPA discharge standards restrict copper sulfate concentrations in runoff-prone Florida and California installations.
- Aquaculture:Commercial shrimp and finfish operators treat water as continuously managed input rather than disposable commodity.
Freshwater Aquariums still account for the largest installed base; Marine Aquariums are gaining share fastest.
Technology:
Capital intensity and technical calibration requirements segment the supplier base between plug-and-play and engineered solutions.
- Biological Filtration:Ceramic and sintered glass substrates depend heavily on Chinese kiln operations, exposing distributors to freight cost swings. Established colonies process ammonia loads in freshwater applications where media replacement cycles determine recurring revenue.
- Chemical Filtration:Activated carbon and ion-exchange resins target dissolved organics and heavy metals. Iodine and specialty chemical feedstock volatility constrains margin flexibility for manufacturers serving price-sensitive segments.
- UV Sterilization:Solid-state ultraviolet systems reduce energy consumption and enable precise pathogen dosing.
- Reverse Osmosis:Polyamide thin-film composites struggle with boron rejection in coastal marine applications, forcing multi-stage configurations that elevate total cost of ownership.
Biological Filtration dominates freshwater placements; UV Sterilization shows the steepest expansion trajectory.
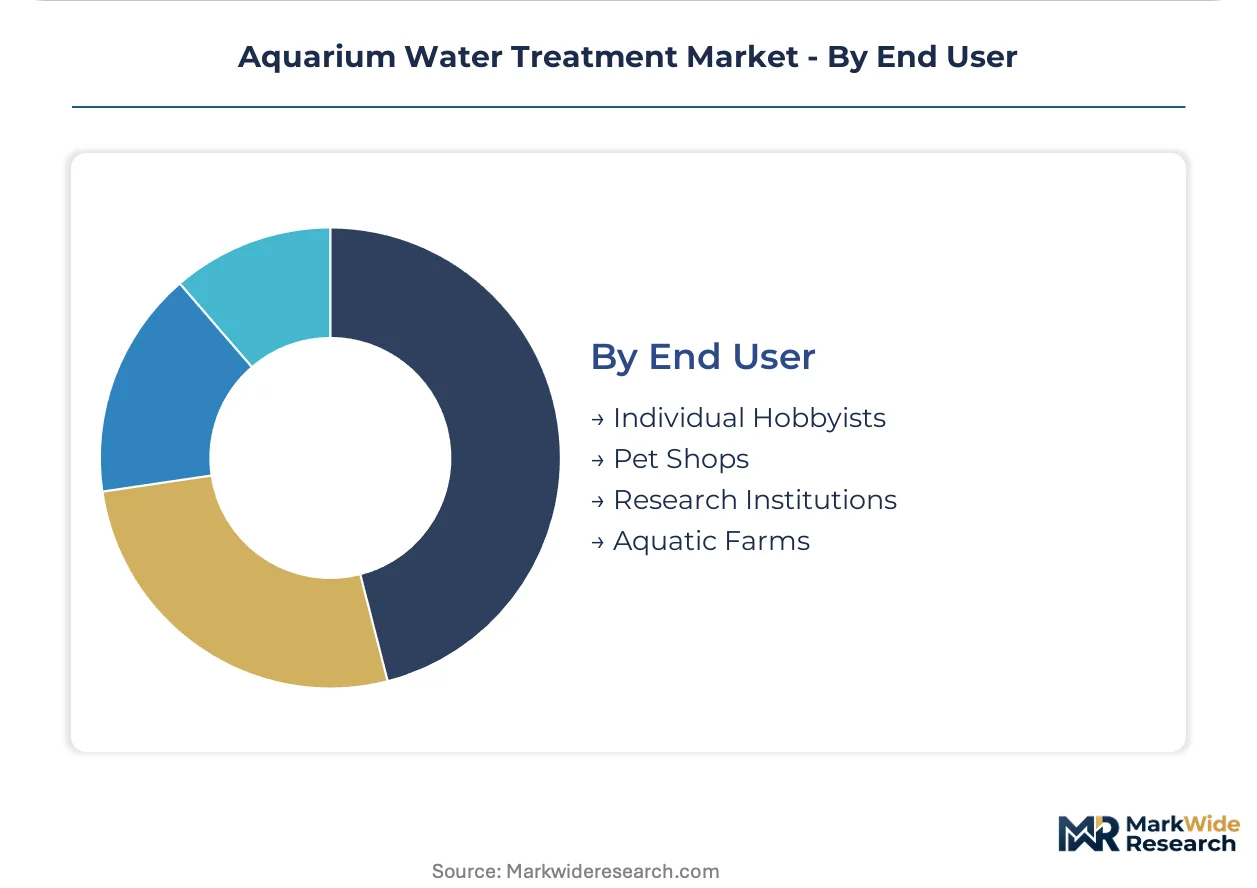
End User:
Procurement sophistication and technical support requirements create distinct channel strategies across fragmented buyer types.
- Individual Hobbyists:Subscription platforms for replacement media now bypass brick-and-mortar retailers in North American reef-keeping communities. After-sales service unbundling disrupts traditional distribution channels previously dependent on foot traffic dependency.
- Pet Shops:Inventory breadth and technical advice requirements favor distributors with localized logistics networks.
- Research Institutions:Multi-parameter probe calibration demands specialized engineering talent scarce in high-humidity environments.
- Aquatic Farms:Bundled water treatment and aeration packages attract transitioning extensive pond operations in underpenetrated markets.
Individual Hobbyists drive the highest transaction frequency; Aquatic Farms offer the largest contract values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese ceramic kiln operations supply the sintered glass substrates that anchor biological filtration media production, exposing distributors worldwide to freight volatility and customs processing delays.
United States
Florida and California pond installations drive algaecide formulation demand under tightening EPA discharge standards for copper sulfate runoff. The EPA restricts copper concentrations in watershed-sensitive areas, forcing chelated copper and peroxide-based substitutes. Miami-Dade and Orange County clusters host commercial aquaculture operations scaling recirculating systems.
Germany
Marine aquarium specialists in Germany modularize canister filtration hardware around standardized hose diameters and media basket dimensions. The EU F-Gas Regulation restricts hydrofluorocarbon refrigerants in climate-controlled facilities, pushing operators toward passive cooling and chemical buffer stabilization. Hamburg and Berlin reef-keeping communities source replacement media through direct-to-consumer subscription platforms.
Indonesia
Java and Sulawesi's shrimp farming belt generates sustained bulk purchasing of dechlorinators and ammonia-neutralizing formulations as producers scale intensive pond systems. The country's national environmental regulator enforces wastewater discharge limits for aquaculture operations. Surabaya and Makassar industrial zones concentrate recirculating system adoption with compressed biological media replacement cycles.
Vietnam
Mekong Delta operations present first-mover potential for bundled water treatment and aeration packages as extensive pond farms transition to intensive systems. The country's national fisheries development program incentivizes commercial aquaculture modernization. Can Tho and An Giang provinces drive demand for automated water quality monitoring as operators treat water as continuously managed input.
Netherlands
Marine hobbyists in the Netherlands mix filtration components from multiple vendors, eroding brand loyalty and forcing competition on individual cartridge performance. The EU REACH framework governs biocide registration for dechlorinators, extending compliance timelines for cross-border suppliers. Rotterdam and Amsterdam distribution hubs sustain premium positioning for canister systems through localized logistics networks.
Aquarium Water Treatment Market Competitive Environment
Global majors compete with regional champions across distribution reach and formulation specialization, producing a tiered structure where scale-driven players anchor volume placements while niche specialists capture premium margins. The vendor base separates into three strategic archetypes: integrated water treatment conglomerates with diversified industrial portfolios, dedicated aquarium equipment manufacturers with deep hobbyist channel relationships, and Asian chemical producers rebalancing toward aquarium-grade conditioners. Dominant competitive moves include geographic expansion into underpenetrated Southeast Asian aquaculture belts and portfolio diversification toward IoT-integrated monitoring systems.
Among Germany-based fabricators, Eheim and JBL occupy positions within the dedicated equipment tier, exemplifying engineering-focused archetypes with established European distribution networks. Pentair represents the integrated conglomerate archetype, leveraging North American infrastructure to sustain premium positioning across multiple water treatment verticals. Seachem anchors the specialty formulation segment, with concentrated dosing products reducing shipping volumes for marine aquarium applications.
| Leading Market Players |
|---|
| Red Sea |
| Eheim |
| Pentair |
| Fluval |
| JBL |
| Tetra |
| Seachem |
| Aquarium Pharmaceuticals |
| API |
| Others |
Value Chain & Pricing Dynamics
Premium-mid-economy pricing differentiation separates hobbyist canister systems from commercial recirculating installations, with warranty bundling and service contracts concentrating in the upper tier while commodity dechlorinators compete on spot pricing. This tiering maps directly onto supply chain configurations: premium hardware vendors maintain captive distribution networks, whereas bulk chemical suppliers ride third-party logistics through Indonesian and Vietnamese port clusters.
Pricing Analysis
Warranty and after-sales service unbundling now defines competitive positioning, with North American reef-keeping communities subscribing to replacement media platforms while commercial aquaculture operators negotiate long-term service contracts. Price differentiation rests on certification grade—EU REACH-compliant dechlorinators command premiums against unregistered alternatives—and volume scale, with Java shrimp farms extracting bulk discounts. Cost compression in commodity water conditioners is intensifying because iodine and activated carbon feedstock volatility squeezes manufacturer margins. Freshwater hobbyists exhibit highest price sensitivity, while marine coral propagation specialists tolerate premium positioning for near-zero TDS guarantees.
Supply Chain Analysis
Dual-sourcing requirements now permeate procurement protocols as distributors qualify secondary ceramic kiln operations beyond China's dominant sintered glass substrate production. Biological filtration media draws from Chinese, German, and emerging Vietnamese kiln operations; activated carbon and ion-exchange resins rest on Sri Lankan and Philippine processing facilities. Single-source vulnerability concentrates in Chinese ceramic substrate supply, exposing distributors to freight cost swings and customs processing delays. Distribution runs through localized logistics networks in Rotterdam and Amsterdam for European marine specialists, while Southeast Asian commercial operators source through Surabaya and Makassar industrial zone distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-side concentration in Chinese kiln operations and REACH-registered formulation capacity props pricing power for incumbents, constraining new entrant scale-up.
For Market Incumbents: Hedge against biological media supply disruption by qualifying Vietnamese kiln alternatives and securing long-term activated carbon offtake agreements. Defensive positioning demands investment in IoT-integrated monitoring platforms as subscription revenue models displace hardware-dependent margins. EU REACH registration timelines create moats against unregistered competitors, warranting dossier maintenance investment. For New Entrants and Emerging Players: Enter via Vietnam's Mekong Delta aquaculture transition, where bundled water treatment and aeration packages address underpenetrated extensive pond operations shifting to intensive systems. White-space concentration sits with automated water quality monitoring deployment, given technician scarcity slows incumbent rollout. Direct-to-consumer subscription platforms for replacement media bypass established retail channels in North American reef-keeping communities. For Investors and Strategic Acquirers: Re-rating potential sits with specialty formulation specialists possessing REACH-registered dechlorinator dossiers, given compliance timeline extensions lock out smaller competitors. Long-term viability across the analysis window favors suppliers with backward integration into ceramic substrate production or captive iodine sourcing. Watch UV-C LED sterilization adoption curves as inflection indicator for solid-state displacement of mercury-vapor lamp installed base.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrate Production | Captive kiln operations in Vietnam reduce exposure to Chinese supply concentration and freight volatility. |
| REACH Dossier Expansion | Extended biocide registration timelines lock out unregistered competitors from EU cross-border sales. |
| IoT Sensor Platform Launch | Cloud-based ammonia probe integration enables recurring subscription revenue from equipment vendors. |
| Direct-to-Consumer Subscription Channel | Replacement media bypasses brick-and-mortar retail dependency in North American reef-keeping markets. |
| Geographic Expansion into Mekong Delta | Bundled treatment and aeration packages capture Vietnam's transitioning extensive pond operations. |
Study Parameters
Multi-period observation of biological media replacement cycles and dechlorinator formulation registrations anchored the trend analysis, supplemented by interviews with commercial aquaculture operations managers, pet shop procurement leads, ceramic kiln operations directors, and marine aquarium specialists. Secondary validation drew from customs trade data, EU REACH registration databases, Indonesian fisheries development program disclosures, and SEC filings of listed water treatment conglomerates. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Input-output matrices mapped installed base volumes through replacement intensity curves, with segmentation dimensions spanning product architecture, application environment, technology protocol, and end-user procurement sophistication. CAGRs were derived from trend extrapolation of observed replacement compression in recirculating aquaculture systems and UV-C LED adoption trajectories. Forecast inputs incorporated EPA discharge standard enforcement patterns and EU F-Gas Regulation compliance cost pass-through assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under acute ceramic substrate supply disruption or abrupt REACH registration requirement expansion. Deviation in Indonesian shrimp farm recirculating system adoption rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
China Water Treatment Chemicals Market
Water & Sludge Treatment
Swimming Pool Treatment Chemicals Market
Water & Sludge Treatment
Membrane Filtration Systems Market
Water & Sludge Treatment
Global Water Clarifiers Market
Water & Sludge Treatment
Asia-Pacific Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Salt Water Softeners Market
Water & Sludge Treatment
Drinking Water Adsorbents Market
Water & Sludge Treatment
Water Treatment Chemicals Market
Water & Sludge Treatment
Global Flocculant and Coagulant Market
Water & Sludge Treatment
Slurry Valves Market
Water & Sludge Treatment
Semiconductor Wastewater Treatment Market
Water & Sludge Treatment
Europe Water Treatment Chemicals Market
Water & Sludge Treatment
Produced Water Treatment Market
Water & Sludge Treatment
Alkalinity Control Chemicals Market
Water & Sludge Treatment
Liquid Waste Container Market
Water & Sludge Treatment
Industrial Water Treatment Chemicals Market