
 Africa Water Treatment Chemicals Market | 2026-2036
Africa Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Water Treatment Chemicals Market Intelligence
Multi-source procurement among municipal water authorities is repositioning supply relationships across the continent. Solenis leverages its regional distribution network to serve coastal desalination projects. Kemira anchors its position through coagulant manufacturing partnerships in Southern Africa. Ecolab Inc. competes on integrated service contracts that bundle chemical supply with monitoring equipment.
Africa water treatment chemicals comprise formulated active ingredients including aluminum sulfate, polyacrylamide polymers, chlorine-based oxidants, and pH correction compounds designed to remove suspended solids, neutralize pathogens, and stabilize distribution system chemistry. These formulations typically target turbidity reduction below 1 NTU and residual disinfection maintenance of 0.2–0.5 mg/L free chlorine. Coagulants and flocculants dominate product value due to their indispensability in surface water clarification, while disinfectants command premium pricing where viral inactivation standards apply. The municipal end user segment absorbs the largest volume, though industrial purchasers in mining and power generation generate higher per-ton margins through specialized corrosion and scale control requirements.
South Africa's Department of Water and Sanitation enforces Blue Drop certification standards that mandate documented chemical dosing protocols and supplier traceability. Nigeria's National Agency for Food and Drug Administration and Control and the Standards Organisation of Nigeria jointly regulate imported treatment chemicals through mandatory product registration and compositional disclosure. Kenya's Water Services Regulatory Board is implementing performance-based operator contracts that tie chemical procurement to treated water quality outcomes. Stakeholders must monitor how divergent national approval timelines affect cross-border supply chain planning and inventory positioning.
Market Dynamics
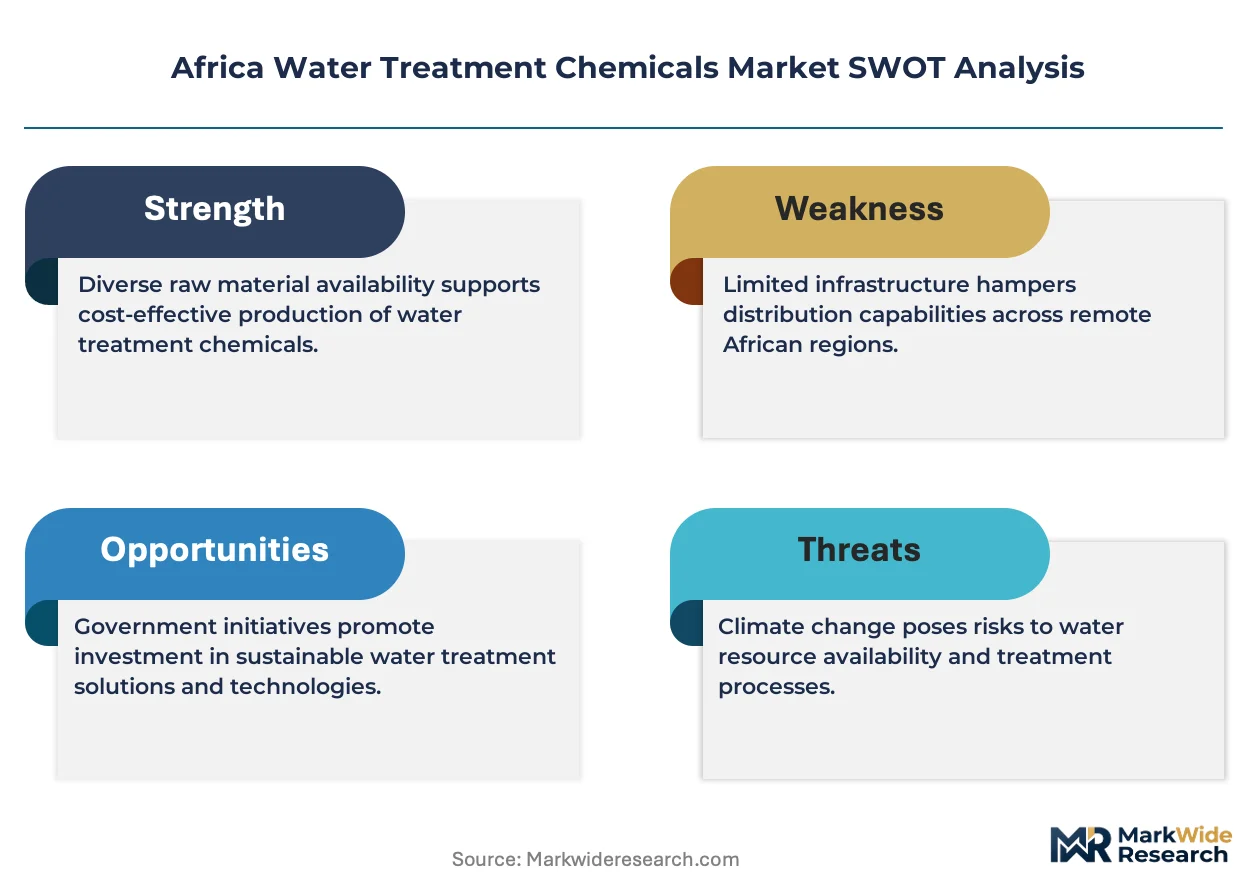
Municipal procurement centralization across West and Southern Africa is compressing supplier margins while elevating technical compliance requirements for coagulant and disinfectant formulations.
Growth Catalysts
- Blue Drop Certification:South Africa's Department of Water and Sanitation mandates documented dosing protocols that lock in multi-year chemical supply agreements with qualified vendors.
- Coastal Desalination Expansion:Nigeria's Lagos State Water Corporation and Ghana Water Company are scaling membrane-based plants that require specialized antiscalants and cleaning chemicals.
- WHO-Aligned Standards:Kenya's Water Services Regulatory Board is adopting residual chlorine specifications that force upgrades in disinfectant procurement across 47 county water utilities.
Market Restraints
- Alum Price Volatility:Aluminum sulfate, the dominant coagulant, tracks London Metal Exchange aluminum pricing with 60-90 day procurement lags that destabilize municipal budgeting.
- Import Dependency:Polyacrylamide polymer supply concentrates in Chinese and European manufacturers, exposing African distributors to freight cost spikes and currency mismatch risks.
- Power Infrastructure Gaps:Chlorine generation via on-site electrolysis requires grid reliability that remains absent in secondary Nigerian and Ethiopian cities, forcing reliance on bulk hypochlorite imports.
Strategic Opportunities
- Angolan Water PPPs:The government's PROÁGUA program is tendering performance-based contracts that bundle chemical supply with operations in Luanda and Benguela provinces.
- Mobile Dosing Units:Containerized chlorine dioxide systems are penetrating informal settlements in Nairobi and Dar es Salaam where fixed infrastructure is uneconomical.
- Industrial Wastewater Reuse:South Africa's National Water Act amendments incentivize mining operators to adopt zero-liquid-discharge chemistries for process water recovery.
Industry Challenges
- Analytical Chemist Shortage:Municipal utilities in Tanzania and Uganda lack personnel capable of jar testing and dosing optimization, leading to overconsumption of coagulants.
- Registration Timeline Variability:Nigeria's NAFDAC product approval process stretches 12-18 months versus Kenya's 6-month PCPB equivalent, complicating regional inventory positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Water Treatment Chemicals Market |
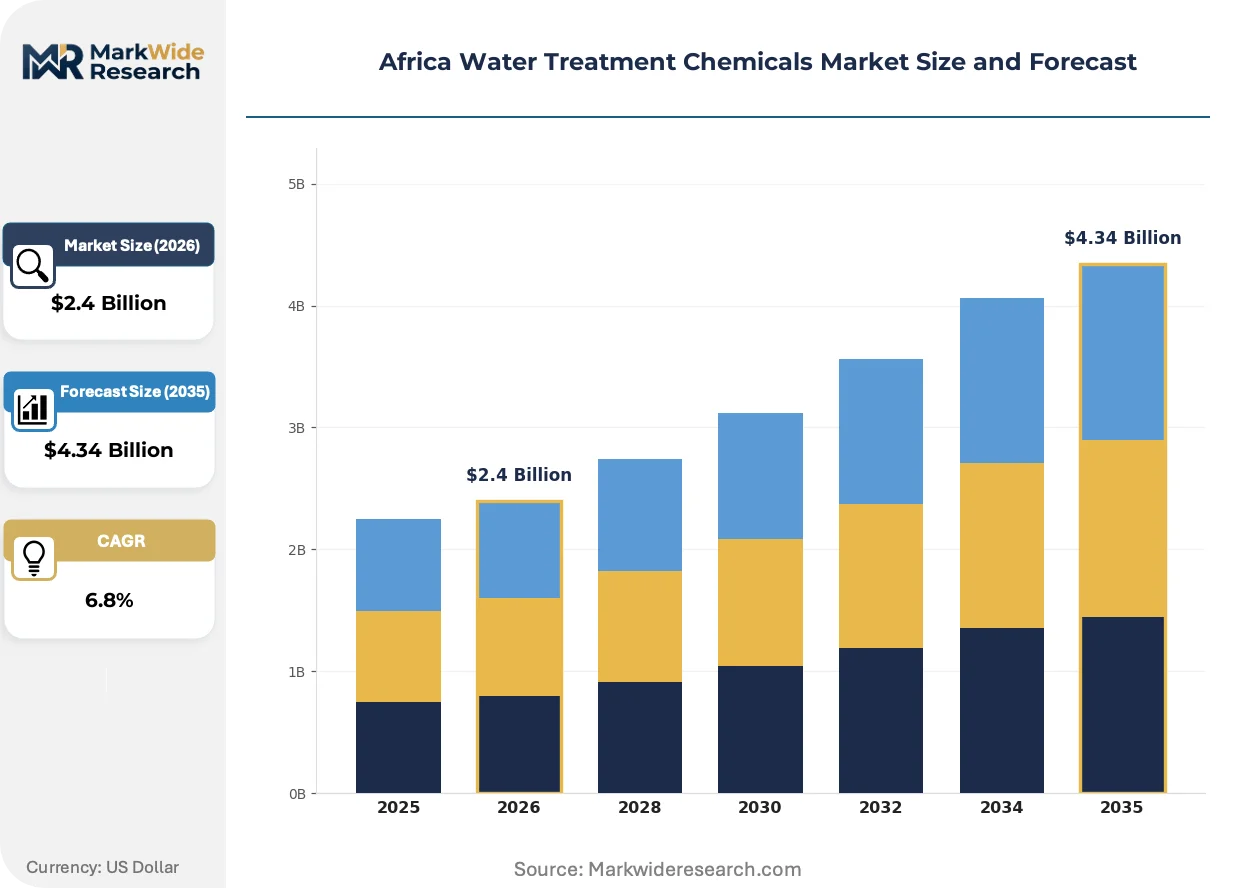
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulants, Flocculants, Disinfectants, pH Adjusters End User: Municipal, Industrial, Residential, Commercial Application: Water Treatment, Wastewater Treatment, Desalination, Swimming Pool Treatment Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Solenis, BASF, Ecolab Inc., Kemira, Dow, Veolia, SUEZ, Nouryon, Buckman, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Water Treatment Chemicals Market Strategic Shifts & Innovations
Digital dosing control and modular treatment architectures are displacing fixed-ratio chemical feeding systems across African municipal networks. These shifts compress capital deployment timelines while elevating real-time monitoring requirements.
Polymeric coagulant blends incorporating polyDADMAC and modified starches are decentralizing treatment plant design by enabling lower-dose clarification at variable raw water turbidities. Kenyan and Tanzanian utilities operating on Lake Victoria source waters are adopting these formulations to reduce sludge volumes. The technology is decentralizing operational expertise requirements, allowing smaller utilities to achieve consistent sub-1 NTU effluent without dedicated process engineers.
South Africa's National Water Act amendments are tightening residual disinfectant monitoring frequencies from weekly to continuous for systems serving populations above 100,000. This regulatory compression is forcing automation upgrades in chlorine analyzer deployment across Gauteng and Western Cape provinces. Bulk chemical suppliers are responding by bundling telemetry-equipped dosing skids with multi-year supply contracts to secure locked-in revenue streams.
Performance-based operator contracts are displacing traditional input-procurement models in Kenyan county water services. The Water Services Regulatory Board's WASREB scorecards tie vendor payments to delivered water quality outcomes rather than chemical tonnage delivered. This restructuring concentrates purchasing authority within Nairobi-based procurement consortia while marginalizing smaller regional distributors unable to underwrite outcome guarantees.
Africa Water Treatment Chemicals Market Segmentation
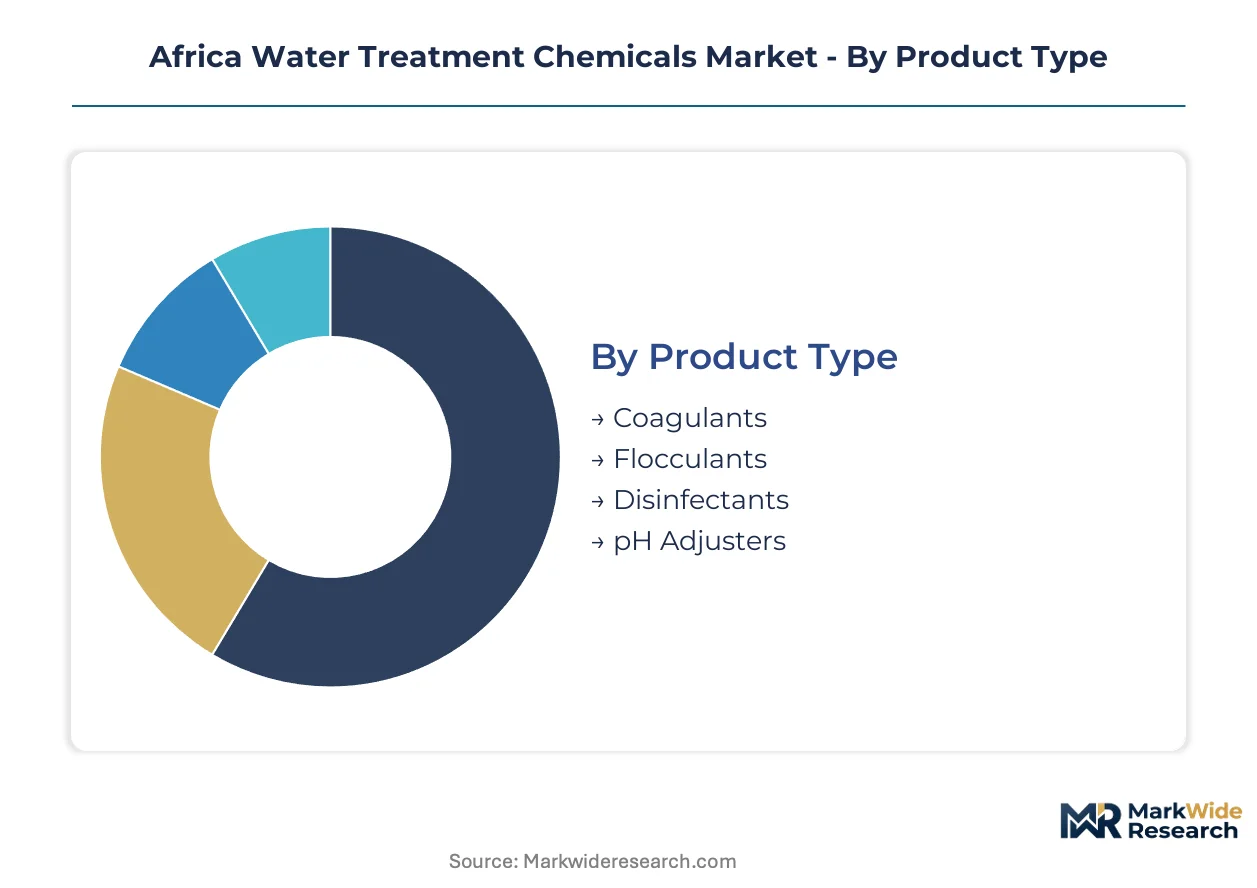
Segmentation in Africa's water treatment chemicals market reveals how regulatory compliance burdens concentrate differently across product formulations and end-use applications. Understanding these divisions clarifies where procurement centralization and certification requirements reshape supplier relationships.
Product Type:
South Africa's Blue Drop certification mandates documented dosing protocols for coagulants and disinfectants, while Nigeria's NAFDAC registration stretches 12-18 months for imported active ingredients.
- Coagulants:Aluminum sulfate and polyacrylamide polymers dominate municipal surface water clarification, targeting turbidity reduction below 1 NTU. Lagos State Water Corporation and Ghana Water Company are scaling procurement as coastal desalination multiplies membrane pretreatment requirements.
- Disinfectants:Chlorine-based oxidants and chlorine dioxide systems command premium pricing where viral inactivation standards apply. Kenya's Water Services Regulatory Board is adopting WHO-aligned residual chlorine specifications of 0.2-0.5 mg/L across 47 county utilities.
- Flocculants:PolyDADMAC and modified starch blends enable lower-dose clarification at variable raw water turbidities.
- pH Adjusters:Sulfuric acid and caustic soda compounds stabilize distribution system chemistry in high-alkalinity source waters.
Leading the category by volume: Coagulants. Expanding most quickly: Disinfectants.
End User:
Cost tier differentiation separates municipal bulk procurement from specialized industrial formulations requiring corrosion and scale control chemistries.
- Municipal:Absorbs the largest chemical volume through centralized procurement by Nigeria's state water corporations and South Africa's Department of Water and Sanitation. Performance-based operator contracts in Kenya tie vendor payments to delivered water quality outcomes.
- Industrial:Mining and power generation purchasers generate higher per-ton margins through specialized zero-liquid-discharge chemistries. South Africa's National Water Act amendments incentivize process water recovery investments.
- Residential:Containerized dosing systems penetrate informal settlements in Nairobi and Dar es Salaam where fixed infrastructure is uneconomical.
- Commercial:Hotels and office complexes in Angola's Luanda province drive demand under PROÁGUA program performance contracts.
Dominating procurement spend: Municipal utilities. Steepest margin expansion: Industrial segment.
Application:
Geographic concentration in West Africa's coastal cities drives divergence between membrane-based desalination chemistries and conventional surface water treatment.
- Water Treatment:Potable water production for urban utilities remains the core application, with jar testing and dosing optimization requirements concentrated in South Africa's Gauteng and Western Cape provinces.
- Wastewater Treatment:Reuse projects are multiplying in water-stressed regions, with Kenyan and Tanzanian utilities on Lake Victoria adopting polymeric blends to reduce sludge volumes.
- Desalination:Antiscalants and cleaning chemicals for membrane-based plants are scaling in Nigeria and Ghana.
- Swimming Pool Treatment:Residential and commercial pool maintenance drives steady demand for stabilized chlorine products.
Highest volume application: Water Treatment. Gaining share fastest: Wastewater Treatment.
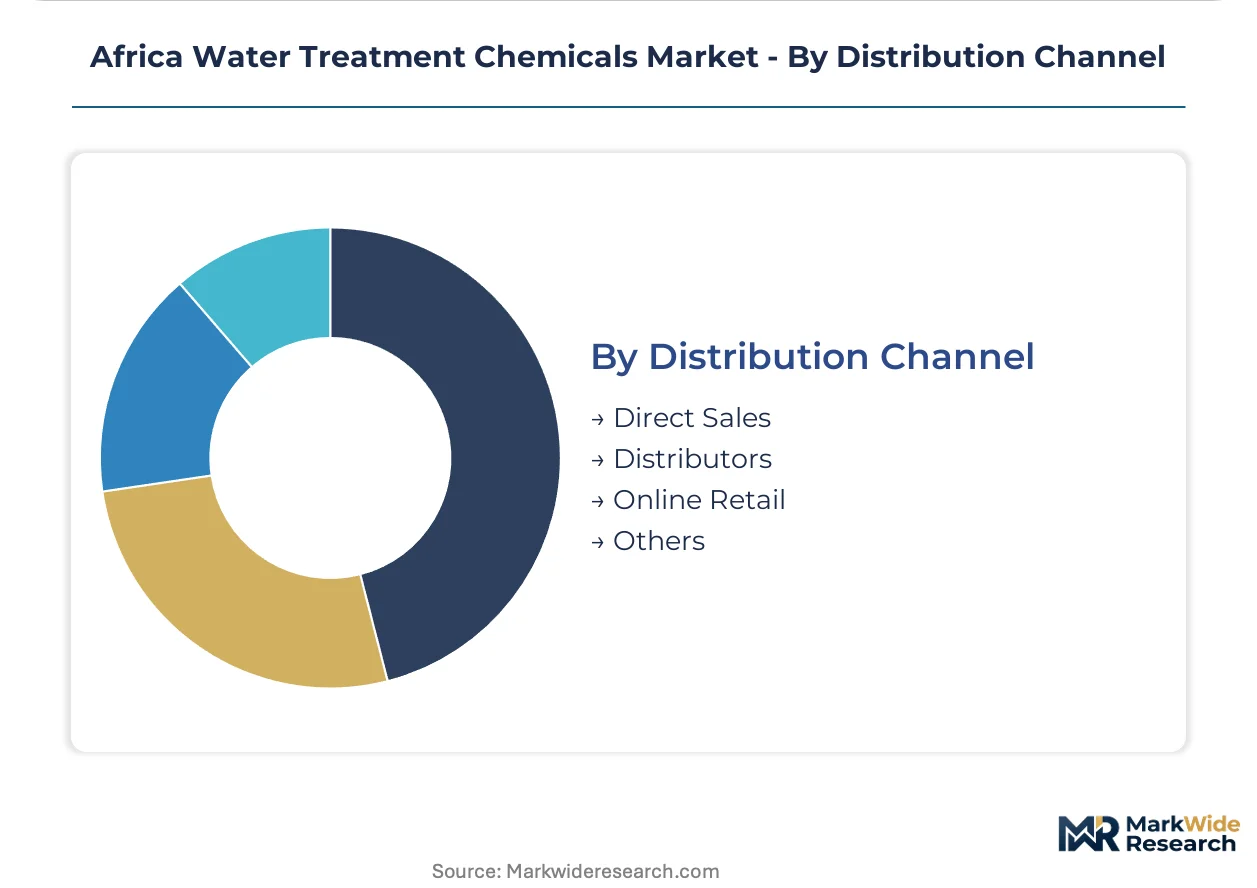
Distribution Channel:
Supply concentration in Chinese and European polyacrylamide manufacturers shapes how African distributors manage freight cost spikes and currency mismatch risks.
- Direct Sales:Multi-year supply agreements with qualified vendors lock in revenue streams for bulk chemical suppliers serving South Africa's Blue Drop-certified utilities.
- Distributors:Regional networks anchor positions for coastal desalination projects, though import dependency exposes margins to London Metal Exchange aluminum pricing volatility.
- Online Retail:Emerging channel for smaller commercial and residential purchasers seeking containerized dosing units.
- Others:Mobile dosing unit leasing and telemetry-equipped skid bundling with chemical supply contracts.
Primary channel by tonnage: Direct Sales. Channel climbing fastest: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bauxite deposits in Guinea's Boké region anchor aluminum sulfate supply chains feeding West African coagulant demand. Coastal infrastructure investments in Nigeria and Ghana reshape chemical logistics corridors.
Nigeria
Lagos State Water Corporation scales membrane-based desalination requiring specialized antiscalants. NAFDAC's 12-18 month product registration timeline complicates inventory planning for imported active ingredients. Port Harcourt and Kano municipal utilities concentrate procurement authority under state water corporation consolidation.
South Africa
Gauteng and Western Cape provinces drive disinfectant automation upgrades under continuous monitoring mandates. The Department of Water and Sanitation enforces Blue Drop certification locking in multi-year chemical supply agreements. Mining operators in the Platinum Belt adopt zero-liquid-discharge chemistries under National Water Act amendments.
Kenya
Lake Victoria source waters push utilities toward polyDADMAC blends reducing sludge volumes. WASREB scorecards tie vendor payments to delivered water quality outcomes rather than tonnage. Nairobi-based procurement consortia centralize purchasing authority across 47 county water utilities.
Ghana
Accra-Tema metropolitan expansion multiplies wastewater reuse project chemical requirements. Ghana Water Company scales coastal desalination plants requiring membrane pretreatment coagulants. Tema industrial zone power generation facilities generate specialized corrosion control demand.
Angola
Luanda and Benguela provinces tender performance-based contracts bundling chemical supply with operations. PROÁGUA program infrastructure investments expand potable water treatment capacity. Cabinda offshore oil operations create industrial water treatment chemical demand separate from municipal procurement.
Africa Water Treatment Chemicals Market Key Industry Players
Global majors compete with regional champions across formulation certification and distribution reach. The supplier base stratifies into three tiers: integrated chemical conglomerates with African manufacturing footprints, specialty chemical distributors serving coastal desalination clusters, and regional service providers bundling equipment with chemical supply. Consolidation pressure intensifies as municipal procurement centralization elevates compliance requirements. Dominant competitive moves include backward integration into aluminum sulfate production and strategic partnerships with membrane technology licensors.
Within the integrated chemical tier, BASF and Dow exemplify scale-driven positioning through diversified active ingredient portfolios. Solenis and Kemira occupy specialist positions anchored in regional distribution networks and coagulant manufacturing partnerships respectively. Ecolab Inc. represents the service-integration archetype, competing through bundled chemical supply and monitoring equipment contracts rather than standalone formulation sales.
| Leading Market Players |
|---|
| Solenis |
| BASF |
| Ecolab Inc. |
| Kemira |
| Dow |
| Veolia |
| SUEZ |
| Nouryon |
| Buckman |
| Others |
Cost & Logistics Intelligence
Backward integration into aluminum sulfate production anchors pricing power for suppliers serving South Africa's Blue Drop-certified utilities, while municipal procurement centralization across West Africa compresses margins for distributors lacking captive manufacturing. This structural divergence separates integrated chemical conglomerates from regional service providers competing on bundled telemetry-equipped dosing skids.
Pricing Analysis
Service bundling separates multi-year supply agreements with continuous monitoring equipment from unbundled chemical-only contracts. Three-tier pricing structure across premium certified-grade, standard municipal-grade, and economy industrial-grade formulations tracks Blue Drop compliance requirements. Cost compression in the standard tier is intensifying because Lagos State Water Corporation and Ghana Water Company are consolidating procurement authority under state-level tenders. Municipal utilities exhibit highest price sensitivity due to budget rigidities, while mining operators in South Africa's Platinum Belt accept premium pricing for specialized zero-liquid-discharge chemistries.
Supply Chain Analysis
Dual-sourcing requirements mandated by Kenya's Water Services Regulatory Board and South Africa's Department of Water and Sanitation force utilities to qualify multiple antiscalant and coagulant suppliers. Geographic supply concentration centers on Chinese polyacrylamide polymer manufacturers, European chlorine dioxide system producers, and Guinea's Boké bauxite deposits feeding West African aluminum sulfate production. Raw material dependencies include London Metal Exchange-tracked aluminum, acrylamide monomer, and sulfuric acid. Single-source vulnerability runs through Chinese polymer supply exposed to freight cost spikes. Distribution runs through regional distributors serving coastal desalination clusters and direct sales channels locking in multi-year municipal agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as municipal procurement centralization elevates technical compliance requirements beyond the reach of smaller regional distributors lacking certification investment capacity.
For Market Incumbents: Cement market position through backward integration into aluminum sulfate production using Guinea's bauxite supply chains, while acquiring telemetry-equipped dosing skid capabilities to defend against Ecolab's bundled service contracts. Lock in multi-year agreements with Kenya's Nairobi-based procurement consortia before WASREB scorecard adoption spreads to neighboring counties. Priority lever rests on Blue Drop certification maintenance as South Africa tightens residual disinfectant monitoring frequencies.
For New Entrants and Emerging Players: Mobile dosing unit leasing partnerships with informal settlement operators in Dar es Salaam and Nairobi offer the most penetrable entry point, bypassing fixed infrastructure requirements that favor established municipal suppliers. Target Angola's PROÁGUA performance-based contracts bundling chemical supply with operations as Luanda and Benguela provinces tender new capacity. Go-to-market angle should emphasize containerized chlorine dioxide systems requiring lower capital deployment than conventional fixed-plant alternatives.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chemical conglomerates seeking African manufacturing footprints, with IPO viability limited by market fragmentation. Long-term viability favors specialists with captive coagulant production and membrane chemistry capabilities aligned with coastal desalination expansion. Acquisition target archetype: regional distributors with established NAFDAC registration timelines and relationships with Nigerian state water corporations. Signal to watch is Kenya's WASREB scorecard adoption rate across remaining counties as indicator of procurement centralization momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Sulfate | Captive supply of coagulant raw materials insulates margins from London Metal Exchange volatility. |
| Telemetry-Equipped Dosing Skid Bundling | Multi-year chemical supply contracts with continuous monitoring meet South Africa's Blue Drop automation mandates. |
| Mobile Dosing Unit Deployment | Containerized systems penetrate Nairobi and Dar es Salaam informal settlements where fixed infrastructure fails. |
| NAFDAC Registration Acceleration | Compressed 12-18 month timelines unlock Nigerian state water corporation procurement opportunities. |
| PROÁGUA Performance Contract Bidding | Angola's bundled chemical-plus-operations tenders in Luanda and Benguela provinces concentrate revenue streams. |
Research Approach
Document review covered customs and trade data from Nigerian and South African port authorities, chemical industry association reports, and SEC filings from listed suppliers, complemented by interviews with municipal water utility procurement directors, plant managers at Ghana Water Company, distribution channel partners serving coastal desalination projects, and technical R&D directors at polyacrylamide manufacturers. Secondary validation drew from WHO drinking water quality guidelines, Kenya's WASREB regulatory publications, and Angola's PROÁGUA tender documentation. Bottom-up demand modeling triangulated against top-down market sizing from chemical consumption intensity benchmarks.
Cross-referencing historical procurement patterns from Lagos State Water Corporation and Nairobi-based county utilities against panel input from chemical supplier sales executives informed the analytical framework. Segmentation dimensions modeled include coagulant grade tier, municipal versus industrial end-use, membrane versus conventional application, and regional regulatory cluster aligned with Blue Drop, NAFDAC, or WASREB compliance pathways. CAGRs were derived from intensity-of-use projections tied to urban population growth and desalination capacity expansion across the analysis window. Industry-specific forecast inputs incorporated London Metal Exchange aluminum price trajectory assumptions and polyacrylamide import dependency ratios.
Caveats apply where alum price volatility, NAFDAC registration timeline extensions, or Kenyan county utility consolidation delays could materially shift the outlook. Forecasts reflect assumptions regarding continuous monitoring mandate adoption rates and coastal desalination project commissioning schedules. Deviation in Nigerian naira exchange rate stability or South African grid reliability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Swimming Pool Treatment Chemicals Market
Water & Sludge Treatment
Germany Water Treatment Chemicals Market
Water & Sludge Treatment
Enzymes for Water Treatment Market
Water & Sludge Treatment
Fluid Waste Disposal Systems Market
Water & Sludge Treatment
Industrial Water Treatment Chemicals Market
Water & Sludge Treatment
Australia Water Treatment Chemicals Market
Water & Sludge Treatment
North America Water Treatment Chemicals Market
Water & Sludge Treatment
Global Valves in Water and Wastewater Market
Water & Sludge Treatment
Global Sludge Treatment Chemicals Market
Water & Sludge Treatment
Global Municipal Water Treatment Chemicals Market
Water & Sludge Treatment
Internal Boiler Treatment Chemicals Market
Water & Sludge Treatment
Europe Water Treatment Chemicals Market
Water & Sludge Treatment
Europe Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
North America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
US Liquid Waste Management Market
Water & Sludge Treatment
Process Chemicals for Water Treatment Market