
 Europe Membrane Water Treatment Chemicals Market | 2026-2036
Europe Membrane Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Membrane Water Treatment Chemicals Market Foresight
Germany's chemical production corridor is tilting toward membrane-compatible formulations as industrial water reuse mandates tighten. Kemira leverages its Nordic R&D base to sustain leadership in antiscalant chemistry for reverse osmosis systems. Veolia Water Solutions and Technologies anchors European service contracts through integrated chemical-and-membrane offerings. Solenis competes on specialty biocide formulations tailored to food-grade membrane applications.
Membrane water treatment chemicals comprise formulated additives that prevent fouling, scaling, and biological degradation of polymeric membrane surfaces in pressure-driven filtration systems; these formulations typically incorporate active ingredients such as phosphonates, polyacrylates, and isothiazolinones dosed at 2–10 ppm depending on feedwater chemistry. Their primary industrial purpose is extending membrane operational life and stabilizing permeate flux across reverse osmosis, nanofiltration, and ultrafiltration trains. Biocides command margin concentration due to stringent ECHA authorization requirements that limit supplier pools, while cleaning chemicals represent the fastest-growing product category as membrane replacement economics favor aggressive chemical recovery protocols. Desalination applications in Southern Europe drive volume, though wastewater treatment for industrial reuse in the Rhine basin generates superior pricing power.
REACH registration obligations and the EU F-Gas Regulation constrain biocide active ingredient availability, forcing reformulation investments that reshape competitive economics. ECHA's substance evaluation timeline creates supply uncertainty for legacy membrane cleaners containing nonylphenol ethoxylates. The EU Drinking Water Directive's revised parametric values for emerging contaminants will expand membrane installation rates, directly lifting chemical demand. Stakeholders must monitor ECHA's candidate list expansions for substances targeted at membrane contact materials, as regulatory lag between restriction proposals and implementation dates compresses reformulation windows.
Market Dynamics
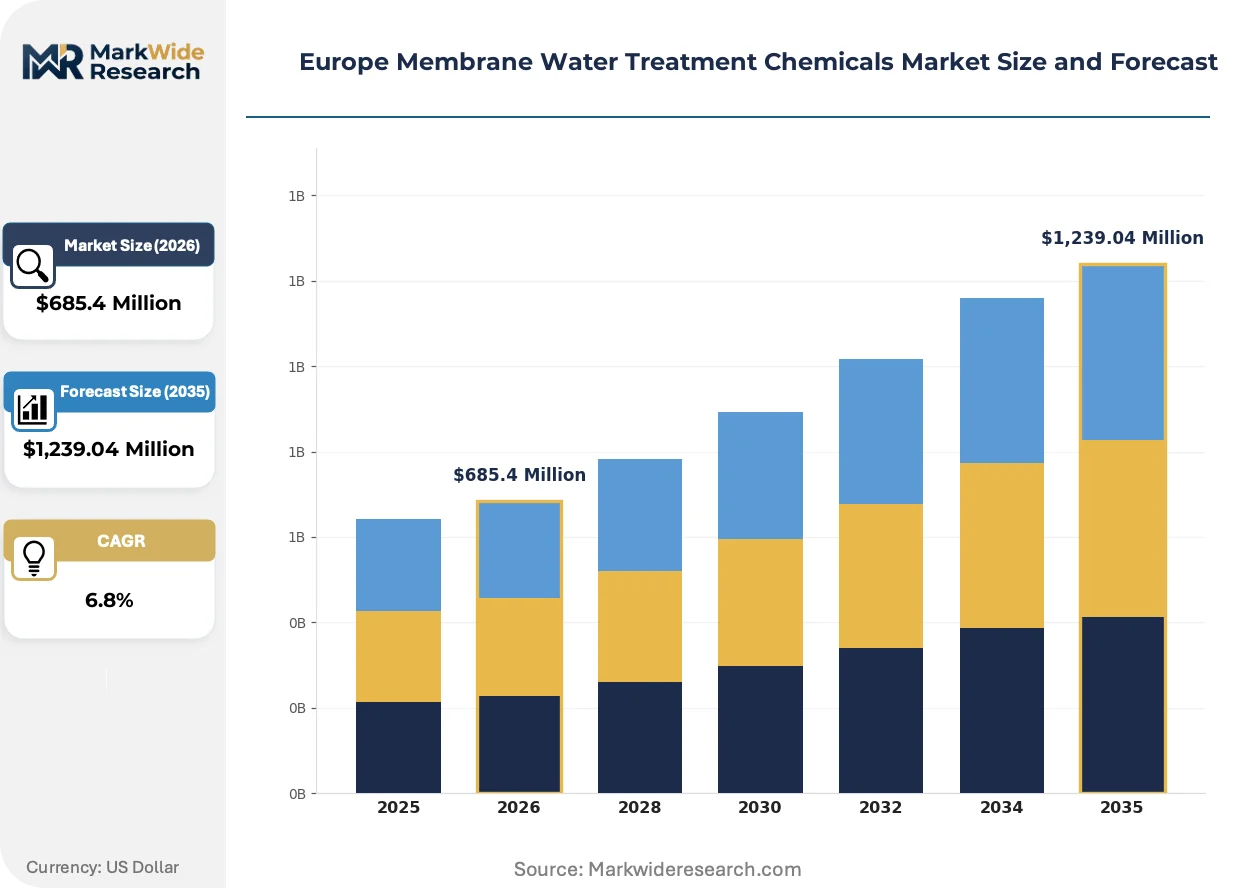
REACH substance evaluation timelines and the EU F-Gas Regulation are compressing reformulation windows for membrane treatment chemical suppliers, forcing simultaneous investments in biodegradable antiscalant chemistry and alternative biocide actives while membrane installation rates accelerate across Southern Europe's desalination corridor.
Growth Catalysts
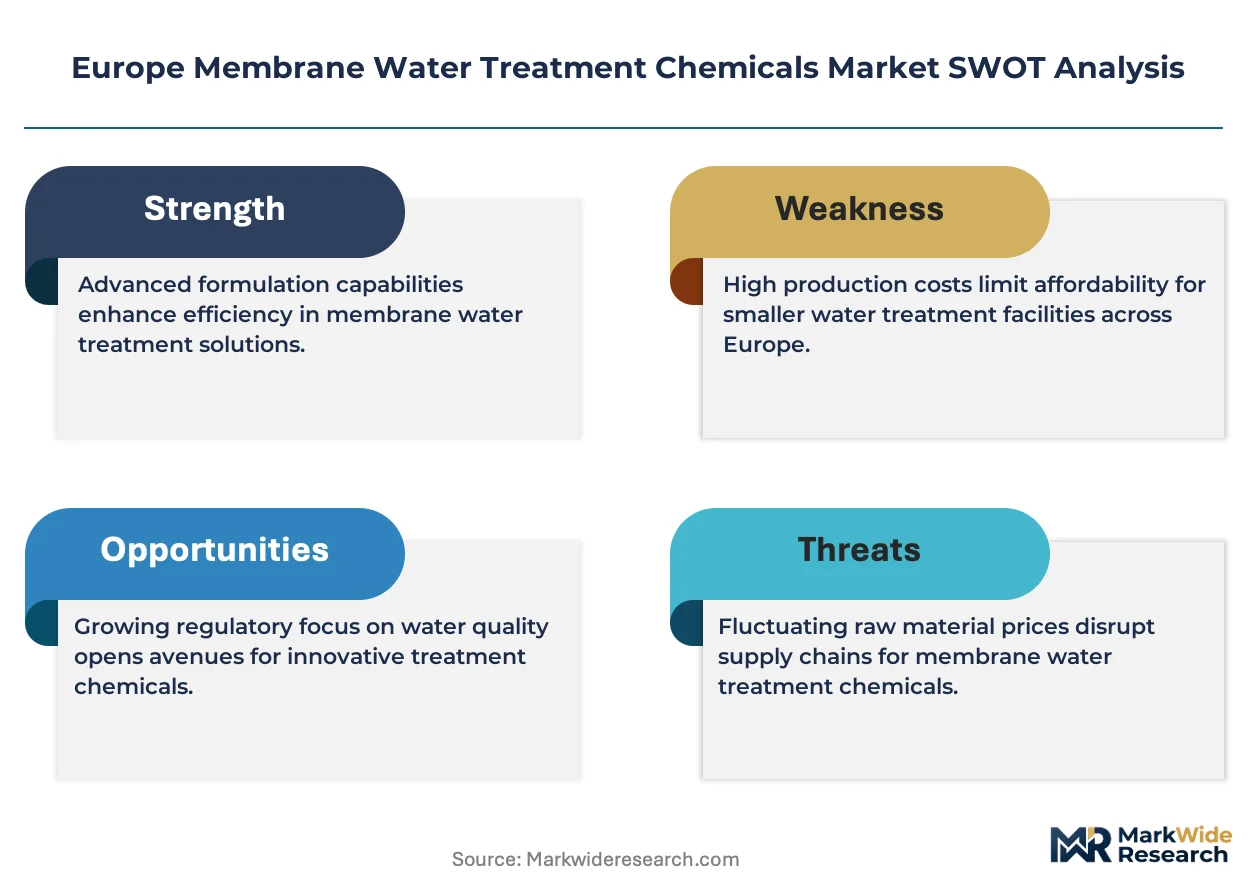
- EU Drinking Water Directive revision:Tightened parametric values for emerging contaminants mandate membrane-based removal systems in municipal treatment plants across France and Spain, directly expanding chemical dosing infrastructure requirements.
- Industrial water reuse mandates:Germany's Rhine-Ruhr chemical corridor faces regulatory pressure to close water loops, driving demand for high-performance antiscalants compatible with concentrated brine chemistries in reverse osmosis trains.
- Biodegradable antiscalant substitution:The EU Green Deal's chemical sustainability requirements accelerate displacement of phosphonate-heavy formulations toward polyaspartate and other bio-based polymers in membrane-compatible applications.
Market Restraints
- ECHA authorization bottlenecks:Isothiazolinone biocide active ingredients face prolonged evaluation timelines under REACH, constraining supplier pools and creating supply uncertainty for membrane preservation chemistry.
- Feedstock volatility in phosphonate supply:Phosphorous acid and phosphonic acid derivative prices fluctuate with phosphate rock export restrictions, compressing margin stability for antiscalant formulators serving the Mediterranean desalination market.
- Technical limitation in high-silica waters:Silica scaling remains inadequately controlled by conventional dispersants, forcing operators in Iberian Peninsula groundwater applications toward expensive thermal pretreatment or reduced membrane recovery rates.
Strategic Opportunities
- Eastern European municipal underpenetration:Poland and Romania's wastewater treatment infrastructure lags Western European membrane penetration rates, creating first-mover advantage for integrated chemical-and-membrane service providers.
- Food-grade membrane convergence:Dairy and beverage processors seek combined sanitation and membrane preservation protocols, opening specialty formulation demand for peracetic acid-compatible biocide systems.
- CSRD disclosure requirements:Corporate Sustainability Reporting Directive mandates drive industrial water users toward verifiable chemical consumption reductions, favoring suppliers offering predictive dosing optimization platforms.
Industry Challenges
- Reformulation talent scarcity:ECHA regulatory toxicologists and biodegradable polymer chemists command premium compensation, constraining mid-size formulators' ability to maintain compliance-paced R&D pipelines.
- Legacy cleaner substitution complexity:Nonylphenol ethoxylate-based membrane cleaners remain embedded in long-term municipal service contracts, complicating phase-out timelines despite ECHA candidate list inclusion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Membrane Water Treatment Chemicals Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biocides, Anti-fouling Agents, pH Adjusters, Cleaning Chemicals Application: Desalination, Wastewater Treatment, Industrial Processing, Drinking Water End User: Municipalities, Power Plants, Manufacturing Facilities, Food & Beverage Delivery Mode: Liquid, Powder, Granular, Tablets |
| Companies Covered | BWA Water Additives, Kemira, Veolia Water Solutions and Technologies, Solenis, Kurita Water Industries Ltd, Suez, Genesys International Ltd, Dow, Ecolab, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Membrane Water Treatment Chemicals Market Shifts & Advancements
Membrane water treatment chemical innovation centers on regulatory-compliant performance preservation, with suppliers racing to match biodegradable actives against legacy efficacy benchmarks while digital dosing integration reshapes service delivery economics.
Polyaspartate-based antiscalant chemistry is hybridizing with traditional phosphonate backbones to maintain calcium carbonate inhibition performance while meeting biodegradability thresholds. Municipal operators in Southern France and Catalonia pilot these hybrid formulations in brackish water reverse osmosis facilities. The technology is hybridizing supplier R&D roadmaps, compressing development timelines for pure bio-based alternatives while extending phosphonate market presence through transitional formulation strategies.
REACH restriction proposals targeting per- and polyfluoroalkyl substances in membrane contact materials force immediate supply chain audits across European membrane module manufacturers. Industrial consequence includes accelerated qualification of fluorine-free membrane substrates that demand reformulated cleaning chemistries compatible with altered surface energetics. The ultrafiltration segment faces greatest near-term disruption as hollow-fiber manufacturers revalidate entire chemical compatibility matrices.
Integrated chemical-and-membrane service contracts displace standalone chemical procurement in large industrial accounts, with Veolia and Suez bundling predictive maintenance algorithms with volume-guaranteed chemical supply. German automotive and chemical processors lead this transition, trading capital expenditure risk for operational expenditure predictability. Rhine basin industrial clusters exhibit fastest contract restructuring as water reuse targets tighten and membrane replacement economics favor vendor-managed inventory models.
Europe Membrane Water Treatment Chemicals Market Segmentation
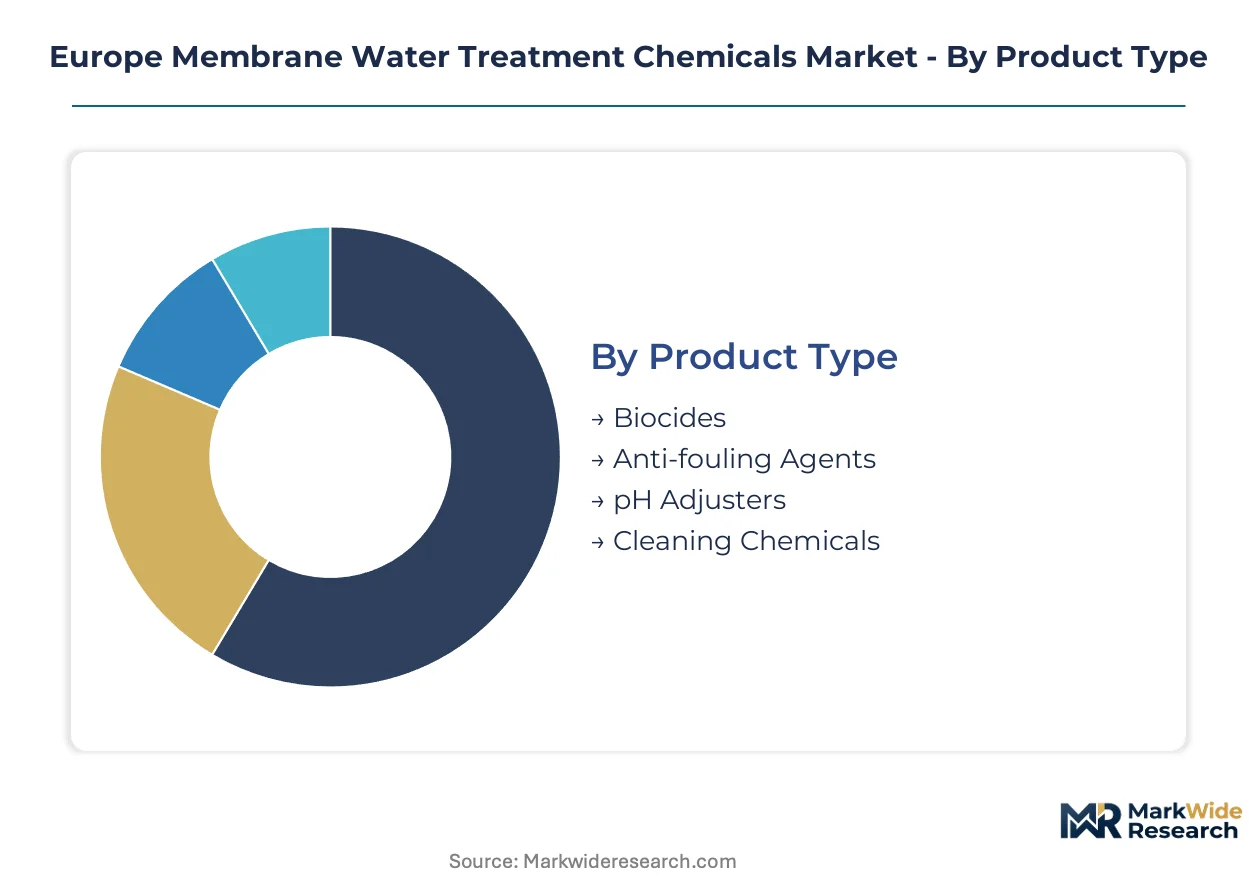
Segmentation in the Europe membrane water treatment chemicals market reveals divergent procurement rhythms and margin structures. Product lifecycles range from commodity biocides with annual contract renewals to specialized cleaning formulations locked into multi-year service agreements.
Product Type:
Cycle times vary dramatically across this category, with cleaning chemicals turning over fastest due to membrane recovery protocols while biocides face extended ECHA authorization timelines that freeze supplier rotations.
- Biocides:Isothiazolinone-based formulations preserve membrane integrity by controlling microbial biofilm formation on polyamide surfaces. Demand concentrates in Mediterranean desalination plants where warm feedwaters accelerate biological fouling, though REACH substance evaluation timelines constrain active ingredient substitution. ECHA authorization bottlenecks protect incumbent suppliers while limiting price competition.
- Cleaning Chemicals:Alkaline and acidic formulations remove organic foulants and mineral scale from membrane modules without compromising polymer integrity. German automotive processors in the Rhine-Ruhr corridor drive demand for high-frequency cleaning cycles as closed-loop water reuse mandates concentrate contaminants. These formulations represent the fastest-growing trajectory as membrane replacement economics favor aggressive chemical recovery over capital expenditure.
- Anti-fouling Agents:Dispersant polymers prevent colloidal particle aggregation on membrane surfaces, with polyacrylate formulations dominating municipal applications.
- pH Adjusters:Sulfuric acid and caustic soda solutions stabilize feedwater chemistry for optimal membrane performance, procured largely through commodity chemical channels.
Cleaning chemicals anchor the volume base while biocides gain share at the steepest rate due to tightening microbial control specifications.
Application:
Cost tier differentiation separates capital-intensive desalination projects from operational-expenditure-driven industrial reuse systems, with procurement patterns reflecting these structural distinctions.
- Desalination:Reverse osmosis trains on Spain's Mediterranean coast and France's Languedoc-Roussillon region require continuous antiscalant dosing to manage high-salinity feedwaters. Southern European municipalities fund these installations through concession financing, bundling chemical supply into long-term operating contracts.
- Wastewater Treatment:Membrane bioreactors in Germany's Rhine basin and the Netherlands treat municipal effluent for industrial reuse, demanding biocide preservation during intermittent operation. Tightening EU Urban Wastewater Treatment Directive standards expand membrane installation rates across Polish and Romanian infrastructure.
- Industrial Processing:Closed-loop cooling and boiler feed systems in Belgium's chemical cluster and northern Italy's textile belt prioritize antiscalant performance over biodegradability.
- Drinking Water:Nanofiltration systems in Paris and Barcelona metropolitan areas remove emerging contaminants under revised EU Drinking Water Directive parametric values.
Wastewater treatment anchors the volume base while drinking water applications expand most quickly on regulatory compliance timelines.
End User:
Customer type determines specification intensity, with food-grade membrane users demanding batch-certified formulations while power plants prioritize cost-optimized bulk supply.
- Municipalities:Public procurement frameworks across France, Spain, and Italy favor integrated chemical-and-membrane service contracts with decade-long durations. Veolia and Suez dominate these relationships through concession structures that bundle predictive maintenance with volume-guaranteed supply.
- Manufacturing Facilities:German automotive and chemical processors in Baden-Württemberg and North Rhine-Westphalia lead industrial water reuse adoption, specifying biodegradable antiscalants to meet CSRD disclosure requirements.
- Power Plants:Combined-cycle gas turbine facilities in the UK and Netherlands require continuous boiler feedwater treatment, procuring phosphonate antiscalants through annual tender processes.
- Food & Beverage:Dairy processors in Denmark and the Netherlands seek peracetic acid-compatible biocide systems that satisfy both sanitation and membrane preservation protocols.
Municipalities anchor the volume base while manufacturing facilities gain share at the steepest rate on industrial water reuse mandate timelines.
Delivery Mode:
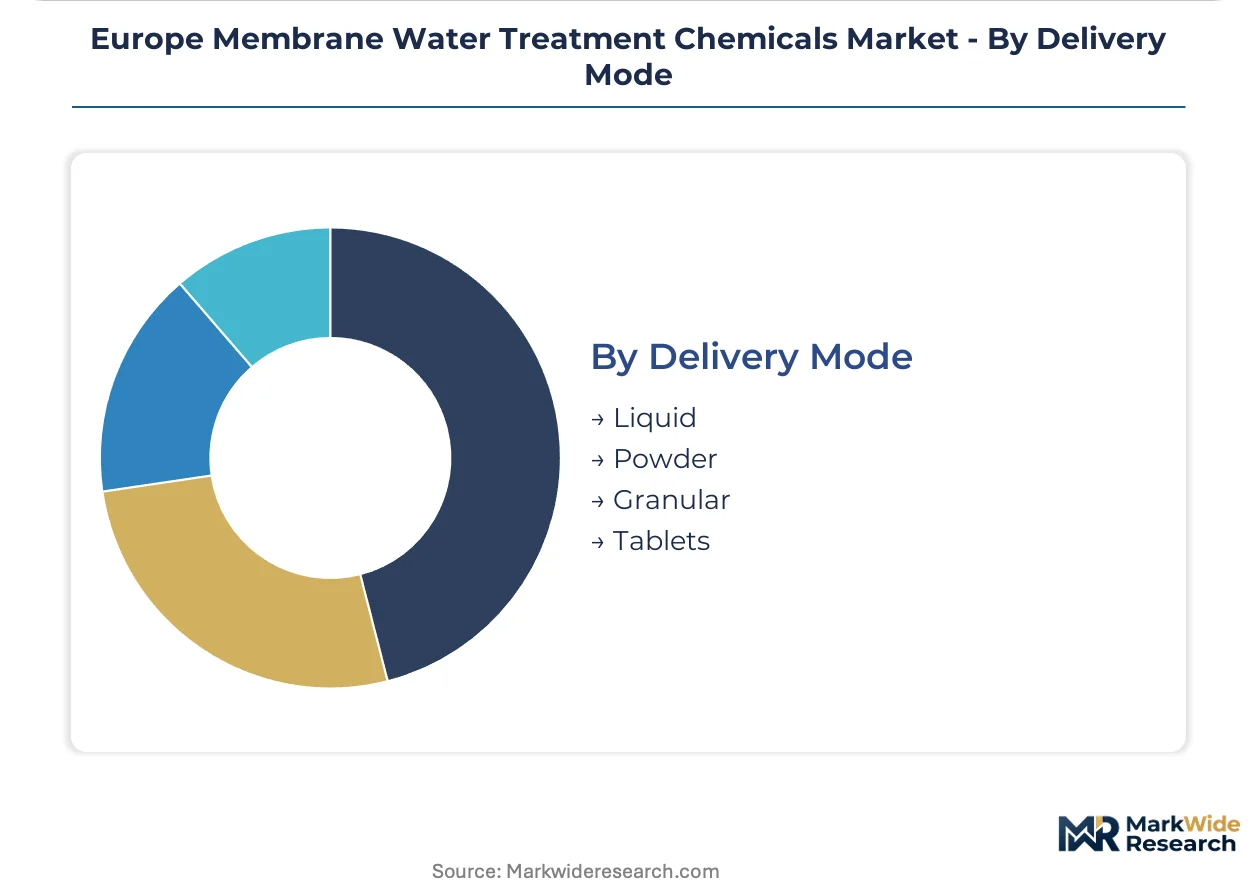
Supply concentration favors liquid formulations near coastal manufacturing hubs while powder and granular alternatives serve inland markets where transport economics reshape procurement.
- Liquid:Ready-to-dose solutions dominate large-scale desalination and industrial applications, with Kemira's Rotterdam terminal supplying Rhine corridor users through barge distribution.
- Powder:Concentrated formulations reduce transport costs for Eastern European municipal customers in Poland and Hungary with limited local blending capacity.
- Granular:Slow-dissolve biocide presentations suit remote desalination facilities with intermittent supply access, particularly on Spanish islands.
- Tablets:Unit-dosed cleaning chemicals target small-scale ultrafiltration users in food processing, simplifying operator handling and dosing accuracy.
Liquid delivery anchors the volume base while powder formulations gain share at the steepest rate on inland market expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central European membrane chemical logistics, connecting Rotterdam's chemical terminals to Bavarian industrial clusters through inland barge networks that slash transport costs for liquid antiscalant formulations.
Germany
Rhine-Ruhr chemical processors and Baden-Württemberg automotive manufacturers drive antiscalant consumption as closed-loop water reuse mandates tighten. REACH registration obligations force continuous reformulation of phosphonate-based products. Munich's semiconductor fabs demand ultrapure water systems that anchor biocide preservation chemistry volumes.
France
Languedoc-Roussillon desalination plants and Paris metropolitan nanofiltration installations expand membrane capacity under revised EU Drinking Water Directive parametric values. ECHA substance evaluations constrain isothiazolinone biocide availability. Lyon's chemical engineering cluster incubates biodegradable polyaspartate antiscalant startups targeting Mediterranean brackish water applications.
Spain
Mediterranean coast reverse osmosis trains and Balearic Islands remote desalination facilities require continuous chemical dosing against warm-feedwater biofouling. EU F-Gas Regulation limits legacy membrane cleaner actives. Barcelona's water technology hub concentrates service engineering talent for integrated chemical-and-membrane contracts.
Netherlands
Rotterdam's chemical terminal infrastructure and North Sea Canal industrial belt sustain bulk liquid antiscalant distribution across the Rhine corridor. CSRD disclosure requirements push manufacturing facilities toward verifiable chemical consumption reductions. Eindhoven's high-tech campus drives ultrapure water demand for semiconductor fabrication.
Italy
Lombardy textile processors and Emilia-Romagna food manufacturers adopt membrane bioreactors for wastewater reuse compliance. ECHA candidate list restrictions on nonylphenol ethoxylates complicate legacy cleaner phase-outs. Milan's industrial water service providers bundle predictive dosing platforms with chemical supply contracts.
Europe Membrane Water Treatment Chemicals Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in formulated chemistry. The European membrane water treatment chemicals market structures around three tiers: multinational water service conglomerates bundling chemical supply with membrane assets, regional formulators with REACH registration expertise, and commodity chemical distributors serving price-sensitive municipal tenders. Strategic moves concentrate on biodegradable antiscalant R&D partnerships and predictive dosing platform acquisitions that lock in long-term service contracts.
Among Nordic-European formulators, Kemira exemplifies the integrated chemical-and-logistics archetype through its Rotterdam terminal and Rhine barge distribution network. Veolia Water Solutions and Technologies occupies the platform integrator position, anchoring concession-based service contracts that bundle membrane maintenance with volume-guaranteed chemical supply. Solenis represents the specialty formulation tier, with its portfolio weighted toward food-grade membrane applications requiring peracetic acid-compatible biocide systems.
| Leading Market Players |
|---|
| BWA Water Additives |
| Kemira |
| Veolia Water Solutions and Technologies |
| Solenis |
| Kurita Water Industries Ltd |
| Suez |
| Genesys International Ltd |
| Dow |
| Ecolab |
| Others |
Supply & Pricing Matrix
Phosphonate precursor manufacturing concentrates in China's phosphate processing belt, anchoring cost structures for European antiscalant formulators and compressing margin pools downstream toward membrane service integrators who bundle chemicals with predictive maintenance platforms.
Pricing Analysis
REACH substance evaluation timelines dictate the pricing tier structure across biocide formulations, separating ECHA-authorized premium grades from standard phosphonate-based antiscalants and economy-grade pH adjusters procured through commodity channels. Price differentiation rests on certification grade and volume scale, with municipal desalination tenders favoring long-term contract stability over spot purchasing. Cost compression in standard antiscalants is intensifying because biodegradable polyaspartate substitution demands R&D premium recovery. Power plants exhibit highest price sensitivity due to annual tender processes, while food-grade membrane users accept premium positioning for batch-certified formulations.
Supply Chain Analysis
Export-control scrutiny on phosphorus-based chemical precursors limits raw material flows from Chinese processors to European formulators, exposing supply chains to regulatory friction. Geographic supply concentration centers on China for phosphonic acid derivatives, Germany for specialty polymer R&D, and the Netherlands for Rotterdam terminal distribution. Raw material dependencies draw from phosphate rock, phosphorous acid, and isothiazolinone active ingredients. Single-source vulnerability in biocide actives creates structural risk as ECHA evaluations constrain supplier pools. Distribution runs through Rhine barge networks connecting Rotterdam to Rhine-Ruhr industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe membrane water treatment chemicals market represents a high-growth disruption as the EU Drinking Water Directive's revised parametric values for emerging contaminants force membrane installation rates upward across municipal infrastructure.
For Market Incumbents: Entrench market position through backward integration into biodegradable polymer feedstocks and captive qualification of REACH-compliant biocide actives before ECHA authorization bottlenecks deepen. Vertical control over polyaspartate supply chains defends margin pools against commodity phosphonate price volatility. Priority investment targets predictive dosing platform acquisitions that lock municipal customers into decade-long service contracts. For New Entrants and Emerging Players: Eastern European municipal underpenetration offers first-mover advantage in Poland and Romania where wastewater treatment infrastructure lags Western European membrane adoption rates. Food-grade membrane applications for dairy and beverage processors present specialty formulation white space demanding peracetic acid-compatible biocide systems. Go-to-market execution should anchor on integrated chemical-and-membrane service bundling rather than standalone chemical procurement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across predictive dosing platform development as software economics displace capital-heavy chemical manufacturing. Long-term viability over the next decade favors platform integrators over pure-play formulators. Acquisition targets should exhibit REACH registration expertise paired with municipal concession relationships. The signal to watch is ECHA candidate list expansion pace as a leading indicator of reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Antiscalant R&D Partnership | Accelerates polyaspartate formulation qualification for Mediterranean brackish water reverse osmosis facilities. |
| Predictive Dosing Platform Acquisition | Locks German automotive and chemical processors into vendor-managed inventory models under CSRD disclosure pressure. |
| REACH Registration Portfolio Expansion | Secures incumbent supplier position as ECHA authorization timelines constrain biocide active ingredient pools. |
| Rhine Barge Distribution Capacity Addition | Reduces liquid antiscalant delivery costs for Rotterdam-terminal-served industrial clusters. |
| Food-Grade Membrane Certification Investment | Opens peracetic acid-compatible biocide demand from Denmark and Netherlands dairy processors. |
Research Methodology
Initial hypotheses were tested against primary input from membrane plant operators, chemical procurement leads at municipal water utilities, technical R&D directors at formulator companies, and ECHA regulatory affairs specialists, then refined through secondary validation. Primary fieldwork combined structured interviews with downstream end-users and channel partners. Secondary sources included REACH registration databases, ECHA substance evaluation timelines, EU customs trade data for phosphonate imports, and Cefic chemical industry reports. Bottom-up membrane installation forecasts were triangulated against top-down chemical consumption intensity models.
Demand-supply balance framing anchored the forecast framework, modeling consumption across product type, application, end user, and delivery mode dimensions over the projection horizon. CAGRs were derived from segmented growth rate analysis applied to baseline intensity metrics. Industry-specific inputs incorporated EU Drinking Water Directive implementation timelines, industrial water reuse mandate compliance deadlines, and ECHA authorization pipeline status.
Practitioners should monitor ECHA candidate list expansions, EU F-Gas Regulation enforcement intensity, and phosphate rock export restriction announcements for early signals of forecast deviation. Forecasts reflect assumptions around regulatory implementation pacing and substitution technology readiness. Material shifts in REACH substance evaluation timelines or breakthroughs in fluorine-free membrane substrate qualification would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Water Softening Systems Market
Water & Sludge Treatment
Global Flocculant and Coagulant Market
Water & Sludge Treatment
Global Municipal Water Treatment Chemicals Market
Water & Sludge Treatment
Membrane Filtration Systems Market
Water & Sludge Treatment
South America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Drilling Waste Management Services Market
Water & Sludge Treatment
Swimming Pool Treatment Chemicals Market
Water & Sludge Treatment
Water Treatment Polymers Market
Water & Sludge Treatment
Sludge Heater Market
Water & Sludge Treatment
Polish Water Treatment Chemicals Market
Water & Sludge Treatment
Global Valves in Water and Wastewater Market
Water & Sludge Treatment
Asia-Pacific Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Enzymes for Water Treatment Market
Water & Sludge Treatment
Electrodeionization (EDI) Technology Market
Water & Sludge Treatment
Sedimentation and Centrifugation Market
Water & Sludge Treatment
Fluid Waste Disposal Systems Market