
 United Kingdom Water Treatment Chemicals Market | 2026-2036
United Kingdom Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Water Treatment Chemicals Market Analytics
Multi-source procurement among UK water utilities is consolidating as Thames Water and United Utilities seek supply security after recent chemical shortages. BASF leverages its Ludwigshafen production network to sustain bulk deliveries of polyacrylamide coagulants into British municipal contracts. Kemira competes through its Runcorn manufacturing footprint, which anchors chlorine dioxide supply for industrial customers across Cheshire and Merseyside.
Water treatment chemicals comprise formulated substances including aluminium sulphate, polyaluminium chloride, sodium hypochlorite, and phosphonate-based corrosion inhibitors, dosed at ppm levels to remove suspended solids, control microbial growth, and protect distribution infrastructure from degradation. These chemicals serve the essential function of ensuring potable water meets microbiological and chemical safety thresholds before reaching consumer taps. Coagulating agents dominate product value due to irreplaceable demand in turbidity removal across both municipal and industrial intake systems. Disinfectants command premium positioning where residual chlorine maintenance is mandated by public health directives. Industrial water applications represent the fastest-expanding consumption segment as food and beverage processors in the Midlands adopt zero-liquid-discharge protocols requiring specialized antiscalant chemistries.
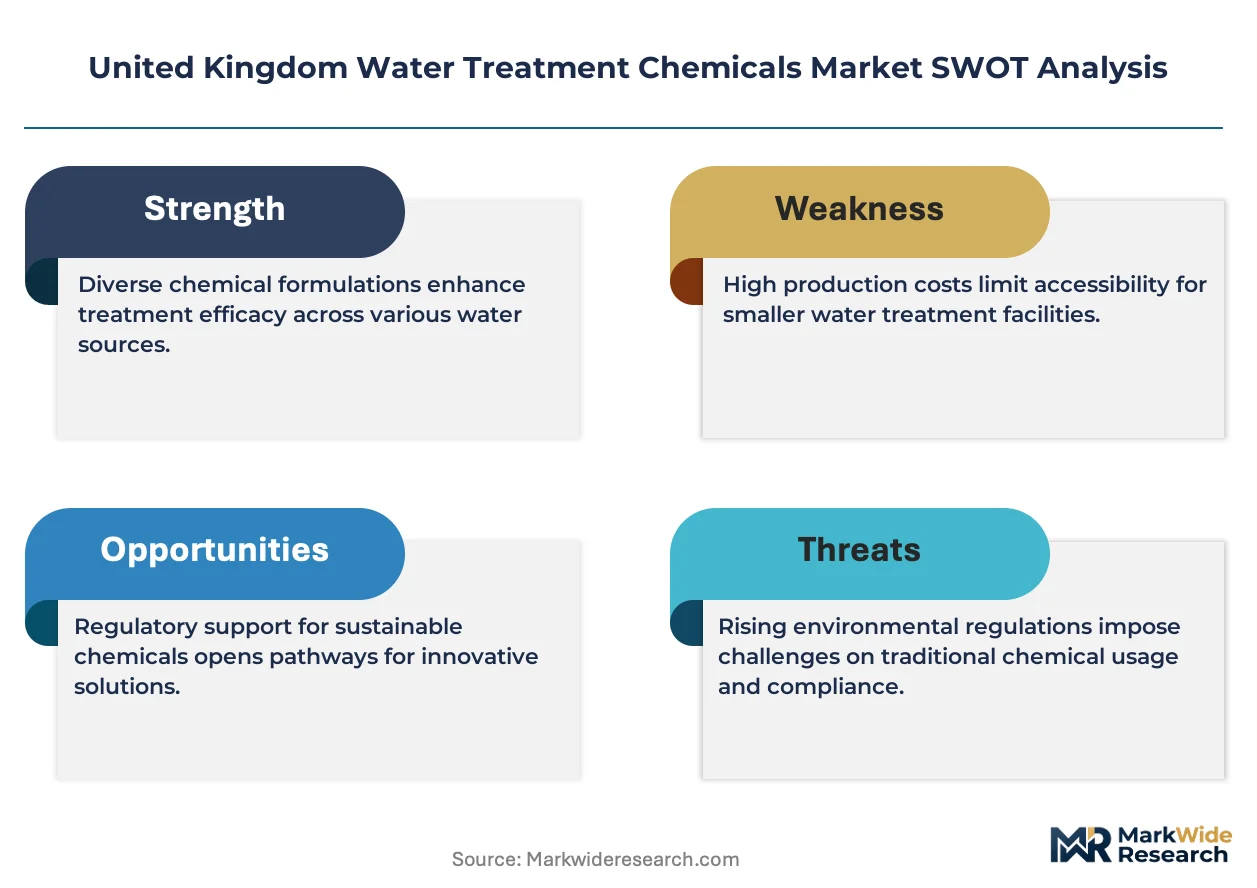
The UK Environment Agency enforces discharge permits under the Environmental Permitting Regulations, while Drinking Water Inspectorate standards mandate residual disinfectant thresholds that shape procurement specifications for utilities. REACH compliance through ECHA restricts certain biocidal active substances, forcing reformulation investments among suppliers serving the British market. Stakeholders must monitor the divergence between post-Brexit UK chemical regulation and retained EU law, as divergence risk threatens product registration continuity and cross-border formulation approvals.
Market Dynamics
The UK Environment Agency's tightening discharge consent limits under the Water Resources Act are forcing municipal and industrial operators to upgrade chemical dosing infrastructure, consolidating procurement around suppliers capable of delivering advanced coagulants and corrosion inhibitors at scale.
Growth Catalysts
- Zero-liquid-discharge mandates:Food and beverage processors across the Midlands face compulsory effluent elimination targets, driving specialized antiscalant consumption for closed-loop cooling systems.
- England's industrial corridor concentration:Manufacturing facilities in North West England confront intensifying regulatory pressure on effluent quality, expanding chemical procurement volumes for on-site pre-treatment.
- Drinking Water Inspectorate residual chlorine thresholds:Mandatory microbiological safety standards sustain irreplaceable demand for sodium hypochlorite and chlorine dioxide across municipal distribution networks.
Market Restraints
- Aluminium sulphate feedstock volatility:Sulphuric acid and bauxite price swings compress margins for coagulant manufacturers serving British utilities.
- REACH-UK divergence friction:Post-Brexit regulatory misalignment with retained EU law threatens product registration continuity for biocidal active substances.
- Membrane bioreactor substitution:Advanced physical separation technologies displace chemical-dependent clarification in select industrial wastewater applications.
Strategic Opportunities
- Scotland's municipal consolidation:Scottish Water's regional procurement centralization creates volume contracts for suppliers offering integrated chemical-plus-service packages.
- Phosphonate corrosion inhibitor convergence:Hybrid chemistries combining scale inhibition with microbial control address dual regulatory mandates in single-dose formulations.
- Digital dosing system integration:IoT-enabled ppm-level automation opens service-revenue streams beyond commodity chemical supply.
Industry Challenges
- Process control engineering scarcity:Utilities struggle to recruit specialists capable of optimizing chemical dosing algorithms across variable raw water quality.
- Legacy infrastructure retrofit complexity:Victorian-era distribution networks require staged chemical upgrade programs without service interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Water Treatment Chemicals Market |
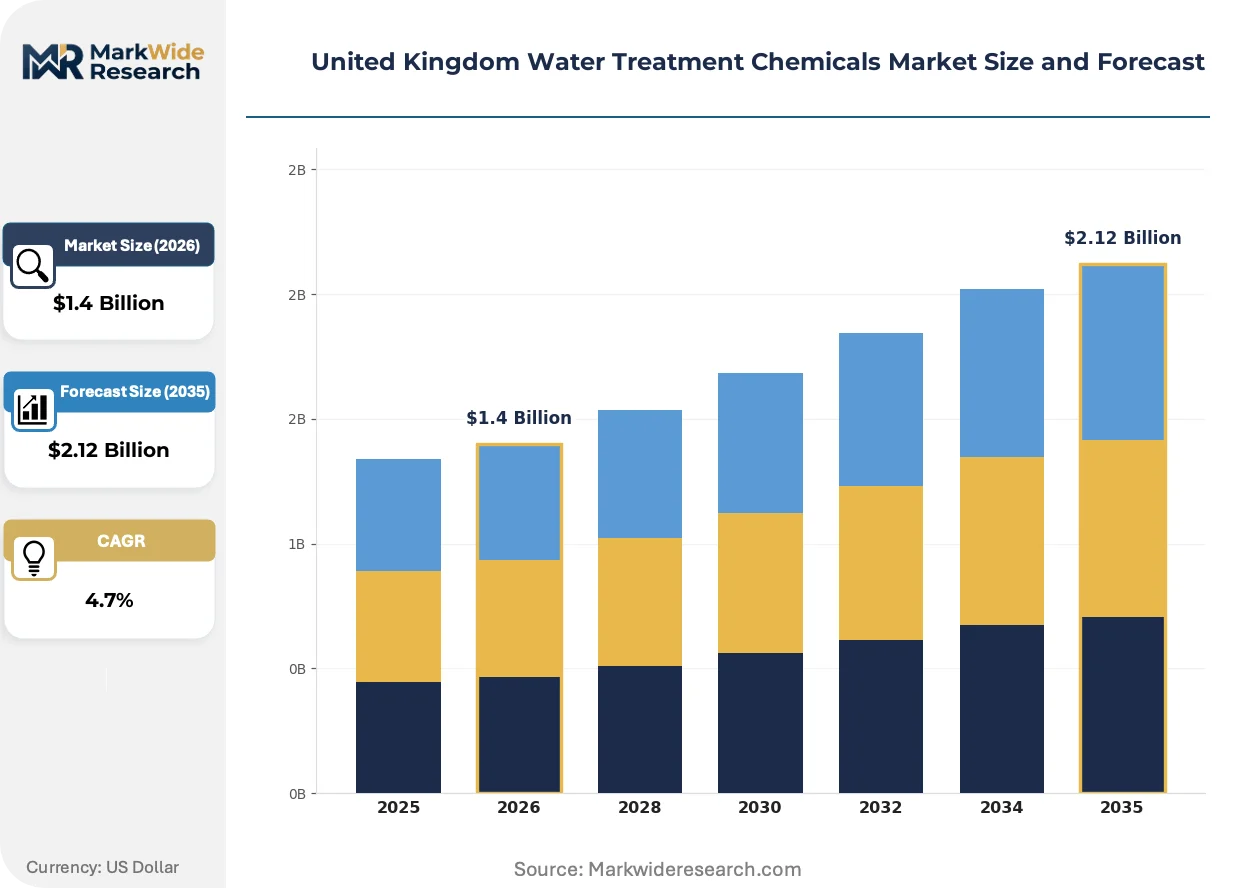
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.12 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulating Agents, Disinfectants, Corrosion Inhibitors, pH Adjusters Application: Municipal Wastewater, Potable Water Treatment, Industrial Water, Swimming Pools End User: Public Utilities, Manufacturing Facilities, Commercial Establishments, Residential Consumers Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesale Suppliers |
| Companies Covered | Veolia Water Solutions & Technologies, BASF, Ecolab, Nouryon, Akzo Nobel, Kemira, SNF, Kurita Water Industries, Solenis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Water Treatment Chemicals Market Evolving Landscape
Electrochemical generation technologies are displacing bulk chemical delivery models across British water utilities, while regulatory divergence post-Brexit forces reformulation investments and digital traceability systems reshape supplier accountability.
On-site electrochlorination systems are electrifying sodium hypochlorite supply chains for municipal operators. Thames Water and United Utilities have accelerated adoption of brine-to-hypochlorite generation units at treatment facilities, eliminating hazardous bulk tanker deliveries. This distributed production model is electrifying traditional chemical logistics structures and compressing regional distributor margins.
The UK Environment Agency's implementation of stricter Environmental Permitting Regulations is mandating real-time effluent quality monitoring for industrial discharge consents. Manufacturing facilities across Cheshire and Merseyside must now install continuous sampling infrastructure with automated chemical adjustment. Metal finishing and chemical processing plants face the steepest compliance costs, driving demand for adaptive dosing control systems.
Multi-year chemical service agreements are replacing spot procurement across England's municipal sector. Water utilities now contract for guaranteed turbidity removal outcomes rather than tonnage deliveries, transferring technical risk to suppliers. This performance-based model is most advanced in North West England, where United Utilities has piloted full-responsibility coagulant management contracts with embedded efficiency penalties.
United Kingdom Water Treatment Chemicals Market Segmentation
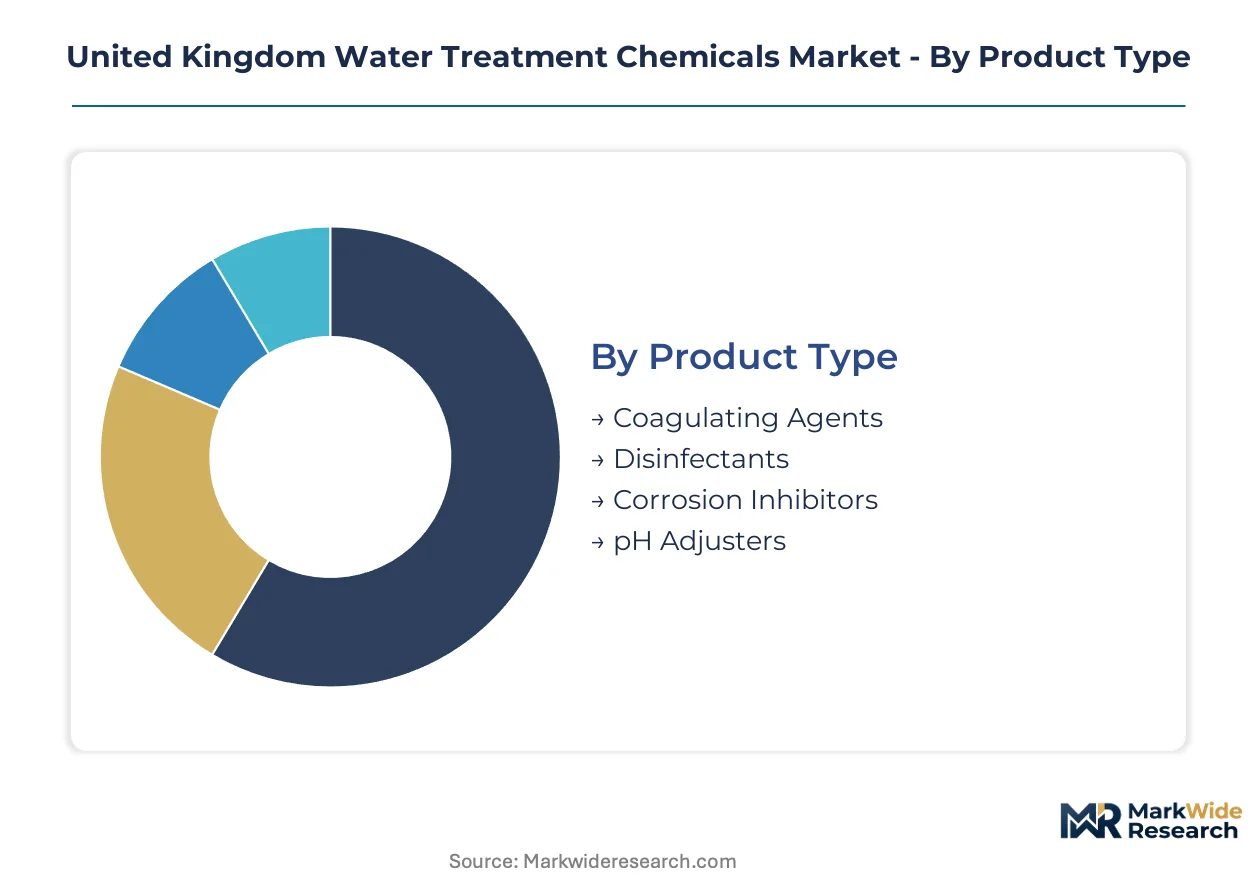
Segmentation of the United Kingdom water treatment chemicals market reveals how procurement priorities diverge between municipal utilities seeking bulk security and industrial operators demanding precision formulations. Understanding these fault lines exposes where suppliers can defend margin through technical differentiation versus where volume contracts dominate commercial terms.
Product Type:
Coagulating agents command the largest volume share while corrosion inhibitors extract premium pricing through specialized phosphonate chemistries.
- Coagulating Agents:Aluminium sulphate and polyaluminium chloride formulations precipitate suspended solids through charge neutralization at intake points. Demand concentrates in North West England municipal facilities facing the Environment Agency's tightened turbidity discharge limits under the Water Resources Act.
- Disinfectants:Sodium hypochlorite and chlorine dioxide maintain residual microbiological protection across distribution networks. Thames Water and United Utilities are electrifying supply chains through on-site electrochlorination systems, displacing hazardous bulk tanker logistics.
- Corrosion Inhibitors:Phosphonate-based chemistries protect Victorian-era distribution infrastructure from degradation.
- pH Adjusters:Sulphuric acid and caustic soda dosing stabilizes treatment process efficiency.
Mature deployment sits with coagulating agents across established municipal clarification infrastructure. Newer deployment is concentrated in corrosion inhibitors as hybrid scale-microbial formulations address dual regulatory mandates.
Application:
Industrial water applications are climbing the fastest as food and beverage processors adopt zero-liquid-discharge protocols requiring specialized antiscalant chemistries.
- Municipal Wastewater:Activated sludge enhancement and tertiary polishing chemicals serve England and Scotland's regional utilities. Scottish Water's procurement centralization creates volume opportunities for integrated chemical-plus-service suppliers.
- Potable Water Treatment:Coagulation, filtration, and disinfection chemistries must meet Drinking Water Inspectorate residual chlorine thresholds. Compliance mandates sustain irreplaceable sodium hypochlorite demand across distribution networks.
- Industrial Water:Closed-loop cooling and boiler treatment chemistries support manufacturing process reliability.
- Swimming Pools:Chlorine stabilizers and pH buffers maintain recreational water quality standards.
Procurement sophistication peaks in municipal wastewater where performance-based contracts transfer technical risk to suppliers. Industrial water is gaining share fastest as environmental permitting tightens on manufacturing effluent quality.
End User:
Public utilities anchor volume procurement while manufacturing facilities drive formulation innovation through site-specific effluent challenges.
- Public Utilities:Regional water and wastewater authorities across England and Scotland consolidate multi-year chemical service agreements. United Utilities' piloted full-responsibility coagulant management contracts embed efficiency penalties and transfer operational risk.
- Manufacturing Facilities:Metal finishing and chemical processing plants in Cheshire and Merseyside face steep compliance costs under real-time effluent monitoring mandates.
- Commercial Establishments:Hotels, hospitals, and office complexes maintain on-site water treatment for heating and cooling systems.
- Residential Consumers:Point-of-use filtration and pool maintenance chemicals represent fragmented, price-sensitive demand.
Contract maturity concentrates with public utilities where multi-source procurement is consolidating after recent chemical shortages. Manufacturing facilities are expanding most quickly as regulatory pressure intensifies on industrial corridor effluent quality.
Distribution Channel:
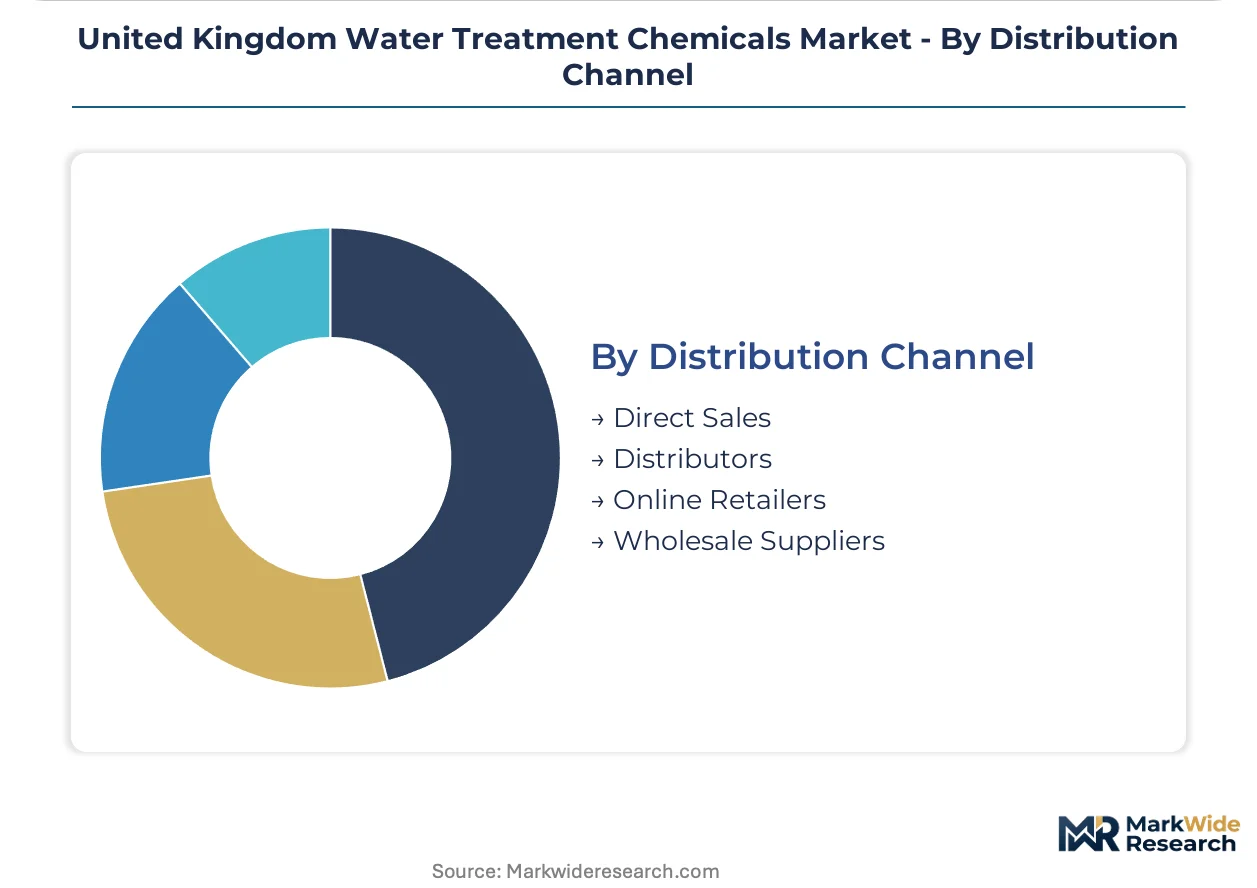
Direct sales capture municipal utility contracts while distributor networks fragment across smaller industrial and commercial accounts.
- Direct Sales:Bulk coagulant and disinfectant supply to Thames Water, United Utilities, and Scottish Water bypasses intermediaries. BASF leverages its Ludwigshafen production network for sustained bulk polyacrylamide deliveries into British municipal contracts.
- Distributors:Regional chemical distributors serve fragmented industrial and commercial demand across the Midlands and North West England.
- Online Retailers:E-commerce platforms capture residential pool chemicals and point-of-use treatment consumables.
- Wholesale Suppliers:Volume aggregators supply smaller municipal operators and industrial facilities without direct manufacturer relationships.
Channel concentration favors direct sales for high-volume municipal procurement. Distributor relevance persists where geographic fragmentation and smaller order sizes prevent manufacturer economies in customer service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminium sulphate feedstock from North Sea bauxite refineries anchors chemical production geography across British industrial corridors. Manufacturing concentration clusters around legacy coagulant facilities in Cheshire and Merseyside, while municipal demand disperses across England and Scotland's water utility networks.
North West England
Metal finishing plants in Cheshire drive phosphonate corrosion inhibitor consumption under real-time effluent monitoring mandates. The UK Environment Agency's Environmental Permitting Regulations enforce continuous sampling infrastructure at manufacturing discharge points. Chemical processing clusters around Runcorn and Widnes sustain chlorine dioxide demand for industrial pre-treatment systems.
Midlands
Food and beverage processors across Birmingham and Leicester adopt zero-liquid-discharge protocols requiring specialized antiscalant chemistries. The Environment Agency's tightening consent limits under the Water Resources Act compel closed-loop cooling system upgrades. Manufacturing facilities in Derbyshire and Nottinghamshire expand on-site chemical procurement volumes for effluent elimination targets.
Scotland
Scottish Water's regional procurement centralization creates volume contracts for integrated chemical-plus-service suppliers. The Drinking Water Inspectorate's residual chlorine thresholds sustain sodium hypochlorite demand across Highland and Lowland distribution networks. Industrial facilities in Grangemouth and Aberdeen face North Sea discharge regulations requiring advanced coagulant dosing at refinery and petrochemical sites.
South East England
Thames Water's multi-source procurement consolidation drives bulk coagulant security agreements after recent chemical shortages. The Drinking Water Inspectorate mandates microbiological safety standards across London's Victorian-era distribution infrastructure. Municipal treatment facilities in the Thames Valley accelerate electrochlorination adoption to eliminate hazardous bulk tanker deliveries.
Wales
Natural Resources Wales enforces river basin management plans that tighten phosphorus discharge limits for municipal operators. Welsh Water's regional procurement patterns favor suppliers offering guaranteed turbidity removal outcomes rather than tonnage contracts. Industrial facilities in Port Talbot and Deeside confront steel and chemical sector effluent quality pressures under devolved environmental permitting.
United Kingdom Water Treatment Chemicals Market Competitive Landscape
Performance-based contracting dominates the current landscape as municipal utilities transfer technical risk to chemical suppliers. The vendor base organizes around three tiers: multinational chemical conglomerates with integrated production networks, regional specialists with localized manufacturing footprints, and service-oriented providers bundling digital dosing systems with commodity supply. Strategic archetypes include scale-driven bulk coagulant suppliers, formulation specialists in phosphonate corrosion inhibitors, and integrated service contractors. Competitive moves center on multi-year chemical service agreements and on-site electrochlorination system deployment.
Among multinational chemical conglomerates, BASF and Kemira exemplify scale-driven archetypes with European production networks serving British municipal contracts. Veolia Water Solutions & Technologies occupies the integrated service contractor position, bundling chemical supply with operational management. Ecolab represents the formulation specialist tier with concentrated presence in industrial water applications. These three anchors illustrate how competitive positioning fragments across commodity scale, technical formulation, and service integration vectors.
| Leading Market Players |
|---|
| Veolia Water Solutions & Technologies |
| BASF |
| Ecolab |
| Nouryon |
| Akzo Nobel |
| Kemira |
| SNF |
| Kurita Water Industries |
| Solenis |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap chemical distributors across the British Isles anchor supply-side discipline through long-standing municipal relationships, translating procurement consolidation into pricing power that resists commodity volatility. Their embedded service contracts with Thames Water and United Utilities create switching costs that protect margin even as electrochlorination technologies displace bulk chemical deliveries.
Pricing Analysis
Service-bundling separates performance-guaranteed turbidity removal contracts from unbundled tonnage deliveries. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under Drinking Water Inspectorate standards and volume scale across municipal procurement. Cost compression in standard-grade coagulants is intensifying because aluminium sulphate feedstock volatility compresses manufacturer margins. Manufacturing facilities in Cheshire and Merseyside exhibit highest price sensitivity due to real-time effluent monitoring compliance costs, while Scottish Water's centralized procurement demonstrates lowest sensitivity through integrated chemical-plus-service packages.
Supply Chain Analysis
Post-Brexit domestic-content preferences in UK public procurement are reshaping sourcing toward Runcorn and Widnes manufacturing clusters over continental European alternatives. Supply concentration rests on Germany, the Netherlands, and domestic British production for polyacrylamide coagulants and phosphonate corrosion inhibitors. Raw material dependencies draw from North Sea bauxite refineries, sulphuric acid feedstock, and brine electrolysis inputs. Single-source vulnerability concentrates in electrochlorination system components imported from European specialist manufacturers. Distribution runs through direct sales for high-volume municipal contracts and regional distributor networks for fragmented industrial accounts across the Midlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom water treatment chemicals market sits in a technology-transition phase as on-site electrochlorination systems replace hazardous bulk tanker logistics across municipal utilities. This electrification of supply chains compresses traditional distributor margins while opening service-revenue streams for integrated chemical-plus-technology providers.
For Market Incumbents: Acquire digital dosing system capabilities to embed chemical supply within IoT-enabled automation contracts. Secure backward integration into brine electrolysis equipment manufacturing to capture electrochlorination margins threatened by membrane bioreactor substitution. Defend municipal volume through multi-year performance-based service agreements that transfer operational risk from utilities. For New Entrants and Emerging Players: Regional chemical distributors in the Midlands represent the most penetrable channel partner type for specialized antiscalant formulations targeting zero-liquid-discharge mandates. Target food and beverage processors in Derbyshire and Nottinghamshire with closed-loop cooling system chemistries underserved by incumbent bulk suppliers. Penetrate through site-specific effluent challenge assessments that demonstrate formulation customization against commodity competitors. For Investors and Strategic Acquirers: Distressed-cycle entries favor electrochlorination technology specialists in South East England where Thames Water's procurement consolidation accelerates adoption. Long-term viability centers on suppliers capable of bridging commodity chemical production with digital service integration. Monitor Scottish Water's regional procurement centralization as the signal indicating volume contract availability for integrated chemical-plus-service providers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrochlorination Equipment | Captures electrification margins as Thames Water eliminates bulk tanker deliveries. |
| Performance-Based Service Contracting | Transfers turbidity removal risk from United Utilities to chemical suppliers. |
| Hybrid Phosphonate Formulation Development | Addresses dual Environment Agency mandates for scale inhibition and microbial control. |
| Scottish Water Procurement Centralization Partnership | Secures volume contracts through integrated chemical-plus-service positioning. |
| Zero-Liquid-Discharge Antiscalant Specialization | Targets compulsory effluent elimination in Midlands food and beverage processing. |
Research Methodology
Environment Agency discharge permit databases, Drinking Water Inspectorate compliance records, and UK trade customs data formed the secondary backbone for this analysis. Primary interviews with municipal procurement directors at Thames Water and United Utilities, plant managers at Runcorn manufacturing facilities, and technical R&D directors at phosphonate formulation specialists combined with secondary validation through bottom-up and top-down triangulation.
Historical trendline analysis across coagulant consumption patterns and electrochlorination adoption rates informed the projection framework. Segmentation modeling incorporated product type, application, end user, and distribution channel dimensions alongside regional regulatory cluster differentiation. CAGRs were derived through growth rate convergence analysis across the projection horizon, with specific inputs from Environment Agency permitting trajectory and Scottish Water procurement centralization timeline.
Several conditions sit outside the modeled scope, including potential REACH-UK divergence outcomes and membrane bioreactor substitution acceleration beyond current adoption curves. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and electrochlorination technology cost reduction trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Anionic Flocculants Market
Water & Sludge Treatment
Asia-Pacific Water Treatment Chemicals Market
Water & Sludge Treatment
Global Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Nanotechnology in Water Treatment Market
Water & Sludge Treatment
Low-Dosage Hydrate Inhibitors (Ldhis) Market
Water & Sludge Treatment
Global Wood Activated Carbon Market
Water & Sludge Treatment
Global Liquid Waste Management Market
Water & Sludge Treatment
Industrial Water Treatment Chemicals Market
Water & Sludge Treatment
Global Water Softeners Market
Water & Sludge Treatment
Water Treatment Polymers Market
Water & Sludge Treatment
Global Mobile Water Treatment Market
Water & Sludge Treatment
Membrane Filtration Systems Market
Water & Sludge Treatment
US Liquid Waste Management Market
Water & Sludge Treatment
South America Membrane Water and Wastewater (WWT) Treatment Market
Water & Sludge Treatment
India Water Treatment Chemicals Market
Water & Sludge Treatment
Sedimentation and Centrifugation Market