
 US Water and Wastewater Treatment Market | 2026-2036
US Water and Wastewater Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
US Water and Wastewater Treatment Market Insights
Public-private partnership structures and availability-based payment models is tilting competitive dynamics toward operators with balance-sheet capacity and long-term contract execution experience. Veolia leverages its integrated service platform across municipal and industrial accounts. Evoqua Water Technologies anchors its position through specialized high-purity water systems for manufacturing plants. Pentair competes on residential and commercial filtration product breadth.
US water and wastewater treatment encompasses physical, chemical, and biological processes that remove contaminants from source water and effluent streams, with membrane filtration achieving removal efficiencies below 0.1 micron for dissolved solids and pathogens. The primary purpose is producing water meeting Safe Drinking Water Act standards for human consumption and discharging treated effluent compliant with Clean Water Act permit limits. Membrane filtration and reverse osmosis command premium equipment margins as industrial users confront tightening discharge limits. Biological treatment dominates municipal installed base volume but faces retrofit pressure from nutrient removal requirements. Operation and maintenance services generate recurring revenue streams that offset cyclical capital spending patterns.
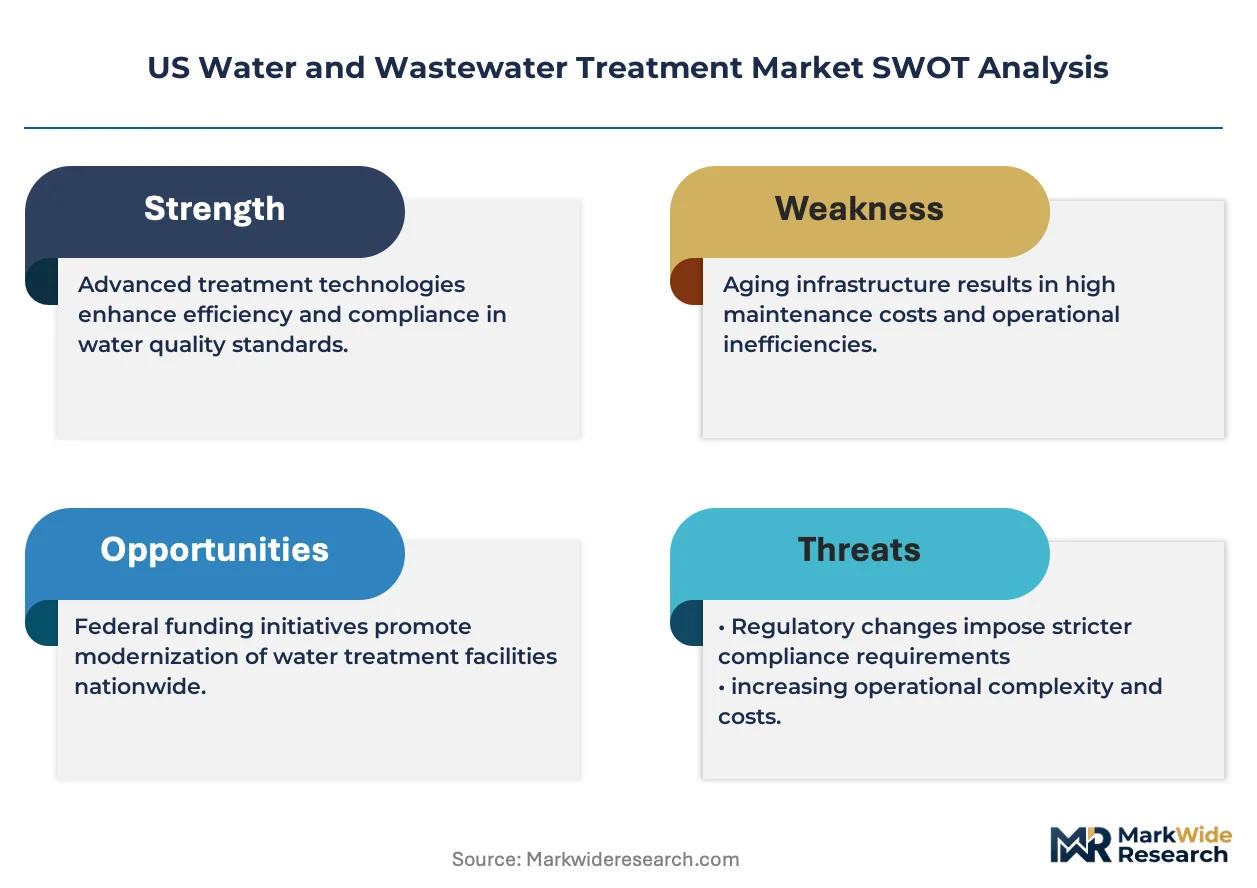
EPA enforcement of Lead and Copper Rule improvements and emerging contaminant standards under the Safe Drinking Water Act is mandating infrastructure investment timelines for municipal authorities. State-level public utility commissions in California and Texas shape rate recovery mechanisms that determine project bankability for treatment upgrades. OSHA confined space and chemical handling protocols affect operational cost structures for service providers. Stakeholders must track how PFAS maximum contaminant level finalization redirects capital toward advanced oxidation and activated carbon systems.
Market Dynamics
EPA Lead and Copper Rule revisions are compressing infrastructure replacement timelines across municipal water systems, forcing capital deployment toward advanced filtration and corrosion control technologies ahead of traditional depreciation cycles.
Growth Catalysts
- PFAS Maximum Contaminant Levels:EPA finalization of enforceable PFAS limits under the Safe Drinking Water Act is mandating activated carbon and ion exchange upgrades at thousands of public water systems.
- Texas and California drought stress:Persistent water scarcity in these high-growth states is accelerating water reuse infrastructure and brackish groundwater desalination project pipelines.
- Membrane bioreactor (MBR) technology:MBR systems are displacing conventional activated sludge in municipal retrofits where nutrient removal requirements and footprint constraints coincide.
Market Restraints
- Specialty chemical input volatility:Coagulants and disinfectants face feedstock cost pressure from chlor-alkali and bromine supply chain disruptions.
- Equipment manufacturing concentration:High-purity membrane production concentrates among a limited supplier base in Japan and Germany, creating import dependency exposure.
- Rate case friction:State public utility commissions in California and Texas impose multi-year lag structures that delay cost recovery for treatment upgrades.
Strategic Opportunities
- Great Lakes advanced treatment corridor:Municipal authorities across Michigan, Ohio, and Wisconsin are expanding biological nutrient removal and UV disinfection capacity.
- Industrial water-as-a-service models:Power plants and semiconductor fabs are outsourcing high-purity water system operation to specialized operators under long-term contracts.
- Smart water network convergence:Integration of SCADA systems with AI-driven leak detection is opening software and analytics revenue streams for equipment vendors.
Industry Challenges
- Certified operator scarcity:State-level licensing requirements for water treatment plant operators create recruitment bottlenecks as veteran staff retire.
- Legacy lead service line inventory:Municipal utilities face decades-long replacement timelines for buried infrastructure with incomplete location records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Water and Wastewater Treatment Market |
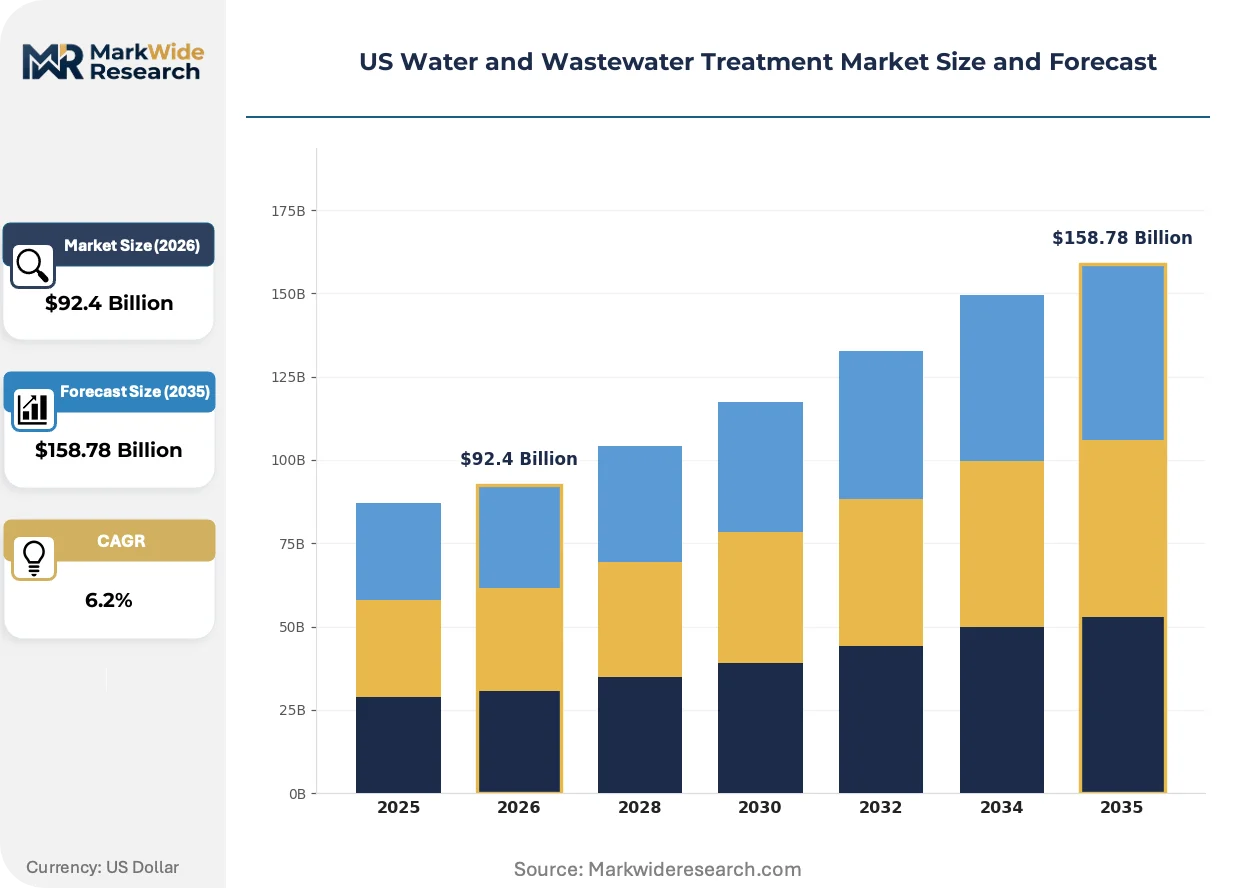
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $158.78 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Membrane Filtration, Ultraviolet Disinfection, Ozone Treatment, Reverse Osmosis, Ion Exchange, Biological Treatment Application: Municipal Supply, Industrial Effluent, Agricultural Runoff, Stormwater Management, Groundwater Purification, Recycled Water End User: Municipal Authorities, Manufacturing Plants, Agricultural Enterprises, Construction Firms, Commercial Facilities, Educational Institutions Service Type: Design & Engineering, Operation & Maintenance, Consulting, Equipment Installation, Monitoring & Analysis, Retrofit Solutions |
| Companies Covered | Aquatech International, Microvi Biotech Inc., American Water, Pentair, Fluence Corporation, Veolia, Culligan, 3M, Evoqua Water Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Water and Wastewater Treatment Market Trends and Innovations
Digital instrumentation and predictive analytics are restructuring how water utilities monitor distribution network integrity, shifting capital from reactive repair toward preventive asset management.
Advanced oxidation processes (AOPs) combining ozone with ultraviolet irradiation are collapsing the treatment footprint required for emerging contaminant destruction at municipal facilities. Utilities in Arizona and Colorado are piloting AOP trains for NDMA and 1,4-dioxane removal ahead of anticipated state standards. The technology is collapsing the capital cost gap between conventional granular activated carbon and full-scale AOP installations.
EPA enforcement discretion around Lead and Copper Rule improvements is tightening permit compliance windows for large community water systems. The agency's revised testing protocols and mandatory replacement triggers are forcing rate case filings in Midwestern and Northeastern states. Small systems in rural Pennsylvania and upstate New York face disproportionate technical assistance needs.
Performance-based service contracting is displacing traditional equipment procurement in industrial water treatment. Semiconductor manufacturers in Texas and pharmaceutical operations in North Carolina are bundling design, build, and operation under single-source agreements. This model concentrates vendor risk but transfers operational liability away from capital-constrained facility managers.
US Water and Wastewater Treatment Market Segmentation
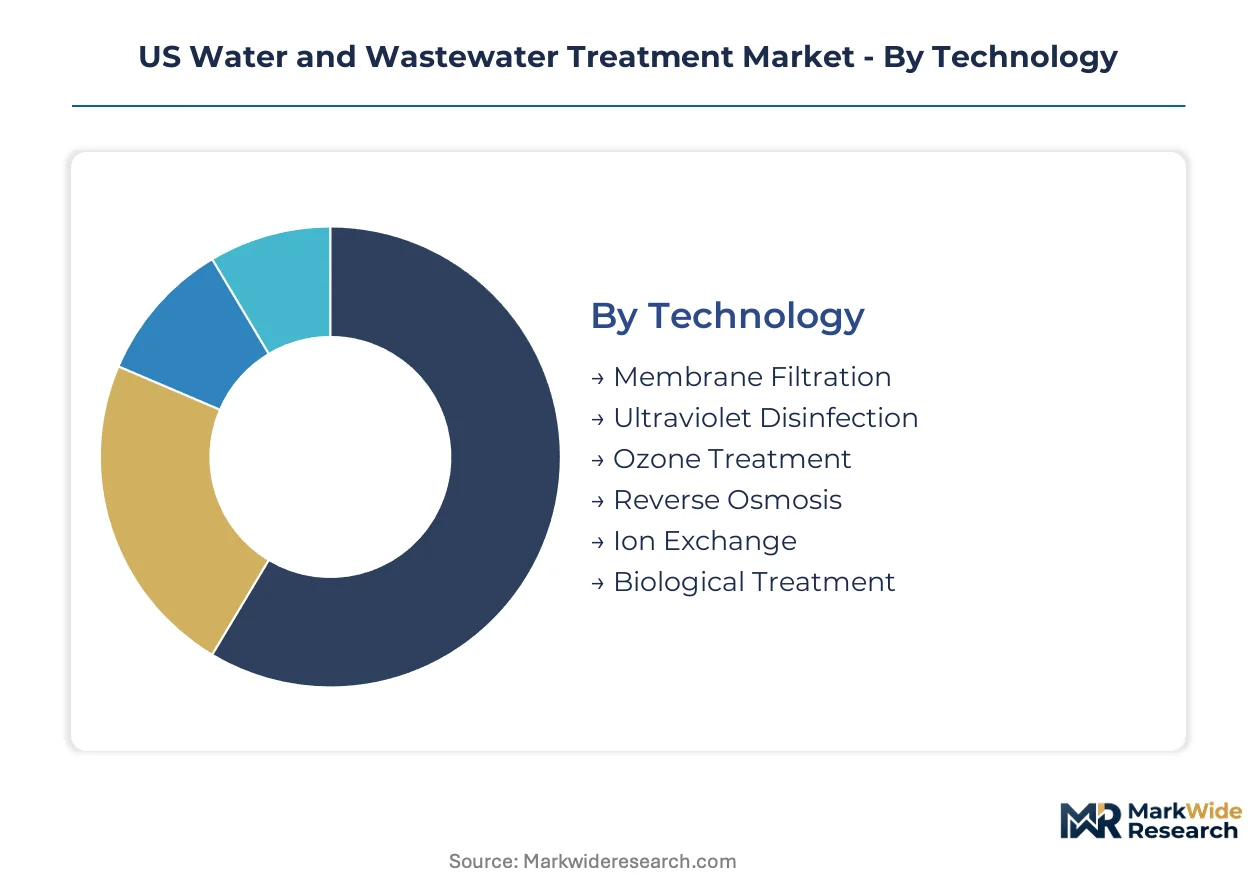
Technology and application segmentation reveals where capital concentrates across US water infrastructure. Treatment modality selection determines project bankability, regulatory compliance pathways, and long-term operational cost structures for municipal and industrial buyers.
Technology:
Cost tier differentiation separates premium membrane systems from conventional biological processes in municipal procurement decisions.
- Membrane Filtration:Hollow-fiber and ceramic membranes achieve sub-micron particle removal without chemical coagulation. Texas and California utilities deploy these systems where footprint constraints and water reuse targets coincide.
- Reverse Osmosis:Semi-permeable membranes operating at 150-800 psi reject dissolved salts and emerging contaminants. Brackish groundwater desalination projects in Arizona and Florida anchor demand as drought stress intensifies.
- Ultraviolet Disinfection:UV-C irradiation at 254 nm wavelength inactivates pathogens without residual chemical formation. Secondary disinfection applications dominate Great Lakes municipal retrofits.
- Ozone Treatment:Strong oxidant generated on-site via corona discharge destroys taste-and-odor compounds and pharmaceutical traces. Advanced oxidation process integration drives industrial adoption.
- Ion Exchange:Resin-based selective removal targets nitrate, arsenic, and perchlorate in small system compliance. Regeneration chemical costs constrain economics at scale.
- Biological Treatment:Activated sludge and fixed-film processes degrade organic loads through microbial metabolism. Dominates installed municipal base volume despite nutrient removal retrofit pressure.
Biological treatment holds installed capacity. Membrane filtration is rotating up the share rankings.
Application:
Volume concentration varies sharply between regulated municipal supply and discretionary industrial effluent treatment.
- Municipal Supply:Public water systems serving 15+ connections treat surface and groundwater to Safe Drinking Water Act standards. EPA Lead and Copper Rule revisions compress replacement timelines across Midwestern and Northeastern systems.
- Industrial Effluent:Manufacturing discharge pretreatment satisfies Clean Water Act permit limits before release to publicly owned treatment works. Semiconductor fabs in Texas and chemical plants in Louisiana drive high-purity system demand.
- Agricultural Runoff:Nutrient and sediment control from concentrated animal feeding operations and irrigated cropland. Chesapeake Bay and Mississippi River watershed TMDL requirements shape investment.
- Stormwater Management:Green infrastructure and detention systems reduce combined sewer overflow frequency. Philadelphia and Milwaukee green city initiatives expand permeable surface mandates.
- Groundwater Purification:Ex-situ pump-and-treat or in-situ bioremediation addresses contaminated aquifers. Superfund sites in California Central Valley and New Jersey drive remediation contracting.
- Recycled Water:Tertiary-treated effluent repurposed for irrigation, cooling, or indirect potable reuse. Orange County Water District and El Paso Water pioneer direct potable reuse regulatory frameworks.
Municipal supply commands capital deployment. Recycled water is climbing the fastest.
End User:
Customer type determines procurement modality, with public-sector rate-case financing contrasting against private capital expenditure cycles.
- Municipal Authorities:City and county water departments operating publicly owned treatment works. State revolving fund access and public utility commission rate recovery shape project timelines.
- Manufacturing Plants:Process water and wastewater treatment integrated into production facilities. Power plants and data centers in water-stressed regions outsource high-purity system operation.
- Agricultural Enterprises:Irrigation water treatment and livestock waste management for regulatory compliance. California Central Valley dairies face nitrate discharge permit requirements.
- Construction Firms:Temporary dewatering and sediment control for infrastructure projects. Erosion and sediment control plan mandates drive equipment rental demand.
- Commercial Facilities:Hotels, hospitals, and office buildings treating on-site water for cooling towers and boilers. Legionella prevention regulations accelerate cooling tower treatment upgrades.
- Educational Institutions:Campus-scale water systems at universities and school districts. Deferred maintenance backlogs constrain capital availability at public institutions.
Municipal authorities dominate contract value. Manufacturing plants are expanding most quickly.
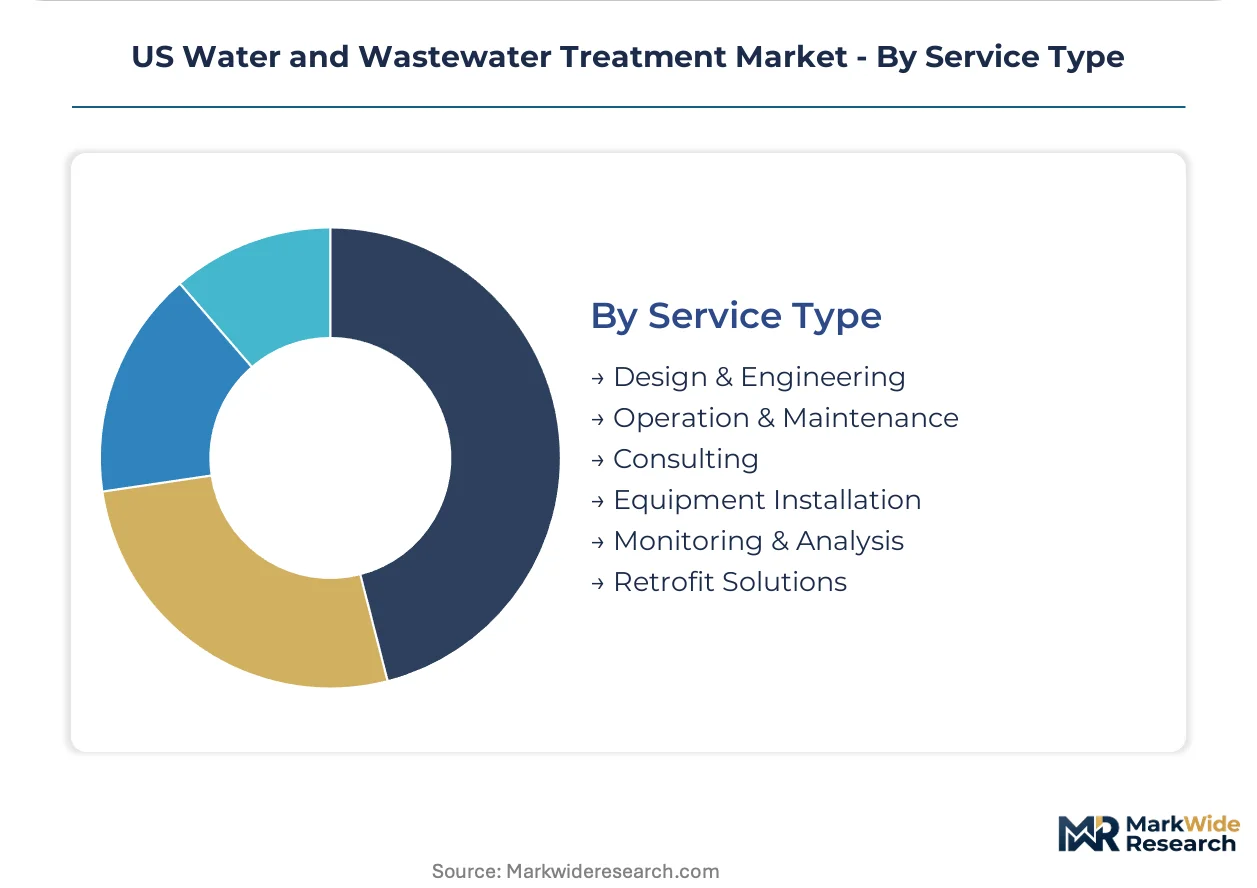
Service Type:
Margin structure stratifies across one-time engineering fees and recurring operational contracts with divergent cash flow profiles.
- Operation & Maintenance:Long-term service agreements covering chemical supply, labor, and equipment upkeep. Recurring revenue streams offset cyclical capital spending for integrated service providers.
- Design & Engineering:Front-end process selection, pilot testing, and construction documentation. Design-build procurement compression reduces standalone engineering margins.
- Consulting:Regulatory compliance strategy, rate case support, and asset management planning. PFAS response planning and lead service line inventories drive near-term demand.
- Equipment Installation:Mechanical and electrical construction for treatment plant expansions. Skilled craft labor shortages extend project schedules in active construction markets.
- Monitoring & Analysis:Laboratory services and continuous monitoring instrumentation for permit compliance. Third-party certified labs handle emerging contaminant analytical methods.
- Retrofit Solutions:Equipment upgrades and process modifications to existing treatment trains. Nutrient removal and disinfection byproduct control dominate municipal retrofit scope.
Operation and maintenance locks in recurring revenue. Retrofit solutions are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US water and wastewater treatment sector operates as a net importer of specialized membrane components and high-purity process equipment, with domestic manufacturing concentrated in legacy biological treatment systems and chemical feed infrastructure.
Texas
Brackish groundwater desalination and industrial reuse projects dominate capital deployment across the Permian Basin and Rio Grande Valley. The Texas Commission on Environmental Quality administers stringent discharge permits for oilfield produced water. Houston and Dallas-Fort Worth anchor engineering procurement for power plant cooling tower upgrades and semiconductor fab high-purity systems.
California
Drought resilience mandates accelerate indirect potable reuse and agricultural runoff treatment investments. The State Water Resources Control Board enforces recycled water objectives through regional water quality control boards. Orange County Water District and Los Angeles Department of Water and Power pioneer regulatory frameworks for direct potable reuse piloting.
Great Lakes Region
Biological nutrient removal and UV disinfection retrofits absorb municipal capital across Michigan, Ohio, and Wisconsin. EPA Great Lakes Restoration Initiative funding supports combined sewer overflow reduction. Cleveland and Milwaukee deploy green infrastructure mandates for stormwater volume control.
Florida
Seawater reverse osmosis and aquifer storage recovery dominate utility planning in water-stressed coastal counties. The Florida Department of Environmental Protection oversees consumptive use permitting for desalination intakes. Tampa Bay Water and Miami-Dade County expand brackish and seawater treatment capacity for municipal supply diversification.
Arizona
Advanced oxidation process piloting for NDMA and 1,4-dioxane removal precedes anticipated state standards. The Arizona Department of Environmental Quality manages aquifer protection permits for treated wastewater recharge. Phoenix and Tucson utilities contract for membrane bioreactor upgrades to meet nutrient removal requirements within constrained footprints.
US Water and Wastewater Treatment Market Competitive Landscape
On the supply side, the industry is bifurcated between integrated service platforms and specialized equipment fabricators. Consolidation pressures favor operators with balance-sheet capacity for long-term municipal contracts. Three archetypes dominate: multinational environmental service conglomerates, mid-cap technology specialists, and regional operation-and-maintenance contractors. Competitive moves concentrate on public-private partnership pursuit and smart water network software integration.
Among diversified environmental service providers, Veolia and American Water exemplify the integrated platform archetype spanning municipal operation and industrial outsourcing. Evoqua Water Technologies occupies a position within the specialized high-purity equipment tier, serving manufacturing accounts with membrane and disinfection systems. Pentair represents the product-breadth approach across residential, commercial, and light industrial filtration segments.
| Leading Market Players |
|---|
| Aquatech International |
| Microvi Biotech Inc. |
| American Water |
| Pentair |
| Fluence Corporation |
| Veolia |
| Culligan |
| 3M |
| Evoqua Water Technologies |
| Others |
Pricing and Supply Chain Analysis
Japanese and German membrane manufacturers anchor the high-purity equipment tier, concentrating margin capture upstream while US municipal utilities absorb downstream cost pass-through for critical filtration components. This upstream concentration funnels pricing power toward specialized ceramic and hollow-fiber suppliers, compressing margins for domestic system integrators competing on bundled service contracts.
Pricing Analysis
Industrial OEM buyers anchor a project-based pricing structure where semiconductor fabs and power plants negotiate lump-sum design-build-operate agreements spanning 10-15 year terms. Price differentiation rests on certification tier—NSF/ANSI 61 potable water system validation commands 15-25% premiums over non-certified industrial grades—and geographic delivery cost to water-stressed Texas and California markets. Cost compression in standard biological treatment equipment is intensifying because Chinese manufacturers are exporting activated sludge basin components at distressed pricing. Municipal authorities exhibit highest price sensitivity due to public utility commission rate case lags, while data center operators demonstrate lowest sensitivity given uptime-driven procurement priorities.
Supply Chain Analysis
Export control restrictions on advanced ceramic membrane manufacturing equipment limit technology transfer to US fabrication facilities, constraining domestic production scale-up. Geographic supply concentration centers on Japan, Germany, and South Korea for high-purity membranes, with China dominating polymeric membrane substrates and ion exchange resin precursors. Raw material dependencies include chlor-alkali-derived coagulants, bromine-based disinfectants, and rare earth catalysts for advanced oxidation processes. Single-source vulnerability runs through Japanese hollow-fiber membrane suppliers holding 60% of global production capacity. Distribution feeds from manufacturer-direct sales for large municipal projects through specialized water treatment distributors serving industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal utility consolidation across Midwestern and Northeastern states is shifting procurement leverage toward fewer, larger buyers with standardized specification power. This buyer concentration fragments competitive positioning for mid-tier equipment vendors unable to scale service footprints.
For Market Incumbents: Harden contract renewal rates by embedding IoT-enabled predictive maintenance modules into existing O&M agreements, raising switching costs for Great Lakes municipal accounts. Deepen backward integration into membrane cleaning chemical production to offset feedstock volatility from chlor-alkali suppliers. Priority defensive investment targets UV disinfection system certification upgrades ahead of anticipated EPA Cryptosporidium treatment requirements. For New Entrants and Emerging Players: Establish a beachhead in PFAS remediation retrofit contracting for small community water systems in rural Pennsylvania and upstate New York, where technical assistance gaps exceed incumbent service capacity. Target mobile advanced oxidation process trailer deployments for temporary 1,4-dioxane treatment at Arizona groundwater sites awaiting permanent infrastructure. Go-to-market leverage: partner with state rural water associations for pre-qualified vendor list placement bypassing traditional procurement cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional O&M contractors holding fragmented Great Lakes and Texas municipal contracts. Long-term viability favors platforms with recurring revenue exceeding 60% of total mix and demonstrated public-private partnership close rates. Acquisition target archetype: specialized PFAS treatment technology developers with EPA-validated analytical methods. Signal to watch: state revolving fund allocation shifts toward emerging contaminant categories triggering vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Public-Private Partnership Expansion | Long-term availability-based contracts with Texas and California municipalities lock in 15-20 year revenue visibility. |
| PFAS Treatment Technology Acquisition | Activated carbon and ion exchange specialists gain EPA enforcement tailwinds from final MCL implementation. |
| Smart Water Network Integration | SCADA-AI convergence creates software recurring revenue streams alongside hardware deployments. |
| Membrane Manufacturing Backward Integration | Ceramic membrane in-house production reduces import dependency exposure to Japanese supply concentration. |
| Industrial Water-as-a-Service Scale-Up | Semiconductor and pharmaceutical outsourcing contracts transfer operational liability from capital-constrained facility managers. |
Research Methodology
A standing panel of municipal water utility directors, industrial facility engineers, membrane system procurement managers, and state environmental regulator staff provided ongoing calibration against market developments. Primary interviews with these stakeholders were cross-validated against EPA enforcement databases, state revolving fund allocation records, SEC 10-K filings from publicly traded water service providers, and American Water Works Association technical conference proceedings. Bottom-up project pipeline tracking across Texas, California, and Great Lakes regions was triangulated with top-down capital expenditure estimates from state environmental agency budgets.
Scenario bracketing around PFAS MCL implementation timing, drought severity projections, and municipal bond market conditions framed the analytical envelope. Segmentation modeling incorporated technology modality, application type, end-user procurement structure, and service delivery format across the projection horizon. CAGRs were derived from unit economics analysis of representative project archetypes rather than aggregate spending trends. Industry-specific forecast inputs included state-level lead service line replacement mandates and semiconductor fab construction permitting velocity.
Stress conditions across membrane import disruption duration, municipal rate case approval delays, and industrial capital expenditure freeze scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement discretion and infrastructure funding continuity. Material shifts in EPA emerging contaminant rulemaking timelines or state public utility commission rate recovery frameworks would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Industrial Wastewater Real-Time Toxicity Monitoring Test Systems Market
Water & Sludge Treatment
Global Municipal Water Treatment Chemicals Market
Water & Sludge Treatment
Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
United Kingdom Water Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Europe Water Treatment Chemicals Market
Water & Sludge Treatment
Swimming Pool Treatment Chemicals Market
Water & Sludge Treatment
Global Water Clarifiers Market
Water & Sludge Treatment
Slurry Heaters Market
Water & Sludge Treatment
Fluid Waste Disposal Systems Market
Water & Sludge Treatment
Water Softening Systems Market
Water & Sludge Treatment
Global Wet Waste Management Market
Water & Sludge Treatment
US Water and Wastewater Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Europe Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
India Water and Wastewater Treatment (WWT) Technology Market