
 Propylene Glycol Alginate Market | 2026-2036
Propylene Glycol Alginate Market Size, Share, and Industry Trends Forecast 2026-2036
Propylene Glycol Alginate Market Intelligence
Pharmaceutical formulators is rotating toward higher-purity propylene glycol alginate grades as oral dosage and controlled-release applications expand. Kerry Group plc leverages its integrated hydrocolloid supply chain to sustain consistent pharmaceutical-grade output across European and North American facilities. Kimica Corporation anchors Japanese supply through proprietary brown-algae sourcing and extraction expertise. DuPont Nutrition & Biosciences competes on fermentation-derived consistency, differentiating its portfolio from traditional seaweed-extracted alternatives.
Propylene glycol alginate is a chemically modified polysaccharide produced by esterifying alginic acid with propylene oxide, yielding a water-soluble biopolymer with controlled viscosity and acid stability under pH 3.5–4.5 conditions. Food-grade formulations serve as stabilizers and emulsifiers in acidic dairy beverages and salad dressings, while pharmaceutical-grade variants function as tablet binders and sustained-release matrices. Food-grade product type dominates volume throughput due to entrenched beverage-industry demand, though pharmaceutical-grade commands superior margin pools from validated excipient supply chains. Personal care application is accelerating fastest as Korean and Japanese cosmetic formulators adopt alginate-derived film-forming agents in sheet-mask and serum formulations.
FDA excipient guidelines and EMA quality standards for pharmaceutical-grade alginates enforce batch-level traceability and residual-solvent limits that shape supplier qualification timelines. REACH registration requirements and EFSA food-additive evaluations in Europe further constrain market entry for uncertified producers. Stakeholders must monitor evolving pharmacopeial monograph revisions and algae-sustainability certification schemes to secure long-term formulation partnerships and avoid supply-chain disqualification.
Market Dynamics
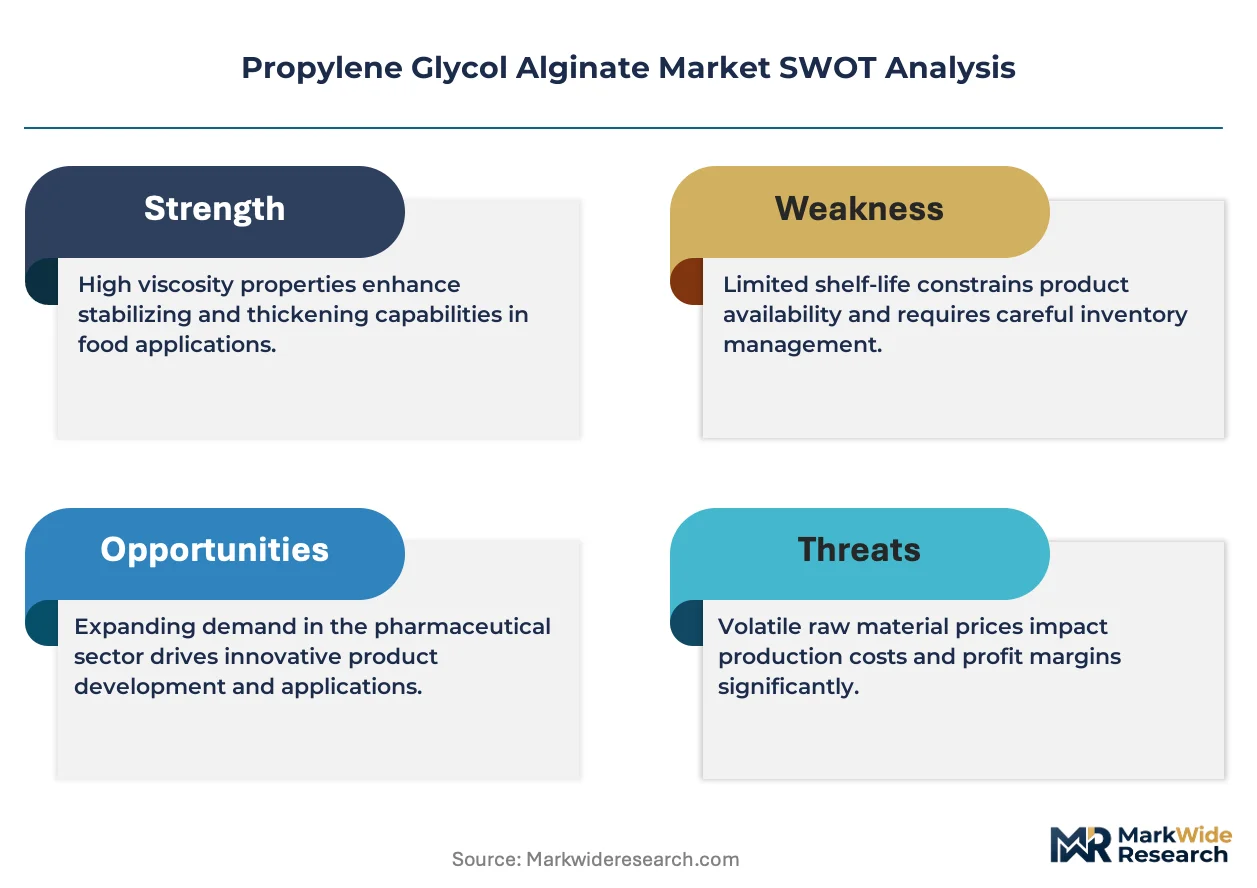
Pharmaceutical-grade purity requirements and brown-algae supply concentration are compressing supplier margins while elevating qualification barriers for new entrants across oral dosage and cosmetic applications.
Growth Catalysts
- EMA Quality Standards:Batch-level traceability mandates for pharmaceutical-grade alginates are locking in validated supplier relationships and extending contract durations for compliant producers.
- Sheet-mask formulations:Korean cosmetic manufacturers are expanding alginate-derived film-forming agent procurement for serum-delivery systems in premium skincare lines.
- Controlled-release matrices:Oral dosage formulators are substituting synthetic polymers with propylene glycol alginate for acid-stable sustained-release tablet cores.
Market Restraints
- Brown-algae harvest volatility:Cold-water kelp yields fluctuate with North Atlantic temperature shifts, concentrating raw material risk among Japanese and Norwegian sourcing networks.
- Residual-solvent testing costs:EMA and FDA pharmacopeial monographs enforce gas chromatography validation for propylene oxide traces, adding $15,000-$25,000 per batch certification.
- Carrageenan substitution:Cost-sensitive beverage stabilizer buyers in Latin America are pivoting toward carrageenan blends for acidic dairy applications.
Strategic Opportunities
- Indian pharmaceutical excipient demand:CDSCO's tightening of import quality standards is creating first-mover advantage for GMP-certified alginate suppliers establishing local technical service presence.
- Fermentation-derived consistency:Microbial alginate production is converging with precision fermentation infrastructure to bypass seaweed harvest seasonality.
- Direct-to-formulator digital platforms:Specialty chemical distributors are launching validated excipient marketplaces with instant COA access and batch reservation systems.
Industry Challenges
- Algae sustainability certification complexity:ASC-MSC seaweed standards require chain-of-custody documentation from harvest to esterification, extending supplier onboarding timelines by 8-14 months.
- Cross-functional talent scarcity:Formulation chemists with combined expertise in hydrocolloid rheology and pharmaceutical QbD principles command 40-60% salary premiums in Germany and Switzerland.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Propylene Glycol Alginate Market |
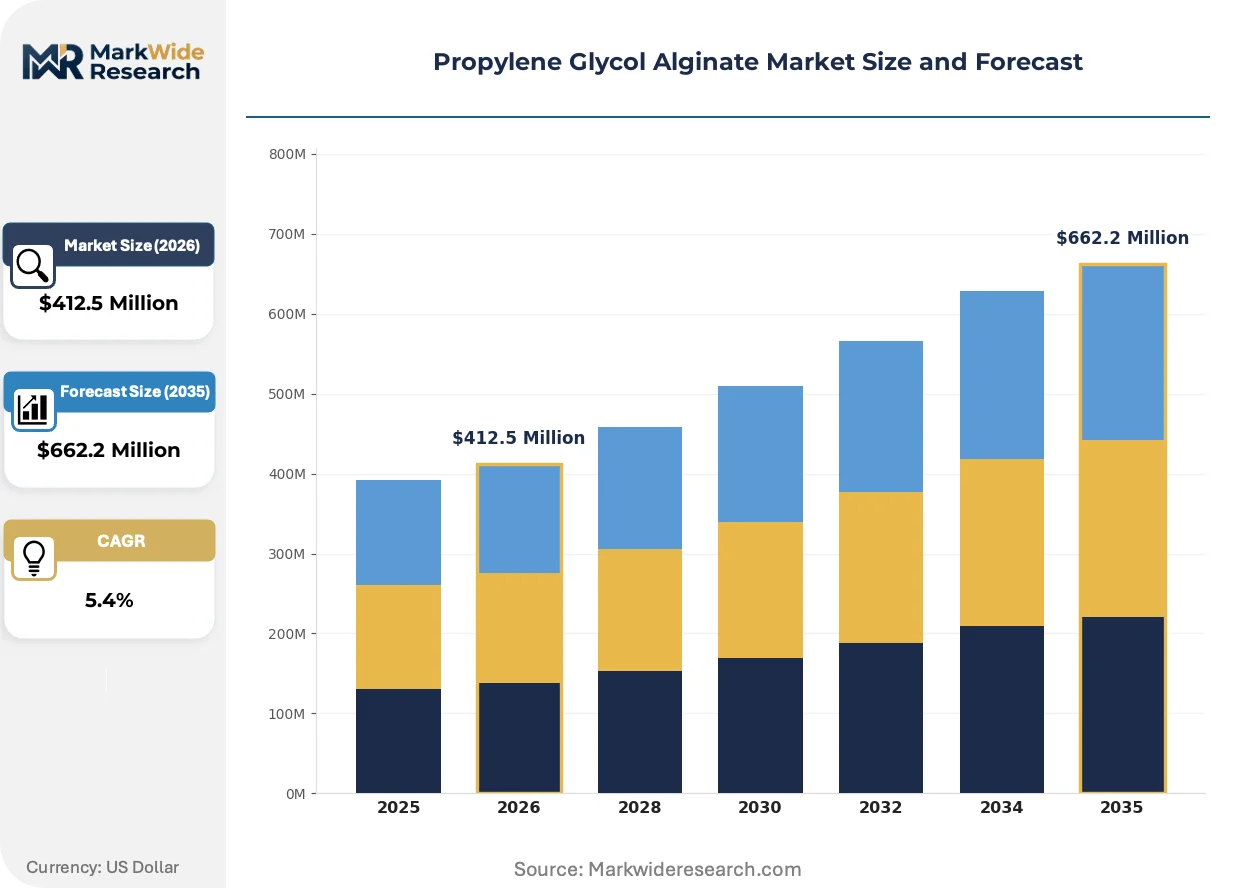
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Cosmetic Grade, Industrial Grade Application: Dairy Products, Beverages, Personal Care, Pharmaceuticals, Bakery Items End User: Food Manufacturers, Drug Makers, Cosmetic Formulators, Nutraceutical Companies Packaging Type: Bulk Bags, Drums, Flexible Intermediate Bulk Containers, Bottles |
| Companies Covered | Kerry Group plc, Kimica Corporation, DuPont Nutrition & Biosciences, IRO Alginate Industry Co., Ltd., Fuji Kasei Co., Ltd, Cargill Incorporated, FMC Corporation, Qingdao Allforlong Biotech Co., Ltd., CP Kelco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Propylene Glycol Alginate Market Strategic Shifts & Innovations
Extraction technology and regulatory data integrity requirements are fragmenting competitive advantage between seaweed-origin purists and biotech-alternative developers.
Precision fermentation of alginate precursors is bifurcating the supply base. Startups with microbial cell lines are achieving batch-to-batch viscosity consistency that seaweed extraction struggles to match. Cosmetic formulators in Japan and South Korea are adopting these alternatives for sheet-mask applications where film-thickness uniformity commands premium positioning.
REACH registration dossiers for propylene glycol alginate are tightening under ECHA's 2024 substance evaluation work program. Residual monomer thresholds and chronic toxicity data requirements are forcing reformulation of industrial-grade products. German and French pharmaceutical excipient buyers are now requiring REACH-compliant supply chain attestations as standard procurement clauses.
Long-term supply agreements with fixed-price escalators are displacing spot-market purchasing for pharmaceutical-grade material. Oral dosage manufacturers in Switzerland and the Netherlands are locking in three-to-five-year contracts with brown-algae processors. This contractual shift concentrates volume commitments among vertically integrated suppliers with captive harvesting operations.
Propylene Glycol Alginate Market Segmentation
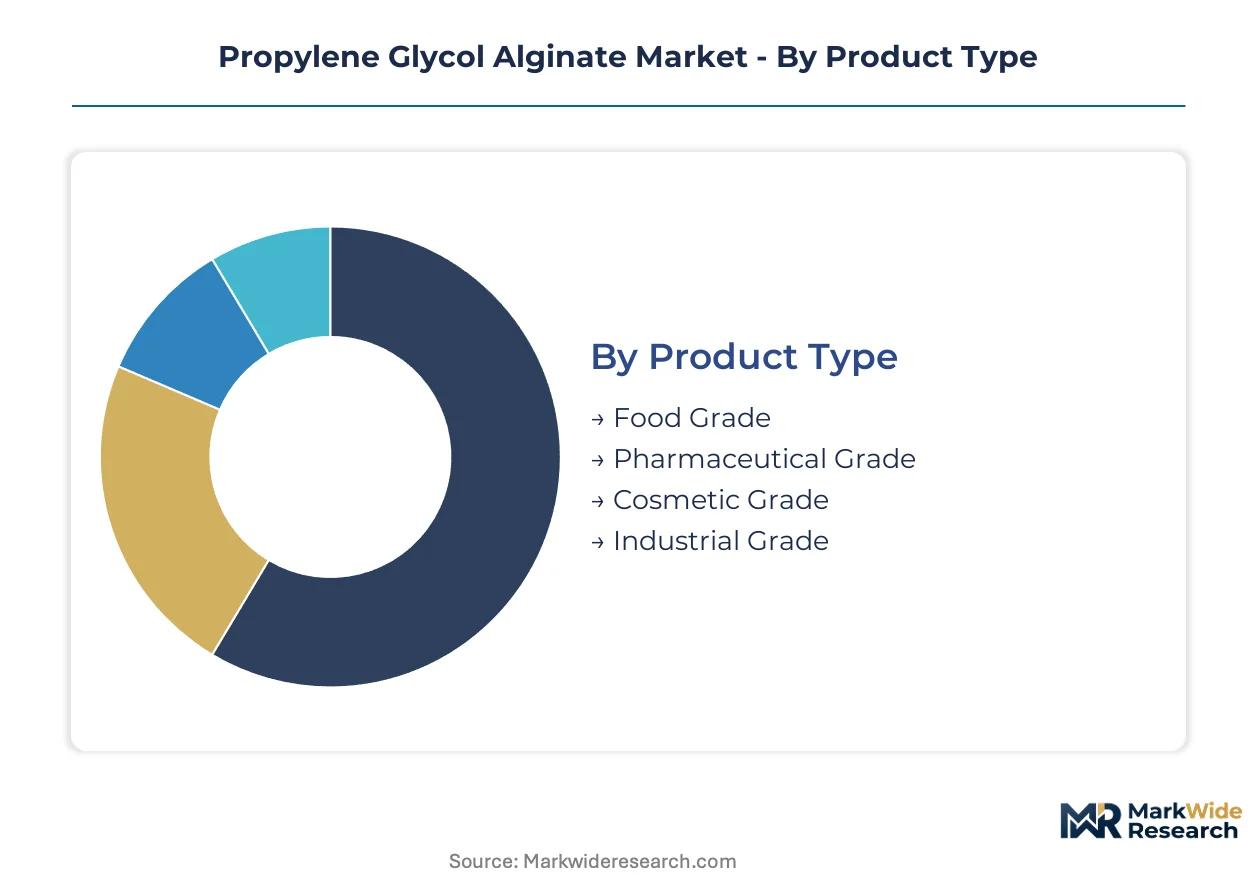
Propylene glycol alginate segmentation reflects divergent purity thresholds and supply chain rigor across end-use verticals. Channel strategies bifurcate between commodity food-grade volume plays and validated pharmaceutical-grade partnerships requiring batch-level documentation.
Product Type:
Food-grade material flows through distributor networks to beverage compounders, while pharmaceutical-grade moves through direct technical service relationships with excipient qualification teams.
- Food Grade:Standard esterification yields 40-60% propylene glycol substitution, delivering acid-stable viscosity for pH 3.5-4.5 beverage systems. Dairy stabilizer procurement in Germany and France concentrates here, though EFSA additive evaluations are tightening residual-solvent documentation requirements.
- Pharmaceutical Grade:Supercritical purification achieves >99.5% purity with propylene oxide residuals below pharmacopeial thresholds. Oral dosage manufacturers in Switzerland and the Netherlands lock in three-to-five-year supply agreements, prioritizing GMP-certified brown-algae sourcing with full chain-of-custody traceability.
- Cosmetic Grade:Film-forming viscosity grades serve Korean sheet-mask formulators seeking serum-delivery uniformity.
- Industrial Grade:Lower-purity esterificates supply textile printing and welding-rod binders where acid stability matters less than cost position.
Food-grade commands installed volume base. Pharmaceutical-grade is where margin expansion and contract duration concentrate.
Application:
Cost-tier stratification separates premium pharmaceutical matrices from commodity beverage stabilization, with personal care occupying a mid-tier growth position.
- Pharmaceuticals:Sustained-release tablet cores exploit propylene glycol alginate's acid-stable gelation for gastric-resistant drug delivery. Swissmedic and EMA quality standards enforce batch-level gas chromatography validation, extending supplier qualification timelines.
- Personal Care:Korean and Japanese cosmetic formulators adopt alginate-derived film-forming agents for premium serum-delivery systems where film-thickness uniformity commands positioning.
- Beverages:Acidic dairy drinks and fruit-juice stabilizers represent mature demand with carrageenan substitution pressure in Latin America.
- Dairy Products:Yogurt and fermented milk stabilization requires cold-soluble grades with rapid hydration kinetics.
- Bakery Items:Frozen dough conditioners utilize propylene glycol alginate's cryoprotective moisture retention.
Pharmaceutical applications dominate value capture. Personal care represents the steepest expansion trajectory.
End User:
Customer-type concentration shapes procurement sophistication, from commodity spot purchasing to validated excipient partnerships with embedded technical service.
- Drug Makers:Oral dosage specialists in Germany and Switzerland require REACH-compliant supply chain attestations and pharmacopeial monograph alignment as standard procurement clauses.
- Cosmetic Formulators:Korean manufacturers lead sheet-mask alginate adoption, demanding batch-to-batch viscosity consistency that fermentation-derived alternatives increasingly satisfy.
- Food Manufacturers:Beverage compounders prioritize cost position and cold-soluble functionality over documentation depth.
- Nutraceutical Companies:Supplement tablet binders occupy a hybrid space between food-grade cost sensitivity and pharmaceutical-grade documentation expectations.
Drug makers anchor premium pricing tiers. Cosmetic formulators are gaining share fastest.
Packaging Type:
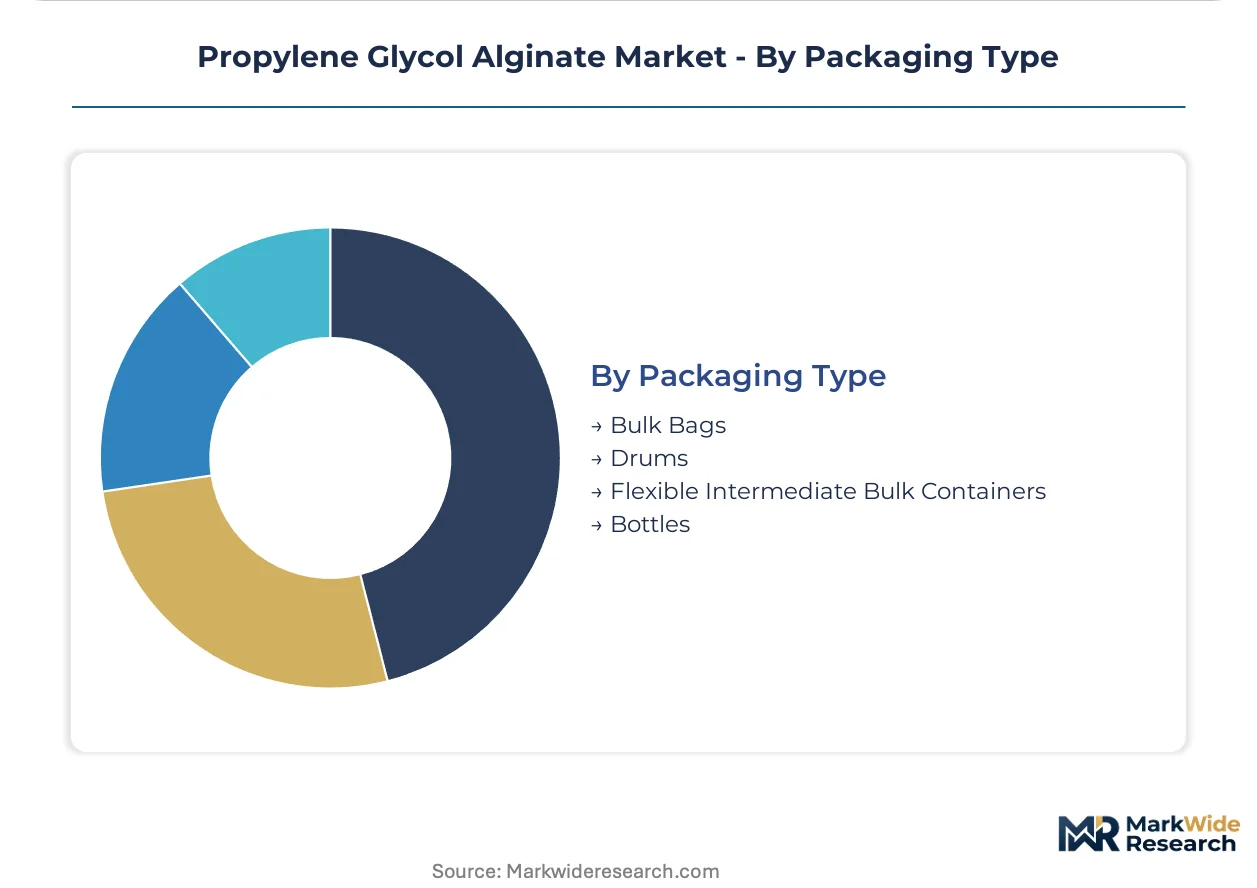
Volume scale and handling infrastructure determine packaging selection, with bulk formats serving integrated manufacturers and unitized packaging serving distributed formulation networks.
- Bulk Bags:One-tonne flexible containers serve high-volume beverage compounders with pneumatic conveying systems and climate-controlled storage.
- Flexible Intermediate Bulk Containers:Intermediate 500-1000 kg formats balance handling efficiency with lot-size flexibility for mid-tier pharmaceutical excipient buyers.
- Drums:200-litre steel or fiber formats protect hygroscopic pharmaceutical-grade material during qualified storage and sampling protocols.
- Bottles:Laboratory-scale packaging supports cosmetic R&D sampling and nutraceutical prototype development.
Bulk bags dominate throughput volume. Flexible intermediate bulk containers concentrate formulation-scale procurement growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical buyers in Germany, Japan, South Korea, Switzerland, and the United States are concentrating procurement of pharmaceutical-grade propylene glycol alginate through validated excipient supply chains. Each market exhibits distinct regulatory friction and end-use specialization.
Germany
EMA quality standards and REACH registration requirements are tightening purity thresholds for alginate derivatives used in oral dosage applications. The country's national pharmaceutical regulator enforces batch-level traceability mandates that extend supplier qualification timelines. The Rhine-Main industrial corridor hosts formulation specialists locking in three-to-five-year supply agreements with GMP-certified brown-algae processors.
Japan
Cosmetic formulators in Tokyo and Osaka are accelerating procurement of alginate-derived film-forming agents for premium sheet-mask applications. METI oversight of hydrocolloid imports maintains strict documentation standards for seaweed-origin materials. The Kansai region anchors domestic brown-algae extraction expertise through proprietary coastal harvesting networks.
South Korea
Korean beauty manufacturers in Seoul and Gyeonggi Province are expanding serum-delivery system formulations requiring batch-to-batch viscosity consistency. The country's national pharmaceutical regulator aligns with MFDS standards for cosmetic ingredient safety assessments. Busan-Ulsan chemical complexes are integrating fermentation-derived alginate alternatives to bypass seaweed harvest seasonality.
Switzerland
Swissmedic quality standards for pharmaceutical-grade alginates are enforcing gas chromatography validation for residual propylene oxide traces. Oral dosage manufacturers in Basel and Zurich prioritize GMP-certified supply chains with full chain-of-custody documentation. The Basel-Land canton concentrates tablet binder procurement through direct technical service relationships.
United States
FDA excipient guidelines are shaping procurement patterns for controlled-release matrix applications in New Jersey and North Carolina pharmaceutical clusters. The agency's pharmacopeial monographs enforce residual-solvent limits that add certification costs per batch. The Research Triangle Park region hosts formulation development teams substituting synthetic polymers with acid-stable biopolymers.
Propylene Glycol Alginate Market Key Industry Players
Player mix skews toward integrated hydrocolloid specialists and fermentation-alternative developers. The vendor base concentrates among seaweed-origin purists with captive harvesting operations and biotech startups achieving viscosity consistency through microbial cell lines. Three archetypes dominate: vertically integrated brown-algae processors, precision-fermentation platforms, and distributor-anchored technical service providers. Competitive moves center on long-term supply agreements with fixed-price escalators and REACH-compliant supply chain attestations as standard procurement clauses.
Within the integrated hydrocolloid tier, Kerry Group plc and Kimica Corporation exemplify archetypes with distinct sourcing strategies. DuPont Nutrition & Biosciences occupies a position representing fermentation-derived consistency. Among Asia-Pacific fabricators, IRO Alginate Industry Co., Ltd. and Qingdao Allforlong Biotech Co., Ltd. sit within the seaweed-extraction specialist category. Fuji Kasei Co., Ltd anchors Japanese supply network representation. Cargill Incorporated and FMC Corporation represent diversified ingredient conglomerates with cross-category hydrocolloid portfolios. CP Kelco exemplifies the distributor-anchored technical service model.
| Leading Market Players |
|---|
| Kerry Group plc |
| Kimica Corporation |
| DuPont Nutrition & Biosciences |
| IRO Alginate Industry Co., Ltd. |
| Fuji Kasei Co., Ltd |
| Cargill Incorporated |
| FMC Corporation |
| Qingdao Allforlong Biotech Co., Ltd. |
| CP Kelco |
| Others |
Cost & Logistics Intelligence
Captive brown-algae harvesting operations in Norway and Japan generate scale efficiencies that compress unit costs for pharmaceutical-grade esterification while establishing price floors resistant to spot-market volatility. These integrated processors leverage GMP-certified extraction infrastructure to command premium positioning against fermentation-derived alternatives, with cost-plus contracts indexed to kelp harvest yields and energy inputs locking in margin stability across multi-year pharmaceutical supply agreements.
Pricing Analysis
Cost-plus contracts with kelp-harvest indexation dominate pharmaceutical-grade procurement, with Swiss and German drug makers accepting fixed-price escalators in exchange for batch-level traceability guarantees. Price differentiation separates GMP-certified pharmaceutical grades from commodity food-grade material, with residual-solvent documentation and REACH-compliant attestations commanding substantial premiums. Pricing pressure stems from carrageenan substitution in Latin American beverage stabilization, where cost-sensitive buyers prioritize unit economics over acid-stability performance. Food manufacturers exhibit highest price sensitivity, while oral dosage specialists in Basel and Zurich demonstrate inelastic demand for validated excipient supply chains.
Supply Chain Analysis
Just-in-time inventory strategies characterize beverage compounder procurement, whereas pharmaceutical formulators maintain strategic stockpiles of GMP-certified material to mitigate batch-qualification delays. Supply concentrates in Japan, Norway, and China, with brown-algae harvesting anchored in North Atlantic kelp beds and proprietary coastal networks in East Asia. Raw material dependencies encompass cold-water kelp species, propylene oxide reagents, and fermentation-derived microbial cell lines. Single-source vulnerability persists for pharmaceutical-grade brown-algae processors lacking diversified harvesting geographies. Distribution runs through validated excipient distributors with embedded technical service capabilities for drug maker qualification support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as precision-fermentation alternatives achieve viscosity consistency that challenges seaweed-origin purists in cosmetic and pharmaceutical applications. Carrageenan cost advantages in beverage stabilization and microbial alginate batch uniformity represent dual displacement threats requiring strategic response.
For Market Incumbents: Shield market position through backward integration into certified brown-algae harvesting operations in Norway and Japan, securing captive supply against kelp yield volatility. Deepen GMP-certification moats by investing in supercritical purification capacity that fermentation alternatives cannot economically replicate, while extending long-term supply agreements with Swiss and German oral dosage manufacturers to lock out emerging competitors. For New Entrants and Emerging Players: Lead with fermentation-derived consistency targeting Korean and Japanese cosmetic formulators frustrated by seaweed-extraction batch variability. White-space opportunity concentrates in Indian pharmaceutical excipient demand, where CDSCO import quality tightening creates first-mover advantage for GMP-certified suppliers establishing local technical service presence. Direct-to-formulator digital platforms with instant COA access represent the optimal go-to-market angle for bypassing incumbent distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated brown-algae processors with captive harvesting operations and multi-year pharmaceutical supply agreements. Long-term viability over the coming decade favors suppliers with diversified sourcing geographies and fermentation-alternative optionality. Acquisition target archetype encompasses mid-cap hydrocolloid specialists with established REACH registration dossiers and underutilized esterification capacity. Signal to watch is ECHA substance evaluation outcomes tightening residual monomer thresholds, which would accelerate consolidation toward compliant integrated processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Harvesting | Captive kelp supply in Norway and Japan mitigates raw material volatility for pharmaceutical-grade output. |
| Supercritical Purification Capacity Expansion | Enables >99.5% purity achievement that satisfies Swissmedic and EMA pharmacopeial monograph requirements. |
| Long-term Supply Agreement Lock-ins | Three-to-five-year contracts with Basel and Zurich drug makers displace spot-market purchasing concentration. |
| Fermentation-Derived Alternative Development | Microbial alginate production bypasses seaweed harvest seasonality for Korean cosmetic formulator demand. |
| Direct-to-Formulator Digital Platform Launch | Validated excipient marketplaces with instant COA access reduce distributor dependency for emerging suppliers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs trade data, ECHA registration dossiers, FDA pharmacopeial monographs, and SEC filings from listed hydrocolloid processors. Primary interviews encompassed pharmaceutical formulation chemists, cosmetic R&D directors, brown-algae procurement managers, and specialty chemical distribution executives. Bottom-up triangulation across product-grade volume estimates and top-down validation against end-use industry consumption patterns ensured analytical consistency.
Segmentation dimensions modeled encompass product grade tier, end-use application, and regional regulatory cluster across the projection horizon. CAGRs were derived from regression analysis of historical price-volume relationships and forward-looking capacity expansion announcements. Forecast inputs incorporated kelp harvest yield projections, EMA quality standard revision timelines, and fermentation-technology maturity curves for microbial alginate alternatives.
Underlying assumptions cover sustained EMA and FDA pharmacopeial enforcement, stable brown-algae harvesting licensing regimes, and gradual fermentation-alternative cost parity achievement, with deviation risk concentrated in North Atlantic temperature anomalies affecting kelp yields and ECHA substance evaluation outcomes tightening residual-solvent thresholds. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals & Materials
Copper Wire Market
Chemicals & Materials
Zinc Ingots Market
Chemicals & Materials
Inlay Paper Market
Chemicals & Materials
Weathering Steel Market
Chemicals & Materials
Europe Hydrocarbon Solvents Market
Chemicals & Materials
Self Locking Nuts Market
Chemicals & Materials
Methidathion (CAS 950-37-8) Market
Chemicals & Materials
Pharma Grade Sodium Bicarbonate Market
Chemicals & Materials
Inorganic Salts Market
Chemicals & Materials
Neon Gas Market
Chemicals & Materials
Amla Extract Market
Chemicals & Materials
Photo Emulsion Market
Chemicals & Materials
Global 3D Printing Construction Material Market
Chemicals & Materials
Bleaching Chemicals Market
Chemicals & Materials
Isoeicosane Market
Chemicals & Materials
2-Ethylhexanol (2-EH) Market