
 Australia Industrial Insulation Market | 2026-2036
Australia Industrial Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Industrial Insulation Market Insights
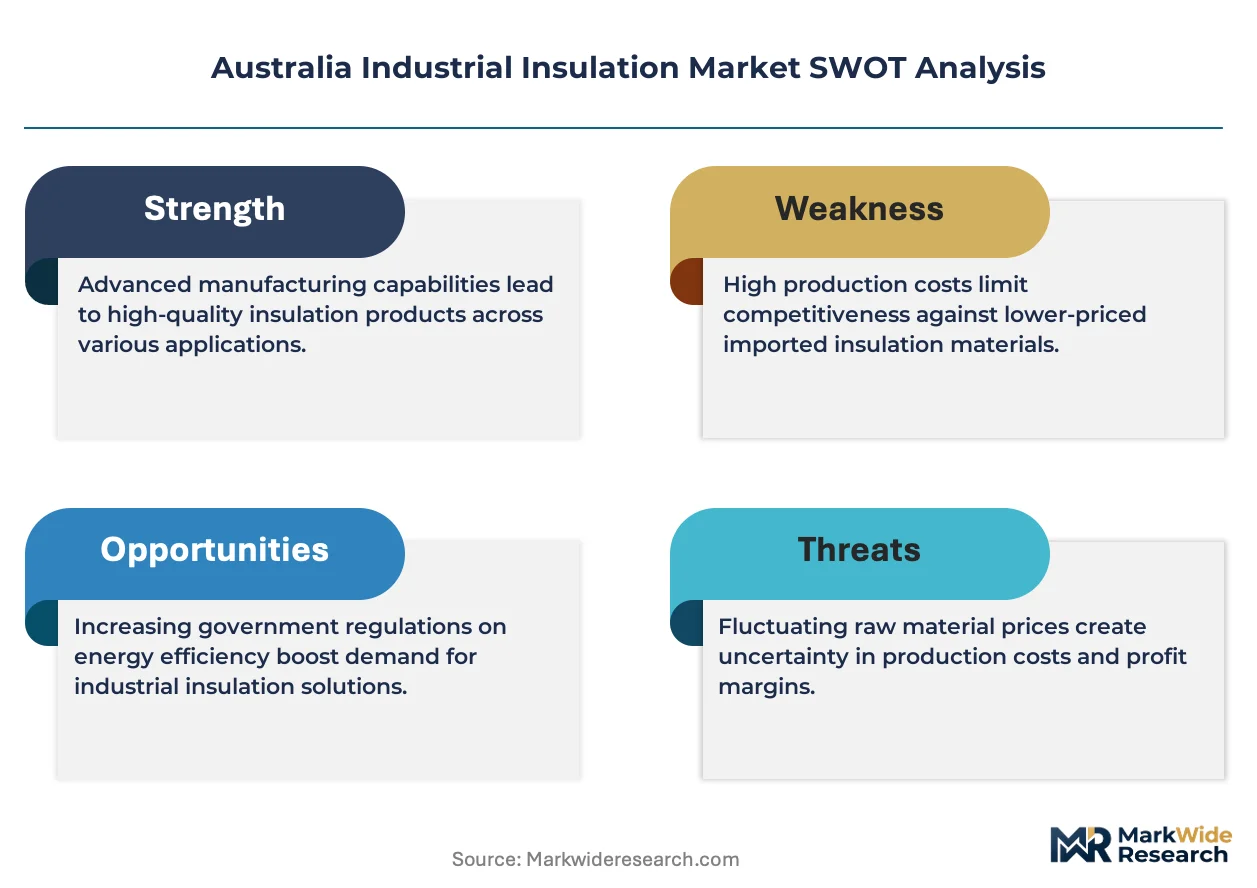
ISO 9001 and AS/NZS 4859.1 certification cycles is bifurcating the supplier base into qualified tier-one contractors and peripheral installers. Rockwool A/S leverages its mineral wool expertise to dominate high-temperature petrochemical applications across Western Australia. BASF SE sustains a strong position in foam systems through formulation R&D tied to LNG cold-chain infrastructure. Owens Corning competes aggressively in fiberglass duct and pipe wraps, capitalizing on established distribution through Melbourne and Sydney building supply channels.
Industrial insulation encompasses thermal, acoustic, and fire-resistant barrier systems engineered from mineral wool, fiberglass, cellular foam, or calcium silicate composites, typically specified by conductivity ratings below 0.045 W/m·K and operating thresholds spanning −180°C cryogenic service to 650°C process heat containment. Mineral wool and fiberglass categories anchor current revenue volumes due to their proven performance in power generation boiler lagging and chemical plant pipework. Calcium silicate segments occupy a premium niche in high-temperature equipment insulation where compressive strength and hydrophobic stability command superior pricing. Spray and wrap installation methods lead deployment preferences in retrofit-heavy brownfield sites across the Latrobe Valley and Newcastle manufacturing corridors.
TGA building product conformity assessments, NCC Section J energy efficiency provisions, and WorkSafe Australia thermal hazard standards collectively shape material selection and contractor accreditation requirements. The Australian Building Codes Board periodically escalates stringency, forcing reformulation cycles and recertification investments. Stakeholders must monitor state-level adoption lags between the NCC baseline and variations enforced by NSW Fair Trading versus Queensland Building and Construction Commission regimes.
Market Dynamics
The National Construction Code 2022 thermal performance mandates are compressing specification windows across Australian industrial builds, forcing reformulation investments and recertification cycles that favor established contractors over peripheral installers.
Growth Catalysts
- Queensland LNG export infrastructure:Cryogenic insulation demand concentrates at Curtis Island and Gladstone facilities, driving cellular foam and mineral wool uptake for liquefaction trains and storage tanks.
- NCC Section J energy efficiency provisions:Mandatory thermal bridging mitigation in new industrial construction expands specification volumes for high-performance insulation systems in processing plants and warehousing.
- Pilbara mining corridor process heat containment:Iron ore and lithium extraction operations require high-temperature boiler and pipe insulation, anchoring calcium silicate and mineral wool demand across Western Australia's northwest.
Market Restraints
- Aluminum and steel input cost volatility:Metal jacketing and cladding materials face commodity price swings that compress contractor margins on fixed-price industrial projects.
- Rockwool supply concentration in Western Australia:Domestic mineral wool production clusters near Perth, exposing Queensland and NSW projects to freight cost premiums and extended lead times.
- AS/NZS 4859.1 certification timeline friction:Extended TGA conformity assessment cycles delay product market entry, particularly for imported foam systems seeking fire performance ratings.
Strategic Opportunities
- Hydrogen energy pilot zones:Emerging electrolyzer and ammonia synthesis facilities in the Hunter Valley and Kwinana Industrial Strip create demand for cryogenic and high-temperature insulation systems.
- Latrobe Valley brownfield retrofit wave:Coal-to-renewables transition projects require extensive pipe and duct insulation replacement, favoring spray-applied cellular foams and wrap systems.
- WorkSafe Australia thermal hazard compliance:Stricter personnel protection mandates around high-temperature equipment expand specification scope for removable insulation blankets and jacketing systems.
Industry Challenges
- Certified insulation applicator shortages:ISO 9001 and AS/NZS 4859.1 qualified installation crews concentrate with tier-one contractors, creating bottlenecks for project execution in regional Queensland and Western Australia.
- Legacy asbestos remediation complexity:Brownfield sites in Newcastle and Port Kembla require hazardous material abatement before insulation replacement, extending project timelines and capex requirements.
- Multi-jurisdictional compliance fragmentation:Variations between NSW Fair Trading, QBCC, and Victorian Building Authority enforcement regimes complicate national contractor operations and product registration strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Industrial Insulation Market |
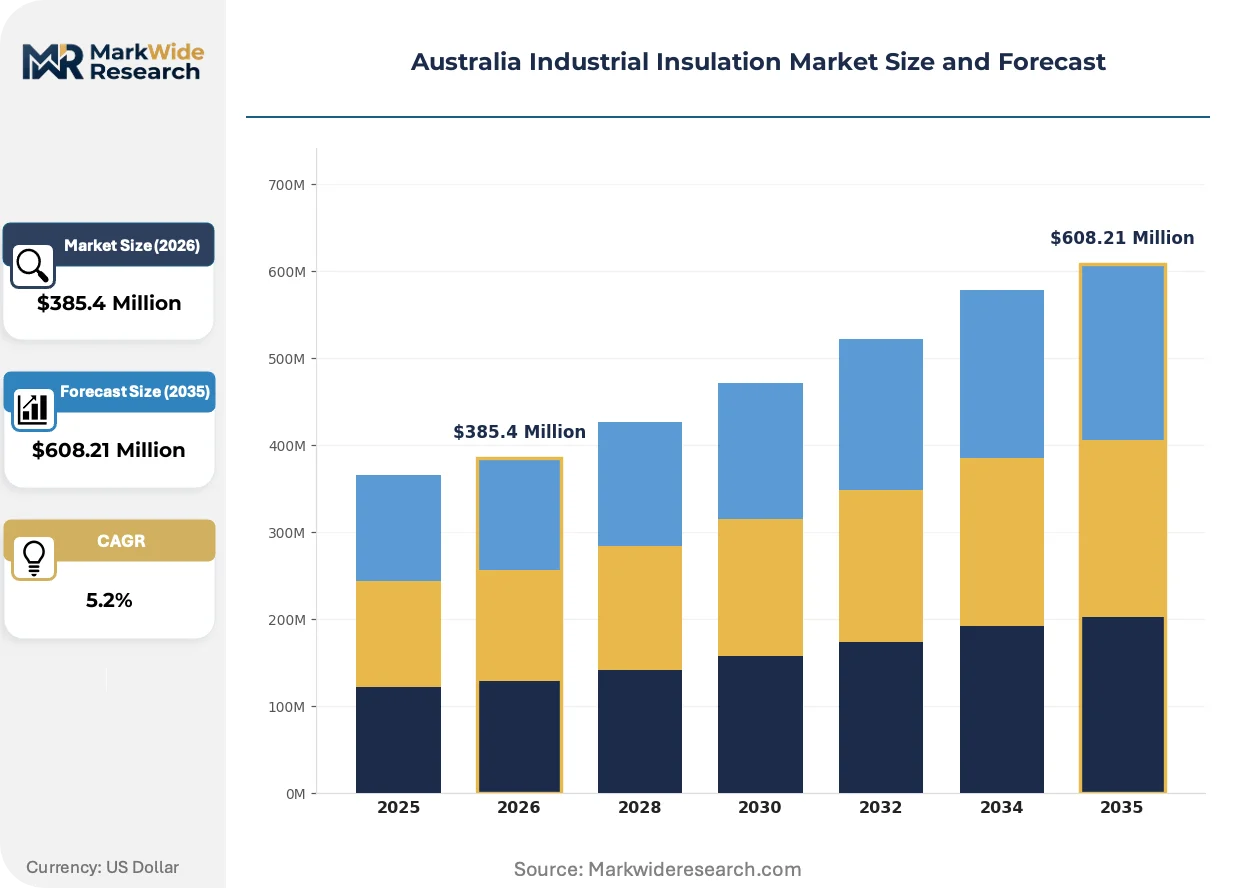
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $608.21 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Fiberglass, Mineral Wool, Foam, Calcium Silicate Application: Pipe Insulation, HVAC Systems, Equipment Insulation, Duct Insulation End User: Chemical, Oil & Gas, Manufacturing, Power Generation Installation Method: Spray, Wrap, Pre-formed, Blanket |
| Companies Covered | Rockwool A/S, BASF SE, Owens Corning, Johns Manville Corporation, Dow Inc., Kingspan Group plc, Knauf Insulation Inc., Autex Industries Ltd., Compagnie de Saint-Gobain S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Industrial Insulation Market Trends and Innovations
Aerogel composite systems and advanced cellular foam formulations are compressing traditional material categories, while regulatory stringency and procurement model evolution reshape how insulation services are contracted and delivered across Australian industrial corridors.
Aerogel-blanket insulation systems are displacing conventional mineral wool in subsea pipeline and LNG cold-chain applications. Woodside Energy and Santos specify these composites for cryogenic service at their Western Australian and Queensland export facilities. The technology is displacing established calcium silicate and cellular glass categories in premium-temperature applications where space constraints and thermal efficiency premiums justify material cost differentials.
The Australian Building Codes Board escalates NCC thermal performance baselines on three-year cycles, with 2025 amendments expected to tighten conductance thresholds for industrial building envelopes. This regulatory compression forces reformulation investments from foam system suppliers and accelerates mineral wool density upgrades. Western Australian petrochemical and LNG facilities face the steepest compliance ramps due to state-level adoption of NCC amendments ahead of eastern state lags.
Engineering-procurement-construction firms now bundle insulation scope within lump-sum turnkey contracts, compressing standalone specification autonomy for facility owners. This procurement consolidation shifts margin pressure onto specialized insulation contractors and favors vertically integrated construction groups with in-house installation capability. The pattern concentrates in Kwinana and Pilbara resource projects where Rio Tinto and BHP consolidate vendor bases to reduce interface risk.
Australia Industrial Insulation Market Segmentation
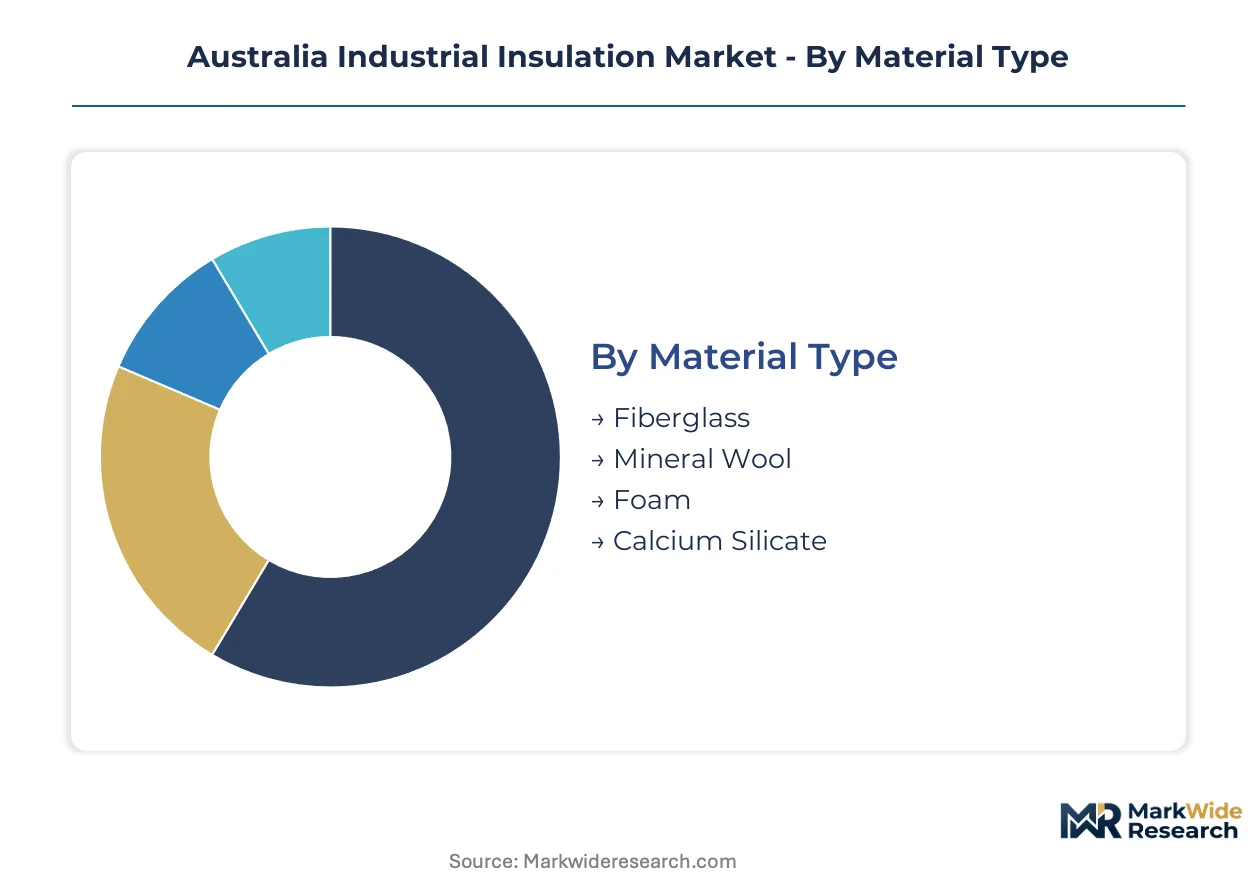
Industrial insulation procurement in Australia fragments across material chemistry, thermal performance requirements, and installation constraints. Specification decisions hinge on operating temperature ranges, fire compliance under AS/NZS 4859.1, and regional contractor availability across Queensland and Western Australia.
Material Type:
Domestic production clusters in Western Australia while Queensland and New South Wales rely on interstate freight corridors for mineral wool and foam systems.
- Mineral Wool:Manufactured from basalt or slag fibers with service temperatures to 650°C. Pilbara iron ore processing and Kwinana petrochemical facilities specify dense-grade formulations for boiler lagging and stack insulation. Western Australia's domestic production base supplies this segment, though Queensland LNG projects absorb significant volumes.
- Fiberglass:Borosilicate glass fibers bound with thermosetting resins, specified for conductivity ratings below 0.040 W/m·K. Melbourne and Sydney distribution channels move substantial duct-wrap and pipe-jacket volumes into manufacturing and commercial HVAC retrofits. Eastern state demand outpaces local manufacturing capacity.
- Foam:Polyurethane and polyisocyanurate cellular systems dominate cryogenic LNG applications at Curtis Island and Gladstone. Curtis Island liquefaction trains specify foam for storage tank bases and pipework.
- Calcium Silicate:Hydrous calcium silicate composites with compressive strength above 1000 kPa command premium positioning in high-temperature equipment insulation. Newcastle chemical plants and Port Kembla steelworks specify this material for reactor vessel lagging.
Mineral wool holds the largest share; momentum sits with foam systems serving LNG export infrastructure.
Application:
Cost tiering separates specification volumes, with pipe insulation commanding project-scale procurement and duct insulation fragmenting across maintenance budgets.
- Pipe Insulation:Pre-formed sections and field-applied wraps for process piping from -180°C cryogenic service to 540°C steam lines. Pilbara mining corridors and Kwinana industrial zones drive specification volumes for iron ore slurry lines and chemical transfer piping.
- Equipment Insulation:Custom-fabricated blankets and rigid sections for vessels, reactors, and turbines. High-temperature stability requirements favor calcium silicate and mineral wool composites in Western Australian resource processing.
- HVAC Systems:Chilled water piping, air handling units, and ductwork thermal barriers. NCC Section J compliance mandates expand specification scope in new industrial construction across Melbourne and Sydney manufacturing corridors.
- Duct Insulation:Internal lining and external wrap systems for air distribution networks. Fiberglass dominates due to acoustic absorption properties and established installer networks in eastern states.
Pipe insulation captures the greatest project value; equipment insulation is climbing the fastest on resource sector capex cycles.
End User:
Customer concentration varies sharply, with Oil & Gas consolidating procurement through EPC firms while Manufacturing fragments across facility maintenance budgets.
- Oil & Gas:LNG export facilities at Curtis Island, Gladstone, and Kwinana specify cryogenic and high-temperature systems through lump-sum turnkey contracts. Woodside Energy and Santos consolidate vendor bases to reduce interface risk.
- Chemical:Process heat containment and hazardous area compliance drive specification complexity. Kwinana Industrial Strip and Newcastle chemical corridors require AS/NZS 4859.1 certified installation crews.
- Power Generation:Latrobe Valley brownfield retrofits and emerging hydrogen pilot zones in the Hunter Valley create demand for pipe and duct replacement. Coal-to-renewables transition projects favor spray-applied cellular foams.
- Manufacturing:Food processing, pharmaceutical, and general industrial facilities specify HVAC and equipment insulation through fragmented maintenance procurement. Melbourne and Sydney building supply channels serve this segment.
Oil & Gas dominates contract value; Power Generation shows the steepest expansion trajectory on energy transition capex.
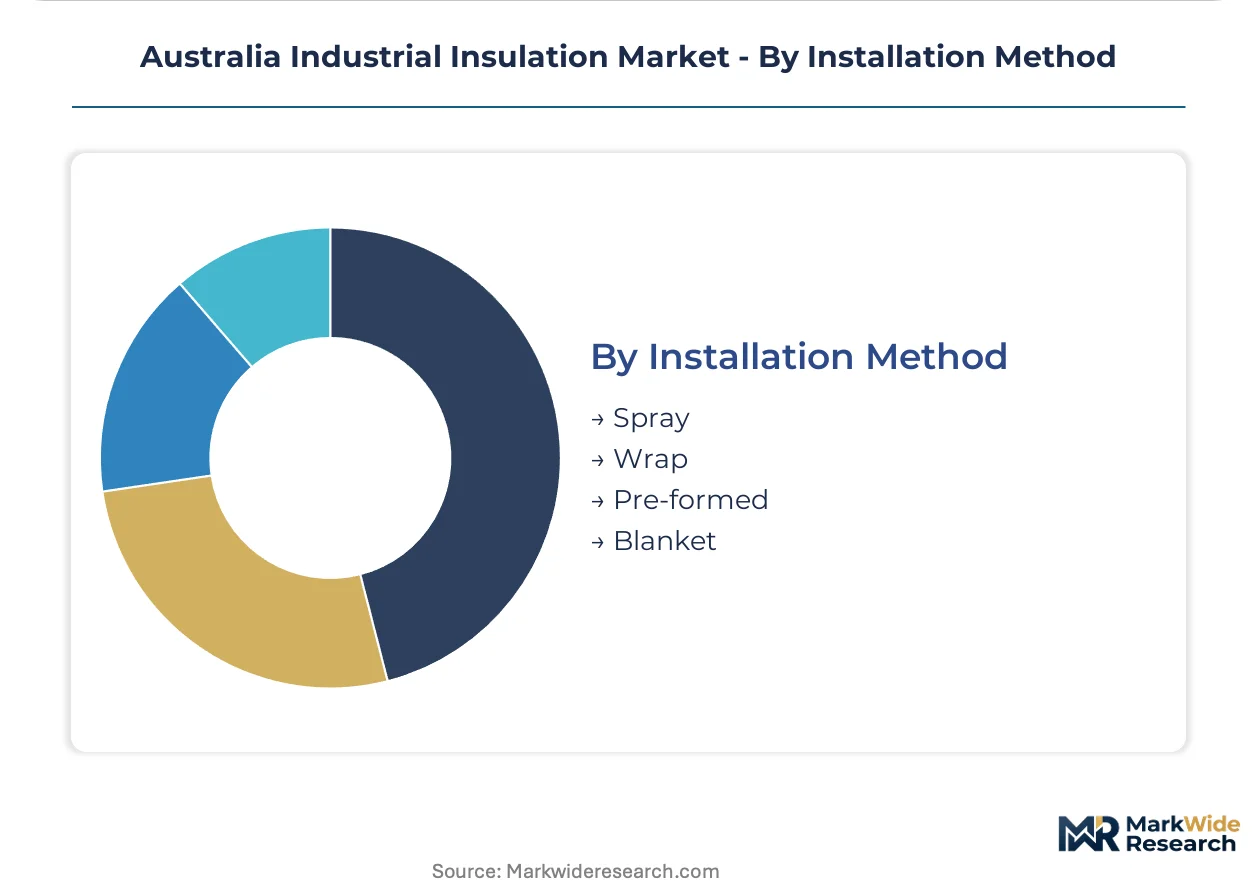
Installation Method:
Supply concentration sits with tier-one contractors holding ISO 9001 and AS/NZS 4859.1 accreditation, while peripheral installers compete on wrap and blanket applications.
- Wrap:Flexible jackets and tapes applied to irregular surfaces and retrofit pipework. Brownfield sites across the Latrobe Valley and Newcastle manufacturing corridors favor this method for expedited installation.
- Spray:Polyurethane and polyisocyanurate foam systems applied to complex geometries and large surface areas. LNG tank bases and industrial building envelopes in Queensland specify spray methods for seamless thermal barriers.
- Pre-formed:Factory-manufactured pipe sections and equipment covers requiring precision fitting. High-volume resource projects in the Pilbara specify pre-formed mineral wool and calcium silicate for schedule certainty.
- Blanket:Removable insulation pads for equipment requiring periodic maintenance access. WorkSafe Australia thermal hazard compliance expands specification scope for reusable blanket systems around high-temperature pumps and valves.
Wrap methods hold the largest installed base; spray applications are gaining share fastest on LNG infrastructure timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The National Construction Code 2022 thermal performance mandates and state-level adoption variations are redistributing insulation demand across Australian industrial corridors. Western Australia and Queensland concentrate resource-sector procurement, while eastern states face retrofit-intensive compliance ramps.
Western Australia
Pilbara iron ore operations and Kwinana petrochemical facilities anchor high-temperature insulation demand for calcium silicate and dense-grade mineral wool. The state's early adoption of NCC 2022 amendments forces accelerated specification upgrades ahead of eastern timelines. Perth-based production clusters supply mineral wool to regional mining corridors, though Queensland LNG projects draw significant interstate volumes.
Queensland
Curtis Island and Gladstone LNG export infrastructure drives cryogenic foam and mineral wool uptake for liquefaction trains and storage tanks. The Queensland Building and Construction Commission enforces NCC compliance with specific fire-performance documentation requirements for imported foam systems. Brisbane and Gladstone industrial zones concentrate contractor accreditation and material staging for northern resource projects.
New South Wales
Newcastle chemical corridors and Port Kembla steelworks specify calcium silicate for reactor vessel lagging amid brownfield asbestos remediation complexity. NSW Fair Trading maintains distinct enforcement timelines for NCC adoption, creating compliance lag versus Queensland and Western Australia. Sydney manufacturing corridors fragment HVAC and duct insulation procurement across maintenance budgets.
Victoria
Latrobe Valley coal-to-renewables transition projects generate pipe and duct insulation replacement demand, favoring spray-applied cellular foams. The Victorian Building Authority oversees thermal performance compliance with specific documentation requirements for industrial building envelopes. Melbourne distribution channels move substantial fiberglass duct-wrap volumes into manufacturing retrofits.
South Australia
Olympic Dam mining operations and emerging hydrogen pilot zones in the Upper Spencer Gulf create niche demand for high-temperature equipment insulation. State-level NCC adoption lags behind Western Australia, compressing contractor preparation windows. Adelaide-based installers face freight cost premiums for mineral wool sourced from Perth production clusters.
Australia Industrial Insulation Market Competitive Landscape
Player mix skews toward multinational material suppliers with established Australian distribution networks, tier-one contractors holding ISO 9001 and AS/NZS 4859.1 accreditation, and regional installers competing on wrap and blanket applications. The supplier base bifurcates between qualified contractors capable of NCC-compliant specification and peripheral installers facing recertification barriers. Dominant competitive moves include portfolio diversification across material chemistries and strategic partnerships with engineering-procurement-construction firms bundling insulation scope within turnkey contracts.
Among multinational material suppliers, Rockwool A/S and BASF SE occupy distinct positioning archetypes. Rockwool A/S represents the mineral wool specialist category with Western Australian production proximity to Pilbara and Kwinana demand centers. BASF SE exemplifies the foam systems formulator archetype, with specification ties to Queensland LNG cold-chain infrastructure. Owens Corning sits within the fiberglass distribution category, leveraging Melbourne and Sydney building supply channels for duct and pipe wrap penetration.
| Leading Market Players |
|---|
| Rockwool A/S |
| BASF SE |
| Owens Corning |
| Johns Manville Corporation |
| Dow Inc. |
| Kingspan Group plc |
| Knauf Insulation Inc. |
| Autex Industries Ltd. |
| Compagnie de Saint-Gobain S.A. |
| Others |
Pricing and Supply Chain Analysis
Western Australia's mineral wool production scale creates natural price floors that Queensland and New South Wales projects absorb through freight premiums. Capacity utilization at Perth-based manufacturing clusters tightens during Pilbara mining corridor expansion cycles, compressing margins for contractors bidding fixed-price industrial insulation packages across state borders.
Pricing Analysis
Certification level under AS/NZS 4859.1 creates the primary spread between tier-one contractor rates and peripheral installer quotes. Project-based pricing dominates, with lump-sum turnkey contracts bundling material and labor for LNG infrastructure. Price differentiation hinges on ISO 9001 accreditation status and fire-performance documentation depth. Cost compression in foam systems intensifies as imported polyisocyanurate faces extended TGA conformity timelines. Manufacturing maintenance budgets prove most price-sensitive, while Oil and Gas EPC consolidations negotiate volume discounts.
Supply Chain Analysis
Strategic stockpiling of metal jacketing materials prevails among tier-one contractors managing aluminum and steel input volatility. Domestic mineral wool production centers on Western Australia, while polyurethane foam systems draw from China and the United States. Raw material dependencies include basalt fiber, borosilicate glass, and petrochemical feedstocks. Single-source vulnerability concentrates in Perth-based mineral wool manufacturing serving Queensland LNG projects. Distribution runs through engineering-procurement-construction firms consolidating insulation scope within turnkey contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through EPC-led vendor consolidation at Rio Tinto and BHP resource projects, fragmenting standalone specification autonomy for facility owners and compressing margin capture for specialized contractors.
For Market Incumbents: Shield market position by deepening captive supply of AS/NZS 4859.1 certified installation crews in regional Queensland and Western Australia. Accelerate mineral wool density upgrades ahead of NCC 2025 amendment cycles. Aerogel composite displacement threatens premium-temperature applications; secure exclusive distribution partnerships with Woodside Energy and Santos before specification lock-in.
For New Entrants and Emerging Players: Differentiate on rapid-turnaround blanket fabrication for WorkSafe Australia thermal hazard compliance mandates. Target brownfield retrofit corridors in the Latrobe Valley and Newcastle where asbestos remediation complexity deters established contractors. Pursue direct procurement relationships with hydrogen pilot zone developers in the Hunter Valley and Kwinana Industrial Strip bypassing EPC intermediation.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among tier-one contractors holding multi-year maintenance agreements with Pilbara mining operators. Long-term viability rests on regulatory compliance depth rather than commodity material supply. Acquisition candidates include regional installers pursuing ISO 9001 accreditation to bridge the qualified labor gap. Watch for NCC adoption lag compression between Western Australia and eastern states as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Wool Manufacturing | Perth-based capacity additions reduce Queensland freight exposure and tighten contractor margins. |
| AS/NZS 4859.1 Certification Investment | TGA conformity acceleration unlocks imported foam system specification at Curtis Island LNG trains. |
| Joint Venture with EPC Firms | Insulation scope bundling within Kwinana and Pilbara turnkey contracts secures volume commitments. |
| Removable Insulation Blanket Product Line Expansion | WorkSafe Australia thermal hazard mandates expand addressable market around high-temperature pumps. |
| Hydrogen Infrastructure Partnership | Electrolyzer and ammonia synthesis facilities in the Hunter Valley create cryogenic specification demand. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, Australian Building Codes Board regulatory filings, WorkSafe Australia enforcement records, and SEC 10-K disclosures from multinational material suppliers. Primary interviews engaged plant engineers at Pilbara mining operations, procurement leads at Queensland LNG facilities, EPC contract managers, and tier-one insulation contractors holding ISO 9001 accreditation. Bottom-up project pipeline assessments triangulated against top-down material consumption estimates derived from NCC compliance mandate modeling.
Segmentation dimensions modeled include material chemistry, thermal performance tier, installation method, end-use industry concentration, and state-level regulatory adoption pattern across the projection horizon. CAGRs derive from volume-weighted capacity utilization trajectories at Western Australian mineral wool manufacturing clusters and Queensland LNG infrastructure commissioning schedules. Industry-specific forecast inputs incorporate TGA conformity assessment timeline assumptions and NCC amendment adoption lag differentials between jurisdictions.
Material uncertainties — commodity price swings in aluminum and steel jacketing, TGA processing delays for imported foam systems, and state-level NCC enforcement fragmentation — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding Pilbara mining corridor capex cycles and Latrobe Valley brownfield retrofit acceleration. Revision becomes warranted when hydrogen pilot zone commercialization crosses investment commitment thresholds or when NCC adoption lag between Western Australia and eastern states compresses beyond modeled parameters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Asphalt Modifiers Market
Building & Construction Materials
I-Joist Market
Building & Construction Materials
Global Roofing Market
Building & Construction Materials
United Kingdom Timber Cladding Market
Building & Construction Materials
Europe Green Buildings Market
Building & Construction Materials
Opening Trim Weatherstrips Market
Building & Construction Materials
Slimline Aluminum Window System Market
Building & Construction Materials
Rubber Expansion Joints Market
Building & Construction Materials
GCC Ceramic Tiles Market
Building & Construction Materials
Particleboard Market
Building & Construction Materials
Asia-Pacific Cross-Laminated Timber Market
Building & Construction Materials
Global Panelized and Modular Building System Market
Building & Construction Materials
Global Iron and Steel Casting Market
Building & Construction Materials
Global Rainscreen Cladding Market
Building & Construction Materials
Asphalt Market
Building & Construction Materials
Vapor Barriers Market