
 Remodeling Market | 2026-2036
Remodeling Market Size, Share, and Industry Trends Forecast 2026-2036
Remodeling Market Analysis
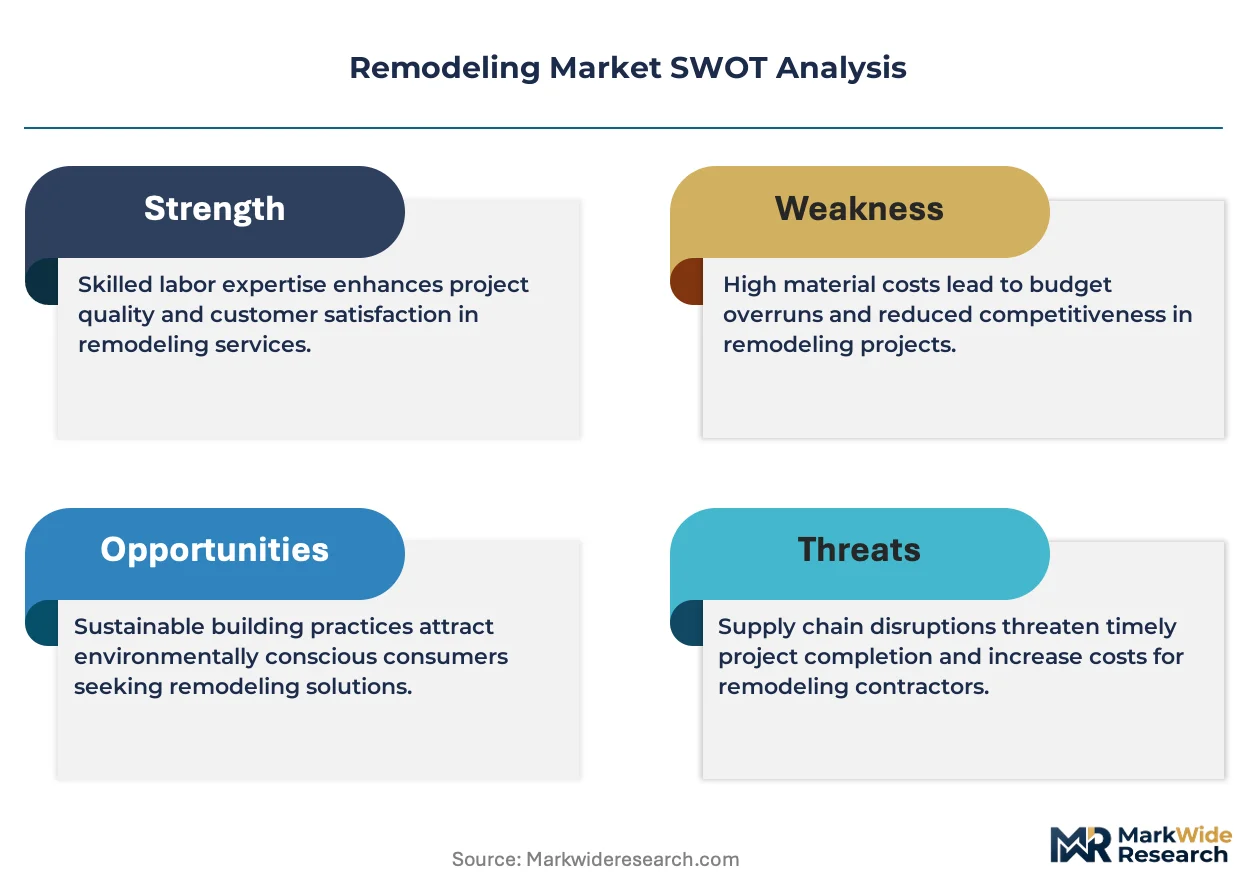
Multifamily property rehabilitation is expanding as institutional landlords upgrade Class B assets to capture rent premiums. BelFOR Holdings Inc. leverages its national catastrophe-response infrastructure to cross-sell planned remodeling services. Power Home Remodeling dominates exterior replacement categories through direct-to-consumer sales channels. ProEdge Remodeling specializes in regional kitchen and bath portfolios with in-house fabrication capabilities.
Remodeling encompasses the structural alteration, aesthetic upgrade, or functional reconfiguration of existing residential and commercial buildings through demolition, material substitution, system replacement, and spatial reconfiguration, typically requiring building permits and adherence to local codes. The process spans design consultation, material procurement, skilled trade execution, and project management to extend building service life or improve occupancy economics. Kitchen and bathroom project types anchor volume demand due to high homeowner willingness-to-pay and financing accessibility through home equity instruments. Wood and concrete material categories sustain margin pools through supply-chain proximity and regional fabrication networks. Contractor customer segments control scheduling and subcontractor selection, creating gatekeeper dynamics that shape vendor market access.
The US Department of Energy enforces appliance efficiency standards under authority delegated from Congress, directing material selection toward low-thermal-conductivity assemblies. EPA lead-safe certification requirements constrain contractor eligibility for pre-1978 housing work, filtering market participation by compliance capability. OSHA fall-protection mandates elevate scaffolding and roofing labor costs, compressing margins on steep-slope exterior projects. Stakeholders must monitor municipal zoning liberalization for accessory dwelling units, as permit streamlining in individual cities could unlock incremental addition-project demand.
Market Dynamics
The Inflation Reduction Act's energy-efficiency mandates are redirecting contractor capacity toward electrification retrofits and thermal envelope upgrades, compressing project timelines and reshaping material procurement priorities across residential portfolios.
Growth Catalysts
- Sun Belt Migration Patterns:Population inflows into metropolitan areas across Texas, Florida, and Arizona sustain above-average permit activity for whole-home renovations and additions.
- IRA Tax Credits:Federal incentives for heat pump installations and window replacements are accelerating homeowner willingness-to-finance deep energy retrofits.
- Aging Housing Stock:Pre-1980 single-family homes require systemic plumbing, electrical, and structural updates that drive recurring contractor demand.
Market Restraints
- Lumber Price Volatility:North American softwood supply disruptions create margin compression for framing-intensive projects.
- EPA Lead-Safe Certification:Pre-1978 housing work requires RRP-trained crews, filtering contractor eligibility and limiting labor pool depth.
- Skilled Trade Shortages:Plumber and electrician pipeline constraints extend project backlogs and elevate wage pressure.
Strategic Opportunities
- Accessory Dwelling Unit Liberalization:California and Oregon municipal zoning reforms are unlocking garage conversion and backyard cottage demand.
- Panelized Prefabrication:Factory-built wall and roof systems are converging with on-site assembly to compress weather-dependent schedules.
- Utility Rebate Stacking:Layered incentives from state energy offices and municipal light departments expand project scope for middle-income households.
Industry Challenges
- Permit Timeline Variability:Jurisdictional backlog dispersion creates scheduling uncertainty that strains subcontractor coordination.
- Digital Tool Adoption Gaps:Field crews resist 3D scanning and AR visualization platforms that design studios mandate for client approval workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remodeling Market |
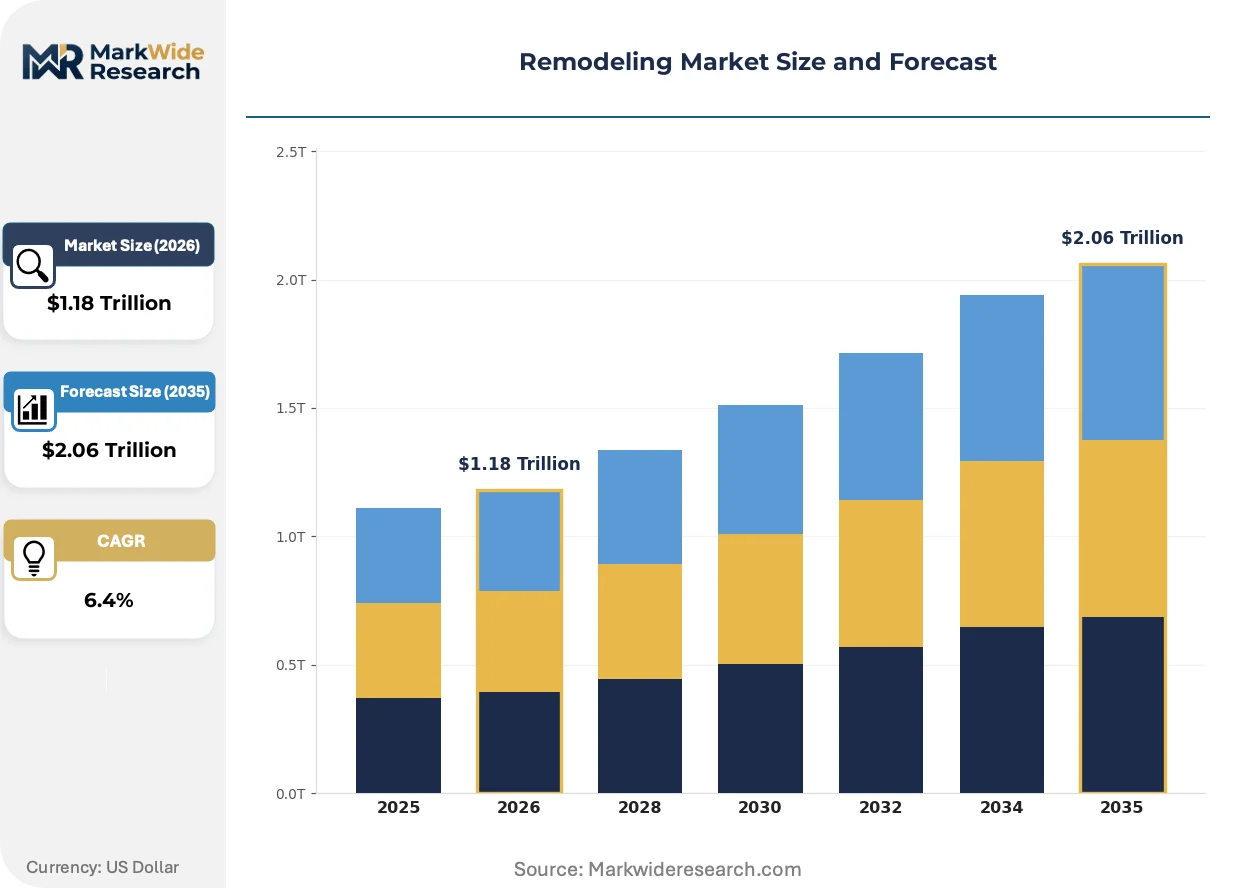
| Market Size in 2026 | $1.18 Trillion |
| Market Size in 2035 | $2.06 Trillion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Kitchens, Bathrooms, Additions, Living Rooms Material Type: Wood, Steel, Glass, Concrete Customer Type: Homeowners, Contractors, Property Managers, Developers Service Type: Design, Renovation, Consulting, Project Management |
| Companies Covered | Power Home Remodeling, ProEdge Remodeling, BelFOR Holdings Inc., Roofr, Porch Group, Leaf Home, Houzz, RenoFi, Great Day Improvements LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remodeling Market Emerging Trajectories
Electrification hardware and software platforms are rewiring competitive advantage around energy monitoring and grid-interactive controls rather than aesthetic finishes alone.
Heat pump water heaters are converging with smart home energy management systems to enable time-of-use optimization and demand-response participation. Multi-unit residential developers in the Pacific Northwest are specifying these packages at scale. The technology is converging with solar-plus-storage retrofits to create whole-home electrification bundles that displace gas appliance maintenance relationships.
OSHA fall-protection mandates for steep-slope roofing work have elevated scaffolding and safety equipment costs, compressing margins on exterior replacement projects. Contractors in Colorado and Utah mountain markets report 15-20% labor cost escalation for compliant crew deployment. The regulation is forcing portfolio diversification toward ground-level exterior work and interior renovations.
Home equity line utilization patterns are shortening project decision cycles from 90 days to 45 days as rate-sensitive homeowners lock financing before Fed adjustments. Direct-to-consumer sales organizations capture this compressed window through same-day estimate technology. The pattern concentrates in Sun Belt metros where appraisal velocity supports rapid credit approval.
Remodeling Market Segmentation
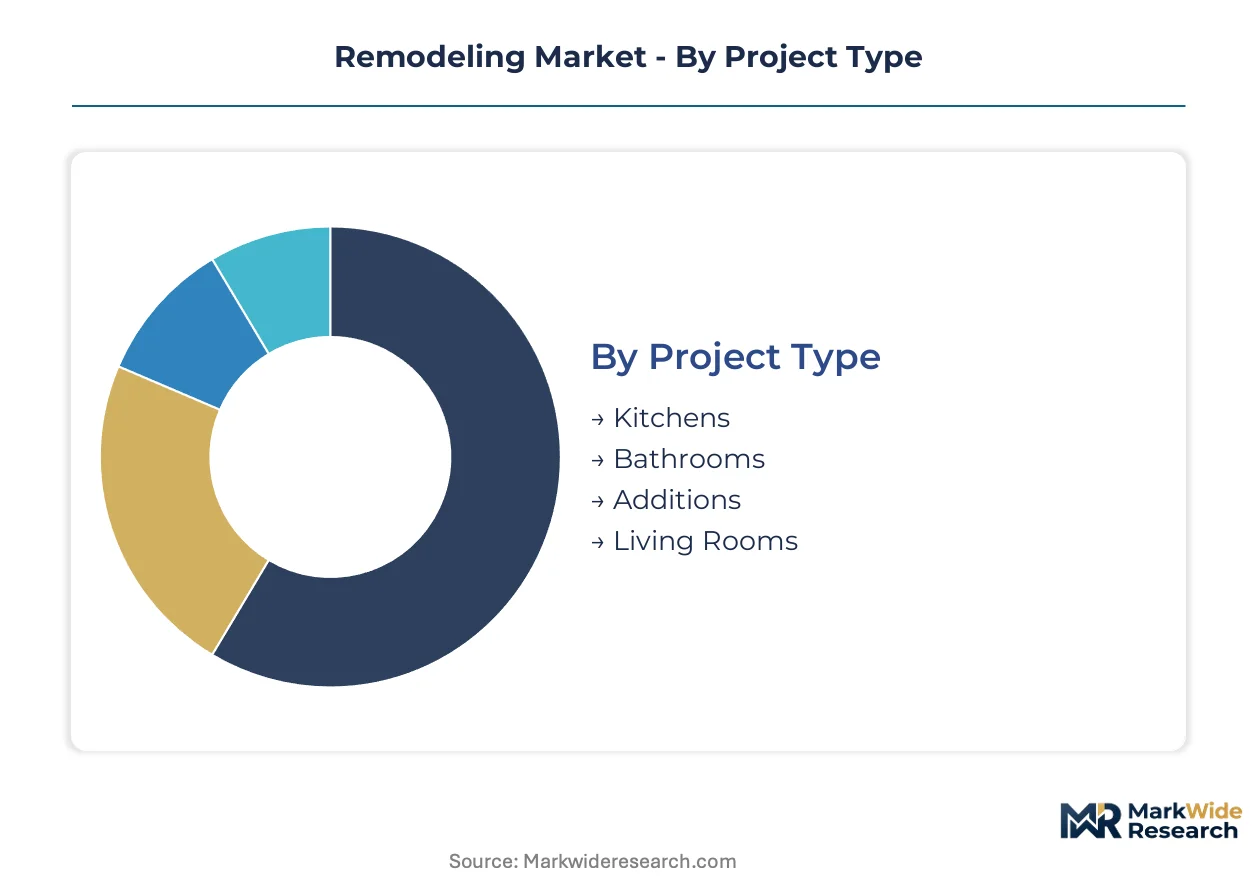
Remodeling market segmentation reveals how contractor capacity, material procurement, and financing access cluster around distinct project economics. Understanding these divisions exposes where margin pools concentrate and which customer relationships command pricing power.
Project Type:
Supply concentration in kitchen and bath fabrication networks shapes regional contractor specialization patterns.
- Kitchens:Cabinetry and countertop fabrication requires proximity to regional distribution hubs. Sun Belt metropolitan areas sustain above-average permit velocity for full-gut renovations driven by home equity accessibility.
- Bathrooms:Plumbing rough-in complexity filters contractor eligibility. EPA lead-safe certification requirements constrain pre-1978 housing work, compressing labor pool depth in Northeast and Midwest markets with older housing stock.
- Additions:Structural engineering and foundation work elevates project minimums. Municipal zoning liberalization for accessory dwelling units in California and Oregon is unlocking garage conversion demand.
- Living Rooms:Open-concept reconfigurations dominate volume in suburban single-family stock. Finishing trades concentrate margin in millwork and built-in specification.
Today's leader: Kitchens. Tomorrow's challenger: Additions.
Material Type:
Cost tier differentiation separates commodity framing from specification-grade architectural assemblies.
- Wood:North American softwood supply disruptions create margin compression for framing-intensive projects. Regional fabrication networks sustain margin pools through supply-chain proximity.
- Concrete:Foundation and hardscaping work anchors ground-level exterior portfolios. OSHA fall-protection mandates are forcing contractor diversification toward flatwork and patio construction.
- Steel:Structural beam replacement and modern aesthetic specification command premium positioning. Lead times from domestic mills constrain scheduling flexibility.
- Glass:Window replacement volumes accelerate under IRA tax credit eligibility. Low-thermal-conductivity assemblies direct material selection toward efficiency-mandated procurement.
Wood commands current volume. Glass is climbing the fastest on electrification retrofit alignment.
Customer Type:
Customer sophistication determines whether design studios or field crews control specification authority.
- Contractors:Gatekeeper dynamics shape vendor market access through scheduling and subcontractor selection control. Direct-to-consumer sales organizations bypass this channel at margin cost.
- Homeowners:Home equity line utilization patterns compress project decision cycles from 90 days to 45 days. Same-day estimate technology captures this financing-sensitive window.
- Property Managers:Institutional landlords upgrade Class B multifamily assets to capture rent premiums. Rehabilitation cycles concentrate in Sun Belt metropolitan inflow markets.
- Developers:New construction adjacent remodeling scales through panelized prefabrication integration. Factory-built wall systems compress weather-dependent schedules.
Contractors dominate current flow. Property Managers represent the steepest expansion trajectory on institutional capital deployment.
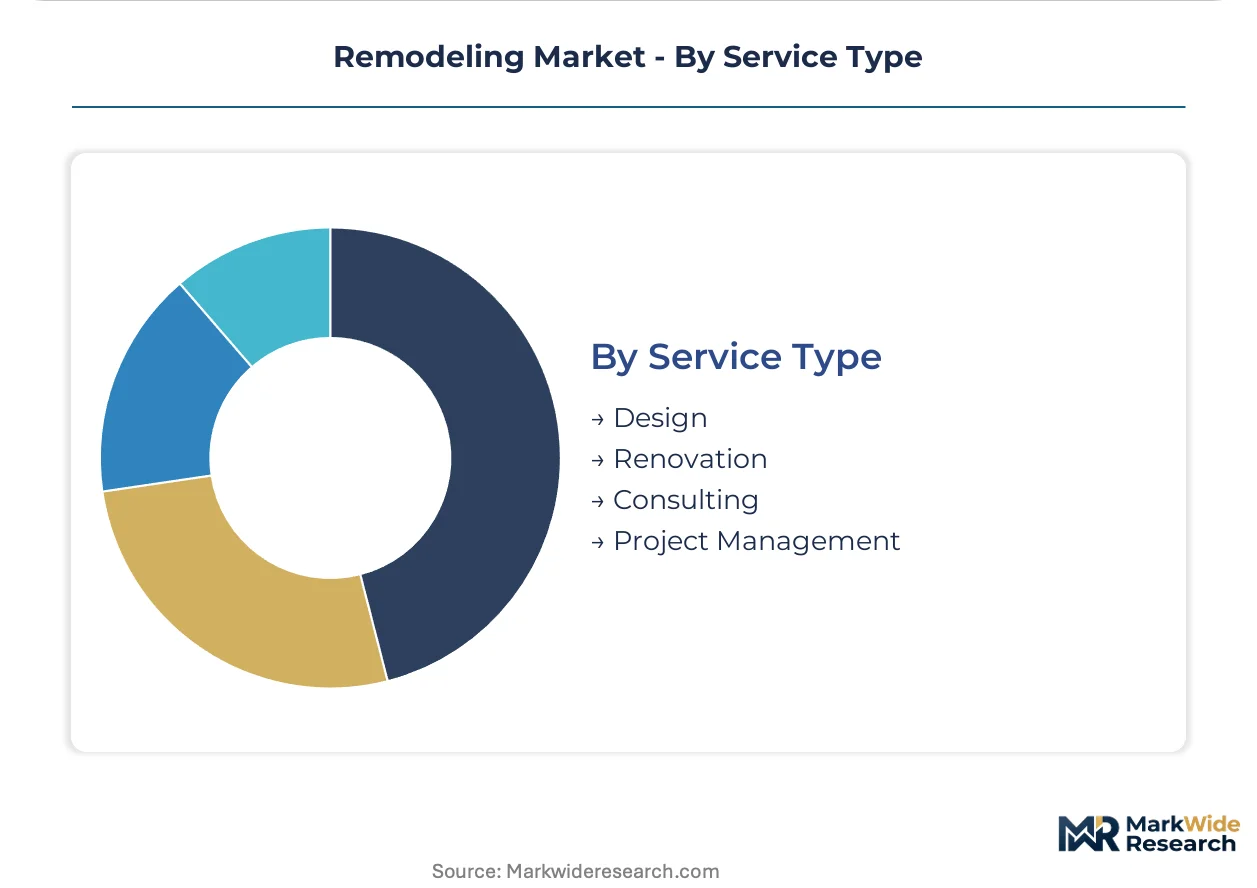
Service Type:
Service bundling separates design-build integrators from trade-specific subcontractors competing on labor rates.
- Renovation:Skilled trade execution spans demolition through finish carpentry. Plumber and electrician pipeline constraints extend project backlogs and elevate wage pressure.
- Design:3D scanning and AR visualization platforms face field crew resistance despite studio mandates for client approval workflows. Digital tool adoption gaps fragment coordination.
- Project Management:Permit timeline variability across jurisdictions strains subcontractor coordination. Municipal backlog dispersion creates scheduling uncertainty.
- Consulting:Energy audit and rebate stacking services expand project scope for middle-income households. Utility incentive layering from state energy offices drives advisory demand.
Renovation anchors revenue. Consulting is gaining share fastest on IRA incentive complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics in remodeling concentrate activity where energy-efficiency mandates create compliance cost gaps between jurisdictions. Contractor migration patterns follow municipal zoning liberalization and permit streamlining differentials across metropolitan markets.
United States
Sun Belt metropolitan areas in Texas, Florida, and Arizona sustain above-average permit velocity for whole-home renovations driven by population inflows. The Inflation Reduction Act directs material selection toward electrification retrofits through heat pump tax credits. Dallas-Fort Worth and Phoenix contractor networks expand capacity for thermal envelope upgrades.
Germany
Building energy efficiency regulations under the EU Green Deal accelerate deep retrofit demand for pre-1990 housing stock. The Federal Ministry for Economic Affairs and Climate Action funds facade insulation through KfW promotional programs. Industrial clusters in North Rhine-Westphalia concentrate panelized prefabrication capacity for multi-family rehabilitation.
Japan
Earthquake-resistant retrofit mandates drive structural reinforcement demand in aging wooden housing. METI enforces energy conservation standards for building materials under the Act on the Rational Use of Energy. Osaka-based contractors specialize in seismic isolation integration for mid-rise residential stock.
Australia
Climate-adaptive renovation demand concentrates in bushfire-prone and flood-affected regions requiring resilient material specification. The National Construction Code mandates minimum thermal performance standards for replacement windows and insulation. Sydney and Melbourne metropolitan areas anchor design-build firm networks for high-end residential alterations.
Canada
Cold-climate envelope upgrade programs accelerate demand for high-R-value insulation and triple-glazed window replacement. Natural Resources Canada administers the Greener Homes Initiative providing grants for heat pump and solar thermal installations. Toronto and Vancouver contractor markets specialize in heritage building retrofit compliance.
Remodeling Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with national direct-to-consumer sales organizations capturing financing-sensitive homeowners while regional fabrication specialists dominate kitchen and bath procurement channels. Market structure fragments across local subcontractor networks and vertically integrated design-build platforms. Three archetypes anchor positioning: catastrophe-response infrastructure cross-sellers, exterior replacement category dominators, and regional in-house fabrication specialists. Competitive moves concentrate on geographic expansion through acquisition and portfolio diversification toward energy-efficiency retrofit bundles.
Within the catastrophe-response cross-selling tier, BelFOR Holdings Inc. exemplifies infrastructure leverage for planned remodeling services. Power Home Remodeling and ProEdge Remodeling occupy positions on the exterior replacement and regional fabrication vectors respectively, representing divergent channel strategies for market access.
| Leading Market Players |
|---|
| Power Home Remodeling |
| ProEdge Remodeling |
| BelFOR Holdings Inc. |
| Roofr |
| Porch Group |
| Leaf Home |
| Houzz |
| RenoFi |
| Great Day Improvements LLC |
| Others |
Supply Flow & Price Mechanics
North American softwood lumber costs cascade through three distinct pricing tiers as framing contractors absorb volatility while design-build integrators pass through specification-grade markups. Labor wage pressure from OSHA fall-protection compliance and EPA lead-safe certification requirements compresses margins at the subcontractor layer, forcing portfolio shifts toward ground-level exterior work and factory-built assemblies.
Pricing Analysis
Distributor margins on commodity building materials compress under direct-to-consumer sales channel expansion from national exterior replacement specialists. Three-tier pricing structure across premium, standard, and economy levels separates turnkey design-build packages from trade-specific bids and big-box retail procurement. Cost compression in the subcontractor tier is intensifying because skilled trade shortages extend project backlogs and elevate wage pressure. Property managers exhibit lowest price sensitivity due to institutional capital deployment timelines, while middle-income homeowners financing through home equity instruments show highest sensitivity to project scope adjustments.
Supply Chain Analysis
Workforce availability constraints in Pacific Northwest and Sun Belt manufacturing geographies limit panelized prefabrication capacity expansion for thermal envelope assemblies. Supply concentration spans Canada for softwood framing, Mexico for millwork fabrication, and domestic regional hubs for concrete flatwork. Raw material dependencies draw from North American lumber futures, Chinese aluminum extrusions for window systems, and domestic steel from domestic mills with extended lead times. Single-source vulnerability concentrates in heat pump water heater imports for electrification retrofit bundles. Distribution runs through contractor-controlled procurement networks with emerging direct-to-homeowner bypass channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The remodeling market functions as a stable compounder anchored by irreversible housing stock aging and recurring maintenance demand cycles. IRA tax credits and municipal zoning liberalization provide incremental growth layers without speculative technology dependencies.
For Market Incumbents: Lock in regional fabrication capacity through captive supply agreements for cabinetry and countertop networks before skilled trade pipeline constraints deepen. Defend against direct-to-consumer sales organizations by embedding project management software into homeowner financing workflows. Prioritize EPA RRP certification density to filter pre-1978 housing work eligibility in Northeast and Midwest markets.
For New Entrants and Emerging Players: Same-day estimate technology platforms offer the most penetrable route for capturing compressed home equity decision windows in Sun Belt metropolitan areas. Target accessory dwelling unit permitting services in California and Oregon municipal zones where zoning liberalization outpaces contractor capacity. Pursue utility rebate stacking advisory as a service wedge to differentiate from commodity installation bids.
For Investors and Strategic Acquirers: Consolidation pressure builds where regional fabrication specialists lack succession planning and institutional capital seeks Class B multifamily rehabilitation exposure. Five-to-ten year viability favors design-build integrators with in-house permitting expertise and energy audit capabilities. Watch permit timeline variability across jurisdictions as the signal indicating where municipal backlog dispersion creates acquisition timing advantages.
| Strategic Initiative | Industry Significance |
|---|---|
| Panelized Prefabrication Capacity Expansion | Factory-built wall systems compress weather-dependent schedules in Pacific Northwest markets. |
| Energy Audit Service Integration | IRA tax credit complexity drives advisory demand from middle-income homeowner segments. |
| Direct-to-Consumer Sales Platform Buildout | Same-day estimate technology captures compressed home equity financing decision windows. |
| EPA Lead-Safe Certification Investment | RRP-trained crew density filters eligibility for pre-1978 housing work in aging stock regions. |
| Accessory Dwelling Unit Permitting Specialization | Municipal zoning liberalization in California and Oregon unlocks garage conversion demand. |
Methodological Framework
Coverage spans the United States, Germany, Japan, Australia, and Canada, with primary inputs from each market informing cross-regional pattern identification. The study combines structured interviews with general contractors, design studio principals, municipal permitting officials, and institutional property managers alongside secondary validation from US Department of Energy appliance efficiency filings, EPA RRP certification databases, and Natural Resources Canada Greener Homes Initiative disbursement records. Bottom-up project-type segmentation triangulates against top-down construction spending aggregates.
Rate-of-change decomposition separates volume drivers from value-per-project escalation across the projection horizon. Segmentation dimensions modeled include project type, material category, customer archetype, and service bundling configuration, with regional regulatory cluster effects layered as interaction terms. CAGRs derive from permit velocity trends, home equity utilization patterns, and electrification retrofit adoption curves without assuming technology discontinuities.
The model assumes a particular technology adoption path for heat pump water heater and thermal envelope upgrade penetration; alternative pathways for whole-home electrification bundles would alter the outlook if natural gas infrastructure maintenance relationships prove stickier than projected. Forecasts reflect assumptions regarding IRA incentive continuity, municipal zoning reform velocity, and skilled trade pipeline recovery. Material deviation in permit backlog dispersion, lumber futures volatility, or Fed policy adjustments on home equity access warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Branched Reinforced Fittings Market
Building & Construction Materials
United Kingdom Prefab Wood Buildings Market
Building & Construction Materials
US Steel Merchant and Rebar Market
Building & Construction Materials
North America Cross-Laminated Timber Market
Building & Construction Materials
Insulating Glass Window Market
Building & Construction Materials
GCC Ceramic Tiles Market
Building & Construction Materials
Asia-Pacific Ceramic Sanitary Ware Market
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
Europe Ready-Mix Concrete Market
Building & Construction Materials
US Commercial Windows Market
Building & Construction Materials
North America Rainscreen Cladding Market
Building & Construction Materials
Middle-East and Africa Gypsum Board Market
Building & Construction Materials
Welded Steel Tanks Market
Building & Construction Materials
North America Residential Water Heater Market
Building & Construction Materials
Plastic Formwork Market
Building & Construction Materials
Risers Market