
 Global Power Grid System Market | 2026-2036
Global Power Grid System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Power Grid System Market Outlook
Aftermarket service revenue is tilting toward predictive maintenance and digital asset management as primary margin pools. Siemens Energy leverages its digital twin platforms to extend service contracts across aging European infrastructure. ABB anchors its position through integrated substation automation and HVDC converter stations. General Electric competes on gas turbine-to-grid integration and grid-scale battery control systems.
A power grid system comprises generation interconnection, high-voltage transmission networks, and medium-to-low voltage distribution infrastructure operating at frequencies of 50 Hz or 60 Hz with nominal voltages ranging from 110 kV to 765 kV for long-distance transmission. Its primary purpose is to deliver electrical energy from centralized and distributed sources to end users with minimal losses while maintaining voltage stability and frequency regulation. Substation equipment commands the largest share of capital expenditure due to transformer and switchgear replacement cycles. Smart grid technology represents the fastest-expanding segment as utilities deploy advanced metering infrastructure and distributed energy resource management systems. Control systems concentrate margin pools where cybersecurity certification and real-time analytics capabilities differentiate vendors.
The US Federal Energy Regulatory Commission mandates grid reliability standards through mandatory reporting requirements under Critical Infrastructure Protection protocols. Europe's CSRD disclosure rules and EU Green Deal taxonomy are forcing utilities to document grid asset carbon footprints and circularity metrics. China's National Energy Administration enforces GB standards for ultra-high voltage transmission corridors. Stakeholders must monitor how divergent cybersecurity mandates between NERC CIP and IEC 62351 frameworks affect cross-border equipment procurement and software interoperability.
Market Dynamics
The collision of aging transformer fleets with mandatory F-Gas phaseouts across Europe is forcing simultaneous capital replacement and refrigerant conversion, compressing procurement cycles and vendor qualification timelines.
Growth Catalysts
- India's National Smart Grid Mission:Central government funding targets 100% smart metering in urban distribution zones, creating immediate demand for AMI hardware and DERMS software stacks.
- Electrification of transport corridors:Highway fast-charging networks in Germany and California require 350 kV+ substation upgrades and dynamic load-balancing controls.
- Solid-state transformer R&D maturation:Silicon carbide power electronics enable compact, bidirectional substation designs that reduce footprint constraints in dense Japanese and South Korean urban centers.
Market Restraints
- Copper and grain-oriented electrical steel volatility:Transformer core material costs swing with mining output from Chile and Indonesia, squeezing OEM margins on fixed-price utility contracts.
- Specialized EPC contractor concentration:Ultra-high voltage installation expertise clusters among state-linked Chinese and Russian firms, limiting competitive procurement for cross-border transmission projects.
- Sulfur hexafluoride containment mandates:Europe's F-Gas Regulation imposes strict leakage monitoring on GIS switchgear, extending commissioning timelines and compliance documentation burdens.
Strategic Opportunities
- Brazil's Amazon basin electrification:Isolated community microgrids with containerized solar-plus-storage bypass transmission buildout costs entirely.
- AI-driven predictive maintenance:Machine learning models trained on dissolved gas analysis data from transformer oil samples unlock performance-based service contracts.
- Green hydrogen electrolyzer co-location:Grid-connected 100 MW+ electrolysis plants in Denmark and the Netherlands create demand for harmonic filtering and reactive power compensation equipment.
Industry Challenges
- Protection engineer scarcity:Specialized expertise in IEC 61850 protocol implementation and substation cybersecurity configuration commands 40% wage premiums in North American and Australian markets.
- Multi-vendor SCADA integration complexity:Legacy DNP3.0 systems from the 1990s resist seamless interoperability with modern cloud-based analytics platforms, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Power Grid System Market |
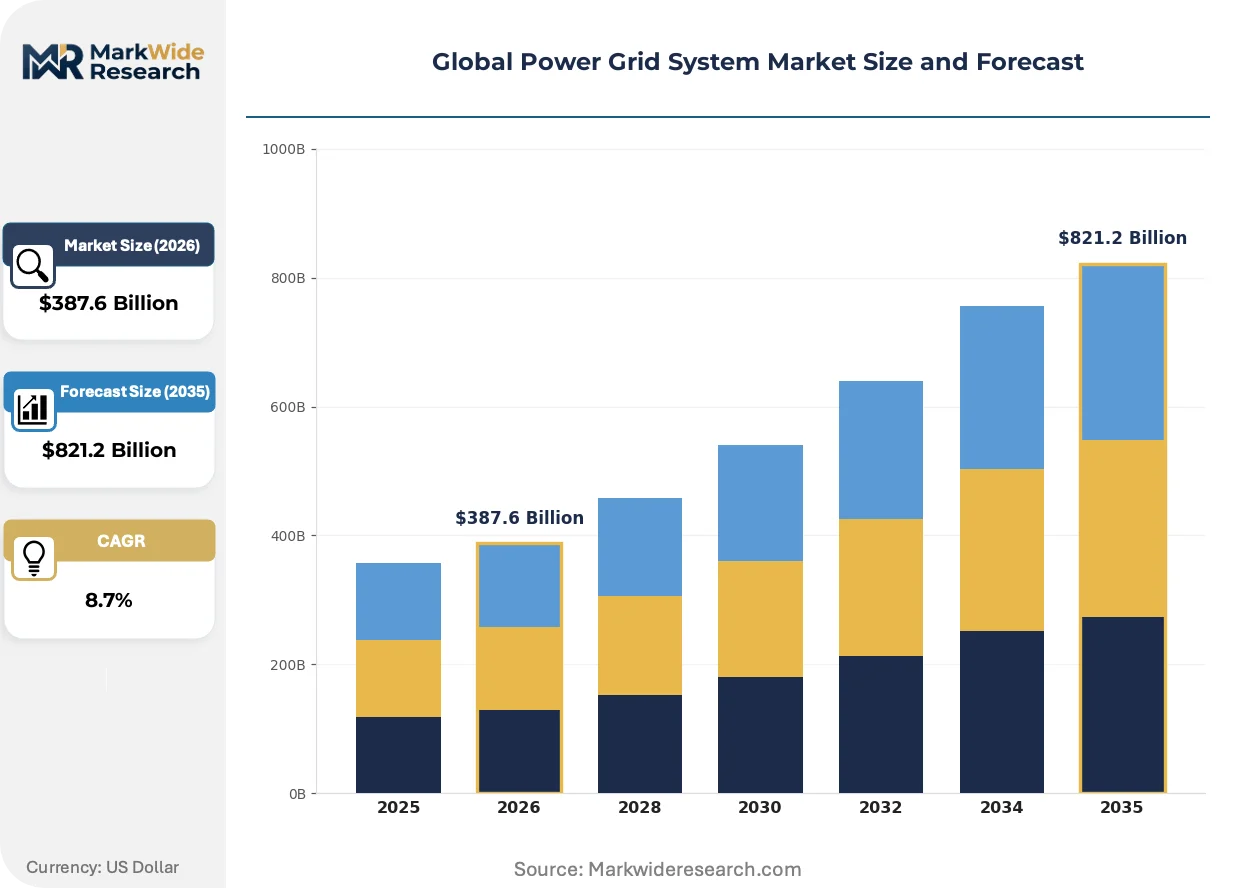
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Substation Equipment, Transmission Lines, Distribution Equipment, Control Systems Technology: Smart Grid, High Voltage Direct Current, Wireless Communication, Energy Management Systems End User: Utility Providers, Independent Power Producers, Government Agencies, Industrial Consumers Application: Renewable Integration, Load Management, Grid Security, Energy Distribution |
| Companies Covered | Siemens Energy, ABB, General Electric, Schneider Electric, Hitachi Energy, Mitsubishi Electric, Prysmian Group, Eaton, Nexans, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Power Grid System Market Strategic Shifts
Digital twin architectures and wide-area monitoring systems are compressing the feedback loop between physical grid events and control room response, eliminating the latency that previously defined contingency management.
Silicon carbide power semiconductors enable solid-state transformers with 50% volume reduction and bidirectional power flow capability. European distribution utilities in Denmark and the Netherlands pilot these units at urban substations where space constraints block conventional equipment upgrades. The technology is collapsing the historical separation between transmission-scale and distribution-scale voltage conversion hardware.
Europe's CSRD disclosure rules now mandate granular Scope 3 emissions reporting for grid infrastructure capex, forcing utilities to document embodied carbon in transformer cores and switchgear housings. Equipment suppliers face pressure to certify circular material content and end-of-life recyclability. German and French transmission operators have begun inserting carbon intensity clauses into procurement specifications.
Utility procurement departments now unbundle hardware purchase from 20-year service agreements, creating separate competitive bidding events for asset management and predictive analytics. This bifurcation favors software-native entrants over integrated OEM incumbents in the Middle East and Southeast Asian markets where greenfield buildout dominates. Saudi Arabia's grid modernization program exemplifies this split-contract structure.
Global Power Grid System Market Segmentation
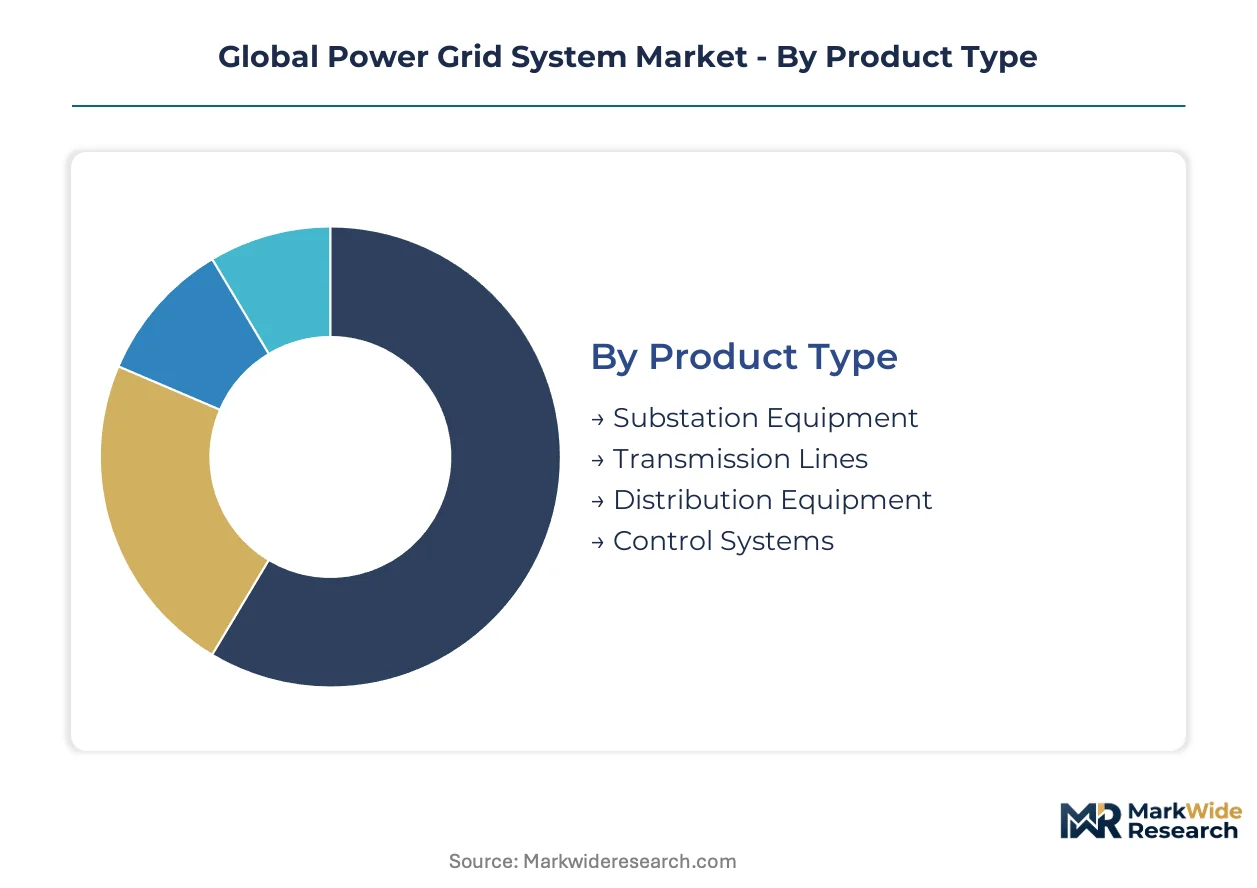
Power grid system segmentation reveals divergent investment cycles across hardware replacement, digital overlay, and customer archetypes. Equipment vendors must align R&D roadmaps with the asynchronous maturity curves governing substation hardware, smart grid software, and industrial offtake patterns.
Product Type:
Mature transformer and switchgear categories coexist with emerging solid-state designs, creating a bifurcated procurement landscape where utilities balance reliability certification against footprint reduction.
- Substation Equipment:Transformers, switchgear, and reactive compensation hardware constitute the capital-intensive core of grid infrastructure. Demand concentrates in Germany and Japan where aging oil-immersed transformer fleets face simultaneous F-Gas phaseout deadlines and seismic resilience upgrades.
- Transmission Lines:Overhead conductors, underground cables, and ultra-high voltage towers enable bulk power transfer across territorial scales. China and India dominate procurement volume through state-led corridor development linking remote generation to coastal load centers.
- Distribution Equipment:Medium-voltage switchgear, ring main units, and pole-mounted transformers deliver power to end users. Brazil and Saudi Arabia drive replacement demand through rural electrification mandates and urban densification programs.
- Control Systems:SCADA platforms, protection relays, and synchrophasor networks govern real-time grid operations. European utilities prioritize cybersecurity-hardened IEC 61850 implementations following NIS2 directive enforcement.
Substation Equipment retains volume leadership; Control Systems holds the steepest expansion curve.
Technology:
Cost tier differentiation separates premium digital architectures from commoditized electromechanical foundations, with procurement committees increasingly unbundling hardware from software service layers.
- Smart Grid:Advanced metering infrastructure, demand response platforms, and distributed energy resource management systems digitize distribution networks. India's National Smart Grid Mission funds 100% urban smart metering, creating immediate AMI hardware demand.
- High Voltage Direct Current:Converter stations and submarine cables enable asynchronous grid interconnection and offshore wind integration. Denmark and the Netherlands deploy HVDC corridors to connect North Sea wind farms to continental load.
- Wireless Communication:Private LTE, 5G private networks, and mesh radio systems replace leased telecom circuits for field device connectivity. Australian utilities pilot 5G for protection relay tripping in bushfire-prone regions.
- Energy Management Systems:Generation dispatch optimization and wholesale market trading platforms balance supply-demand economics. Independent power producers in Texas and the UK procure EMS upgrades to capture volatility price spikes.
Smart Grid commands premium pricing tiers; Wireless Communication is climbing the fastest on unit shipment growth.
End User:
Customer type determines contract structure, with government-funded utilities favoring 20-year service bundles while industrial offtakers prioritize availability guarantees and power quality specifications.
- Utility Providers:Vertically integrated and unbundled distribution companies operate regulated transmission and distribution infrastructure. State-owned utilities in China and Saudi Arabia dominate capital deployment through centralized procurement.
- Independent Power Producers:Merchant generators and renewable developers require interconnection equipment and grid code compliance systems. IPPs in Brazil and Mexico drive demand for harmonic filtering and reactive power compensation.
- Government Agencies:Rural electrification authorities and defense installations procure isolated microgrids and resilient backup systems. India's REC and Brazil's ANEEL administer concessional financing for last-mile connectivity.
- Industrial Consumers:Mining, smelting, and semiconductor fabrication facilities purchase dedicated substations and premium power quality equipment. German automotive battery gigafactories demand voltage sag immunity and dynamic load balancing.
Utility Providers retain volume leadership; Industrial Consumers are expanding most quickly on manufacturing reshoring investments.
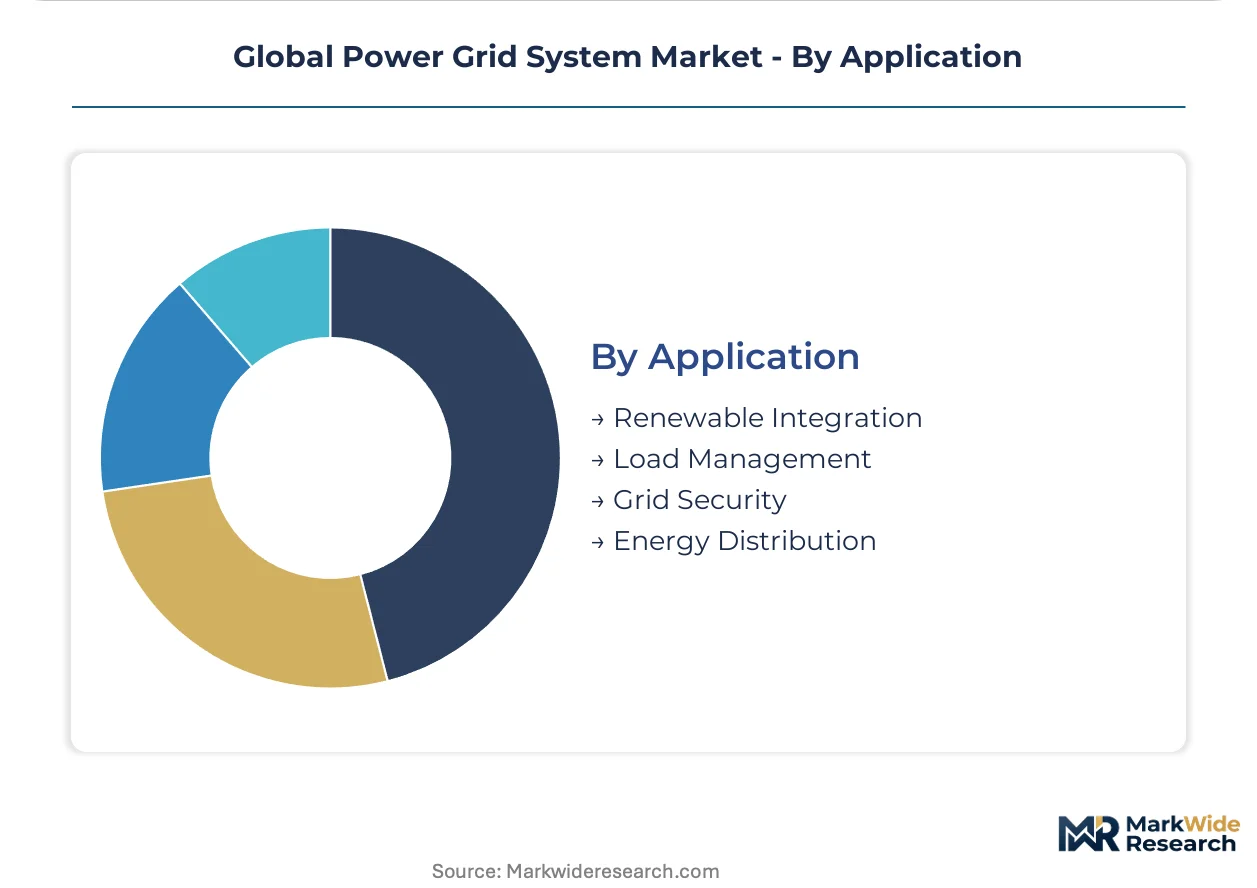
Application:
Geography shapes application priority, with renewable-rich regions prioritizing integration infrastructure while load-constrained markets emphasize demand-side management and security hardening.
- Renewable Integration:Grid-forming inverters, synchronous condensers, and storage coupling equipment stabilize variable generation output. California and Germany lead procurement for solar and wind interconnection upgrades.
- Load Management:Demand response aggregation, time-of-use pricing infrastructure, and flexible load control reduce peak capacity requirements. Japanese utilities deploy load management to defer nuclear restart capacity investments.
- Grid Security:Physical perimeter protection, cyber intrusion detection, and geomagnetic disturbance monitoring defend critical infrastructure. NERC CIP enforcement drives North American cybersecurity procurement cycles.
- Energy Distribution:Last-mile automation, outage management systems, and voltage optimization reduce technical losses. South Korean distribution utilities prioritize distribution automation for dense urban networks.
Renewable Integration retains volume leadership; Grid Security holds the steepest expansion trajectory on regulatory mandate acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ultra-high voltage transmission corridors concentrate manufacturing capacity and EPC expertise among Chinese state-linked enterprises, while European utilities grapple with simultaneous F-Gas phaseouts and transformer fleet replacement cycles.
China
The National Energy Administration enforces GB standards for ultra-high voltage transmission corridors linking remote western generation to coastal load centers. State Grid Corporation deploys thousand-kilometer UHVDC lines across the Gobi Desert and Tibetan Plateau. Xian and Shenyang host domestic transformer manufacturing clusters serving both domestic buildout and Belt and Road export contracts.
United States
FERC mandates grid reliability standards through Critical Infrastructure Protection protocols requiring mandatory cybersecurity reporting. Texas and California utilities procure grid-scale battery control systems and dynamic load-balancing equipment for renewable integration. ERCOT and CAISO market operators drive demand for generation dispatch optimization platforms.
Germany
The F-Gas Regulation imposes strict leakage monitoring on gas-insulated switchgear, compressing procurement timelines for SF6-free alternatives. Transmission operators TenneT and 50Hertz insert carbon intensity clauses into transformer procurement specifications. Hamburg and Munich distribution utilities pilot solid-state transformers for urban substation footprint reduction.
India
The Central Electricity Authority oversees National Smart Grid Mission funding targeting complete urban smart metering deployment. State-owned utilities in Maharashtra and Gujarat accelerate AMI hardware procurement and DERMS software stack integration. Rural Electrification Corporation administers concessional financing for last-mile distribution automation in Bihar and Uttar Pradesh.
Brazil
ANEEL regulates concessional financing for Amazon basin electrification through isolated community microgrids. State utilities in São Paulo and Minas Gerais deploy containerized solar-plus-storage systems bypassing transmission buildout costs. The Belo Monte transmission corridor drives demand for harmonic filtering equipment at grid connection points.
Global Power Grid System Market Competitive Environment
Integrated industrial conglomerates and specialized power equipment manufacturers split the market between bundled turnkey solutions and component-focused supply relationships. The vendor base concentrates among European and Japanese industrial groups with century-long certification histories in high-voltage equipment, alongside emerging Chinese state-linked EPC contractors capturing ultra-high voltage installation contracts. Two dominant competitive moves define current positioning: unbundling hardware procurement from long-term service agreements to capture predictive maintenance revenue pools, and silicon carbide power electronics R&D investments enabling next-generation solid-state transformer portfolios.
Among diversified European industrial groups, Siemens Energy and ABB occupy positions spanning digital twin platforms through integrated substation automation, while Hitachi Energy exemplifies the Japanese conglomerate archetype with deep vertical integration in HVDC converter stations and protection relay systems. These three companies represent contrasting strategic postures toward software-native service revenue versus hardware-centric equipment supply.
| Leading Market Players |
|---|
| Siemens Energy |
| ABB |
| General Electric |
| Schneider Electric |
| Hitachi Energy |
| Mitsubishi Electric |
| Prysmian Group |
| Eaton |
| Nexans |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Rotterdam maritime freight corridors transmit copper and grain-oriented electrical steel cost volatility directly into transformer OEM pricing spreads, compressing margins on fixed-price utility contracts while amplifying price differentiation between certified and non-certified equipment tiers.
Pricing Analysis
Europe's F-Gas Regulation dictates the pricing tier structure across gas-insulated switchgear procurement, separating SF6-compliant premium tiers from conversion-ready standard offerings. Three-tier pricing stratifies across IEC 61850-certified premium systems, legacy-compatible standard platforms, and economy-grade electromechanical alternatives. Cost compression in the standard tier intensifies as Chinese state-linked EPC contractors underbid European incumbents on Belt and Road corridor projects. Government-funded utilities in Saudi Arabia and India exhibit lowest price sensitivity due to concessional financing availability, while independent power producers in Brazil and Mexico face acute margin pressure.
Supply Chain Analysis
Copper cathode from Chilean mining concessions and grain-oriented electrical steel from Japanese and Korean rolling mills feed transformer core manufacturing clusters in China, Germany, and India. Silicon carbide wafers draw from US and Japanese semiconductor foundries, creating single-source vulnerability for solid-state transformer R&D programs. Distribution runs through state-linked procurement portals in China and Saudi Arabia alongside competitive tendering platforms in Europe and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The power grid system market exhibits cyclical recovery characteristics anchored to transformer fleet replacement cycles and F-Gas phaseout deadlines across European transmission networks.
For Market Incumbents: Insulate service revenue pools by unbundling predictive analytics contracts from hardware supply agreements, responding to software-native entrants capturing DERMS procurement in Southeast Asian greenfield markets. Deepen backward integration into silicon carbide power electronics to secure solid-state transformer cost positions against Japanese conglomerates.
For New Entrants and Emerging Players: Pursue containerized microgrid deployment opportunities in Brazil's Amazon basin and India's unelectrified districts, where transmission bypass economics favor modular solar-plus-storage architectures over centralized infrastructure. Target AMI hardware supply contracts under India's National Smart Grid Mission through joint venture structures with domestic system integrators.
For Investors and Strategic Acquirers: Specialized cybersecurity-hardened control system developers with IEC 62351 certification capabilities represent priority acquisition targets as NIS2 enforcement accelerates European utility procurement cycles. Long-term viability hinges on software service revenue durability rather than equipment replacement cyclicality. Monitor FERC CIP audit violation trends as early indicator of North American cybersecurity spending inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Development | Machine learning models trained on transformer dissolved gas analysis data unlock performance-based service contracts with European transmission operators. |
| SF6-Free Switchgear Certification | EU F-Gas Regulation compliance positions vendors for accelerated procurement timelines as TenneT and 50Hertz phase out gas-insulated systems. |
| Solid-State Transformer Pilot Deployment | Silicon carbide-based urban substation units address footprint constraints in Hamburg and Munich distribution networks. |
| HVDC Converter Station Expansion | North Sea wind interconnection demand in Denmark and Netherlands drives order book visibility for asynchronous grid coupling equipment. |
| AMI Hardware Localization | Domestic manufacturing partnerships in Maharashtra and Gujarat align with India's National Smart Grid Mission localization requirements. |
Study Parameters
Operator-level perspectives from utility planning officers, IPP project developers, EPC contractors, and grid operations directors anchored the qualitative base for this analysis. Primary interview data combined with secondary validation from FERC filings, IEA transmission investment reports, EIA grid infrastructure databases, and project development tracking platforms. Bottom-up equipment shipment analysis and top-down utility capex triangulation informed market sizing across substation hardware, control systems, and digital overlay segments.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling volume and value outputs through segmentation across voltage tier, technology maturity curve, end-user procurement structure, and regional regulatory framework. CAGRs derived from utility capital deployment pipelines and equipment replacement cycle analysis. Forecast inputs incorporated transformer fleet age demographics, F-Gas phaseout enforcement calendars, and smart grid subsidy allocation trajectories.
Macroeconomic conditions sit as an overlay; deviation in copper and electrical steel commodity indices, freight rate volatility, and emerging market currency stability would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timing and technology cost reduction curves. Cross-checking against IEA World Energy Investment benchmarks and national utility regulatory filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Temporary Power Generation & Power Rental Market
Power Generation
Myanmar Power Generation EPC Market
Power Generation
Indonesia Power Generation EPC Market
Power Generation
Captive Power Plant Market
Power Generation
South East Asia Power Market
Power Generation
Mobile Power Plant Market
Power Generation
Combined Cycle Power Plant Market
Power Generation
South America Thermal Power Market
Power Generation
Captive Power Generation Market
Power Generation
Global Distributed Energy Generation Market
Power Generation
Canada Power EPC Market
Power Generation
Power Plant EPC Market
Power Generation
Australia Thermal Power Market
Power Generation
Gas Fired Power Plant Market
Power Generation
Indonesia Power Market
Power Generation
India Thermal Power Plant Market