
 Asia-Pacific Distributed Power Generation Market | 2026-2036
Asia-Pacific Distributed Power Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Distributed Power Generation Market Outlook
Chinese solar module manufacturers are rebalancing capacity toward n-type TOPCon and heterojunction cell architectures, tightening supply availability for legacy p-type lines across Southeast Asia. Trina Solar Limited leverages its integrated polysilicon-to-module footprint to sustain margin control in Australia's utility-scale segment. JinkoSolar Holding Co. Ltd. anchors procurement contracts with Indonesian and Vietnamese industrial parks seeking captive renewable supply. Schneider Electric SE competes on microgrid control software and energy management platforms that integrate solar, storage, and backup generation into unified dispatch systems.
Asia-Pacific distributed power generation encompasses modular electricity production assets sited near or within consumption centers, typically operating below 50 MW per installation and employing reciprocating engines, gas turbines, photovoltaic arrays, or fuel cells with combined heat recovery. These systems serve commercial and industrial loads requiring resilience against transmission congestion, voltage fluctuation, or tariff volatility inherent to centralized grid architectures. Solar technology dominates incremental capacity additions across the region, though hybrid systems pairing PV with lithium-ion energy storage are capturing the fastest growth as islanding capabilities and time-shifted dispatch become standard procurement requirements. Fuel cells remain nascent outside Japan and South Korea, where Toshiba Fuel Cell Power Systems Corporation and domestic hydrogen infrastructure pilots sustain early adoption curves.
India's CEA mandates technical standards for grid-connected distributed generation, while China's MIIT enforces GB certification for inverter efficiency and harmonic limits; Australia's Clean Energy Regulator operates the Small-scale Renewable Energy Scheme, which shapes residential solar economics through tradable certificate mechanisms. Japan's METI oversees feed-in tariff transitions that now steer commercial and industrial adopters toward market-linked power purchase frameworks. Stakeholders must monitor how evolving carbon border adjustments and domestic content requirements across these jurisdictions reshape equipment sourcing strategies and project finance structures.
Market Dynamics
China's MIIT enforcement of GB certification for inverter efficiency and harmonic limits is compressing equipment qualification timelines across Southeast Asian procurement chains, forcing developers to pre-certify components before bid submission.
Growth Catalysts
- India's PLI scheme for solar manufacturing:Domestic module and cell production incentives are redirecting capital toward captive supply chains, reducing import dependency for Vietnamese and Indonesian project developers.
- Commercial and industrial rooftop demand:State-level net metering policies across Maharashtra, Gujarat, and Karnataka are enabling hybrid system deployments at scale for textile and automotive manufacturing clusters.
- Lithium-ion battery cost compression:Falling cell prices are making solar-plus-storage configurations economically viable for islanding capabilities in Philippine and Thai industrial parks.
Market Restraints
- Polysilicon supply concentration:Xinjiang-based ingot production dominates upstream feedstock, exposing Southeast Asian module assemblers to forced labor due diligence disruptions and tariff exposure.
- Land acquisition friction:Industrial rooftop solar in India faces tenancy fragmentation and structural load verification delays that extend project development timelines.
- Grid code heterogeneity:Australia's Clean Energy Regulator, India's CEA, and Japan's METI maintain incompatible interconnection standards, fragmenting inverter design specifications.
Strategic Opportunities
- Vietnamese industrial zone electrification:Northern manufacturing hubs near Hanoi lack transmission capacity, creating captive microgrid demand for gas-solar hybrid configurations.
- Australia's Small-scale Renewable Energy Scheme:Tradable certificate mechanisms for residential solar are extending into commercial strata properties, opening aggregated behind-the-meter portfolios.
- Fuel cell convergence with hydrogen pilots:Toshiba Fuel Cell Power Systems deployments in Kobe and Fukuoka are validating proton exchange membrane integration with existing gas infrastructure.
Industry Challenges
- Power systems engineering talent scarcity:Microgrid control software deployment requires expertise in both utility protection schemes and distributed energy resource management platforms that remains concentrated in Tokyo and Bangalore.
- Legacy diesel asset stranding:Indonesian and Philippine island grids carry substantial reciprocating engine capacity with residual book value, complicating hybrid retrofit financing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Distributed Power Generation Market |
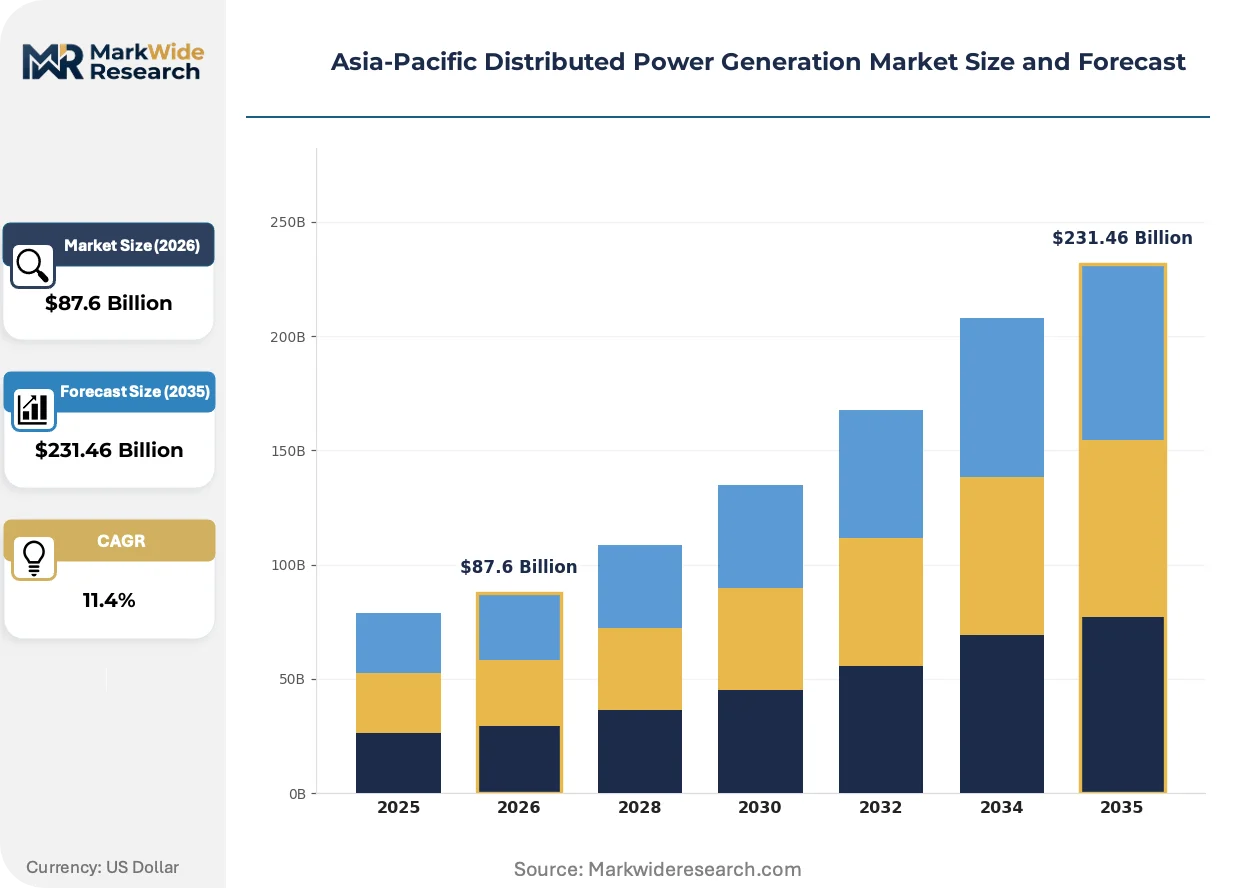
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $231.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Biomass, Fuel Cells Product Type: Microgrid, Hybrid Systems, Energy Storage, Smart Meters End User: Residential, Commercial, Industrial, Utilities Installation Type: On-site, Off-site, Grid-connected, Standalone |
| Companies Covered | Trina Solar Limited, Schneider Electric SE, Caterpillar Inc., Siemens AG, Canadian Solar Inc., JinkoSolar Holding Co. Ltd., Sharp Solar Energy Solutions Group, Toshiba Fuel Cell Power Systems Corporation, Cummins Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Distributed Power Generation Market Strategic Shifts
n-type TOPCon cell architectures are rewriting equipment procurement specifications across the Asia-Pacific distributed generation value chain, compressing p-type module viability windows and accelerating fab retooling decisions.
Heterojunction cell production lines are rewriting the cost-performance frontier for high-temperature climates. Australian utility-scale developers are specifying bifacial glass-glass constructions with temperature coefficients below minus 0.26 percent per degree Celsius. This architecture is compressing mono-PERC margins and forcing Southeast Asian module distributors to clear legacy inventory.
Japan's METI feed-in tariff transition is rewriting commercial power purchase frameworks. The shift from guaranteed 20-year rates to market-linked contracts is redirecting C&I adopters toward self-consumption optimization and battery dispatch strategies. Australian and Indian regulators are monitoring this mechanism for potential adoption.
Industrial offtakers are consolidating procurement through engineering-procure-construct contractors with captive financing arms. Vietnamese textile manufacturers and Thai automotive suppliers are bypassing traditional equipment distributors, instead contracting directly with integrated developers. This channel compression is most visible in Ho Chi Minh City and Bangkok industrial corridors.
Asia-Pacific Distributed Power Generation Market Segmentation
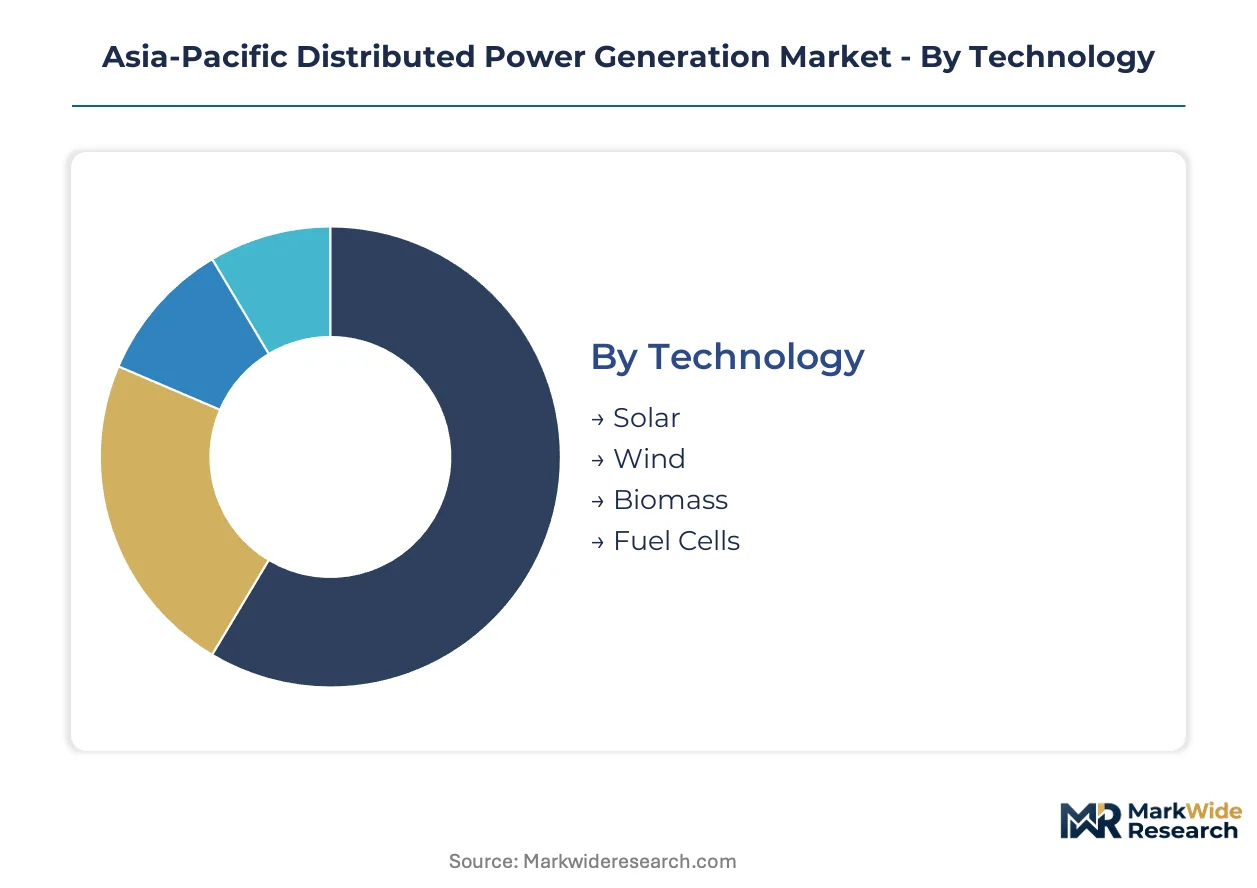
Technology heterogeneity across Asia-Pacific distributed generation creates distinct procurement channels, financing structures, and regulatory compliance pathways. Each segmentation axis reveals how developers align equipment specifications with site constraints, offtaker risk profiles, and grid interconnection standards.
Technology:
Cell architecture and fuel chemistry dictate project development timelines, equipment sourcing strategies, and O&M contracting models across the region.
- Solar:n-type TOPCon and heterojunction cell architectures dominate new capacity, with bifacial glass-glass modules specified for high-temperature climates in Australia and Southeast Asia. Indian textile clusters and Vietnamese industrial parks are procuring rooftop arrays with 25-year performance warranties to hedge against tariff volatility.
- Fuel Cells:Proton exchange membrane systems integrated with existing gas infrastructure are validating commercial viability in Japanese hydrogen pilot zones. Toshiba deployments in Kobe and Fukuoka demonstrate 40% electrical efficiency with combined heat recovery for district applications.
- Wind:Small-scale turbines below 1 MW serve remote mining and island communities where solar resource variability requires generation diversity.
- Biomass:Agricultural residue-fired reciprocating engines provide baseload capability for Thai and Indonesian palm oil processing facilities with captive feedstock supply.
Mature deployment sits with Solar. Newer deployment is concentrated in Fuel Cells.
Product Type:
System integration depth determines margin capture and customer stickiness across the value chain.
- Hybrid Systems:Solar-plus-lithium-ion configurations with islanding capability are becoming standard procurement specifications for Philippine and Thai industrial parks. Falling cell prices and state-level net metering policies in Maharashtra and Gujarat enable 4-8 hour storage dispatch.
- Microgrid:Gas-solar hybrid configurations address transmission congestion in northern Vietnamese manufacturing hubs near Hanoi. Schneider Electric control platforms integrate distributed resources into unified dispatch systems with utility-grade protection schemes.
- Energy Storage:Standalone battery installations provide frequency regulation and peak shaving for Australian C&I offtakers under market-linked contract structures.
- Smart Meters:Advanced metering infrastructure enables time-of-use optimization and demand response participation for Japanese commercial adopters transitioning from feed-in tariffs.
Volume concentrates in Hybrid Systems. Steepest expansion trajectory belongs to Microgrid deployments.
End User:
Load profile characteristics and risk tolerance shape technology selection and financing structures.
- Industrial:Captive renewable supply contracts anchor procurement for Indonesian and Vietnamese manufacturing parks seeking resilience against grid unreliability. Textile and automotive clusters bypass traditional distributors, contracting directly with integrated EPC developers.
- Commercial:Strata properties and retail portfolios in Australian cities are aggregating behind-the-meter assets through tradable certificate mechanisms extended from residential schemes.
- Residential:Rooftop solar penetration varies sharply across the region, with Australia's Small-scale Renewable Energy Scheme driving highest adoption rates through certificate trading.
- Utilities:Distribution companies deploy distributed assets as non-wires alternatives to transmission upgrades in congested corridors.
Revenue concentration sits with Industrial. Emerging volume is building in Commercial aggregated portfolios.
Installation Type:
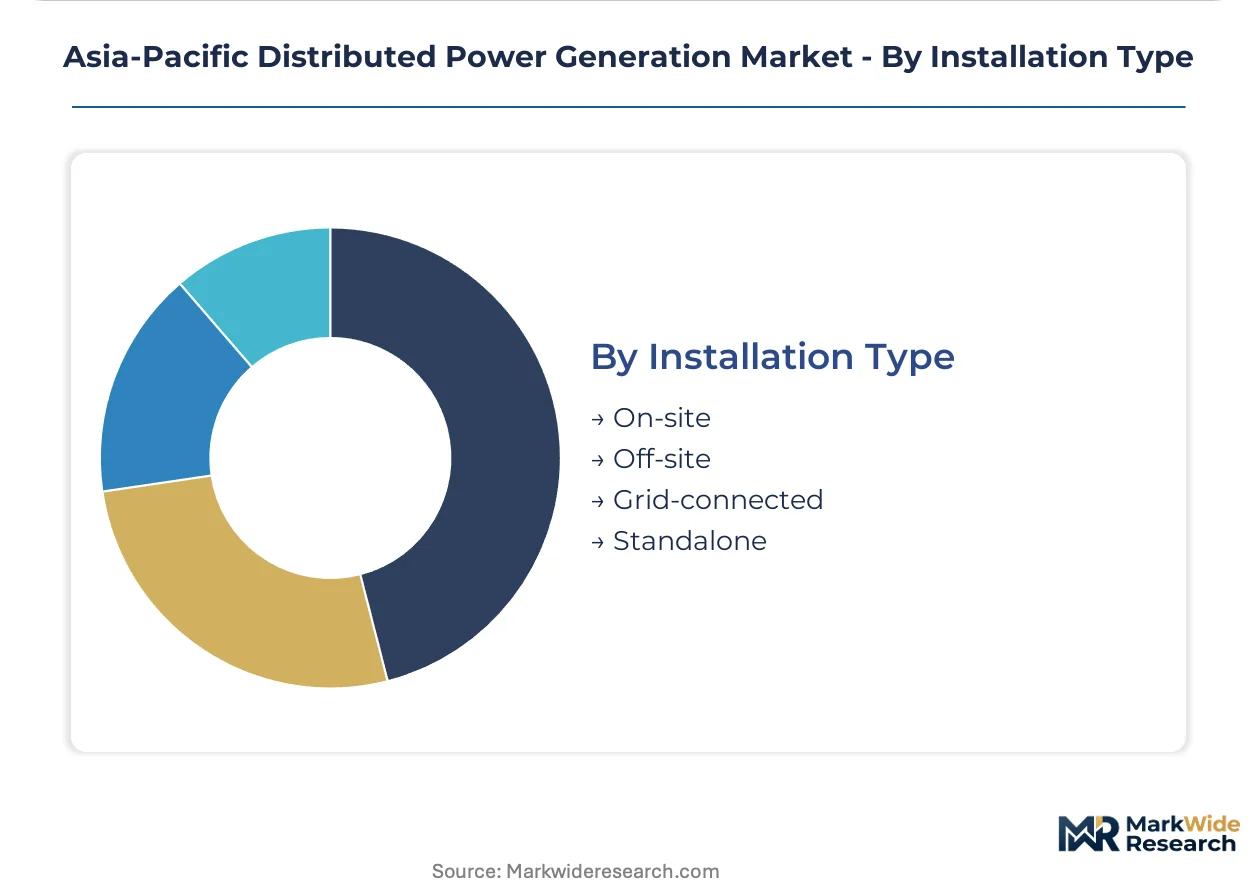
Interconnection architecture determines regulatory jurisdiction, technical standards compliance, and revenue stacking opportunities.
- On-site:Behind-the-meter generation sited within consumption centers dominates C&I procurement, with India's CEA technical standards and China's MIIT GB certification shaping equipment qualification timelines.
- Grid-connected:Export-capable systems require harmonic compliance and anti-islanding protection under incompatible standards across Australia's Clean Energy Regulator, India's CEA, and Japan's METI.
- Standalone:Islanded microgrids serve Indonesian and Philippine island grids with legacy diesel assets complicating hybrid retrofit financing.
- Off-site:Virtual power purchase arrangements and aggregated remote generation are emerging structures for corporate renewable procurement.
Established deployment sits with On-site. Newer deployment is concentrated in Standalone islanded configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Xinjiang's polysilicon ingot concentration anchors upstream feedstock supply for module assembly across Southeast Asia, while manufacturing demand clusters in industrial corridors from Maharashtra to northern Vietnam reshape procurement patterns.
China
MIIT's GB certification for inverter efficiency compresses equipment qualification timelines for Vietnamese and Indonesian developers sourcing Chinese components. The dual carbon goals redirect capital toward domestic n-type cell production, tightening legacy p-type availability for regional assemblers. Yangtze River Delta fabs dominate TOPCon and heterojunction capacity expansion.
India
State-level net metering policies in Maharashtra, Gujarat, and Karnataka enable hybrid solar-plus-storage deployments for textile and automotive manufacturing clusters. CEA technical standards for grid-connected distributed generation shape equipment procurement specifications. Commercial and industrial rooftop installations concentrate in Pune, Ahmedabad, and Bengaluru industrial corridors.
Vietnam
Northern manufacturing hubs near Hanoi lack transmission capacity, creating captive microgrid demand for gas-solar hybrid configurations. Industrial parks in Bac Ninh and Hai Phong provinces contract directly with integrated EPC developers rather than traditional equipment distributors. Procurement bypasses conventional channels as textile manufacturers seek supply security.
Japan
METI's feed-in tariff transition steers commercial and industrial adopters toward market-linked power purchase frameworks and self-consumption optimization. Toshiba Fuel Cell Power Systems validates proton exchange membrane integration in Kobe and Fukuoka hydrogen pilot zones. Battery dispatch strategies replace guaranteed 20-year rate structures for new installations.
Australia
The Clean Energy Regulator's Small-scale Renewable Energy Scheme extends tradable certificate mechanisms into commercial strata properties, opening aggregated behind-the-meter portfolios. Bifacial glass-glass module specifications with sub-minus 0.26 percent per degree Celsius temperature coefficients dominate utility-scale procurement. New South Wales and Victoria lead commercial solar aggregation.
Asia-Pacific Distributed Power Generation Market Competitive Environment
Global majors compete with regional champions across equipment integration depth, with consolidated module supply contrasting fragmented microgrid control software segments. Chinese polysilicon-to-module players anchor volume supply while European and Japanese specialists capture premium system integration margins. Three archetypes dominate: integrated cell-to-module manufacturers, microgrid platform specialists, and captive EPC-financing hybrids. Competitive moves concentrate on backward integration into polysilicon feedstock and geographic expansion through industrial park anchor contracts.
Within the integrated manufacturing tier, Trina Solar Limited and JinkoSolar Holding Co. Ltd. represent the dominant Chinese cell-to-module archetype with captive polysilicon supply chains. Schneider Electric SE occupies a position exemplifying the microgrid control and energy management platform specialist, competing on unified dispatch system integration rather than component supply. These three anchors illustrate how equipment qualification timelines and industrial park procurement bypass strategies are reshaping competitive positioning across the region.
| Leading Market Players |
|---|
| Trina Solar Limited |
| Schneider Electric SE |
| Caterpillar Inc. |
| Siemens AG |
| Canadian Solar Inc. |
| JinkoSolar Holding Co. Ltd. |
| Sharp Solar Energy Solutions Group |
| Toshiba Fuel Cell Power Systems Corporation |
| Cummins Inc. |
| Others |
Value Chain & Pricing Dynamics
Vietnamese and Indonesian industrial park developers anchor procurement volume, locking in contract-based long-term offtake structures that bundle equipment supply with 25-year performance warranties and O&M service contracts. This buyer concentration compresses pricing power for module assemblers while elevating margin capture for integrated EPC-financing hybrids with captive balance-sheet capacity.
Pricing Analysis
Extended warranty and predictive maintenance bundling separates premium-tier integrated developers from unbundled equipment distributors serving price-sensitive Southeast Asian project aggregators. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with GB-certified inverters from Chinese suppliers commanding margin premiums over uncertified alternatives. Cost compression in lithium-ion battery cells is intensifying because of oversupply in Chinese cell manufacturing, forcing storage integrators to absorb price erosion or surrender market share. Philippine and Thai industrial parks exhibit highest price sensitivity, while Australian utility-scale developers prioritize temperature coefficient performance over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from Japanese and Australian offtakers require module and inverter qualification across at least two manufacturing bases, fragmenting procurement timelines but reducing forced-labor due diligence exposure. Polysilicon ingot production concentrates in Xinjiang, Jiangsu, and Sichuan provinces, with cell and module assembly drawing from Vietnam, Thailand, and Malaysia to circumvent tariff exposure. Upstream dependency rests on high-purity quartz crucibles, silver paste metallization, and fluorinated backsheet films. Single-source vulnerability in Xinjiang-based polysilicon feedstock threatens Southeast Asian module assemblers with supply disruption and reputational risk. Distribution runs through integrated EPC contractors with captive financing arms, bypassing traditional equipment distributors in Ho Chi Minh City and Bangkok corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
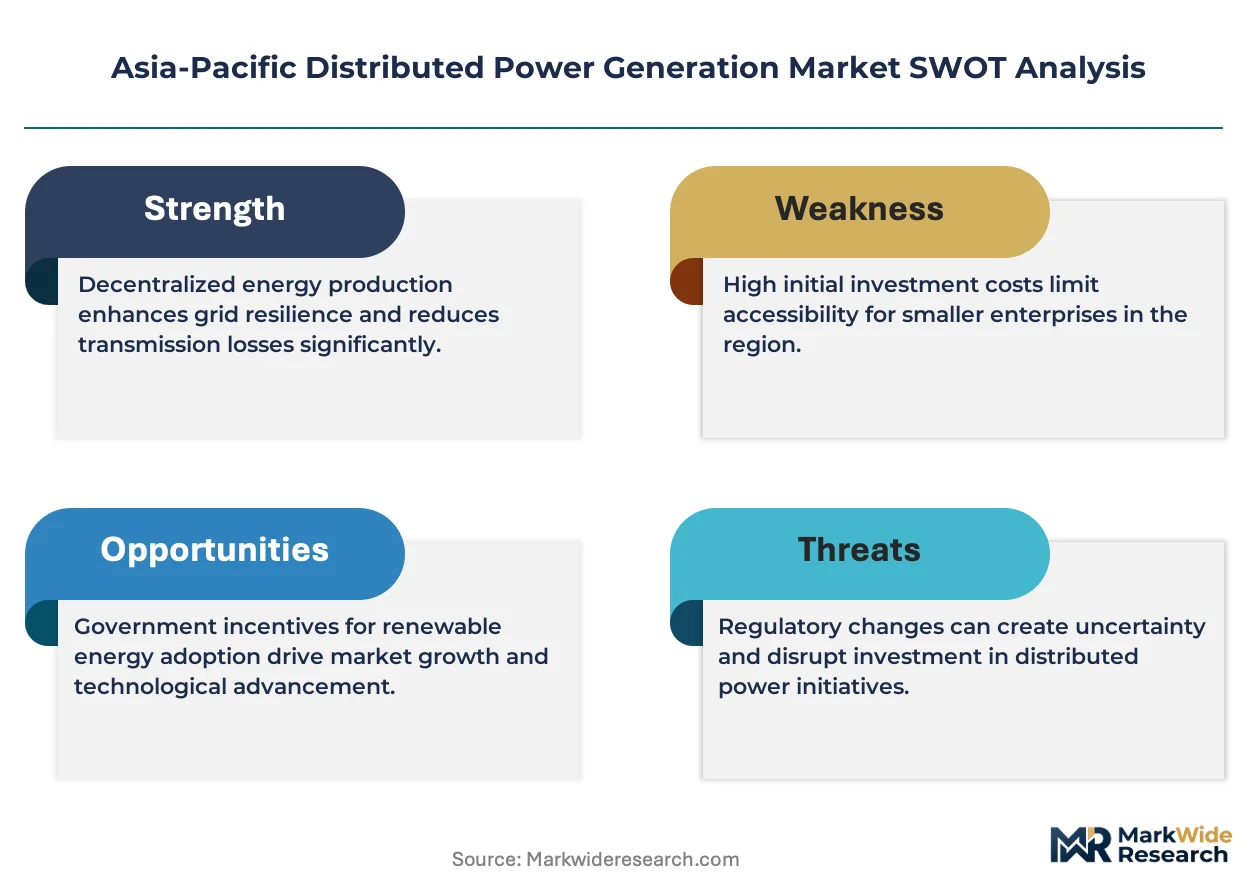
Equipment qualification timelines under China's MIIT GB certification and India's CEA technical standards erect compliance moats that favor incumbents with pre-certified component libraries and in-house testing facilities.
For Market Incumbents: Deploy backward integration into polysilicon feedstock to secure margin control against Xinjiang supply disruption risks. Anchor industrial park contracts in Bac Ninh and Hai Phong provinces through captive EPC-financing structures that lock out distributor competitors. Channel control represents the priority defensive lever, as Vietnamese textile manufacturers increasingly bypass traditional equipment vendors for integrated developers. For New Entrants and Emerging Players: The premium-to-economy price gap in microgrid control software opens white-space opportunity for specialized energy management platform developers. Target northern Vietnamese manufacturing hubs lacking transmission capacity, where gas-solar hybrid configurations face limited incumbent competition. Australian commercial strata property aggregation through tradable certificate mechanisms offers the most penetrable geography for new software entrants with SaaS-tiered pricing models. For Investors and Strategic Acquirers: The window for entry favors microgrid platform specialists with utility-grade protection scheme expertise and existing METI or CEA certification relationships. Long-term viability hinges on acquisition of engineering talent concentrated in Tokyo and Bangalore rather than manufacturing assets. Watch for inflection in Japan's feed-in tariff transition pace, as accelerated market-linkage adoption would redirect capital toward battery dispatch optimization technologies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Xinjiang supply disruption risks force captive feedstock strategies for margin defense. |
| Microgrid Control Platform Development | Schneider Electric's unified dispatch systems demonstrate premium capture in Vietnamese industrial zones. |
| Industrial Park Anchor Contracting | Bac Ninh and Hai Phong procurement bypasses traditional distribution channels entirely. |
| GB/CEA Pre-Certification Investment | MIIT inverter efficiency standards compress bid qualification timelines for unprepared competitors. |
| Lithium-Ion Storage Integration | Falling cell prices enable solar-plus-storage islanding capabilities for Philippine and Thai manufacturing parks. |
Study Parameters
Multi-period observation of module pricing indices, inverter certification timelines, and industrial park procurement patterns anchored the trend analysis, supplemented by interviews with IPP project developers, EPC contractors, grid operators, and utility planning officers across the Asia-Pacific region. Primary fieldwork combined with secondary validation from EIA data, IEA renewable energy reports, FERC-style regulatory filings, and project development databases. Bottom-up capacity installation tracking and top-down policy impact assessment were triangulated to cross-verify volume estimates.
Segment-weighting across technology, product type, end user, and installation type dimensions shaped the analytical framework, with additional weighting for regulatory framework clusters given heterogeneity across METI, CEA, and Clean Energy Regulator jurisdictions. CAGRs were derived from fitted growth curves applied to base-year capacity data and policy-driven deployment scenarios. Key forecast inputs included lithium-ion battery cost trajectories, n-type cell capacity expansion schedules, and feed-in tariff transition timelines.
Inputs from regulatory filing databases and industrial park procurement registries were available through the study window; gaps in real-time module inventory positioning introduce uncertainty bands around near-term price elasticity assumptions. Deviation in China's dual carbon policy enforcement intensity or Xinjiang labor due diligence sanctions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Cogeneration System Market
Power Generation
India Gensets Market
Power Generation
Steam Turbine Market
Power Generation
Thermal Power Market
Power Generation
Venezuela Power Market
Power Generation
LAMEA Microturbine Market
Power Generation
Oman Power Market
Power Generation
Tunisia Power Market
Power Generation
Mobile Power Plant Market
Power Generation
Global Natural Gas Fired Electricity Generation Market
Power Generation
Canada Power EPC Market
Power Generation
India Gas Generator Market
Power Generation
Power Plant EPC Market
Power Generation
Europe Thermal Power Market
Power Generation
Mexico Combined Heat and Power Market
Power Generation
Third Generation Energy Sources Market