
 Gas Gensets Market | 2026-2036
Gas Gensets Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Gensets Market Analysis
Data center power reliability is hardening as the dominant demand vector for gas gensets. Cummins sustains technology leadership through its integrated paralleling controls and lean-burn engine architectures. Caterpillar dominates the heavy continuous-duty segment with its G3516 product line and global dealer service density. Kohler differentiates through its residential standby portfolio and channel control across North American homebuilder networks.
Gas gensets are internal combustion engines fueled by natural gas, biogas, or renewable gas that convert mechanical energy into electrical power through synchronous generators, typically operating at 1500 or 1800 RPM depending on grid frequency requirements. Standby gensets constitute the largest revenue pool given data center and healthcare uptime mandates, while continuous-duty units serving oilfield and remote mining operations carry higher per-unit margins. Prime power applications are gaining traction in regions with weak grid infrastructure where biogas and renewable gas fuel types reduce operating cost exposure.
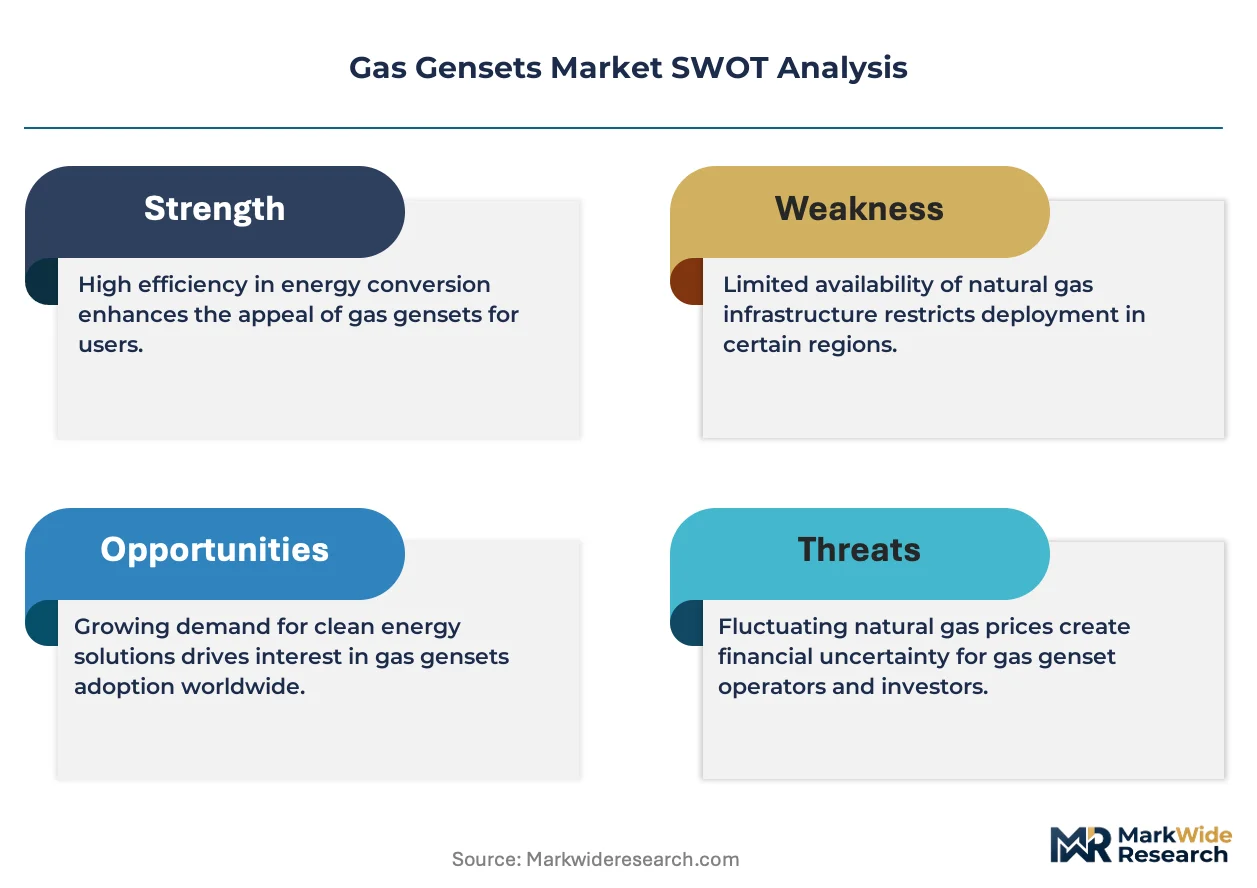
EPA Tier 4 Final standards in the United States and EU Stage V regulations in Europe enforce stringent limits on nitrogen oxide and particulate emissions from non-road engines, compelling manufacturers to invest in selective catalytic reduction and oxidation catalyst technologies. India's CPCB norms for genset emissions and China's GB standards for stationary engine pollution control are tightening compliance timelines across Asia-Pacific manufacturing bases. Stakeholders must monitor fuel price spreads between diesel and natural gas, biogas feedstock availability, and evolving carbon accounting rules that will determine genset competitiveness against battery storage alternatives.
Market Dynamics
Data center uptime mandates and EPA Tier 4 Final compliance deadlines are forcing synchronous investments in lean-burn engine architectures and emissions aftertreatment systems across the gas genset supply base.
Growth Catalysts
- EPA Tier 4 Final mandates:The regulation compels replacement of aging diesel standby units with natural gas alternatives in U.S. healthcare and data center applications.
- Biogas fuel infrastructure:Anaerobic digester installations at U.S. wastewater treatment plants are creating captive fuel supplies for continuous-duty genset deployments.
- Data center construction:Hyperscale facility builds in Northern Virginia and Phoenix are absorbing multi-megawatt gas genset blocks for N+1 redundancy configurations.
Market Restraints
- Natural gas price volatility:Henry Hub spot fluctuations compress operating cost advantages versus diesel in U.S. prime power applications.
- Aftertreatment capex burden:Selective catalytic reduction and oxidation catalyst systems add 15-25% to genset bill-of-materials.
- Lithium-ion substitution:Battery energy storage systems are capturing short-duration standby roles below four-hour runtime requirements.
Strategic Opportunities
- Renewable natural gas certification:EPA renewable fuel standard credits and California LCFS incentives reward biogas-to-electricity pathways.
- Hybrid microgrid integration:Synchronous gensets paired with solar PV and battery storage are securing islanding contracts at U.S. military installations.
- Virtual power plant aggregation:Grid operators in Texas and California are enrolling standby gensets in demand response pools for ancillary services revenue.
Industry Challenges
- Emissions calibration complexity:EPA certification timelines for new engine families extend 18-24 months, delaying product launches.
- Service technician scarcity:Specialized training for high-pressure fuel systems and aftertreatment diagnostics outpaces vocational pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Gensets Market |
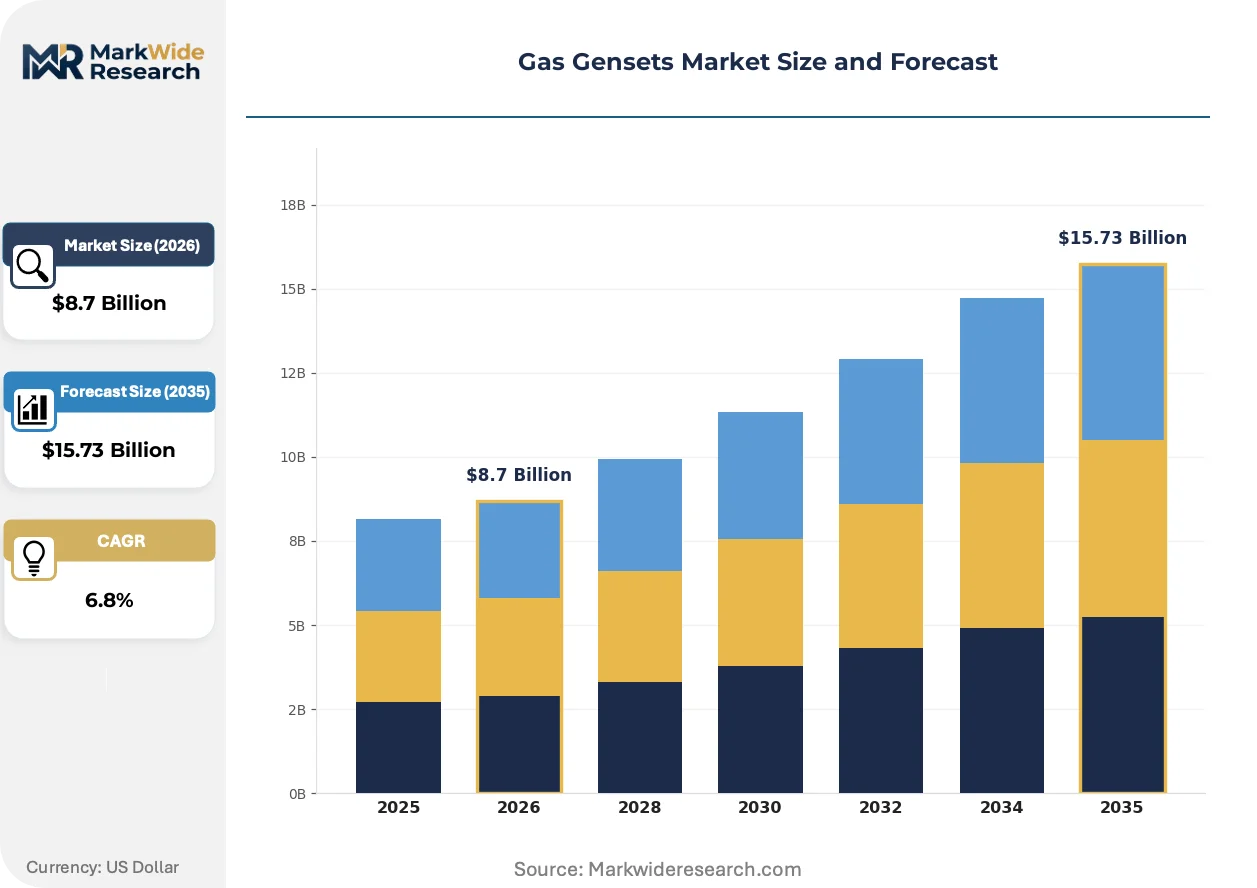
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Standby, Prime, Continuous Application: Residential, Commercial, Industrial, Backup Power Fuel Type: Naturally Aspirated, Turbocharged, Biogas, Renewable Gas Customer Type: Residential Users, Businesses, Government, Utilities |
| Companies Covered | Caterpillar, Cummins, Generac Power Systems, Kohler, MTU Onsite Energy, Cooper Corporation, Mahindra Powerol, Briggs & Stratton, FG Wilson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Gensets Market Emerging Trajectories
Lean-burn combustion architectures and digital paralleling controls are redefining genset performance benchmarks while regulatory tightening accelerates technology turnover across the installed base.
Advanced lean-burn pre-chamber designs are overtaking conventional stoichiometric engines in data center standby applications. Operators in Ashburn and Phoenix are specifying these units for sub-0.5 g/bhp-hr NOx without urea injection. The technology is overtaking legacy rich-burn architectures in bids above 1 MW.
EPA Tier 4 Final certification requirements now cover all non-emergency stationary engines above 25 horsepower. Manufacturers must demonstrate durability across 8,000-hour test cycles with portable analyzers. The rule compresses product development calendars and favors integrated engine-aftertreatment suppliers.
Power-as-a-service contracting is displacing traditional equipment ownership at industrial campuses. Third-party operators in Texas and Ohio are retaining genset titles and selling uptime guarantees to chemical processors. The model transfers capex burdens and compliance risks while locking in decade-long fuel supply agreements.
Gas Gensets Market Segmentation
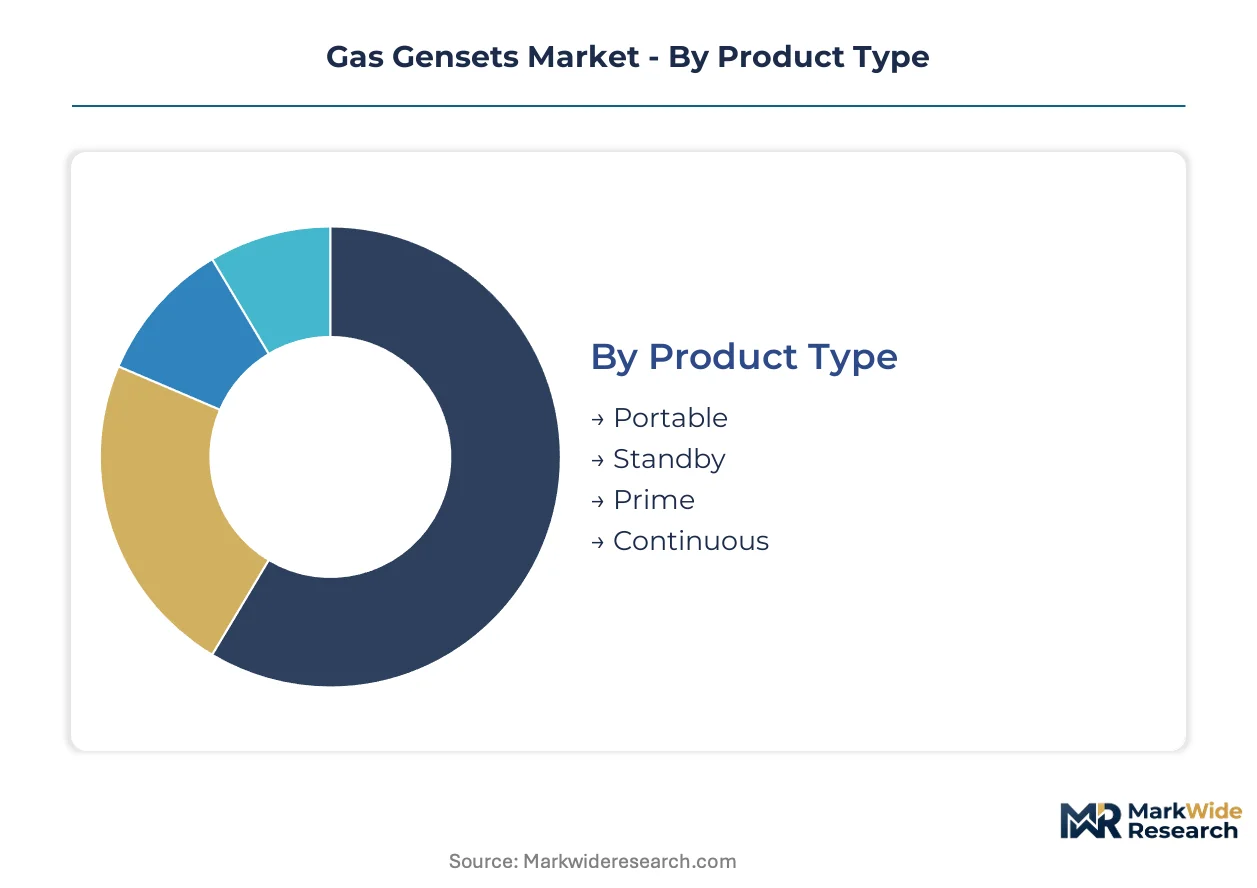
Gas genset procurement patterns diverge sharply across duty cycles, end-use environments, and fuel sourcing strategies. Each segmentation axis reveals distinct margin structures, compliance burdens, and technology specifications that shape supplier positioning.
Product Type:
Customization intensity rises with runtime duty, from standardized portable units to engineered continuous-duty blocks.
- Standby:These units activate automatically during grid failure, serving data center N+1 redundancy and hospital life-safety circuits. Northern Virginia hyperscale campuses absorb multi-megawatt blocks as EPA Tier 4 Final deadlines force diesel-to-gas conversions.
- Continuous:Designed for unlimited annual operating hours at constant load, these engines power remote oilfield operations and mining camps. Biogas-fueled installations at U.S. wastewater treatment plants create captive fuel economics.
- Portable:Trailer-mounted or skid-based units deliver temporary power for construction sites and emergency response. Rental fleet operators in Texas and Florida dominate procurement.
- Prime:Rated for variable load with unlimited hours, these serve weak-grid regions where natural gas undercuts diesel operating costs. Prime applications are gaining share in sub-Saharan African markets.
Leading the category by volume: Standby. Expanding most quickly: Continuous.
Application:
End-use concentration tracks grid reliability investments and regulatory enforcement intensity.
- Industrial:Manufacturing campuses and chemical processors deploy megawatt-scale blocks for process continuity. Power-as-a-service contracting in Ohio and Texas transfers capex burdens to third-party operators.
- Backup Power:Critical infrastructure mandates drive healthcare and telecommunications deployments. Uptime Institute certification requirements harden specifications for data center standby.
- Commercial:Retail chains and office complexes specify sub-500 kW units for business continuity. California's SB 100 carbon neutrality targets accelerate renewable gas adoption.
- Residential:Single-family standby systems dominate North American homebuilder specifications. Kohler's channel control across U.S. builder networks shapes competitive dynamics.
Highest revenue concentration: Industrial. Steepest expansion trajectory: Backup Power.
Fuel Type:
Margin structure varies with fuel infrastructure maturity and carbon accounting rules.
- Biogas:Anaerobic digester output powers continuous-duty installations with EPA renewable fuel standard credit eligibility. California LCFS incentives reward biogas-to-electricity pathways.
- Turbocharged:Forced induction enables higher power density and lean-burn combustion for sub-0.5 g/bhp-hr NOx without urea injection. Data center operators in Ashburn and Phoenix specify these for emissions compliance.
- Renewable Gas:Pipeline-injected biomethane and power-to-gas synthetic methane qualify for carbon-neutral claims. European utilities lead procurement under EU Green Deal targets.
- Naturally Aspirated:Simpler architectures serve cost-sensitive residential and small commercial markets. Limited to lower power ratings and higher emissions profiles.
Widest installed base: Turbocharged. Gaining share fastest: Biogas.
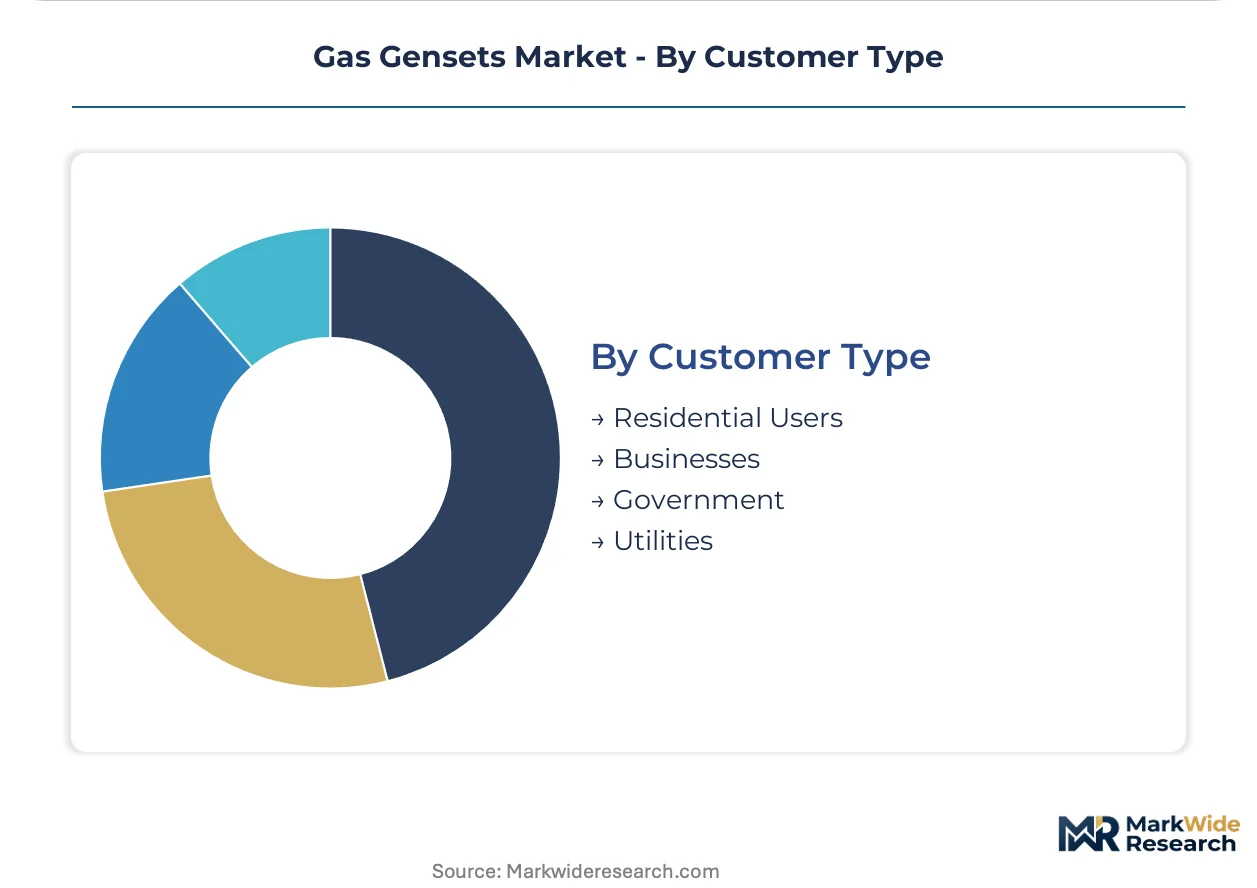
Customer Type:
Procurement sophistication scales with technical staff depth and regulatory exposure.
- Utilities:Grid operators in Texas and California enroll standby gensets in demand response pools for ancillary services revenue. Virtual power plant aggregation requires synchronous paralleling controls.
- Government:Military installations specify hybrid microgrid configurations with solar PV and battery storage for islanding capability. Federal energy resilience mandates drive multi-year procurement cycles.
- Businesses:Corporate sustainability targets and ESG disclosure requirements favor renewable gas certification. CDP reporting frameworks influence fuel sourcing decisions.
- Residential Users:Homeowner associations and individual buyers prioritize automatic transfer switches and noise attenuation. Financing through home improvement loans shapes purchase timing.
Largest unit volume: Businesses. Most complex specifications: Utilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones in Northern Virginia and Phoenix anchor hyperscale data center construction, concentrating multi-megawatt gas genset procurement for N+1 redundancy configurations.
United States
Data center uptime mandates and EPA Tier 4 Final compliance deadlines drive diesel-to-gas conversions across healthcare and critical infrastructure. The EPA enforces 8,000-hour durability testing for non-emergency stationary engines above 25 horsepower. Northern Virginia's Loudoun County hosts the world's densest concentration of hyperscale facilities, absorbing continuous genset deployments.
Germany
Industrial backup requirements and grid stability investments sustain demand from chemical processors and manufacturing campuses. EU Stage V regulations impose stringent nitrogen oxide and particulate matter limits on non-road engines. The Rhine-Ruhr industrial corridor specifies lean-burn architectures for sub-0.5 g/bhp-hr NOx compliance without urea injection.
China
Weak grid infrastructure in western provinces accelerates prime power deployments for remote mining and oilfield operations. GB standards for stationary engine pollution control tighten compliance timelines across manufacturing bases. The Yangtze River Delta industrial clusters integrate biogas-fueled continuous-duty units at wastewater treatment facilities.
India
Manufacturing expansion and commercial real estate development sustain standby power procurement across sub-500 kW ratings. CPCB norms for genset emissions mandate particulate matter and hydrocarbon limits in urban airsheds. Maharashtra's Pune-Aurangabad industrial belt deploys turbocharged units for variable load prime power applications.
United Arab Emirates
Desalination plant reliability requirements and district cooling infrastructure sustain continuous-duty genset installations. Federal energy resilience mandates drive multi-year procurement cycles for hybrid microgrid configurations. Dubai's Mohammed bin Rashid Al Maktoum Solar Park integrates synchronous gensets with solar PV for islanding capability.
Gas Gensets Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated engine-aftertreatment suppliers commanding premium positioning in emissions-critical applications. The vendor base concentrates around three strategic archetypes: diversified industrial conglomerates with global dealer networks, focused power generation specialists with lean-burn combustion expertise, and regional fabricators serving cost-sensitive portable and residential markets. Competitive dynamics center on selective catalytic reduction technology licensing and power-as-a-service contracting models that transfer capex burdens to third-party operators.
Within the diversified industrial tier, Caterpillar and Cummins exemplify scale-driven positioning through integrated paralleling controls and global service density. Generac Power Systems occupies a specialist position in residential standby applications, while Kohler anchors premium-tier channel control across North American homebuilder networks. These three companies represent distinct competitive vectors: heavy continuous-duty dominance, residential market penetration, and dealer network exclusivity respectively.
| Leading Market Players |
|---|
| Caterpillar |
| Cummins |
| Generac Power Systems |
| Kohler |
| MTU Onsite Energy |
| Cooper Corporation |
| Mahindra Powerol |
| Briggs & Stratton |
| FG Wilson |
| Others |
Supply Flow & Price Mechanics
Lean-burn combustion architectures and integrated selective catalytic reduction systems are compressing manufacturing cost curves while concentrating procurement leverage among EPA-certified engine families. This technology transition simultaneously elevates R&D amortization burdens and rewards scale economics across integrated engine-aftertreatment suppliers.
Pricing Analysis
Short lead-time premiums command pricing power for Tier 4 Final-certified blocks in data center N+1 configurations, while spot inventory of legacy rich-burn units trades at distressed levels. Three-tier pricing structure across premium, standard, and economy levels separates emissions-certified continuous-duty engines from uncertified standby units and portable rental fleet equipment. Cost compression in the economy tier is intensifying because rental operators are extending asset depreciation cycles. Data center operators show least price sensitivity given uptime mandate rigidity, whereas municipal wastewater treatment plants exhibit highest sensitivity due to biogas project return thresholds.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme for stationary engines and China's GB standards compliance requirements are reshaping sourcing toward localized assembly and captive component production. Manufacturing gravity centers on the United States, Germany, and China, with turbocharger and high-pressure fuel injection systems drawing from Japan and precision casting operations feeding from India. Single-source vulnerability concentrates in selective catalytic reduction substrate supply from German and Austrian ceramic manufacturers. Distribution runs through Caterpillar and Cummins dealer networks for heavy continuous-duty units, while residential standby flows through Kohler-controlled homebuilder channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftertreatment catalyst capacity constraints and EPA certification backlog are propping pricing power for certified engine families. Supply scarcity favors incumbents with durable regulatory relationships.
For Market Incumbents: Deploy backward integration into high-pressure fuel system manufacturing to defend margin position against emerging Asian competitors. Consolidate service technician training pipelines through community college partnerships to address scarcity in aftertreatment diagnostics. Battery energy storage substitution in sub-four-hour standby roles threatens core revenue pools; counter with hybrid microgrid bundling that captures islanding contracts at military installations. For New Entrants and Emerging Players: The 40-60% price-point gap between premium Tier 4 Final-certified units and economy-grade rich-burn alternatives opens white-space in sub-500 kW prime power for weak-grid regions. Target biogas-fueled continuous-duty deployments at U.S. wastewater treatment plants where captive fuel economics override first-cost sensitivity. Pursue power-as-a-service contracting to transfer capex burdens while locking decade-long fuel supply agreements. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking EPA certification assets. Long-term viability hinges on renewable natural gas credentialing and carbon accounting rule evolution. Acquisition target archetype: regional fabricators with established biogas digester relationships and lean-burn engineering talent. Watch California LCFS credit pricing as the inflection indicator for biogas-to-electricity project economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fuel Systems | Captive production of high-pressure injection components insulates margin from Japanese supplier pricing power. |
| Hybrid Microgrid Bundling | Synchronous genset plus solar PV plus battery configurations secure islanding contracts at U.S. military installations. |
| Power-as-a-Service Contracting | Third-party operators retain asset titles and sell uptime guarantees, transferring capex burdens to chemical processors. |
| Renewable Natural Gas Certification | EPA renewable fuel standard credits and California LCFS incentives reward biogas-to-electricity pathways with carbon-neutral claims. |
| Technician Training Pipeline Investment | Community college partnerships address aftertreatment diagnostics scarcity that outpaces vocational output. |
Methodological Framework
Multi-period observation of EPA certification timelines, Henry Hub spot price volatility, and data center construction permitting anchored the trend analysis, supplemented by interviews with plant engineers at hyperscale facilities, aftermarket service directors at dealer networks, procurement leads at chemical processors, and grid operators in ERCOT and CAISO territories. Secondary validation drew from EIA natural gas consumption data, FERC interconnection queue filings, EPA engine certification databases, and IEA power system reliability reports. Bottom-up unit deployment tracking across duty cycles and fuel types triangulated against top-down infrastructure investment flow analysis.
Input-output matrices modeled capacity utilization, fuel price spreads, and regulatory compliance cost trajectories across the projection horizon. Segmentation dimensions included duty cycle tier, fuel sourcing strategy, end-use environment, and regional regulatory framework. CAGRs derived from fitted growth curves calibrated to historical deployment velocity and infrastructure investment commitment patterns. Industry-specific forecast inputs incorporated anaerobic digester installation rates and data center power density specifications.
Underlying measurement precision varies by segment; standby genset deployment in Northern Virginia carries tighter precision than prime power projections in sub-Saharan African markets due to data availability asymmetry. Forecasts reflect assumptions around EPA enforcement continuity, natural gas infrastructure buildout, and battery cost decline trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
United Kingdom Combined Heat and Power (CHP) Market
Power Generation
Global Black Start Generator Market
Power Generation
India Thermal Power Plant Market
Power Generation
Hydrogenerators Market
Power Generation
Malaysia Power Generation EPC Market
Power Generation
Algeria Power Market
Power Generation
Micro CHP Market
Power Generation
Vietnam Power Generation EPC Market
Power Generation
Microturbine Market
Power Generation
Iraq Power EPC Market
Power Generation
Captive Power Plant Market
Power Generation
Global Turbines Market
Power Generation
Global Gensets Market
Power Generation
Cogeneration System Market
Power Generation
Global Power Grid System Market
Power Generation
Brazil Power Plant EPC Market